
 Medicated Fitness Supplements Market | 2026-2036
Medicated Fitness Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Medicated Fitness Supplements Market Analytics
Subscription-based personalized nutrition programming is shifting how medicated fitness supplements reach end users. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital-to-home rehabilitation channels. Herbalife Nutrition sustains direct-selling infrastructure across emerging markets. Glanbia Performance Nutrition dominates whey protein isolate sourcing for premium medicated formulations.
Medicated fitness supplements are clinically formulated ingestible products containing pharmaceutical-grade active compounds, standardized botanical extracts, or bioavailable nutrient complexes manufactured under current Good Manufacturing Practice conditions; their primary purpose is to support physiological recovery, muscle protein synthesis, or metabolic function under medical or supervised fitness supervision. Protein powders occupy the largest revenue pool due to established reimbursement pathways in post-surgical nutrition, while microencapsulation technology commands premium positioning through taste masking and targeted intestinal release. Pre-workout formulas compete on stimulant-free positioning for cardiac-rehabilitation patients, and online retailers capture margin expansion via telehealth-integrated subscription models.
The FDA oversees New Dietary Ingredient notifications, while the EMA enforces Novel Food assessments for cross-border European distribution; China's NMPA mandates registration for imported health foods containing medicinal ingredients. Stakeholders must monitor evolving pharmacovigilance requirements that could reclassify high-dose formulations as borderline medicinal products.
Market Dynamics
Microencapsulation technology is compressing formulation differentiation cycles as manufacturers race to mask clinical-grade bitterness while enabling targeted intestinal release for cardiac-rehabilitation and post-surgical patient segments.
Growth Catalysts
- Physician-backed distribution channels:Hospital-to-home rehabilitation protocols in Germany and the United States now integrate reimbursed protein powders, creating institutional pull-through for supervised fitness nutrition.
- EMA Novel Food assessments:Streamlined cross-border European distribution pathways reduce regulatory friction for standardized botanical extracts entering supervised fitness programs.
- Telehealth-integrated subscriptions:Online retailers capture recurring revenue through remote patient monitoring platforms that automate supplement replenishment for metabolic recovery patients.
Market Restraints
- Whey protein isolate supply concentration:Premium formulation sourcing clusters in Irish and New Zealand dairy processing regions, exposing margin compression from input volatility.
- FDA New Dietary Ingredient notification delays:Pharmaceutical-grade compound approvals stretch 12-18 months, freezing pipeline innovation for bioavailable nutrient complexes.
- Whole-food protein substitutes:Plant-based complete amino acid profiles from precision fermentation threaten clinical positioning of animal-derived medicated formulations.
Strategic Opportunities
- China's NMPA health food registration:Imported medicinal ingredient pathways for supervised fitness nutrition remain underdeveloped relative to domestic TCM-infused sports products.
- Stimulant-free pre-workout cardiac rehabilitation:Nitrate-rich beetroot extracts and citrulline malate combinations address unmet demand from post-myocardial infarction patients cleared for resistance training.
- AI-driven personalization engines:Metabolic phenotyping algorithms converging with continuous glucose monitoring data enable dynamic dosing adjustments for insulin-sensitive athletes.
Industry Challenges
- Current Good Manufacturing Practice talent scarcity:Pharmaceutical-quality cleanroom operations for ingestible fitness products require operators cross-trained in both nutraceutical and medical device protocols.
- Pharmacovigilance integration complexity:High-dose formulation tracking systems must interface with national adverse event databases as regulators scrutinize borderline medicinal thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicated Fitness Supplements Market |
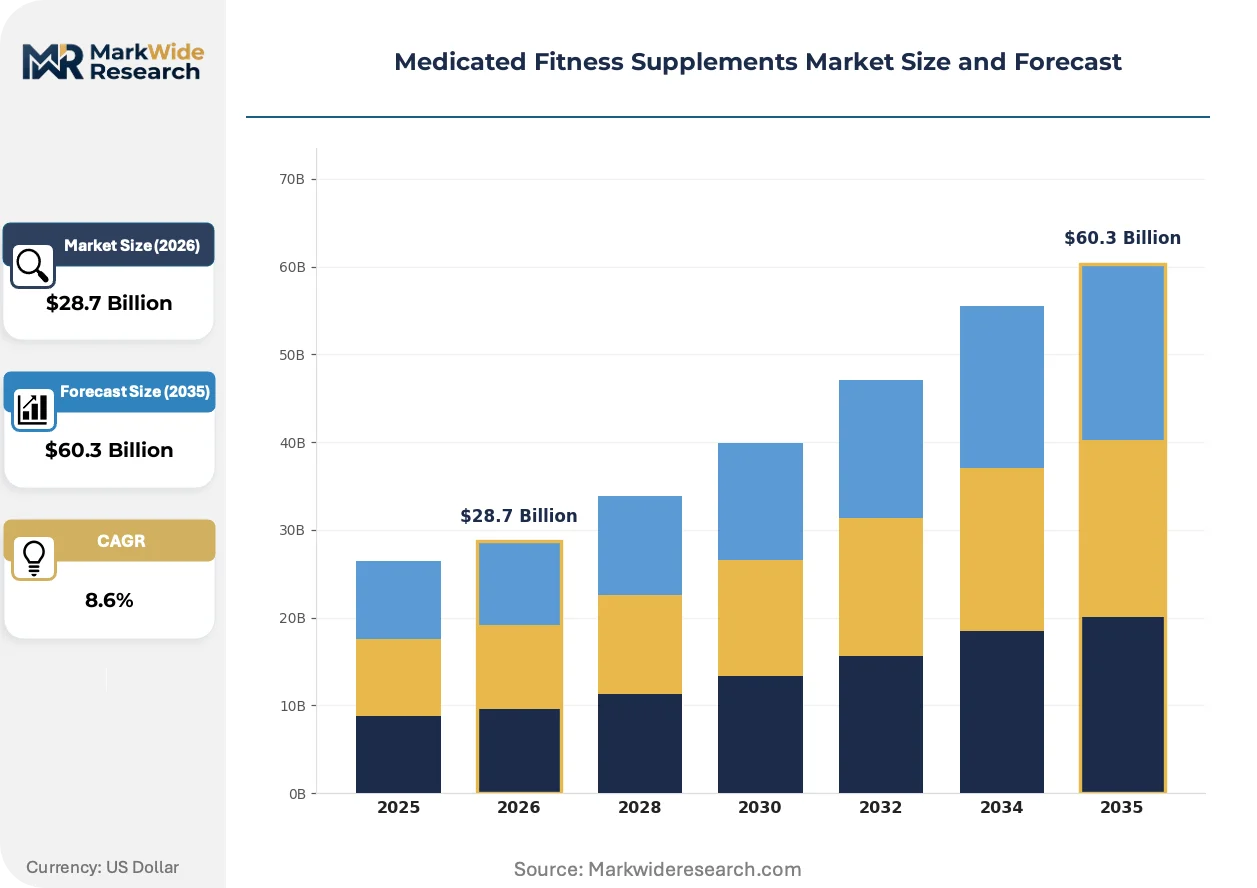
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $60.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Pre-Workout Formulas, Recovery Drinks Technology: Microencapsulation, Liquid Formulation, Powdered Blends, Enhanced Absorption End User: Athletes, Bodybuilders, Health Enthusiasts, Rehabilitation Patients Distribution Channel: Specialty Stores, Online Retailers, Gyms, Health Food Stores |
| Companies Covered | Glanbia Performance Nutrition, Abbott Laboratories, Herbalife Nutrition, Amway, Nestle Health Science, GNC Holdings, MusclePharm Corporation, BellRing Brands, Optimum Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicated Fitness Supplements Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous transformation as clinical evidence requirements tighten and patient supervision models fragment across settings.
Liposomal delivery systems is converging with effervescent tablet formats to enhance bioavailability of fat-soluble vitamins in post-bariatric surgery patients. German rehabilitation clinics and United States cardiac centers are piloting these combinations for malabsorption protocols. The technology is compressing the efficacy gap between standard dietary supplements and prescription medical foods.
China's NMPA dual carbon goals are reshaping manufacturing location decisions for imported health foods, with carbon footprint disclosures now influencing registration timelines. Domestic producers leveraging renewable energy certificates gain expedited review pathways. European exporters with verified supply chain emissions data capture preferential positioning in hospital procurement tenders.
Subscription bundling with remote biomarker testing is displacing traditional retail pharmacy pickup for metabolic recovery patients. United States telehealth platforms integrate HbA1c and inflammation marker results to auto-adjust protein and omega-3 dosing. This pattern concentrates among post-surgical nutrition programs in California and Texas where payer contracts reward adherence monitoring.
Medicated Fitness Supplements Market Segmentation
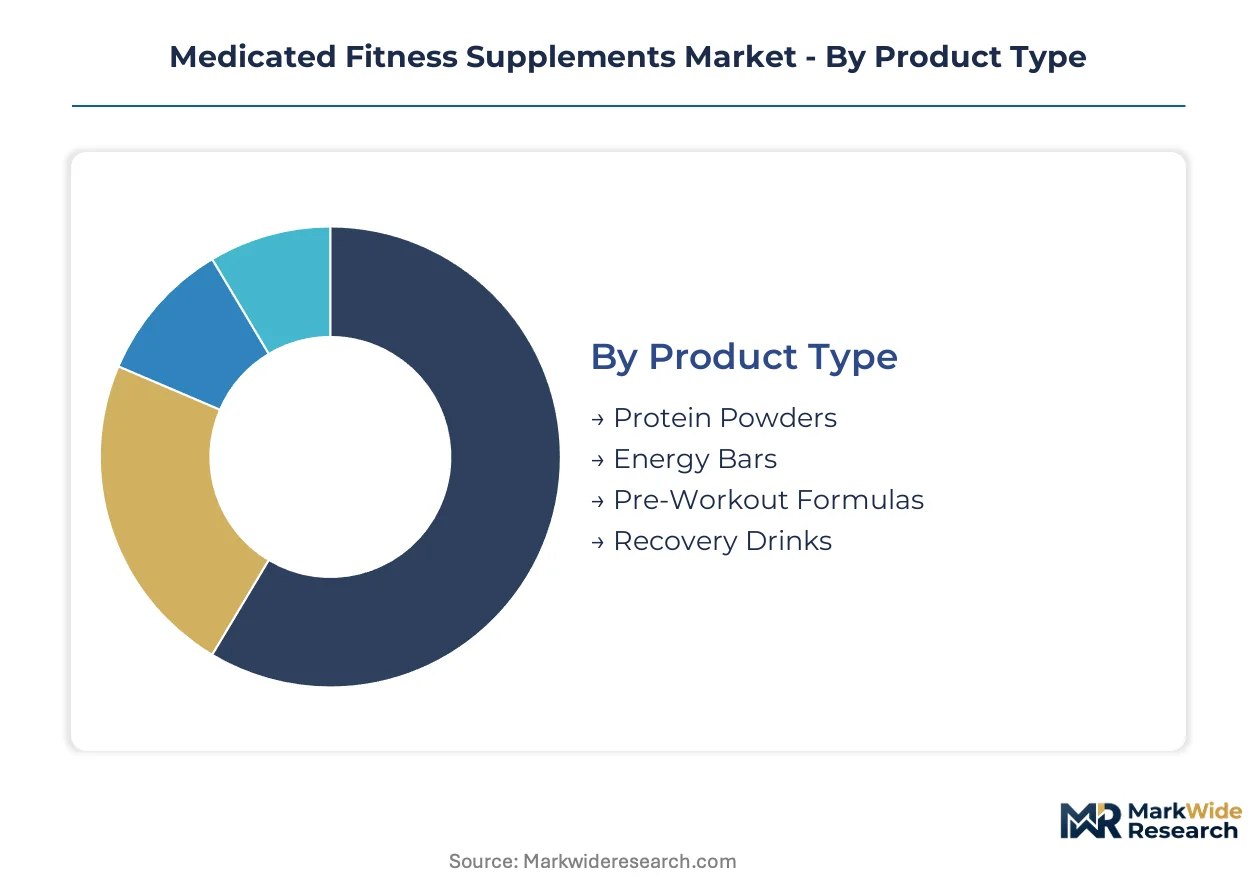
Medicated fitness supplements fragment across four orthogonal dimensions that determine formulation complexity, regulatory pathway, and margin structure. Product type and technology choices anchor manufacturing investment, while end user and channel segmentation dictate reimbursement eligibility and customer acquisition costs.
Product Type:
Standardization dominates protein powders and energy bars, while pre-workout and recovery formulations demand physician-calibrated customization for cardiac and post-surgical protocols.
- Protein Powders:Clinically dosed whey and casein isolates manufactured under cGMP conditions support muscle protein synthesis in post-operative patients. Hospital-to-home rehabilitation programs in Germany and the United States drive institutional procurement through reimbursed nutrition protocols.
- Pre-Workout Formulas:Stimulant-free compositions featuring nitrate-rich botanicals address unmet demand from post-myocardial infarction patients cleared for supervised resistance training. Cardiac rehabilitation centers in Texas and Bavaria pilot these formulations under remote monitoring.
- Energy Bars:Microencapsulated micronutrient fortification enables taste-masked delivery of clinical-grade compounds for ambulatory patients.
- Recovery Drinks:Liposomal vitamin complexes target malabsorption in bariatric surgery follow-up care.
Leading the category by volume: Protein Powders. Expanding most quickly: Pre-Workout Formulas.
Technology:
Cost tiers separate commodity powdered blends from premium microencapsulation and enhanced absorption platforms that command hospital procurement premiums.
- Microencapsulation:Taste-masking matrices and targeted intestinal release systems enable compliance among pediatric and geriatric rehabilitation patients. German clinics demand this technology for cardiac protocol adherence.
- Enhanced Absorption:Liposomal and effervescent delivery systems compress the efficacy gap between dietary supplements and prescription medical foods for post-bariatric malabsorption cases.
- Liquid Formulation:Ready-to-drink formats suit dysphagia patients in acute care transitions.
- Powdered Blends:Bulk manufacturing serves cost-sensitive gym-direct channels with minimal clinical positioning.
Technology leadership concentrates in microencapsulation patent holders. Fastest uptake: enhanced absorption platforms for metabolic recovery.
End User:
Application intensity varies from performance optimization in athletes to physiological recovery mandates in rehabilitation patients that determine reimbursement eligibility.
- Rehabilitation Patients:Post-surgical and cardiac recovery protocols require physician-supervised dosing with adverse event tracking integrated into national pharmacovigilance databases. United States telehealth platforms automate replenishment via HbA1c and inflammation marker monitoring.
- Athletes:Insulin-sensitive competitors demand AI-driven personalization converging continuous glucose monitoring with dynamic protein and omega-3 adjustments.
- Bodybuilders:High-volume protein consumption drives commodity whey isolate demand with minimal clinical differentiation.
- Health Enthusiasts:Self-directed consumers access subscription bundles through direct-to-consumer telehealth integrations.
Rehabilitation Patients generate highest per-user revenue through reimbursed protocols. Athletes represent the steepest expansion trajectory via biometric-integrated personalization.
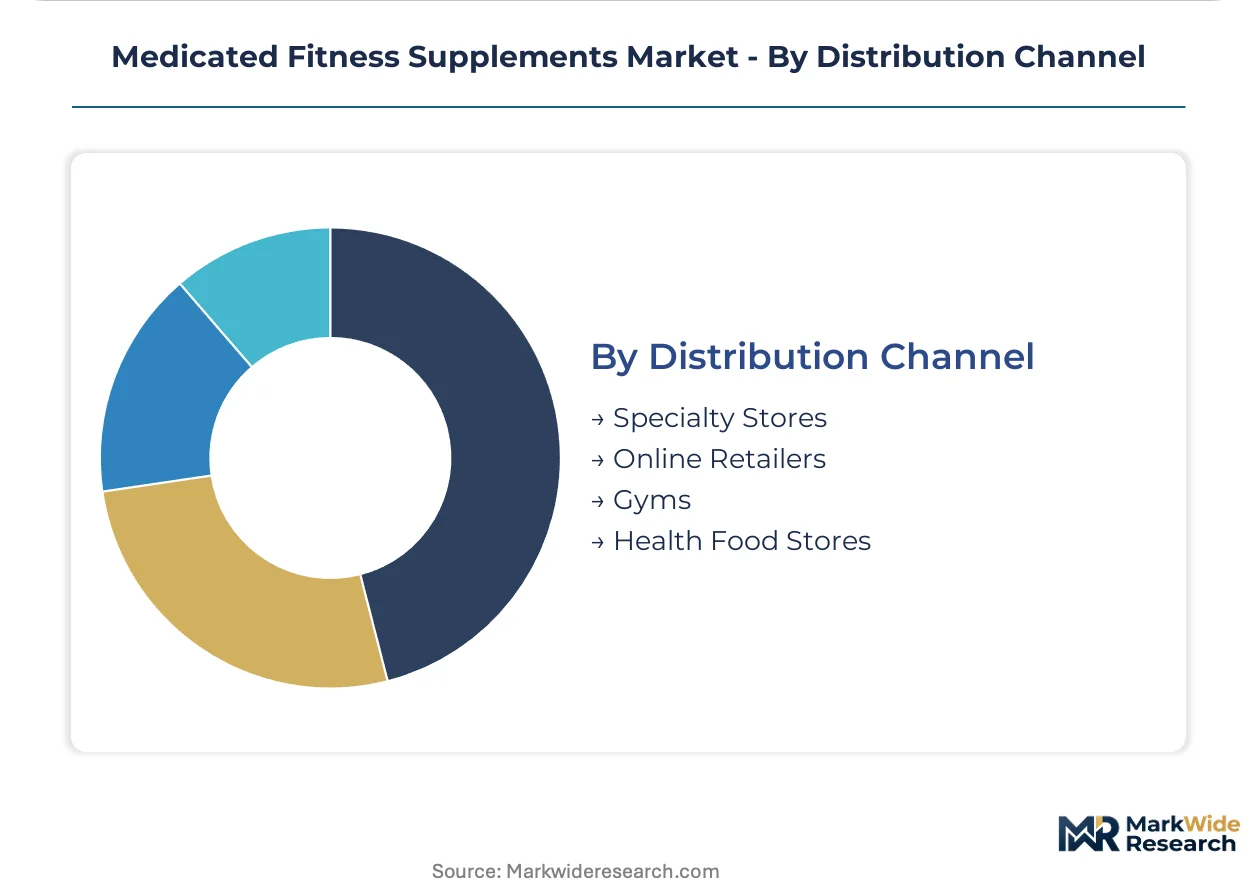
Distribution Channel:
Customer type stratifies between institutional procurement through specialty channels and automated replenishment via telehealth-integrated online platforms.
- Online Retailers:Telehealth-integrated subscription models capture recurring revenue through remote patient monitoring platforms that automate supplement dosing adjustments based on biomarker results. California and Texas post-surgical programs concentrate here.
- Specialty Stores:Hospital outpatient dispensaries and rehabilitation clinic pharmacies handle reimbursed protein powder fulfillment for German and United States discharge protocols.
- Gyms:Direct-selling infrastructure reaches bodybuilders and health enthusiasts with minimal clinical oversight.
- Health Food Stores:Traditional retail captures self-pay consumers outside reimbursed pathways.
Online Retailers lead channel growth through subscription bundling. Specialty Stores retain institutional volume leadership in reimbursed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the United States medicated fitness supplements corridor through its concentration of hospital-to-home rehabilitation networks and telehealth-integrated subscription platforms. Clinical nutrition procurement from Massachusetts General and Brigham Health systems drives institutional demand for reimbursed protein formulations. The FDA New Dietary Ingredient notification pathway shapes cross-state distribution compliance for pharmaceutical-grade compounds.
United States
Post-surgical nutrition reimbursement through Medicare Advantage plans drives protein powder procurement in Texas and California rehabilitation networks. The FDA enforces cGMP standards for clinical-grade manufacturing facilities supplying hospital outpatient dispensaries. Dallas-Fort Worth cardiac centers pilot stimulant-free pre-workout protocols under remote patient monitoring integration.
Germany
EMA Novel Food assessments enable streamlined cross-border distribution of standardized botanical extracts into Bavarian rehabilitation clinics. Hospital-to-home protocols in Munich and Cologne integrate reimbursed whey isolate formulations for post-operative muscle protein synthesis. The country's dual carbon goals accelerate carbon footprint disclosure requirements for imported health food registration.
China
NMPA health food registration pathways for imported medicinal ingredients remain underdeveloped against domestic TCM-infused sports nutrition dominance. Shanghai and Beijing hospital procurement tenders prioritize suppliers with verified renewable energy certificates. The dual carbon policy framework expedites review timelines for domestic manufacturers leveraging clean energy documentation.
United Kingdom
Post-Brexit regulatory divergence from EMA Novel Food assessments creates parallel compliance obligations for cross-channel supplement distribution. London rehabilitation clinics source microencapsulated protein formulations through specialty pharmacy channels. The Medicines and Healthcare products Regulatory Agency monitors borderline medicinal thresholds for high-dose nutrient complexes.
Medicated Fitness Supplements Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the medicated fitness supplements landscape. The market structure consolidates around three tiers: pharmaceutical-nutrition conglomerates with hospital distribution infrastructure, direct-selling networks with emerging market penetration, and specialty sports nutrition formulators with cGMP-certified manufacturing. Strategic archetypes include clinical-channel anchors, subscription-platform operators, and ingredient-sourcing specialists. Competitive moves concentrate on telehealth integration partnerships and microencapsulation technology licensing rather than capacity expansion.
Within the clinical-channel anchor tier, Abbott Laboratories and Glanbia Performance Nutrition exemplify divergent positioning strategies. Abbott leverages its pharmaceutical heritage through hospital-to-home rehabilitation procurement networks. Glanbia occupies a sourcing-specialist position controlling premium whey protein isolate supply chains for third-party formulation. Herbalife Nutrition represents the direct-selling archetype with infrastructure spanning emerging market penetration outside reimbursed clinical pathways.
| Leading Market Players |
|---|
| Glanbia Performance Nutrition |
| Abbott Laboratories |
| Herbalife Nutrition |
| Amway |
| Nestle Health Science |
| GNC Holdings |
| MusclePharm Corporation |
| BellRing Brands |
| Optimum Nutrition |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty ingredient producers anchor supply discipline across Irish and New Zealand dairy processing corridors, translating concentrated whey protein isolate ownership into procurement premiums for cGMP-certified formulation houses. Their financing structures reward long-term offtake contracts that stabilize input costs for hospital-to-home rehabilitation channels while compressing margin flexibility for commodity gym-direct competitors.
Pricing Analysis
Value-based pricing anchored to patient recovery outcomes dominates reimbursed hospital-to-home protocols, with protein powder dosing tied to post-surgical muscle protein synthesis metrics. Three-tier pricing structure across premium microencapsulated clinical formulations, standard cGMP-certified isolates, and economy powdered blends separates reimbursement-eligible from self-pay channels. Pricing pressure stems from precision-fermented plant-based complete amino acid profiles threatening animal-derived positioning. Rehabilitation patients cleared for resistance training exhibit lowest price sensitivity due to insurance coverage, while health enthusiasts in gym-direct channels drive commoditization.
Supply Chain Analysis
China's dual carbon goals and NMPA health food registration requirements are reshaping sourcing decisions for imported medicinal ingredients, favoring domestic TCM-infused producers with renewable energy documentation. Premium whey protein isolate draws from Irish and New Zealand dairy processing regions, while microencapsulation technology patents cluster in German and United States specialty chemical houses. Single-source vulnerability runs through concentrated Irish dairy cooperatives supplying cGMP-certified isolate. Distribution runs through telehealth-integrated online platforms for metabolic recovery patients and specialty pharmacy channels for reimbursed hospital discharge protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
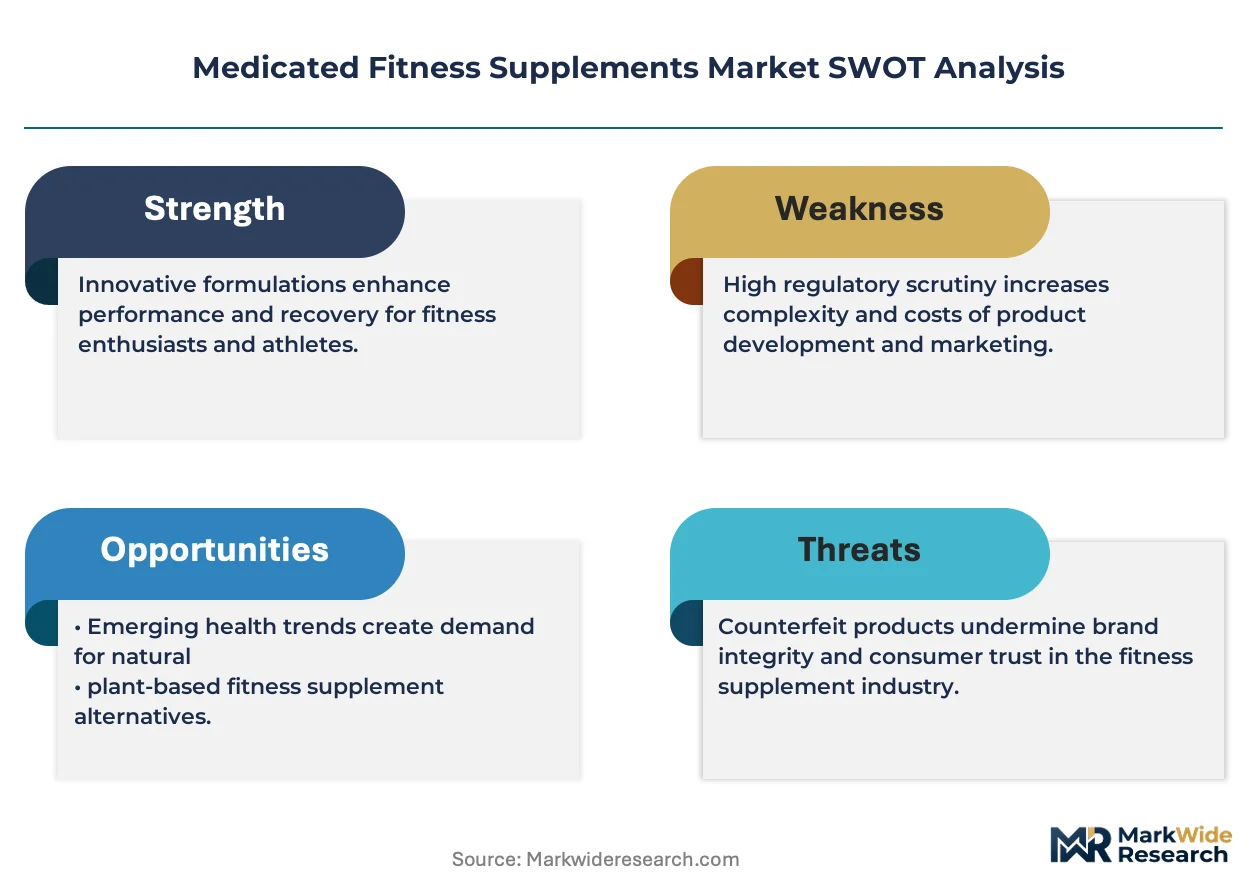
This market reads as a cost-of-compliance story where FDA New Dietary Ingredient notification requirements and EMA Novel Food assessments erect barrier-to-entry moats favoring pharmaceutical-nutrition conglomerates with established regulatory affairs infrastructure.
For Market Incumbents: Cement hospital-to-home rehabilitation procurement relationships through cGMP certification investments that freeze out commodity competitors lacking adverse event tracking capabilities. Deepen backward integration into microencapsulation patent portfolios to defend margin position against formulation science commoditization. Threats from precision-fermented plant-based substitutes demand clinical evidence generation preserving animal-derived premium positioning. For New Entrants and Emerging Players: Post-myocardial infarction patients cleared for supervised resistance training represent an underserved buyer archetype with unmet demand for stimulant-free pre-workout formulations. China's NMPA registration pathways for imported medicinal ingredients offer white-space penetration against domestic TCM-infused dominance. AI-driven personalization engines converging continuous glucose monitoring with dynamic dosing adjustments provide a differentiable go-to-market angle for insulin-sensitive athlete segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor telehealth-integrated subscription platform operators in United States post-surgical nutrition corridors where payer contracts reward adherence monitoring. Long-term viability over the analysis window hinges on regulatory compliance infrastructure rather than formulation innovation alone. Acquisition targets should demonstrate cGMP-certified manufacturing with pharmacovigilance database integration. The signal to watch is FDA reclassification activity around high-dose nutrient complexes approaching borderline medicinal thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | German cardiac rehabilitation clinics demand taste-masking matrices for pediatric and geriatric compliance. |
| Telehealth Platform Integration | United States post-surgical programs in California and Texas automate replenishment via HbA1c monitoring. |
| cGMP Certification Investment | FDA enforcement on clinical-grade manufacturing facilities creates procurement eligibility for hospital dispensaries. |
| Backward Integration into Whey Isolate Sourcing | Irish and New Zealand dairy processing concentration exposes margin compression from input volatility. |
| AI-Driven Personalization Engine Development | Continuous glucose monitoring convergence enables dynamic protein and omega-3 dosing for insulin-sensitive athletes. |
Research Methodology
Multi-period observation of FDA New Dietary Ingredient notification timelines, EMA Novel Food assessment outcomes, and NMPA health food registration patterns anchored the trend analysis, supplemented by interviews with cGMP facility operators, hospital procurement managers, telehealth platform executives, and regulatory affairs specialists. Secondary validation drew from FDA filings, EMA submission databases, NMPA registration disclosures, and hospital procurement contract repositories. Bottom-up segmentation modeling triangulated against top-down macro indicator tracking.
Input-output matrices mapped formulation technology adoption rates against end-user reimbursement eligibility across product type, technology platform, patient segment, and distribution channel dimensions. CAGRs were derived from segment-level growth trajectory convergence over the projection horizon. Industry-specific forecast inputs incorporated pharmacovigilance integration requirements and carbon footprint disclosure timelines influencing registration pathways.
Revisions become necessary when FDA reclassification activity, EMA borderline medicinal threshold adjustments, or NMPA dual carbon policy enforcement shifts materialize beyond modeled assumptions. Forecasts reflect documented scenario parameters around regulatory timeline uncertainty and supply concentration risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
China Sports Drink Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Creatine Market