
 Middle East and Africa Sports Nutrition Market | 2026-2036
Middle East and Africa Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sports Nutrition Market Foresight
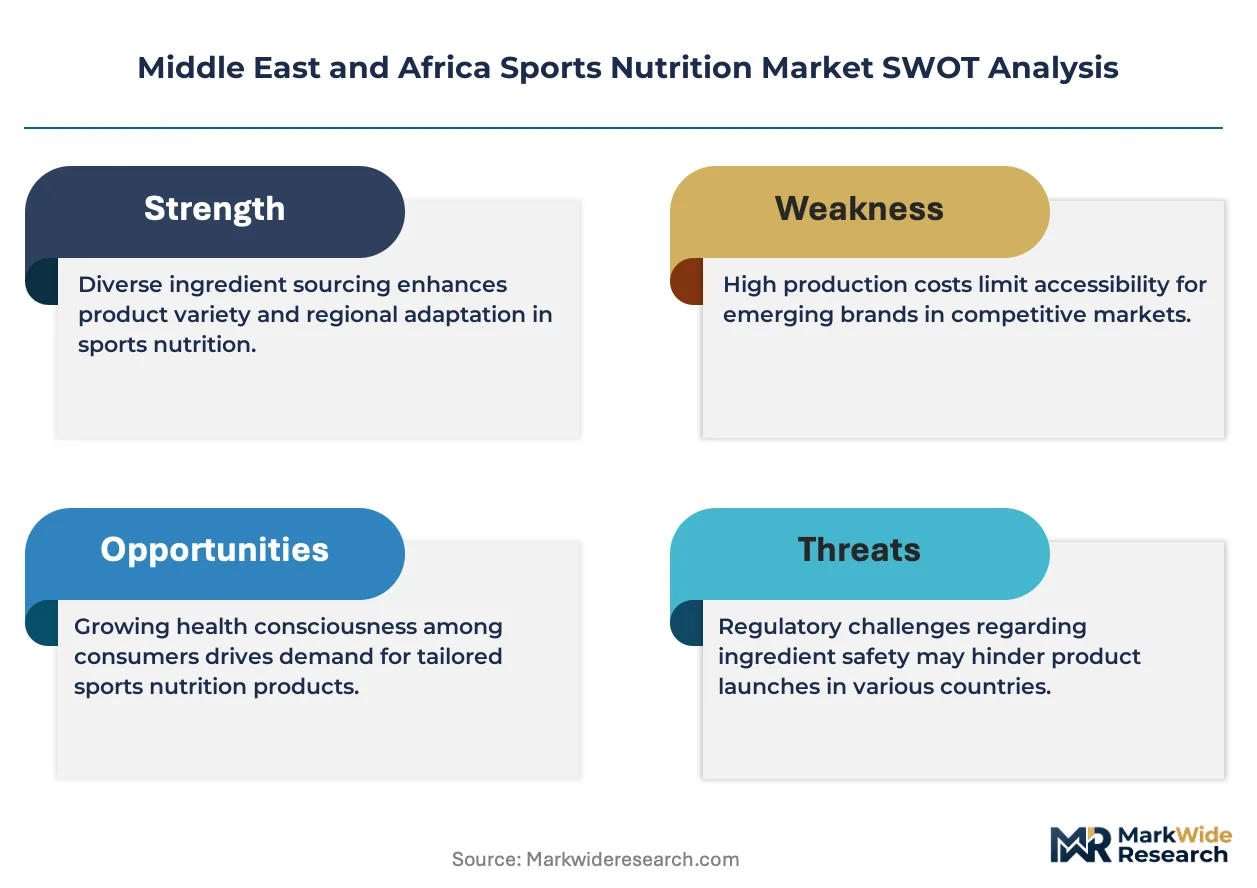
Amateur endurance sports participation across the Middle East and Africa is expanding faster than traditional bodybuilding demand, reshaping how manufacturers formulate and position their portfolios. Glanbia Plc leverages its dairy-derived protein expertise to supply whey isolates favored by marathon and triathlon communities in the Gulf states. Abbott anchors its medical nutrition credibility to penetrate clinical-adjacent recovery segments where healthcare practitioner endorsement carries premium weight. Ascendis Health competes through localized manufacturing in South Africa that reduces import duty exposure and shortens replenishment cycles for regional distributors.
Middle East and Africa sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, and body composition, typically containing protein isolates, carbohydrate matrices, caffeine, creatine, or branched-chain amino acids in specified dosages. These products undergo spray-drying, extrusion, or cold-pressed bar formation to preserve bioactive integrity and achieve shelf stability in climates exceeding forty degrees Celsius. Protein Supplements dominate value capture due to higher per-unit pricing and repeat purchase frequency among committed users, while Energy Bars represent the fastest-growing form factor as convenience-seeking casual consumers enter the category. The End User split reveals Fitness Enthusiasts overtaking Bodybuilders in volume contribution, a structural shift that redistributes margin pools toward flavor innovation and portable formats rather than bulk commodity tubs.
South Africa's National Regulator for Compulsory Specifications enforces labeling and contaminant thresholds that determine which imports reach shelf, while Saudi Arabia's Food and Drug Authority evaluates novel ingredient petitions through a framework that increasingly references EFSA safety opinions. The UAE's Ministry of Industry and Advanced Technology coordinates with municipal health departments to inspect gym-affiliated retail channels where unlicensed products previously circulated. Stakeholders must monitor how harmonization between Gulf Cooperation Council technical regulations and Codex Alimentarius standards reshapes formulation requirements and certificate-of-analysis obligations for cross-border suppliers.
Market Dynamics
Amateur endurance sports participation across the Middle East and Africa is outpacing traditional bodybuilding demand, forcing manufacturers to reformulate portfolios toward sustained-release proteins and electrolyte matrices suited for marathon and triathlon communities rather than bulk-gain powders.
Growth Catalysts
- Dubai's fitness infrastructure expansion:Government-backed wellness districts and influencer-driven culture create premium product uptake channels that reward branded formulations over commodity imports.
- South Africa's NRCS enforcement:Updated contaminant thresholds and labeling mandates professionalize retail channels, squeezing out unlicensed competitors and expanding addressable market for compliant suppliers.
- Plant protein extraction advances:Cold-pressed and enzymatic processing of fava and chickpea isolates enables halal-certified alternatives that penetrate Gulf states where dairy sourcing faces religious scrutiny.
Market Restraints
- Whey concentrate import dependency:Limited regional dairy processing infrastructure forces reliance on European and Oceanian suppliers, exposing margins to currency volatility and shipping congestion at Jebel Ali and Durban ports.
- Heat degradation in distribution:Ambient supply chains across the Gulf frequently exceed protein denaturation thresholds, forcing costly cold-chain investments that commodity players cannot absorb.
- Pharmaceutical substitution threat:Prescription anabolic recovery protocols in Saudi Arabia's sports medicine clinics capture high-value athlete segments that might otherwise purchase over-the-counter nutrition.
Strategic Opportunities
- Nigeria's underpenetrated gym channel:Lagos and Abuja fitness club density remains below regional benchmarks, creating first-mover advantage for brands establishing direct distributor relationships before formal retail consolidation.
- MOHAP's novel ingredient fast-track:UAE's streamlined petition evaluation for clinically substantiated compounds accelerates launch timelines versus Gulf Cooperation Council harmonization delays elsewhere.
- E-commerce pharmacy convergence:Saudi Arabia's SFDA-licensed digital dispensaries merge supplement and clinical nutrition categories, opening practitioner-endorsed positioning previously reserved for medical device suppliers.
Industry Challenges
- Formulation chemist scarcity:Regional universities produce limited sports nutrition specialists, forcing manufacturers to recruit from European dairy science programs at premium compensation multiples.
- Halal certification timeline compression:Multiple Gulf jurisdictions maintain non-mutually-recognized religious approval bodies, requiring parallel audit tracks that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sports Nutrition Market |
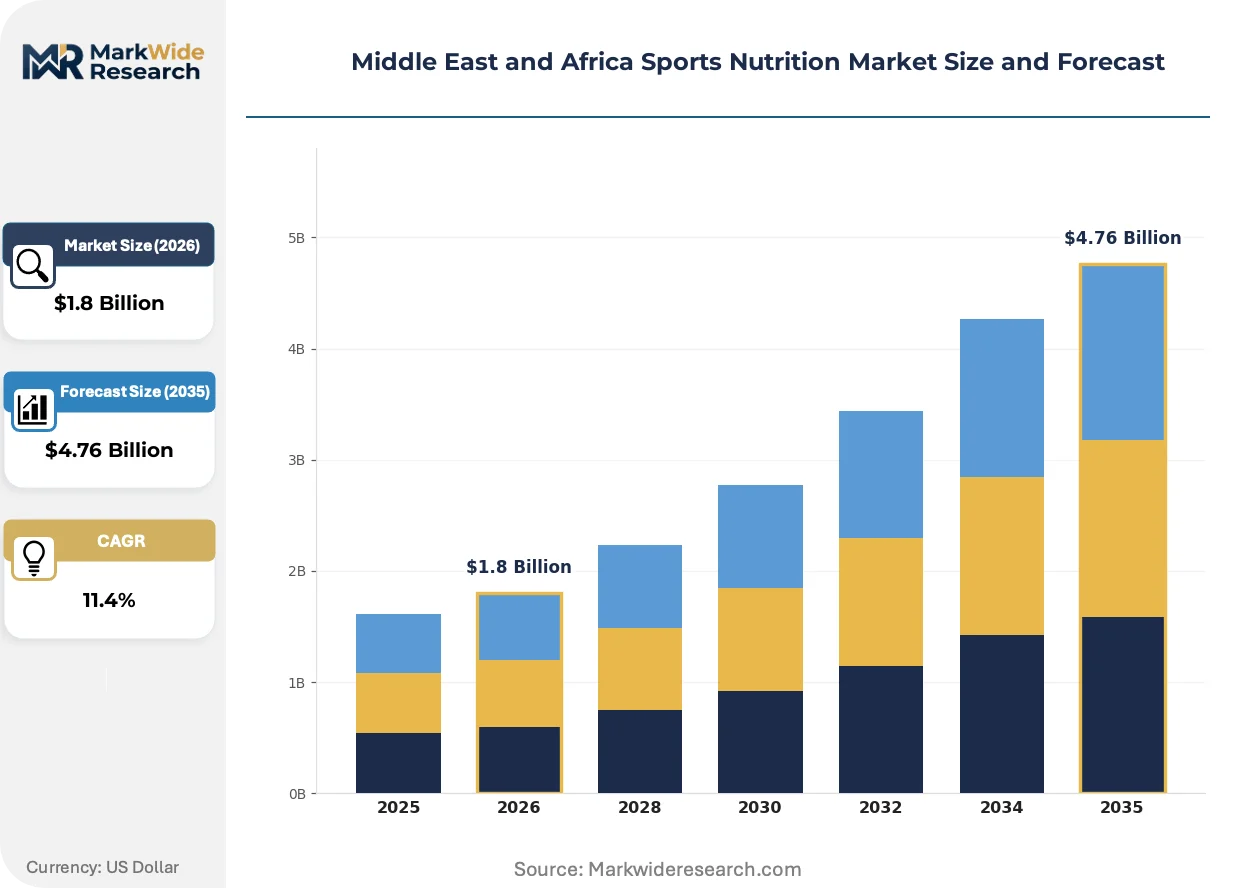
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Energy Bars, Meal Replacements, Pre-Workout Supplements End User: Athletes, Fitness Enthusiasts, Bodybuilders, Casual Consumers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Gyms Form: Powders, Bars, Drinks, Capsules |
| Companies Covered | The Coca-Cola Company, Abbott, PepsiCo Inc., Glanbia Plc, Herbalife Nutrition Ltd, GNC Holdings LLC, Amway Corporation, Bayer AG, Ascendis Health, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sports Nutrition Market Shifts & Advancements
Formulation science and distribution architecture are converging to address climate-specific degradation risks and religious dietary requirements that generic Western products fail to satisfy across Middle Eastern and African markets.
Spray-dried encapsulation of branched-chain amino acids is decentralizing production economics for regional manufacturers. Egyptian and Moroccan facilities now license European drying technology to produce heat-stable isolates that previously required refrigerated import. Mid-market gym chains in Kuwait and Qatar are adopting these locally compounded powders, compressing the premium that multinational brands commanded for climate-resilient formulations.
Saudi Arabia's SFDA has aligned novel ingredient safety evaluations with EFSA technical opinions, creating a reference framework that reduces redundant toxicology studies for applicants. This regulatory convergence accelerates petition approvals for creatine derivatives and caffeine matrices while tightening exclusion of stimulant-adulterated imports. UAE and Bahrain distributors are restructuring supplier qualification protocols around this EFSA-referenced documentation, disadvantaging legacy traders dependent on outdated certificate-of-analysis formats.
Subscription-based replenishment is displacing gym-anchored impulse purchasing across affluent Gulf consumer segments. Dubai-based fitness platforms bundle personalized macro coaching with auto-shipped protein schedules, capturing lifetime value that transactional retail cannot match. This behavioral pivot is most visible among female fitness enthusiasts in Riyadh and Jeddah, where home delivery circumvents cultural friction around public supplement purchases.
Middle East and Africa Sports Nutrition Market Segmentation
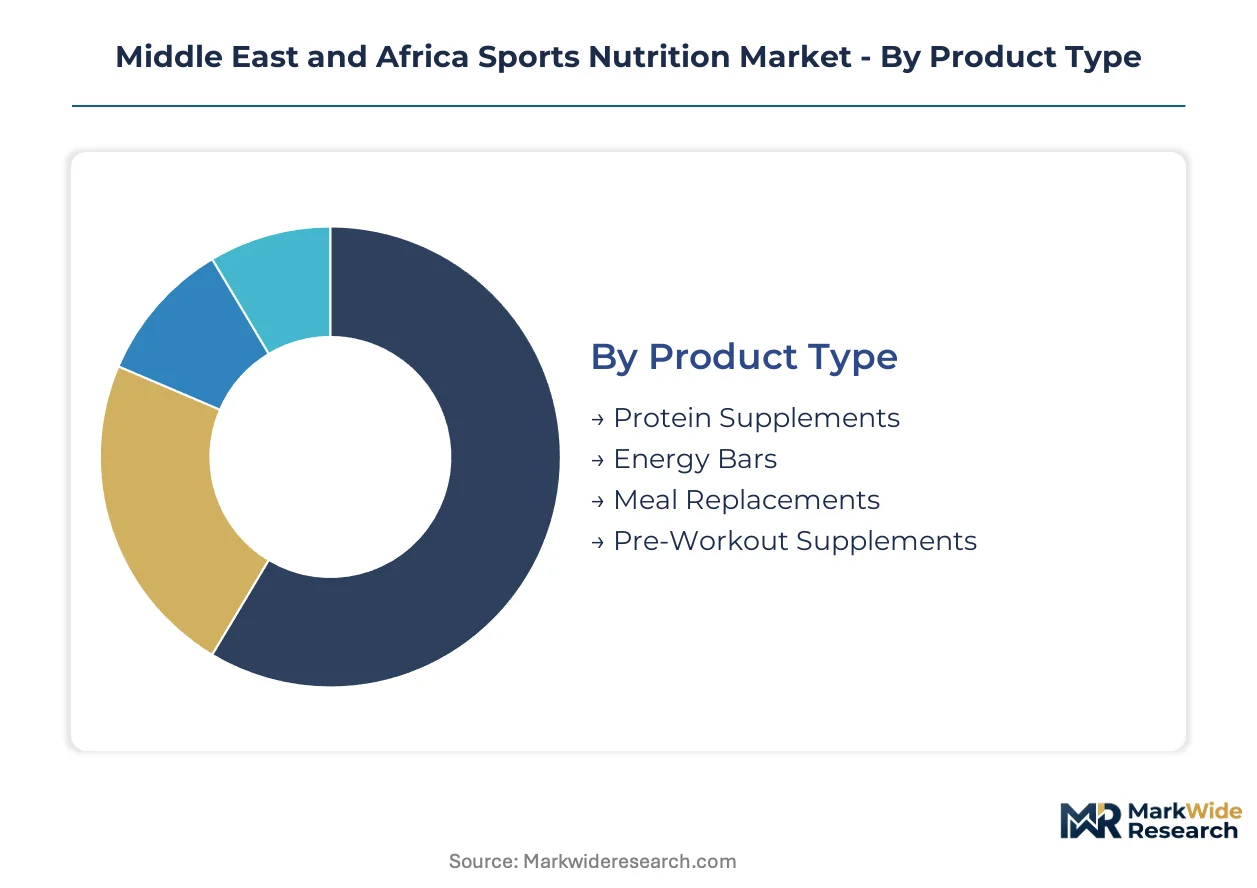
Segmentation in Middle East and Africa sports nutrition reveals how climate constraints, religious dietary requirements, and distribution infrastructure gaps reshape product formulation and channel strategy across distinct buyer groups. Understanding these divides exposes where margin pools concentrate and which segments reward specialized investment.
Product Type:
Purchase frequency and per-unit pricing diverge sharply between committed performance users and convenience-seeking entrants.
- Protein Supplements:Whey isolates and sustained-release casein blends dominate value capture through higher repeat purchase frequency among committed users. Demand concentrates in Dubai's premium gym channels and Saudi Arabia's sports medicine-adjacent retail, where SFDA-compliant labeling commands price premiums over commodity imports.
- Energy Bars:Cold-pressed and extruded formulations with halal-certified binding agents penetrate Gulf states where ambient storage resilience matters. Lagos and Abuja fitness clubs represent underdeveloped distribution nodes where first-mover brands establish direct relationships before retail consolidation.
- Meal Replacements:Clinically positioned formulas leverage Abbott-style medical nutrition credibility in UAE recovery segments where healthcare practitioner endorsement carries premium weight.
- Pre-Workout Supplements:Caffeine and creatine matrices face tighter SFDA scrutiny on novel stimulant petitions, compressing formulation flexibility versus European markets.
Protein Supplements lead volumes today; Energy Bars are gaining share fastest.
End User:
Training modality and supplement sophistication separate buyers more than demographics alone.
- Fitness Enthusiasts:Marathon and triathlon participants across the Gulf states drive sustained-release protein and electrolyte matrix demand that displaces bulk-gain powders. This segment's expansion outpaces traditional bodybuilding participation, redistributing manufacturer R&D toward endurance-optimized formulations.
- Bodybuilders:High-volume whey concentrate purchasers remain concentrated in South Africa's NRCS-regulated retail channels where contaminant threshold compliance filters unlicensed competitors.
- Athletes:Prescription anabolic recovery protocols in Saudi Arabia's sports medicine clinics capture high-value segments that might otherwise purchase over-the-counter nutrition.
- Casual Consumers:Flavor-forward, portable formats purchased through subscription platforms in Riyadh and Jeddah circumvent cultural friction around public supplement purchases.
Fitness Enthusiasts now exceed Bodybuilders in volume contribution; Casual Consumers show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines cold-chain investment requirements and regulatory exposure intensity.
- Online Retail:Subscription-based replenishment platforms in Dubai bundle personalized macro coaching with auto-shipped protein schedules, capturing lifetime value that transactional retail cannot match.
- Supermarkets:Ambient supply chain constraints across the Gulf frequently exceed protein denaturation thresholds, forcing costly climate-control investments that commodity players cannot absorb.
- Health Food Stores:South Africa's NRCS enforcement professionalizes this channel, squeezing out unlicensed competitors and expanding addressable market for compliant suppliers.
- Gyms:UAE Ministry of Industry and Advanced Technology inspections of gym-affiliated retail have reduced unlicensed product circulation, consolidating volume toward certified distributors.
Online Retail climbs the fastest; Gyms retain highest per-transaction values.
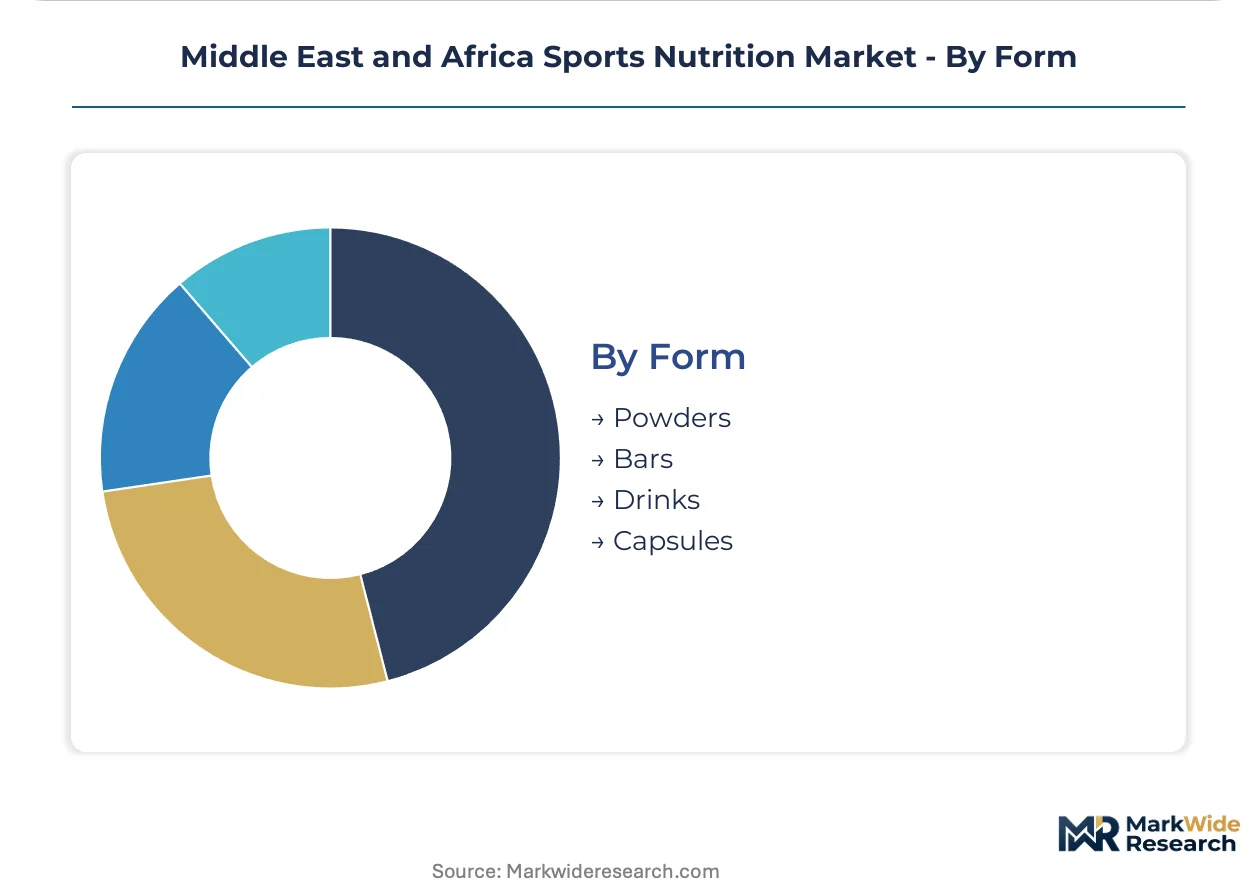
Form:
Heat stability and portability requirements dominate formulation decisions across Middle Eastern and African climates.
- Powders:Spray-dried encapsulation of branched-chain amino acids enables Egyptian and Moroccan facilities to license European drying technology, decentralizing production economics for regional manufacturers.
- Bars:Extruded formats with halal-certified protein isolates achieve shelf stability in climates exceeding forty degrees Celsius where liquid alternatives degrade.
- Drinks:Ready-to-drink formulations face prohibitive cold-chain costs across ambient Gulf distribution networks, limiting penetration to premium convenience channels.
- Capsules:Creatine derivatives and caffeine matrices benefit from Saudi Arabia's SFDA alignment with EFSA safety opinions, accelerating petition approvals versus stimulant-adulterated import exclusions.
Powders lead volumes today; Bars are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's fitness infrastructure anchors premium product uptake across the Middle East and Africa, while regulatory divergence between Gulf Cooperation Council members and sub-Saharan African states fragments compliance pathways for cross-border suppliers.
United Arab Emirates
Marathon and triathlon participation in Dubai and Abu Dhabi drives sustained-release protein demand that displaces bulk-gain powders. MOHAP's streamlined petition evaluation for clinically substantiated compounds accelerates launch timelines versus Gulf Cooperation Council harmonization delays elsewhere. Dubai's wellness districts consolidate volume toward certified distributors following Ministry of Industry and Advanced Technology inspections of gym-affiliated retail.
Saudi Arabia
Sports medicine clinics in Riyadh and Jeddah capture high-value athlete segments through prescription anabolic recovery protocols. SFDA's alignment with EFSA safety opinions on novel ingredient petitions accelerates approvals for creatine derivatives while tightening exclusion of stimulant-adulterated imports. Riyadh-based fitness platforms bundle personalized macro coaching with auto-shipped protein schedules, capturing lifetime value through subscription models.
South Africa
NRCS-enforced contaminant thresholds and labeling mandates professionalize retail channels in Johannesburg and Cape Town, squeezing out unlicensed competitors. Updated food safety standards for supplements determine which imports reach shelf through binding specifications on heavy metals and microbial limits. Ascendis Health leverages localized manufacturing in Gauteng to reduce import duty exposure and shorten replenishment cycles for regional distributors.
Nigeria
Lagos and Abuja fitness club density remains below regional benchmarks, creating first-mover advantage for brands establishing direct distributor relationships. General import regulations and customs enforcement vary by port, exposing shipments to documentation delays that favor suppliers with established clearing-agent networks. Lagos gym channels represent underdeveloped distribution nodes where formal retail consolidation has yet to concentrate purchasing power.
Egypt
Spray-dried encapsulation facilities in Cairo and Alexandria license European drying technology to produce heat-stable amino acid isolates. Domestic production decentralizes economics for regional manufacturers serving mid-market gym chains in Kuwait and Qatar. Egyptian facilities now compound climate-resilient powders that previously required refrigerated import from European suppliers.
Middle East and Africa Sports Nutrition Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers reformulate toward endurance-optimized matrices and halal-certified alternatives. The vendor base spans multinational nutrition conglomerates, regional pharmaceutical licensees, and specialized dairy processors with protein extraction expertise. Three strategic archetypes emerge: medical-nutrition credentialed players penetrating clinical-adjacent recovery, localized manufacturers exploiting duty advantages, and influencer-aligned lifestyle brands capturing subscription-driven replenishment. Capacity expansion in Egyptian and Moroccan spray-drying facilities and strategic partnerships with Gulf fitness platforms constitute the dominant competitive moves.
Within the medical-nutrition tier, Abbott anchors practitioner-endorsed positioning in UAE recovery segments where healthcare credentialing carries premium weight. Glanbia Plc exemplifies dairy-derived protein specialists supplying whey isolates favored by marathon communities in the Gulf states. Ascendis Health occupies a position among regional pharmaceutical licensees leveraging South African manufacturing to compress replenishment cycles. These three represent distinct archetypes rather than exhaustive market coverage, with each sitting within a differentiated competitive vector shaped by regulatory proximity and supply chain configuration.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Abbott |
| PepsiCo Inc. |
| Glanbia Plc |
| Herbalife Nutrition Ltd |
| GNC Holdings LLC |
| Amway Corporation |
| Bayer AG |
| Ascendis Health |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity in Egypt and Morocco widens labor-cost differentials against European dairy science programs, compressing pricing-tier spreads between locally compounded powders and refrigerated imports from Oceanian suppliers. This workforce geography anchors three-tier pricing structure across premium, standard, and economy levels as manufacturers arbitrage halal certification timelines and cold-chain investments.
Pricing Analysis
Input-cost pass-through from whey concentrate import dependency exposes margins to currency volatility at Jebel Ali and Durban ports, forcing price differentiation between SFDA-compliant labeled products and commodity imports. Premium tiers absorb cold-chain investments through subscription bundling in Dubai, while economy segments face pricing pressure from Egyptian spray-dried alternatives that displace refrigerated European supply. Fitness enthusiasts purchasing sustained-release proteins show lowest price sensitivity; casual consumers in Lagos gym channels exhibit highest.
Supply Chain Analysis
Halal certification gating through multiple non-mutually-recognized Gulf religious approval bodies fragments supplier qualification protocols, concentrating geographic supply in South Africa for NRCS-compliant manufacturing, Egypt for spray-drying technology licensing, and Morocco for amino acid isolate production. Raw material dependencies center on European whey concentrates, Oceanian dairy proteins, and regional fava and chickpea isolates. Tariff exposure at Nigerian ports with variable customs enforcement creates structural risk. Distribution runs through direct distributor relationships in underpenetrated markets and subscription platforms in affluent Gulf segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as geographic-arbitrage play between South Africa's localized manufacturing duty advantages and Gulf states' premium pricing power anchored by Dubai's wellness infrastructure and influencer-driven channels.
For Market Incumbents: To counter Egyptian and Moroccan spray-drying facilities decentralizing production economics, compress replenishment cycles through backward integration into regional dairy processing and lock in exclusive distributor relationships before formal retail consolidation in Lagos and Abuja. Prioritize MOHAP fast-track petition investments to accelerate novel ingredient launches versus Gulf Cooperation Council harmonization delays elsewhere. For New Entrants and Emerging Players: Casual female fitness enthusiasts in Riyadh and Jeddah represent underserved buyer archetype circumventing cultural friction around public supplement purchases through home delivery platforms. Penetrate Nigeria's underpenetrated gym channel through direct distributor relationships with established clearing-agent networks before retail consolidation concentrates purchasing power. Lead with subscription-based replenishment bundled with personalized macro coaching to capture lifetime value. For Investors and Strategic Acquirers: Regional pharmaceutical licensees with localized manufacturing footprints are the most active acquirer in this space, seeking spray-drying capacity and Gulf fitness platform partnerships. Long-term viability hinges on climate-resilient formulation IP and halal certification infrastructure spanning multiple jurisdictions. Watch for SFDA alignment with EFSA safety opinions accelerating versus delaying novel ingredient approvals as inflection indicator for premium product launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Dairy Processing | South African NRCS compliance and duty reduction compress margins against European import dependency. |
| Halal Certification Infrastructure Investment | Parallel audit track reduction accelerates product launches across multiple Gulf jurisdictions. |
| Spray-Drying Technology Licensing | Egyptian and Moroccan facilities displace refrigerated European supply through heat-stable amino acid encapsulation. |
| Subscription Platform Partnership | Dubai fitness platforms capture lifetime value through auto-shipped protein schedules bundled with coaching. |
| Direct Distributor Relationship in Nigeria | Lagos and Abuja gym channels reward first-mover advantage before retail consolidation concentrates power. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with sports nutrition formulators, regulatory affairs specialists at SFDA and MOHAP, gym chain procurement managers, and regional distribution channel partners combined with secondary validation from customs and trade data, NRCS enforcement records, EFSA safety opinion databases, and Gulf Cooperation Council technical regulation harmonization documents. This approach triangulates consumption patterns against manufacturing capacity and import flow data.
Historical trendline analysis of protein supplement and energy bar consumption patterns across fitness enthusiast, bodybuilder, athlete, and casual consumer segments informed projection modeling. Segmentation dimensions include product type, end-user training modality, distribution channel cold-chain requirements, and form factor heat stability. CAGRs derive from regression analysis of amateur endurance sports participation growth and halal-certified product penetration rates, with climate-specific degradation risk and regulatory petition timeline inputs shaping trajectory assumptions.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time Nigerian customs enforcement variability and Gulf halal certification body coordination introduce uncertainty bands around market entry timeline forecasts. Forecasts reflect documented assumptions regarding SFDA-EFSA alignment pace and spray-drying technology licensing diffusion. A model refresh is warranted upon material change in Gulf Cooperation Council technical regulation harmonization progress or South African NRCS contaminant threshold enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Creatine Market
Sports Nutrition
Japan Sports Drink Market