
 North America Protein Based Sports Drinks Market | 2026-2036
North America Protein Based Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protein Based Sports Drinks Market Insights
Canada is narrowing its production gap with expanded blending and bottling capacity near Toronto and Vancouver. PepsiCo, Inc. leverages its Gatorade manufacturing footprint to anchor protein-enhanced line extensions across mass retail channels. Abbott Laboratories sustains clinical credibility through its Ensure Sport positioning, competing directly in recovery-oriented segments. Protein2o Inc. specializes in clear protein water formulations, differentiating from traditional dairy-based competitors.
North America protein based sports drinks are formulated beverages delivering 10–30 grams of complete or hydrolyzed protein per serving, typically utilizing whey isolate, milk protein concentrate, or plant-based alternatives, manufactured through cold-fill aseptic processing or high-temperature short-time pasteurization to preserve bioactive peptide integrity. These products serve post-exercise muscle protein synthesis, meal replacement, and satiety management for active consumers. Ready-to-Drink formats dominate volume due to convenience-driven consumption patterns among time-constrained athletes and fitness enthusiasts. E-commerce channels represent the fastest-expanding distribution pathway, capturing subscription-based repeat purchases that bypass traditional retail slotting constraints.
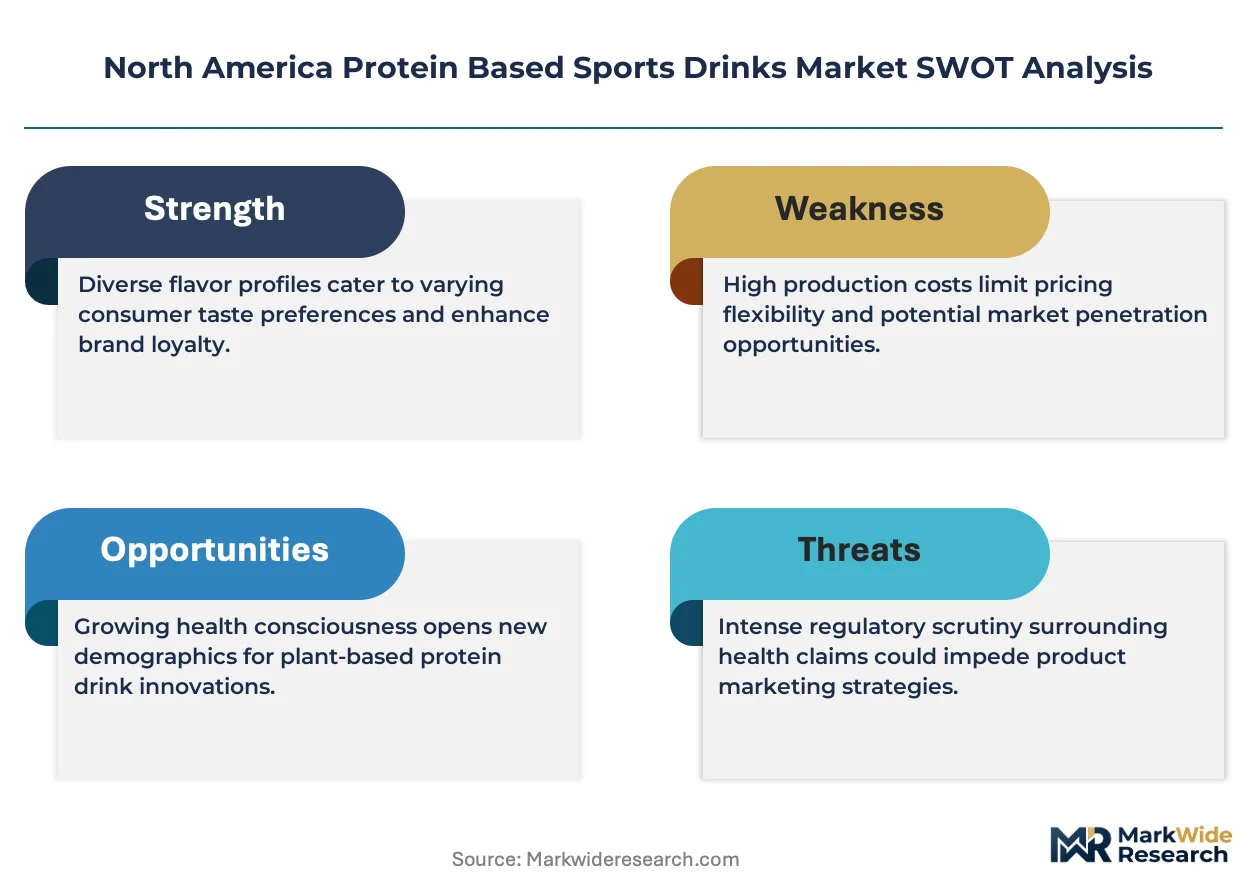
The FDA governs protein content accuracy through nutrition labeling regulations, while Health Canada mandates bilingual labeling and natural health product notifications for certain protein fortification claims. USDA organic certification and NSF Certified for Sport standards increasingly filter market access for premium-positioned entrants. Stakeholders must monitor evolving state-level sugar tax proposals and clean-label ingredient disclosure requirements that threaten reformulation cycles and margin structures.
Market Dynamics
FDA protein labeling enforcement is compressing formulation cycles as manufacturers recalibrate analytical verification protocols to meet stricter substantiation thresholds for content claims.
Growth Catalysts
- Collegiate Athletic Procurement:University athletic departments are expanding dedicated sports nutrition budgets, creating institutional demand for bulk recovery beverage contracts.
- Cold-Fill Aseptic Processing:This manufacturing method preserves bioactive peptide integrity in whey isolate formulations, extending shelf stability without thermal degradation.
- California Fitness Corridor Density:Metropolitan clusters in Los Angeles and San Francisco concentrate boutique gym memberships and premium protein consumption per capita.
Market Restraints
- Whey Protein Concentrate Volatility:Dairy commodity price swings directly compress margin structures for dairy-based formulation portfolios.
- Supply Concentration Risk:Domestic whey isolate production clusters heavily in Wisconsin and New York processing facilities, creating geographic vulnerability.
- Plant Protein Technical Limitations:Pea and rice protein isolates exhibit solubility challenges and off-flavor profiles that complicate clear beverage formulation.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Alberta represent underpenetrated markets with rising CrossFit affiliate density and limited local production capacity.
- Subscription E-Commerce Channel:Direct-to-consumer replenishment models bypass retail slotting fees and capture lifetime value through automated reordering.
- NSF Certified for Sport Tailwind:This third-party certification opens institutional procurement channels for collegiate and professional athletic programs requiring banned-substance screening.
Industry Challenges
- Peptide Chemistry Talent Scarcity:Formulation scientists with expertise in protein stability and flavor masking command premium compensation in a thin labor pool.
- Clean-Label Reformulation Timelines:Removing artificial sweeteners and stabilizers requires 18-24 month sensory testing cycles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protein Based Sports Drinks Market |
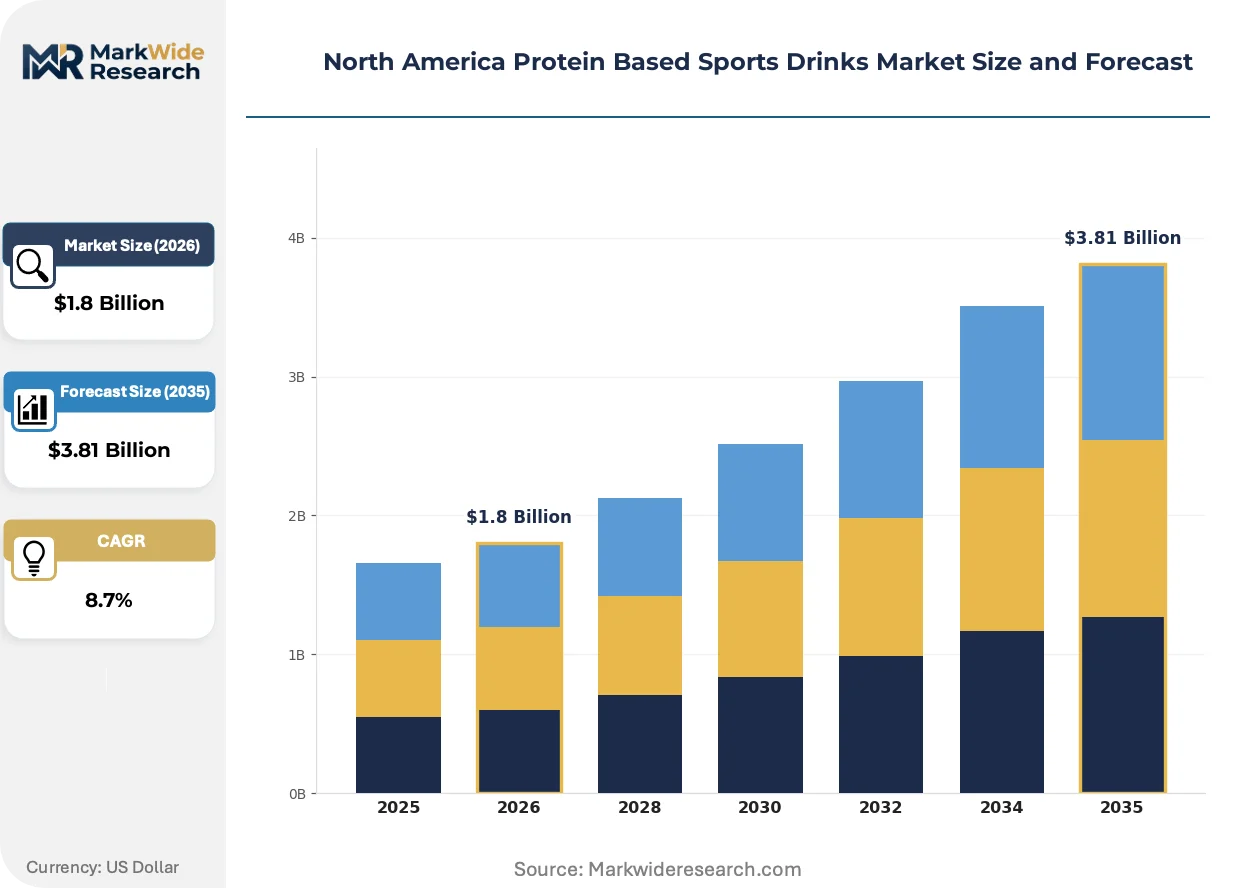
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Powder, Liquid Concentrate, Gel Distribution Channel: Supermarkets, Health Food Stores, E-commerce, Gyms End User: Athletes, Fitness Enthusiasts, Casual Users, Bodybuilders Flavor: Chocolate, Vanilla, Strawberry, Mixed Berry |
| Companies Covered | PepsiCo, Inc., Nestlé S.A., Abbott Laboratories, Protein2o Inc., The Vita Coco Company Inc., Danone S.A., BioSteel Sports Nutrition Inc., Premier Nutrition Co., BellRing Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protein Based Sports Drinks Market Trends and Innovations
Formulation science is collapsing the functional gap between dairy and plant proteins, while distribution infrastructure adapts to subscription-native consumption patterns.
Microfiltration technology is collapsing the taste-performance tradeoff in clear protein waters. Beverage developers at functional drink startups are adopting ceramic membrane filtration at pilot scale, enabling 20-gram protein loads in transparent, non-dairy formats. This process is collapsing the category boundary between sports nutrition and mainstream refreshment beverages.
FDA updated nutrition labeling requirements for protein content claims are forcing reformulation investments. Manufacturers must now verify protein quality through PDCAAS or DIAAS scoring methods rather than simple nitrogen content, raising analytical costs but filtering out substandard fortification. Ready-to-drink brands targeting mass retail are most affected, accelerating partnerships with third-party testing laboratories.
Subscription-based replenishment is displacing impulse retail purchasing among committed fitness enthusiasts. Dedicated athletes in Texas and Florida metropolitan markets are locking into 30-day auto-ship programs, bypassing traditional grocery and convenience store channels. This behavioral shift concentrates customer lifetime value with direct brands while eroding slotting-fee-dependent distribution economics for legacy players.
North America Protein Based Sports Drinks Market Segmentation
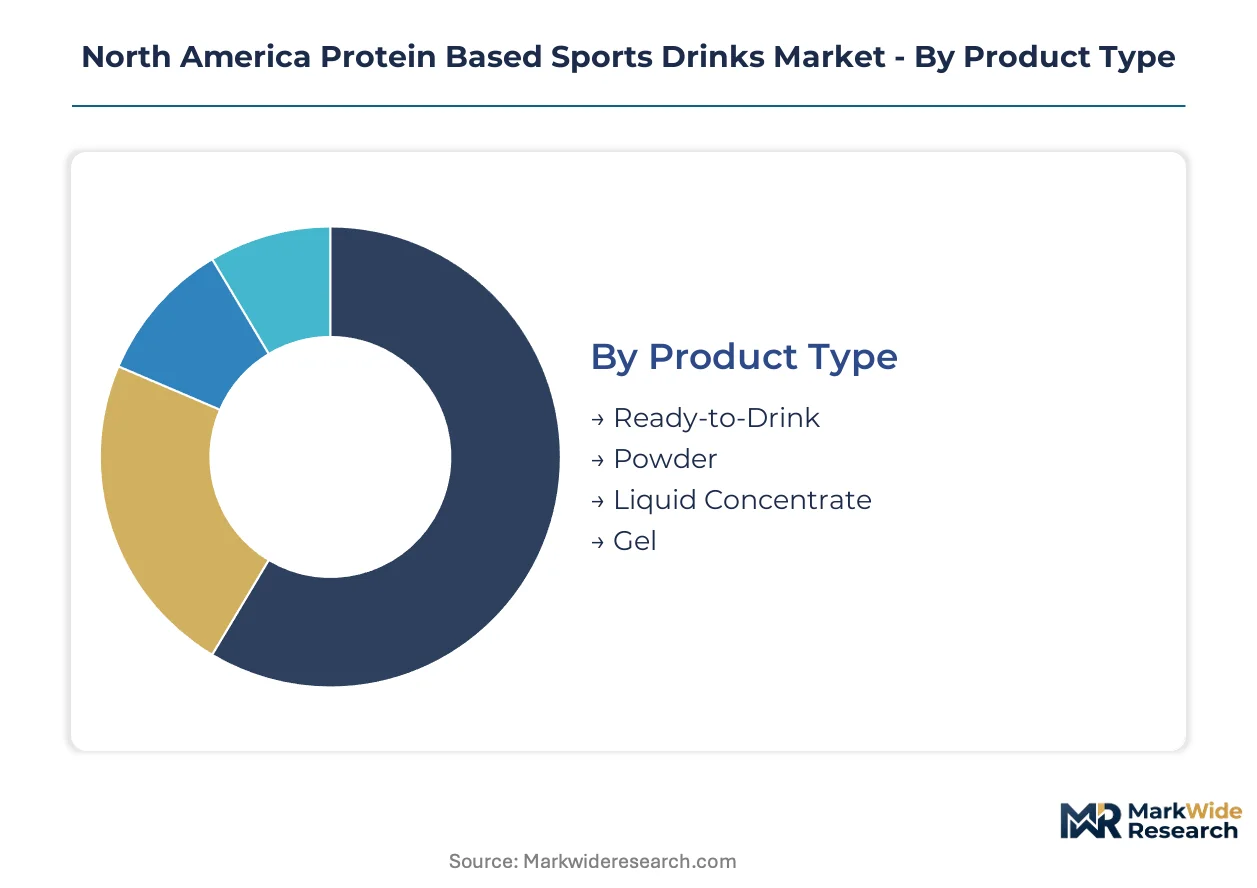
Segmentation in protein sports drinks reveals divergent velocity patterns across consumption formats and purchase channels. Ready-to-drink formats turn inventory fastest through convenience-driven replenishment, while powder segments exhibit slower cycles tied to bulk purchasing behavior. Understanding these temporal dynamics shapes inventory deployment and margin capture strategies.
Product Type:
Cycle times vary dramatically across formats, with single-serve ready-to-drink products rotating weekly through cold-chain retail while powder formats sit in pantry stockpiles for months.
- Ready-to-Drink:Pre-mixed beverages in shelf-stable or refrigerated formats deliver 15-30 grams protein per 12-16 ounce serving. Demand concentrates in California and Texas metropolitan fitness corridors where time-constrained athletes prioritize grab-and-go convenience over preparation overhead. Cold-fill aseptic processing preserves peptide bioactivity but constrains production flexibility.
- Powder:Dry concentrate requiring water or milk reconstitution offers cost-per-gram protein advantages and extended shelf stability. Bodybuilders and collegiate athletic programs in the US Midwest bulk-procure multi-pound containers, stretching purchase intervals to 60-90 days. Scoop-based dosing allows precise macronutrient targeting unavailable in pre-mixed alternatives.
- Liquid Concentrate:Reduced-volume formulations requiring dilution before consumption occupy niche positioning between convenience and economy. Health food store distribution in Vancouver and Toronto clusters supports this format's limited penetration.
- Gel:Viscous semi-liquid formats engineered for rapid gastric emptying during endurance exercise. Marathon training collectives in Florida represent concentrated demand pockets for this portability-optimized segment.
Ready-to-drink dominates installed base. Powder is where expansion concentrates among price-sensitive volume consumers.
Distribution Channel:
Channel economics separate by working capital intensity, with e-commerce absorbing inventory risk through subscription models while brick-and-mortar demands slotting fee investments and turns velocity.
- Supermarkets:Mass retail placement through Kroger, Walmart, and Safeway networks delivers impulse exposure but demands trade promotion spending and refrigerated shelf space premiums. Turn rates in Texas and Florida exceed national averages due to year-round athletic activity patterns.
- Health Food Stores:Specialty retailers like Whole Foods and Sprouts curate premium-positioned SKUs with organic and clean-label certifications. Staff consultation drives higher attachment rates for protein education-dependent purchasers in California wellness corridors.
- E-commerce:Direct-to-consumer and Amazon marketplace channels bypass retail margin stacking through subscription auto-ship programs. Customer lifetime value concentration is climbing the fastest in this channel as Texas and Florida metropolitan athletes lock into 30-day replenishment cycles.
- Gyms:Point-of-sweat placement through Equinox, LA Fitness, and CrossFit affiliate networks captures consumption immediacy post-workout. Limited SKU breadth and refrigerated storage constraints restrict format selection primarily to ready-to-drink.
Supermarkets anchor volume throughput. E-commerce is where margin expansion concentrates.
End User:
User sophistication tiers separate by protein literacy, nutritional tracking discipline, and willingness to trade preparation time against cost efficiency.
- Athletes:Collegiate and professional competitors with institutional procurement support demand NSF Certified for Sport verification and batch-tested banned substance screening. University athletic departments in California and Texas are expanding dedicated sports nutrition budgets for this segment.
- Fitness Enthusiasts:Regular gym attendees with structured training programs represent the commercial core, balancing convenience preferences against macronutrient precision. Los Angeles and San Francisco boutique gym density concentrates per-capita consumption here.
- Casual Users:Intermittent exercisers and meal-replacement seekers prioritize palatability and accessibility over performance optimization. This segment exhibits highest trial-to-discontinuation rates and drives flavor innovation cycles.
- Bodybuilders:Physique competitors and hypertrophy-focused lifters demand protein density exceeding 25 grams per serving with minimal carbohydrate contamination. Powder formats dominate this specification-driven segment through cost-efficient bulk purchasing.
Fitness enthusiasts dominate installed base. Athletes represent the steepest expansion trajectory through institutional procurement growth.
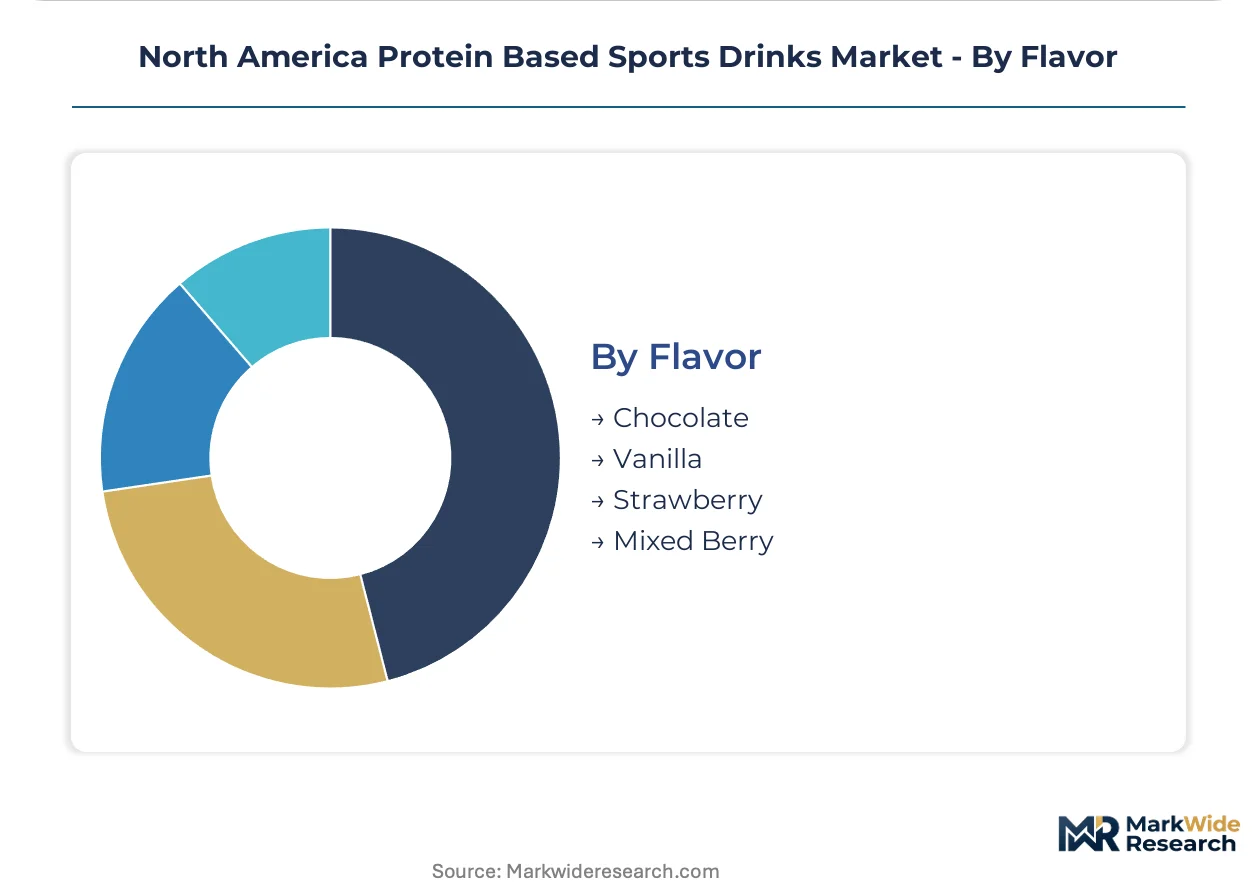
Flavor:
Flavor development cycles track sensory fatigue patterns, with core varieties sustaining baseline volume while limited releases drive trial and social media engagement.
- Chocolate:Cocoa-based formulations leveraging alkalized powder or natural cacao deliver masking properties that neutralize whey protein off-notes. This variety sustains highest baseline velocity across all distribution channels.
- Vanilla:Neutral canvas supporting mix-in customization with fruit, nut butters, or coffee. Versatility positioning captures consumers seeking variety without multiple SKU purchases.
- Strawberry:Fruit-forward profiles utilizing natural or nature-identical flavor systems. Summer seasonal velocity spikes in Florida and Southern California exceed winter baselines significantly.
- Mixed Berry:Polyphenol-rich blends targeting antioxidant positioning alongside protein delivery. Health food store distribution in Vancouver and Toronto shows disproportionate preference for this variety.
Chocolate anchors volume consistency. Mixed berry is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA protein labeling enforcement and Health Canada bilingual notification requirements create distinct compliance environments across the continent. Metropolitan fitness corridors concentrate demand while regional production capacity expands to match.
United States
California, Texas, and Florida metropolitan clusters drive per-capita consumption through year-round athletic activity patterns. FDA updated nutrition labeling requirements mandate PDCAAS or DIAAS scoring for protein content claims, raising analytical verification costs for manufacturers targeting mass retail. Cold-fill aseptic processing facilities in Wisconsin and New York supply whey isolate formulations to institutional buyers.
Canada
Health Canada mandates bilingual labeling and natural health product notifications for protein fortification claims above threshold levels. Expanded blending and bottling capacity near Toronto and Vancouver narrows the production gap with US supply. Saskatchewan and Alberta prairie markets exhibit rising CrossFit affiliate density with limited local manufacturing presence.
Mexico
Central Mexican manufacturing zones serve as export platforms for US-bound contract production. COFEPRIS nutrition labeling standards align partially with FDA frameworks, simplifying cross-border formulation strategies. Monterrey and Guadalajara industrial corridors host toll-processing operations for ready-to-drink beverage brands.
North America Protein Based Sports Drinks Market Competitive Landscape
Multinational beverage conglomerates and specialized sports nutrition firms split the market along convenience versus clinical credibility vectors. Three strategic archetypes dominate: mass-market refreshment brands leveraging existing distribution infrastructure, clinical nutrition specialists emphasizing recovery science positioning, and agile direct-to-consumer startups exploiting subscription channel economics. Capacity expansion and NSF certification acquisition represent the dominant competitive moves as players vie for collegiate athletic procurement contracts.
Within the mass-market tier, PepsiCo, Inc. and Nestlé S.A. exemplify scale-driven distribution leverage. Abbott Laboratories occupies a clinical credibility position through recovery-oriented formulation science. Protein2o Inc. represents the direct-to-consumer specialist archetype with clear protein water differentiation. These three anchors illustrate the strategic spectrum from refreshment convenience through medical-grade positioning to niche format innovation.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Nestlé S.A. |
| Abbott Laboratories |
| Protein2o Inc. |
| The Vita Coco Company Inc. |
| Danone S.A. |
| BioSteel Sports Nutrition Inc. |
| Premier Nutrition Co. |
| BellRing Brands Inc. |
| Others |
Pricing and Supply Chain Analysis
Wisconsin and New York whey isolate processing clusters concentrate upstream supply leverage, anchoring margin capture downstream with ready-to-drink brands while compressing economics for dairy-dependent portfolios. Cold-fill aseptic capacity scarcity in these states amplifies pricing power for contract manufacturers serving NSF-certified institutional buyers.
Pricing Analysis
California and Texas metropolitan corridors command 15-20% shelf price premiums over Midwest mass retail, reflecting cold-chain logistics costs and boutique gym density concentration. Three-tier pricing structure across premium NSF-certified, standard mass-market, and economy private-label levels dominates the landscape. Pricing pressure stems from Health Canada bilingual labeling compliance costs and FDA PDCAAS verification investments. Casual users exhibit highest price elasticity, while collegiate athletic procurement shows lowest sensitivity due to institutional budget insulation.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for whey protein concentrate suppliers financing working capital gaps across the dairy commodity cycle. Wisconsin, New York, and Idaho anchor North American whey isolate production, drawing from Midwest dairy cooperative networks. Supply chain risk centers on single-source vulnerability at Wisconsin microfiltration facilities. Distribution runs through refrigerated trucking networks serving California, Texas, and Florida fitness corridors with 48-hour freshness windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around subscription-native consumption patterns displacing legacy slotting-fee economics, creating white-space for agile direct-to-consumer entrants between mass-market refreshment and clinical recovery positioning.
For Market Incumbents: Build certification moats through NSF Certified for Sport acquisition and cold-fill aseptic capacity expansion in Wisconsin or New York to defend against plant-protein substitutes and direct-to-consumer subscription brands eroding retail channel control. Backward integration into whey isolate toll-processing secures supply priority during dairy commodity volatility cycles. For New Entrants and Emerging Players: Pursue Saskatchewan and Alberta prairie markets where CrossFit affiliate density rises without local production capacity, leveraging direct-to-consumer auto-ship models to bypass refrigerated retail slotting fees entirely. Clear protein water formulations utilizing ceramic membrane filtration offer the most penetrable format differentiation against dairy-incumbent taste profiles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer brands holding subscription customer lifetime value concentration in Texas and Florida metropolitan markets. Five-to-ten year viability hinges on cold-chain logistics network control and formulation talent retention. Monitor FDA enforcement actions on protein content claims as inflection signal for compliance-cost driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certified for Sport Acquisition | Opens institutional procurement channels for collegiate athletic programs requiring banned-substance screening protocols. |
| Cold-Fill Aseptic Capacity Expansion | Preserves bioactive peptide integrity in whey formulations while extending shelf stability without thermal degradation damage. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and captures automated replenishment revenue from Texas and Florida fitness enthusiasts. |
| Ceramic Membrane Filtration Adoption | Enables transparent 20-gram protein loads in plant-based clear waters collapsing category boundaries with refreshment beverages. |
| Canadian Prairie Distribution Buildout | Addresses rising CrossFit affiliate density in Saskatchewan and Alberta with limited local manufacturing presence currently. |
Research Methodology
Cross-validation between regulatory filing analysis and channel inventory audits anchors the qualitative findings in this study. Primary interviews with formulation scientists at beverage manufacturers, procurement directors at collegiate athletic departments, category buyers at mass retailers, and supply planners at dairy processing cooperatives combined with secondary validation through FDA warning letter databases, Health Canada natural health product notifications, USDA organic certification records, and Nielsen retail audit data. Bottom-up volume modeling and top-down value reconciliation triangulate market sizing across the projection horizon.
Calibration against historical protein commodity price cycles and subscription channel adoption curves in adjacent functional beverage categories shaped the analytical framework. Segmentation dimensions modeled include product format, distribution channel, end-user sophistication tier, and flavor profile across the analysis window. CAGRs derived from weighted average of category velocity trends and per-capita consumption elasticity in California, Texas, and Florida metropolitan fitness corridors. Forecast inputs incorporated collegiate athletic budget expansion rates and cold-chain logistics capacity constraints.
Sensitivities concentrate around FDA enforcement intensity on protein content claims, whey protein concentrate commodity volatility, and subscription churn rates in direct-to-consumer channels. Forecasts reflect documented assumptions on institutional procurement growth and plant-protein solubility technology advancement. Macroeconomic contraction affecting discretionary fitness spending, regulatory deviation in Health Canada notification requirements, or breakthrough clear-format plant protein formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
L-Carnitine Supplements Market