
 Europe Sports Nutrition Market | 2026-2036
Europe Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports Nutrition Market Analysis
Germany is fragmenting as new production capacity enters the European sports nutrition landscape, with contract manufacturers expanding whey processing facilities in Bavaria and North Rhine-Westphalia. Glanbia PLC leverages its dairy ingredient supply chain to sustain cost advantages across protein powder lines. The Hut Group competes through direct-to-consumer platform control, while Science in Sport plc specializes in endurance-focused formulations that anchor its presence within professional cycling and triathlon channels.
Europe sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, or body composition, typically containing protein isolates, branched-chain amino acids, creatine monohydrate, or caffeine complexes at specified dosages. These products serve competitive athletes, fitness enthusiasts, and recreational users seeking measurable physiological outcomes from structured training regimens. Protein powders occupy the largest margin pool due to ingredient scale economies and repeat purchase frequency, while vegan formulations represent the fastest-growing segment as pea and rice protein extraction technologies mature. Online retail channels are displacing specialty stores for initial discovery, though health food stores retain loyalty among consumers seeking in-person formulation guidance.
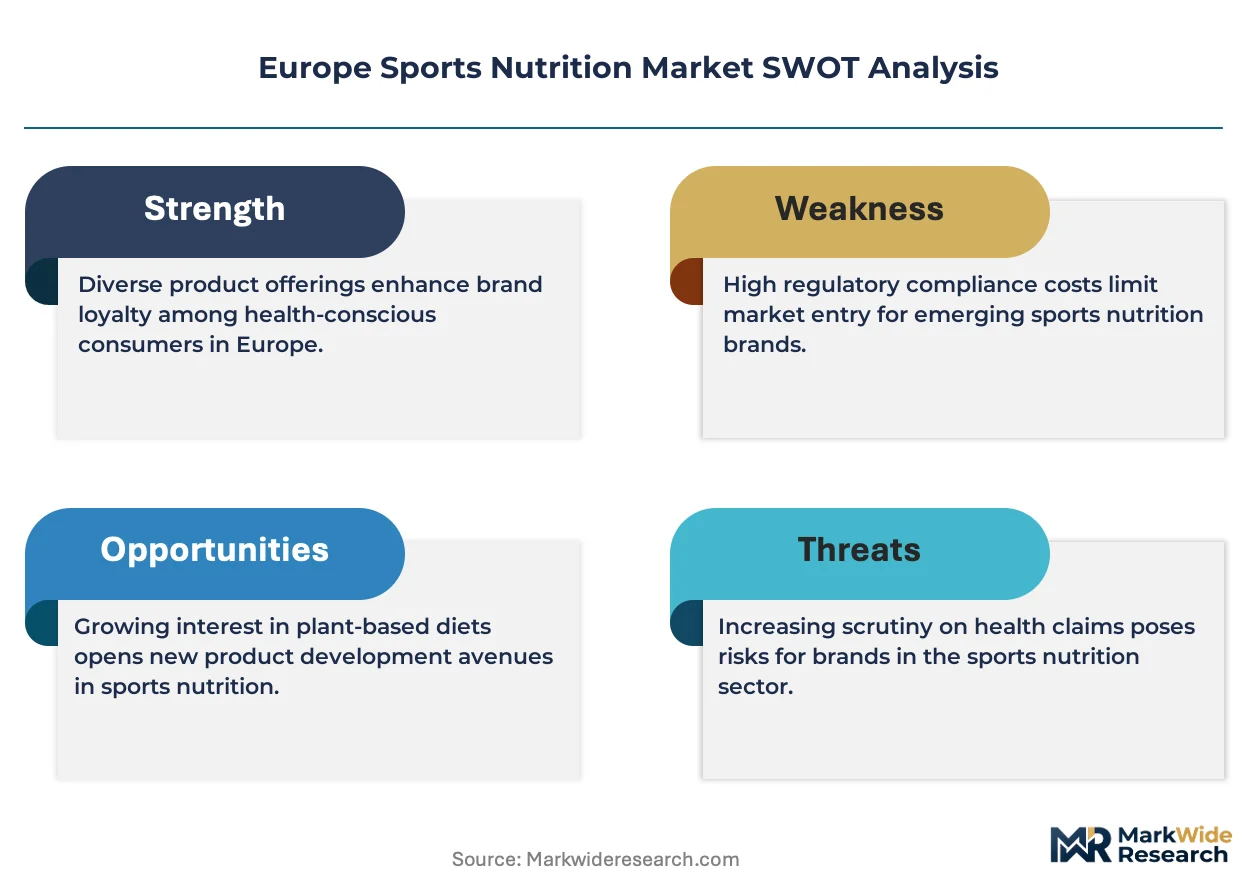
EFSA evaluates all novel food ingredients and health claims before products enter EU markets, creating a compliance bottleneck that favors established players with dedicated regulatory affairs teams. EMA frameworks for contaminant testing and REACH chemical safety standards further constrain formulation flexibility and supplier qualification. France enforces additional national restrictions through ANSM oversight of stimulant-containing supplements. Stakeholders must monitor evolving EU packaging sustainability rules and plant protein labeling requirements to anticipate reformulation costs and channel strategy adjustments.
Market Dynamics
EFSA novel food assessments and EU health claims regulations are compressing product development timelines while concentrating competitive advantage among firms with dedicated regulatory affairs infrastructure. This compliance bottleneck favors established players capable of navigating multi-year approval cycles for innovative ingredients.
Growth Catalysts
- Professional cycling and football demand:Elite teams in France, Italy, and Spain drive adoption of tailored recovery formulations with specified branched-chain amino acid ratios. These institutional buyers validate premium positioning for mass-market extensions.
- REACH chemical safety standards:Harmonized contaminant testing protocols reduce supplier qualification friction across member states, enabling faster scale-up for contract manufacturers meeting ECHA thresholds.
- Pea and rice protein extraction maturation:Improved solubility and amino acid completeness in plant isolates unlocks formulation parity with whey for vegan product lines.
Market Restraints
- Whey concentrate input volatility:Dairy commodity price swings in Bavaria and North Rhine-Westphalia compress margin predictability for protein powder producers dependent on regional whey processing.
- ANSM stimulant oversight:France's national restrictions on caffeine complexes and synephrine-containing supplements create fragmented compliance requirements within the single market.
- EFSA health claims backlog:Novel ingredient assessments averaging 18-24 months delay revenue recognition for innovative formulations.
Strategic Opportunities
- Poland and Romania penetration:Underdeveloped specialty retail infrastructure in these markets offers first-mover advantage for direct-to-consumer platform entry.
- EU packaging sustainability rules:Anticipated mandates for recyclable mono-material sachets create reformulation partnerships with flexible packaging converters ahead of compliance deadlines.
- Telehealth integration:Sports dietitian platforms in Germany and the Netherlands are emerging as prescription channels for medical-grade recovery nutrition.
Industry Challenges
- Regulatory affairs talent scarcity:EFSA submission expertise concentrates among senior consultants in Brussels and Amsterdam, inflating personnel costs for mid-tier firms.
- Legacy ERP integration:Batch traceability requirements under EU food law force expensive upgrades for manufacturers running outdated quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports Nutrition Market |
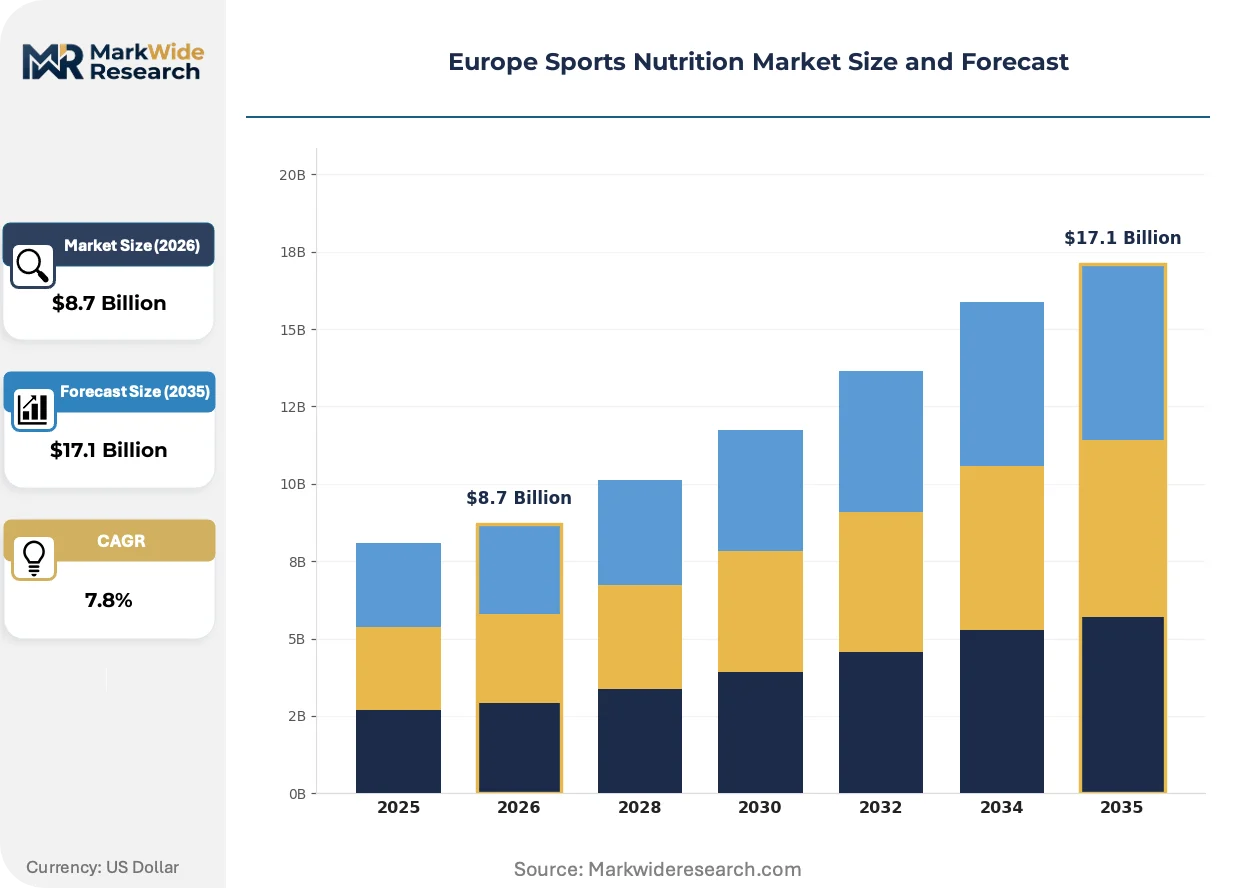
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Amino Acid Supplements, Pre-Workout Supplements Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores Target Consumer: Professional Athletes, Amateur Athletes, Fitness Enthusiasts, Recreational Users Formulation: Vegan, Whey Protein, Casein Protein, Hydrolyzed Protein |
| Companies Covered | Glanbia PLC, PepsiCo Inc., Nestle SA, Abbott Laboratories, The Hut Group, Herbalife Nutrition Ltd., Post Holdings Inc., Science in Sport plc, Grenade UK Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports Nutrition Market Emerging Trajectories
Precision fermentation and enzymatic hydrolysis are compressing ingredient development cycles while reshaping supplier relationships across the European sports nutrition value chain. These biotechnologies are altering competitive positioning in protein sourcing.
Precision fermentation of whey proteins without dairy agriculture is rendering obsolete traditional whey processing dependencies for premium positioning. Clean-label startups in Denmark and the Netherlands are adopting these ingredients at pilot scale. This technology is compressing the sustainability premium that previously justified plant protein price gaps.
CSRD sustainability disclosure requirements are mandating Scope 3 emissions reporting for ingredient suppliers. Large formulation houses must now audit dairy and plant protein farms across their supply bases. German and French brands with retail listings in major supermarket chains face the most immediate compliance pressure.
Subscription-based replenishment models are capturing repeat purchase loyalty previously held by health food stores. Fitness enthusiasts in the United Kingdom and Sweden are migrating to automated delivery for protein powders and creatine monohydrate. This channel shift is most visible among consumers under 35 purchasing through mobile-optimized platforms.
Europe Sports Nutrition Market Segmentation
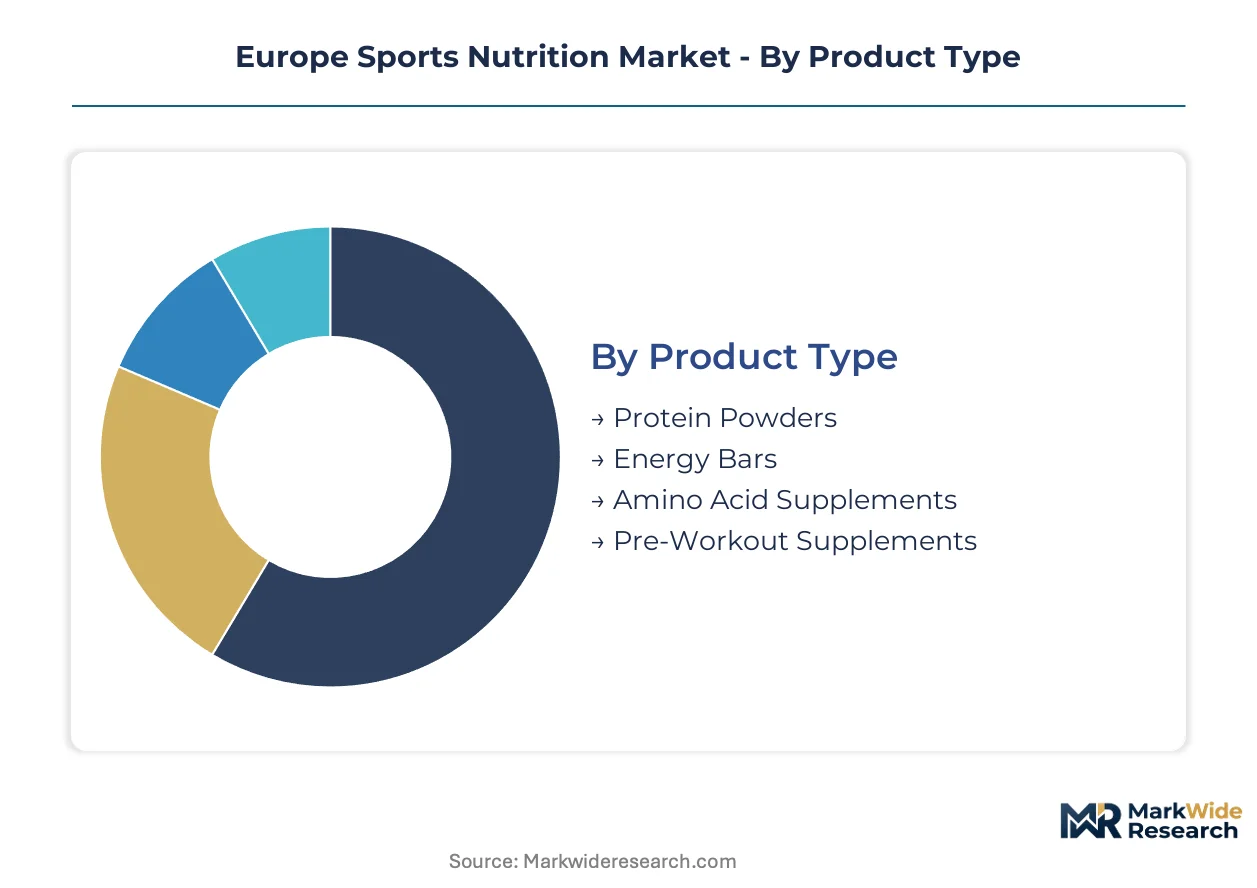
Segmentation in the Europe Sports Nutrition Market reveals distinct profit pools and regulatory exposure profiles across product formats and consumer tiers. Manufacturers optimize R&D allocation and channel strategy by matching formulation investments to specific purchasing behaviors and compliance thresholds.
Product Type:
Cost tier differentiation across product formats determines margin structure and repeat purchase economics for European manufacturers.
- Protein Powders:Concentrated isolates and concentrates deliver 20-30g protein per serving with established whey and emerging plant-based variants. German and UK fitness enthusiasts drive volume through subscription replenishment, though whey concentrate input volatility in Bavaria compresses margin predictability for mid-tier brands.
- Energy Bars:Shelf-stable carbohydrate-protein matrices formulated for portability and glycemic control during endurance activity. Professional cycling teams in France and Italy validate premium positioning, creating brand halo effects for mass-market extensions through retail pharmacy channels.
- Amino Acid Supplements:Branched-chain and essential amino acid isolates targeting muscle protein synthesis signaling.
- Pre-Workout Supplements:Caffeine complexes and nitric oxide precursors with stimulant content subject to ANSM oversight in France.
Protein powders command the established base. The steepest expansion runs through energy bars.
Distribution Channel:
Application-specific purchasing contexts shape channel profitability and customer acquisition costs across European markets.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with mobile-optimized subscription interfaces. UK and Swedish consumers under 35 migrate fastest to automated delivery for creatine and protein replenishment, displacing specialty store discovery for initial purchases.
- Specialty Stores:Dedicated sports nutrition retailers with staffed consultation and sampling infrastructure. German consumers seeking formulation guidance sustain loyalty here despite online price competition, particularly for novel ingredient introductions requiring education.
- Supermarkets:Mass-market shelf placement for established brands with EFSA-approved health claims.
- Health Food Stores:Natural and organic positioning with vegan formulation emphasis in Netherlands and Denmark.
Online retail captures volume growth. Health food stores retain margin premium through advisory services.
Target Consumer:
Volume concentration varies dramatically by training intensity and institutional purchasing power within European markets.
- Professional Athletes:Institutional buyers with specified nutritional protocols and batch testing requirements. Elite football clubs and cycling teams in Spain and Italy drive adoption of tailored recovery formulations with validated branched-chain amino acid ratios, anchoring premium positioning for downstream consumer extensions.
- Amateur Athletes:Competitive recreational participants with structured training regimens and event-specific nutrition planning.
- Fitness Enthusiasts:Regular gym attendees with discretionary spending on physique and performance optimization.
- Recreational Users:Occasional exercisers seeking convenience and general wellness positioning.
Professional athletes anchor premium pricing. Fitness enthusiasts deliver the broadest volume base.
Formulation:
Customer type alignment with dietary preference and digestibility requirements drives formulation R&D allocation.
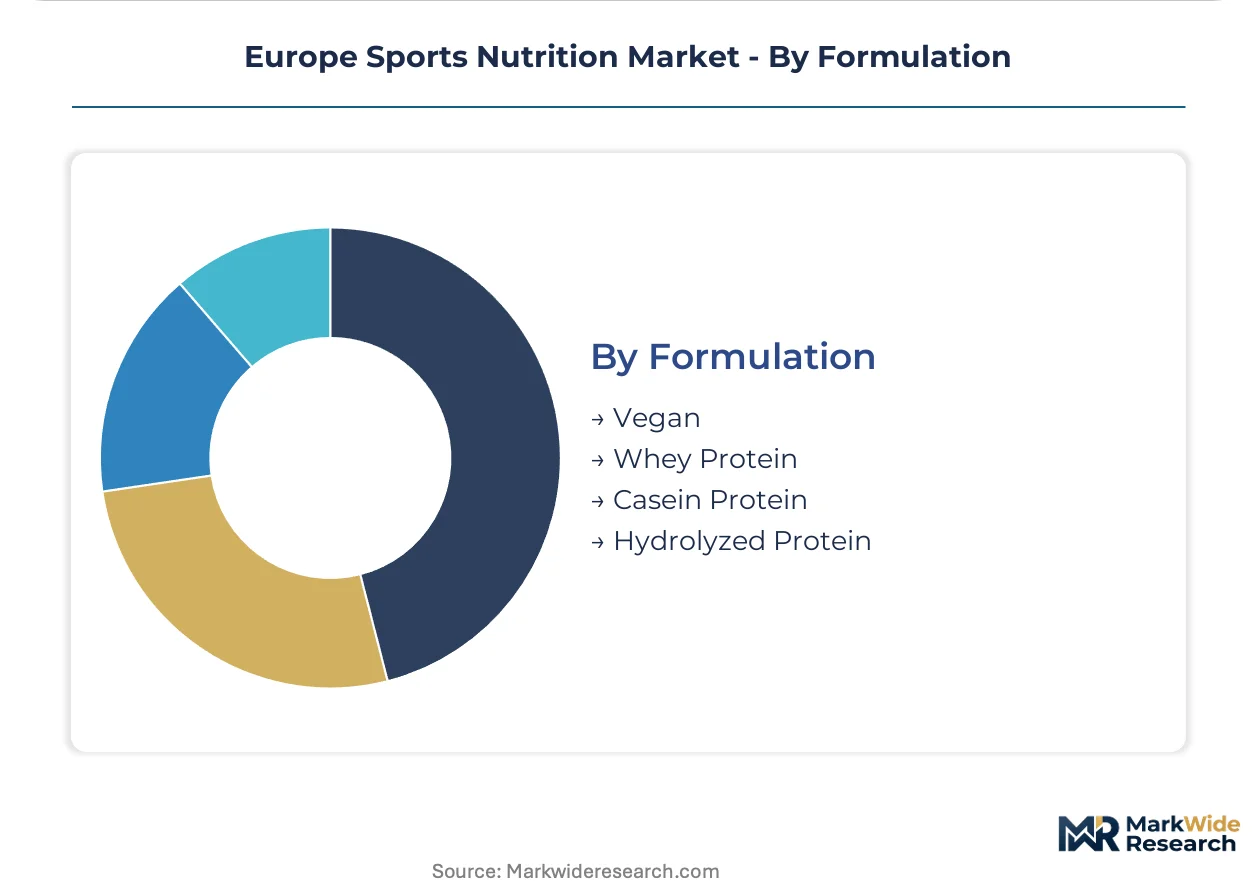
- Vegan:Pea, rice, and fava bean protein isolates with enzymatic processing for amino acid completeness. Improved solubility technologies unlock formulation parity with whey, expanding fastest among Danish and Dutch clean-label startups responding to CSRD sustainability disclosure pressures.
- Whey Protein:Rapid-absorption concentrates and isolates from dairy processing with established supply chains.
- Casein Protein:Slow-release micellar structures for overnight recovery applications.
- Hydrolyzed Protein:Enzymatically pre-digested peptides for reduced allergenicity and faster gastric emptying.
Whey protein maintains the volume foundation. Vegan formulations are climbing the fastest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments anchor regulatory complexity across the European sports nutrition landscape, compressing product development timelines and concentrating competitive advantage among firms with dedicated compliance infrastructure in Brussels-adjacent clusters.
Germany
Professional football clubs and elite cycling teams drive institutional demand for tailored recovery formulations with specified branched-chain amino acid ratios. The country's national pharmaceutical regulator enforces strict contaminant testing protocols that exceed baseline EU requirements. Bavaria and North Rhine-Westphalia host expanding whey processing facilities where contract manufacturers are scaling production capacity.
United Kingdom
Fitness enthusiasts under 35 migrate fastest to automated subscription delivery for protein powders and creatine monohydrate through mobile-optimized platforms. REACH chemical safety standards harmonize supplier qualification across the single market. Greater London anchors direct-to-consumer platform control, with The Hut Group leveraging digital infrastructure for customer acquisition.
France
ANSM oversight of stimulant-containing supplements creates fragmented compliance requirements for pre-workout formulations with caffeine complexes. Professional cycling teams validate premium positioning for mass-market extensions through retail pharmacy channels. The Île-de-France region concentrates regulatory affairs expertise and formulation R&D for endurance-focused products.
Italy
Elite football institutions specify nutritional protocols that anchor premium pricing for downstream consumer extensions. EU health claims regulations shape product development cycles with multi-year approval timelines for innovative ingredients. The Lombardy and Emilia-Romagna clusters concentrate specialty retail infrastructure and sports dietitian networks.
Netherlands
Clean-label startups respond to CSRD sustainability disclosure pressures with pea and rice protein extraction technologies. Improved solubility in plant isolates unlocks formulation parity with whey for vegan product lines. The Randstad region hosts precision fermentation pilots that compress ingredient development cycles without dairy agriculture dependencies.
Europe Sports Nutrition Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where regulatory affairs expertise and dairy supply chain control define competitive positioning. Established players with dedicated EFSA submission teams capture novel ingredient first-mover benefits, while scale-driven operators leverage whey processing volume for cost leadership. Three archetypes dominate: dairy-integrated ingredient suppliers, direct-to-consumer platform operators, and endurance-specialized formulation houses. M&A activity targets regulatory affairs talent acquisition, and capacity expansion concentrates in Bavaria and North Rhine-Westphalia processing clusters.
Among dairy-integrated multinationals, Glanbia PLC exemplifies supply chain control through captive whey processing infrastructure. Direct-to-consumer platform operators include The Hut Group, which occupies a position defined by digital customer acquisition rather than manufacturing ownership. Science in Sport plc represents the endurance-specialized tier, anchoring its presence within professional cycling and triathlon channels where institutional validation drives premium positioning.
| Leading Market Players |
|---|
| Glanbia PLC |
| PepsiCo Inc. |
| Nestle SA |
| Abbott Laboratories |
| The Hut Group |
| Herbalife Nutrition Ltd. |
| Post Holdings Inc. |
| Science in Sport plc |
| Grenade UK Ltd. |
| Others |
Supply Flow & Price Mechanics
Whey concentrate input volatility in Bavaria and North Rhine-Westphalia compresses margin predictability for protein powder producers while simultaneously widening spreads between economy-tier whey formulations and precision-fermented premium isolates. This commodity exposure dictates both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of contract manufacturing capacity near dairy processing infrastructure.
Pricing Analysis
Price spreads between German and Romanian retail channels exceed those observed in Western European markets due to fragmented distribution infrastructure and divergent VAT treatment of sports nutrition products. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated health claim products from generic formulations and private-label alternatives. Cost compression in the standard tier is intensifying because contract manufacturers in Poland and Romania are scaling whey processing capacity. Fitness enthusiasts under 35 demonstrate highest price sensitivity, while professional cycling teams and football clubs exhibit lowest sensitivity due to institutional procurement protocols.
Supply Chain Analysis
Contract manufacturers in Bavaria and North Rhine-Westphalia hold dominant whey processing capacity, with Glanbia PLC leveraging captive dairy infrastructure for cost leadership. Raw material sourcing draws from Irish and Dutch dairy cooperatives for whey isolates, while pea protein extraction feeds from French and Belgian agricultural processors. Single-source vulnerability concentrates in precision fermentation startups dependent on Danish and Dutch pilot facilities. Distribution runs through direct-to-consumer platforms for subscription replenishment, though German specialty retailers retain batch-traceable procurement channels for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation threatens to obsolete traditional whey processing cost structures, forcing incumbents to defend formulation differentiation while new entrants exploit geographic white space.
For Market Incumbents: Build regulatory affairs moats by acquiring EFSA submission expertise concentrated in Brussels-adjacent consultant networks. Anchor premium positioning through exclusive supply agreements with precision fermentation pilots in the Netherlands and Denmark. Defend against plant protein substitution by accelerating enzymatic hydrolysis R&D for whey peptide differentiation. For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania where specialty retail infrastructure remains underdeveloped and direct-to-consumer platform penetration lags Western Europe. Target amateur cycling and triathlon segments with subscription-based recovery formulations validated through regional race partnerships. Pursue telehealth integration with German sports dietitian platforms as a prescription channel bypass. For Investors and Strategic Acquirers: EFSA novel food approval acceleration reshapes the acquisition landscape toward targets with validated ingredient dossiers and established Brussels regulatory relationships. Long-term viability centers on supply chain decarbonization credentials under CSRD disclosure mandates. Monitor precision fermentation scale-up announcements as the signal indicating commodity whey margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Danish and Dutch pilot facilities compress dairy-free protein development cycles without agricultural land constraints. |
| EFSA Health Claim Submission | Novel ingredient approvals averaging 18-24 months create first-mover exclusivity windows for validated formulations. |
| Direct-to-Consumer Platform Expansion | Mobile-optimized subscription interfaces capture UK and Swedish consumers under 35 from specialty retail channels. |
| CSRD Supply Chain Audit | German and French supermarket-listed brands face immediate Scope 3 emissions reporting pressure on dairy and plant protein farms. |
| Telehealth Channel Integration | Sports dietitian platforms in Germany and the Netherlands emerge as prescription channels for medical-grade recovery nutrition. |
Methodological Framework
A standing panel of sports nutrition brand managers, contract manufacturing procurement leads, EFSA regulatory affairs consultants, and elite team nutritionists provided ongoing calibration across the study period. Primary interviews with formulation scientists at whey processing facilities in Bavaria and specialty retail buyers in Lombardy were triangulated against secondary validation from EFSA novel food registers, REACH chemical safety filings, and EU customs trade data for protein isolate imports. Bottom-up demand modeling across consumer segments was reconciled with top-down value chain analysis.
Scenario-bracketing framed projections across the analysis window by modeling demand sensitivity to EFSA approval timelines, dairy commodity price bands, and precision fermentation scale-up trajectories. Segmentation dimensions included product format, distribution channel, target consumer tier, and formulation type. CAGRs were derived from volume trajectory analysis incorporating repeat purchase frequency data and channel shift elasticities. Forecast inputs included professional team procurement contract renewal cycles and CSRD compliance cost pass-through assumptions.
Sensitivities concentrate around EFSA health claims backlog resolution, whey concentrate price volatility in German dairy regions, and precision fermentation yield improvements. Forecasts reflect assumptions regarding regulatory approval cadence and substitution elasticity between dairy and plant proteins. Quarterly review of EFSA novel food register updates, ECHA contaminant threshold revisions, and CSRD implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Weight Management Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Creatine Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
United States Sports Nutrition Market