
 Creatine Market | 2026-2036
Creatine Market Size, Share, and Industry Trends Forecast 2026-2036
Creatine Market Intelligence
The historical dominance of the hardcore bodybuilder archetype is unwinding as Everyday Consumers and general fitness enthusiasts enter the market for wellness and cognitive benefits. AlzChem AG specializes in high-purity creatine monohydrate with its Creapure® brand, targeting quality-conscious segments. In contrast, major consumer brands like Optimum Nutrition and Myprotein leverage extensive distribution networks and online retail channels to reach a broader, more diverse customer base.
Creatine is a nitrogenous organic acid that facilitates the recycling of adenosine triphosphate (ATP), the primary energy currency of the cell, particularly in muscle and brain tissue. It is endogenously synthesized from amino acids but is commonly supplemented to enhance physical performance and power output. While Creatine Monohydrate remains the most researched and dominant product type, newer forms like Creatine HCl gain niche adoption. The powder delivery format holds the largest share, though capsules and chewable tablets are growing for convenience.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) govern health claims and permissible ingredient levels, shaping product marketing. Manufacturing processes often adhere to quality standards like ISO 9001 to ensure purity, a critical factor for market access in jurisdictions like Japan and South Korea. Future growth trajectories will be dictated by the ability of producers to substantiate novel health claims for cognitive function and healthy aging.
Market Dynamics
The market's central dynamic is the expansion of the consumer base beyond elite athletes to include general wellness and healthy aging segments. This demographic shift is reorienting product development and marketing toward cognitive function and metabolic health claims.
Growth Catalysts
- Regulatory Stability:The US FDA's established Generally Recognized as Safe (GRAS) status for creatine monohydrate provides a secure foundation for market access, boosting consumer confidence and simplifying product launches in North America.
- Emerging Fitness Cultures:Government-led health initiatives in China, like the "Healthy China 2030" plan, are accelerating fitness participation and supplement adoption, creating a significant new source of demand for creatine products.
- Expanding Scientific Validation:Growing clinical research into creatine's benefits for cognitive function, mental fatigue, and neurological support is opening new application pathways beyond sports nutrition, attracting a non-athletic consumer base.
Market Restraints
- Raw Material Concentration:The supply chain's heavy reliance on a few large-scale producers in China for key precursors creates price volatility and geopolitical supply risks for formulators worldwide.
- Perceived Efficacy Misconceptions:Persistent marketing of alternative creatine forms with unsubstantiated superiority claims over creatine monohydrate can fragment consumer understanding and create skepticism, slowing adoption for new users.
- Stringent Health Claim Regulations:The European Food Safety Authority (EFSA) maintains a strict approval process for new health claims, limiting marketers' ability to promote emerging benefits like cognitive enhancement in the EU market.
Strategic Opportunities
- Healthy Aging Formulations:Developing creatine products specifically targeting sarcopenia prevention and cognitive maintenance in aging populations represents a major area for growth, moving beyond the youth-focused sports market.
- Convenience-Driven Delivery Formats:Innovation in ready-to-drink beverages, functional foods, and chewable tablets offers an opportunity to capture consumers seeking convenience over traditional bulk powders.
- Market Entry in Southeast Asia:Expanding distribution and educational marketing into underpenetrated markets like Vietnam and Indonesia, where fitness and wellness trends are nascent, presents a long-term growth vector.
Industry Challenges
- Purity and Contaminant Control:Ensuring the absence of contaminants like dicyandiamide (DCD) and dihydrotriazine (DHT) requires rigorous manufacturing processes and third-party testing, adding cost and complexity to production.
- Consumer Education Gap:Combating persistent misinformation regarding side effects and proper dosing protocols remains a significant operational challenge, requiring substantial investment in clear, science-backed marketing communications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatine Market |
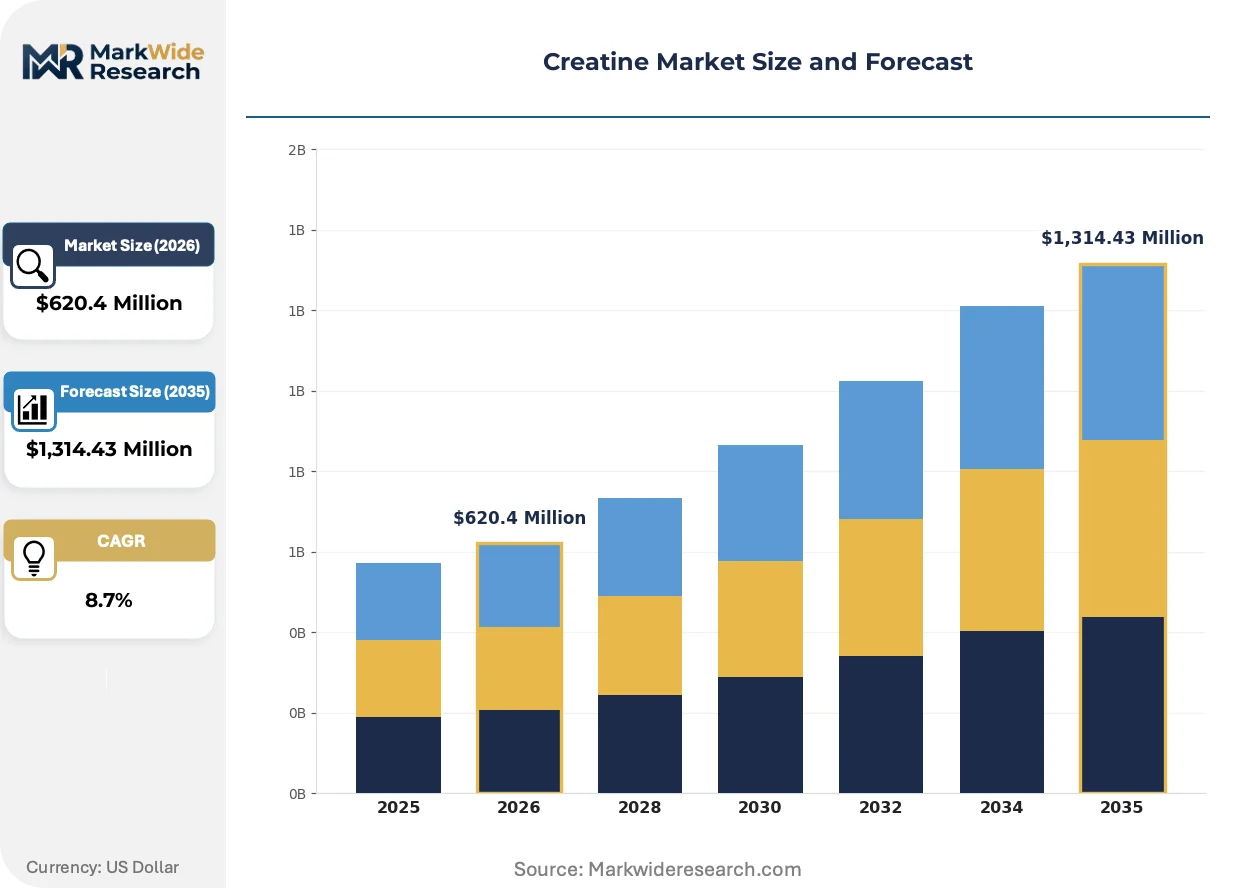
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,314.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creatine Monohydrate, Creatine Ethyl Ester, Buffered Creatine, Creatine HCl Delivery Format: Powder, Capsules, Chewable Tablets, Liquid End User: Athletes, Bodybuilders, Fitness Enthusiasts, Everyday Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms |
| Companies Covered | Optimum Nutrition, MuscleTech, BSN, Glanbia Nutritionals, Myprotein, Dymatize, Cellucor, Universal Nutrition, AlzChem AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatine Market Strategic Shifts & Innovations
Scientific validation is converging with new delivery technologies to make creatine more accessible and appealing to a broader consumer demographic. This shift is moving the product from a niche supplement to a mainstream wellness ingredient with diverse applications.
Newer forms like Creatine HCl and buffered creatine are designed to improve solubility or reduce gastrointestinal discomfort compared to traditional monohydrate. While niche, these alternatives are adopted by consumers sensitive to side effects or seeking perceived technological advantages. This development is fragmenting the product landscape, creating specialized tiers beyond the monohydrate standard.
The European Food Safety Authority (EFSA) has authorized a specific health claim linking creatine to increased physical performance in successive bursts of short-term, high-intensity exercise. This authorization provides a clear marketing pathway for sports nutrition brands within the European Union. Consequently, products targeting athletes in markets like Germany and France prominently feature this claim on packaging.
Consumer purchasing behavior is moving from bulk, one-time buys at specialty retail to subscription-based models via direct-to-consumer (D2C) websites. This shift disintermediates traditional brick-and-mortar supplement stores, allowing brands to own the customer relationship and data. This trend is most prominent in digitally mature markets like the United States and the UK.
Creatine Market Segmentation
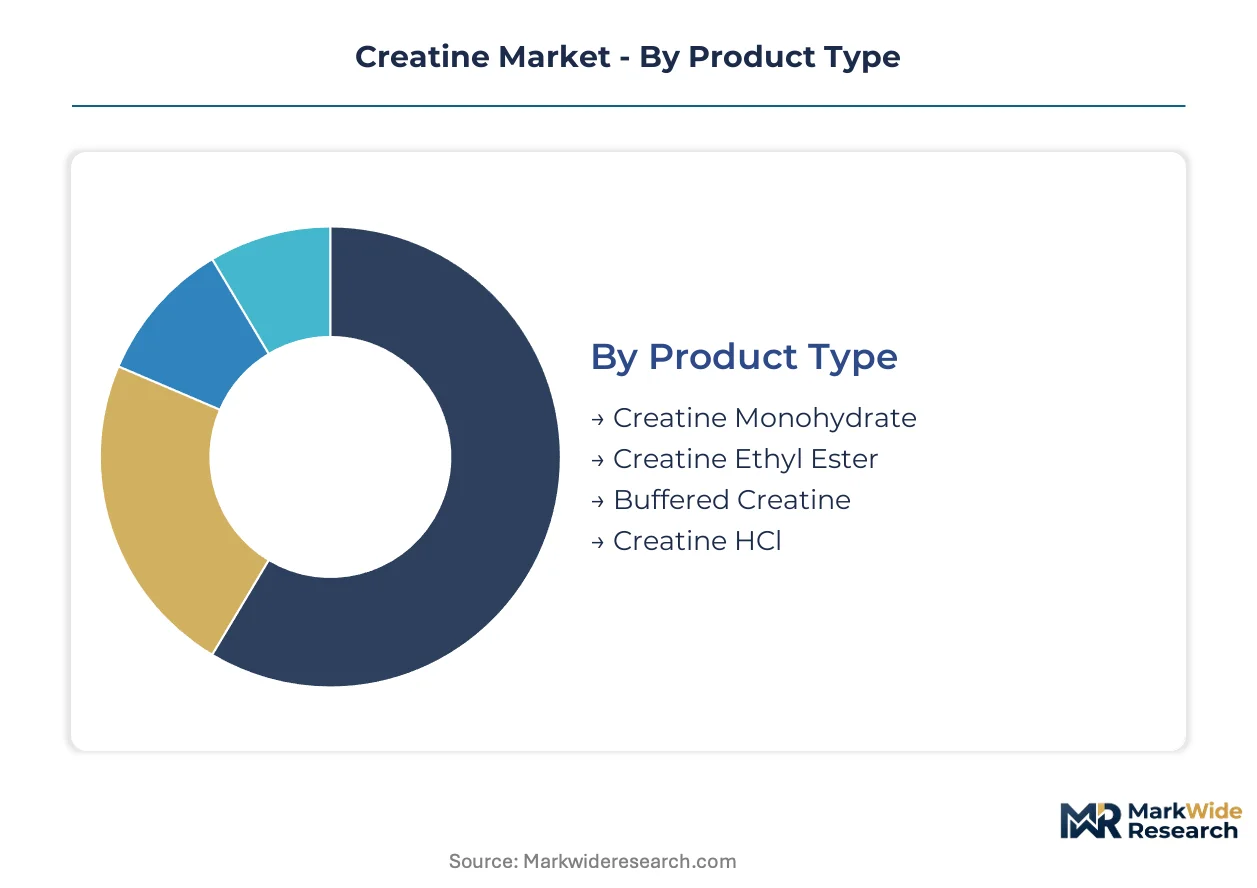
Market segmentation clarifies the diverse needs and purchasing behaviors within the creatine industry, allowing producers to tailor product offerings and marketing strategies effectively. Understanding these distinct segments helps manufacturers target specific consumer groups, optimize distribution, and drive product innovation for sustained market expansion.
Product Type:
The channel mix for product types often dictates consumer exposure, with established forms dominating broad retail while newer variants seek specialty distribution. Creatine Monohydrate remains the cornerstone of the market, recognized for its extensive scientific backing and cost-effectiveness. Creatine HCl offers enhanced solubility and reduced gastrointestinal discomfort for sensitive users, gaining traction in specific online communities.
- Creatine Monohydrate:This highly researched and widely available form consists of a creatine molecule bound to a water molecule, offering proven efficacy for strength and power output. Demand in the United States concentrates among both athletes and everyday consumers, driven by its GRAS status and consistent performance benefits.
- Creatine HCl:This creatine hydrochloride salt is perceived to offer superior absorption and requires lower dosing, appealing to consumers seeking convenience and minimal gastric issues. Fitness enthusiasts in Germany increasingly adopt this form, influenced by its perceived technological advantage and ease of use.
- Creatine Ethyl Ester:This form aims to improve bioavailability through esterification, though scientific evidence for its superiority over monohydrate is limited. Bodybuilders in Australia occasionally experiment with this variant, seeking marginal performance gains.
- Buffered Creatine:Designed to resist stomach acid degradation, this form aims to reduce potential side effects and enhance absorption, often marketed to individuals with digestive sensitivities. Specialty supplement stores in Canada stock this product, catering to niche consumer preferences.
By volume, Creatine Monohydrate leads the market. By growth pace, Creatine HCl is ahead, driven by targeted marketing efforts.
Delivery Format:
The choice of delivery format directly impacts consumer convenience and product integration into daily routines, influencing purchasing patterns across different demographics. Powdered creatine offers cost efficiency and dosage flexibility, appealing to bulk purchasers and those who mix supplements. Capsules provide discreet, pre-measured doses, catering to on-the-go lifestyles.
- Powder:This format offers the highest concentration of creatine per serving and allows for flexible dosing, typically mixed with water or other beverages. Athletes and bodybuilders in the United States and China primarily prefer this format, valuing its cost-effectiveness and versatility.
- Capsules:Providing a convenient, pre-measured dose, capsules are easy to consume without mixing, appealing to individuals seeking simplicity and portability. Everyday consumers and fitness enthusiasts in the United Kingdom increasingly choose capsules for their ease of integration into busy schedules.
- Chewable Tablets:These flavored tablets offer an alternative for consumers who dislike swallowing pills or mixing powders, providing a palatable and convenient option. New users in Japan often select chewable tablets, attracted by their ease of consumption and novel form.
- Liquid:Liquid creatine formulations aim for rapid absorption and ease of intake, though stability and potency can be challenges for manufacturers. Specific niche markets in France occasionally offer liquid creatine, targeting consumers seeking immediate post-workout options.
Convenience and ease of use are primary drivers in this segment. Product development focuses on enhancing consumer experience.
End User:
End-user segmentation highlights the evolving consumer base for creatine, moving beyond traditional athletic applications to broader wellness objectives. Athletes and bodybuilders represent the historical core, focused on performance and muscle growth. Everyday Consumers are a rapidly expanding segment, seeking cognitive and general health benefits.
- Everyday Consumers:This expanding demographic includes individuals seeking general wellness benefits, cognitive support, and healthy aging, often integrating creatine into their daily health regimen. Older adults in Germany are increasingly adopting creatine for sarcopenia prevention and cognitive maintenance, supported by emerging clinical research.
- Athletes:This segment comprises professional and amateur athletes across various sports, utilizing creatine for enhanced physical performance, strength, and recovery. Competitive athletes in Canada rely on creatine to improve power output and reduce fatigue during high-intensity training.
- Bodybuilders:Focused on muscle hypertrophy and strength gains, bodybuilders are traditional heavy users of creatine, integrating it into their rigorous training and dietary protocols. Bodybuilders in Australia prioritize creatine for its proven ability to support lean muscle mass and strength development.
- Fitness Enthusiasts:This broad group includes individuals engaged in regular physical activity for health and fitness goals, using creatine to support energy levels and exercise performance. Casual gym-goers in Brazil incorporate creatine to optimize their workouts and accelerate recovery.
This segment's expansion into wellness applications is a significant market shift. Product innovation now targets diverse health outcomes.
Distribution Channel:
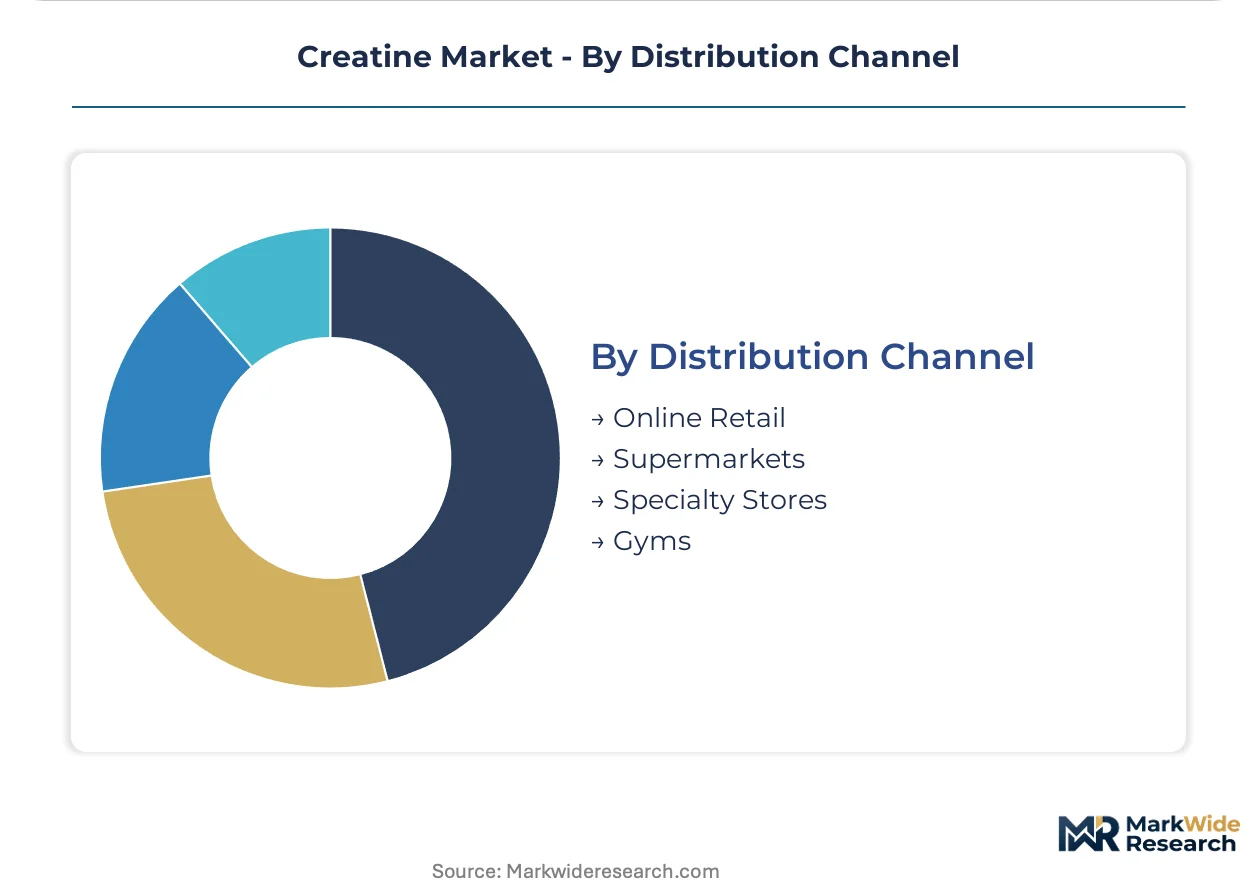
Distribution channels determine market reach and consumer accessibility, with online retail gaining prominence due to its convenience and direct-to-consumer models. Supermarkets offer broad accessibility for mainstream consumers, while specialty stores cater to informed buyers.
- Online Retail:This channel includes e-commerce platforms, brand-specific websites, and subscription services, offering wide product selection, competitive pricing, and direct consumer engagement. Consumers in the United States and the United Kingdom increasingly purchase creatine through online channels, valuing convenience and direct delivery.
- Supermarkets:Mass market grocery stores and hypermarkets provide broad physical access to creatine products, often targeting general wellness consumers with established brands. Everyday consumers in Japan frequently encounter creatine in supermarket health sections, driving impulse purchases.
- Specialty Stores:These outlets include dedicated sports nutrition shops and health food stores, offering a curated selection of products and expert advice to informed consumers. Bodybuilders and serious athletes in France often frequent specialty stores for premium creatine brands and personalized recommendations.
- Gyms:On-site sales at fitness centers and health clubs provide immediate access to supplements for gym members, often featuring popular brands or those promoted by trainers. Fitness enthusiasts in South Korea often purchase creatine directly from their gyms, influenced by trainer endorsements.
Online retail dominates in terms of growth. Traditional retail channels maintain significant volume for established brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominant position in creatine precursor production underpins global supply streams, creating a significant trade corridor with major consumer markets. This supply chain dynamic influences pricing and availability for formulators and brands worldwide. Demand concentration in key regions shapes market development.
United States
United States demand for creatine is strong, driven by widespread sports nutrition adoption and expanding wellness applications. The US FDA's GRAS status for creatine monohydrate provides a stable regulatory foundation. California's extensive supplement manufacturing and distribution networks actively introduce diverse creatine formulations.
Germany
Germany exhibits robust demand for high-purity creatine, fueled by health-conscious consumers and an aging demographic seeking cognitive support. The European Food Safety Authority (EFSA) authorizes specific health claims for physical performance, guiding EU product labeling. Bavaria, a key chemical manufacturing region, houses producers like AlzChem AG, ensuring stringent quality control.
China
China's creatine market experiences rapid expansion due to a burgeoning fitness culture and government-backed health initiatives. The "Healthy China 2030" plan directly stimulates supplement adoption among its vast population. Shandong province, a significant chemical production base, concentrates much of the world's creatine precursor manufacturing.
Japan
Japan's creatine consumption trends towards convenient delivery formats and healthy aging applications. METI and PMDA regulatory frameworks ensure stringent quality control for all imported and domestically produced supplements. Tokyo's urban centers show a preference for chewable tablets, reflecting a consumer demand for ease of use.
Canada
Canada's athletes and fitness enthusiasts consistently drive demand for creatine to enhance performance and aid recovery. Health Canada regulates creatine as a natural health product, ensuring consumer safety and proper labeling. Ontario, with its large urban populations, represents a primary market for creatine supplements.
Creatine Market Key Industry Players
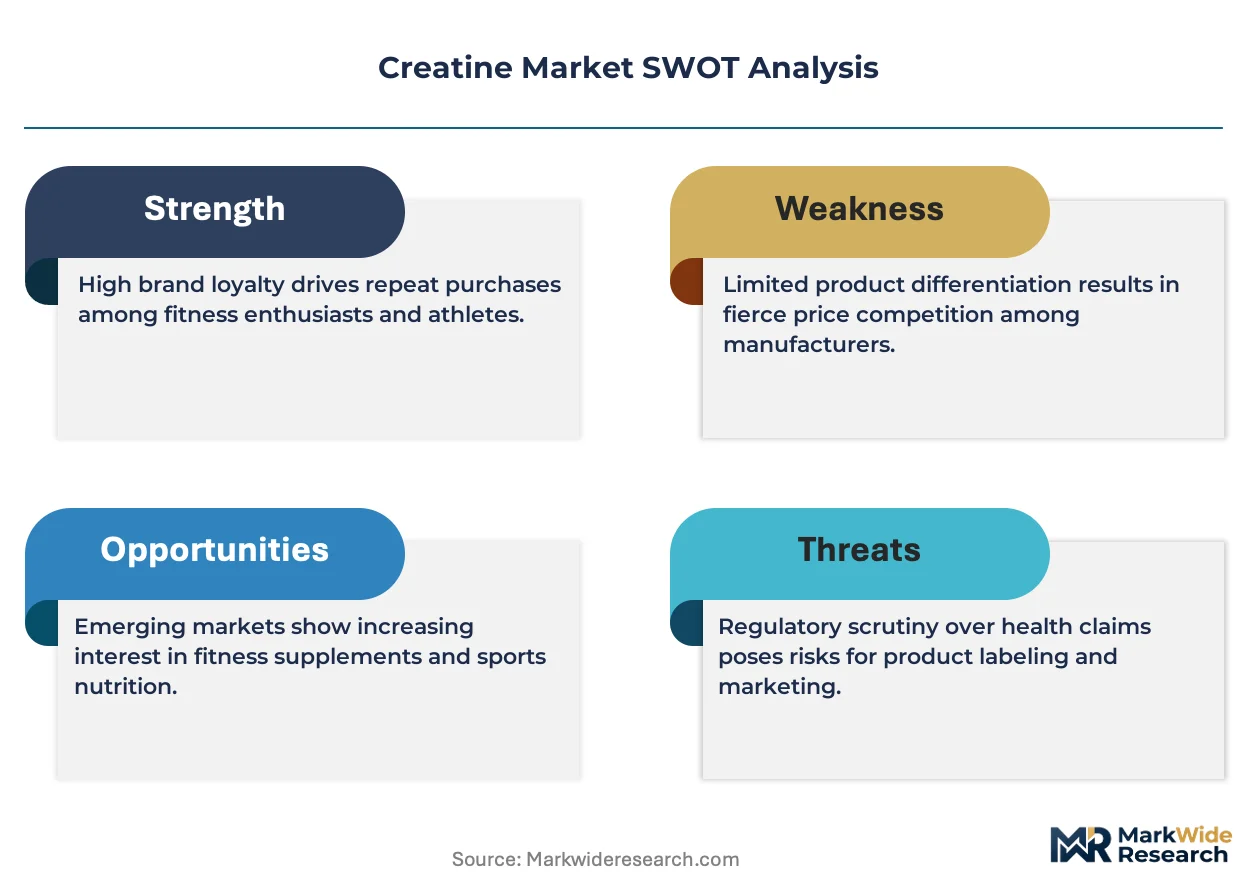
Player mix skews toward established consumer brands leveraging extensive distribution networks alongside specialized producers focused on high-purity ingredients. The market balances between broad accessibility for everyday consumers and niche offerings for performance-oriented segments. Strategic archetypes include large-scale supplement manufacturers and ingredient-focused chemical companies. Companies frequently expand distribution channels and diversify product portfolios to capture new consumer segments.
Within the consumer-focused tier, Optimum Nutrition and Myprotein exemplify brands with extensive reach through online retail and broad distribution. These entities represent large-scale supplement providers catering to a diverse global customer base. AlzChem AG, a German-based chemical company, occupies a distinct position by specializing in high-purity creatine monohydrate, anchoring the quality-conscious segment of the market. Its Creapure® brand is synonymous with stringent manufacturing standards and purity.
| Leading Market Players |
|---|
| Optimum Nutrition |
| MuscleTech |
| BSN |
| Glanbia Nutritionals |
| Myprotein |
| Dymatize |
| Cellucor |
| Universal Nutrition |
| AlzChem AG |
| Others |
Cost & Logistics Intelligence
The US FDA's GRAS status for creatine monohydrate gates supply qualification for North American markets, while also enabling price differentiation for producers meeting stringent purity standards.
Pricing Analysis
Creatine monohydrate, as the established standard, sets the baseline transactional pricing, while newer forms like Creatine HCl command a premium due to perceived technological advantages. Quality grade and brand premium drive price differentiation among product types in markets like Germany. Pricing softness stems from intense competition in the bulk monohydrate segment, particularly with Chinese suppliers. Everyday consumers demonstrate higher price sensitivity compared to performance-focused athletes and bodybuilders.
Supply Chain Analysis
Strategic stockpiling of key creatine precursors is a common inventory strategy for formulators worldwide, mitigating risks from concentrated production. Global supply concentrates heavily in China, particularly Shandong province, for creatine precursor manufacturing. Formulators globally source from these few large-scale producers, creating single-source vulnerability and commodity price volatility. Distribution runs through online retail platforms and specialty stores, reaching diverse consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The creatine market presents a fragmentation opportunity as demand shifts towards everyday consumers seeking cognitive and wellness benefits. This reorients product development towards specialized health outcomes, creating new niches.
For Market Incumbents: Shield core market share by investing in rigorous scientific validation for creatine monohydrate's established benefits, countering perceived efficacy misconceptions. Consolidate raw material procurement through long-term contracts with Chinese producers, mitigating geopolitical supply risks. Expand distribution channels into emerging markets like Southeast Asia to diversify revenue streams.
For New Entrants and Emerging Players: Differentiate on convenience-driven delivery formats, targeting consumers seeking ease of use over traditional powders, such as chewable tablets for new users in Japan. Penetrate the healthy aging segment with formulations specifically addressing sarcopenia prevention and cognitive maintenance. Leverage direct-to-consumer (D2C) online channels to build brand loyalty and educate consumers on niche benefits.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the specialized ingredient production segment, driven by demand for stringent purity and quality control. The market demonstrates strong long-term viability, underpinned by expanding scientific validation and consumer adoption beyond athletic circles. Target acquisition profiles should focus on high-purity creatine manufacturers or innovators in novel delivery formats. Watch for regulatory approvals of new cognitive health claims as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (high-purity monohydrate) | Ensures stable supply for quality-conscious segments globally. |
| Product Line Diversification (chewables/RTDs) | Captures convenience-seeking everyday consumers in urban centers. |
| Clinical Research Investment (cognitive benefits) | Substantiates novel health claims for healthy aging populations. |
| Direct-to-Consumer Channel Development | Enhances brand ownership and customer data for subscription models. |
| ISO 9001 Certification (manufacturing) | Facilitates market access in quality-sensitive jurisdictions like Japan. |
Research Approach
A standing panel of supplement brand managers, sports nutritionists, and regulatory affairs specialists provided ongoing calibration for primary interview insights. This approach combined direct engagement with industry experts and validation against secondary sources like US FDA GRAS notices and academic research databases. Bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
Forecast outputs were validated for consistency against external benchmarks, including historical market growth rates and consumer trend reports. The analytical framework modeled segmentation across product type, delivery format, end-user, distribution channel, and regional regulatory frameworks over the projection horizon. Compound annual growth rates were derived from historical data analysis and projected market dynamics, integrating inputs like fitness participation rates.
Material uncertainties — geopolitical supply chain disruptions or unforeseen regulatory changes — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Revision becomes warranted when significant scientific breakthroughs or major shifts in consumer perception cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market