
 Cricket Protein Powder Market | 2026-2036
Cricket Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cricket Protein Powder Market Analysis
Ingredient sourcing revenue is fragmenting as brands diversify beyond commodity cricket suppliers toward controlled vertical operations. Chapul Cricket Protein leverages its early-mover brand recognition to sustain premium positioning in North American direct-to-consumer channels. Entomo Farms anchors Canadian production scale with industrial-grade farming infrastructure that supplies B2B ingredient clients. Protix competes through proprietary automation systems that reduce larval-to-powder conversion costs.
Cricket protein powder consists of defatted, milled Acheta domesticus or Gryllodes sigillatus biomass standardized to 60-75% protein content by dry weight, produced through controlled-environment rearing, thermal processing, and fine mechanical grinding for human consumption. Protein isolate commands the highest margin pool due to extraction complexity and sports nutrition demand, while whole powder occupies the volume-dominant tier serving bakery and beverage manufacturers. Online retail extends fastest among distribution channels as subscription models reduce customer acquisition costs for specialty nutrition brands.
The European Food Safety Authority Novel Food regulation governs market entry for cricket-derived ingredients across EU member states, while the FDA exercises enforcement discretion over insect protein under existing food additive frameworks in the United States. Health Canada and Food Standards Australia New Zealand maintain parallel assessment pathways that shape multinational product launch sequencing. Stakeholders must monitor evolving allergen labeling mandates and cumulative toxicology data requirements that will determine which product formats achieve broad retail authorization.
Market Dynamics
EFSA Novel Food authorization pathways are compressing commercialization timelines for cricket-derived ingredients, forcing manufacturers to accelerate toxicology dossiers while sports nutrition brands front-load formulation partnerships ahead of regulatory clarity.
Growth Catalysts
- EFSA Novel Food Streamlining:Centralized safety assessments under EU Regulation 2015/2283 reduce member-state fragmentation, enabling cross-border ingredient sales from single authorization points.
- Pre-Workout Formulation Pull:Sports nutrition manufacturers are embedding defatted cricket biomass into pump-focused supplements, capitalizing on complete amino acid profiles and digestibility claims.
- Controlled-Environment Rearing:Automated climate systems for Acheta domesticus colonies stabilize protein yield variance, reducing batch-to-batch quality penalties that previously constrained bakery sector adoption.
Market Restraints
- Feed Input Cost Volatility:Organic grain substrates for cricket colonies fluctuate with commodity wheat and soy markets, compressing margin pools for non-vertically integrated processors.
- Allergen Labeling Friction:EFSA mandates for shellfish cross-reactivity warnings create packaging complexity that deters mainstream retail placement in EU member states.
- Plant Protein Substitution:Pea and fava isolates achieve comparable protein content at lower per-kilogram cost, anchoring vegan formulation defaults among cost-sensitive manufacturers.
Strategic Opportunities
- German Fitness Retail Penetration:Specialty nutrition stores in Berlin and Munich exhibit highest consumer willingness-to-pay for insect-derived products, supporting premium positioning tests.
- Subscription Channel Expansion:Direct-to-consumer auto-replenishment models reduce customer acquisition costs for specialty brands while building usage habituation.
- EU Green Deal Protein Diversification:Farm-to-Fork strategy incentives for alternative protein sources create grant funding pools for domestic cricket farming infrastructure.
Industry Challenges
- Entomology Talent Scarcity:Commercial-scale cricket rearing requires specialized knowledge in colony health management that outpaces university agricultural program output.
- Capex-Intensive Automation:Larval-to-powder processing lines demand seven-figure capital commitments for thermal treatment and fine milling equipment that achieve food-grade certification.
- Standardization Delays:Absence of harmonized protein content measurement protocols between ISO and national food standards bodies creates inter-laboratory variance in product labeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cricket Protein Powder Market |
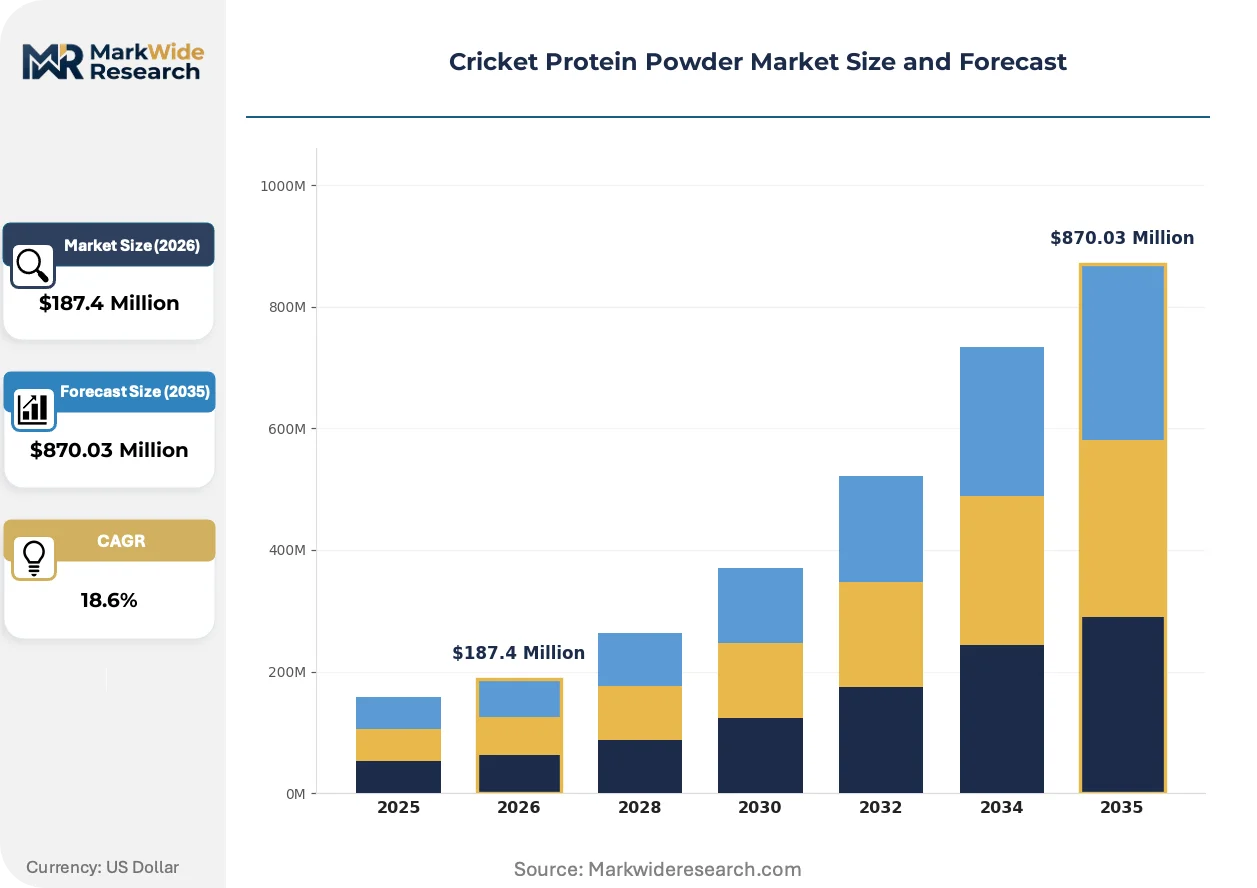
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Powder, Protein Isolate, Energy Bars, Snacks End User: Fitness Enthusiasts, Athletes, Vegan Consumers, Health-Conscious Individuals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Stores Application: Diet Supplements, Bakery Products, Beverages, Meal Replacement |
| Companies Covered | Chapul Cricket Protein, JR Unique Foods Ltd., Entomo Farms, Protix, All Things Bugs, Aspire Food Group, Cricket Flours LLC, Proti-Farm, Exo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cricket Protein Powder Market Emerging Trajectories
Processing technology convergence with regulatory data requirements is compressing the gap between pilot-scale production and retail-ready certification. Manufacturers are reconfiguring operational footprints around automation and traceability mandates.
Mechanical fractionation systems for cricket biomass are hybridizing thermal processing with enzymatic extraction, enabling simultaneous protein isolate recovery and chitin separation for secondary revenue streams. Sports nutrition contract manufacturers in Germany and the Netherlands are piloting these hybrid lines at 500-kilogram daily throughput. The technology is hybridizing capital deployment strategies, forcing mid-scale processors to choose between equipment leasing partnerships and equity dilution for in-house installation.
EFSA's cumulative toxicology data requirements under the 2015 Novel Food regulation are extending dossier preparation timelines, compelling ingredient suppliers to front-load heavy metal and pesticide residue testing. This regulatory compression favors established players with existing toxicology portfolios over new market entrants. Protein isolate formats face the steepest compliance burden, while whole powder applications benefit from streamlined safety assessments.
Fitness-oriented consumers in German-speaking markets are rotating toward subscription-based specialty nutrition procurement, displacing single-purchase retail patterns. Direct-to-consumer brands capture this shift through algorithm-driven flavor customization and replenishment timing. Berlin and Munich metropolitan clusters exhibit the strongest concentration of this behavioral pivot, with specialty retail partners reporting declining foot traffic for standalone protein powder purchases.
Cricket Protein Powder Market Segmentation
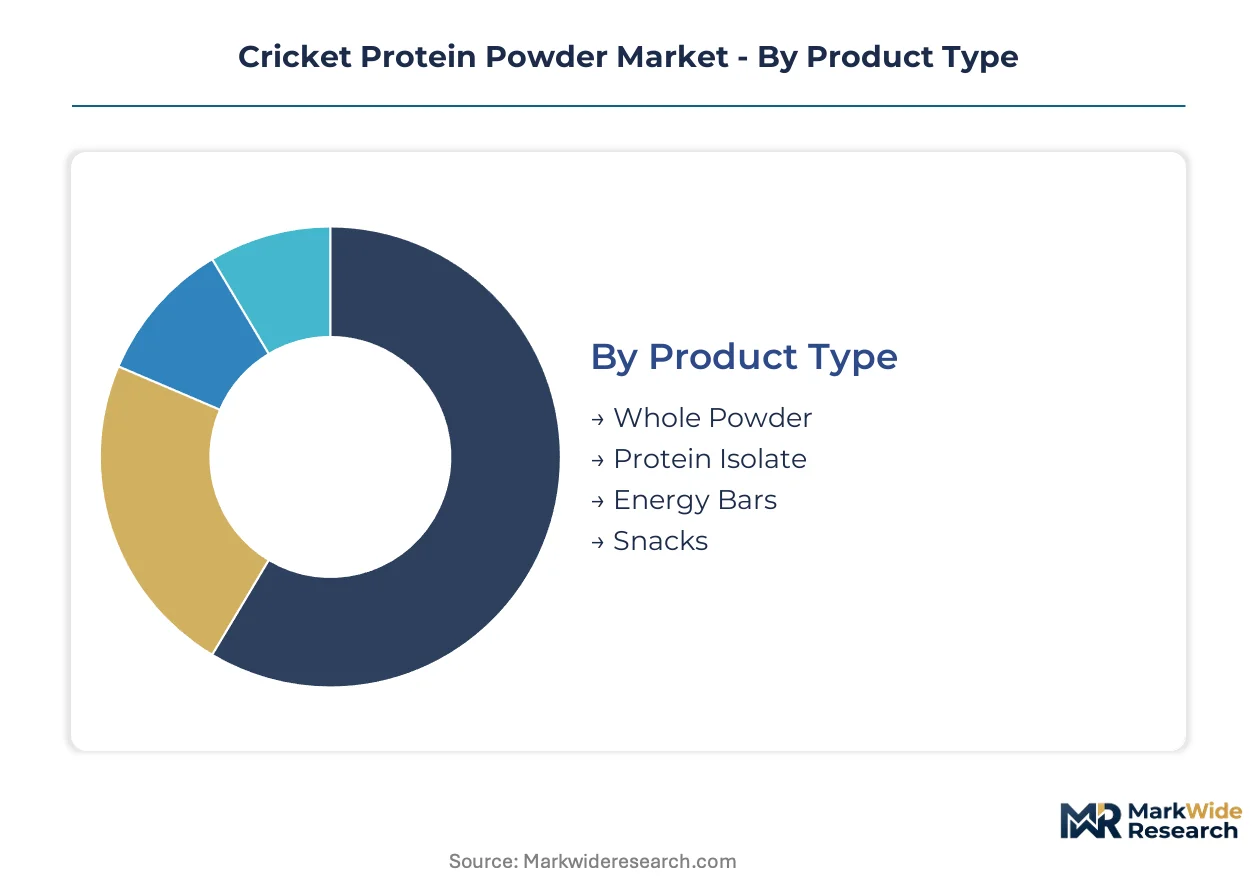
Cricket protein powder segmentation reveals how processing intensity and distribution economics reshape competitive positioning across formulation tiers. Manufacturers calibrate product development around regulatory pathway complexity and end-use protein specification requirements.
Product Type:
After-sales service intensity varies sharply across product tiers, with isolate formats demanding technical support for formulation integration while whole powder requires minimal post-purchase engagement.
- Whole Powder:Defatted, milled Acheta domesticus or Gryllodes sigillatus biomass standardized to 60-75% protein content serves bakery and beverage manufacturers seeking cost-efficient functional ingredients. Demand concentrates in Germany, where industrial bakers leverage whole powder for clean-label protein fortification amid EFSA Novel Food authorization clarity.
- Protein Isolate:Extracted fractions achieving 80-90% protein purity command premium positioning through complex enzymatic or mechanical separation processes. Sports nutrition formulators in the Netherlands and Belgium drive procurement, prioritizing complete amino acid profiles for pre-workout applications despite higher per-kilogram cost structures.
- Energy Bars:Co-extruded or cold-pressed formats combining cricket protein with binding agents and flavor systems target on-the-go consumption occasions.
- Snacks:Roasted or puffed whole cricket products occupy impulse purchase segments with lower processing barriers and shorter shelf-life requirements.
Whole Powder holds the largest share; momentum sits with Protein Isolate.
End User:
Cost tier differentiation separates premium-positioned athlete formulations from mass-market health-conscious positioning, with vegan consumers occupying a price-elastic middle ground.
- Fitness Enthusiasts:Recreational exercisers seeking protein supplementation for body composition goals represent volume-dominant demand with moderate price sensitivity. German specialty nutrition retailers report highest conversion rates in Berlin and Munich metropolitan clusters.
- Athletes:Competitive and professional sports participants demand batch-tested, contaminant-screened products with documented amino acid profiles. Procurement concentrates through sports dietitian recommendations and team nutrition partnerships in Belgium and the Netherlands.
- Vegan Consumers:Plant-forward eaters seeking complete protein alternatives drive interest in cricket-derived options despite non-vegan classification, creating positioning tension for brands.
- Health-Conscious Individuals:General wellness seekers motivated by sustainability claims and novel ingredient curiosity exhibit lower retention rates and higher channel-hopping behavior.
Fitness Enthusiasts anchor volume absorption; Athletes deliver margin expansion.
Distribution Channel:
Volume concentration tilts toward digital channels as subscription mechanics reduce customer acquisition costs, while physical retail maintains relevance for trial and impulse categories.
- Online Retail:Direct-to-consumer platforms and marketplace listings enable algorithm-driven personalization and auto-replenishment models. German-speaking markets exhibit strongest subscription adoption, with Berlin-based brands pioneering flavor-customization interfaces.
- Supermarkets:Mass retail placement remains limited by allergen labeling friction and shelf-space economics, though select organic chains in the Netherlands pilot dedicated alternative protein sections.
- Specialty Stores:Fitness-focused nutrition retailers in Munich and Hamburg sustain premium positioning through staff education and sampling programs.
- Health Stores:Natural products channels emphasize sustainability narratives and clean-label claims for cricket-derived formats.
Online Retail climbs the fastest; Specialty Stores defend margin pools.
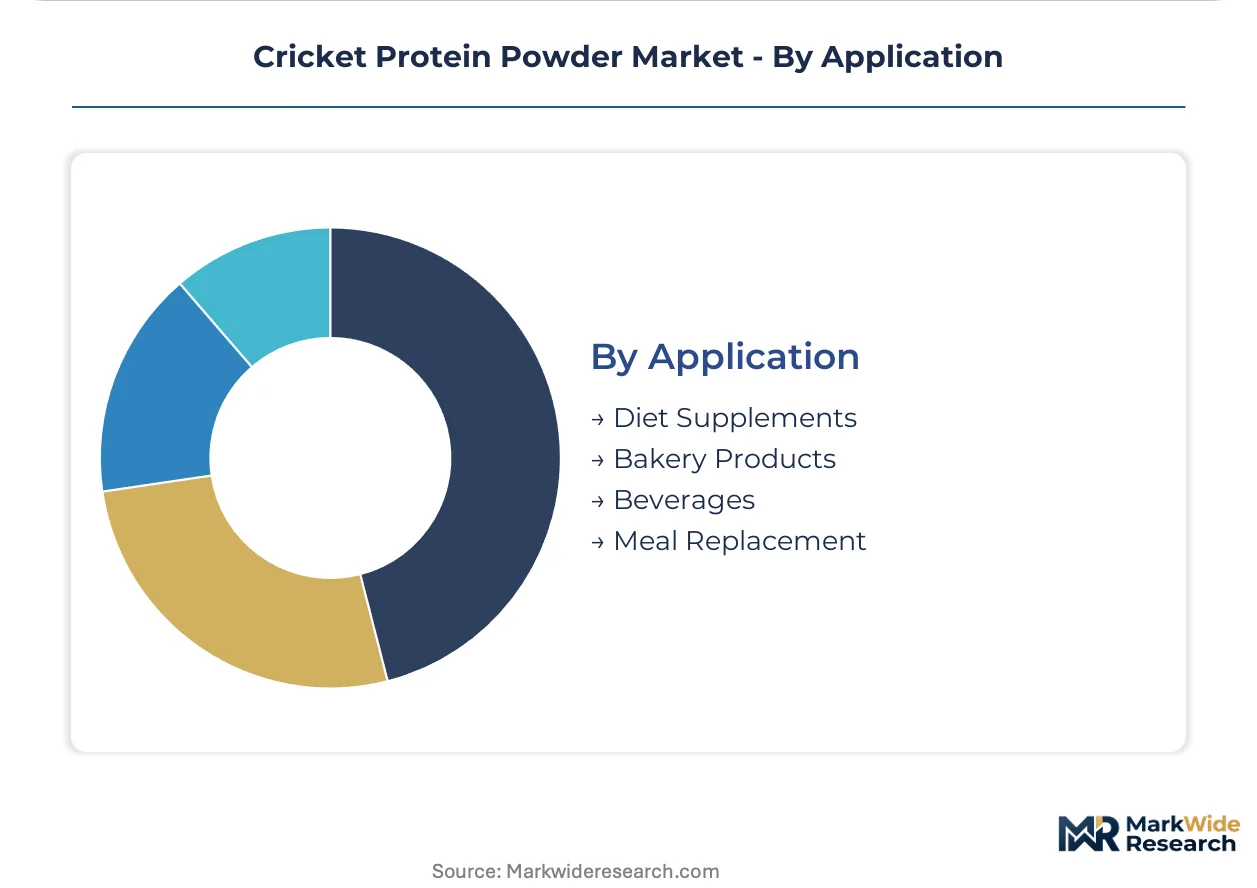
Application:
Supply concentration in sports nutrition contract manufacturing shapes formulation partnerships, while bakery sector adoption accelerates with standardized ingredient specifications.
- Diet Supplements:Powder and capsule formats targeting micronutrient and macronutrient supplementation dominate current revenue composition. Dutch contract manufacturers lead pilot-scale production for isolate-based formulations.
- Bakery Products:Protein-enriched bread, pastry, and snack applications leverage whole powder for functional properties with minimal flavor impact. German industrial bakers drive specification development for clean-label fortification.
- Beverages:Ready-to-drink and powder-mix applications require advanced emulsification and suspension technologies to manage insolubility challenges.
- Meal Replacement:Complete nutrition formulations combining cricket protein with lipid and carbohydrate matrices target convenience-oriented consumers.
Diet Supplements holds established revenue; Bakery Products gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cricket farming infrastructure clusters in temperate zones with established food-grade insect rearing protocols. Automated colony management systems concentrate in jurisdictions with clear Novel Food pathways. Processing capacity expansion tracks regulatory authorization sequencing across North America and Europe.
Germany
Fitness-oriented consumers in Berlin and Munich drive specialty retail demand for cricket-derived supplements. EFSA Novel Food regulation under EU 2015/2283 enables cross-border ingredient sales from German production bases. North Rhine-Westphalia hosts industrial-scale farming operations supplying B2B ingredient clients across the Benelux region.
Netherlands
Sports nutrition contract manufacturers in the Randstad area pilot hybrid mechanical-enzymatic extraction systems for protein isolate recovery. The Dutch national food authority aligns with EFSA assessment timelines for toxicology dossier approval. Eindhoven Region automation specialists develop larval-to-powder processing equipment for export markets.
United States
Direct-to-consumer brands leverage FDA enforcement discretion over insect protein to accelerate product launches ahead of formal additive frameworks. California and Texas host early-mover cricket farming ventures with vertical integration into powder production. Pacific Northwest metropolitan clusters exhibit highest subscription adoption for specialty nutrition procurement.
Canada
Health Canada maintains parallel assessment pathways to EFSA that shape multinational launch sequencing for cricket-derived ingredients. Ontario-based producers anchor North American supply scale with industrial-grade rearing infrastructure. Greater Toronto Area distribution hubs serve cross-border B2B clients under USMCA trade provisions.
Belgium
Athlete procurement concentrates through sports dietitian recommendations in Brussels and Antwerp metropolitan areas. EFSA Novel Food authorization clarity enables ingredient import from Dutch and German suppliers. Flanders region hosts pilot programs for bakery sector whole powder integration into clean-label fortification applications.
Cricket Protein Powder Market Vendor Landscape
Vertically integrated producers and specialist ingredient suppliers split the market between captive supply chains and open B2B distribution. Mid-scale processors face equipment leasing decisions against equity dilution for in-house automation installation. Two archetypes dominate: early-mover consumer brands with direct-to-consumer channel control, and industrial-scale farming operations with B2B ingredient focus. Competitive moves center on backward integration into feed substrate production and strategic partnerships with sports nutrition contract manufacturers.
Within the early-mover brand tier, Chapul Cricket Protein and Exo Inc. exemplify direct-to-consumer positioning built on specialty nutrition subscription mechanics. Entomo Farms and Protix anchor the industrial-scale archetype with Canadian and Dutch production bases respectively. These four entities represent the strategic spectrum from premium consumer brand recognition to automated processing infrastructure deployment.
| Leading Market Players |
|---|
| Chapul Cricket Protein |
| JR Unique Foods Ltd. |
| Entomo Farms |
| Protix |
| All Things Bugs |
| Aspire Food Group |
| Cricket Flours LLC |
| Proti-Farm |
| Exo Inc. |
| Others |
Supply Flow & Price Mechanics
North Rhine-Westphalia's industrial-scale cricket farming clusters translate concentrated production capacity into downstream pricing leverage for B2B ingredient suppliers serving Benelux sports nutrition manufacturers. EFSA Novel Food authorization timelines compress margin pools for non-vertically integrated processors while premium isolate formats command sustained price premiums through extraction complexity.
Pricing Analysis
EU Regulation 2015/2283 dictates the pricing tier structure through cumulative toxicology compliance burdens that stratify costs across product formats. Three-tier pricing structure across premium isolate, standard whole powder, and economy feed-grade tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from organic grain substrate volatility tethered to commodity wheat markets. Cost-sensitive bakery manufacturers exhibit highest price elasticity, while sports nutrition formulators absorb premium isolate costs for amino acid profile advantages.
Supply Chain Analysis
Dutch and German contract manufacturers hold dominant processing capacity for larval-to-powder conversion lines with food-grade thermal certification. Geographic supply concentrates in the Netherlands, Germany, and Canada, drawing from organic grain feed substrates, automated climate control systems, and enzymatic extraction reagents. Single-source vulnerability runs through proprietary automation equipment suppliers. Distribution runs through B2B ingredient partnerships with sports nutrition contract manufacturers and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cricket protein powder markets exhibit cyclical recovery characteristics as EFSA Novel Food authorization clarity triggers postponed commercialization investments from sports nutrition brands. Regulatory milestone completion functions as the cyclical driver resetting procurement timelines.
For Market Incumbents: Entrench position through backward integration into organic feed substrate production, mitigating margin compression from wheat price volatility. Lock in multi-year formulation partnerships with Dutch and Belgian contract manufacturers ahead of toxicology dossier approvals. Prioritize isolate capacity expansion over whole powder to defend margin pools against plant protein substitution threats.
For New Entrants and Emerging Players: Establish a beachhead in German specialty fitness retail through Berlin and Munich metropolitan clusters where consumer willingness-to-pay sustains premium positioning. Target subscription-based direct-to-consumer channels with algorithm-driven flavor customization interfaces. Deploy grant funding from EU Green Deal Farm-to-Fork incentives to offset capex-intensive automation requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with captive farming infrastructure and existing toxicology portfolios. Long-term viability hinges on regulatory authorization breadth across isolate formats and bakery applications. Monitor EFSA cumulative heavy metal data releases as the inflection signal for retail-ready certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Completion | Unlocks cross-border ingredient sales from single authorization points across EU member states. |
| Hybrid Extraction Technology Deployment | Enables simultaneous protein isolate recovery and chitin separation for secondary revenue streams. |
| Subscription Platform Launch | Reduces customer acquisition costs through algorithm-driven replenishment timing in German-speaking markets. |
| Backward Feed Integration | Stabilizes margin pools against organic grain substrate volatility from commodity wheat markets. |
| Sports Nutrition Partnership | Secures formulation slots for pre-workout applications through Dutch and Belgian contract manufacturers. |
Methodological Framework
Desk research of EFSA Novel Food authorization databases, EU trade customs records, and sports nutrition ingredient specifications preceded structured interviews with cricket farming operations managers, sports nutrition formulators, specialty retail buyers, and regulatory affairs consultants. Primary fieldwork across North Rhine-Westphalia and Randstad production clusters combined with secondary validation from Health Canada parallel assessment documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held EFSA authorization timelines and organic feed substrate pricing as fixed baseline conditions while varying sports nutrition formulation adoption rates and subscription channel penetration across German metropolitan clusters. Segmentation modeling spanned product type, end user archetype, distribution channel, and application vertical. CAGRs derived from regression analysis against protein isolate premiumization trends and bakery sector whole powder specification development.
Sensitivities concentrate around EFSA toxicology data requirements, cumulative heavy metal threshold revisions, and allergen labeling mandate expansions. Forecasts reflect documented assumptions on regulatory pathway clarity and consumer acceptance velocity. Quarterly review of EFSA authorization bulletins and German specialty retail sell-through data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Creatine Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Medicated Fitness Supplements Market