
 Asia-Pacific Sports Drink Market | 2026-2036
Asia-Pacific Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sports Drink Market Outlook
Aftermarket service revenue from subscription-based hydration coaching apps is reconfiguring how beverage firms capture recurring value. PepsiCo leverages its bottling infrastructure across Southeast Asia to sustain distribution density in emerging markets. Otsuka Holdings anchors its position through pharmacy-channel dominance in Japan, where consumers associate sports drinks with medical-grade electrolyte balance. Nongfu Spring competes aggressively on price in China's mass retail tier while building brand equity through marathon sponsorships.
Asia-Pacific sports drinks are formulated beverages containing electrolytes, carbohydrates, and functional additives designed to restore fluid balance and energy during or after physical exertion, typically manufactured through hot-fill aseptic processing to preserve shelf stability without refrigeration. Isotonic formulations dominate commercial volume due to their osmolarity matching human blood plasma, while hypotonic variants gain share among endurance athletes seeking faster gastric emptying. Online retail channels capture the fastest growth trajectory as direct-to-consumer platforms enable flavor customization and replenishment subscriptions that bypass traditional supermarket slotting fees.
Japan's Ministry of Health, Labour and Welfare and Food for Specified Health Uses standards, alongside China's National Health Commission and State Administration for Market Regulation, enforce compositional limits and functional claim verification that determine which products qualify for premium shelf positioning. Australia's Therapeutic Goods Administration and Food Standards Australia New Zealand further constrain caffeine levels and additive palettes across trans-Tasman trade. Stakeholders must monitor evolving ASEAN harmonization talks on functional beverage classification, as unified standards would reshape cross-border manufacturing strategies and label compliance costs.
Market Dynamics
Gym culture proliferation across Southeast Asian cities is compressing consumption cycles, as fitness enthusiasts demand electrolyte replenishment products that align with workout schedules rather than traditional meal occasions. Japan's Ministry of Health, Labour and Welfare labeling standards force formulation adjustments that ripple through regional supply chains.
Growth Catalysts
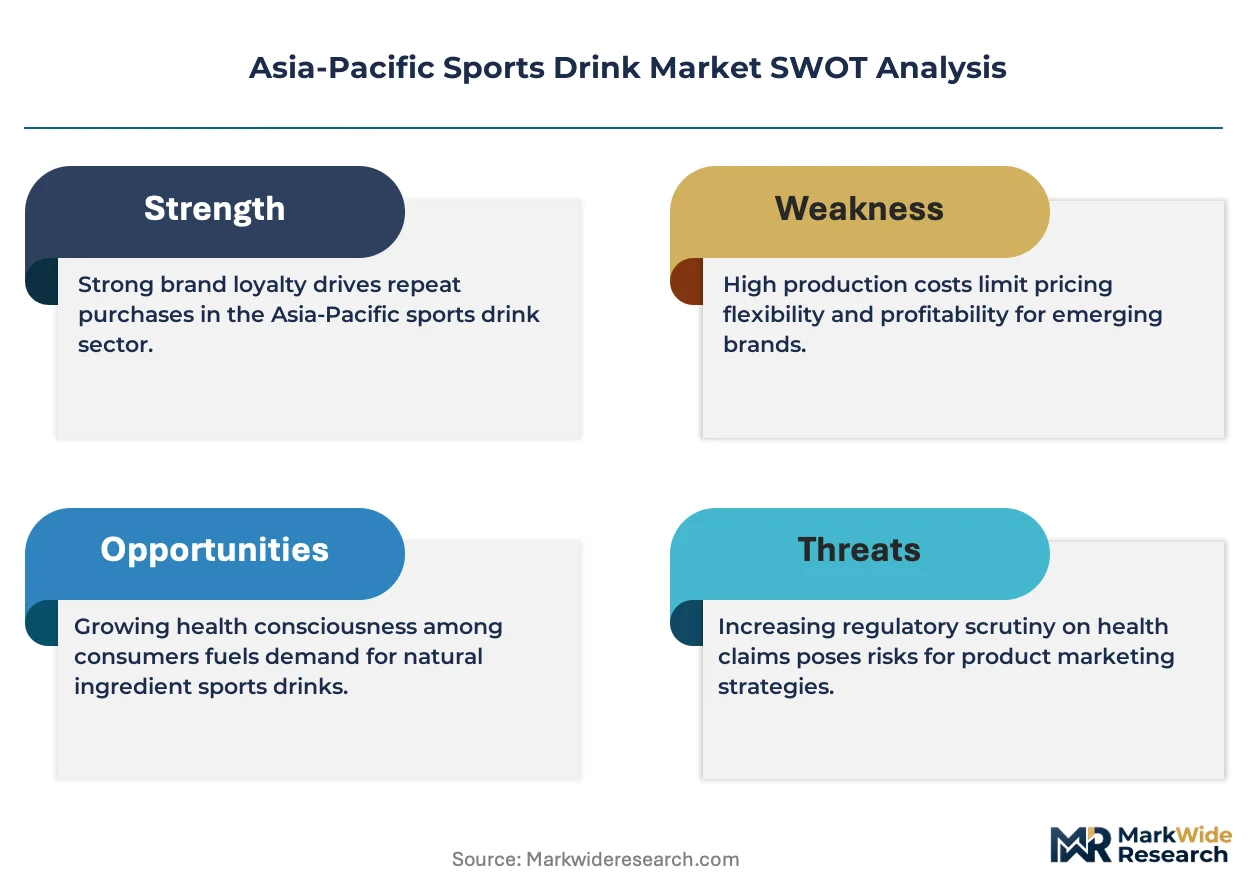
- Urban Fitness Infrastructure:Marathon sponsorships and gym partnerships in China's tier-one cities create habitual consumption patterns among white-collar professionals seeking post-workout recovery solutions.
- Food for Specified Health Uses (FOSHU):Japan's functional beverage certification pathway enables premium shelf positioning for electrolyte products meeting medical-grade compositional thresholds.
- Hot-fill Aseptic Processing:This manufacturing technology eliminates refrigeration requirements, extending distribution reach into Southeast Asia's ambient retail channels and reducing logistics costs.
Market Restraints
- High-fructose Corn Syrup Price Volatility:Carbohydrate sourcing costs fluctuate with agricultural commodity cycles, squeezing margin structures for mass-market isotonic formulations.
- Pharmacy Channel Concentration:Japan's retail landscape funnels sports drink sales through Otsuka Holdings-dominated pharmacy networks, creating entry barriers for new entrants.
- State Administration for Market Regulation (SAMR) Claim Verification:China's functional claim approval timelines extend 18-24 months, delaying product launches and compressing effective patent windows.
Strategic Opportunities
- Vietnam and Indonesia Mass Retail:Underpenetrated secondary cities present first-mover advantages for brands establishing ambient distribution before local competitors consolidate shelf space.
- Direct-to-Consumer Replenishment Subscriptions:Online retail platforms enable flavor customization and auto-replenishment models that bypass supermarket slotting fee structures.
- Hypotonic Formulation Innovation:Endurance athlete segments seeking faster gastric emptying represent untapped white space distinct from commoditized isotonic volume.
Industry Challenges
- ASEAN Harmonization Timeline Uncertainty:Divergent functional beverage classification standards across member states force manufacturers to maintain multiple label variants and compliance protocols.
- Electrolyte Stability Expertise Gap:Formulation chemists capable of balancing osmolarity targets with shelf-stable mineral solubility command premium compensation, constraining R&D team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sports Drink Market |
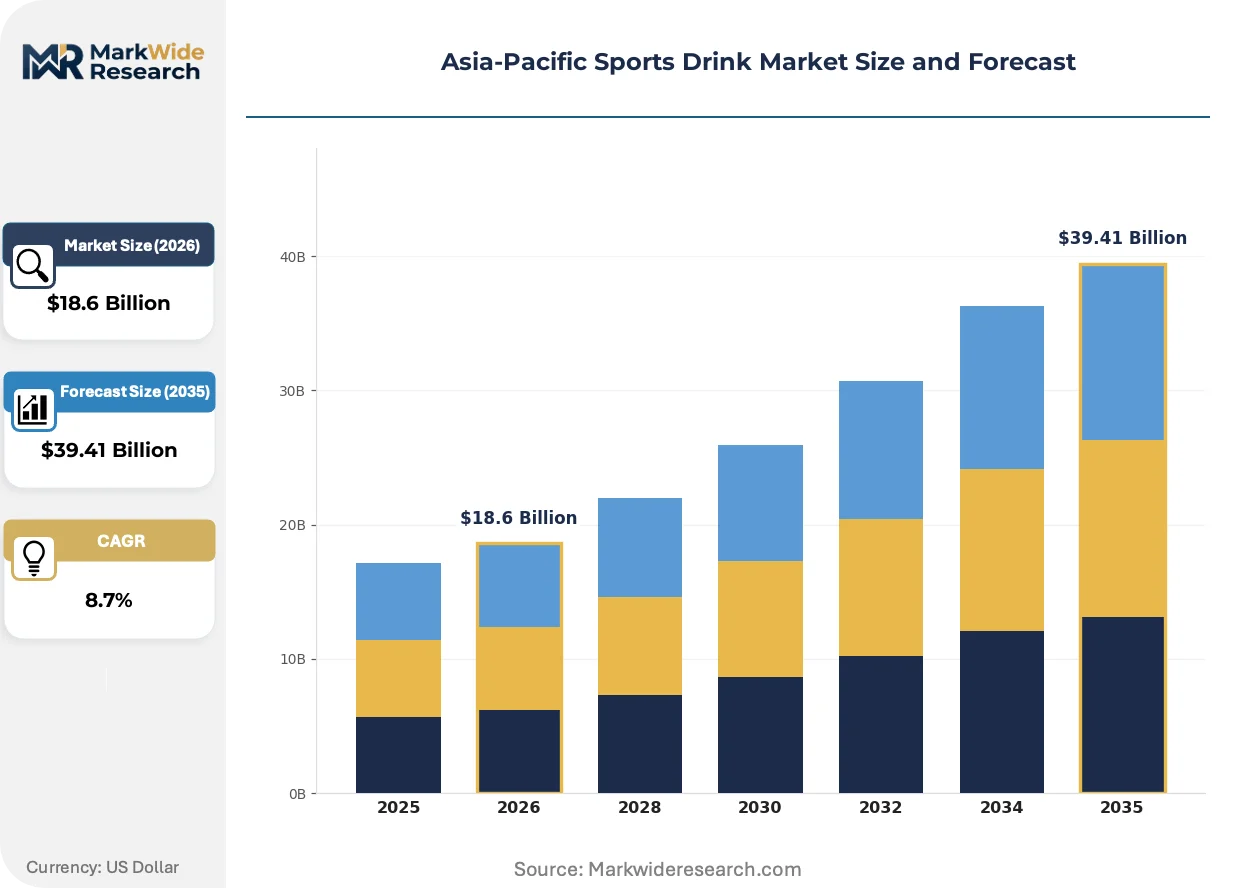
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Energy Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Athletes, Fitness Enthusiasts, Casual Consumers, Children Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Thai Beverages PCL, Carabao Group Public Company Limited, Otsuka Holdings Co Ltd, Nongfu Spring Co., Ltd., Beijing Genki Forest Beverage Co Ltd, PepsiCo, Inc., The Coca-Cola Company, Sapporo Holdings Limited, Suntory Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sports Drink Market Strategic Shifts
Formulation science and channel architecture are converging to redefine how hydration products reach consumers. Beverage firms now compete on physiological efficacy claims backed by compositional precision rather than flavor innovation alone.
Electrolyte-carbohydrate matrices incorporating branched-chain amino acids and adaptogenic botanicals are hybridizing traditional sports drink functionality with wellness positioning. Endurance athletes and weekend warriors adopt these enhanced formulations at accelerating rates. The technology is hybridizing product categories, compressing boundaries between medical-grade rehydration solutions and lifestyle beverages.
Japan's Ministry of Health, Labour and Welfare maintains strict labeling standards that shape regional formulation requirements. Manufacturers must reformulate sugar content and electrolyte ratios to qualify for functional beverage certification. Premium positioning in Japanese retail channels depends on compliance with these medical-adjacent thresholds.
Subscription-based replenishment models are displacing supermarket-centric purchasing patterns among urban professionals. Direct-to-consumer platforms capture athlete segments seeking personalized flavor profiles and delivery cadences. China's tier-one cities exhibit the fastest migration toward digital-first hydration procurement.
Asia-Pacific Sports Drink Market Segmentation
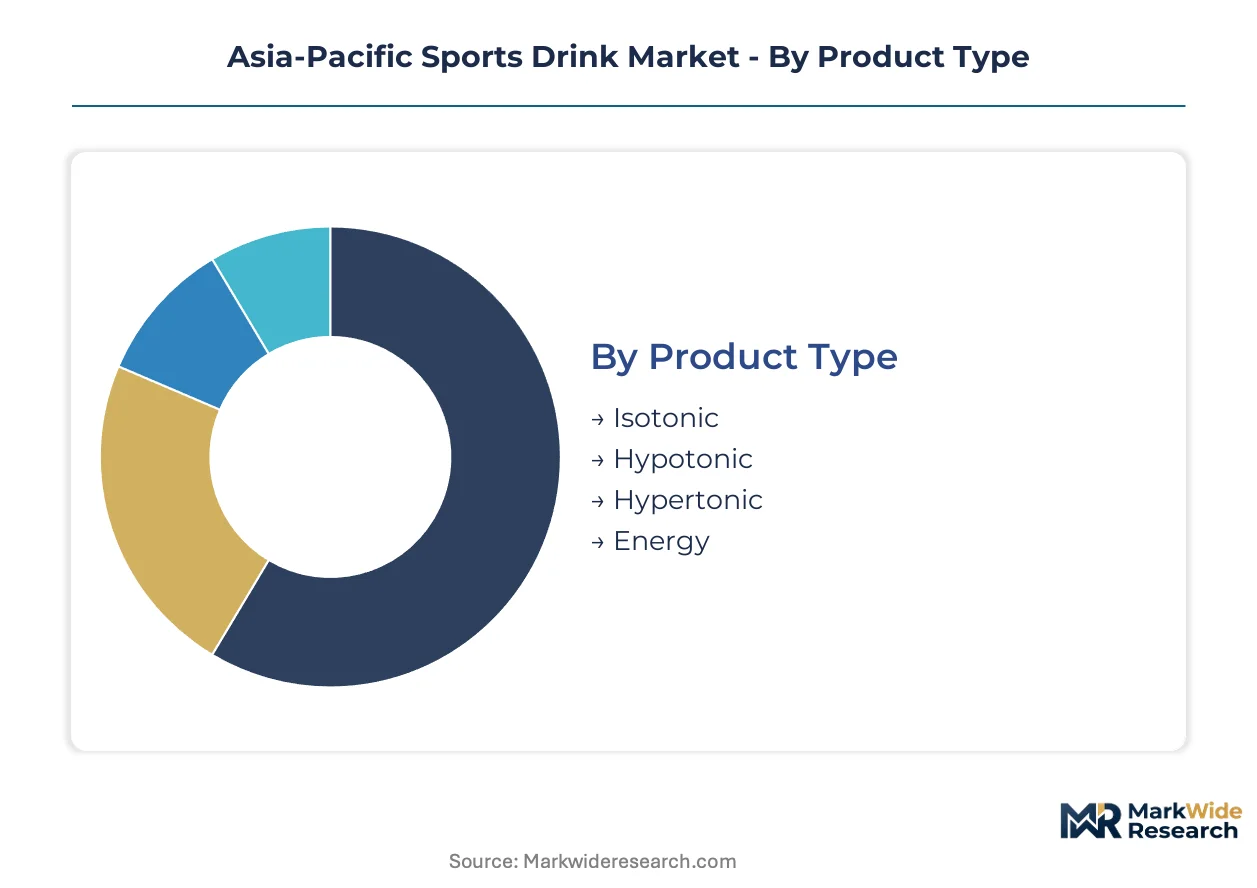
Formulation osmolarity, channel architecture, and consumer physiology intersect to create distinct competitive battlegrounds across the Asia-Pacific sports drink landscape. Each segmentation dimension carries regulatory and logistical implications that reshape how manufacturers configure their regional portfolios.
Product Type:
Cost tier stratification separates medical-grade formulations from mass-market hydration, with osmolarity specifications determining shelf positioning and margin structures.
- Isotonic:Electrolyte-carbohydrate matrices matching human blood plasma osmolarity deliver balanced fluid absorption without gastric distress. China's tier-one cities concentrate habitual consumption among white-collar professionals seeking post-workout recovery, though high-fructose corn syrup price volatility squeezes margin structures for volume producers.
- Hypotonic:Lower solute concentration accelerates gastric emptying for endurance athletes prioritizing rapid hydration over energy delivery. Marathon sponsorships and gym partnerships across Southeast Asian cities are compressing consumption cycles as fitness enthusiasts adopt these formulations for workout-aligned replenishment rather than traditional meal occasions.
- Hypertonic:Elevated carbohydrate density targets energy-intensive endurance events requiring sustained glycogen replenishment.
- Energy:Caffeine-amino acid hybrids blur boundaries between hydration and stimulant categories, constrained by Australia's Therapeutic Goods Administration caffeine limits.
Isotonic formulations command the established base. The steepest expansion runs through hypotonic variants.
Distribution Channel:
Channel selection dictates refrigeration requirements, slotting fee exposure, and consumer relationship depth across ambient and cold-chain retail networks.
- Supermarkets:Mass retail footprints in China's urban centers sustain volume throughput for standardized flavor portfolios, though slotting fees erode net margins for new entrants.
- Convenience Stores:Ambient shelf-stable formats enabled by hot-fill aseptic processing extend distribution reach into Southeast Asia's high-frequency purchase locations.
- Online Retail:Direct-to-consumer platforms bypass traditional supermarket slotting structures while enabling flavor customization and auto-replenishment subscriptions. China's tier-one cities exhibit the fastest migration toward digital-first hydration procurement among urban professionals.
- Specialty Stores:Pharmacy-channel concentration in Japan funnels medical-grade electrolyte products through Otsuka Holdings-dominated networks, creating entry barriers for competing brands.
Supermarket and convenience store networks anchor volume throughput. Digital channels are gaining share fastest.
End User:
Application intensity varies from medical-grade rehydration protocols to lifestyle-oriented consumption, with physiological requirements shaping formulation specifications.
- Athletes:Competitive and endurance participants demand precise electrolyte ratios verified by Japan's Ministry of Health, Labour and Welfare labeling standards.
- Fitness Enthusiasts:Gym culture proliferation across Southeast Asian cities compresses consumption cycles as this segment seeks workout-schedule-aligned replenishment. The segment is expanding most quickly as urban fitness infrastructure penetrates secondary cities.
- Casual Consumers:Lifestyle hydration positioning captures non-athletic occasions, constrained by China's SAMR functional claim verification timelines.
- Children:Pediatric formulations face stricter compositional limits under Food Standards Australia New Zealand additive palettes.
Casual consumption commands the established base. Fitness enthusiasts represent the steepest expansion trajectory.
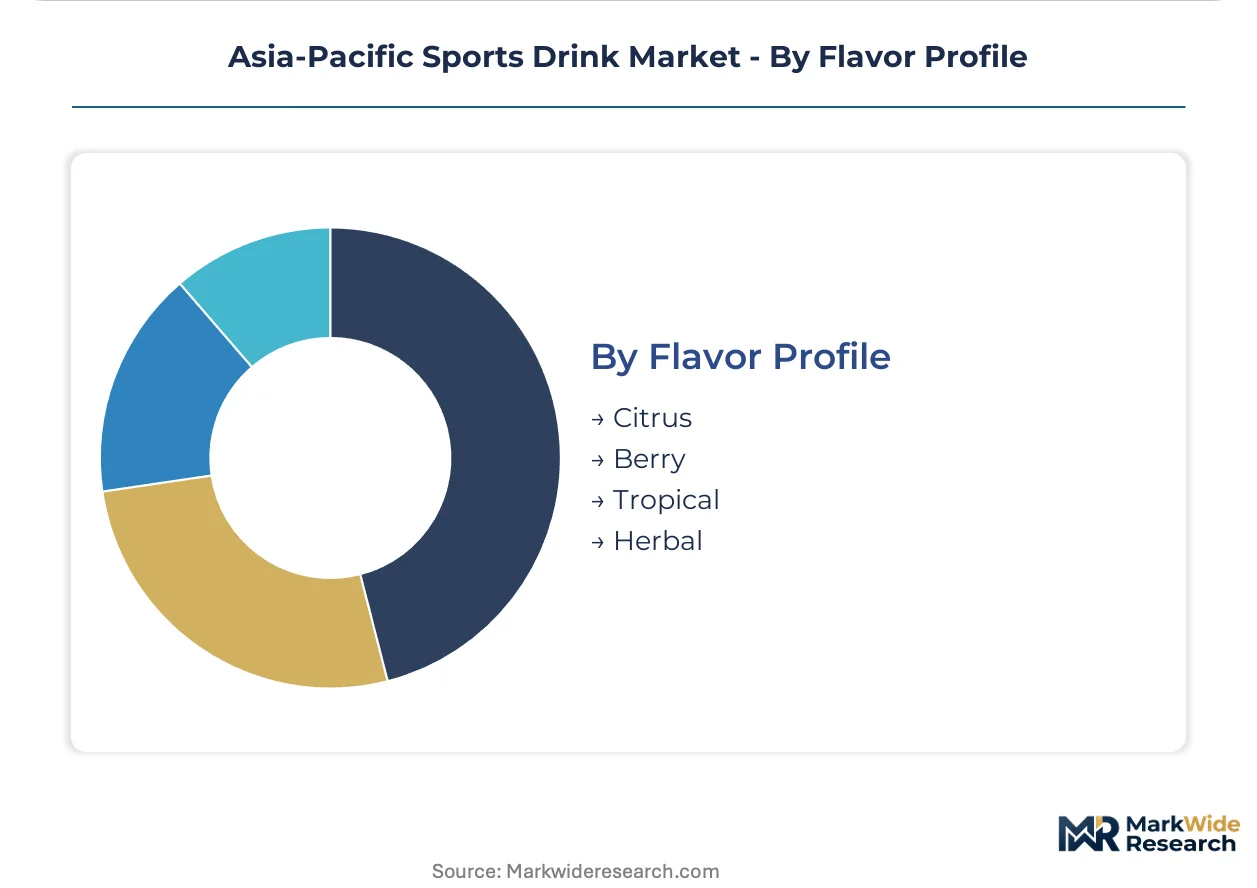
Flavor Profile:
Regional palate preferences and botanical ingredient availability differentiate formulation portfolios across tropical and temperate climate zones.
- Citrus:Lemon-lime and orange variants dominate mass-market isotonic formulations with established consumer recognition.
- Berry:Anthocyanin-rich profiles align with wellness positioning among urban female consumers in Japan's pharmacy channels.
- Tropical:Coconut water and passionfruit extracts leverage Southeast Asian agricultural supply chains for localized production.
- Herbal:Adaptogenic botanicals hybridize traditional sports drink functionality with wellness claims, requiring navigation of China's functional claim approval protocols.
Citrus and berry profiles command the established base. Herbal infusions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific sports drink landscape. Japanese consumers treat electrolyte beverages as medical-grade rehydration solutions purchased through pharmacy channels. Southeast Asian markets favor ambient shelf-stable formats distributed through convenience stores.
China
Marathon sponsorships and gym partnerships in Beijing, Shanghai, and Shenzhen compress consumption cycles among white-collar professionals. SAMR functional claim verification timelines extend 18-24 months, delaying product launches for enhanced formulations. Yangtze River Delta manufacturing clusters supply hot-fill aseptic processing capacity for domestic brands.
Japan
Pharmacy-channel concentration funnels medical-grade electrolyte sales through specialized retail networks. METI and PMDA labeling standards enforce compositional thresholds that determine premium shelf positioning. Kanto region consumers associate sports drinks with heatstroke prevention during humid summer months.
Thailand
Energy-drink heritage creates consumer receptivity to caffeine-amino acid hybrid formulations. Tropical climate sustains year-round hydration demand absent seasonal compression. Bangkok-based distributors leverage ambient retail infrastructure to reach secondary cities.
Vietnam
Underpenetrated mass retail in secondary cities presents first-mover advantages for brands establishing ambient distribution. Local sugar supply chains reduce carbohydrate sourcing costs relative to import-dependent neighbors. Ho Chi Minh City fitness infrastructure spreads gym culture consumption patterns.
Indonesia
Archipelago logistics challenge cold-chain distribution, favoring shelf-stable hot-fill processed formats. Java-based manufacturing clusters serve domestic demand while navigating halal certification requirements for export markets. Jakarta fitness enthusiasts drive adoption of workout-schedule-aligned replenishment.
Asia-Pacific Sports Drink Market Competitive Environment
Capability concentration sits with pharmaceutical-grade formulators; scale advantage sits with beverage conglomerates with Southeast Asian bottling networks. The market structures around three tiers: multinational soft drink giants, regional health beverage specialists, and domestic water companies diversifying into functional hydration. Dominant competitive moves include pharmacy-channel partnerships in Japan and marathon sponsorships in China's tier-one cities.
Among Japan-based health beverage specialists, Otsuka Holdings occupies a position exemplifying pharmacy-channel dominance. Chinese domestic water companies diversifying into functional hydration include Nongfu Spring and Beijing Genki Forest Beverage. PepsiCo represents multinational soft drink giants leveraging Southeast Asian bottling infrastructure for distribution density.
| Leading Market Players |
|---|
| Thai Beverages PCL |
| Carabao Group Public Company Limited |
| Otsuka Holdings Co Ltd |
| Nongfu Spring Co., Ltd. |
| Beijing Genki Forest Beverage Co Ltd |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Sapporo Holdings Limited |
| Suntory Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta hot-fill aseptic processing clusters is driving contract manufacturers toward aggressive pricing to secure volume commitments, compressing margins for branded players while enabling new entrants to access production capacity without capital-intensive facility investments.
Pricing Analysis
Long-term offtake agreements between beverage conglomerates and Southeast Asian bottling networks dominate procurement structures, insulating volume producers from high-fructose corn syrup spot price volatility. Price differentiation rests on FOSHU certification tier in Japan and halal compliance grade in Indonesia. Pricing pressure intensifies in China's mass retail tier as Nongfu Spring's marathon-sponsored volume plays compress competitor margin structures. Casual consumers in Vietnam's secondary cities exhibit highest price sensitivity; pharmacy-channel fitness enthusiasts in Japan's Kanto region demonstrate lowest.
Supply Chain Analysis
Contract-manufacturing concentration sits with Thai Beverages PCL's Bangkok facilities, Suntory Holdings' Kanto region plants, and PepsiCo's archipelago bottling network across Indonesia. Raw material dependencies center on Australian cane sugar, Vietnamese passionfruit extracts, and Malaysian palm-derived emulsifiers. Supply chain risk concentrates in single-source vulnerability for electrolyte mineral premixes sourced through Japanese trading houses. Distribution runs through ambient convenience store networks in Southeast Asia and pharmacy-channel cold-chain in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific sports drinks are reconfiguring around service-attach revenue streams, with subscription-based hydration coaching apps and auto-replenishment platforms expanding faster than base beverage volume as urban professionals prioritize personalized consumption cadences over supermarket replenishment.
For Market Incumbents: Build switching-cost moats through proprietary electrolyte stability IP and locked-in pharmacy-channel shelf space. Defend against direct-to-consumer entrants by accelerating flavor customization capabilities and deepening auto-replenishment subscription penetration in China's tier-one cities. Prioritize backward integration into mineral premix sourcing to insulate margins from Japanese trading house concentration.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated secondary cities before local competitors consolidate ambient distribution networks. Target hypotonic formulation white space among endurance athletes seeking faster gastric emptying, distinct from commoditized isotonic volume. Launch through digital-first replenishment subscriptions bypassing supermarket slotting fee structures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-to-consumer platform infrastructure as cloud-native fulfillment stacks reduce warehouse requirements. Five-to-ten year viability favors brands with pharmacy-channel certification pathways and proprietary formulation IP over pure-play distribution assets. Watch ASEAN harmonization timeline announcements as inflection signal for cross-border manufacturing consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy-Channel Partnership | Otsuka Holdings' network dominance in Japan creates certification-dependent shelf access. |
| Direct-to-Consumer Platform Launch | Auto-replenishment subscriptions in China's tier-one cities bypass supermarket slotting fees. |
| Hypotonic Formulation Introduction | Endurance athlete targeting differentiates from commoditized isotonic volume plays. |
| Backward Integration into Mineral Sourcing | Electrolyte premix captive supply reduces Japanese trading house dependency. |
| Marathon Sponsorship Expansion | Beijing and Shanghai event partnerships compress consumption cycles among white-collar professionals. |
Study Parameters
Operator-level perspectives from brand managers at multinational beverage conglomerates, category buyers at Chinese supermarket chains, pharmacy-channel procurement leads in Japan, formulation chemists at health beverage specialists, and Southeast Asian bottling network operations directors anchored the qualitative base. Secondary validation drew from customs records, Nielsen retail audit data, Ministry of Health Labour and Welfare FOSHU certification databases, and State Administration for Market Regulation functional claim filings. Bottom-up volume modeling triangulated against top-down category spend analysis.
Scenario-bracketing across high-fructose corn syrup price volatility bands, ASEAN harmonization timeline variants, and digital channel penetration rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled included formulation osmolarity tier, distribution channel type, end-user application intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to category-level consumption data, with electrolyte stability expertise scarcity and pharmacy-channel shelf access constraints as industry-specific forecast inputs.
Stress conditions across agricultural commodity cycles, regulatory approval timeline extensions, and cold-chain logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding urban fitness infrastructure penetration and digital platform adoption curves. Cross-checking against external beverage industry volume benchmarks and regional retail audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
South America Sports Drinks Market