
 Global Gummy Supplements Market | 2026-2036
Global Gummy Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gummy Supplements Market Foresight
The EU's novel food regulation is pivoting how gummy supplement entrants structure their clinical substantiation budgets. Bayer AG leverages its pharmaceutical heritage to anchor premium positioning across European pharmacies. Nestlé S.A. competes through pediatric formulation expertise and licensed character partnerships. Unilever Plc extends its wellness portfolio into gummy formats via targeted channel expansion in emerging Asian markets.
Gummy supplements are chewable, gelatin or pectin-based delivery vehicles containing vitamins, minerals, botanical extracts, or functional actives, manufactured through starch molding or depositing processes at controlled temperature and humidity parameters to preserve bioactive stability. Their primary commercial purpose centers on converting reluctant pill consumers into compliant daily users through palatability and convenience. Multivitamin gummies occupy the largest revenue pool due to household penetration and repeat purchase frequency, while probiotic gummies represent the fastest-expanding category as microbiome science migrates into mainstream consumer awareness. Collagen gummies concentrate margin in the beauty-from-within segment, where per-unit pricing tolerates premium positioning.
FDA's Current Good Manufacturing Practice enforcement, EFSA health claim authorization pathways, and China's SAMR blue-hat registration requirements collectively determine which formulations achieve cross-border commercialization. These frameworks elevate barriers for unvalidated ingredient suppliers while creating competitive shelter for dossier-complete incumbents. Stakeholders must monitor evolving substantiation thresholds as regulators tighten the evidentiary gap between structure-function claims and disease-prevention language.
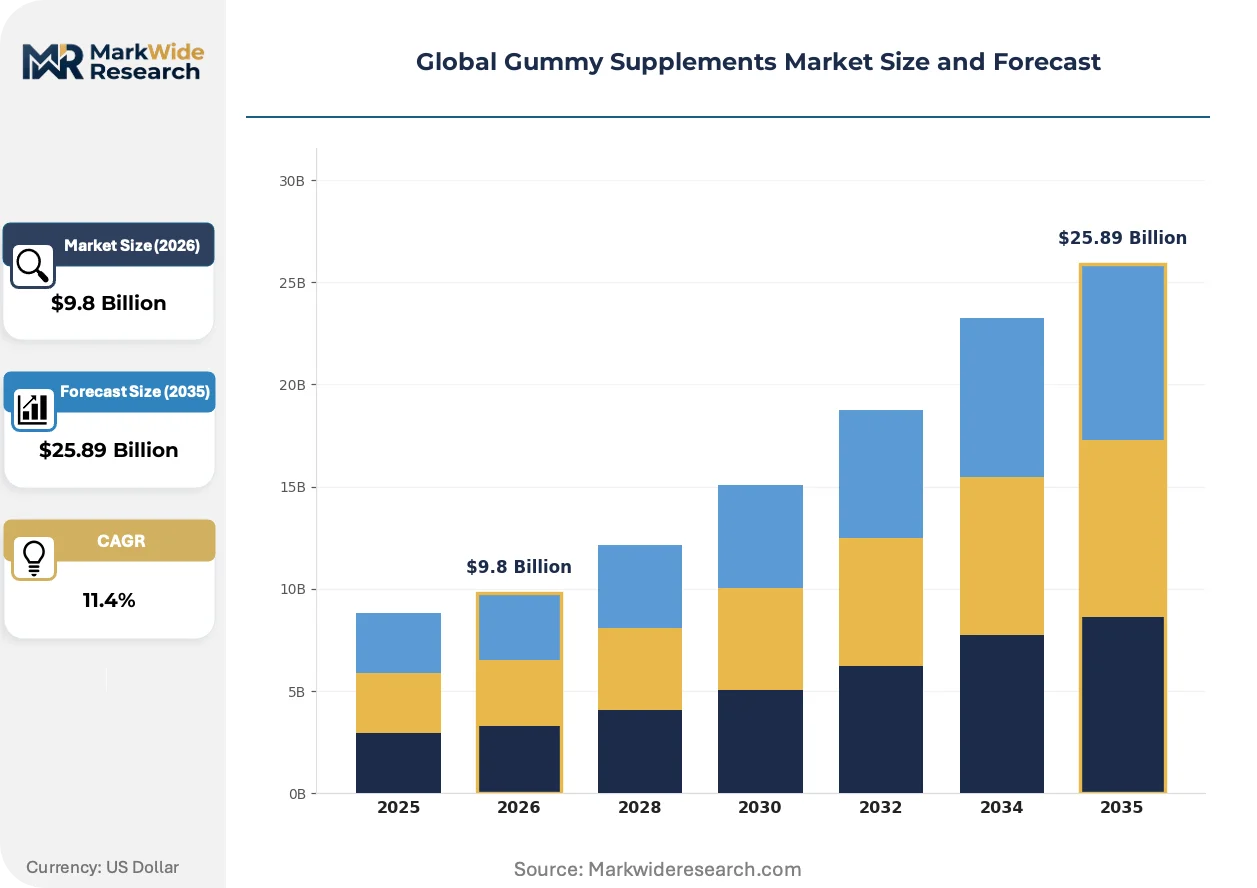
Market Dynamics
Post-pandemic preventive health normalization has permanently altered adult purchasing patterns for palatable delivery formats, while FDA labeling enforcement and EFSA novel food pathways simultaneously elevate compliance thresholds and favor scaled manufacturers with dossier capabilities.
Growth Catalysts
- Adult Preventive Health Routines:Post-pandemic wellness behavior change sustains household penetration of daily-use formats among working-age demographics seeking compliance without pill fatigue.
- FDA Current Good Manufacturing Practice Enforcement:Elevated cGMP scrutiny filters out substandard operators, creating competitive shelter for manufacturers with validated quality systems and documented batch records.
- Microbiome Science Translation:Probiotic gummies capture expanding consumer awareness of gut-brain axis research, converting clinical findings into mainstream shelf presence.
Market Restraints
- Gelatin and Pectin Input Volatility:Collagen-derived gelatin prices fluctuate with meat processing byproduct availability, compressing margin for non-vertically integrated formulators.
- EFSA Health Claim Authorization Pathways:Substantiation requirements for structure-function crossover claims extend European commercialization timelines and inflate clinical trial budgets.
- Pharmaceutical-Grade Tablet Substitution:Prescription-strength vitamin D and B-complex formulations retain physician preference for diagnosed deficiencies, limiting gummy penetration in clinical channels.
Strategic Opportunities
- India Preventive Wellness Expansion:FSSAI functional food notification pathways and rising disposable incomes create white space for palatable supplement formats beyond traditional Ayurvedic delivery.
- China SAMR Blue-Hat Registration:Foreign brands with complete stability dossiers access the world's largest vitamin consumer base through cross-border e-commerce and domestic pharmacy integration.
- Beauty-From-Within Convergence:Collagen peptide and ceramide gummies capture margin in dermocosmetic adjacencies where per-unit pricing tolerates premium positioning.
Industry Challenges
- Moisture-Sensitive Actives Stabilization:Heat and humidity parameters during starch molding and depositing processes degrade probiotic viability, requiring specialized encapsulation expertise.
- Cross-Border Dossier Harmonization:Divergent FDA, EFSA, and SAMR evidentiary standards force redundant clinical investment for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gummy Supplements Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamin Gummies, Omega-3 Gummies, Probiotic Gummies, Collagen Gummies, Fiber Gummies Application: Immune Support, Digestive Health, Skin Care, Bone Strength, Energy Boost End User: Children, Adults, Seniors, Athletes, Pregnant Women Packaging Type: Bottle, Blister Pack, Sachet, Jar, Tube |
| Companies Covered | Church & Dwight Co., Inc., Haleon Plc, Bayer AG, The Clorox Company, Unilever Plc, Nestlé S.A., H&H Group, Pharmavite LLC, Hero Nutritionals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gummy Supplements Market Shifts & Advancements
Manufacturing automation and regulatory data requirements are compressing competitive dynamics while channel integration and format innovation reshape how consumers encounter and purchase gummy supplements.
Continuous depositing and starch molding systems with inline weight verification and vision inspection are automating quality assurance throughout high-throughput production environments. Scaled contract manufacturers in the United States and Germany deploy these platforms to achieve lot-to-lot consistency demanded by pharmacy retail integration. This automation is compressing the cost gap between artisan small-batch positioning and mass-market unit economics.
EFSA's evolving substantiation thresholds for botanical and probiotic novel food applications are extending European commercialization timelines. Manufacturers must now generate human intervention studies for ingredient dossiers previously accepted on mechanistic rationale. Probiotic gummies with multi-strain formulations face the steepest evidentiary burden, driving some entrants toward single-strain, well-documented cultures.
Direct-to-consumer subscription models with personalized regimen algorithms are displacing intermittent pharmacy and mass retail purchasing among urban adult demographics. These platforms capture recurring revenue through convenience and dosage reminders, while gathering consumption data that informs new product development. Subscription concentration is highest in United States coastal metropolitan markets where wellness app penetration already conditions consumers to automated replenishment.
Global Gummy Supplements Market Segmentation
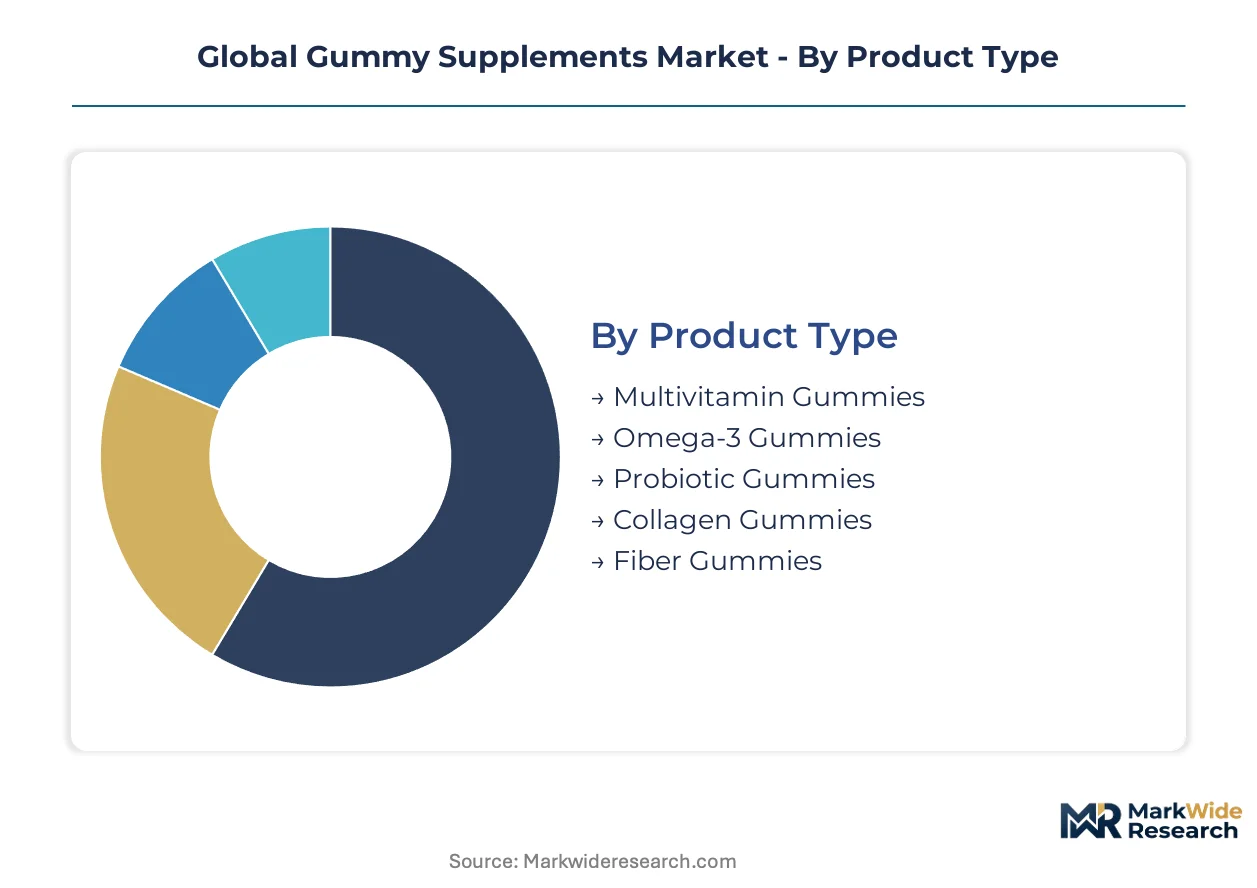
Consumer upgrade cycles in gummy supplements accelerate as households trade up from single-nutrient formats to condition-specific portfolios. Manufacturers calibrate formulation depth, packaging convenience, and demographic targeting to capture recurring purchase commitments across divergent wellness routines.
Product Type:
Reformulation cycles compress as consumers cycle through benefit-specific gummies rather than remaining loyal to single-format multivitamins.
- Multivitamin Gummies:Broad-spectrum vitamin and mineral matrices address baseline nutritional gaps for households seeking simplified compliance routines. United States pharmacy retail channels concentrate demand for these entry-level formats among working-age adults normalizing preventive supplementation.
- Probiotic Gummies:Live culture delivery systems require specialized encapsulation to survive starch molding heat parameters and gastric transit. Microbiome science translation into mainstream consumer awareness drives fastest category expansion in direct-to-consumer subscription channels.
- Omega-3 Gummies:EPA/DHA fatty acid formulations from marine or algal sources target cardiovascular and cognitive benefit claims with taste-masking challenges.
- Collagen Gummies:Hydrolyzed peptide matrices concentrate in beauty-from-within positioning where per-unit pricing tolerates premium tier placement.
- Fiber Gummies:Soluble fiber matrices address digestive regularity with lower active ingredient cost structures enabling mass-market penetration.
Multivitamin Gummies sits at the top of the volume ranking, with Probiotic Gummies climbing the fastest.
Application:
Benefit-specific positioning commands pricing power as consumers graduate from generic wellness claims to targeted condition management.
- Immune Support:Zinc, vitamin C, and elderberry combinations dominate seasonal purchase spikes with repeat cycles tied to cold-weather patterns. United States households concentrate demand for these formulations in pharmacy and mass retail channels.
- Digestive Health:Probiotic and prebiotic fiber combinations address gut microbiome optimization with clinical substantiation requirements varying by jurisdiction. EFSA novel food pathways impose steepest evidentiary burdens for multi-strain probiotic claims in European markets.
- Skin Care:Collagen, biotin, and antioxidant matrices target dermocosmetic adjacencies with premium pricing tolerance.
- Bone Strength:Calcium and vitamin D3 combinations compete with pharmaceutical-grade tablets for diagnosed deficiency markets.
- Energy Boost:B-complex and adaptogenic formulations target working-age demographics seeking fatigue management without stimulant dependency.
Immune Support commands the largest revenue pool, while Digestive Health gains share fastest on microbiome research translation.
End User:
Life-stage targeting determines formulation potency, palatability engineering, and channel selection with distinct compliance drivers across cohorts.
- Adults:Working-age demographics drive preventive health normalization with highest subscription platform penetration and willingness to pay for convenience. Direct-to-consumer channels concentrate demand in United States coastal metropolitan markets.
- Children:Pediatric formulations require precise dosing control and licensed character partnerships to overcome parental compliance resistance. Nestlé S.A. competes through formulation expertise and entertainment property licensing.
- Seniors:Bioavailability-optimized matrices address absorption decline with pharmacy retail integration preferred for trust transfer.
- Athletes:NSF Certified for Sport and Informed Sport verification requirements elevate quality system investment for this credibility-sensitive cohort.
- Pregnant Women:Folate and DHA combinations face stringent purity requirements with healthcare practitioner endorsement critical for purchase authorization.
Adults anchor volume leadership, with Seniors expanding most quickly on aging demographic tailwinds.
Packaging Type:
Packaging selection trades moisture protection, portability, and shelf presence against unit economics with channel-specific optimization requirements.
- Bottle:HDPE and PET containers with desiccant integration dominate pharmacy retail and household pantry storage with lowest per-unit packaging cost. United States mass retail channels concentrate demand for these high-count formats.
- Blister Pack:Individual cavity sealing delivers maximum moisture protection for humidity-sensitive probiotics with travel convenience premium. EFSA-substantiated European brands favor this format for premium positioning.
- Sachet:Single-serve flexibility supports trial conversion and on-the-go consumption with higher packaging cost ratios.
- Jar:Wide-mouth glass or plastic containers enable bulk scooping formats for collagen and fiber matrices.
- Tube:Squeezable or rigid cylindrical formats target portability and counter display optimization.
Bottle formats lead volume, with Blister Pack formats ascending fastest on probiotic moisture protection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gummy supplements first achieved commercial scale in the United States during the early 2000s, when pediatric vitamin brands pioneered starch-molded delivery formats to overcome pill-averse children. This American innovation diffused through European pharmacy channels and Asian cross-border e-commerce, creating geographically distinct regulatory and consumption patterns.
United States
Direct-to-consumer subscription platforms and pharmacy retail integration drive category velocity, with coastal metropolitan households normalizing daily preventive supplementation. FDA Current Good Manufacturing Practice enforcement elevates compliance costs, filtering substandard operators while sheltering scaled manufacturers with validated quality systems. Contract manufacturing clusters in New Jersey and California deploy automated depositing systems to serve private-label and branded customers.
Germany
Pharmacy retail channels concentrate demand for premium-positioned formats, with consumers exhibiting high willingness-to-pay for EFSA-substantiated health claims. The country's novel food regulation extends commercialization timelines for botanical and probiotic entrants, inflating clinical trial budgets. Manufacturing capabilities concentrate in North Rhine-Westphalia, where scaled producers serve both domestic pharmacy chains and export markets.
China
Cross-border e-commerce and domestic pharmacy integration create dual-channel access for foreign brands with complete stability dossiers. SAMR blue-hat registration requirements impose stringent evidentiary standards, favoring incumbents with dossier capabilities over unvalidated entrants. Yangtze River Delta manufacturing hubs specialize in moisture-sensitive active encapsulation for probiotic gummies targeting domestic consumption.
India
Rising disposable incomes and FSSAI functional food notification pathways open white space beyond traditional Ayurvedic delivery formats. Urban working-age demographics in Maharashtra and Karnataka demonstrate growing receptivity to palatable supplement alternatives. Mumbai-based contract manufacturers expand capacity to serve both domestic brands and export markets seeking cost-competitive production.
United Kingdom
Boots and Holland & Barrett pharmacy retail integration sustains demand for mid-tier multivitamin formats, while direct-to-consumer startups capture premium positioning through subscription models. MHRA borderline classification scrutiny tightens enforcement against disease-prevention language in marketing materials. Manufacturing activity clusters in the Midlands, where producers leverage proximity to raw material import infrastructure.
Global Gummy Supplements Market Competitive Landscape
The competitive structure tilts toward diversified consumer health conglomerates with pharmaceutical heritage, creating tiered positioning across mass-market and premium segments. Scale advantages concentrate with manufacturers possessing validated quality systems and complete regulatory dossiers for multi-territory launches. Strategic archetypes include pharmaceutical-descended brands leveraging clinical credibility, FMCG giants extending wellness portfolios, and specialized gummy contract manufacturers serving private-label demand. Dominant competitive moves encompass pharmacy retail integration partnerships and backward integration into gelatin and pectin supply.
Within the pharmaceutical-descended tier, Bayer AG and Haleon Plc exemplify archetypes that anchor premium positioning through clinical heritage and pharmacy channel relationships. Among FMCG-extended players, Nestlé S.A. and Unilever Plc occupy positions translating pediatric formulation expertise and wellness portfolio breadth into gummy format expansion. Church & Dwight Co., Inc. represents the diversified consumer health model, sitting within a structure where household penetration strategies intersect with direct-to-consumer channel experimentation.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Haleon Plc |
| Bayer AG |
| The Clorox Company |
| Unilever Plc |
| Nestlé S.A. |
| H&H Group |
| Pharmavite LLC |
| Hero Nutritionals LLC |
| Others |
Supply & Pricing Matrix
Pharmacy retail and direct-to-consumer subscription buyers concentrate purchasing power in the United States and Germany, anchoring a three-tier pricing structure across premium, standard, and economy levels where EFSA-substantiated claims and cGMP certification command substantial premiums over private-label alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-positioned brands with clinical dossiers from mass-market private labels and entry-level imports. Price differentiation rests on FDA cGMP certification tier and brand heritage, with pharmaceutical-descended incumbents capturing 40-60% premiums over unvalidated entrants. Cost compression in the economy tier is intensifying because gelatin and pectin input volatility squeezes non-vertically integrated formulators. Direct-to-consumer subscribers exhibit lowest price sensitivity, while mass retail immune-support purchasers drive hardest bargain negotiations.
Supply Chain Analysis
FDA cGMP and EFSA novel food qualification gates filter supplier participation, concentrating gelatin and pectin sourcing in the United States, Germany, and Brazil where collagen byproduct processing achieves pharmaceutical-grade consistency. Raw material dependencies center on porcine and bovine collagen derivatives, citrus peel pectin extracts, and specialized probiotic culture banks. Single-source vulnerability in marine collagen peptide supply creates exposure to fisheries regulation shifts. Distribution runs through pharmacy retail chains in developed markets and cross-border e-commerce platforms penetrating China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in gummy supplements hinges on automation-driven cost compression in high-throughput manufacturing and consumer willingness to pay premium tiers for microbiome-targeted formulations with clinical substantiation.
For Market Incumbents: Acquire specialized encapsulation technology providers to secure probiotic viability through starch molding heat parameters. Consolidate backward into gelatin rendering operations to insulate margin from meat processing byproduct volatility. Defensive priority centers on preempting emerging Asian contract manufacturers from capturing EFSA dossier capabilities. For New Entrants and Emerging Players: Encapsulation innovation for moisture-sensitive actives offers the most penetrable wedge against established probiotic gummy incumbents. Target India's FSSAI functional food notification pathway before domestic Ayurvedic brands pivot to palatable formats. Go-to-market leverage rests on direct-to-consumer subscription algorithms with personalized regimen recommendations. For Investors and Strategic Acquirers: Pharmaceutical-descended consumer health divisions are the most active acquirer in this space, seeking gummy format capabilities to extend clinical credibility into preventive wellness. Long-term viability favors scaled manufacturers with complete FDA-EFSA-SAMR dossier harmonization. Acquisition target archetype: mid-cap contract manufacturers with validated quality systems and pharmacy retail integration. Watch for SAMR blue-hat registration backlog clearance as inflection signal for China market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Harmonization | Complete FDA-EFSA-SAMR alignment reduces redundant clinical investment for multi-territory launches. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture in United States coastal metros displaces intermittent pharmacy purchasing patterns. |
| Probiotic Encapsulation Scale-Up | Specialized heat-resistant culture delivery separates premium microbiome positioning from commodity multivitamin tiers. |
| Pharmacy Retail Integration | Boots and CVS shelf presence transfers clinical credibility that pure-play digital brands cannot replicate. |
| Backward Integration into Gelatin Supply | Captive collagen rendering insulates margin from meat processing byproduct price volatility. |
Research Methodology
Multiple input streams — executive interviews with contract manufacturing heads, regulatory affairs specialists at scaled brands, pharmacy category buyers, and formulation R&D directors — were reconciled against FDA cGMP inspection records, EFSA novel food application databases, SAMR blue-hat registration filings, and Nielsen retail audit data. Bottom-up volume modeling across product type, application, end user, and packaging format segments was cross-validated against top-down market sizing from trade customs data and pharmaceutical company segment disclosures.
Data-stream reconciliation applied growth rate derivation from historical trajectory analysis and driver elasticity modeling across the projection horizon. Segmentation dimensions encompassed product type, application benefit claim, life-stage end user, packaging moisture protection tier, and regional regulatory cluster. Forecast inputs incorporated probiotic culture stability parameters, gelatin price index movements, and e-commerce penetration curves by metropolitan market.
The model holds under stable regulatory substantiation thresholds; deviation in EFSA evidentiary requirements or SAMR registration timelines would shift commercialization feasibility and competitive shelter dynamics. Forecasts embody assumptions regarding preventive health behavior persistence and pharmacy retail channel stability. A model refresh is warranted upon material change in FDA cGMP enforcement intensity or cross-border e-commerce tariff treatment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Creatine Market