
 Europe Protein Bar Market | 2026-2036
Europe Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Protein Bar Market Foresight
EU Green Deal packaging mandates are shifting the cost-of-entry calculus for new protein bar entrants. Barebells Functional Foods AB leverages its Nordic supply chain to sustain premium positioning across health stores. General Mills Inc. competes through scale advantages in supermarket distribution. Mondelēz International, Inc. anchors its European portfolio with snack-bar formats that navigate stricter labeling thresholds.
Europe protein bars are shelf-stable, high-protein confectionery products typically containing whey, casein, soy, or pea protein isolates at concentrations of 15–25 grams per serving, manufactured via cold-extrusion or baked-bar processes to preserve amino acid integrity and extend ambient shelf life. Snack bars occupy the largest volume position while meal replacement formats capture disproportionate margin pools in pharmacy and dietetic channels. Chocolate flavor profiles dominate impulse purchases, yet berry variants lead growth in health-conscious consumer segments across Nordic markets.
EFSA nutrition and health claims regulation shapes permissible front-of-pack messaging, while REACH compliance governs migration limits for wrapper laminates and food-contact substances. The EU AI Act will soon classify algorithmic personalization in direct-to-consumer nutrition platforms as high-risk, demanding audit trails for recommendation engines. Stakeholders must monitor how ECHA's expanding restriction candidate list affects novel protein extraction solvents and barrier coatings.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing formulation timelines and forcing capital reallocation toward biodegradable barrier materials and plant-protein supply chains across European manufacturing networks.
Growth Catalysts
- REACH compliance migration limits:ECHA's tightening food-contact substance thresholds are accelerating adoption of cellulose-based wrapper laminates in German and French production facilities.
- Gym culture penetration:Fitness enthusiasts in Warsaw, Prague, and Bucharest are driving snack-bar consumption in Eastern European health clubs and convenience retail.
- EFSA health claims pathway:The regulator's clarified protein-quantity thresholds enable front-of-pack messaging that unlocks pharmacy and dietetic channel placement.
Market Restraints
- Pea protein supply concentration:European extraction capacity clusters in Denmark and the Netherlands, creating input price volatility during harvest disruptions.
- Biodegradable film technical limitations:Current cellulose and PLA barriers exhibit 40-60% shorter shelf stability versus conventional multilayer plastics, constraining export logistics.
- EU AI Act algorithmic audit requirements:Direct-to-consumer personalization engines face high-risk classification, demanding documentation trails that slow platform deployment.
Strategic Opportunities
- Underpenetrated Polish retail:Functional food shelf space in Warsaw and Kraków remains 30-40% below Western European density, offering first-mover positioning.
- Pharmacy channel expansion:Meal-replacement formats with EFSA-backed claims capture disproportionate margins in German and Swedish apothecary networks.
- Cold-extrusion and enzyme technology convergence:Novel protease treatments preserve amino acid integrity at lower thermal inputs, enabling cleaner-label positioning.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise combining protein chemistry with biodegradable packaging engineering concentrates in Nordic and Benelux labor markets.
- Dual certification timelines:Parallel EFSA health-claims validation and ECHA substance registration extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Protein Bar Market |
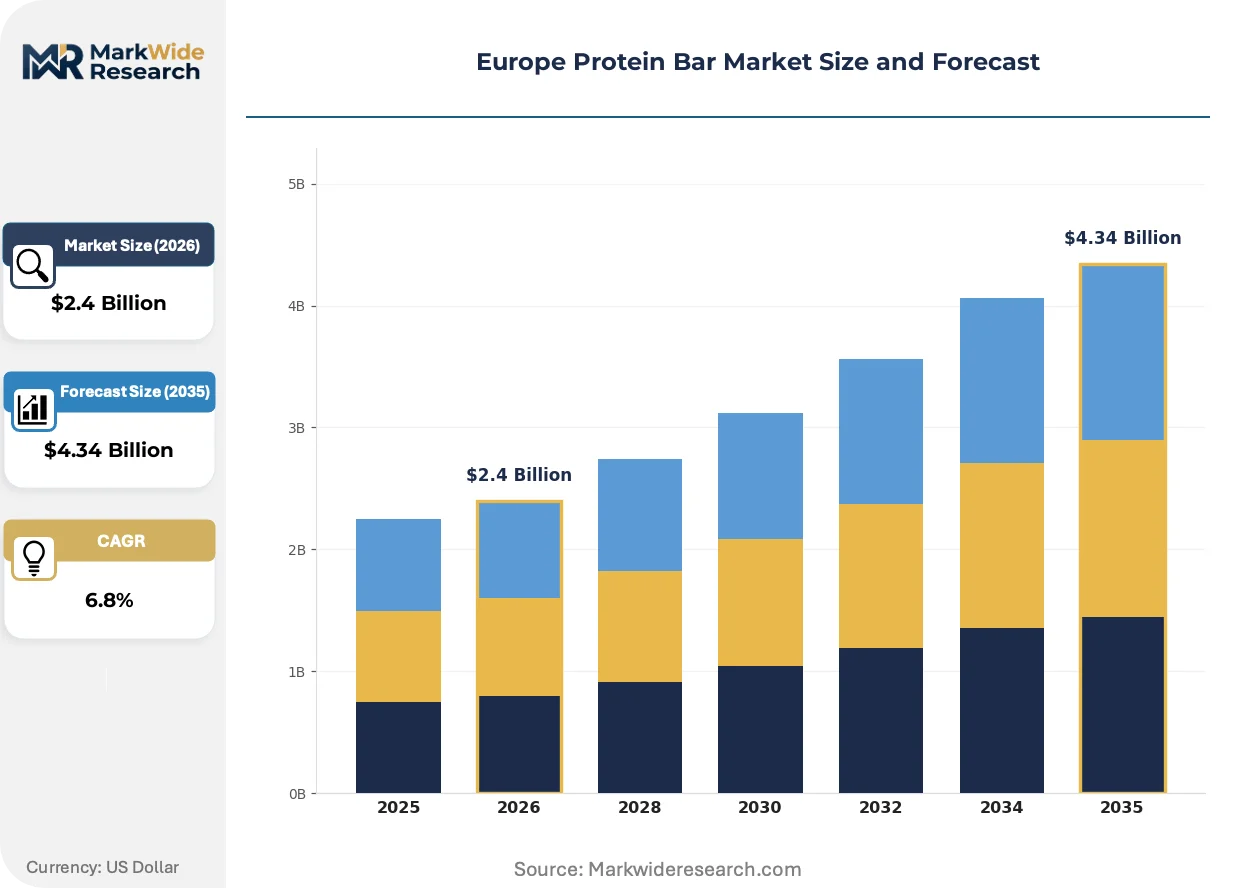
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Snack Bar, Energy Bar, Nutrition Bar Consumer Type: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Diabetics Flavor Profile: Chocolate, Vanilla, Peanut Butter, Berry Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | General Mills Inc., Barebells Functional Foods AB, Mars Inc., The Kellogg Company, PepsiCo Inc., Mondelēz International, Inc., Glanbia plc, Optimum Nutrition Inc., Nestlé S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Protein Bar Market Shifts & Advancements
Formulation science and regulatory compliance are converging to redefine competitive advantage, with shelf-life engineering and algorithmic personalization emerging as distinct capability battlegrounds.
Fermented protein isolates from fungal biomass are expanding into European manufacturing lines as an alternative to soy and pea concentrates. Dutch and Danish ingredient suppliers are scaling precision-fermentation capacity to serve mid-tier bar manufacturers seeking differentiated amino-acid profiles. This biotechnology is expanding into premium positioning claims that command shelf-space allocation in health-focused retail banners.
EFSA's 2023 guidance on protein-quantity thresholds for front-of-pack claims has compressed permissible messaging to 15-gram minimums per serving. German and Austrian manufacturers are reformulating recipes to clear this bar while maintaining taste profiles acceptable to mass-market palates. The regulation is reshaping competitive positioning most acutely in supermarket channels where label clarity drives impulse conversion.
Gym-goers in Berlin, Munich, and Hamburg are consolidating purchases through subscription-based direct-to-consumer platforms that bypass traditional retail markup. These digital-native buyers prioritize flavor rotation and personalized macronutrient stacking over brand loyalty. Subscription penetration runs highest among 25-34-year-old male consumers in German metropolitan zones.
Europe Protein Bar Market Segmentation
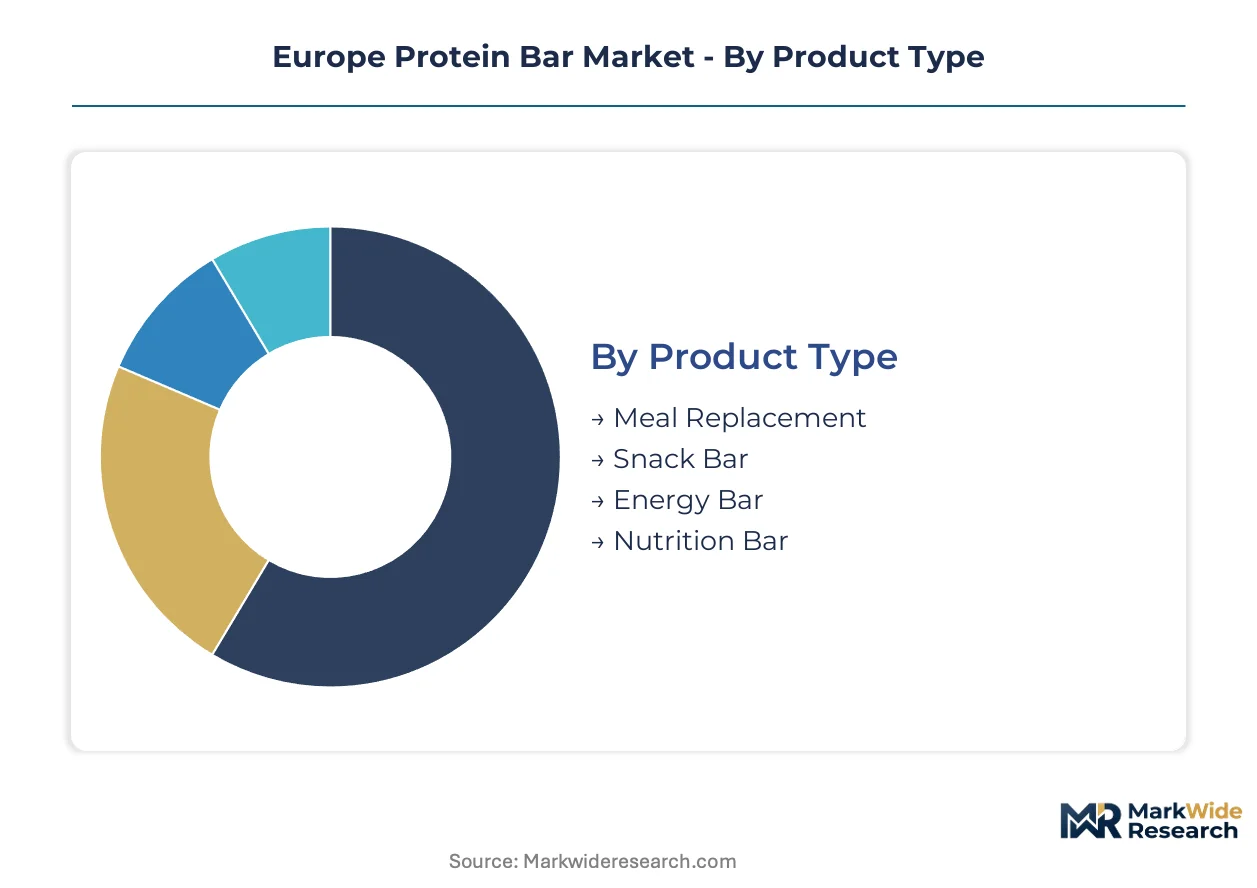
Protein bar manufacturers in Europe configure their portfolios across four intersecting dimensions. Product format determines margin structure and channel access. Consumer targeting shapes formulation intensity and regulatory pathway. These segment boundaries dictate where specialized players compete versus where scale operators dominate.
Product Type:
Standalone formats operate independently of meal timing, while embedded systems integrate into broader nutrition protocols.
- Meal Replacement:High-protein formulations exceeding 20 grams per serving with fortified micronutrient matrices. German and Swedish pharmacy chains capture premium placement for diabetic and weight-management protocols. EFSA health-claims validation unlocks reimbursement-adjacent positioning.
- Snack Bar:Mid-range protein concentrations of 10–15 grams optimized for impulse purchase and convenience retail. Warsaw and Prague health clubs drive volume through grab-and-go placement near checkout counters. Gym culture penetration in Eastern Europe accelerates this segment's expansion trajectory.
- Energy Bar:Carbohydrate-forward formulations with moderate protein for endurance activity support. Cyclists and trail runners in Alpine regions generate concentrated demand during seasonal peaks.
- Nutrition Bar:Broad-spectrum positioning targeting general wellness consumers without specific performance claims. Supermarket banners in France and Italy allocate shelf space based on clean-label ingredient transparency.
Snack bars lead volumes today; meal replacement formats are gaining share fastest.
Consumer Type:
Cost tiers stratify sharply between performance-optimized and lifestyle-oriented buyer groups.
- Athletes:Competitive and recreational competitors requiring batch-tested formulations with banned-substance certification. Nordic markets concentrate demand through specialized sports nutrition retail.
- Fitness Enthusiasts:Gym members pursuing body composition goals through structured macronutrient timing. Bucharest and Budapest health clubs represent underpenetrated expansion zones with rising membership density.
- Health-Conscious Consumers:Mainstream buyers prioritizing convenience and perceived wellness benefits over performance metrics. Berry flavor variants outperform in this segment across Scandinavian markets.
- Diabetics:Medically indicated users requiring glycemic control through low-carbohydrate, high-protein formulations. German apothecary networks capture disproportionate margins through prescription-adjacent counseling.
Fitness enthusiasts anchor volume concentration; diabetic-targeted formulations are expanding most quickly.
Flavor Profile:
Application context determines whether flavor serves impulse conversion or sustained consumption loyalty.
- Chocolate:Dominant impulse purchase driver across supermarket and convenience channels. Cocoa-based coatings mask protein aftertaste in whey-dominant formulations. German mass-market retail depends on this profile for basket-building promotions.
- Vanilla:Neutral base supporting mix-in customization and clean-label positioning. Meal replacement formats in Swedish pharmacy channels favor this profile for perceived naturalness.
- Peanut Butter:Texture-forward variant with satiety signaling for American-influenced product lines. Dutch and Belgian consumers show elevated preference in health store channels.
- Berry:Antioxidant-associated positioning capturing health-conscious segments in Nordic markets. Cold-extrusion processes preserve delicate flavor compounds for premium shelf placement.
Chocolate dominates absolute volumes; berry variants are climbing the fastest in health-focused retail banners.
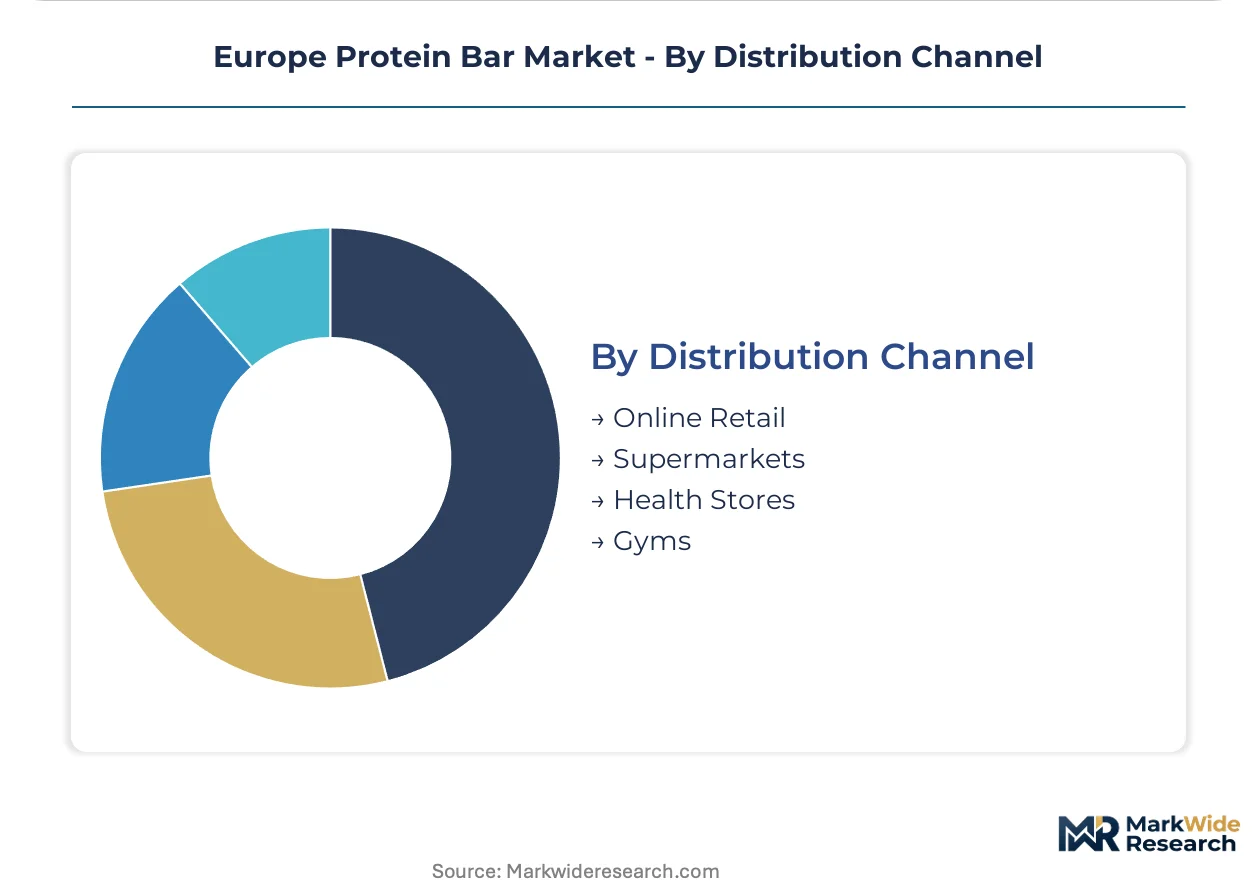
Distribution Channel:
Customer acquisition economics diverge between high-touch physical environments and algorithmic digital platforms.
- Online Retail:Subscription-based direct-to-consumer models with personalized macronutrient stacking. Berlin and Hamburg metropolitan zones show highest penetration among 25–34-year-old male demographics.
- Supermarkets:Mass-market volume engine dependent on front-of-pack EFSA-compliant claims and promotional slotting fees. German retail density outpaces neighboring markets.
- Health Stores:Premium positioning through curated assortment and staff recommendation. Barebells and Nordic competitors defend shelf space through exclusive flavor rotations.
- Gyms:Immediate consumption occasion with minimal price sensitivity during post-workout windows. Eastern European health clubs in Warsaw and Prague represent first-mover expansion opportunities.
Supermarkets anchor volume today; online retail is gaining share fastest through subscription lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and food technologists cluster in Nordic and Benelux labor markets, anchoring Europe's protein bar innovation pipeline. German retail density and sports nutrition acceptance outpace neighboring markets. Eastern European gym culture penetration creates new demand concentrations.
Germany
Fitness enthusiasts in Berlin, Munich, and Hamburg drive subscription-based direct-to-consumer purchases through personalized macronutrient platforms. EFSA's clarified protein-quantity thresholds for front-of-pack claims enable pharmacy channel placement for meal replacement formats. Baden-Württemberg and Bavaria house concentrated cold-extrusion manufacturing capacity serving mass-market supermarket distribution.
Sweden
Apothecary networks in Stockholm and Gothenburg capture disproportionate margins through prescription-adjacent counseling for diabetic-targeted formulations. REACH compliance migration limits accelerate cellulose-based wrapper laminate adoption in production facilities. Nordic supply chain integration sustains premium positioning across health store channels nationwide.
Poland
Warsaw and Kraków health clubs represent underpenetrated expansion zones with functional food shelf space 30-40% below Western European density. Gym culture penetration drives snack-bar consumption through grab-and-go placement near checkout counters. The country's central European logistics position enables export distribution into neighboring Baltic states.
Netherlands
Precision-fermentation capacity from Dutch ingredient suppliers scales alternative protein isolates for mid-tier bar manufacturers seeking differentiated amino-acid profiles. ECHA's tightening food-contact substance thresholds shape biodegradable barrier material selection. Rotterdam and Amsterdam anchor plant-protein extraction clusters supplying reformulation pipelines across the region.
France
Supermarket banners in Paris and Lyon allocate shelf space based on clean-label ingredient transparency for broad-spectrum nutrition bars. EU Green Deal packaging waste directives compress formulation timelines toward biodegradable solutions. The country's food-contact regulatory expertise concentrates compliance advisory services for cross-border market access.
Europe Protein Bar Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate scale advantages in supermarket distribution while boutique health store channels sustain premium fragmentation. Three strategic archetypes dominate: multinational CPG operators leveraging existing retail relationships, Nordic-born functional food specialists with supply chain integration, and sports nutrition pure-plays targeting gym-channel immediacy. Competitive moves center on portfolio diversification into plant-protein formats and strategic partnerships for biodegradable packaging co-development.
Among diversified CPG operators, General Mills Inc. and Mondelēz International, Inc. occupy positions exemplifying scale-driven supermarket penetration. Barebells Functional Foods AB represents the focused specialist archetype with Nordic supply chain anchoring. These three companies illustrate the competitive tension between mass-market reach and premium positioning that shapes category dynamics.
| Leading Market Players |
|---|
| General Mills Inc. |
| Barebells Functional Foods AB |
| Mars Inc. |
| The Kellogg Company |
| PepsiCo Inc. |
| Mondelēz International, Inc. |
| Glanbia plc |
| Optimum Nutrition Inc. |
| Nestlé S.A. |
| Others |
Supply & Pricing Matrix
Fitness enthusiasts concentrated in German metropolitan zones anchor the dominant subscription-based pricing model, with direct-to-consumer platforms capturing recurring revenue streams that bypass traditional retail markup structures. This buyer archetype's preference for personalized macronutrient stacking over brand loyalty compresses pricing power for mass-market supermarket tiers while sustaining premium positioning in health store channels.
Pricing Analysis
Unbundled product-only transactions dominate supermarket and gym channels, while bundled subscription services incorporating flavor rotation and algorithmic personalization command sustained premium positioning in direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated meal replacement formats in pharmacy channels from mid-range snack bars and basic nutrition bars in mass retail. Cost compression in standard-tier supermarket placement is intensifying because of promotional slotting fee escalation and private-label encroachment. Fitness enthusiasts show lowest price sensitivity during immediate post-workout consumption windows, while health-conscious mainstream buyers in French and Italian supermarkets exhibit highest elasticity.
Supply Chain Analysis
Food technologist talent scarcity in Nordic and Benelux labor markets constrains formulation capacity expansion, with protein chemistry and biodegradable packaging engineering expertise clustering in Denmark, Sweden, and the Netherlands. Manufacturing draws from pea protein extraction facilities in Denmark and the Netherlands, cellulose-based wrapper laminate producers in Germany and France, and precision-fermentation capacity from Dutch ingredient suppliers. Single-source vulnerability runs through concentrated pea protein extraction capacity exposed to harvest disruption risks. Distribution runs through supermarket banners in Germany, pharmacy networks in Sweden, health store channels across Nordic markets, and emerging gym-based immediate consumption points in Eastern European cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe protein bar market functions as a stable compounder, with gym culture penetration across Eastern European cities generating predictable volume expansion that offsets margin pressure in saturated Western European retail channels.
For Market Incumbents: To counter algorithmic personalization platforms eroding brand loyalty among 25-34-year-old male consumers in Berlin and Hamburg, incumbents should deepen exclusive flavor rotation partnerships with health store banners and accelerate in-house production of cellulose-based wrapper laminates to secure biodegradable packaging supply. Channel control through direct-to-consumer platform investment represents the critical defensive lever against subscription-based disintermediation. For New Entrants and Emerging Players: Precision-fermentation protein isolates offer technology-first wedge positioning for mid-tier manufacturers seeking differentiated amino-acid profiles without competing against established whey and soy supply chains. Polish health clubs in Warsaw and Kraków present the most penetrable geography, with functional food shelf space 30-40% below Western European density. Pharmacy channel expansion with EFSA-backed meal replacement claims captures disproportionate margin pools in German and Swedish apothecary networks. For Investors and Strategic Acquirers: Diversified CPG conglomerates seeking sports nutrition portfolio expansion are the most active acquirer in this space, targeting functional food specialists with integrated Nordic supply chains and established health store distribution. Long-term viability rests on regulatory compliance capabilities spanning EFSA health-claims validation and ECHA substance registration. Watch for EU AI Act enforcement triggering documentation trail requirements that slow direct-to-consumer platform deployment as an inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Co-Development | EU Green Deal compliance accelerates cellulose laminate adoption in German and French production facilities. |
| Pharmacy Channel Expansion | EFSA-validated meal replacement formats unlock reimbursement-adjacent positioning in Swedish apothecary networks. |
| Precision-Fermentation Scale-Up | Dutch ingredient suppliers expand fungal biomass protein capacity serving mid-tier bar manufacturers. |
| Direct-to-Consumer Platform Launch | Subscription models bypass retail markup in Berlin and Hamburg metropolitan zones among fitness enthusiasts. |
| Eastern European Gym Distribution | Warsaw and Prague health clubs represent underpenetrated grab-and-go placement opportunities. |
Research Methodology
Multiple input streams — formulation interviews with R&D directors at protein bar manufacturers, procurement discussions with health store category managers, regulatory consultations with EFSA and ECHA specialists, and distribution channel analysis with supermarket buyers — were reconciled against secondary validation from EU regulatory filings, Nielsen retail audit data, customs trade records, and sports nutrition industry association reports. Bottom-up volume modeling across product format, consumer type, and distribution channel segments was cross-checked against top-down market sizing from macro consumption trends.
Historical consumption patterns were cross-referenced against expert panel inputs from food technologists and supply chain planners to generate projection trajectories across the analysis window. Segmentation dimensions modeled include product format, consumer targeting, flavor profile, and distribution channel, with additional granularity on regulatory compliance tier. CAGRs were derived from trend extrapolation adjusted for identified catalyst and restraint dynamics, incorporating pea protein supply volatility indices and biodegradable packaging adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement timing, ECHA restriction candidate list expansion, and Eastern European gym membership growth trajectories. Forecasts reflect assumptions about regulatory pathway stability and supply chain configuration continuity. Material deviation in biodegradable barrier material technical performance or EFSA claims validation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Weight Management Products Market