
 Parallel Bars Market | 2026-2036
Parallel Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Parallel Bars Market Analytics
Sporting goods distribution through specialty fitness dealers is reconfiguring as direct-to-institution sales gain share. Taishan Sports Industry Group leverages its Olympic supplier status to anchor government procurement contracts across Asia. American Athletic competes through domestic manufacturing scale and rapid custom fabrication turnaround. Bailey Manufacturing Company specializes in rehabilitation-grade parallel bars with ADA-compliant adjustability, occupying the medical channel with differentiated clinical specifications.
Parallel bars consist of two horizontal rails supported by vertical uprights, typically manufactured from laminated maple, powder-coated steel, or aircraft-grade aluminum with height adjustability ranging from ground level to 2.0 meters. These apparatuses serve competitive gymnastics, physical therapy protocols, and adaptive fitness programs requiring bilateral upper-extremity support. Adjustable parallel bars command the widest addressable base across end users, while composite materials represent the fastest-growing material category as facilities seek moisture-resistant alternatives to traditional wood. The rehabilitation application segment carries the strongest margin profile due to clinical certification requirements and insurance reimbursement pathways that sustain premium positioning.
ASTM International governs apparatus safety standards in the United States, while the International Gymnastics Federation (FIG) regulates competitive equipment specifications for international events. The European Committee for Standardization (CEN) oversees EN 913 harmonized standards for gymnastics equipment across EU member states, creating a dual compliance burden for exporters. China's National Standards (GB) mandate load testing and surface finish protocols through the Standardization Administration. Stakeholders must monitor evolving FIG apparatus norms and national accessibility mandates, as these standards will determine which product configurations qualify for institutional funding and competitive certification.
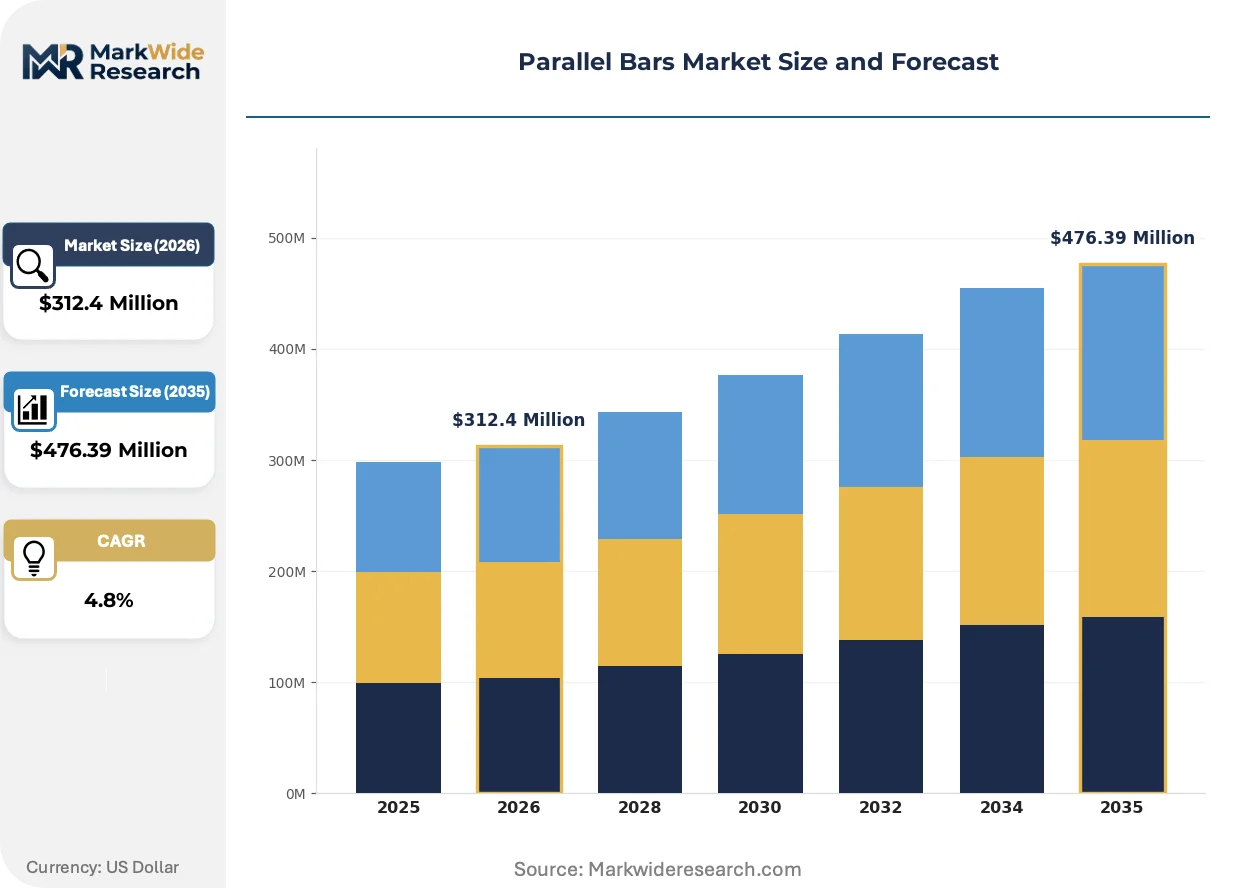
Market Dynamics
Adaptive sports infrastructure investment across Germany, China, and the United States is compressing procurement cycles and forcing manufacturers to certify products simultaneously under FIG competition standards and national accessibility mandates.
Growth Catalysts
- ASTM F1749 Safety Standards:Tightened certification requirements in North America are filtering out uncertified suppliers and consolidating procurement toward verified manufacturers.
- Rehabilitation Clinics:Physical therapy protocols are expanding equipment procurement as insurance reimbursement pathways stabilize for bilateral upper-extremity support apparatus.
- Adaptive Sports Infrastructure:School physical education programs in China are mandating inclusive equipment specifications that require height-adjustable parallel bars.
Market Restraints
- Aircraft-Grade Aluminum Input Costs:Volatility in aerospace-grade metal pricing compresses margin structures for premium adjustable systems.
- Dual Compliance Burden:EN 913 harmonized standards and FIG apparatus norms create redundant testing costs for European exporters.
- Composite Material Substitution:Moisture-resistant synthetic alternatives threaten traditional laminated maple in climate-variable facilities.
Strategic Opportunities
- Underpenetrated Rehabilitation Channels:Medical-grade parallel bars with ADA-compliant adjustability remain undersupplied in outpatient clinics.
- Direct-to-Institution Sales:Specialty fitness dealer disintermediation opens margin recovery for manufacturers with government procurement credentials.
- Convergence of Telehealth and Home Rehabilitation:Remote physical therapy protocols are creating demand for compact, collapsible parallel bar systems.
Industry Challenges
- Certification Timeline Compression:Simultaneous FIG, ASTM, and GB standard compliance requires extended laboratory validation cycles.
- Legacy Woodworking Skill Scarcity:Laminated maple rail fabrication expertise concentrates among aging craftspeople in traditional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parallel Bars Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable, Fixed, Portable, Wall-mounted End User: Gymnasts, Physiotherapists, Fitness Centers, Schools Material: Wood, Steel, Aluminum, Composite Application: Rehabilitation, Training, Competitive, Recreational |
| Companies Covered | Lebert, Tumbl Trak, Taishan Sports Industry Group, GoBeast, Juperbsky, IDEER LIFE, American Athletic, Mancino Manufacturing, Bailey Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parallel Bars Market Evolving Landscape
Material science advances and procurement model evolution are fragmenting traditional supply relationships while elevating clinical certification as a primary purchase determinant.
Composite reinforcement technology is migrating from marine and aerospace applications into gymnastics apparatus manufacturing. Rehabilitation centers in the United States are specifying carbon-fiber hybrid rails for moisture resistance and load consistency. This migration from conventional wood-laminate construction is compressing maintenance budgets and extending equipment depreciation schedules.
China's GB standards for load testing and surface finish protocols are tightening export certification requirements for foreign manufacturers. The Standardization Administration mandates third-party laboratory verification for all apparatus entering domestic competition venues. European suppliers targeting Chinese adaptive sports programs must now duplicate testing under both EN 913 and GB frameworks.
Institutional buyers are consolidating vendor relationships around Olympic supplier status and rapid custom fabrication capabilities. Government procurement contracts across Asia now require demonstration of prior major event supply credentials. This concentration is visible in municipal physical education tenders where single-source awards replace competitive bidding.
Parallel Bars Market Segmentation
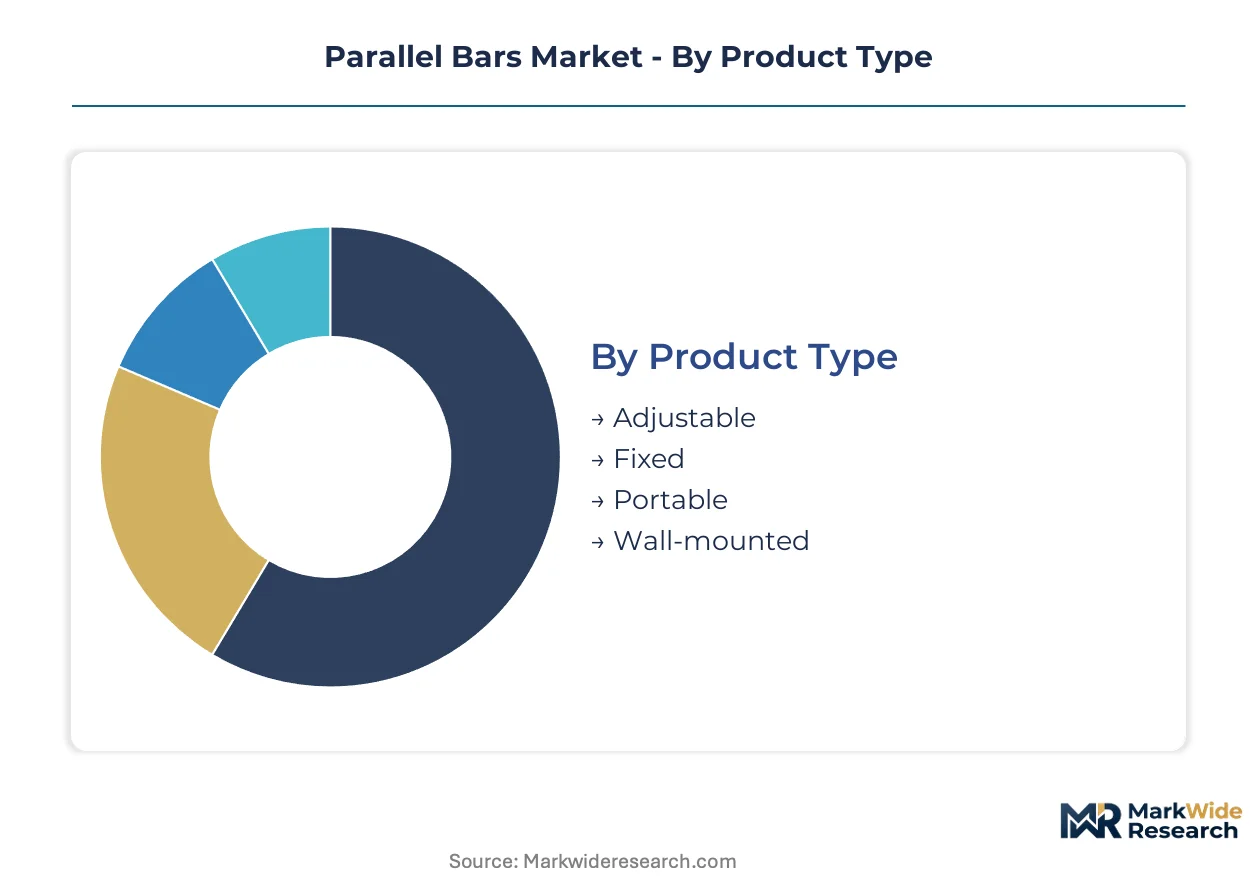
Parallel bars segmentation reveals how equipment specifications diverge across institutional buyers with distinct compliance burdens and performance requirements. Product configurations must simultaneously satisfy FIG competition norms, clinical certification standards, and school accessibility mandates.
Product Type:
Mature fixed installations dominate established gymnastics venues, while emerging portable formats address telehealth and home rehabilitation expansion.
- Adjustable:Height-modifiable systems spanning ground level to 2.0 meters incorporate powder-coated steel uprights with aircraft-grade aluminum rails. Rehabilitation clinics in the United States specify these for ADA-compliant patient protocols, with insurance reimbursement pathways sustaining premium procurement.
- Fixed:Permanent installations with laminated maple rails anchored to concrete foundations serve competitive gymnastics venues. Germany's adaptive sports infrastructure investments concentrate demand here, as municipal tenders require FIG-certified apparatus with extended depreciation schedules.
- Portable:Collapsible frames with quick-release mechanisms enable remote physical therapy delivery. Compact systems address home rehabilitation growth.
- Wall-mounted:Space-constrained installations fold against vertical surfaces when not in active use. School physical education programs in China specify these for multi-purpose gymnasiums.
Adjustable systems handle the majority of throughput; portable configurations are gaining share fastest as telehealth protocols expand.
End User:
Cost tier stratification separates clinical-grade procurement from mass-market institutional purchasing.
- Physiotherapists:Clinical-grade parallel bars with bilateral upper-extremity support specifications command the strongest margin profile. Medical certification requirements and insurance reimbursement pathways in the United States sustain premium positioning for ADA-compliant adjustability.
- Gymnasts:Competition-grade apparatus must satisfy FIG apparatus norms for international events. Laminated maple rail construction concentrates among aging craftspeople with legacy woodworking expertise.
- Fitness Centers:Commercial installations balance durability against maintenance budget constraints. Moisture-resistant composite alternatives displace traditional wood in climate-variable facilities.
- Schools:Inclusive equipment specifications mandate height-adjustable configurations for adaptive physical education. China's government procurement contracts require prior major event supply credentials.
Physiotherapists drive margin concentration; schools provide the steepest volume expansion trajectory through infrastructure mandates.
Material:
Supply concentration for laminated maple fabrication expertise shapes competitive positioning among traditional manufacturers.
- Composite:Carbon-fiber hybrid rails migrated from marine and aerospace applications deliver moisture resistance and load consistency. Rehabilitation centers in the United States specify these to compress maintenance budgets and extend depreciation schedules.
- Wood:Traditional laminated maple construction remains standard for FIG competition apparatus. Legacy craftsmanship scarcity concentrates production among established manufacturing clusters.
- Steel:Powder-coated uprights provide structural support across adjustable and fixed configurations. Cost volatility affects margin structures less severely than aerospace metals.
- Aluminum:Aircraft-grade specifications enable lightweight rail systems with precise adjustability. Input cost volatility from aerospace sector pricing compresses margins for premium systems.
Wood retains the installed base; composite materials are expanding most quickly as facilities prioritize moisture resistance.
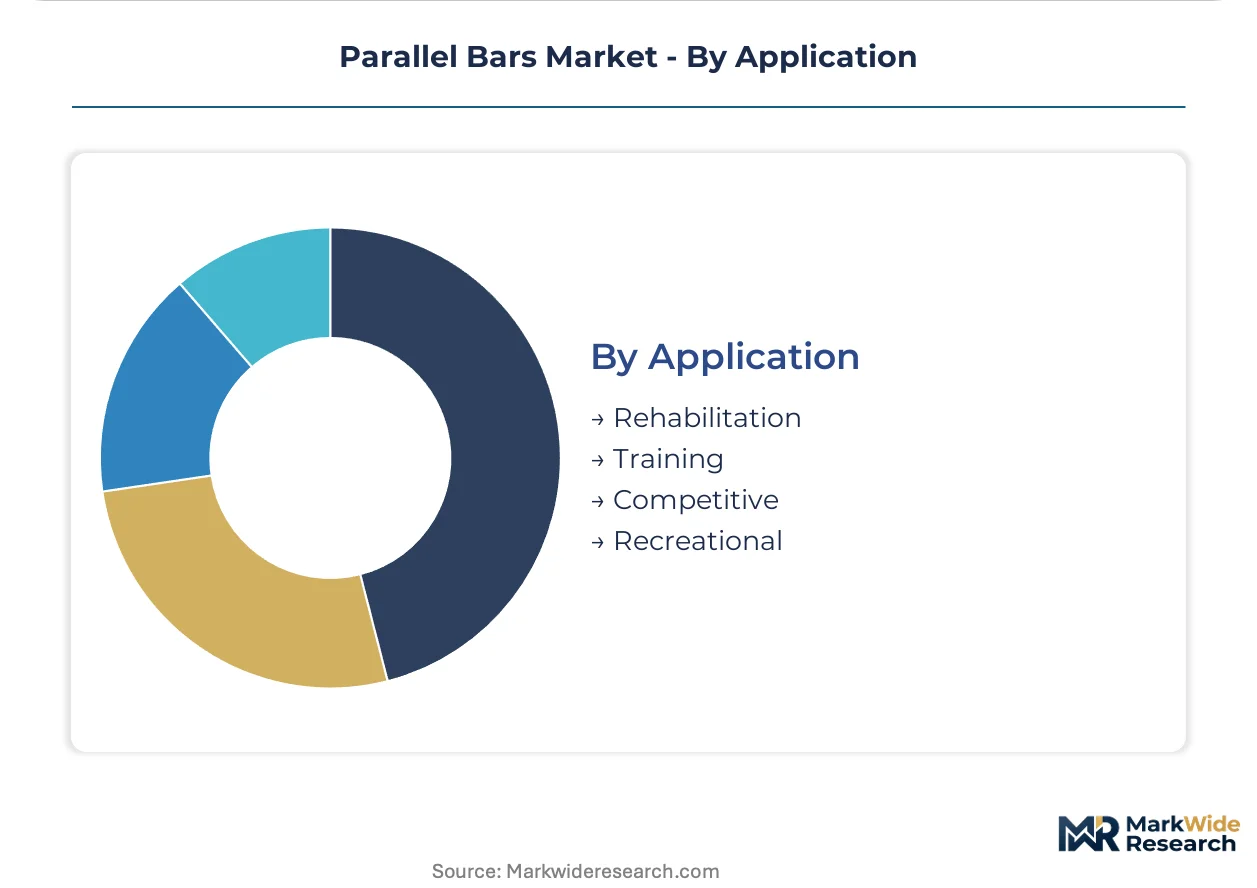
Application:
Margin differentiation separates clinically certified rehabilitation equipment from recreational installations with minimal compliance burden.
- Rehabilitation:Medical-grade parallel bars require clinical certification and satisfy insurance reimbursement pathways. ADA-compliant adjustability specifications in the United States sustain premium positioning absent in other segments.
- Competitive:FIG apparatus norms govern international event equipment with harmonized EN 913 standards creating dual compliance burden for European exporters. Load testing and surface finish protocols demand third-party laboratory verification.
- Training:Gymnastics practice equipment balances durability against cost constraints for high-frequency institutional use. Municipal physical education programs drive volume procurement.
- Recreational:Community center and home fitness installations prioritize accessibility and storage efficiency over competitive specifications. Price sensitivity concentrates demand in standard-grade configurations.
Rehabilitation commands the strongest margin structure; competitive applications face the most stringent certification timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM International governs apparatus safety standards in the United States, while parallel bar demand concentrates across Germany, China, and the United States as these nations expand adaptive sports infrastructure and rehabilitation clinic networks.
United States
Rehabilitation clinics drive equipment procurement through stabilized insurance reimbursement pathways for bilateral upper-extremity support apparatus. ASTM F1749 safety standards tighten certification requirements, filtering procurement toward verified manufacturers. Manufacturing clusters in the Midwest and Southeast concentrate domestic production capacity for medical-grade adjustable systems.
Germany
Municipal adaptive sports infrastructure investments compress procurement cycles for FIG-certified permanent installations. The European Committee for Standardization oversees EN 913 harmonized standards, creating dual compliance burdens for equipment exporters. Industrial fabricators in Bavaria and North Rhine-Westphalia anchor European supply for laminated maple competition apparatus.
China
School physical education programs mandate inclusive equipment specifications requiring height-adjustable parallel bars. The Standardization Administration mandates GB standards for load testing and surface finish protocols through third-party laboratory verification. Manufacturing gravity centers in Shandong Province leverage Olympic supplier credentials to anchor government procurement contracts.
Japan
Aging demographics expand demand for rehabilitation-grade equipment in outpatient clinical settings. METI oversees industrial standards coordination while JIS specifications govern structural load requirements. Fabrication expertise concentrates in the Chubu region around Nagoya, where precision metalworking traditions support aircraft-grade aluminum rail production.
Australia
Adaptive fitness programs in municipal recreation centers drive specification of moisture-resistant composite rail systems. The Therapeutic Goods Administration influences clinical equipment procurement standards through alignment with international certification frameworks. Equipment distribution concentrates through Sydney and Melbourne specialty fitness dealer networks serving institutional buyers.
Parallel Bars Market Competitive Landscape
Olympic-credentialed suppliers and domestic manufacturing specialists split the market along certification depth and fabrication speed vectors. The vendor base concentrates around three strategic archetypes: government-contract anchor firms leveraging prior major event supply credentials, rapid-turnaround custom fabricators serving institutional procurement cycles, and clinical-grade specialists occupying rehabilitation channels through ADA-compliant specifications. Competitive maneuvering centers on simultaneous multi-standard certification acceleration and direct-to-institution sales channel development to bypass traditional specialty dealer networks.
Among Asia-Pacific-based suppliers, Taishan Sports Industry Group occupies the government-contract anchor position, while American Athletic and Bailey Manufacturing Company exemplify the North American manufacturing specialist tier. Taishan leverages its Olympic supplier status to secure municipal physical education tenders across Chinese provinces. American Athletic competes through domestic fabrication scale and compressed custom order turnaround timelines. Bailey Manufacturing Company sits within the clinical-grade specialist archetype, serving rehabilitation channels where insurance reimbursement pathways sustain premium equipment positioning.
| Leading Market Players |
|---|
| Lebert |
| Tumbl Trak |
| Taishan Sports Industry Group |
| GoBeast |
| Juperbsky |
| IDEER LIFE |
| American Athletic |
| Mancino Manufacturing |
| Bailey Manufacturing Company |
| Others |
Value Network & Pricing Analysis
Aircraft-grade aluminum input cost volatility from aerospace sector pricing swings compresses margin structures for premium adjustable systems while simultaneously forcing manufacturers to tier procurement strategies across domestic and offshore fabrication sources. This commodity exposure determines both the spread between clinical-grade and standard equipment pricing and the geographic distribution of laminate rail versus metal rail production capacity.
Pricing Analysis
Configured-to-order pricing for ADA-compliant rehabilitation systems commands substantial premiums over standard institutional configurations. Pricing stratifies across premium clinical certification, standard FIG-compliant competition, and economy recreational tiers, with differentiation driven by ASTM F1749 compliance depth and customization turnaround speed. Cost compression in the economy tier intensifies as composite material substitution erodes traditional wood-laminate positioning. School physical education programs exhibit highest price sensitivity; rehabilitation clinics demonstrate lowest sensitivity due to insurance reimbursement pathways.
Supply Chain Analysis
Contract manufacturing concentration for laminated maple rail fabrication rests with aging craft clusters in the American Midwest and Germany's Bavaria region. Raw material dependencies include Canadian maple veneer, Chinese powder-coated steel uprights, and aerospace-grade aluminum from domestic US mills. Single-source vulnerability concentrates in legacy woodworking expertise as generational skill transfer stalls. Distribution runs through direct-to-institution government procurement channels and specialty fitness dealer networks serving municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face an urgent substitution defense as carbon-fiber composite rails displace traditional laminated maple in moisture-sensitive installations. Composite migration threatens to commoditize the wood-laminate premium that has sustained FIG-certified competition equipment positioning.
For Market Incumbents: Entrench clinical certification advantages by accelerating simultaneous ASTM F1749, EN 913, and GB standard compliance to capture rehabilitation channel premiums. Deepen backward integration into carbon-fiber rail fabrication before composite expertise concentrates among aerospace suppliers. Lock government procurement credentials through Olympic supplier status demonstration to forestall dealer network disintermediation.
For New Entrants and Emerging Players: Outpatient rehabilitation clinic networks in Japan's aging demographic regions offer the most penetrable white-space opportunity. Compact portable systems for telehealth home delivery protocols remain undersupplied relative to remote physical therapy expansion. Enter through direct-to-clinic sales bypassing established dealer relationships, leveraging rapid custom fabrication turnaround as competitive wedge.
For Investors and Strategic Acquirers: The market sits at a certification consolidation phase that favors clinical-grade specialists with multi-standard laboratory relationships over commodity recreation suppliers. Long-term viability over the next decade hinges on adaptive sports infrastructure mandates stabilizing institutional demand. Acquisition targets should demonstrate existing FIG, ASTM, and GB testing credentials. Monitor quarterly FIG apparatus norm revisions and national accessibility mandate rollouts as inflection indicators for procurement priority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Acceleration | Simultaneous ASTM F1749, EN 913, and GB compliance unlocks government procurement contracts across US, EU, and Chinese adaptive sports programs. |
| Composite Rail Manufacturing Scale-Up | Carbon-fiber hybrid production capacity captures rehabilitation center demand for moisture-resistant alternatives to traditional laminated maple. |
| Direct-to-Institution Channel Development | Bypassing specialty fitness dealer networks recovers margin compression from distributor markups in municipal physical education tenders. |
| Telehealth-Compatible Portable System Launch | Collapsible quick-release designs address remote physical therapy protocol expansion in home rehabilitation segments. |
| Olympic Supplier Credential Leverage | Prior major event supply demonstration anchors single-source government awards in Asian municipal procurement cycles. |
Research Methodology
Desk research of FIG apparatus norm documentation, ASTM International safety standards filings, and national accessibility mandate databases preceded structured interviews with rehabilitation clinic procurement directors, gymnastics equipment fabricators, municipal physical education administrators, and adaptive sports program coordinators. Secondary validation drew from customs trade data for gymnastics apparatus imports, hospital equipment procurement databases, and GPO contract disclosures. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from institutional funding flow analysis.
Fixed assumptions across the projection horizon held FIG certification requirements stable, insurance reimbursement pathways for bilateral upper-extremity support apparatus unchanged, and aerospace aluminum pricing volatility within observed historical bands. Segmentation dimensions modeled included product type tier, material category, end-user channel, and application compliance burden. CAGRs derived from regression analysis against adaptive sports infrastructure investment trajectories and rehabilitation clinic network expansion rates, incorporating carbon-fiber substitution elasticity and woodworking skill scarcity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration into composite manufacturing by traditional wood-laminate specialists would shift outcomes substantially. Regulatory acceleration in Chinese GB standard enforcement or sudden FIG apparatus norm revision represents primary forecast revision risk. Quarterly review of national accessibility mandate adoption rates and aerospace sector aluminum pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Air Cushion Basketball Shoes Market