
 Sports Nutrition Ingredients Market | 2026-2036
Sports Nutrition Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Nutrition Ingredients Market Analysis
Ingredient customization revenue is reconfiguring margin pools away from bulk commodity sales toward tailored premix and flavor-system services. Glanbia plc leverages its dairy protein extraction infrastructure to dominate whey isolate supply for North American performance brands. Kerry Group plc sustains competitive positioning through encapsulated amino acid technologies that mask bitterness in ready-to-drink formats. Cargill anchors global carbohydrate ingredient flows with modified starches engineered for sustained-release energy applications.
Sports nutrition ingredients comprise bioactive compounds, macronutrient fractions, and micronutrient complexes formulated at specified purity thresholds, typically exceeding 80% protein content for isolates or defined BCAA ratios of 2:1:1 leucine to isoleucine to valine, serving primarily to enhance athletic recovery, hypertrophy, and metabolic performance in commercial supplement manufacturing. Proteins occupy the largest value share due to established consumer recognition and higher per-kilogram pricing, while amino acids represent the fastest-expanding category as endurance athletes and aging populations adopt targeted leucine supplementation for muscle protein synthesis. Powder formulations retain volume leadership across distribution channels, though liquid concentrates gain traction in health club vending and convenience retail.
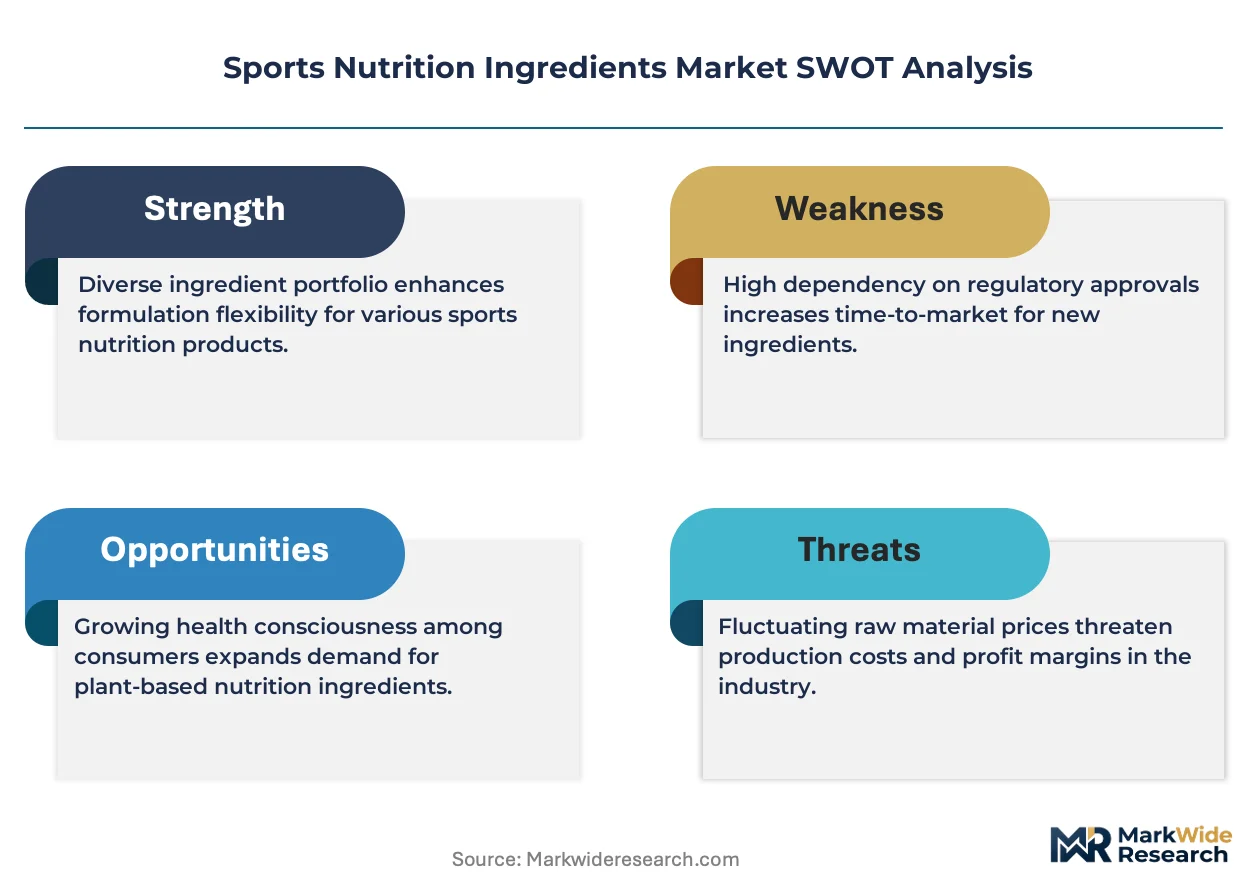
EFSA novel food assessments and FDA GRAS self-affirmation pathways shape ingredient approval timelines and label claim permissibility across European and North American markets. FSSAI fortification standards in India and China's SAMR health food registration requirements create additional compliance layers for brands seeking Asian market access. Stakeholders must monitor evolving caffeine and stimulant thresholds from ANVISA and TGA, as regulatory divergence between jurisdictions threatens formulation standardization strategies and complicates global product portfolio architecture.
Market Dynamics
Clean-label certification mandates from EFSA and FDA are compressing supplier qualification timelines and forcing ingredient manufacturers to reconfigure extraction and purification protocols to maintain commercial access across North American and European markets.
Growth Catalysts
- EFSA Novel Food Pathway:Accelerated approval timelines for fermented protein isolates enable European brands to launch differentiated recovery products ahead of regulatory lag in competing jurisdictions.
- Collegiate Athletic Procurement:NCAA Division I programs now mandate third-party NSF Certified for Sport verification, creating structured demand pull for tested amino acid premixes.
- Precision Fermentation:Microbial production of leucine and valine is reducing dependency on agricultural protein feedstocks and enabling supply security for endurance nutrition formulators.
Market Restraints
- Whey Protein Input Volatility:Dairy commodity price swings tied to New Zealand and EU milk production cycles compress margin predictability for isolate manufacturers.
- Chinese Supply Concentration:Bulk BCAA crystallization capacity clusters in Shandong and Jiangsu provinces, creating single-point vulnerability for global amino acid flows.
- Bitterness Masking Limitations:Encapsulation technologies struggle to fully suppress hydrophobic amino acid off-notes in low-pH ready-to-drink applications.
Strategic Opportunities
- India FSSAI Fortification Mandates:Government-mandated protein enrichment in mid-day meal programs opens institutional procurement channels for cost-optimized isolates.
- Health Club Vending Integration:Post-workout recovery shots in Equinox and Life Time Fitness locations are displacing traditional retail powder purchases among urban professionals.
- SAMR Health Food Registration:China's streamlined blue-hat certification for sports nutrition creates regulatory tailwind for brands willing to navigate extended documentation timelines.
Industry Challenges
- Cross-Functional Talent Scarcity:Formulation chemists with simultaneous expertise in sports physiology and flavor systems command premium compensation and extend R&D cycle times.
- Dual Certification Burden:Brands targeting both US and EU markets must maintain parallel NSF and Informed Sport testing protocols, duplicating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Nutrition Ingredients Market |
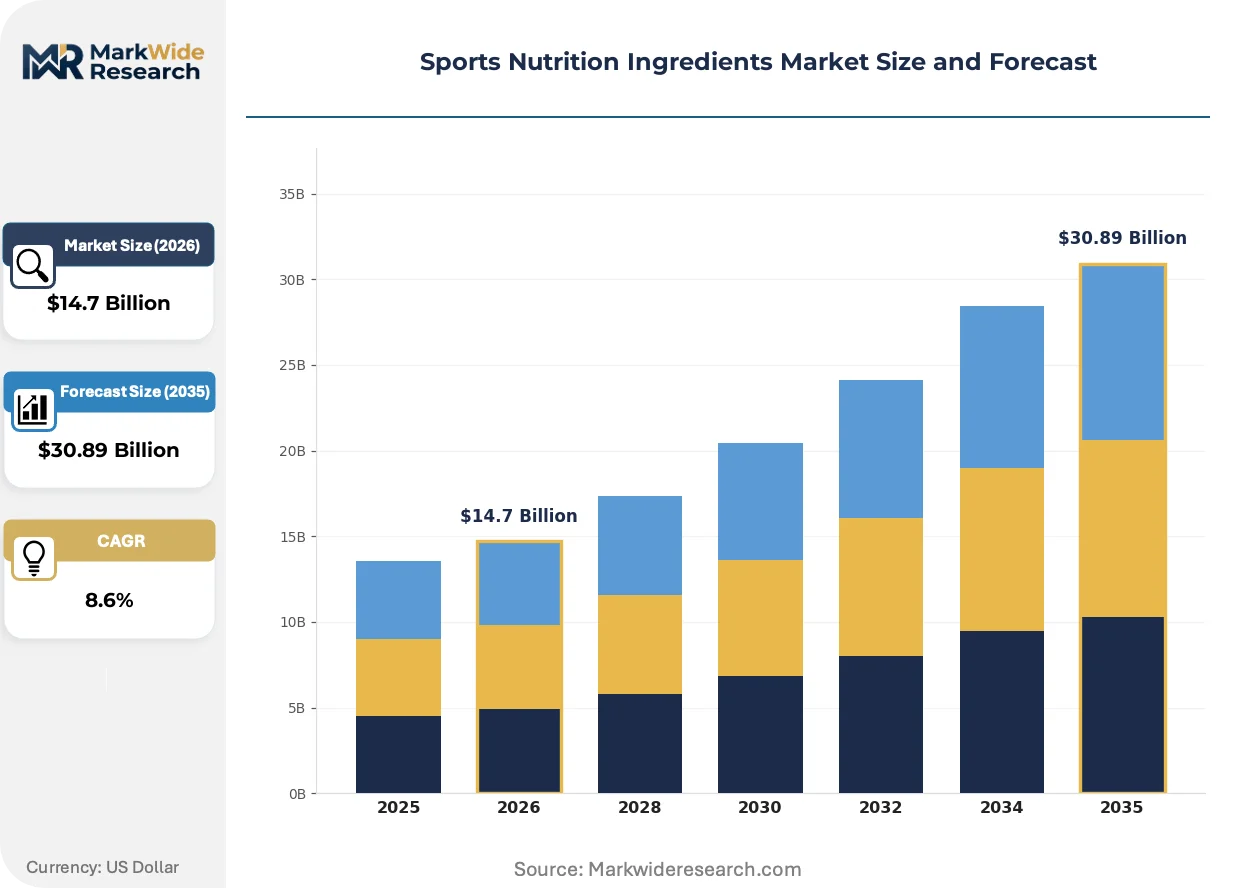
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Proteins, Amino Acids, Carbohydrates, Fats Form: Powder, Liquid, Bar, Capsule Functionality: Muscle Recovery, Endurance, Energy Boost, Weight Management Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Clubs |
| Companies Covered | Glanbia plc, Kerry Group plc, Arla Foods Ingredients, ADM, FrieslandCampina Ingredients, BASF SE, Tate & Lyle, Cargill, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Nutrition Ingredients Market Emerging Trajectories
Digital traceability platforms and bioprocess automation are compressing development cycles while regulatory divergence between major markets is fragmenting formulation standardization strategies.
Blockchain-enabled ingredient provenance tracking is digitizing supply chain documentation for whey isolate batches. Premium performance brands in Germany and the United States now require farm-to-facility traceability as a procurement gate. This transparency infrastructure is digitizing quality assurance workflows and compressing supplier audit cycles from months to weeks.
REACH registration requirements for novel bioactive peptides are extending European market entry timelines. The industrial consequence is a geographic bifurcation where innovation launches first in US markets under FDA GRAS self-affirmation. Small-molecule recovery compounds face the steepest compliance burden, with several developers prioritizing North American commercialization.
Direct-to-consumer subscription models for personalized amino acid stacks are displacing mass-market powder purchases. Endurance athletes and masters competitors in Australia and California represent the earliest adopters, with algorithm-driven dosing recommendations replacing static label serving sizes. This behavioral shift is most visible in coastal metropolitan markets where fitness club density supports hybrid online-offline fulfillment.
Sports Nutrition Ingredients Market Segmentation
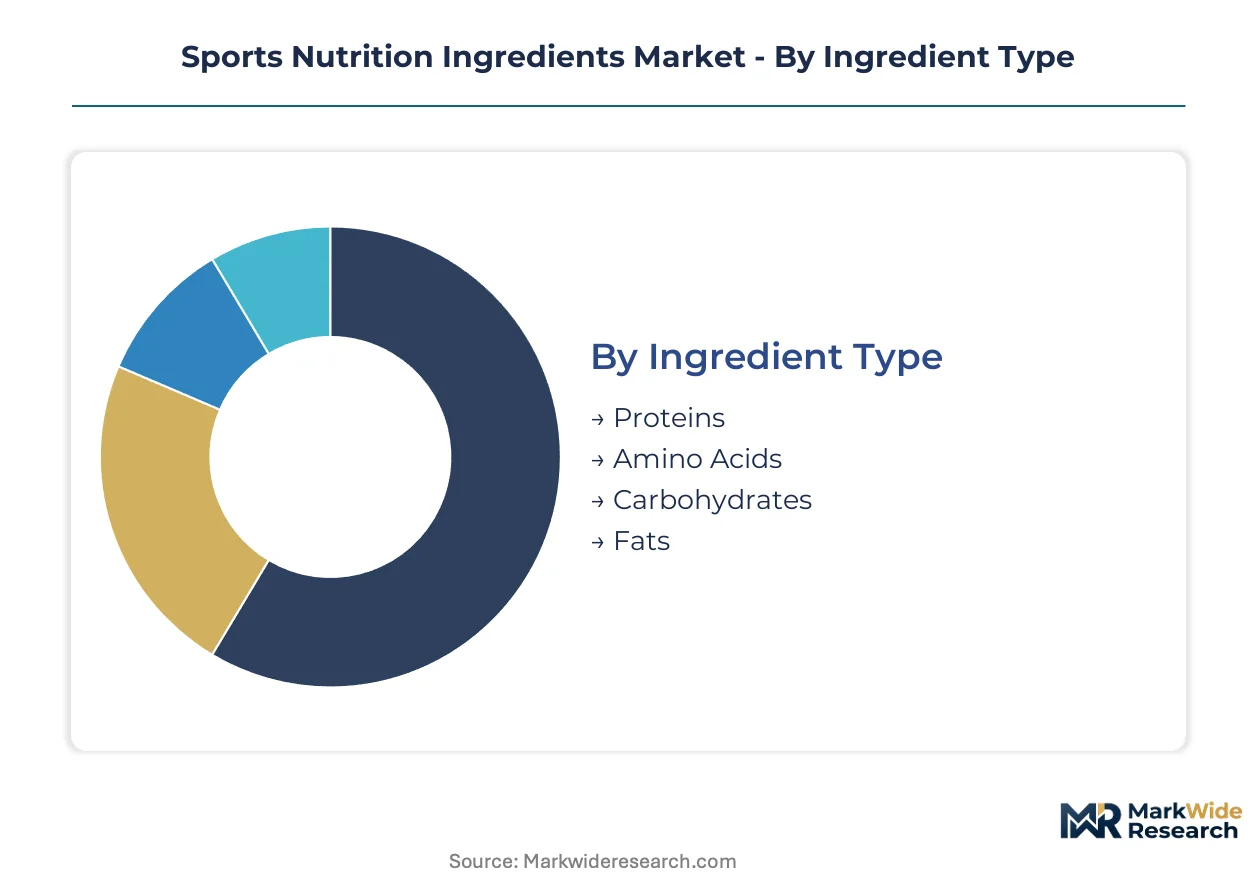
Sports nutrition ingredients serve distinct physiological protocols across athletic performance tiers, from collegiate strength programs to endurance competitors. Segmentation reveals how formulation requirements diverge by delivery mechanism, metabolic objective, and procurement channel.
Ingredient Type:
The use-case spectrum spans rapid absorption protocols for post-workout windows to sustained-release formulations for endurance events.
- Proteins:Whey isolates and casein hydrolysates deliver 80-90% purity thresholds for muscle protein synthesis. NCAA Division I programs in the United States mandate NSF Certified for Sport verification, pulling demand toward third-party tested isolates.
- Amino Acids:Branched-chain formulations at 2:1:1 leucine ratios target leucine threshold theory for mTOR activation. Precision fermentation in Germany and California is displacing agricultural feedstock dependency for BCAAs.
- Carbohydrates:Modified starches and maltodextrins engineered for glycemic index control.
- Fats:Medium-chain triglycerides and omega-3 concentrates for ketogenic and anti-inflammatory protocols.
The dominant share belongs to Proteins, while Amino Acids is closing the gap fastest.
Form:
Cost tiers separate commodity bulk powders from premium convenience formats with flavor-system investments.
- Powder:Bulk commodity base requiring reconstitution, dominating institutional procurement and value-oriented consumer segments. E-commerce subscription models in the United States and Germany are displacing mass-market retail purchases.
- Liquid:Ready-to-drink concentrates with encapsulated amino acid technologies masking bitterness in low-pH applications. Health club vending at Equinox and Life Time Fitness locations in New York and Los Angeles is accelerating adoption.
- Bar:Shelf-stable formats with protein binding and moisture retention challenges.
- Capsule:Precision-dosed delivery for targeted micronutrient and stimulant stacks.
Powder retains volume leadership, though Liquid is expanding most quickly through convenience retail integration.
Functionality:
Application intensity varies by athletic discipline and training periodization requirements.
- Muscle Recovery:Post-exercise protein synthesis optimization with leucine-enriched formulations. Professional rugby and American football programs in Australia and the United States structure recovery protocols around 3g leucine thresholds.
- Endurance:Carbohydrate-electrolyte and amino acid combinations for substrate preservation. Marathon and triathlon competitors in California and Queensland represent the earliest adopters of personalized dosing algorithms.
- Energy Boost:Caffeine and stimulant blends subject to evolving ANVISA and TGA thresholds.
- Weight Management:Thermogenic and appetite-modulating ingredients with regulatory divergence between FDA and EFSA claim permissibility.
Muscle Recovery commands the largest formulation investment, while Endurance is gaining share fastest through precision nutrition adoption.
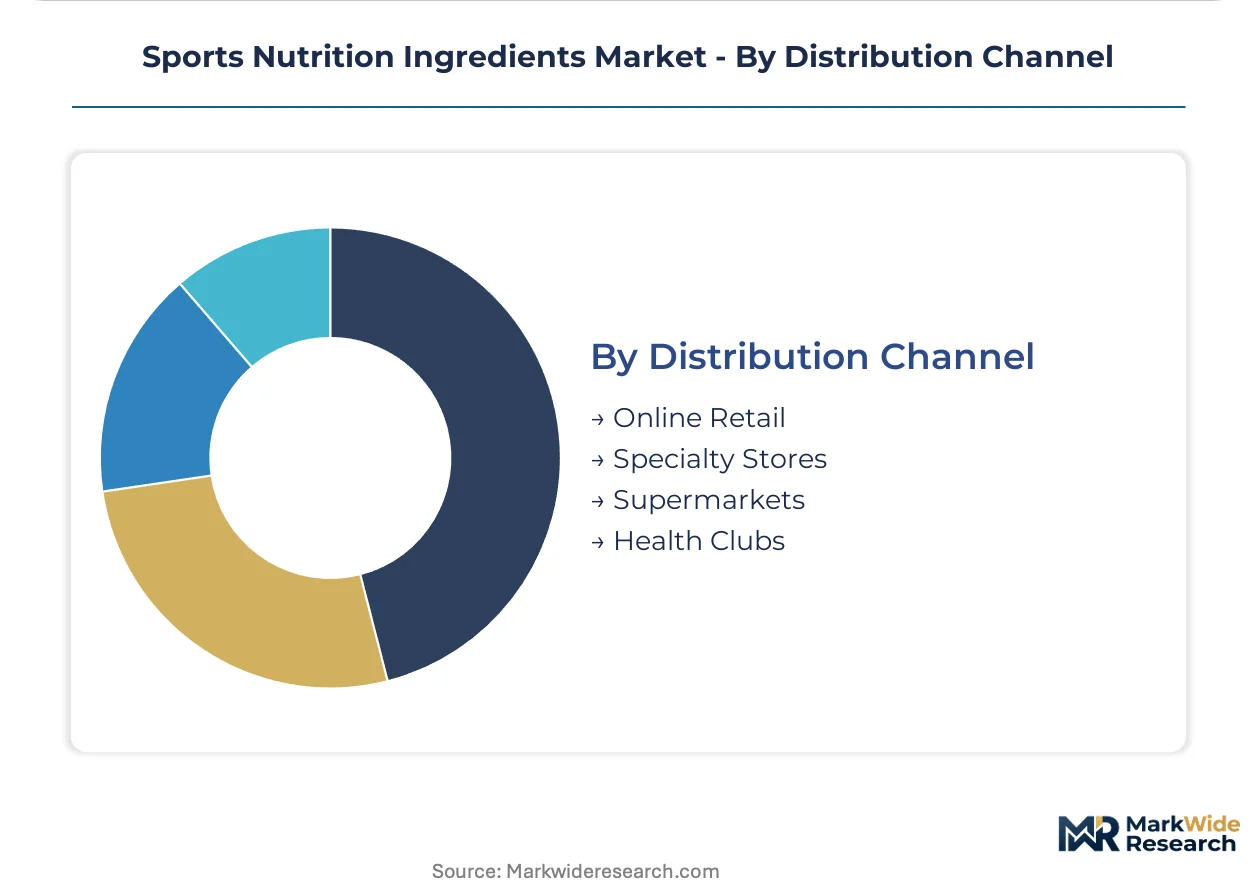
Distribution Channel:
Customer type and purchase context reshape margin structures and brand loyalty mechanics.
- Online Retail:Direct-to-consumer subscription models with algorithm-driven amino acid stacking. Coastal metropolitan markets in Australia and California show highest penetration among masters athletes.
- Specialty Stores:Staff-guided selection with third-party certification verification. German specialty retailers emphasize EFSA novel food compliance documentation.
- Supermarkets:Mass-market accessibility with simplified label claims and price compression.
- Health Clubs:Immediate consumption context with premium pricing tolerance. Post-workout recovery shots in urban fitness centers are capturing share from traditional powder purchases.
Online Retail holds the dominant position, yet Health Clubs are climbing the fastest through vending integration and impulse consumption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States buyers prioritize third-party certification and convenience formats, while German purchasers emphasize EFSA novel food compliance, and Chinese procurement concentrates on domestic SAMR registration for blue-hat status.
United States
NCAA Division I athletic programs and professional sports franchises drive institutional demand for NSF Certified for Sport verified isolates. FDA GRAS self-affirmation pathways enable faster novel ingredient launches compared to European timelines. California and New York fitness club density supports health club vending expansion for ready-to-drink recovery formats.
Germany
Endurance athletes and masters competitors in Bavaria and North Rhine-Westphalia adopt precision-fermented amino acid stacks with algorithm-driven dosing. EFSA novel food assessments extend approval timelines for bioactive peptides, pushing innovators toward US-first launches. Cologne and Frankfurt host specialty retailers emphasizing clean-label certification documentation.
China
Fitness club penetration in Shanghai and Beijing accelerates e-commerce ingredient procurement for personalized nutrition stacks. SAMR health food registration requirements create structured barriers for foreign brands seeking blue-hat certification. Shandong and Jiangsu provinces concentrate bulk BCAA crystallization capacity for domestic and export supply.
India
FSSAI fortification mandates for government school meal programs open institutional channels for cost-optimized protein isolates. Maharashtra and Gujarat manufacturing clusters scale dairy protein extraction for domestic sports nutrition brands. Mumbai and Delhi metropolitan areas show rising health club membership driving retail powder demand.
Australia
Marathon and triathlon competitors in Queensland and New South Wales represent early adopters of personalized amino acid subscription models. TGA caffeine threshold regulations constrain stimulant formulation options compared to US permissibility. Sydney and Melbourne specialty retailers emphasize third-party testing verification for endurance nutrition products.
Sports Nutrition Ingredients Market Vendor Landscape
Capability concentration sits with ingredient technology specialists; scale advantage sits with diversified nutrition conglomerates. The market structure tiers between premium premix formulators and bulk commodity suppliers. Three archetypes dominate: dairy protein extraction specialists, encapsulation technology innovators, and precision fermentation entrants. Competitive moves center on backward integration into agricultural feedstocks and strategic partnerships with certified testing laboratories.
Within the dairy protein tier, Glanbia plc and Arla Foods Ingredients occupy positions anchored by European milk supply access and North American processing infrastructure. Kerry Group plc exemplifies the flavor-system and encapsulation specialist archetype, while Cargill represents the agricultural commodity giant diversifying into performance nutrition inputs. These three entities illustrate how competitive positioning splits between extraction-scale dominance and formulation-technology differentiation.
| Leading Market Players |
|---|
| Glanbia plc |
| Kerry Group plc |
| Arla Foods Ingredients |
| ADM |
| FrieslandCampina Ingredients |
| BASF SE |
| Tate & Lyle |
| Cargill |
| Lactalis Ingredients |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu province concentration for bulk BCAA crystallization anchors margin capture downstream with ingredient brands and premix formulators. Dairy commodity cycles in New Zealand and the European Union transmit volatility through whey isolate pricing tiers, compressing predictability for North American and European finished goods manufacturers.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from NCAA Division I programs and professional sports franchises, while spot purchasing persists for commodity whey powder in value-oriented consumer segments. Price differentiation hinges on NSF Certified for Sport verification tier and volume scale, with certified isolates commanding substantial premiums over uncertified commodity grades. Cost compression in standard-tier powders is intensifying because Chinese manufacturing capacity expansion is eroding regional sourcing premiums. Collegiate athletic departments exhibit lowest price sensitivity due to mandated compliance budgets, while mass-market supermarket buyers remain most responsive to per-kilogram fluctuations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for amino acid procurement, with crystallization capacity clustering creating single-source vulnerability for global BCAA flows. Raw material dependencies center on dairy protein feedstocks from New Zealand and the European Union, agricultural starch sources from the United States and Brazil, and fermentation substrates from corn belt regions. Distribution runs through dual-channel structures: direct institutional sales to athletic programs and health club vending networks, alongside e-commerce platforms for personalized subscription stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating with collegiate athletic consortiums and health club chains, fragmenting procurement decisions away from individual consumers toward institutional gatekeepers with standardized compliance requirements.
For Market Incumbents: Insulate certification infrastructure against emerging precision-fermentation entrants by deepening NSF and Informed Sport laboratory partnerships. Backward integration into dairy protein extraction in Wisconsin and Idaho secures captive supply against New Zealand commodity volatility. Channel control through exclusive health club vending agreements at Equinox and Life Time Fitness locations defends premium positioning against ready-to-drink challengers.
For New Entrants and Emerging Players: Pursue white-space opportunities in India FSSAI-compliant institutional isolates for government meal program procurement, where cost-optimized formulations face limited established competition. Algorithm-driven personalized amino acid subscription models in Australian and California coastal markets offer penetrable entry with direct-to-consumer logistics. Precision-fermented leucine production from German or California bioprocess facilities provides differentiated positioning against agricultural BCAA incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed flavor-system and encapsulation specialists holding Kerry Group plc-adjacent capabilities. Long-term viability over the projection horizon favors precision-fermentation platforms with microbial strain IP and regulatory approval momentum. Monitor EFSA novel food pathway acceleration for fermented proteins as inflection indicator for geographic competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial leucine production in Germany reduces agricultural feedstock dependency for endurance nutrition formulators. |
| NSF Certification Expansion | Third-party testing laboratory partnerships secure NCAA Division I procurement mandates and collegiate athletic demand. |
| Health Club Vending Integration | Post-workout recovery shot placement at Equinox and Life Time Fitness captures impulse consumption from urban professionals. |
| India FSSAI Compliance Investment | Government school meal program certification opens institutional channels for cost-optimized protein isolate procurement. |
| Blockchain Traceability Deployment | Farm-to-facility documentation digitization compresses supplier audit cycles from months to weeks for German premium brands. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Formulation chemists at premix manufacturers, procurement directors at NCAA athletic departments, quality assurance leads at third-party testing laboratories, and flavor systems specialists at encapsulation technology providers contributed primary perspectives. Secondary validation drew from FDA GRAS notification databases, EFSA novel food assessment registers, SAMR health food registration filings, and FSSAI fortification standard documentation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Calibration against historical price series and procurement volume patterns informs the analytical framework across the analysis window. Segmentation dimensions modeled include ingredient type, delivery form, functionality application, and distribution channel, with regional regulatory cluster as an additional industry-specific layer. CAGRs derive from trend extrapolation adjusted for patent expiry timelines, regulatory approval velocity, and technology substitution curves. Forecast inputs incorporate dairy commodity cycle patterns and precision-fermentation capacity buildout trajectories.
Sensitivities concentrate around EFSA novel food pathway acceleration, Chinese export tariff regimes, and precision-fermentation yield improvements. Forecasts reflect documented assumptions regarding regulatory stability and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Sports Hydration Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Creatine Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Brazil Sports Nutrition Market