
 Sports Nutrition Market | 2026-2036
Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Nutrition Market Intelligence
Amateur fitness enthusiasts is reorganizing demand away from traditional bodybuilder-centric portfolios toward everyday wellness positioning. PepsiCo leverages its beverage distribution infrastructure to push ready-to-drink protein into mainstream retail. Glanbia anchors its competitive position through captive dairy protein supply and ingredient specialization. Abbott differentiates via clinical nutrition credibility that extends into performance-oriented consumer segments.
Sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, or body composition, typically containing protein isolates at 20-30 grams per serving, creatine monohydrate, branched-chain amino acids, or electrolyte matrices manufactured through spray-drying, microencapsulation, or cold-pressed bar formation. These products serve commercial purposes spanning pre-workout energy modulation, post-exercise muscle protein synthesis, and hydration maintenance during sustained exertion. Protein powders and ready-to-drink formats occupy the largest margin pools due to manufacturing scale and repeat purchase velocity, while gummies and functional hydration sachets represent the fastest-expanding form categories as convenience-seeking recreational users enter the category. The endurance training and recovery application segments deepen as marathon participation and boutique fitness studio attendance expand across urban centers.
FDA oversees supplement labeling and Good Manufacturing Practice compliance in the United States, while EFSA governs health claim substantiation across European markets, and both frameworks intensify scrutiny of proprietary blend transparency and contaminant testing. These regulatory architectures elevate compliance costs for new entrants but simultaneously reward established operators with validated quality systems and documented supply chain traceability. Stakeholders must monitor evolving positions on novel ingredients such as synthetic peptides and precision-fermented proteins across multiple jurisdictions to anticipate reformulation requirements and market access barriers.
Market Dynamics
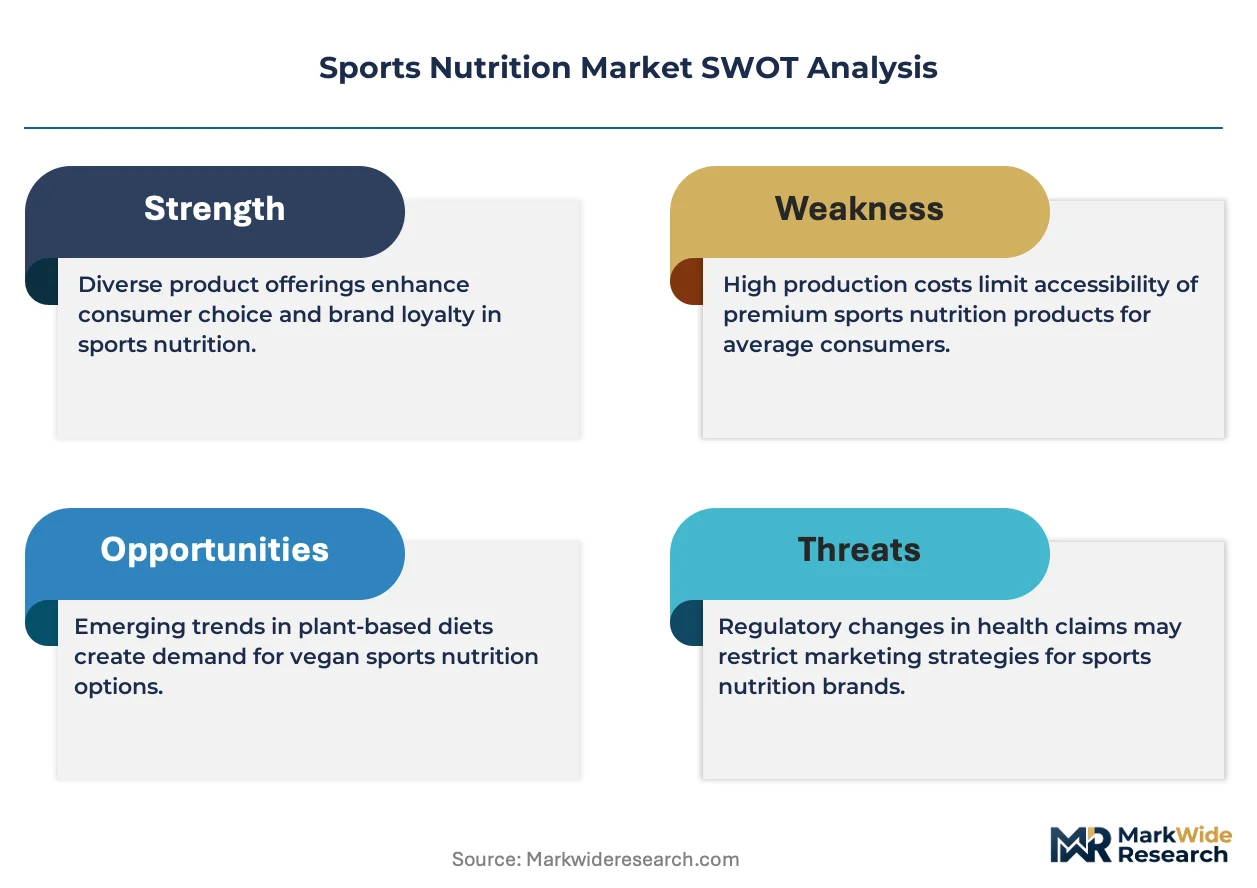
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to restructure supply chains and eliminate proprietary blend opacity, compressing margin structures for mid-tier operators while rewarding those with validated ingredient traceability systems.
Growth Catalysts
- Amateur fitness democratization:Recreational marathoners and boutique studio attendees in the United States now purchase protein powders at volumes rivaling traditional bodybuilders, expanding addressable demand pools.
- EFSA health claim substantiation pathways:Validated scientific dossiers for creatine monohydrate and branched-chain amino acids enable premium positioning and reduced marketing friction across European retail channels.
- Precision fermentation scale-up:Synthetic whey and casein alternatives from microbial hosts are reducing dairy supply dependency and enabling vegan-certified product lines for allergen-sensitive segments.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings tied to New Zealand and EU milk production cycles compress gross margins for powder-dependent portfolios.
- Proprietary blend transparency mandates:FDA labeling enforcement requires gram-disclosure of all active ingredients, eliminating margin protection through undisclosed dosing ratios.
- Plant protein functionality gaps:Pea and rice protein isolates exhibit inferior solubility and mouthfeel versus dairy counterparts, limiting ready-to-drink format adoption.
Strategic Opportunities
- Functional hydration sachets in China:Urban marathon participation growth and convenience-store channel expansion create white space for electrolyte-delivery formats beyond traditional powder tubs.
- IRA-aligned sustainable manufacturing:Energy-efficient spray-drying facilities in the United States qualify for clean production tax credits, reducing unit economics for domestic powder manufacturing.
- Microbiome-targeted recovery formulations:Convergence of sports nutrition and gut-health science enables premium positioning through synbiotic protein blends with documented metabolite outcomes.
Industry Challenges
- Dual-certification timeline compression:Informed Sport and NSF Certified for Sport testing protocols require 6-12 month validation cycles that delay new product launches.
- Cold-chain RTD distribution infrastructure:Ready-to-drink protein beverages require refrigerated last-mile logistics that strain direct-to-consumer fulfillment economics outside major metropolitan clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Nutrition Market |
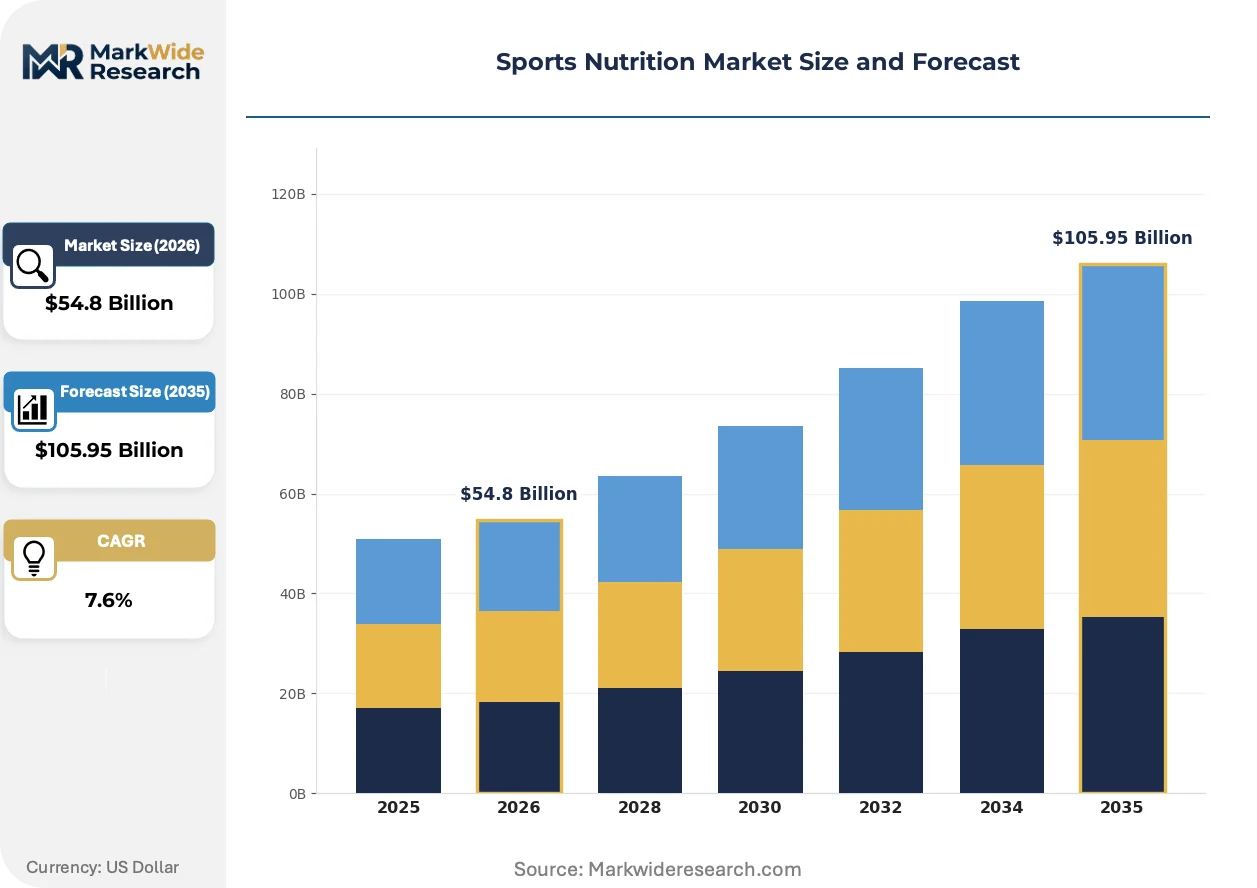
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $105.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Electrolyte Drinks, Creatine Supplements, Amino Acids Form: Powder, Ready-to-Drink, Capsules, Gummies, Tablets Application: Endurance Training, Muscle Building, Recovery, Weight Management, Hydration End User: Professional Athletes, Fitness Enthusiasts, Bodybuilders, Recreational Sportspeople, Senior Athletes |
| Companies Covered | PepsiCo, The Coca-Cola Company, Abbott, Glanbia, Quest Nutrition, Optimum Nutrition, MusclePharm, Post Holdings, GNC Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Nutrition Market Strategic Shifts & Innovations
Formulation science and regulatory transparency are converging to reshape product architecture, with novel protein sources and clean-label mandates driving technical investment while distribution models adapt to recreational user convenience expectations.
Precision-fermented dairy proteins from microbial hosts are displacing conventional whey and casein isolates in premium positioning tiers. Boutique fitness operators and endurance athletes in Germany now specify fermentation-derived proteins for sustainability credentials. This displacement is compressing traditional dairy processor margins while enabling ingredient suppliers to capture value previously held by commodity cooperatives.
EFSA's evolving guidance on novel food authorizations for synthetic peptides is tightening substantiation requirements across European markets. Manufacturers must now submit comprehensive toxicology and bioavailability dossiers before market entry, elevating R&D spend for innovative formulations. Sports nutrition brands targeting EU distribution are responding by front-loading clinical validation budgets and extending development timelines.
Recreational users now favor single-serve sachets and grab-and-go formats over bulk powder tubs, compressing purchase cycles and expanding convenience-store penetration. Direct-to-consumer subscription models in the United States are ceding ground to retail immediacy as amateur athletes prioritize purchase spontaneity over cost optimization. This behavioral pivot is most visible in urban marathon training clusters where mid-workout consumption drives format preference.
Sports Nutrition Market Segmentation
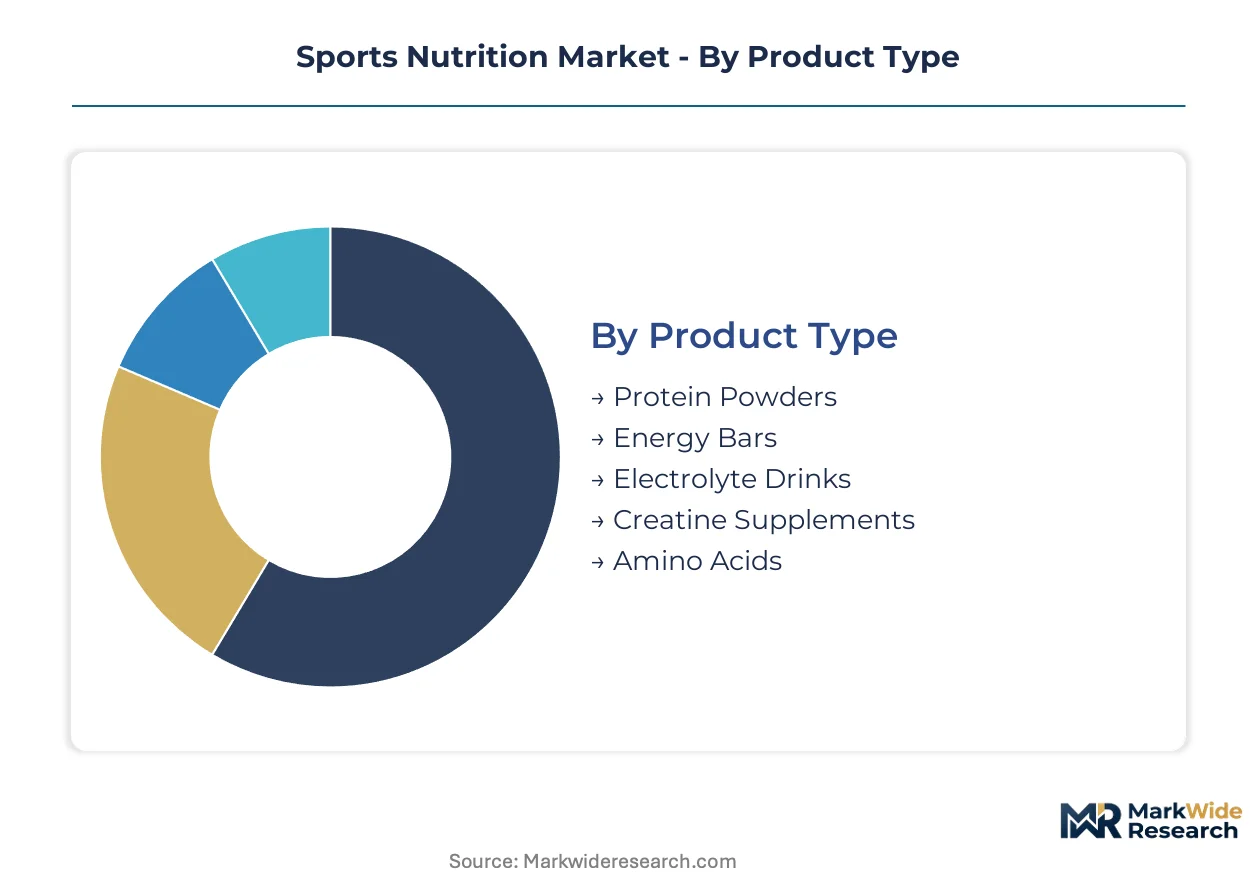
Sports nutrition segmentation reveals divergent margin profiles and channel strategies across product architectures. Protein powders and ready-to-drink formats command repeat purchase velocity through retail and direct-to-consumer channels, while emerging formats like gummies and functional sachets reshape convenience-store penetration patterns.
Product Type:
Channel-mix dynamics concentrate high-velocity protein formats in club retail and e-commerce, while specialized supplements navigate specialty nutrition stores and professional athletic procurement channels.
- Protein Powders:Spray-dried whey and casein isolates at 20-30 gram serving specifications dominate manufacturing scale. United States amateur marathoners and boutique studio attendees in Germany now drive volume comparable to traditional bodybuilder demand, compressing bulk tub formats against single-serve sachet preferences.
- Energy Bars:Cold-pressed formations combining protein isolates with carbohydrate matrices serve mid-workout consumption occasions. Recreational sportspeople across urban China clusters favor grab-and-go portability over powder preparation, expanding convenience-store shelf space allocation.
- Electrolyte Drinks:Functional hydration formulations with sodium-potassium matrices target endurance training segments. Urban marathon participation growth in the United States and China expands ready-to-drink distribution infrastructure.
- Creatine Supplements:Monohydrate powders and micronized variants serve muscle protein synthesis protocols. EFSA-validated health claim substantiation enables premium European retail positioning.
- Amino Acids:Branched-chain and essential amino acid isolates target intra-workout consumption windows. Precision fermentation alternatives reduce dairy supply dependency for vegan-certified lines.
Protein powders dominate installed base. Energy bars are where expansion concentrates.
Form:
Manufacturing cost tiers separate commodity powder operations from specialized encapsulation and gummy formation technologies requiring distinct capital equipment and quality validation protocols.
- Powder:Spray-drying and agglomeration processes yield scalable unit economics with established supply chains. Dairy commodity price volatility tied to New Zealand and EU production cycles compresses margin stability.
- Ready-to-Drink:Aseptic filling and cold-chain logistics require refrigerated last-mile infrastructure. United States metropolitan clusters support viable direct-to-consumer economics while secondary markets strain fulfillment models.
- Capsules:Hard-shell gelatin and vegetable-based encapsulation serve precision-dosing requirements. Professional athletes and senior segments prioritize convenience over taste optimization.
- Gummies:Pectin-based and gelatin matrices with microencapsulated actives represent the steepest expansion trajectory. Recreational users in Germany and the United States drive format innovation for palatability-sensitive entry segments.
- Tablets:Direct compression and film-coating technologies enable shelf-stable portability. Compression-molded formats cede share to gummies in convenience-oriented demographics.
Powder formats retain volume leadership. Gummies are climbing the fastest.
Application:
End-use concentration patterns align with distinct training modalities and recovery protocols, each demanding specialized formulation architectures and dosing regimens.
- Endurance Training:Electrolyte matrices and carbohydrate-protein blends support sustained exertion protocols. Marathon participation growth across United States urban centers and Chinese tier-one cities expands addressable demand.
- Muscle Building:High-leucine protein isolates and creatine monohydrate target myofibrillar protein synthesis. Bodybuilders and professional athletes sustain premium pricing tolerance for validated efficacy.
- Recovery:Synbiotic protein blends and anti-inflammatory botanicals converge sports nutrition with gut-health science. Post-exercise consumption windows drive repeat purchase velocity.
- Weight Management:Meal replacement formulations with controlled macronutrient ratios serve caloric deficit protocols. Fitness enthusiasts seeking body composition optimization expand beyond traditional athletic segments.
- Hydration:Isotonic and hypotonic electrolyte delivery systems target fluid balance maintenance. Functional sachet formats penetrate convenience channels in China and Germany.
Muscle building commands premium pricing. Recovery applications are gaining share fastest.
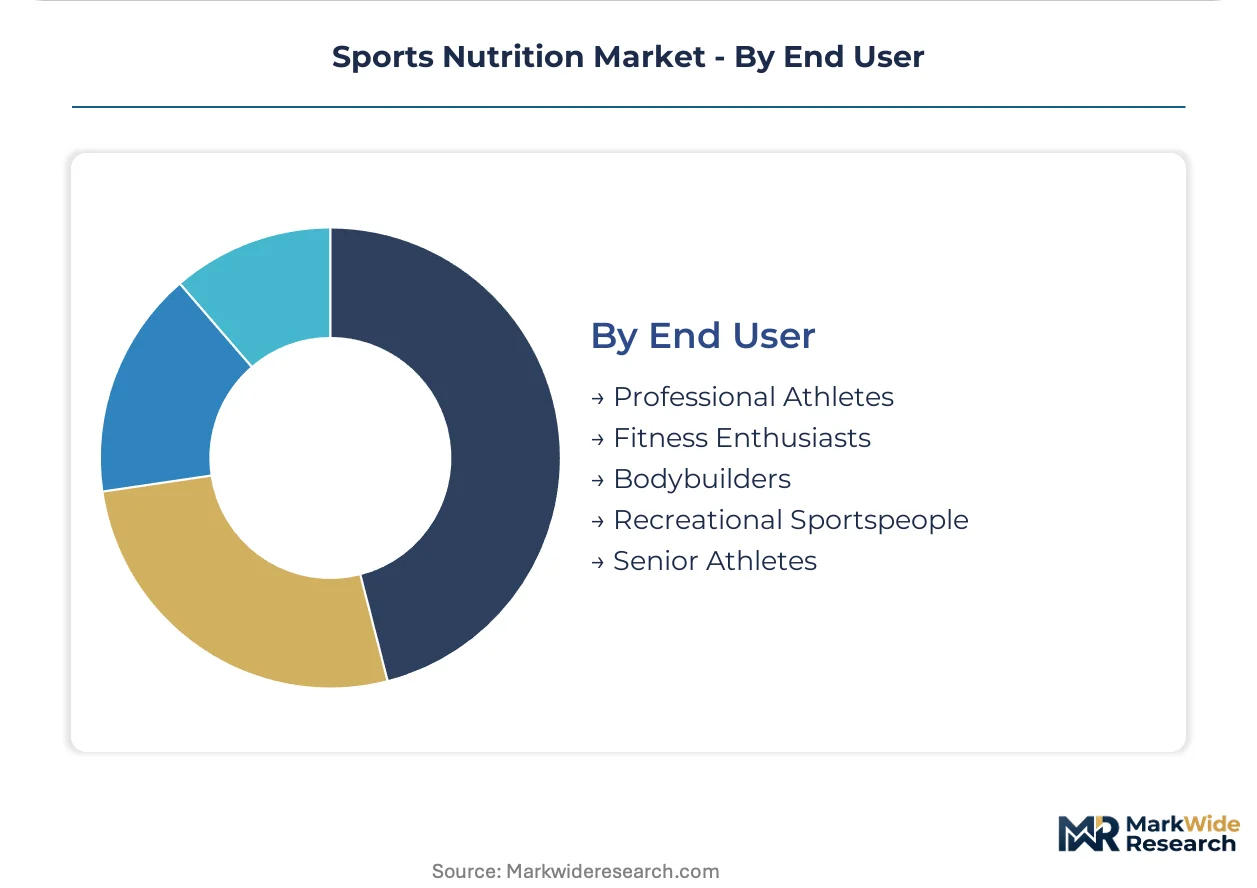
End User:
Customer-type stratification reveals divergent purchasing behaviors across professional procurement, subscription loyalty, and spontaneous retail acquisition patterns.
- Professional Athletes:Informed Sport and NSF Certified for Sport validation requirements drive 6-12 month testing timelines. Documented supply chain traceability and contaminant screening support institutional procurement contracts.
- Fitness Enthusiasts:Amateur marathoners and boutique studio attendees in the United States and Germany now constitute volume-comparable demand to traditional bodybuilders. Subscription models cede ground to retail immediacy as purchase spontaneity prioritizes over cost optimization.
- Bodybuilders:High-protein, high-creatine protocols sustain bulk powder consumption. This segment retains price tolerance for premium isolates despite amateur demographic expansion.
- Recreational Sportspeople:Convenience-seeking entry segments favor single-serve formats and palatability-optimized gummies. Urban marathon training clusters drive mid-workout consumption occasions.
- Senior Athletes:Sarcopenia-targeted formulations with enhanced leucine content and digestive enzymes serve aging demographics. Clinical nutrition credibility extends into performance-oriented positioning.
Fitness enthusiasts dominate volume expansion. Recreational sportspeople are where format innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European distribution efficiency for temperature-sensitive ready-to-drink formats. Union Pacific's refrigerated rail network connects West Coast manufacturing to Midwest marathon training clusters. China's high-speed rail grid enables same-day replenishment of convenience-store electrolyte sachets in tier-one cities.
United States
Urban marathon participation in Boston, Chicago, and New York expands demand for mid-workout consumption formats. FDA labeling enforcement under the Dietary Supplement Health and Education Act mandates gram-disclosure of proprietary blends. The Pacific Northwest hosts precision-fermented protein scale-up facilities serving West Coast boutique fitness operators.
Germany
Boutique studio attendance in Berlin and Munich drives single-serve sachet preferences over bulk powder tubs. EFSA health claim substantiation pathways for creatine monohydrate enable premium retail positioning across EU markets. Bavaria's dairy processing clusters supply whey isolates while fermentation-derived alternatives gain sustainability credentials.
China
Convenience-store channel expansion in Shanghai and Beijing creates white space for functional hydration formats. SAMR's evolving novel food regulations tighten import requirements for synthetic peptide ingredients. The Yangtze River Delta concentrates spray-drying facilities serving domestic protein powder demand.
United Kingdom
Recreational endurance athletes in London and Manchester prioritize grab-and-go formats over subscription models. MHRA guidance on sports supplement safety monitoring elevates testing requirements for e-commerce direct-to-consumer brands. The Midlands hosts contract manufacturing facilities serving European export markets.
Australia
Triathlon participation growth in Sydney and Melbourne expands electrolyte drink demand. TGA's therapeutic goods framework classifies high-dose creatine products under distinct compliance pathways. Queensland's dairy cooperatives supply whey concentrates while import dependency for specialty isolates persists.
Sports Nutrition Market Key Industry Players
Concentration sits with diversified food and beverage conglomerates that leverage existing distribution infrastructure. Fragmentation characterizes the specialist protein powder segment where mid-tier operators face margin compression from clean-label compliance costs. Three archetypes dominate: beverage-led conglomerates with retail reach, dairy-integrated ingredient suppliers with captive supply, and clinical nutrition specialists extending into performance segments. Competitive moves center on supply chain restructuring for transparency compliance and format innovation targeting recreational convenience.
Among beverage-led conglomerates, PepsiCo and The Coca-Cola Company exemplify scale-driven distribution advantage. Glanbia occupies a position within dairy-integrated supply archetypes. Abbott anchors the clinical credibility extension strategy. These three represent distinct competitive vectors without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Abbott |
| Glanbia |
| Quest Nutrition |
| Optimum Nutrition |
| MusclePharm |
| Post Holdings |
| GNC Holdings |
| Others |
Cost & Logistics Intelligence
Spray-drying capacity utilization at 85 percent-plus in the United States and Germany establishes minimum viable scale thresholds that price out sub-scale competitors while anchoring protein powder price floors. This concentration of processing infrastructure simultaneously compresses margins for mid-tier operators lacking backward integration into dairy supply or precision-fermented alternatives.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from retail subscription models and convenience-store single-serve purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—Informed Sport and NSF Certified for Sport validation commands 15-25 percent premiums—while pricing pressure stems from EFSA and FDA transparency mandates that eliminate proprietary blend opacity. Amateur fitness enthusiasts exhibit highest price sensitivity through channel-switching behaviors, whereas professional athletes retain tolerance for premium tiers tied to contaminant-tested supply chains.
Supply Chain Analysis
Inventory cycles extending 8-12 weeks for whey protein concentrate isolate supply from New Zealand and EU dairy cooperatives against 4-6 week lead times for precision-fermented alternatives. Raw material dependencies center on dairy commodity markets, microbial fermentation feedstocks, and specialized encapsulation polymers for gummy formats. Single-source vulnerability concentrates in New Zealand milk powder exports and Chinese pectin suppliers. Distribution runs through refrigerated rail networks for ready-to-drink formats and direct-to-consumer fulfillment centers for powder subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated ingredient traceability systems constitute the scarcest capability in this market, separating operators with documented supply chain architecture from commodity assemblers facing compliance-driven margin compression.
For Market Incumbents: Fortify competitive position through captive supply integration—backward integration into precision-fermentation facilities or long-term offtake agreements with dairy cooperatives—and accelerate Informed Sport certification coverage across full product portfolios. The threat of EFSA novel food authorization delays for synthetic peptides demands front-loaded clinical validation budgets. Channel control through exclusive convenience-store distribution partnerships in China and Germany represents the priority defensive lever.
For New Entrants and Emerging Players: Subscription-model service gaps among incumbent beverage conglomerates create entry points for personalized nutrition platforms with microbiome-targeted recovery formulations. White space concentrates in functional hydration sachets for Chinese urban marathon clusters and synbiotic protein blends for gut-health convergence segments. A direct-to-consumer launch anchored by precision-fermented protein sustainability credentials bypasses refrigerated logistics constraints while capturing boutique fitness operator procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-fermented ingredient suppliers with multi-year supply contracts to branded finished goods manufacturers. Long-term viability across the analysis window favors operators with dual-certification capabilities and demonstrated EFSA dossier submission experience. The acquisition target archetype is mid-scale spray-drying facilities with IRA-aligned energy efficiency credentials. The signal to watch is SAMR novel food regulation finalization for synthetic peptides in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Scale-Up | Synthetic whey from microbial hosts reduces dairy commodity dependency for vegan-certified lines. |
| EFSA Health Claim Dossier Submission | Validated creatine monohydrate substantiation enables premium positioning across European retail channels. |
| Cold-Chain RTD Infrastructure Partnership | Refrigerated last-mile logistics with Union Pacific unlocks Midwest marathon training cluster penetration. |
| Clean-Label Reformulation Investment | Gram-disclosure compliance with FDA labeling mandates eliminates proprietary blend opacity risks. |
| Functional Sachet Format Launch | Single-serve electrolyte delivery captures convenience-store expansion in Shanghai and Beijing. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sports nutrition brand managers, dairy processor procurement leads, precision-fermentation R&D directors, boutique fitness studio owners, and convenience-store category buyers. Secondary validation drew from FDA warning letter databases, EFSA novel food authorization registers, SAMR import regulation filings, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the projection horizon, the analytical framework modeled product type, form, application, and end-user dimensions alongside regulatory certification tier. CAGRs derived from segment-level growth trajectory analysis incorporating amateur fitness demographic expansion rates and precision-fermentation capacity buildout schedules. Forecast inputs included urban marathon participation indices and EFSA health claim approval timelines.
Forecasts assume regulatory continuity in FDA, EFSA, and SAMR regimes; material policy shifts on synthetic peptide authorization or dairy import tariffs would require re-modeling. Commodity price volatility in whey protein concentrate and pectin supply constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Pre-Workout Supplements Market