
 Brazil Sports Drinks Market | 2026-2036
Brazil Sports Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Sports Drinks Market Outlook
Single-serve and multi-pack bundling is repositioning purchase behavior across Brazilian retail channels. AmBev leverages its national distribution density to dominate shelf placement in convenience stores. The Coca-Cola Company sustains brand recognition through its Powerade portfolio in organized sports settings. PepsiCo competes via Gatorade's entrenched relationships with football clubs and athletic federations.
Brazil sports drinks are formulated aqueous beverages containing electrolytes, carbohydrates, and functional additives designed to replenish fluids and energy during or after physical exertion, with osmolality levels distinguishing isotonic, hypotonic, and hypertonic variants for specific hydration protocols. Isotonic formulations anchor volume sales due to their alignment with football and endurance training regimens, while protein-infused variants represent the fastest-growing product type as post-workout recovery protocols gain traction among fitness enthusiasts. Online retail channels capture expanding margin pools as direct-to-consumer subscription models reduce intermediary costs and enable flavor customization.
ANVISA mandates front-of-package warning labels and caps added sugar content, compelling reformulation toward reduced-calorie and natural sweetener alternatives. Brazil's Consumer Protection Code and INMETRO certification requirements further govern nutritional claims and product safety testing protocols. Stakeholders must monitor pending regulatory adjustments to caffeine thresholds and monitor municipal plastic waste ordinances affecting single-use bottle formats.
Market Dynamics
ANVISA's front-of-package warning label mandate and sugar content caps are forcing wholesale reformulation across Brazil's sports drinks sector, compressing legacy portfolios while accelerating natural sweetener adoption and clean-label positioning among agile producers.
Growth Catalysts
- Amateur football league expansion:Semi-professional and recreational football leagues across São Paulo state and Rio de Janeiro drive isotonic beverage consumption during training and match protocols.
- ANVISA regulatory clarity:Updated beverage labeling requirements create standardized formulation benchmarks that reduce compliance ambiguity for domestic manufacturers.
- Protein recovery protocols:Post-workout nutrition science adoption among fitness enthusiasts accelerates demand for protein-infused variants in metropolitan gym chains.
Market Restraints
- Natural sweetener input volatility:Stevia and monk fruit extract supply fluctuations from Paraguay and China squeeze margin predictability for reduced-calorie formulations.
- Southeast distribution concentration:Cold-chain logistics infrastructure clusters disproportionately in São Paulo and Rio de Janeiro states, limiting shelf penetration in northern and central-west markets.
- Substitution from coconut water:Unprocessed coconut water positioning as a natural electrolyte source captures price-sensitive consumers in coastal fitness zones.
Strategic Opportunities
- Northern corridor underpenetration:Amazonas and Pará states present whitespace for isotonic distribution expansion as organized sports participation formalizes in Manaus and Belém metropolitan areas.
- Direct-to-consumer subscription models:E-commerce platforms enable flavor customization and recurring revenue capture outside traditional retail margin structures.
- INMETRO certification premiumization:Nutritional claims verification under national metrology standards supports pricing differentiation for certified functional formulations.
Industry Challenges
- Reformulation R&D talent scarcity:Food chemists with osmolality optimization expertise for isotonic-hypotonic-hypertonic variants command premium compensation in São Paulo's competitive labor market.
- Municipal plastic waste ordinance fragmentation:Divergent single-use bottle restrictions across Rio de Janeiro, São Paulo, and Curitiba municipalities complicate packaging standardization and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Sports Drinks Market |
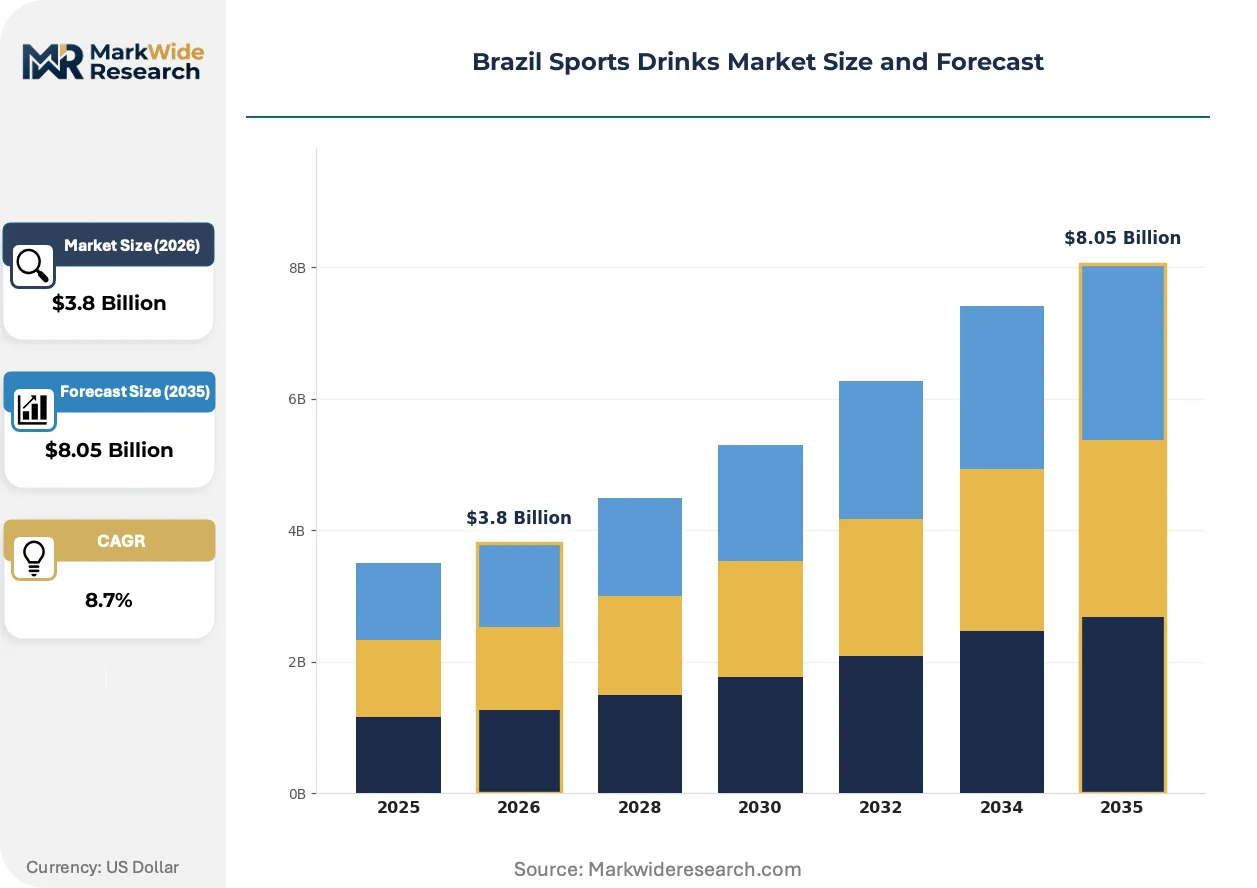
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Protein Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Athletes, Fitness Enthusiasts, Casual Drinkers, Recreational Users Flavor: Citrus, Berry, Tropical, Green Apple |
| Companies Covered | Monster Beverage Corporation, Suntory Beverage & Food Limited, PepsiCo, Kill Cliff, Fraser and Neave Holdings Bhd, The Coca-Cola Company, BA Sports Nutrition, LLC, AmBev, Red Bull GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Sports Drinks Market Strategic Shifts
Formulation science and channel architecture are converging to reshape how Brazilian consumers access and consume functional hydration products, with regulatory pressure accelerating ingredient transparency and digital infrastructure enabling direct manufacturer relationships.
Electrolyte microencapsulation technology is electrifying shelf stability and taste masking for mineral-dense formulations. Premium fitness clubs in Rio de Janeiro's Zona Sul are piloting these enhanced beverages for high-frequency members. The technology is compressing traditional flavor-masking additive loads while extending product viability in Brazil's variable ambient temperature distribution networks.
ANVISA's pending caffeine threshold adjustments are forcing preemptive reformulation across energy-sports hybrid categories. Manufacturers are recalibrating stimulant levels to maintain functional positioning within anticipated regulatory ceilings. The proposed framework most acutely affects pre-workout and endurance-focused SKUs targeting competitive amateur athletes in São Paulo state's organized racing circuits.
Subscription-based replenishment models are displacing impulse-driven convenience store purchases among dedicated fitness practitioners. Direct-to-consumer platforms capture recurring revenue from CrossFit affiliates and boutique studio networks in São Paulo and Rio de Janeiro. This behavioral pivot concentrates most visibly in metropolitan corridors where delivery logistics density supports reliable cold-chain fulfillment.
Brazil Sports Drinks Market Segmentation
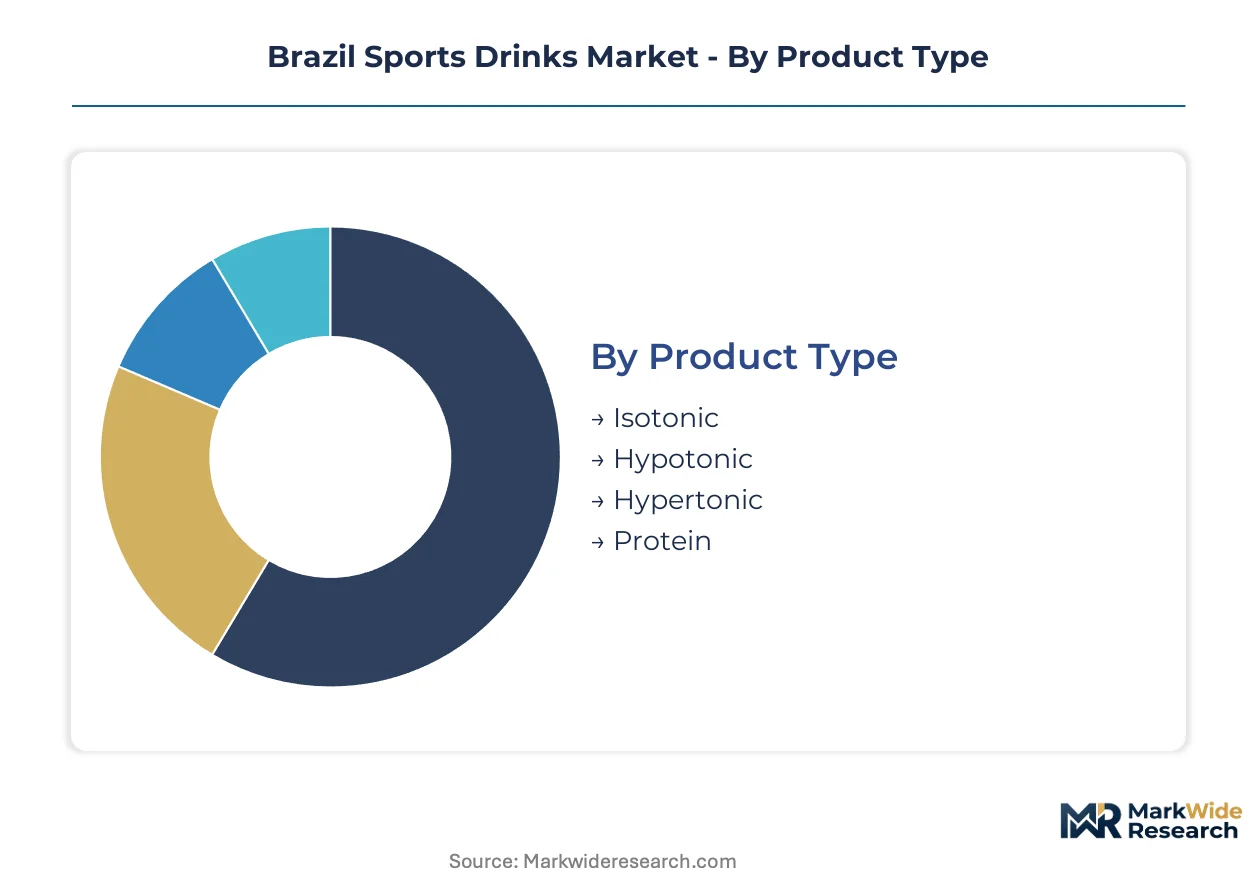
Segmentation reveals how ANVISA certification burdens and distribution infrastructure shape competitive positioning across Brazil's sports drinks landscape. Product chemistry, channel economics, and user behavior create distinct margin profiles that manufacturers must navigate.
Product Type:
INMETRO certification requirements vary sharply across osmolality categories, with isotonic formulations facing the most stringent electrolyte verification protocols while protein-infused variants trigger additional nutritional claims scrutiny.
- Isotonic:Balanced electrolyte and carbohydrate concentration matching body fluid osmolality for rapid absorption. São Paulo state's amateur football leagues anchor demand during match-day hydration protocols, with ANVISA sugar caps forcing reformulation toward stevia-sweetened variants.
- Protein:Post-workout recovery formulations combining whey or plant-based protein with electrolyte matrices. Metropolitan gym chains in Rio de Janeiro's Zona Sul drive adoption as recovery science penetrates boutique fitness studios, though INMETRO protein content verification adds 8-12 weeks to product launch timelines.
- Hypotonic:Lower carbohydrate concentration optimized for rapid fluid replacement without energy load. Marathon training circuits in Curitiba and Porto Alegre represent concentrated demand pockets.
- Hypertonic:High carbohydrate density for glycogen replenishment after extended exertion. Cycling clubs in Minas Gerais state's mountainous terrain sustain niche consumption.
Isotonic sits at the top of the volume ranking, with Protein climbing the fastest.
Distribution Channel:
Cold-chain reliability requirements and margin structures differentiate channel economics, with direct-to-consumer models capturing premium pricing power while mass retail optimizes throughput.
- Supermarkets:High-volume shelf space commanding national distribution scale. São Paulo and Rio de Janeiro metropolitan corridors concentrate promotional spending and multi-pack bundling strategies.
- Convenience Stores:Impulse-driven single-serve purchases tied to football match schedules and gym proximity. AmBev's route density advantages dominate shelf placement in this channel.
- Online Retail:Subscription-based replenishment with flavor customization and direct manufacturer relationships. CrossFit affiliates in São Paulo's Pinheiros district anchor early adoption clusters.
- Specialty Shops:Curated premium formulations targeting competitive amateur athletes. INMETRO certification visibility supports pricing premiums in this channel.
Supermarkets retain volume leadership, though Online Retail is gaining share fastest through recurring revenue capture.
End User:
Usage intensity and price sensitivity stratify formulation requirements, with competitive athletes demanding osmolality precision while casual users prioritize taste and convenience.
- Athletes:Competitive and semi-professional performers requiring precise hydration protocols. São Paulo state's organized racing circuits and football leagues drive isotonic specification adherence.
- Fitness Enthusiasts:Regular gym practitioners adopting structured recovery regimens. Protein-infused variants penetrate this segment through personal trainer recommendations in Rio de Janeiro's Leblon and Ipanema districts.
- Casual Drinkers:Taste-driven consumers substituting sports drinks for soft beverages. ANVISA front-of-package warnings influence brand switching behavior in this price-sensitive cohort.
- Recreational Users:Occasional consumption tied to weekend sports and social fitness activities. Coconut water substitution pressure concentrates here.
Fitness Enthusiasts show the steepest expansion trajectory as boutique studio networks proliferate.
Flavor:
Regional taste preferences and natural flavoring cost structures influence formulation decisions, with citrus and berry profiles benefiting from established supply chains while tropical variants leverage local ingredient sourcing.
- Citrus:Lemon-lime and orange profiles dominating football pitch consumption. Established flavor masking for electrolyte bitterness reduces additive costs.
- Berry:Acai and mixed berry variants resonating with health-positioned consumers. Amazonas state ingredient sourcing supports clean-label claims.
- Tropical:Passion fruit and mango formulations targeting coastal fitness zones. Rio de Janeiro's beach culture sustains differentiated positioning.
- Green Apple:Tart profiles appealing to younger demographics in urban gym chains. Limited natural flavoring supply increases input cost volatility.
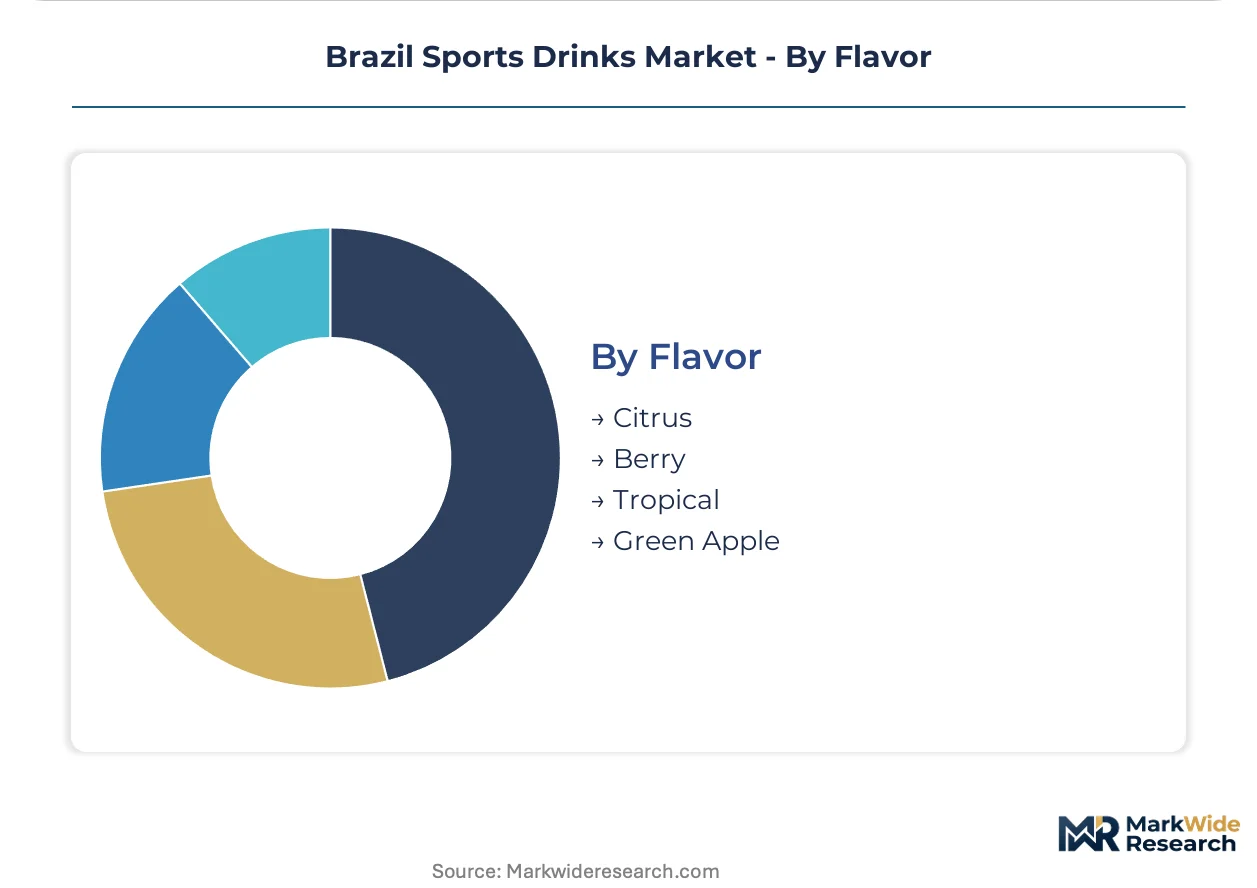
Citrus maintains volume dominance, with Berry expanding most quickly through superfruit positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's industrial corridor birthed Brazil's modern sports drinks sector during the 1990s fitness boom. Manufacturing infrastructure concentrated around metropolitan distribution nodes before spreading to coastal demand centers.
São Paulo
Amateur football leagues and organized racing circuits anchor isotonic consumption across the metropolitan corridor. ANVISA's sugar content caps force reformulation toward stevia-sweetened variants among local manufacturers. Campinas and Sorocaba industrial zones host concentrated production facilities serving southeastern distribution networks.
Rio de Janeiro
Coastal fitness culture and beach sports sustain differentiated tropical flavor demand in Zona Sul districts. Municipal plastic waste ordinances complicate single-use bottle standardization across city boundaries. Niterói and Duque de Caxias logistics clusters support cold-chain fulfillment for boutique studio networks.
Minas Gerais
Cycling clubs in mountainous terrain drive hypertonic formulation demand for glycogen replenishment protocols. INMETRO certification requirements govern nutritional claims verification for products manufactured in Belo Horizonte industrial parks. Juiz de Fora and Uberlândia serve as secondary distribution nodes for central-west penetration.
Rio Grande do Sul
Marathon training circuits in Porto Alegre sustain hypotonic beverage consumption for rapid fluid replacement. State-level consumer protection enforcement adds compliance layers beyond federal ANVISA mandates. Caxias do Sul manufacturing base leverages proximity to southern cold-chain infrastructure.
Paraná
Curitiba's organized endurance sports community anchors steady isotonic demand through seasonal training cycles. Municipal recycling programs affect packaging material selection for regional brands. Londrina and Maringá present expansion corridors as formalized sports participation spreads through northern Paraná metropolitan areas.
Brazil Sports Drinks Market Competitive Environment
The competitive structure tilts toward multinational beverage conglomerates with national distribution density. AmBev and The Coca-Cola Company anchor shelf placement through route-to-market advantages in convenience channels. PepsiCo competes via athletic federation relationships. Strategic moves concentrate on reformulation R&D for ANVISA compliance and direct-to-consumer platform development.
Among multinational conglomerates, AmBev, The Coca-Cola Company, and PepsiCo exemplify scale-driven archetypes leveraging existing beverage infrastructure. These entities occupy positions defined by cold-chain logistics density and retail relationship depth rather than sports-specific innovation. Regional specialists and energy drink crossovers including Monster Beverage Corporation and Red Bull GmbH sit within adjacent-category expansion vectors, representing hybrid positioning between functional beverages and traditional sports hydration.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Suntory Beverage & Food Limited |
| PepsiCo |
| Kill Cliff |
| Fraser and Neave Holdings Bhd |
| The Coca-Cola Company |
| BA Sports Nutrition, LLC |
| AmBev |
| Red Bull GmbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap Brazilian manufacturers anchor production clusters across São Paulo state's Campinas and Sorocaba industrial zones, translating concentrated supply ownership into disciplined margin management that resists commodity-style pricing erosion despite ANVISA reformulation pressures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs shelf positioning, with INMETRO certification and natural sweetener grade driving tier separation. Cost compression in economy tiers intensifies because stevia extract supply volatility from Paraguay squeezes input budgets. Casual drinkers exhibit highest price sensitivity, while competitive athletes in organized football leagues accept premium positioning for osmolality-verified formulations.
Supply Chain Analysis
Natural sweetener supply rests on Paraguayan stevia cultivation and Chinese monk fruit extraction, creating dual-hemisphere dependency for reduced-calorie formulations. Cold-chain logistics infrastructure draws from São Paulo and Rio de Janeiro distribution nodes, with northern states relying on fragmented trucking networks. Single-source vulnerability concentrates in stevia leaf processing capacity. Distribution runs through AmBev's national route density for convenience penetration, while direct-to-consumer platforms bypass traditional retail margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's sports drinks sector reads as a late-cycle quality story where protein-infused recovery formulations displace commodity isotonic volumes as fitness enthusiasts adopt structured post-workout protocols.
For Market Incumbents: Anchor shelf position through backward integration into natural sweetener sourcing partnerships that insulate against Paraguayan supply volatility. Deepen route density advantages in convenience channels to preempt coconut water substitution in coastal markets. Certification investment in INMETRO protocols creates defendable pricing tiers against emerging clean-label competitors. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models targeting CrossFit affiliates in São Paulo's Pinheiros district, where delivery logistics density supports reliable cold-chain fulfillment. Northern corridor whitespace in Amazonas and Pará states offers penetrable geography as organized sports participation formalizes in Manaus and Belém metropolitan areas. Flavor customization platforms provide differentiated go-to-market positioning against mass-market bundling strategies. For Investors and Strategic Acquirers: Beverage conglomerates seeking functional portfolio expansion are the most active acquirer in this space, particularly targets with established ANVISA-compliant reformulation capabilities and e-commerce infrastructure. Five-to-ten year viability hinges on regulatory adaptation speed rather than volume scale alone. Acquisition target archetype: regional specialists with INMETRO certification and direct-to-consumer subscriber bases. Watch ANVISA caffeine threshold adjustments as inflection signal for energy-sports hybrid category restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation for ANVISA Compliance | Natural sweetener transition enables front-of-package warning avoidance and clean-label positioning. |
| Direct-to-Consumer Platform Launch | Subscription models capture recurring revenue from São Paulo CrossFit affiliates outside retail margin structures. |
| Backward Integration into Sweetener Sourcing | Paraguayan stevia partnerships reduce input volatility exposure for reduced-calorie portfolios. |
| INMETRO Certification Investment | Nutritional claims verification supports pricing premiums in specialty shop channels. |
| Northern Corridor Distribution Expansion | Manaus and Belém logistics nodes capture formalizing sports participation in Amazonas and Pará states. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade flow databases, and channel audit data — were reconciled through structured primary interviews with beverage formulation chemists, ANVISA compliance officers, retail category buyers, and gym chain procurement managers. Secondary validation drew from ANVISA public consultation records, INMETRO certification registries, and customs import documentation for natural sweetener shipments. Bottom-up SKU-level volume estimates and top-down category expenditure models were triangulated to constrain forecast variance.
Historical consumption patterns were cross-referenced against panel input from distribution channel partners to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include osmolality category, distribution channel economics, end-user intensity tier, and metropolitan corridor demand cluster. CAGRs were derived from category expenditure elasticity analysis calibrated to amateur sports participation growth and regulatory compliance cost pass-through assumptions. Forecast inputs incorporated ANVISA reformulation timelines and cold-chain logistics expansion trajectories.
Caveats apply where ANVISA caffeine threshold adjustments or municipal plastic waste ordinance fragmentation could materially shift the outlook for energy-sports hybrid categories and single-serve packaging formats. Forecasts reflect assumptions about natural sweetener supply stabilization and northern corridor distribution infrastructure buildout. A small set of named triggers — stevia harvest volatility, ANVISA enforcement intensity, and coconut water pricing — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market