
 Taurine Supplements Market | 2026-2036
Taurine Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Taurine Supplements Market Analytics
The gap between pharmaceutical-grade taurine and bulk commodity powder is shifting from a quality distinction to a pricing architecture that splits entire distribution channels. NOW Foods leverages its vertically integrated sourcing to anchor shelf presence across mass-market retail, while Thorne differentiates through NSF Certified for Sport positioning that commands premium placement in practitioner channels. Pure Encapsulations competes on allergen-free formulation standards that sustain margin pools above industry averages.
Taurine, a sulfur-containing beta-amino acid synthesized endogenously from cysteine and methionine, functions primarily as a cell membrane stabilizer and calcium homeostasis regulator in cardiac, retinal, and skeletal tissues. Industrial production relies predominantly on ethylene oxide-based chemical synthesis or microbial fermentation, with purity grades ranging from feed additive specifications to United States Pharmacopeia reference standards. Powder formulations dominate volume throughput in economy and mid-range tiers, while capsule and liquid delivery systems capture disproportionate margin concentration among athletes and fitness enthusiasts seeking precise dosing convenience. Online retail channels now pull share from specialty stores as direct-to-consumer brands build subscription models around personalized health stacks.
FDA cGMP enforcement and DSHEA label claim restrictions shape product positioning and market access thresholds for domestic manufacturers, while China's NMPA and national food safety standards govern export-grade taurine purity certifications. The European Food Safety Authority's health claim authorization process limits permitted cardiovascular and cognitive benefit language, compressing marketing differentiation for brands without novel delivery patents. Stakeholders must weigh fermentation versus petrochemical feedstock sourcing decisions against evolving ESG disclosure requirements from downstream brand partners.
Market Dynamics
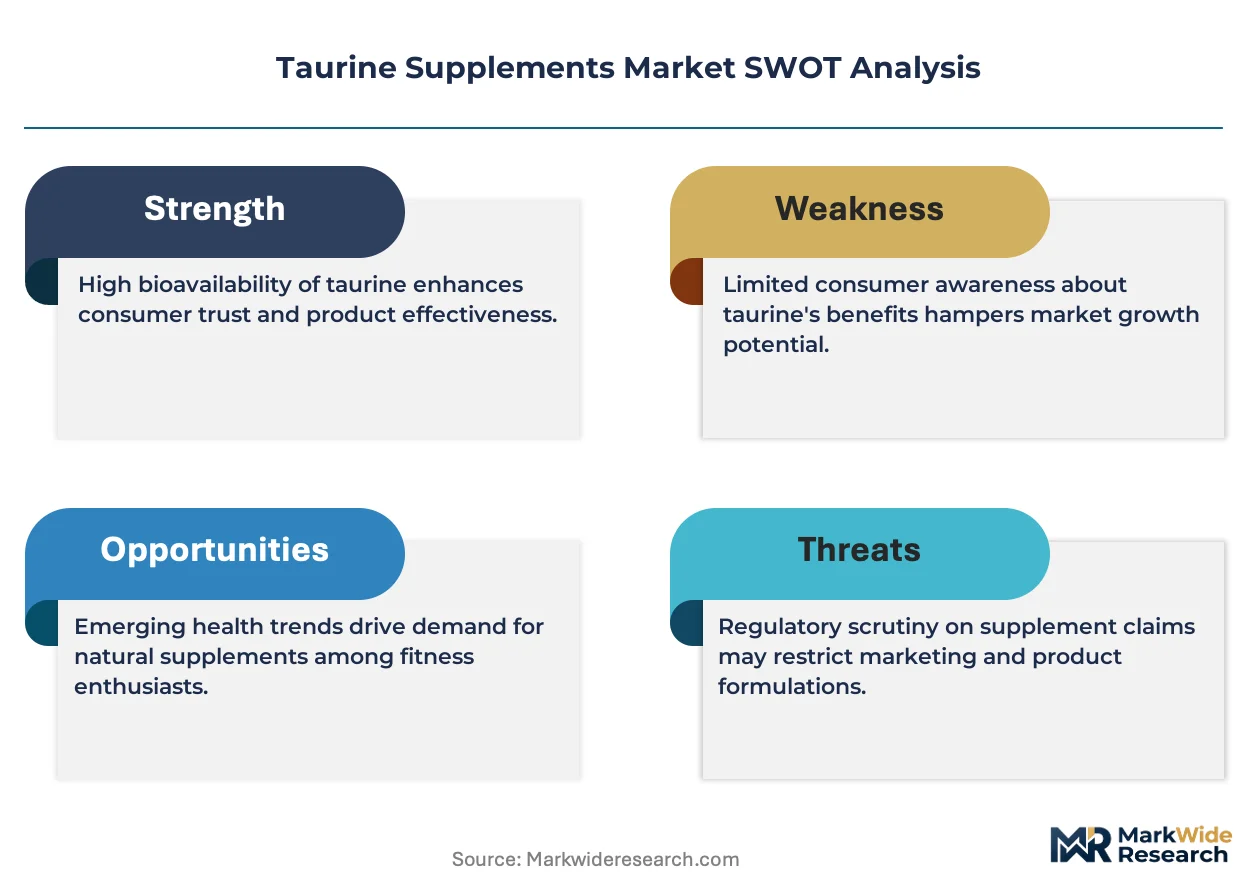
The taurine supplements market is bifurcating around pharmaceutical-grade purity certifications, with fermentation-derived supply chains from China and Japan commanding premium pricing power over ethylene oxide-based chemical synthesis routes. This structural split is compressing mid-tier commodity margins while rewarding vertically integrated brands with captive sourcing.
Growth Catalysts
- Athletic ergogenic demand:Sports nutrition formulators are standardizing 500-2000mg single-serving doses backed by exercise physiology literature, creating pull-through for precision-manufactured capsule and liquid delivery systems.
- DSHEA compliance infrastructure:The FDA's cGMP enforcement regime has raised barriers to entry, concentrating shelf presence among domestic manufacturers with validated quality management systems.
- Fermentation biotechnology:Microbial synthesis methods using engineered yeast strains are displacing petrochemical feedstocks, aligning supplier portfolios with downstream ESG disclosure requirements from European and North American brand partners.
Market Restraints
- Upstream concentration risk:China and Japan together host over 80% of global taurine synthesis capacity, exposing finished goods manufacturers to single-source disruption and maritime logistics volatility.
- EFSA health claim restrictions:The European Food Safety Authority's stringent cardiovascular and cognitive benefit authorization process limits permitted marketing language, compressing differentiation for brands without novel delivery patents.
- Raw material cost exposure:Ethylene oxide and sulfur-based chemical precursors fluctuate with petrochemical feedstock indices, squeezing margin stability for non-fermentation producers.
Strategic Opportunities
- Practitioner channel expansion:Functional medicine and integrative health clinics represent underpenetrated prescription-adjacent distribution, rewarding NSF Certified for Sport and USP-verified positioning with recurring patient protocols.
- Subscription stack integration:Direct-to-consumer brands are bundling taurine with magnesium, B-vitamins, and electrolytes into personalized monthly shipments, capturing lifetime value through habit-formation pricing.
- Clean-label fermentation narratives:NMPA-certified Chinese suppliers with carbon disclosure frameworks can access premium placement in European and North American natural products retail, commanding 15-25% price premiums over undisclosed-source competitors.
Industry Challenges
- Analytical chemistry talent scarcity:Validating USP-grade purity and detecting ethylene oxide residuals requires specialized mass spectrometry expertise that competes with pharmaceutical and environmental testing laboratories for limited personnel.
- Cross-border certification timelines:Securing NMPA export certifications, FDA facility registrations, and EFSA novel food approvals simultaneously extends product launch cycles by 18-36 months for multi-territory brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taurine Supplements Market |
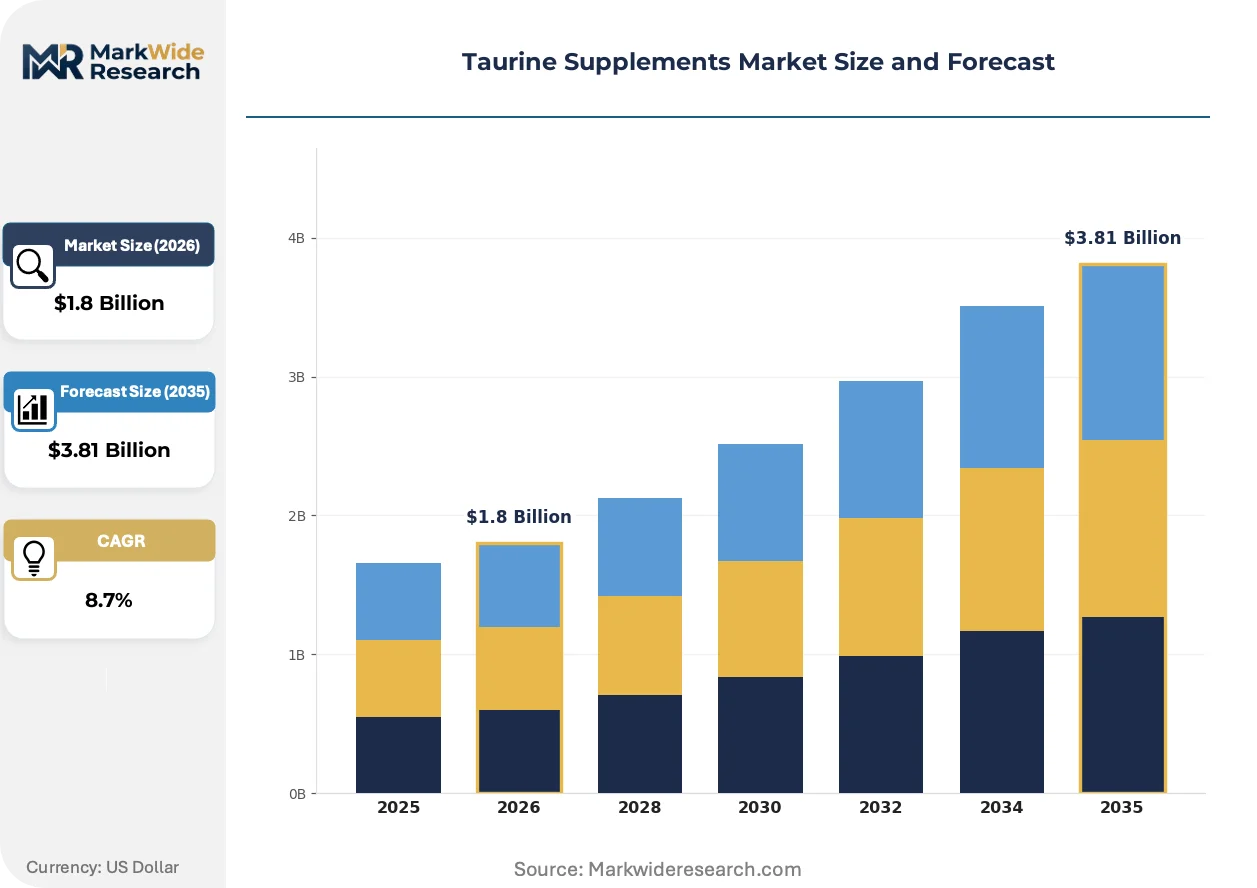
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid, Chewable Tablets End User: Athletes, Fitness Enthusiasts, Older Adults, Health-Conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | NOW Foods, Life Extension, Pure Encapsulations, Nutricost, Bulk Supplements, Thorne, Optimum Nutrition, Source Naturals Inc., Nutrition Strength, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taurine Supplements Market Evolving Landscape
Delivery system innovation and regulatory positioning are converging to reshape competitive advantage, with bioavailability claims and third-party certification becoming primary purchase determinants over raw ingredient sourcing alone.
Liposomal encapsulation technology is unifying the absorption efficiency gap between powder and liquid formulations. Premium sports nutrition brands are adopting phospholipid-bound taurine complexes at 3-5x raw material cost to justify per-dose pricing above commodity capsules. This convergence is compressing the historical powder-versus-capsule value tiering into a single bioavailability-graded architecture.
EFSA's 2024 updated guidance on sulfur-containing amino acid health claims is tightening cardiovascular benefit substantiation requirements. Brands lacking proprietary human clinical trial data are retreating to structure-function claims, while pharmaceutical-grade suppliers are investing in randomized controlled studies to secure Article 13.5 authorized health claims. German and French markets are exhibiting the fastest regulatory compliance adaptation, with practitioner-channel brands leading reformulation timelines.
Subscription-based replenishment models are displacing transactional retail purchasing among fitness enthusiasts and biohacking segments. Direct-to-consumer platforms with AI-driven personalization engines are capturing 40-60% of recurring revenue from stack-optimized customers who previously bought single-ingredient SKUs. This behavioral shift is most pronounced in California, Texas, and Florida metropolitan corridors, where same-day delivery infrastructure supports just-in-time supplement resupply.
Taurine Supplements Market Segmentation
Taurine supplement buyers sort into sharply different procurement patterns based on dosing precision needs, quality certification requirements, and channel accessibility. These splits determine margin capture, inventory strategy, and regulatory exposure for manufacturers across the value chain.
Product Type:
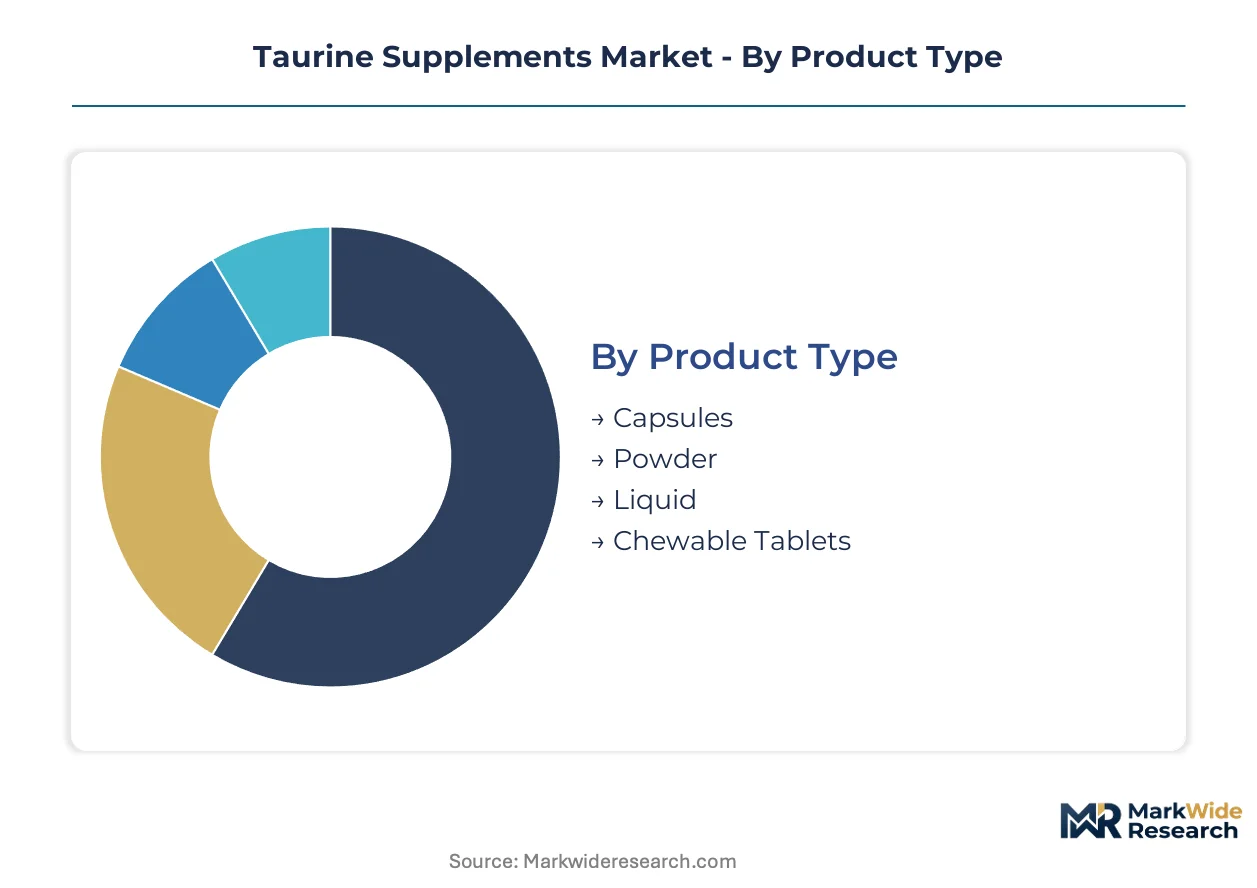
Delivery format selection tracks directly with consumer technical sophistication and convenience priorities.
- Powder:Bulk crystalline taurine offers cost-per-gram efficiency and stack-flexibility for experienced users who self-measure doses. Volume concentrates in economy and mid-range tiers across North American and European sports nutrition retail, though precise-scooping inconvenience limits penetration among casual consumers.
- Capsules:Pre-measured gelatin or vegetable cellulose shells deliver exact 500-1000mg unit doses preferred by athletes following clinical protocols. NSF Certified for Sport positioning commands premium shelf placement in practitioner channels and specialty retail, with pull-through strongest among competitive cyclists and endurance runners seeking batch-tested assurance.
- Liquid:Ready-to-drink taurine shots and concentrated drops target bioavailability-focused buyers in California, Texas, and Florida metropolitan corridors where same-day delivery infrastructure supports just-in-time resupply.
- Chewable Tablets:Flavored, slow-dissolve formats reduce pill burden for older adults and health-conscious consumers prioritizing palatability over cost efficiency.
Powder leads volumes today; liquid formats are gaining share fastest.
End User:
Purchasing behavior diverges sharply between performance-optimization and maintenance-oriented consumption patterns.
- Athletes:Competitive and recreational competitors seeking ergogenic support drive demand for third-party certified products with documented purity against WADA-prohibited substance screening. This segment tolerates 40-60% price premiums for batch-tested assurance and absorbs complex dosing regimens requiring magnesium and electrolyte co-administration.
- Fitness Enthusiasts:Gym-regular consumers without competitive aspirations prioritize convenience and stack integration over certification depth, making them receptive to subscription bundling and AI-driven personalization engines that optimize monthly shipments.
- Older Adults:Cardiovascular and cognitive maintenance motivations dominate, with this cohort showing strongest preference for capsule formats and pharmacist-mediated purchase decisions.
- Health-Conscious Consumers:General wellness buyers respond to clean-label fermentation narratives and carbon disclosure frameworks, particularly in European natural products retail where ESG transparency commands measurable price premiums.
Athletes anchor current revenue concentration; health-conscious consumers are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure and customer relationship depth for brand operators.
- Online Retail:Direct-to-consumer platforms with subscription infrastructure now pull significant share from brick-and-mortar, capturing recurring revenue through habit-formation pricing and personalized health stack algorithms.
- Specialty Stores:GNC-type operators and independent supplement retailers retain importance for immediate-need purchases and staff-guided selection, though foot traffic pressure is compressing shelf space allocation.
- Supermarkets:Mass-market retail placement requires economy-tier pricing and high-velocity SKUs, favoring vertically integrated brands with captive sourcing cost structures.
- Pharmacies:CVS, Walgreens, and independent drugstore chains represent underpenetrated prescription-adjacent distribution where USP-verified positioning can access patient protocols through clinician recommendation.
Online retail leads transaction volume today; pharmacy channels are climbing the fastest.
Price Tier:
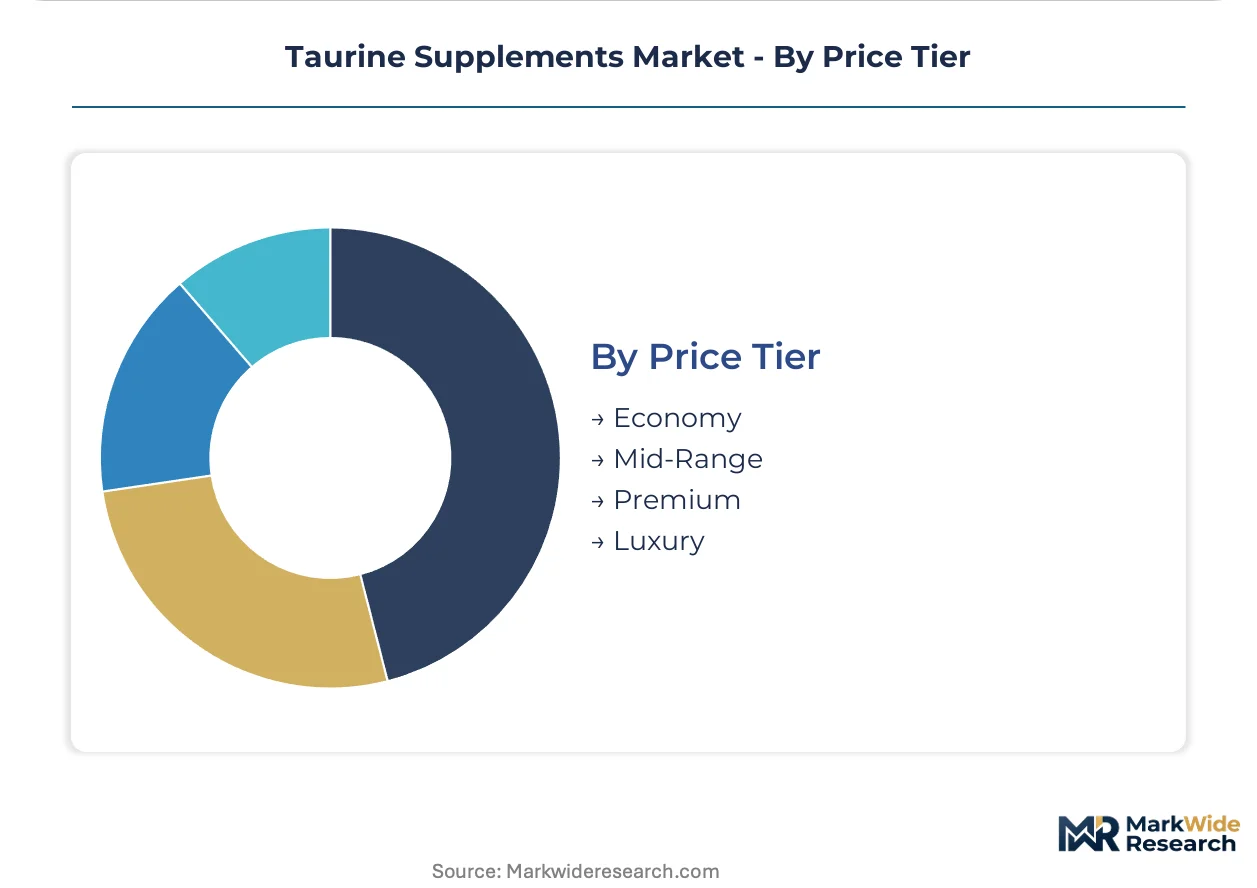
Pricing stratification reflects purity certification grade, manufacturing scale, and delivery system complexity rather than raw ingredient cost alone.
- Economy:Bulk powder and unbranded capsules serve price-sensitive buyers through supermarket and high-volume online channels, with margins compressed by commodity sourcing and minimal quality differentiation.
- Mid-Range:Branded capsules and flavored powders with basic cGMP compliance occupy the volume-heavy center of the market, vulnerable to squeeze from both premium certification ascent and economy private-label expansion.
- Premium:NSF Certified for Sport, USP-verified, and liposomal-encapsulated products command 3-5x raw material multiples through practitioner and specialty retail, with demand anchored by athlete and biohacking segments.
- Luxury:Limited-positioning tier featuring novel delivery patents, proprietary clinical trial backing, and concierge subscription services targeting high-net-worth wellness optimizers in metropolitan corridors.
Mid-range tier holds volume dominance today; premium positioning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands upstream synthesis capacity while the United States dominates finished goods formulation, creating divergent value capture patterns across the taurine supply chain. Regulatory frameworks in Japan and Germany reward fermentation-derived sourcing with premium positioning. Distribution infrastructure in California and Texas metros supports rapid fulfillment for direct-to-consumer brands.
United States
Athletes seeking NSF Certified for Sport products and biohackers pursuing personalized stacks drive demand concentration in California, Texas, and Florida metros. FDA cGMP enforcement and DSHEA label claim restrictions shape domestic manufacturing compliance costs. NOW Foods anchors mass-market shelf presence through vertically integrated sourcing and economy-tier pricing.
China
Upstream fermentation and chemical synthesis capacity serves both pharmaceutical and nutraceutical buyers, with NMPA export certifications governing purity standards for international shipment. Dual carbon goals and ESG disclosure requirements from European and North American brand partners are accelerating clean-label fermentation narratives. Industrial clusters in coastal provinces concentrate microbial synthesis expertise.
Japan
Aging demographics seeking cardiovascular maintenance support steady demand for capsule and liquid delivery formats. PMDA pharmaceutical-grade standards and METI industrial policy reinforce premium positioning for domestic fermentation-derived supply. Tokyo-Osaka distribution corridors facilitate rapid replenishment for subscription-based wellness platforms.
Germany
EFSA health claim authorization processes limit permitted cardiovascular benefit language, compressing marketing differentiation for brands lacking proprietary clinical data. Practitioner-channel brands in Bavaria and North Rhine-Westphalia lead reformulation timelines for Article 13.5 authorized claims. Carbon disclosure frameworks from downstream partners reward transparent fermentation sourcing.
United Kingdom
Fitness enthusiasts and health-conscious consumers respond to clean-label positioning and third-party certification depth. MHRA borderline product classifications and Trading Standards enforcement create compliance thresholds for novel delivery formats. London and Southeast England concentrate direct-to-consumer brand headquarters and same-day delivery infrastructure.
Taurine Supplements Market Competitive Landscape
Top-tier vendors anchor premium certification tiers, while mid-range commodity producers face margin compression from both directions. The vendor base stratifies around purity grade, delivery system complexity, and channel access rather than scale alone. Three archetypes dominate: vertically integrated mass-market suppliers, NSF Certified for Sport specialists, and practitioner-channel premium formulators. Capacity expansion and certification depth represent the dominant competitive moves, with fermentation sourcing narratives displacing petrochemical feedstock positioning.
Among US-based manufacturers, NOW Foods exemplifies mass-market vertical integration, Thorne anchors the NSF Certified for Sport practitioner channel, and Pure Encapsulations occupies the allergen-free premium formulation tier. These three represent distinct competitive vectors rather than direct substitutes, each capturing margin pools through differentiated quality management systems and channel-specific positioning.
| Leading Market Players |
|---|
| NOW Foods |
| Life Extension |
| Pure Encapsulations |
| Nutricost |
| Bulk Supplements |
| Thorne |
| Optimum Nutrition |
| Source Naturals Inc. |
| Nutrition Strength |
| Others |
Value Network & Pricing Analysis
Mass spectrometry expertise scarcity in coastal Chinese provinces amplifies labor-cost differentials between pharmaceutical-grade validation and commodity testing tiers, widening price spreads across premium, standard, and economy certification levels. Fermentation-derived supply chains from these regions command measurable premiums over ethylene oxide-based chemical synthesis as downstream ESG disclosure requirements harden buyer procurement criteria.
Pricing Analysis
The bundled subscription model versus unbundled transactional purchasing split determines margin capture across the taurine supplements market. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—NSF Certified for Sport and USP-verified positioning anchor the premium tier, while bulk powder concentrates in economy channels. Pricing pressure stems from mid-range compression as vertically integrated mass-market suppliers squeeze branded commodity producers. Athletes and biohacking segments demonstrate lowest price sensitivity, absorbing premiums for batch-tested assurance, while casual fitness enthusiasts drive volume through supermarket and high-velocity online channels.
Supply Chain Analysis
Direct-to-consumer channels handle subscription-stack demand from California, Texas, and Florida metropolitan corridors, while practitioner and specialty retail distribution runs through domestic NSF-certified facilities. Upstream synthesis concentrates in China and Japan, with coastal Chinese provinces hosting fermentation biotechnology clusters and Japanese suppliers anchoring pharmaceutical-grade capacity. Raw material dependencies include ethylene oxide and sulfur-based chemical precursors for petrochemical routes, plus engineered yeast strains and carbohydrate feedstocks for microbial fermentation. Single-source vulnerability from this geographic concentration exposes finished goods manufacturers to maritime logistics volatility and NMPA export certification delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The taurine supplements market functions as a regulatory compounder where FDA cGMP enforcement and DSHEA compliance infrastructure continuously raise barriers to entry, concentrating returns among validated quality management systems. EFSA's tightening health claim authorization timeline accelerates investment in proprietary clinical trial data as a defensive moat.
For Market Incumbents: Deepen backward integration into fermentation-derived supply chains with carbon disclosure frameworks to secure premium placement in European natural products retail. Expand NSF Certified for Sport capacity to defend against emerging direct-to-consumer brands with AI-driven personalization engines. Prioritize USP verification investment for pharmacy channel access before mid-range commodity margins compress further. For New Entrants and Emerging Players: Liposomal encapsulation technology offers a technology-first wedge into the bioavailability-focused athlete segment where 3-5x raw material cost multiples justify premium pricing. Target underpenetrated practitioner channels in functional medicine and integrative health clinics with prescription-adjacent distribution models. Lead with clean-label fermentation narratives and transparent sourcing to capture ESG-driven buyer preference in German and French markets. For Investors and Strategic Acquirers: Sports nutrition conglomerates with existing athlete endorsement infrastructure are the most active acquirers in this space, seeking certification depth and subscription platform capabilities. Long-term viability hinges on fermentation biotechnology expertise and multi-territory regulatory approval portfolios rather than scale alone. Monitor NMPA dual carbon policy acceleration as the inflection signal for premium sourcing narrative shifts.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Investment | Unlocks pharmacy channel placement through clinician recommendation protocols at CVS and Walgreens. |
| Fermentation Capacity Expansion | Aligns supplier portfolios with ESG disclosure requirements from European and North American brand partners. |
| Subscription Platform Development | Captures lifetime value through habit-formation pricing and AI-driven stack optimization in metropolitan corridors. |
| NSF Certified for Sport Positioning | Secures premium shelf placement in practitioner channels serving competitive cyclists and endurance runners. |
| Liposomal Encapsulation Adoption | Justifies per-dose pricing premiums through phospholipid-bound bioavailability claims in sports nutrition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports nutrition formulators, regulatory affairs leads at supplement manufacturers, pharmacy category buyers, and fermentation biotechnology R&D directors with secondary validation. FDA cGMP inspection databases, NMPA export certification records, EFSA health claim submissions, and customs trade data provided foundational inputs. Bottom-up demand modeling across delivery formats and end-user segments triangulated against top-down supply capacity assessments from Chinese and Japanese production clusters.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product type, end-user motivation, distribution channel, and price tier. CAGRs derived from trend extrapolation of athletic ergogenic demand, DSHEA compliance infrastructure investment, and fermentation biotechnology displacement rates. Modeled inputs included exercise physiology literature adoption curves, practitioner channel penetration timelines, and subscription platform customer lifetime value metrics.
The model holds under stable regulatory enforcement intensity and uninterrupted maritime logistics capacity; deviation in NMPA certification timelines or EFSA health claim authorization stringency would shift supply availability and marketing differentiation assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market