
 Africa Sports Drink Market | 2026-2036
Africa Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Sports Drink Market Outlook
Electrolyte micro-dosing technology is narrowing the performance gap between premium formulations and mass-market offerings across African manufacturing facilities. The Coca-Cola Company leverages its continent-wide bottling infrastructure to sustain distribution density in peri-urban zones. Tiger Brands Ltd. anchors its competitive position through deep supermarket penetration in South African metropolitan retail. PepsiCo, Inc. differentiates via localized flavor development calibrated to regional taste profiles in West and East African markets.
Africa sports drinks are functional beverages formulated with water, carbohydrates, electrolytes such as sodium and potassium, and flavoring agents, typically manufactured through hot-fill or aseptic processing to achieve shelf stability without preservatives. Their primary commercial purpose is rapid rehydration and glycogen replenishment for individuals engaged in sustained physical exertion across tropical and subtropical climates. Isotonic formulations currently dominate volume due to their osmotic parity with human blood plasma, while hypotonic variants represent the fastest-expanding segment among marathon runners and cycling clubs seeking faster gastric emptying. Distribution through fitness centers is capturing disproportionate margin pools as gym chains in Accra and Dar es Salaam bundle branded hydration into membership tiers.
South Africa's sugar tax framework and Nigeria's National Agency for Food and Drug Administration and Control labeling requirements are tightening compositional standards and compressing formulation flexibility for imported and domestically produced beverages alike. Kenya's Bureau of Standards and Ghana's Food and Drugs Authority are synchronizing electrolyte content disclosure rules, creating a patchwork compliance landscape that favors manufacturers with regional regulatory affairs capabilities. Stakeholders must monitor harmonization momentum between the African Continental Free Trade Area's technical committees and national standards bodies to anticipate whether unified specifications will accelerate cross-border product registration or entrench localized formulation requirements.
Market Dynamics
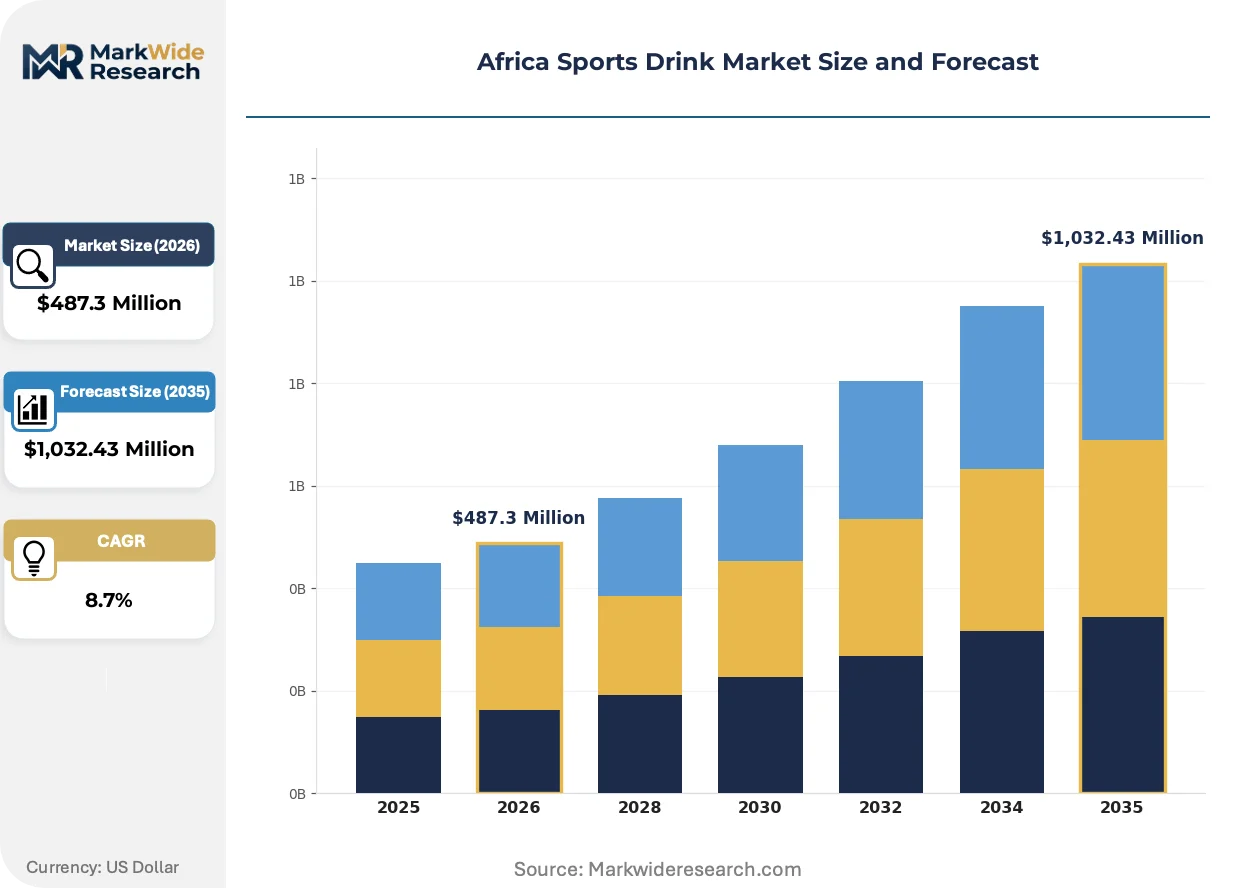
Electrolyte micro-dosing technology is compressing formulation cost curves while South Africa's sugar tax regime forces portfolio restructuring toward reduced-calorie variants. The collision of technical democratization and regulatory stringency is redrawing competitive boundaries across the continent.
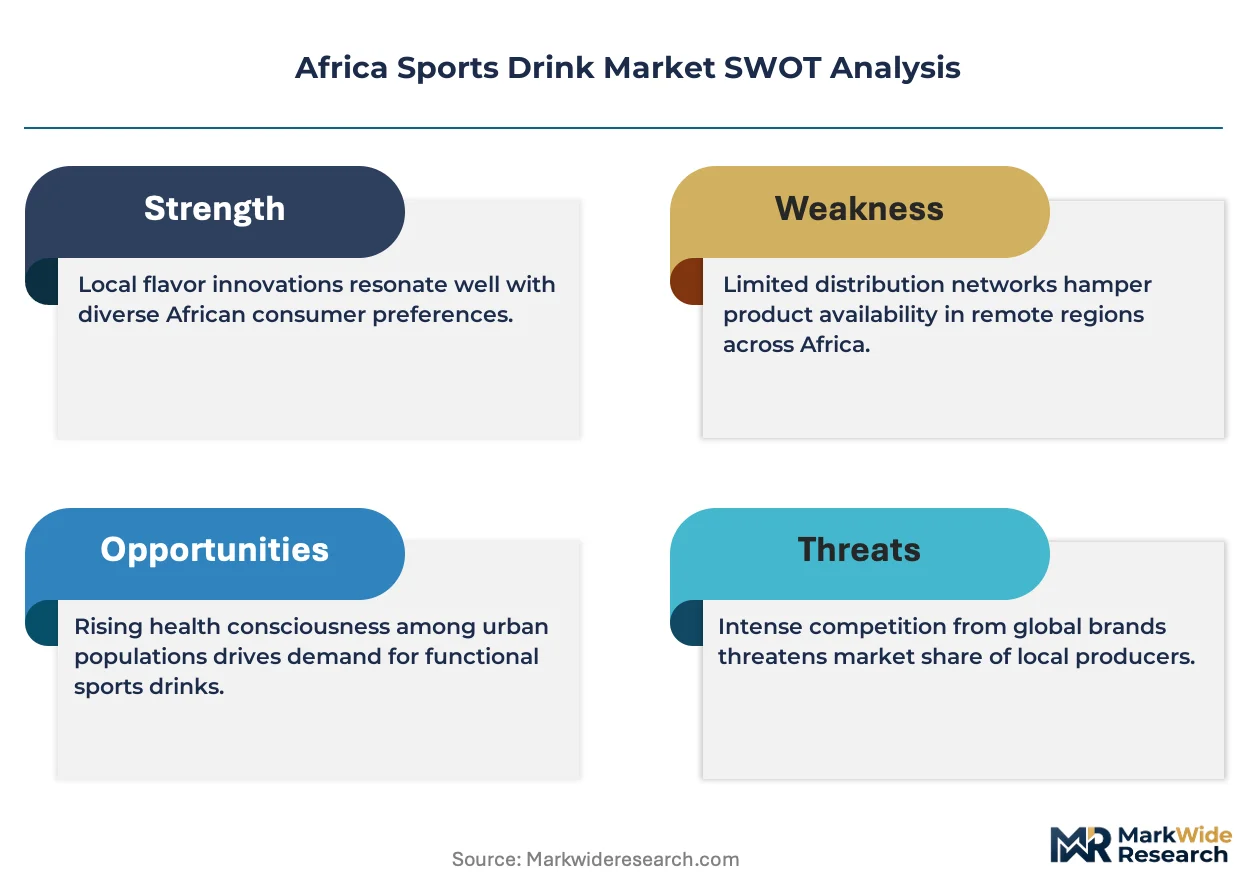
Growth Catalysts
- Sugar Tax Reformulation Mandates:South Africa's Health Promotion Levy is accelerating reduced-calorie product development pipelines. Domestic manufacturers are capturing shelf space from imported full-sugar alternatives.
- Urban Fitness Ecosystem Expansion:Gym chains in Lagos and Nairobi are bundling branded hydration into membership tiers. This channel is capturing disproportionate margin pools through direct consumer relationships.
- Electrolyte Micro-Dosing:Precision mineral delivery systems are narrowing performance gaps between mass-market and premium formulations. African manufacturing facilities are deploying this capability at scale.
Market Restraints
- Input Cost Volatility:Sucrose and citric acid prices fluctuate with currency instability in Nigeria and Kenya. Formulation flexibility is constrained by working capital limitations.
- Supply Concentration Risk:PET resin and aluminum can supply clusters in South Africa and Egypt create geographic dependency. Disruptions cascade through regional bottling networks.
- Regulatory Fragmentation:Kenya's Bureau of Standards and Ghana's Food and Drugs Authority maintain divergent electrolyte disclosure rules. Cross-border product registration requires duplicate compliance investments.
Strategic Opportunities
- Underpenetrated East African Markets:Tanzania and Ethiopia exhibit low per-capita sports drink consumption relative to fitness infrastructure growth. Localized flavor development can preempt multinational entry.
- Peri-Urban Distribution Innovation:Independent convenience networks in secondary Nigerian cities lack systematic hydration product access. Direct distribution partnerships with regional wholesalers unlock penetration.
- Regulatory Harmonization Tailwinds:African Continental Free Trade Area technical committees are advancing unified beverage standards. Early alignment positions manufacturers for accelerated cross-border registration.
Industry Challenges
- Formulation Talent Scarcity:Food chemists with tropical beverage stability expertise are concentrated in South Africa and Egypt. Recruitment for Nigerian and Kenyan facilities requires compensation premiums.
- Cold Chain Infrastructure Gaps:Ambient-stable aseptic processing equipment demands capital outlays that strain mid-tier domestic producers. Financing access varies sharply across national banking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Sports Drink Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Powders Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Fitness Centers End User: Athletes, Casual Sports Participants, Fitness Enthusiasts, Children Flavor: Citrus, Berry, Tropical, Others |
| Companies Covered | Tiger Brands Ltd., Congo Brands, The Coca-Cola Company, BOS Brands (Pty) Ltd, Aje Group, PepsiCo, Inc., Kingsley Beverages Ltd., Ekhamanzi Springs (Pty) Ltd, Suntory Holdings Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Sports Drink Market Strategic Shifts
Three convergent forces are restructuring the Africa sports drink landscape: manufacturing technology is flattening quality hierarchies, regulatory jurisdictions are tightening compositional standards, and consumption occasions are fragmenting beyond traditional athletic use.
Electrolyte micro-dosing technology enables precise sodium and potassium delivery at reduced raw material volumes. Marathon runners and cycling clubs in Nairobi and Accra are adopting hypotonic variants formulated with this approach. The technology is rendering obsolete the cost premium historically commanded by imported isotonic formulations.
South Africa's updated Health Promotion Levy framework now captures beverages with broader sugar concentration ranges. Domestic bottlers are reformulating portfolios to maintain price competitiveness against reduced-calorie imports. The regulatory pressure is compressing full-sugar variant shelf life in supermarket chains across Johannesburg and Cape Town metropolitan zones.
Fitness center procurement managers are consolidating hydration supply contracts into exclusive multi-year agreements. Independent distributors serving traditional retail channels face margin compression as gym chains in Dar es Salaam and Accra bundle branded products into membership tiers. This concentration is most visible in Nigerian urban centers where premium gym expansion outpaces general retail coverage.
Africa Sports Drink Market Segmentation
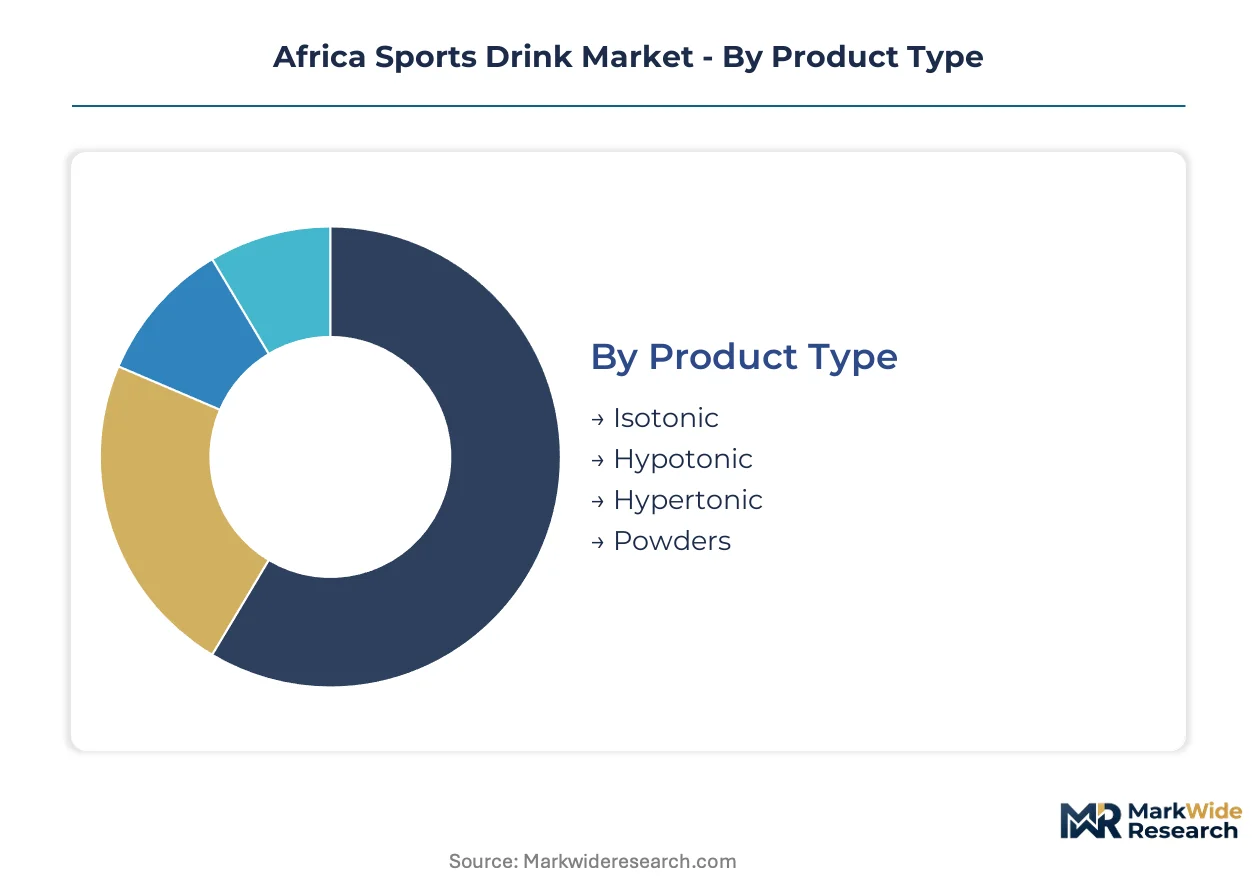
Segmentation reveals how hydration demand fragments across performance intensity, purchase occasion, and consumer physiology. Manufacturers must align formulation, packaging, and channel strategy to each distinct use case rather than deploying uniform portfolios.
Product Type:
Cost tier determines raw material intensity and manufacturing complexity across formulation categories.
- Isotonic:Osmotic parity with blood plasma delivers balanced fluid and electrolyte replacement. Professional football clubs in Nigeria and South Africa specify these formulations for match-day hydration protocols. Sugar tax pressures in South Africa are forcing reformulation toward reduced-calorie isotonic variants.
- Hypotonic:Lower solute concentration accelerates gastric emptying for rapid absorption. Marathon runners and cycling clubs in Nairobi and Accra are adopting these variants as electrolyte micro-dosing technology narrows performance gaps. This segment is climbing the fastest in volume rankings among serious amateur athletes.
- Hypertonic:High carbohydrate density targets glycogen replenishment post-exertion. Compact serving formats suit backpack-portable consumption.
- Powders:Dry concentrate sachets reduce shipping weight and retail shelf space. Urban fitness enthusiasts in Lagos favor single-serve portability.
Isotonic holds installed capacity across African bottling networks. Hypotonic is rotating up the share rankings among endurance sports participants.
Distribution Channel:
Application context shapes procurement behavior from impulse purchase to planned replenishment.
- Supermarkets:Multi-SKU displays enable comparison shopping across price tiers. Tiger Brands Ltd. anchors shelf presence in South African metropolitan retail through deep penetration agreements.
- Convenience Stores:Ambient-stable formats dominate impulse purchases in transit corridors. Independent networks in secondary Nigerian cities represent systematic underpenetration.
- Online Retail:Subscription models capture recurring demand from committed fitness enthusiasts. Lagos and Johannesburg urban logistics infrastructure supports same-day delivery windows.
- Fitness Centers:Bundled hydration in membership tiers captures disproportionate margin pools. Gym chains in Dar es Salaam and Accra are consolidating supply into exclusive multi-year agreements.
Supermarkets hold installed capacity in South African metropolitan zones. Fitness centers are rotating up the share rankings through direct consumer relationships.
End User:
Customer type determines electrolyte concentration requirements, flavor preferences, and price sensitivity thresholds.
- Athletes:Competitive performers demand precise sodium-potassium ratios calibrated to sweat loss rates. Professional clubs across Nigeria specify batch-tested formulations.
- Casual Sports Participants:Weekend footballers and social runners prioritize palatability over performance optimization. This segment shows steepest expansion trajectory as urban recreational leagues multiply.
- Fitness Enthusiasts:Gym-regular consumers integrate hydration into daily wellness rituals. Nairobi and Lagos premium gym expansion outpaces general retail coverage.
- Children:Paediatric formulations require adjusted electrolyte loads and allergen labeling. Kenya's Bureau of Standards maintains specific disclosure requirements for this demographic.
Athletes hold installed capacity in institutional procurement systems. Fitness enthusiasts are rotating up the share rankings through membership-tier bundling.
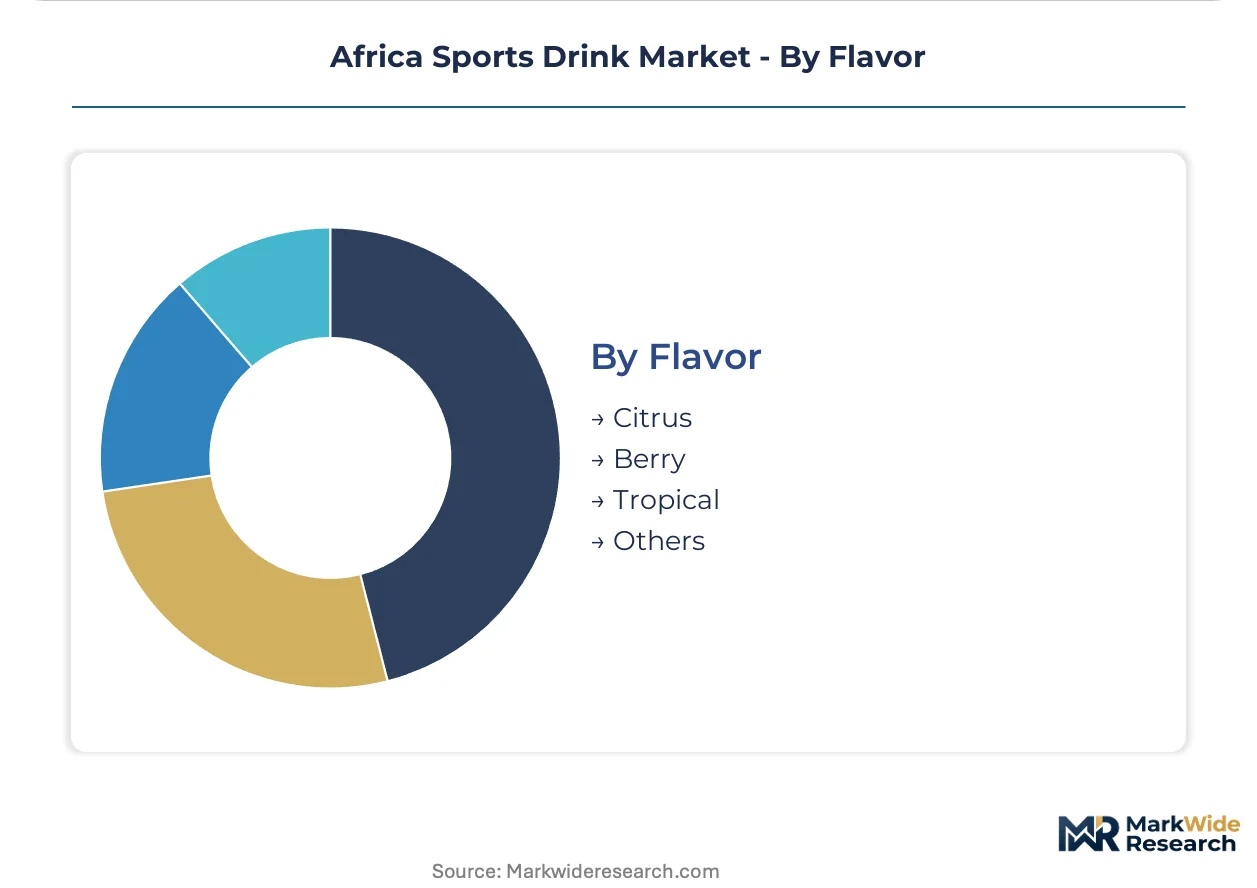
Flavor:
Geography drives taste calibration as regional preference clusters diverge across West and East African markets.
- Citrus:Lemon-lime and orange profiles dominate standard formulations. PepsiCo, Inc. differentiates through localized citrus variants calibrated to West African palates.
- Berry:Mixed berry blends command premium positioning in South African supermarket chains. The Coca-Cola Company deploys continent-wide bottling infrastructure to sustain distribution density.
- Tropical:Mango, pineapple, and passionfruit variants align with indigenous fruit profiles. Localized development pipelines target East African consumer panels.
- Others:Ginger, watermelon, and experimental botanicals occupy niche positioning. Limited production runs test market receptivity before scale-up.
Citrus holds installed capacity in mass-market formulations. Tropical is rotating up the share rankings through regional taste localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African bottlers export reduced-calorie formulations into Nigerian and Kenyan distribution networks. Cross-border trade corridors concentrate premium product flows through Johannesburg logistics hubs.
South Africa
Johannesburg metropolitan retail anchors continental distribution density for reduced-calorie variants. The Health Promotion Levy compresses full-sugar product shelf life. Cape Town manufacturing clusters deploy electrolyte micro-dosing equipment at scale.
Nigeria
Lagos urban fitness ecosystems drive demand for isotonic formulations among professional football clubs. The National Agency for Food and Drug Administration and Control enforces strict labeling disclosure requirements. Secondary city convenience networks in Ibadan and Kano remain systematically underpenetrated.
Kenya
Nairobi marathon runners and cycling clubs adopt hypotonic variants for rapid gastric emptying. The Bureau of Standards synchronizes electrolyte content rules with Ghanaian counterparts. Mombasa port logistics facilitate East African regional distribution.
Ghana
Accra gym chains bundle branded hydration into exclusive membership tiers. The Food and Drugs Authority maintains divergent disclosure standards from Kenyan regulators. Takoradi manufacturing zones process imported concentrate for local formulation.
Ethiopia
Addis Ababa fitness infrastructure expansion outpaces per-capita sports drink consumption. The country's national food and drug regulator develops technical standards for electrolyte beverages. Industrial zones near the capital attract preliminary bottling investment.
Africa Sports Drink Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented metropolitan retail and consolidated fitness center procurement. The market exhibits tiered concentration: multinational bottlers leverage continent-wide infrastructure while domestic formulators anchor regional taste preferences. Three archetypes dominate: infrastructure-leveraged multinationals, supermarket-anchored domestic bottlers, and flavor-specialist regional players. Competitive moves center on exclusive gym chain supply contracts and reduced-calorie portfolio restructuring.
Within the infrastructure-leveraged tier, The Coca-Cola Company and PepsiCo, Inc. exemplify scale-driven distribution density. Tiger Brands Ltd. occupies a position as a supermarket-anchored domestic specialist. These three represent distinct competitive vectors: continental bottling networks, localized flavor development pipelines, and deep metropolitan retail penetration.
| Leading Market Players |
|---|
| Tiger Brands Ltd. |
| Congo Brands |
| The Coca-Cola Company |
| BOS Brands (Pty) Ltd |
| Aje Group |
| PepsiCo, Inc. |
| Kingsley Beverages Ltd. |
| Ekhamanzi Springs (Pty) Ltd |
| Suntory Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Input cost volatility around sucrose and citric acid determines both the spread between premium and mass-market pricing tiers and the geographic clustering of manufacturing capacity across African bottling networks. Currency instability in Nigeria and Kenya compresses formulation flexibility while forcing working capital trade-offs that reshape supplier relationships.
Pricing Analysis
The electrolyte micro-dosing technology gap separates legacy isotonic formulations from next-generation hypotonic variants calibrated for rapid gastric emptying. Three-tier pricing structure across premium, standard, and economy levels stratifies by electrolyte precision and brand positioning, with South Africa's Health Promotion Levy accelerating cost compression in full-sugar tiers. Price differentiation hinges on certification alignment with Kenya's Bureau of Standards and volume scale through fitness center procurement consolidation. Casual sports participants exhibit highest price sensitivity while professional football clubs prioritize batch-tested performance over cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Tiger Brands Ltd. and The Coca-Cola Company's continent-wide bottling infrastructure, supplemented by regional specialists in Takoradi and Mombasa. Geographic supply concentration clusters in South Africa and Egypt for PET resin and aluminum can inputs, with formulation chemistry anchored in Johannesburg and Cape Town manufacturing zones. Raw material dependencies rest on sucrose, citric acid, and electrolyte mineral concentrates sourced through Egyptian and South African chemical distributors. Single-source vulnerability around PET resin creates cascading disruption risk through Nigerian and Kenyan bottling networks. Distribution runs through supermarket chains in metropolitan Johannesburg and exclusive fitness center agreements in Lagos and Accra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa sports drink market tracks a cyclical recovery pattern as sugar tax reformulation mandates force portfolio restructuring and create replacement demand for reduced-calorie variants. Urban fitness ecosystem expansion provides the demand-side cyclical driver as gym chain penetration outpaces general retail coverage across major metropolitan zones.
For Market Incumbents: Harden defensive positions through backward integration into electrolyte concentrate supply and exclusive multi-year fitness center procurement agreements. Threats from emerging flavor-specialist regional players in East Africa require preemptive localized product development pipelines. Capacity addition in peri-urban Nigerian distribution networks represents the priority lever for margin protection. For New Entrants and Emerging Players: Pursue white-space opportunities in Tanzania and Ethiopia where fitness infrastructure growth exceeds per-capita sports drink consumption penetration. Secondary Nigerian cities including Ibadan and Kano present the most penetrable geography through direct distribution partnerships with independent convenience networks. Go-to-market execution should anchor on tropical flavor localization calibrated to East African consumer panels. For Investors and Strategic Acquirers: African Continental Free Trade Area technical committee harmonization reshapes the acquisition landscape by favoring manufacturers with pre-established regional regulatory affairs capabilities. Long-term viability across a five-to-ten-year window rests on positioning for unified beverage standards that accelerate cross-border product registration. Acquisition target archetypes include flavor-specialist regional players with established Ghanaian or Kenyan regulatory compliance. The signal to monitor is momentum between AfCFTA technical committees and national standards bodies toward specification convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Calorie Portfolio Restructuring | South Africa's Health Promotion Levy compresses full-sugar variant shelf life in Johannesburg supermarkets. |
| Electrolyte Micro-Dosing Manufacturing Scale-Up | Cape Town facilities deploying precision mineral delivery narrow premium-mass market performance gaps. |
| Exclusive Fitness Center Supply Agreements | Gym chains in Dar es Salaam and Accra consolidate hydration procurement into bundled membership tiers. |
| East African Flavor Localization Pipeline | Tropical variants targeting Nairobi and Addis Ababa preempt multinational entry into underpenetrated markets. |
| Peri-Urban Distribution Network Expansion | Direct wholesaler partnerships unlock secondary Nigerian city penetration beyond Lagos metropolitan coverage. |
Study Parameters
Cross-validation between executive interviews and secondary regulatory filings anchors the qualitative findings across the Africa sports drink landscape. Primary fieldwork engaged beverage formulation chemists, fitness center procurement managers, supermarket category buyers, and regulatory affairs specialists at national standards bodies. Secondary sources included Kenya's Bureau of Standards disclosure requirements, Ghana's Food and Drugs Authority labeling guidelines, South African Revenue Service customs records, and Nielsen retail audit data. Bottom-up channel volume estimates triangulate against top-down macroeconomic consumption projections.
Calibration against historical sugar tax implementation timelines and fitness center membership growth curves shapes the analytical framework. Segmentation dimensions span product type, distribution channel, end user physiology, and regional regulatory cluster across the projection horizon. CAGRs derive from electrolyte micro-dosing adoption curves and urban fitness infrastructure build-out rates. Forecast inputs incorporate South Africa's Health Promotion Levy expansion scope and AfCFTA technical committee harmonization momentum.
Sensitivities concentrate around currency volatility in Nigeria and Kenya, PET resin supply disruptions from Egyptian manufacturing zones, and divergent national standards body rulings on electrolyte disclosure. Forecasts reflect documented assumptions on regulatory timelines and technology adoption rates. Quarterly review of AfCFTA technical committee proceedings and national sugar tax amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Cricket Protein Powder Market