
 GCC Sports Nutrition Market | 2026-2036
GCC Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Sports Nutrition Market Intelligence
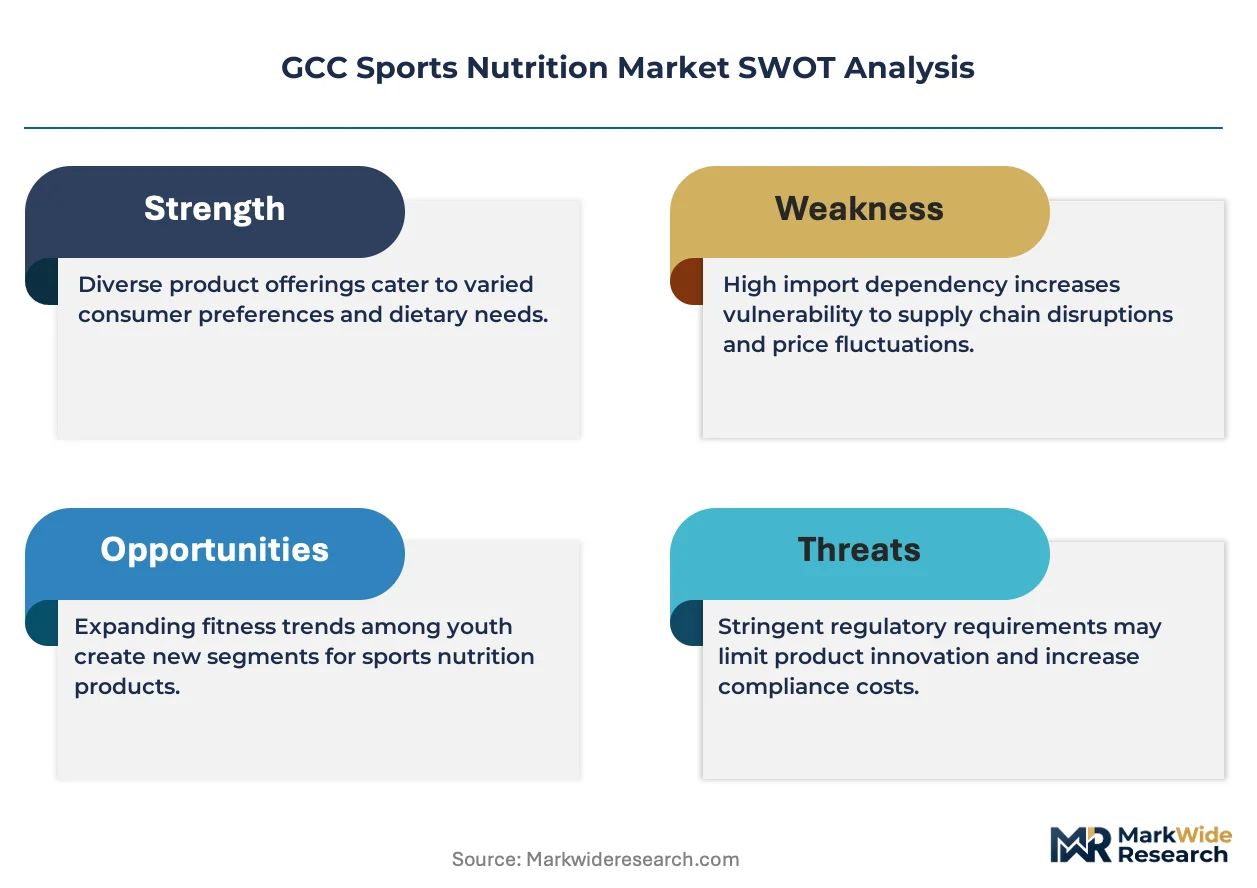
Premium whey isolate formulations and commodity-grade soy blends is decoupling across Gulf retail shelves as ingredient transparency becomes a decisive purchase criterion. Optimum Nutrition leverages its certified manufacturing partnerships to sustain shelf placement in UAE pharmacy chains. Myprotein competes through direct-to-consumer pricing that undercuts traditional import markups. Abbott Nutrition anchors the clinical recovery segment with hospital-endorsed formulations.
GCC sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, or body composition, typically specifying protein content per serving, amino acid profiles, and banned-substance screening under WADA-aligned protocols. These products serve competitive athletes, gym members, and lifestyle consumers seeking measurable physiological outcomes. Protein powders dominate volume through recurring purchase patterns among bodybuilders, while ready-to-drink beverages capture the fastest expansion as convenience-seeking fitness enthusiasts shift from kitchen preparation to grab-and-go formats. Online retail channels now command margin pools previously captured by specialty stores, reflecting platform-level subscription mechanics and influencer-driven discovery.
MOHAP in the UAE and the Saudi Food and Drug Authority enforce distinct label Arabicization and ingredient disclosure standards that filter non-compliant imports before market entry. The Gulf Standardization Organization's harmonization push is reducing cross-border registration friction for compliant manufacturers. Stakeholders must monitor evolving halal certification requirements for fermentation-derived ingredients as biotech proteins enter regional formulations.
Market Dynamics
Personalized nutrition protocols now penetrate professional sports conditioning programs across Saudi Arabia and the UAE, creating tiered demand structures that separate clinical-grade formulations from commodity supplements. This segmentation is compressing margins for undifferentiated imports while rewarding certified manufacturers with pharmacy and hospital channel access.
Growth Catalysts
- SFDA Registration Harmonization:Saudi Arabia's streamlined food supplement approval pathways reduce time-to-market for compliant international brands seeking Gulf expansion.
- Fitness Center Density Concentration:Riyadh and Jeddah host the highest per-capita gym memberships in the GCC, generating recurring protein powder demand from bodybuilders and lifestyle consumers.
- Ready-to-Drink Format Migration:Convenience-seeking athletes are displacing kitchen-prepared shakes with grab-and-go beverages, expanding addressable occasions beyond traditional workout windows.
Market Restraints
- Whey Protein Input Volatility:Global dairy commodity price swings transmit directly to isolate and concentrate production costs, squeezing margin buffers for mid-tier brands.
- Import Concentration Risk:European and North American suppliers dominate premium formulation supply, exposing distributors to currency fluctuation and shipping disruption exposure.
- MOHAP Label Arabicization Requirements:UAE's mandatory bilingual disclosure standards filter non-compliant products before market entry, creating registration friction for smaller exporters.
Strategic Opportunities
- Biotech Protein Halal Certification:Fermentation-derived ingredients require novel religious approval frameworks, creating first-mover advantage for manufacturers securing advance rulings from regional Islamic authorities.
- Subscription Platform Economics:Direct-to-consumer models with automated replenishment mechanics capture lifetime value pools previously fragmented across retail intermediaries.
- Clinical Recovery Segment Expansion:Hospital-endorsed formulations for post-surgical and rehabilitation patients remain underpenetrated relative to athletic performance positioning.
Industry Challenges
- Specialized Formulation Talent Scarcity:Gulf universities produce limited sports nutrition scientists, forcing manufacturers to import R&D capabilities or outsource product development.
- Cross-Border Registration Complexity:Divergent standards between Saudi SFDA and UAE MOHAP require duplicate compliance investments despite Gulf Standardization Organization harmonization efforts.
- Influencer-Driven Quality Assurance:Social media endorsement cycles compress product testing timelines, elevating risk of banned-substance contamination in rushed launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Sports Nutrition Market |
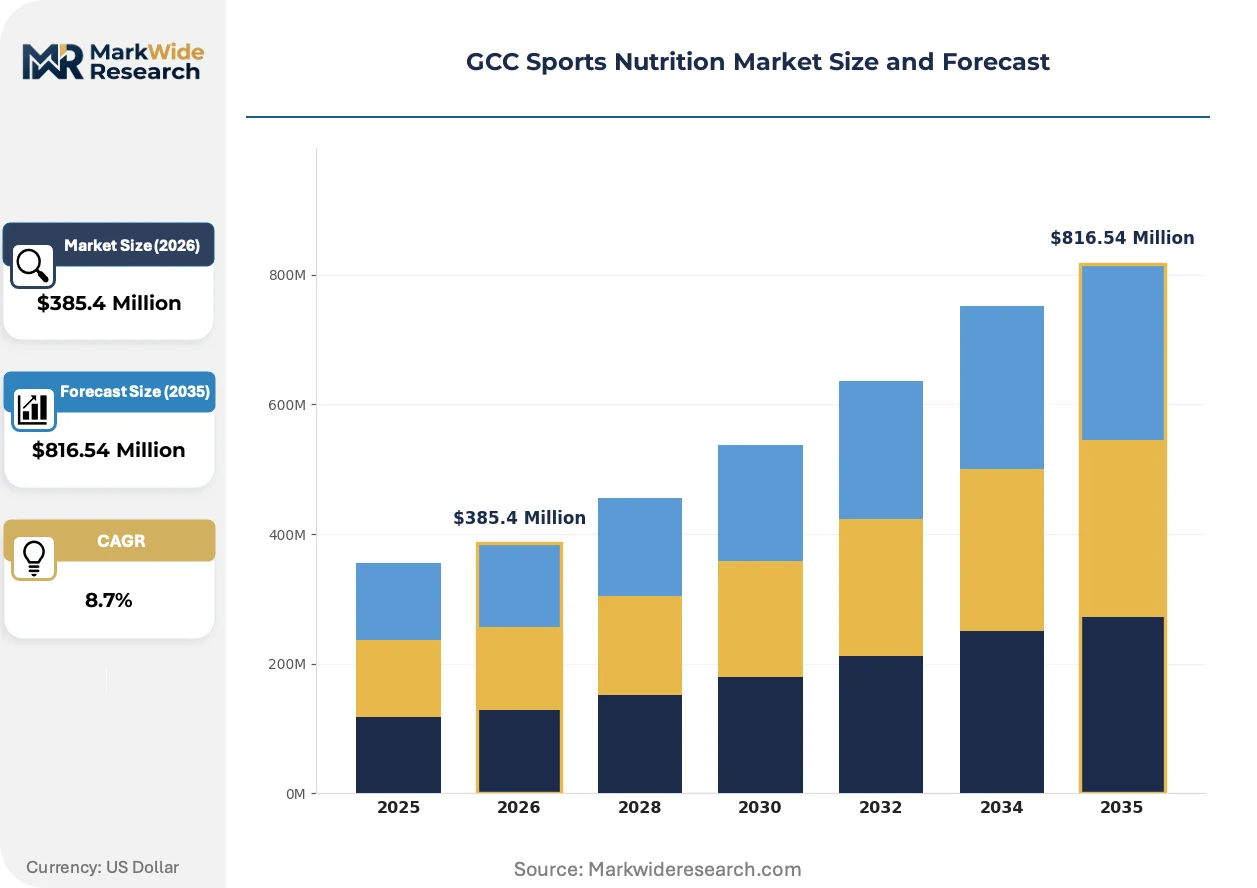
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Energy Bars, Ready-to-Drink Beverages, Supplements End User: Athletes, Fitness Enthusiasts, Bodybuilders, Recreational Users Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Shops Packaging Type: Tubs, Sachets, Cans, Bottles |
| Companies Covered | BSN, Myprotein, Optimum Nutrition, Olimp Sport Nutrition, Scitec Nutrition, Abbott Nutrition, Herbalife Nutrition, Amway, GNC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Sports Nutrition Market Strategic Shifts & Innovations
Digital health integration and ingredient traceability systems are restructuring how Gulf consumers evaluate supplement efficacy and safety. These shifts favor transparent supply chains over opaque commodity sourcing.
Blockchain-enabled batch tracking is unifying supplier verification with end-consumer scanning apps across UAE pharmacy networks. Athletes and fitness enthusiasts now authenticate whey origin and halal certification status before purchase. This transparency compression is eliminating information asymmetry that previously protected lower-grade competitors.
MOHAP's updated food supplement registration requirements under UAE federal health law mandate expanded ingredient disclosure and stability testing documentation. Imported brands must accelerate compliance investments or surrender shelf placement to certified alternatives. The policy shift most acutely affects European exporters previously relying on mutual recognition agreements.
Online retail channels now command margin pools previously captured by Dubai and Abu Dhabi specialty supplement stores. Platform-level subscription mechanics and TikTok-driven discovery are displacing in-person consultation as the primary purchase trigger. This channel rotation is most visible among Saudi consumers aged 18-34 in Riyadh's metropolitan district.
GCC Sports Nutrition Market Segmentation
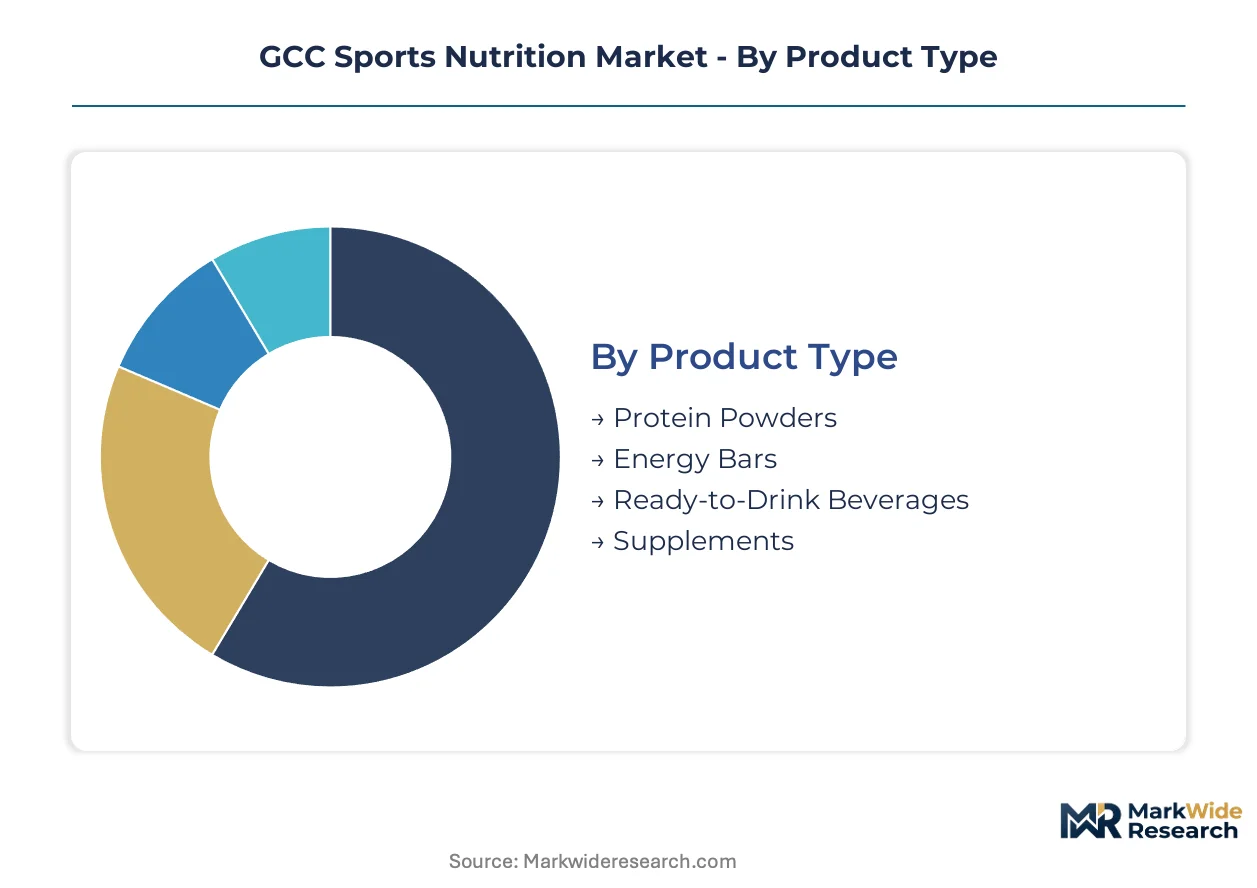
Product formulation complexity and regulatory compliance intensity vary dramatically across the GCC sports nutrition landscape. Capital deployment patterns and margin structures diverge sharply between clinical-grade manufacturing and commodity blending operations.
Product Type:
Protein isolates and ready-to-drink beverages demand the heaviest upfront manufacturing investment due to sterile processing infrastructure and shelf-stability testing protocols.
- Protein Powders:Whey isolate and concentrate formulations dominate recurring purchase volumes among bodybuilders and lifestyle consumers. Riyadh and Jeddah fitness centers generate concentrated demand for 2-5kg bulk tubs with WADA-aligned banned-substance screening.
- Ready-to-Drink Beverages:Aseptic filling lines and extended shelf-life validation require capital-intensive production setups. Convenience-seeking athletes across the UAE's Dubai-Abu Dhabi corridor are displacing kitchen-prepared shakes with grab-and-go formats.
- Energy Bars:Co-manufacturing partnerships reduce fixed asset requirements for brands entering the GCC.
- Supplements:Pre-workout and amino acid formulations face stricter MOHAP disclosure standards for stimulant content.
Most installed capacity flows through Protein Powders. Expansion is steepest in Ready-to-Drink Beverages.
End User:
Application intensity determines procurement sophistication, with professional athletes demanding batch-level traceability unavailable to casual consumers.
- Athletes:Professional football clubs in Saudi Arabia now mandate personalized nutrition protocols with clinical-grade formulations. SFDA registration and halal certification requirements filter supplier pools aggressively.
- Bodybuilders:High-volume protein consumption drives recurring bulk purchases with price sensitivity concentrated in mid-tier brands.
- Fitness Enthusiasts:Subscription platform mechanics capture this digitally native cohort through automated replenishment.
- Recreational Users:Impulse purchasing through supermarket channels dominates with minimal brand loyalty.
Professional athletes command premium pricing power. Recreational Users are gaining share fastest through mass-market channel expansion.
Distribution Channel:
Customer acquisition economics and margin retention rates diverge sharply between platform-native and brick-and-mortar intermediaries.
- Online Retail:Direct-to-consumer models with TikTok-driven discovery and subscription mechanics now capture lifetime value pools previously fragmented across retail intermediaries. Saudi consumers aged 18-34 in Riyadh's metropolitan district drive this channel rotation.
- Specialty Stores:In-person consultation and taste sampling retain importance for first-time purchasers evaluating flavor profiles.
- Supermarkets:Mass-market placement sacrifices margin for volume exposure to recreational users.
- Health Food Shops:Pharmacy-adjacent positioning in UAE chains requires MOHAP registration and bilingual label compliance.
Specialty Stores retain the highest customer lifetime value. Online Retail shows the steepest expansion trajectory.
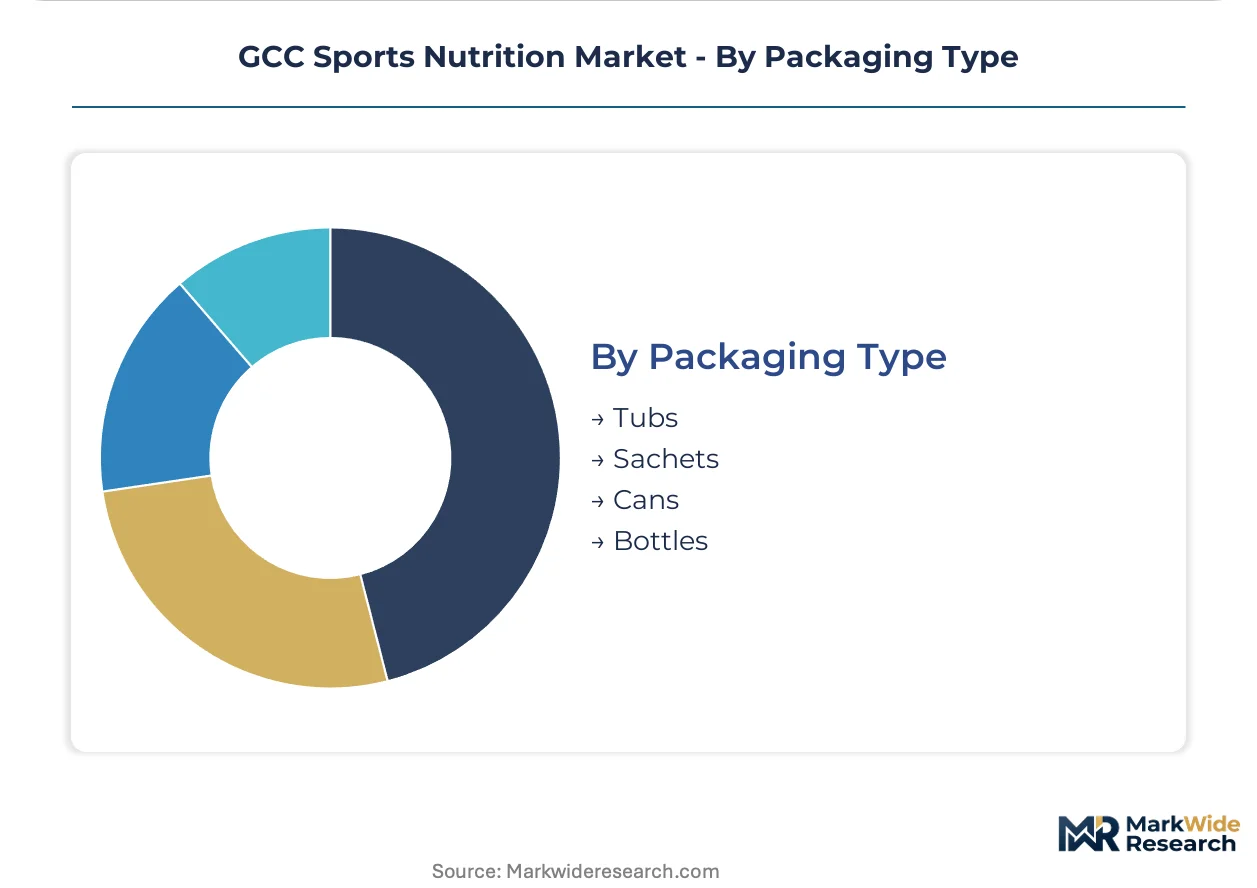
Packaging Type:
Unit economics and logistics complexity vary with format scale and shelf-preservation requirements.
- Tubs:Multi-serving containers dominate bodybuilder bulk purchasing with lowest per-gram packaging cost.
- Sachets:Single-serve formats command premium pricing for travel and trial occasions across UAE gym networks.
- Cans:Aseptic processing requirements align with ready-to-drink beverage manufacturing infrastructure.
- Bottles:PET and glass variants serve distinct temperature-control needs in Gulf climate conditions.
Tubs carry the highest shipment volumes. Sachets are climbing the fastest as trial-size sampling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands larger absolute volumes than the UAE, yet Dubai's regulatory infrastructure attracts more international brand registrations per capita. This divergence shapes divergent market entry strategies across the Gulf.
Saudi Arabia
Riyadh and Jeddah fitness centers generate concentrated demand for clinical-grade formulations with WADA-aligned banned-substance screening. SFDA registration harmonization accelerates approval pathways for compliant international brands. The Riyadh-Jeddah corridor hosts the highest per-capita gym memberships in the GCC, driving recurring bulk protein purchases.
United Arab Emirates
Dubai's pharmacy chains and Abu Dhabi's hospital networks anchor premium product distribution with MOHAP-mandated bilingual label requirements. MOHAP's updated food supplement registration standards filter non-compliant imports before market entry. The Dubai-Abu Dhabi corridor leads ready-to-drink beverage adoption among convenience-seeking fitness enthusiasts.
Qatar
Doha's professional sports infrastructure and rising fitness center density generate demand for personalized nutrition protocols. The country's national health regulator enforces ingredient disclosure standards aligned with Gulf Standardization Organization frameworks. West Bay and Lusail districts concentrate high-income consumers driving premium product trials.
Kuwait
Kuwait City's gym networks and specialized supplement retailers sustain mid-tier brand volumes despite smaller population scale. The national food and nutrition authority applies SFDA-aligned halal certification requirements for imported formulations. Salmiya and Hawalli districts host the densest specialty store concentrations for bodybuilder procurement.
Bahrain
Manama's fitness enthusiasts and cross-border shoppers from Saudi Arabia's Eastern Province sustain niche demand for premium imports. The national health regulator maintains bilateral recognition agreements with UAE MOHAP for streamlined product registration. Seef and Juffair districts concentrate gym memberships and health food shop placements.
GCC Sports Nutrition Market Key Industry Players
Top-tier vendors anchor pharmacy and hospital channels, while direct-to-consumer specialists compete on price transparency and subscription mechanics. The market structures around three tiers: certified manufacturers with SFDA/MOHAP registrations, import-dependent distributors with retail network access, and platform-native brands leveraging social media discovery. Strategic archetypes include clinical-grade formulators, mass-market commoditizers, and influencer-driven digital natives. Competitive moves concentrate on compliance investments for regulatory access and subscription platform builds for customer lifetime value capture.
Among established supplement specialists, Optimum Nutrition, Myprotein, and Abbott Nutrition occupy distinct positioning vectors. Optimum Nutrition exemplifies the certified manufacturing archetype with sustained pharmacy chain placements. Myprotein represents the direct-to-consumer pricing model that undercuts traditional import markups through platform-native distribution. Abbott Nutrition anchors the clinical recovery segment with hospital-endorsed formulations, occupying a defensible position in post-surgical and rehabilitation applications.
| Leading Market Players |
|---|
| BSN |
| Myprotein |
| Optimum Nutrition |
| Olimp Sport Nutrition |
| Scitec Nutrition |
| Abbott Nutrition |
| Herbalife Nutrition |
| Amway |
| GNC |
| Others |
Cost & Logistics Intelligence
Global whey protein commodity benchmarks cascade through GCC supply chains into three distinct pricing strata. European and North American dairy price volatility transmits directly to isolate and concentrate production costs, compressing margin buffers for import-dependent distributors while rewarding certified manufacturers with pharmacy channel access.
Pricing Analysis
Capacity additions in UAE pharmaceutical manufacturing are reshaping price floors for compliant formulations. Three-tier pricing structure across premium clinical-grade, standard certified, and economy unbranded levels stratifies the market. SFDA and MOHAP registration investments drive premium tier pricing power, while direct-to-consumer subscription models undercut traditional import markups in the standard tier. Pricing pressure stems from whey protein input volatility and currency fluctuation exposure. Bodybuilders and recreational users exhibit highest price sensitivity; professional athletes and hospital procurement committees demonstrate lowest.
Supply Chain Analysis
Direct-to-consumer channels handle digitally native fitness enthusiast demand through platform-native subscription mechanics. European and North American suppliers dominate premium whey isolate and concentrate feedstocks. Raw material dependencies center on dairy-derived proteins, fermentation-derived biotech alternatives, and aseptic packaging materials. Single-source vulnerability concentrates in European whey protein concentrate supply routes through Rotterdam and Hamburg logistics hubs. Distribution runs through Dubai's Jebel Ali port complex for Gulf-wide redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC sports nutrition functions as a stable compounder anchored by recurring protein powder consumption patterns among Riyadh-Jeddah fitness center members. Regulatory compliance investments create durable competitive moats that sustain incumbent positioning.
For Market Incumbents: Deploy halal certification advance-rulings for fermentation-derived proteins to preempt biotech protein entry. Secure exclusive pharmacy chain placements through MOHAP registration maintenance. Counter direct-to-consumer pricing pressure by emphasizing batch-level traceability and WADA-aligned banned-substance screening that platform-native competitors cannot replicate. For New Entrants and Emerging Players: Capture the clinical recovery segment expansion for post-surgical and rehabilitation patients that Abbott Nutrition currently dominates with hospital-endorsed formulations. Target subscription platform mechanics with automated replenishment for Saudi consumers aged 18-34 in Riyadh's metropolitan district. Leverage TikTok-driven discovery to bypass established retail intermediary networks. For Investors and Strategic Acquirers: Asymmetric upside sits with certified manufacturers possessing existing SFDA and MOHAP registrations amid tightening compliance standards. Five-to-ten year viability favors clinical-grade formulators with hospital channel access over commodity importers exposed to dairy price volatility. Monitor biotech protein halal certification rulings from regional Islamic authorities as inflection indicator for fermentation-derived ingredient adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Advance-Rulings | First-mover positioning for fermentation-derived proteins secures religious authority approval before competitor entry. |
| Subscription Platform Buildout | Automated replenishment mechanics capture lifetime value pools previously fragmented across Dubai and Abu Dhabi retail intermediaries. |
| Clinical Recovery Segment Entry | Hospital-endorsed formulations for post-surgical patients unlock premium pricing unavailable in athletic performance positioning. |
| Blockchain Batch Tracking Integration | UAE pharmacy network adoption of origin-verification apps eliminates information asymmetry protecting lower-grade competitors. |
| SFDA Registration Harmonization Exploitation | Streamlined Saudi approval pathways accelerate Gulf expansion for compliant international brands ahead of regulatory backlog. |
Research Approach
Multiple input streams — primary interviews with sports nutrition formulators, regulatory affairs specialists at SFDA and MOHAP, fitness center procurement managers, and hospital pharmacy directors; secondary validation through customs import records, Gulf Standardization Organization harmonization documents, and WADA banned-substance screening protocols — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end user archetype, distribution channel, and packaging format dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating fitness center density metrics, disposable income clustering, and regulatory approval timeline assumptions.
Underlying measurement precision varies by segment; protein powders and ready-to-drink beverages carry tighter precision than energy bars and supplements due to established trade flow documentation. Forecasts reflect assumptions around SFDA harmonization pace, biotech protein halal certification timelines, and subscription platform adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Creatine Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
United States Sports Drink Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Caloric Supplements Market