
 Sports Supplement Market | 2026-2036
Sports Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Supplement Market Analysis
FDA enforcement of New Dietary Ingredient notifications is pivoting the cost-of-entry calculus for smaller brands seeking shelf space. Glanbia plc leverages its vertically integrated dairy protein supply chain to sustain margin pressure from compliance investments. PepsiCo anchors its position through mass-channel distribution density that navigates retailer certification demands. Abbott differentiates via clinical validation protocols that exceed baseline regulatory thresholds.
Sports supplements comprise formulated ingestible products containing bioactive compounds—protein isolates, branched-chain amino acids, micronutrient complexes, and ergogenic substrates—manufactured through spray-drying, microencapsulation, or cold-pressed bar formation to deliver targeted physiological support for muscular recovery, energy metabolism, or cognitive performance. Protein Powders occupy the largest revenue pool given established consumption rituals among resistance-trained populations, while Energy Bars represent the fastest-expanding form factor as convenience-oriented fitness enthusiasts seek portable macronutrient delivery. The Capsule segment leads in precision-dosing applications where bioavailability enhancement technologies command premium positioning.
US FDA cGMP inspections, NSF Certified for Sport protocols, and Informed Sport accreditation collectively determine market access eligibility for products targeting collegiate and professional athletic programs. The EU's EFSA health claims framework and novel food assessments impose additional substantiation burdens for brands seeking cross-border expansion. Stakeholders must monitor evolving enforcement patterns around synthetic stimulant analogues and adapt quality systems accordingly.
Market Dynamics
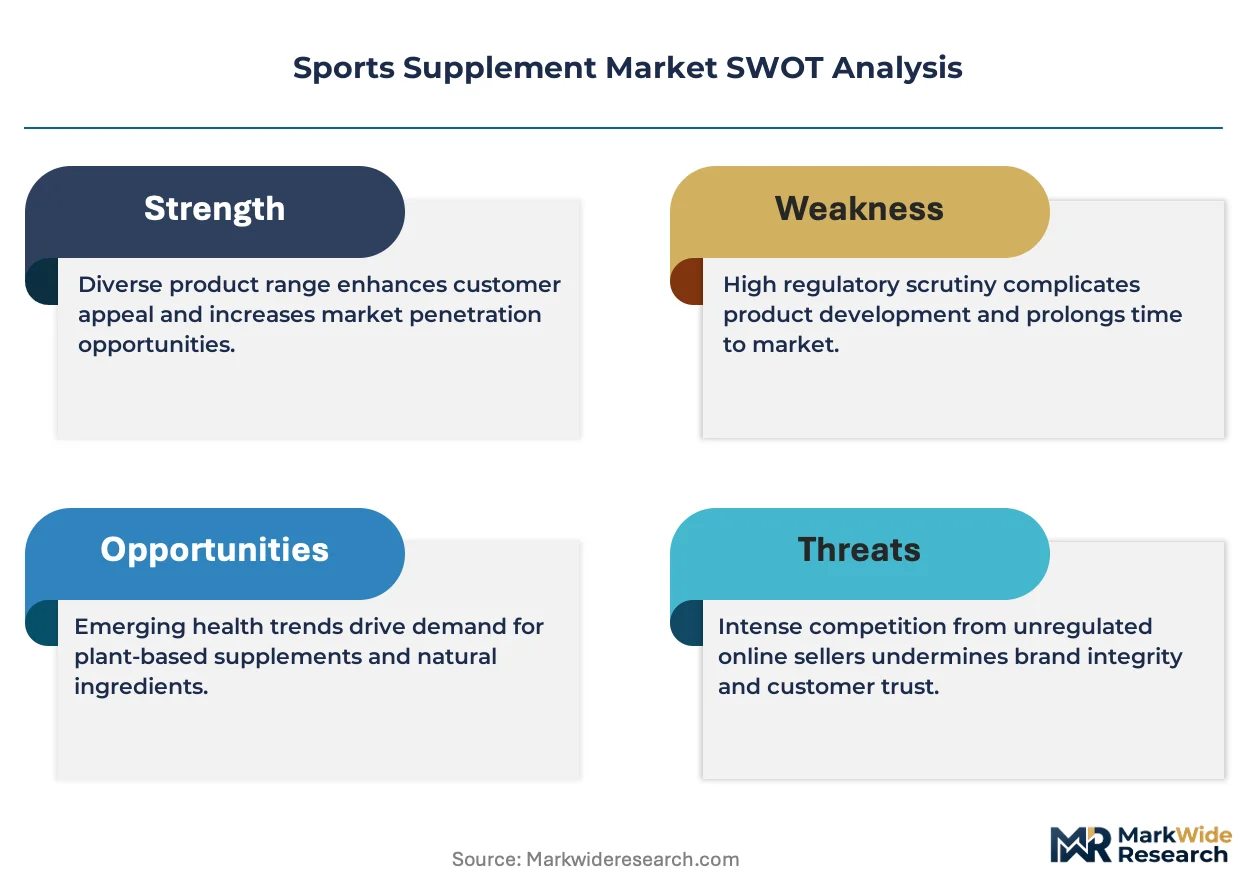
FDA's New Dietary Ingredient notification requirements are recalibrating compliance costs, forcing smaller brands to consolidate or exit while vertically integrated dairy processors absorb margin pressure through captive supply chains.
Growth Catalysts
- Institutional Sports Science:Collegiate and professional athletic programs now mandate nutrition protocols, creating procurement pull for NSF Certified for Sport and Informed Sport accredited products.
- EFSA Health Claims Framework:European brands that successfully navigate novel food assessments gain cross-border expansion rights into adjacent markets with harmonized standards.
- Microencapsulation Technology:Bioavailability enhancement through lipid-shell delivery systems commands premium positioning in precision-dosing applications, expanding addressable spend per user.
Market Restraints
- Whey Protein Concentrate Volatility:Dairy commodity price swings transmit directly to formulated product margins, squeezing brands without backward integration into milk processing.
- Chinese Ingredient Concentration:Bulk amino acid and botanical extract supply clusters in Shandong and Jiangsu provinces, exposing formulators to geopolitical friction and shipping disruption.
- Synthetic Stimulant Analogue Bans:FDA enforcement actions against undisclosed DMAA and DMHA variants force reformulation cycles that burn R&D runway.
Strategic Opportunities
- India's Fitness Penetration:Urban gym density in Mumbai, Delhi, and Bangalore is accelerating protein powder adoption among first-time resistance-trained consumers.
- Subscription Direct-to-Consumer Models:Replacing retail slotting fees with recurring revenue streams bypasses retailer certification demands and captures lifetime value.
- Plant Protein Convergence:Pea-rice protein blending with enzymatic texture modification is closing the sensory gap with dairy isolates, opening vegan-adjacent segments.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Validating label claims against banned substance lists requires mass spectrometry expertise that outpaces supply in contract lab markets.
- NSF Certified for Sport Timeline Compression:The 12-16 week accreditation window delays product launches and ties working capital in inventory hold.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Supplement Market |
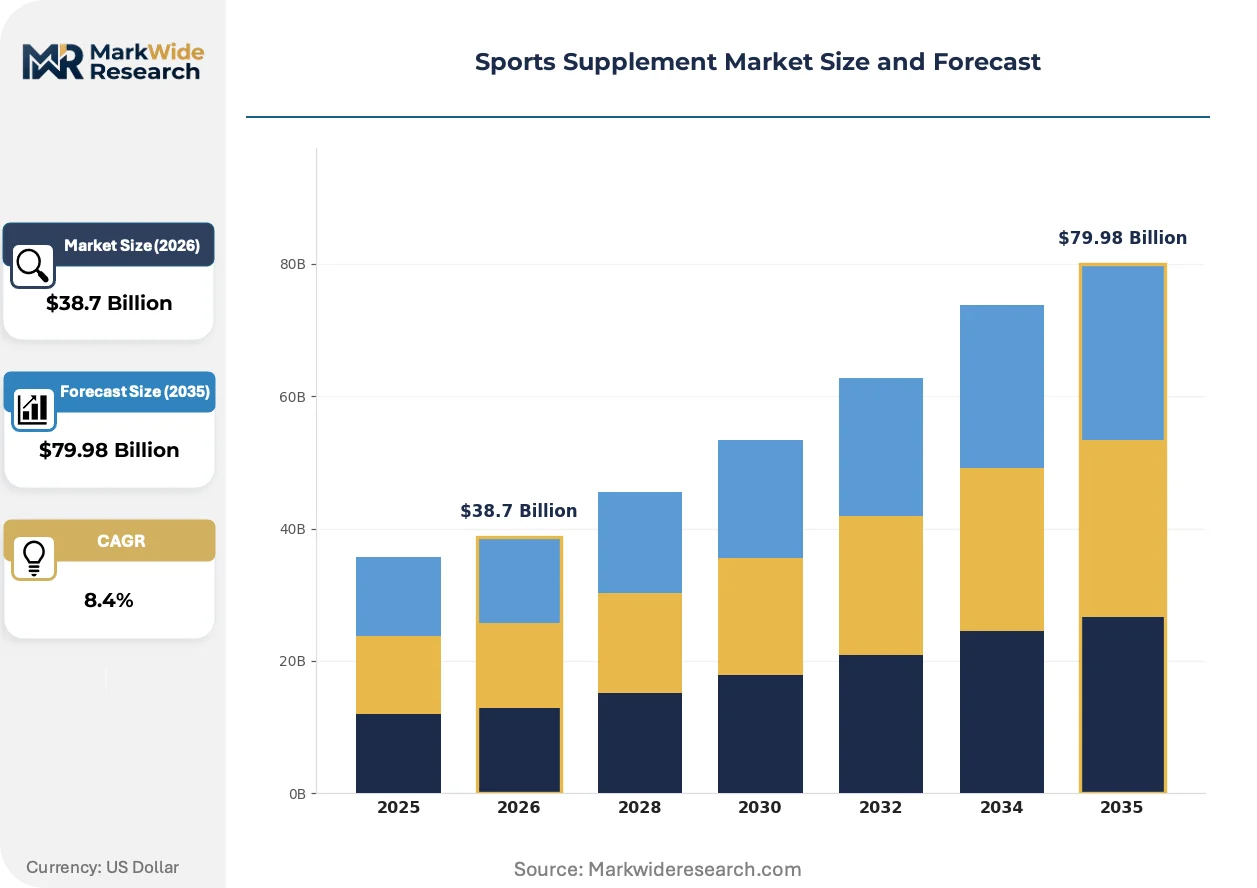
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Amino Acids, Vitamins, Energy Bars End User: Athletes, Fitness Enthusiasts, Bodybuilders, Recreational Users Form: Powder, Liquid, Capsule, Chewable Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gyms |
| Companies Covered | Glanbia plc, Abbott, PepsiCo, The Coca-Cola Company, Herbalife International, GNC Holdings, Quest Nutrition, Post Holdings, Clif Bar & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Supplement Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how bioactive compounds reach end-users, with transparency and personalization displacing mass-market opacity.
Personalized nutrition platforms leveraging at-home microbiome testing and blood biomarker analysis are decentralizing product selection away from generic protein SKUs toward algorithm-matched micronutrient stacks. Functional medicine practitioners and elite training facilities are adopting these tools fastest, compressing the traditional retail intermediary layer. This shift is decentralizing brand discovery toward digital-native entrants with data-science capabilities rather than shelf-space dominance.
The EU's CSRD sustainability disclosure requirements are mandating supply chain carbon accounting for imported protein isolates and botanical extracts. Formulators sourcing Brazilian açaí or New Zealand whey must now document farm-level emissions or face exclusion from institutional procurement channels. European premium brands are responding by anchoring supplier contracts to regenerative agriculture certifications that exceed baseline compliance.
Certification-driven purchasing now governs collegiate athletic department procurement, where banned-substance liability has compressed vendor lists to NSF and Informed Sport accredited suppliers exclusively. Digital marketplaces aggregating these pre-vetted products are displacing traditional brick-and-mortar nutrition stores on university campuses. This concentration is most visible across NCAA Division I programs in the United States, where compliance officers now hold veto power over sports nutrition procurement.
Sports Supplement Market Segmentation
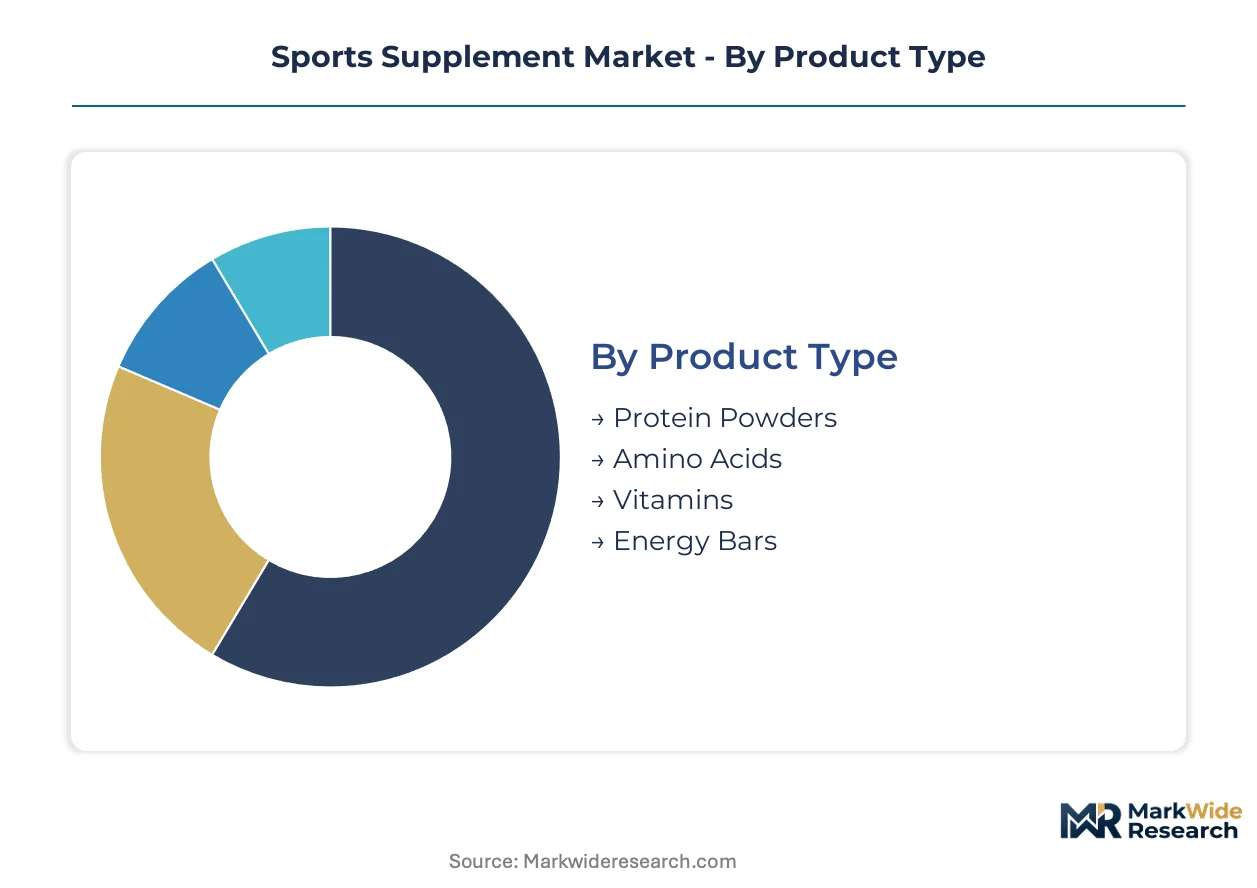
Sports supplement segmentation reveals how formulation science and consumption rituals fragment demand across distinct user profiles and purchase contexts. Each category exposes different margin structures, certification requirements, and channel access rules that determine competitive viability.
Product Type:
Customization versus standardization tensions manifest most acutely in this category, where precision-dosing formulations command premium positioning against commodity protein SKUs.
- Protein Powders:Spray-dried and cold-processed isolates from whey, casein, or blended plant sources deliver complete amino acid profiles for post-workout recovery. Demand concentrates among resistance-trained populations in the United States, where established consumption rituals and gym culture sustain volume leadership despite dairy commodity price volatility.
- Energy Bars:Cold-pressed or extruded formulations combining protein isolates with carbohydrate substrates and micronutrient fortification enable portable macronutrient delivery. Fitness enthusiasts in urban India and Southeast Asia are adopting these fastest as convenience-oriented nutrition replaces sit-down meals.
- Amino Acids:Free-form branched-chain and essential amino acid powders target intra-workout oxidation prevention and muscle protein synthesis signaling.
- Vitamins:Micronutrient complexes address deficiency correction and metabolic cofactor support for high-training-load athletes.
Leading the category by volume: Protein Powders. Growing fastest: Energy Bars.
End User:
Application intensity separates casual consumers from performance-optimized protocols, with institutional procurement creating divergent compliance thresholds.
- Athletes:Collegiate and professional competitors operating under NSF Certified for Sport or Informed Sport mandates require batch-tested, banned-substance-free formulations. Procurement concentrates through athletic department nutrition staff and team dietitians, with compliance officers holding veto authority over vendor selection.
- Bodybuilders:High-frequency resistance trainers prioritize leucine-rich protein dosing and peri-workout nutrient timing to maximize hypertrophy stimuli. This segment absorbs premium pricing for bioavailability-enhanced delivery systems and specialized ergogenic substrates.
- Fitness Enthusiasts:Regular gym attendees seeking general health and aesthetic outcomes drive mass-market volume through retail and direct-to-consumer channels.
- Recreational Users:Occasional exercisers and wellness-oriented consumers purchasing sporadically based on promotional activity and brand familiarity.
Dominant by procurement value: Athletes. Expanding most quickly: Fitness Enthusiasts.
Form:
Manufacturing capital requirements and sensory engineering investments stratify margin capture across delivery modalities.
- Powder:Bulk dry blending and flavor masking technologies enable the lowest per-serving manufacturing cost and highest dose flexibility. Powder dominates home-use consumption in North America and Europe where shaker bottle rituals are culturally embedded.
- Capsule:Hard-shell gelatin or vegetable-derived encapsulation with microencapsulated actives enables precision dosing and taste masking for bioactive compounds with poor palatability. Clinical validation protocols and pharmaceutical-grade manufacturing attract premium positioning.
- Liquid:Ready-to-drink formulations requiring aseptic processing and extended shelf-life stabilization command higher logistics costs but capture on-the-go consumption occasions.
- Chewable:Confectionery-processed delivery systems with texture-modified protein matrices target entry-level users and those averse to swallowing pills.
Highest volume: Powder. Steepest expansion trajectory: Capsule.
Distribution Channel:
Channel selection determines certification burden, working capital intensity, and customer data access for personalization engines.
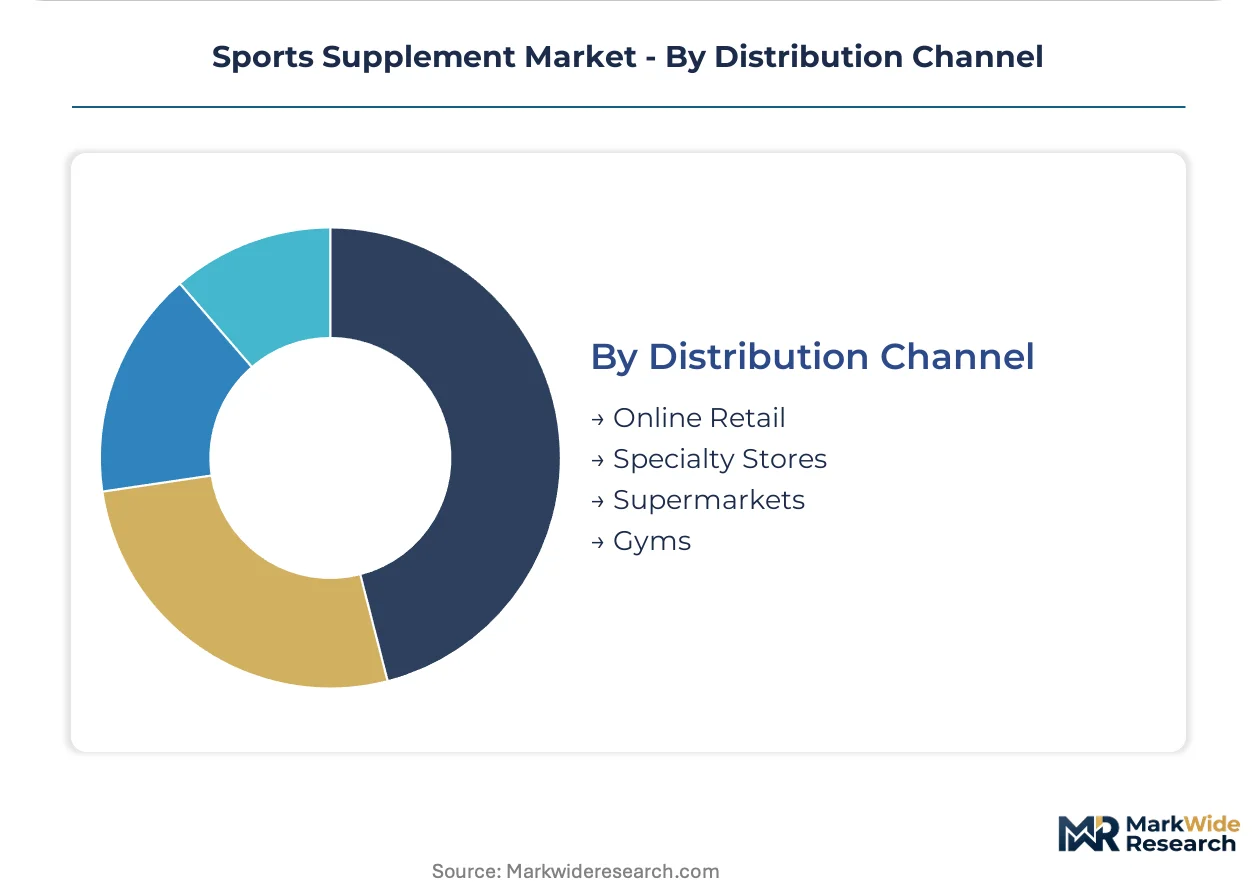
- Online Retail:Direct-to-consumer and marketplace platforms bypass retailer slotting fees and capture subscription recurring revenue. First-party data enables algorithm-matched product recommendations, with digital-native brands leveraging this for microbiome-informed personalization.
- Specialty Stores:Dedicated sports nutrition retailers with educated floor staff provide trial access and immediate fulfillment, though shelf space consolidation is compressing independent operators.
- Supermarkets:Mass-market retail placement requires trade spend investment and simplified SKU portfolios, favoring brands with PepsiCo-scale distribution density.
- Gyms:Point-of-workout vending and pro-shop placement captures impulse consumption with minimal price sensitivity, though revenue concentrates in premium club chains.
Largest transaction volume: Online Retail. Gaining share fastest: Gyms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zone incentives in Jebel Ali and Dubai South are concentrating Middle East distribution hubs for sports supplement re-export into African and South Asian markets.
United States
Fitness culture penetration and collegiate athletic procurement drive demand concentration. FDA cGMP inspections and NSF Certified for Sport protocols govern market access eligibility. Manufacturing clusters in Utah and California process dairy isolates and plant proteins for domestic consumption and export.
Germany
EFSA health claims substantiation requirements filter market entrants while regenerative agriculture certifications gain procurement priority. The EU's CSRD sustainability disclosure mandates now apply to imported protein isolates. Industrial activity concentrates in Bavaria and North Rhine-Westphalia where contract manufacturers serve Central European brands.
China
Urban gym density in Shanghai and Beijing accelerates protein powder adoption among first-time resistance-trained consumers. NMPA novel food assessments and GB standards regulate ingredient safety and labeling. Bulk amino acid production clusters in Shandong and Jiangsu provinces supply domestic formulators and export markets.
India
FSSAI compliance requirements and rising disposable incomes in metropolitan areas expand addressable consumer base. The PLI scheme for food processing incentivizes domestic manufacturing capacity. Mumbai, Delhi, and Bangalore anchor consumption growth as organized fitness penetration deepens.
Brazil
ANVISA pharmaceutical-grade manufacturing standards create compliance thresholds for precision-dosing formulations. São Paulo and Rio de Janeiro concentrate demand from bodybuilding and fitness enthusiast segments. Regional brands leverage local whey processing to offset import dependency.
Sports Supplement Market Vendor Landscape
United States producers anchor one tier; European specialists hold premium positioning through certification density. The vendor base stratifies across three tiers: multinational food conglomerates with mass-channel distribution, vertically integrated dairy processors with captive protein supply, and digital-native direct-to-consumer brands with data-science capabilities. Consolidation pressure intensifies as FDA New Dietary Ingredient compliance costs force smaller brands toward exit or acquisition. Dominant competitive moves include backward integration into milk processing and subscription model deployment to bypass retailer certification demands.
Within the conglomerate tier, PepsiCo and The Coca-Cola Company exemplify scale-driven distribution density that navigates retailer certification requirements. Glanbia plc occupies a position representing vertically integrated dairy processors absorbing margin pressure through captive whey supply chains. Abbott sits within the clinical validation archetype where pharmaceutical-grade manufacturing protocols exceed baseline regulatory thresholds.
| Leading Market Players |
|---|
| Glanbia plc |
| Abbott |
| PepsiCo |
| The Coca-Cola Company |
| Herbalife International |
| GNC Holdings |
| Quest Nutrition |
| Post Holdings |
| Clif Bar & Company |
| Others |
Supply Flow & Price Mechanics
Mass spectrometry expertise scarcity in North American contract labs widens pricing spreads between NSF Certified for Sport formulations and uncertified commodity powders. Labor-cost differentials between accredited analytical chemists and standard quality technicians translate directly into three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Short lead-time premiums for NSF Certified for Sport accreditation compress margins for brands launching collegiate athletic programs. Subscription direct-to-consumer models anchor the dominant pricing structure, with certification level and volume scale driving price differentiation. Pricing pressure stems from whey protein concentrate commodity volatility transmitting through formulated product margins. Fitness enthusiasts exhibit highest price sensitivity through retail channels, while institutional athletic procurement shows minimal elasticity given liability compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements for banned-substance-free raw materials now govern procurement protocols at tier-one formulators. Bulk amino acid supply concentrates in China, India, and Germany, with botanical extract dependencies drawing from Brazilian açaí regions and New Zealand dairy processing clusters. Single-source vulnerability in Shandong province amino acid production exposes formulators to geopolitical friction. Distribution runs through Jebel Ali Free Trade Zone hubs for Middle East re-export into African and South Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry talent scarcity constrains batch-testing capacity, propping pricing premiums for NSF Certified for Sport products through the projection horizon.
For Market Incumbents: To counter synthetic stimulant analogue enforcement actions forcing reformulation cycles, Glanbia plc and Abbott should deepen backward integration into regenerative agriculture-certified dairy supply and accelerate captive mass spectrometry lab capacity in Utah manufacturing clusters. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to institutional procurement bypass, targeting urban India protein powder penetration in Mumbai and Bangalore where organized gym density accelerates first-time resistance-trained consumer acquisition through microbiome-informed personalization engines. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated dairy processors given FDA New Dietary Ingredient compliance cost recalibration forcing smaller brand consolidation. The signal to watch is NSF Certified for Sport accreditation timeline compression easing from current inventory hold constraints.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certified for Sport Accreditation Investment | Banned-substance liability compression at NCAA Division I programs mandates batch-tested procurement protocols exclusively. |
| Backward Integration into Regenerative Agriculture | EU CSRD sustainability disclosure requirements now govern imported protein isolate carbon accounting for institutional channels. |
| Direct-to-Consumer Subscription Launch | Recurring revenue streams bypass retailer slotting fees and capture lifetime value through first-party data personalization. |
| Pea-Rice Protein Blending Capacity | Enzymatic texture modification closes sensory gaps with dairy isolates, opening vegan-adjacent segments in European premium positioning. |
| Microencapsulation Technology Licensing | Lipid-shell delivery systems command premium positioning in precision-dosing applications for clinical validation protocols. |
Methodological Framework
Independent corroboration across supply chain directors at Glanbia plc, quality assurance leads at NSF International, and procurement officers at NCAA Division I athletic departments underwrites the qualitative findings. Primary interviews with contract manufacturing executives, sports dietitians, and regulatory affairs specialists combined with secondary validation from FDA cGMP inspection records, EFSA novel food assessment databases, and FSSAI compliance filings. Bottom-up SKU-level volume aggregation and top-down macroeconomic calibration ensure analytical robustness.
Rate-of-change decomposition across protein powder, energy bar, amino acid, and vitamin segments structured the analytical framework over the projection horizon. Product type, end user archetype, delivery form, and distribution channel dimensions modeled volume trajectories with geographic regulatory cluster overlays. CAGRs derived from historical consumption elasticity coefficients applied to gym density penetration curves and institutional procurement budget forecasts, with whey commodity price scenarios and certification timeline assumptions as sensitivity inputs.
The model holds under stable FDA enforcement patterns and sustained collegiate athletic nutrition protocol institutionalization; deviation in synthetic stimulant analogue regulatory action intensity or geopolitical disruption to Chinese amino acid supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Sports Nutrition Market