
 B2B Payments Market | 2026-2036
B2B Payments Market Size, Share, and Industry Trends Forecast 2026-2036
B2B Payments Market Intelligence
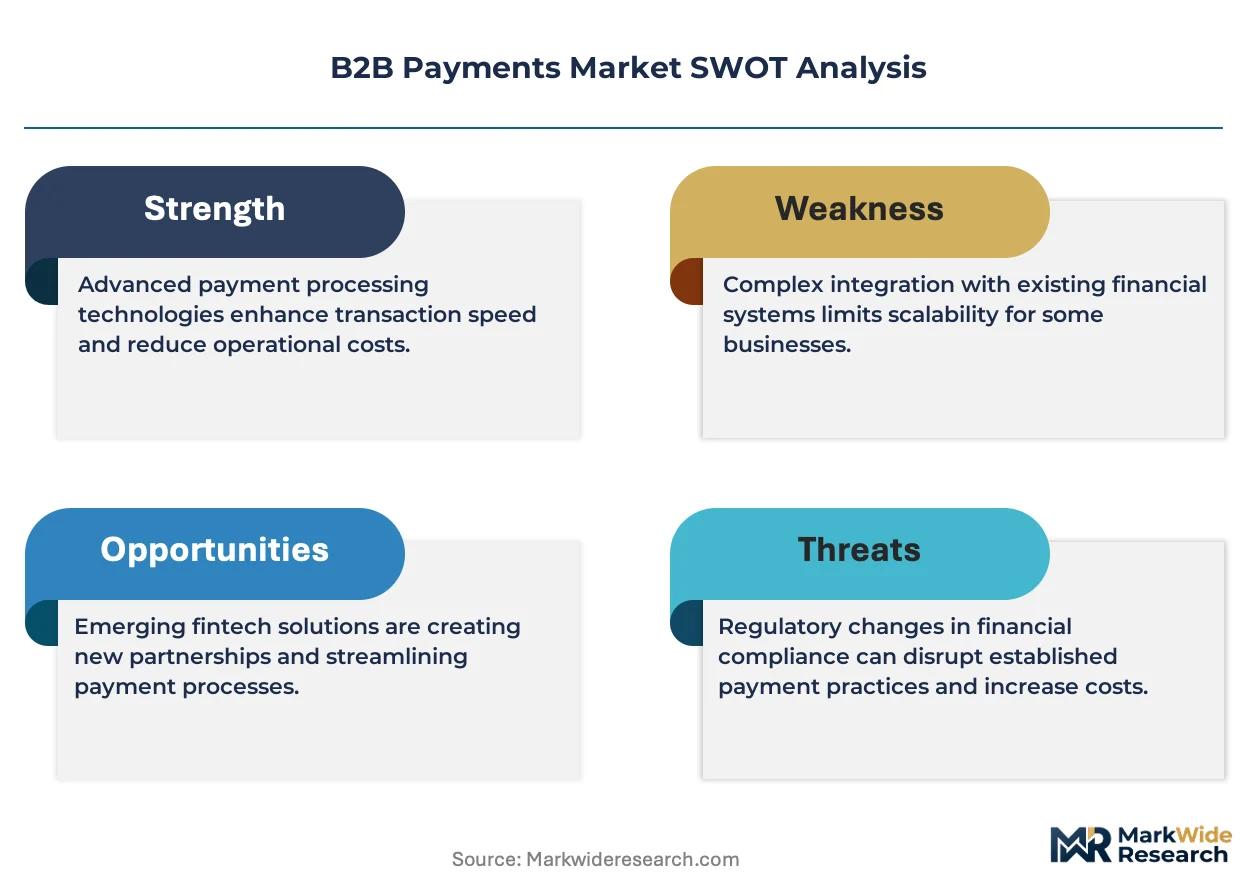
Enterprise-grade security certification is rotating toward the center of procurement decisions in the B2B Payments Market. Mastercard Inc. leverages its tokenization infrastructure to anchor high-value cross-border settlement flows. Stripe Inc. specializes in developer-first API architectures that embed payment rails directly into enterprise resource planning systems. Visa Inc. dominates commercial card networks through its B2B Connect platform, which navigates correspondent banking friction.
B2B payments denote electronic fund transfers between business entities, typically processed through automated clearing house networks, wire systems, or commercial card rails, with settlement cycles ranging from real-time to three business days depending on rail selection and jurisdictional clearing rules. These systems serve the primary commercial purpose of replacing paper-based invoice reconciliation with digitized, auditable transaction workflows that reduce days sales outstanding and optimize working capital. ACH transfers and wire transfers retain the largest transaction value share, though digital wallets are recording the fastest adoption velocity among small and medium transaction sizes. Manufacturing and professional services verticals generate the deepest margin pools for platform providers due to high invoice frequency and complex multi-entity reconciliation requirements.
The Federal Reserve's FedNow instant payment service, the European Union's PSD2 open banking framework, and the SEC's electronic recordkeeping requirements for broker-dealers collectively shape platform compliance burdens and product roadmaps across jurisdictions. ISO 20022 migration deadlines in the United States and Europe are forcing legacy infrastructure upgrades that favor cloud-native payment orchestration providers over on-premise installations. Stakeholders must monitor central bank digital currency pilot programs and real-time rail expansions as these developments will determine which payment networks capture the next wave of enterprise treasury modernization.
Market Dynamics
Enterprise treasury modernization is compressing settlement cycles from days to seconds, forcing payment infrastructure providers to rebuild core architectures around real-time clearing rails rather than batch-processing legacy systems.
Growth Catalysts
- FedNow instant payment service:The Federal Reserve's real-time rail is mandating ISO 20022 message formats that accelerate interoperability adoption across US correspondent banking networks.
- Manufacturing invoice digitization:High-frequency B2B transactions in industrial supply chains are displacing paper-based reconciliation with automated payment workflows that reduce days sales outstanding.
- Cloud-native orchestration platforms:API-first architectures are embedding payment rails directly into enterprise resource planning systems, eliminating manual intervention in treasury operations.
Market Restraints
- Legacy core banking infrastructure:On-premise mainframe systems at tier-one banks require multi-year migration timelines that delay real-time rail connectivity for corporate clients.
- Cross-border correspondent banking concentration:High-value settlement flows depend on a shrinking pool of global systemically important banks, creating single-point-of-failure risk in dollar clearing.
- Commercial interchange rate compression:Regulatory pressure on card network pricing is squeezing margin pools that historically subsidized B2B platform investments.
Strategic Opportunities
- Central bank digital currency pilots:Wholesale CBDC programs in Singapore and Hong Kong are testing programmable settlement that could eliminate correspondent banking friction for cross-border trade.
- Embedded finance in vertical SaaS:Industry-specific software platforms for construction and logistics are white-labeling payment orchestration to capture treasury services revenue.
- Open banking API monetization:PSD2 framework compliance in Europe is creating data-sharing obligations that fintechs are converting into cash flow forecasting products for SMEs.
Industry Challenges
- Cybersecurity certification complexity:PCI DSS Level 1 compliance for high-volume merchants demands 12-month audit cycles that delay product launches and inflate compliance headcount.
- ISO 20022 migration fragmentation:Inconsistent implementation timelines across US, European, and Asian clearing systems are forcing payment service providers to maintain multiple message format stacks.
- Treasury talent scarcity:Enterprise demand for professionals fluent in both legacy SWIFT messaging and modern API architectures is outstripping supply in major financial centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B Payments Market |
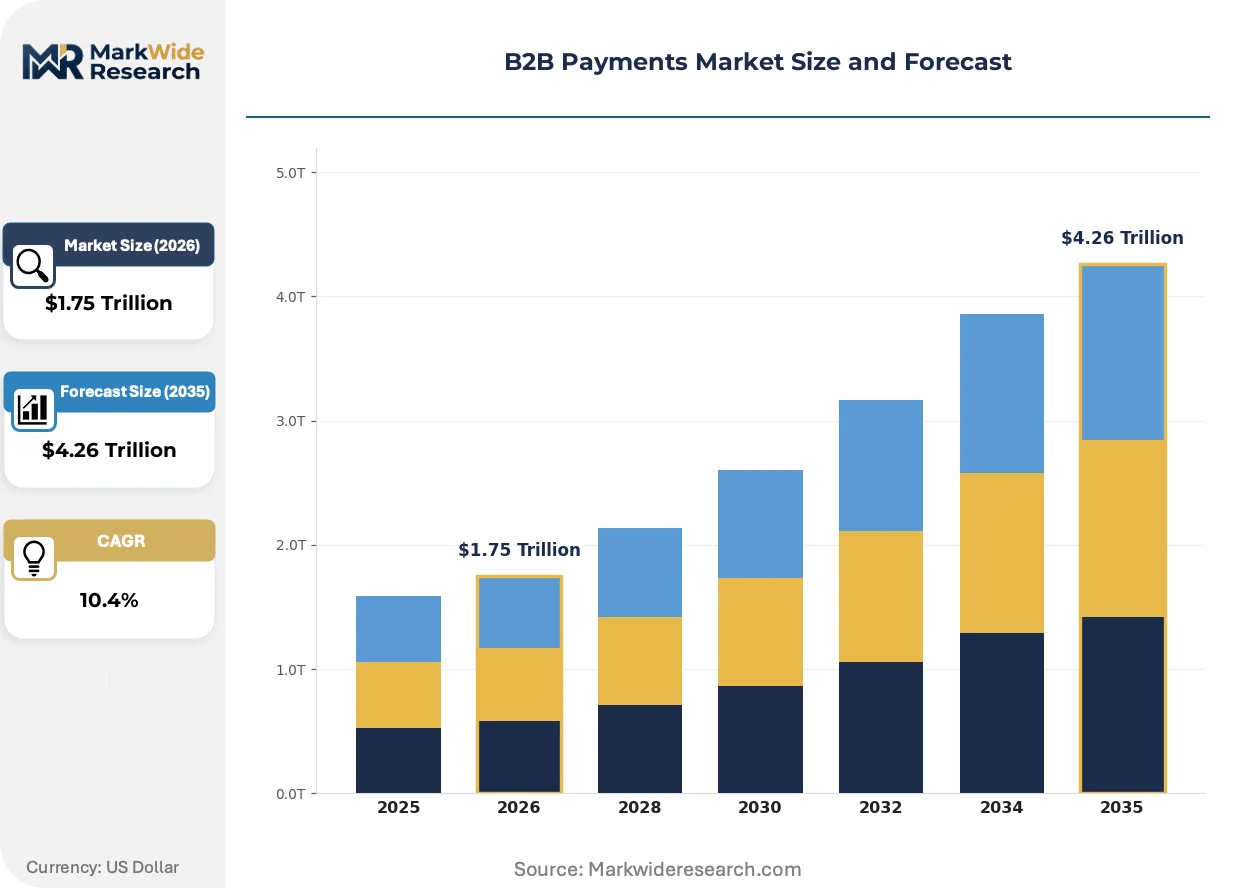
| Market Size in 2026 | $1.75 Trillion |
| Market Size in 2035 | $4.26 Trillion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: ACH Transfers, Wire Transfers, Credit Cards, Digital Wallets Industry Vertical: Manufacturing, Healthcare, Retail, Professional Services Transaction Size: Small, Medium, Large, Enterprise Billing Model: Subscription, Pay-Per-Use, Invoice, Retainer |
| Companies Covered | Stripe Inc., Mastercard Inc., Visa Inc., American Express Company, PayPal Holdings Inc., FIS, Adyen, Airwallex, Bill.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B Payments Market Strategic Shifts & Innovations
Payment infrastructure is fragmenting into modular, API-composable layers that let enterprises assemble custom treasury stacks rather than accepting monolithic bank-provided platforms.
Payment orchestration software is decomposing the traditional acquiring stack into discrete microservices for routing, fraud detection, and reconciliation. Mid-market enterprises are adopting these modular platforms fastest, building bespoke payment flows that optimize for cost in low-value transactions and speed in high-priority settlements. This decomposition is compressing vendor switching costs and eroding the lock-in that historically protected incumbent bank relationships.
PSD2's Strong Customer Authentication mandates are forcing European payment service providers to rebuild authentication flows around biometric verification and dynamic linking. The regulation's industrial consequence is a surge in delegated authentication partnerships between banks and specialized identity providers. Merchant acquirers in Germany and France are most affected, accelerating investment in 3D Secure 2.0 infrastructure to avoid transaction abandonment.
Treasury departments are unbundling payment execution from relationship banking, selecting optimal rails for each transaction type rather than defaulting to primary bank channels. This behavior shift is disrupting the traditional cash management sales model and elevating payment aggregators that offer multi-rail visibility. The pattern is most visible in US professional services and technology sectors, where finance teams maintain active connections to five or more payment providers.
B2B Payments Market Segmentation
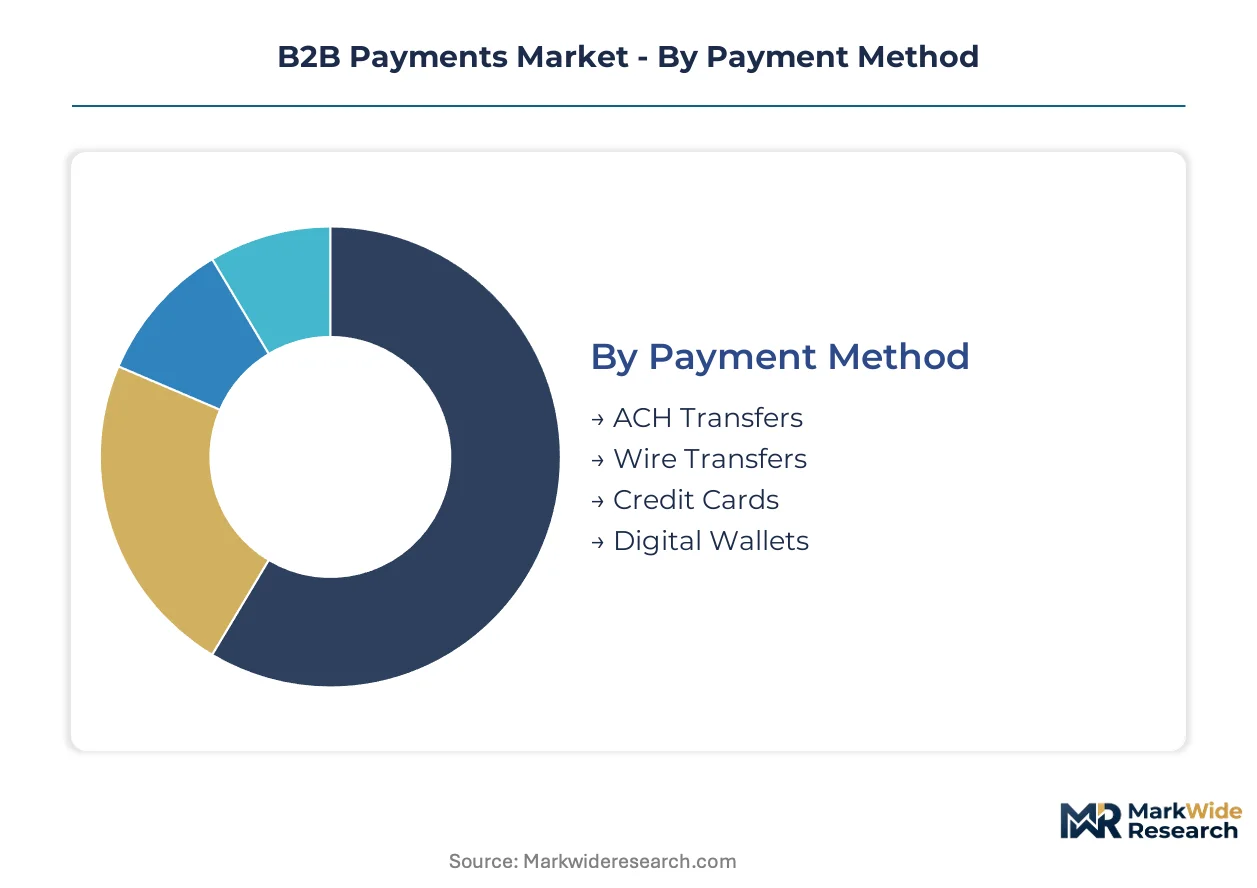
Payment method selection determines clearing rail access, settlement velocity, and compliance burden for enterprise treasury departments. Industry vertical shapes invoice frequency, reconciliation complexity, and fraud risk profiles. Transaction size and billing model together dictate platform economics and working capital optimization strategies.
Payment Method:
ACH transfers dominate domestic US settlement flows, while wire transfers anchor high-value cross-border corridors. Digital wallets concentrate in emerging market corridors where correspondent banking access remains fragmented.
- ACH Transfers:Batch-processed electronic debits and credits routed through Federal Reserve and The Clearing House networks, settling in one to two business days. Manufacturing supply chains in the US Midwest leverage ACH for high-frequency supplier payments where speed is secondary to cost efficiency.
- Wire Transfers:Real-time gross settlement through Fedwire and CHIPS networks with irrevocable finality. Corporate treasuries in New York and London deploy wires for time-sensitive M&A escrow releases and commodity margin calls where settlement risk is non-negotiable.
- Credit Cards:Commercial card rails with interchange-funded rewards programs and detailed merchant category coding.
- Digital Wallets:Tokenized stored-value accounts accessible via mobile interfaces and API integrations.
ACH transfers command the established base. The steepest expansion runs through digital wallets.
Industry Vertical:
Manufacturing generates the deepest invoice volumes, while professional services drives the highest margin capture for platform providers. Healthcare payment flows face distinct regulatory fragmentation that shapes vendor selection criteria.
- Manufacturing:Complex multi-tier supplier networks with purchase order-matched payment releases and letter-of-credit coordination. Automotive and electronics producers in Germany and Japan prioritize platforms with ISO 20022-native messaging for ERP integration.
- Healthcare:Claims adjudication workflows intersecting HIPAA transaction standards and state-level prompt-pay regulations. US hospital systems demand payment orchestration that reconciles Explanation of Benefit documents against patient responsibility estimates.
- Retail:High-velocity supplier settlements with seasonal working capital swings and chargeback dispute volumes.
- Professional Services:Milestone-based invoicing with retainer drawdowns and time-and-materials reconciliation.
Manufacturing anchors transaction value. Professional services is climbing the fastest as SaaS-embedded finance penetrates legal and consulting workflows.
Transaction Size:
Enterprise transactions concentrate platform revenue, while small-ticket flows drive API integration density and data network effects. Medium-sized payments occupy the most contested competitive terrain.
- Enterprise:Seven-figure settlements requiring multi-bank redundancy, FX hedging integration, and SWIFT gpi tracking. Multinational commodity traders in Singapore and Houston mandate real-time visibility into nostro account positions across correspondent banking relationships.
- Large:Six-figure payments with automated approval workflows and dual-control release protocols.
- Medium:Five-figure transactions where cost optimization and speed tradeoffs vary by vendor.
- Small:Sub-five-figure flows with standardized routing rules and minimal manual intervention.
Enterprise payments deliver the revenue concentration. Small transactions are gaining share fastest through vertical SaaS embedding.
Billing Model:
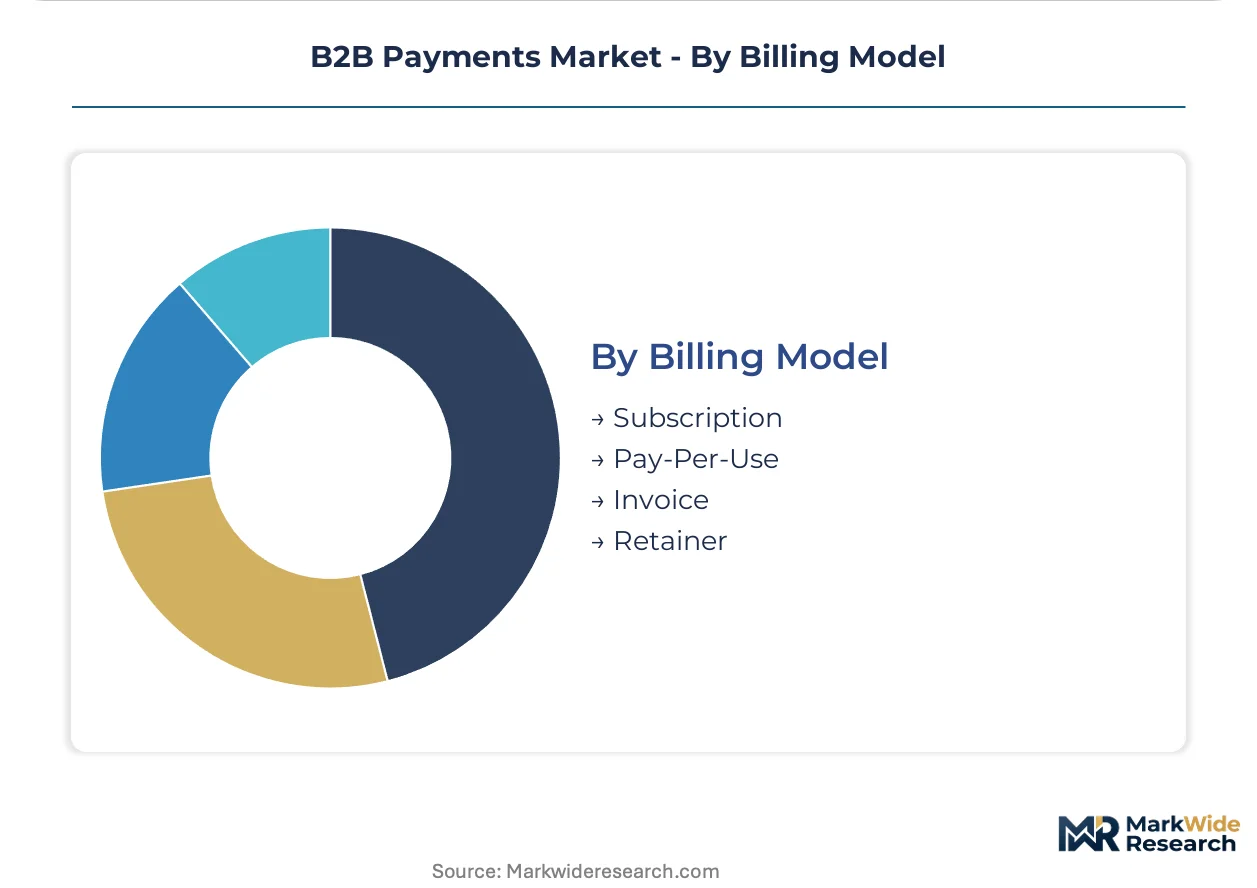
Subscription billing creates predictable cash flow forecasting for platform providers, while pay-per-use aligns revenue with actual transaction consumption. Invoice and retainer models retain entrenched positions in legacy B2B relationships.
- Subscription:Fixed monthly fees for platform access with tiered transaction allowances and overage pricing. US software vendors favor this model for SaaS treasury platforms that bundle payment execution with cash positioning analytics.
- Pay-Per-Use:Per-transaction pricing with volume discounts and rail-specific rate cards.
- Invoice:Post-delivery payment terms with net-30 to net-60 cycles and early-pay discount programs.
- Retainer:Pre-funded engagement deposits with periodic true-up reconciliations.
Invoice billing commands the established base. Subscription models are expanding most quickly as finance teams seek cost predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment concentrates in jurisdictions with active real-time rail deployments and open banking regulatory mandates. Enterprise treasury modernization drives platform differentiation across three dominant corridors where correspondent banking networks and fintech innovation clusters overlap.
United States
The Federal Reserve's FedNow instant payment service and SEC electronic recordkeeping requirements for broker-dealers compress settlement cycles for corporate treasuries. Large corporate payment volumes in New York and San Francisco drive platform investment, with fintech innovation clusters embedding payment rails directly into enterprise resource planning systems.
Germany
Automotive and electronics producers prioritize ISO 20022-native messaging for ERP integration across complex multi-tier supplier networks. The EU's PSD2 open banking framework and Strong Customer Authentication mandates force authentication flow rebuilds around biometric verification. Frankfurt's banking concentration anchors correspondent banking relationships for high-value euro settlement flows.
Singapore
Wholesale central bank digital currency pilots test programmable settlement that could eliminate correspondent banking friction for cross-border trade. The Monetary Authority of Singapore's regulatory sandbox accelerates payment orchestration licensing for API-first platforms. Commodity traders mandate real-time visibility into nostro account positions across correspondent banking relationships.
United Kingdom
London's position in dollar and euro clearing sustains demand for multi-currency treasury platforms with SWIFT gpi tracking. The Financial Conduct Authority's open banking implementation creates data-sharing obligations that fintechs convert into cash flow forecasting products. Professional services firms in the City maintain active connections to five or more payment providers.
Japan
METI's digitalization push and the Bank of Japan's real-time gross settlement infrastructure upgrades accelerate cloud-native payment orchestration adoption. Automotive and electronics supply chains in Nagoya and Osaka demand ISO 20022 messaging for purchase order-matched payment releases. Corporate treasuries prioritize platforms with dual redundancy across domestic and offshore clearing rails.
B2B Payments Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the B2B Payments Market. Incumbent card networks leverage tokenization infrastructure and established correspondent banking relationships to anchor high-value settlement flows. API-native fintechs compete on developer experience and embedded finance integration velocity. Strategic moves concentrate on payment orchestration acquisitions and vertical SaaS partnership programs that embed treasury services into industry-specific workflows.
Within the card network tier, Mastercard Inc. and Visa Inc. occupy positions defined by tokenization scale and commercial card network density. Among API-first specialists, Stripe Inc. exemplifies the developer-centric archetype embedding payment rails directly into enterprise software stacks. These three anchors represent divergent competitive vectors: infrastructure depth versus integration velocity versus network effect lock-in.
| Leading Market Players |
|---|
| Stripe Inc. |
| Mastercard Inc. |
| Visa Inc. |
| American Express Company |
| PayPal Holdings Inc. |
| FIS |
| Adyen |
| Airwallex |
| Bill.com |
| Others |
Cost & Logistics Intelligence
Cloud-native orchestration platforms displacing on-premise legacy systems simultaneously redistribute supply geography toward API-first fintech clusters in New York and San Francisco while compressing pricing power for traditional bank-provided treasury stacks that carry higher infrastructure amortization burdens.
Pricing Analysis
PSD2 and FedNow ISO 20022 mandates dictate the pricing tier structure across the B2B payments landscape. Three-tier pricing stratifies across enterprise-grade orchestration with real-time rail access, mid-market SaaS-embedded solutions, and basic ACH batch processing for cost-sensitive buyers. Price differentiation rests on ISO 20022 certification depth and API integration velocity. Cost compression in the mid-market tier is intensifying because vertical SaaS providers are white-labeling payment rails at subscription rates below standalone platform fees. Small and medium enterprises exhibit the highest price sensitivity, while multinational commodity traders prioritize settlement finality over per-transaction economics.
Supply Chain Analysis
Inventory-light software architectures and zero marginal cost replication compress traditional lead-time constraints in payment infrastructure delivery. Supply concentrates in the United States, Germany, and Singapore where FedNow deployment, PSD2 enforcement, and MAS regulatory sandbox programs respectively anchor platform development. Core dependencies include cloud compute capacity from hyperscale providers, tokenization security modules, and SWIFT network access agreements. Single-source vulnerability runs through concentrated correspondent banking relationships for dollar clearing. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and vertical SaaS embedding channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of treasury professionals fluent in both legacy SWIFT messaging and modern API architectures constrains platform deployment velocity and inflates implementation costs for enterprise clients.
For Market Incumbents: Secure ISO 20022-native certification ahead of migration deadlines to defend against cloud-native entrants capturing ERP-embedded payment flows. Prioritize backward integration into tokenization infrastructure to reduce third-party security module dependencies that compress margins. Channel control through systems integrator exclusivity agreements protects against vertical SaaS disintermediation. For New Entrants and Emerging Players: Differentiate on real-time rail orchestration for mid-market manufacturing supply chains where invoice digitization lags behind professional services adoption. Target construction and logistics verticals with milestone-based payment workflows that incumbent banks serve poorly through legacy cash management products. Embed through industry-specific software partnerships rather than direct treasury sales cycles. For Investors and Strategic Acquirers: The market sits at an infrastructure consolidation phase that favors payment orchestration platforms with multi-rail connectivity and existing ERP integrations. Long-term viability hinges on capturing data network effects from transaction flow visibility that enables working capital analytics. Acquisition target archetype: API-first specialists with ISO 20022 compliance and vertical SaaS distribution partnerships. The signal to watch is central bank digital currency pilot program expansion that would obsolete correspondent banking-dependent business models.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Acceleration | FedNow and European deadlines force legacy infrastructure replacement favoring cloud-native providers. |
| Vertical SaaS Partnership Program | Construction and logistics platforms white-label treasury services to capture embedded finance revenue. |
| Real-Time Rail Connectivity Expansion | FedNow integration enables instant settlement for manufacturing supply chains reducing days sales outstanding. |
| Tokenization Infrastructure Investment | Mastercard and Visa leverage proprietary security layers to anchor high-value cross-border settlement flows. |
| Central Bank Digital Currency Readiness | Singapore and Hong Kong wholesale pilots test programmable settlement eliminating correspondent banking friction. |
Research Approach
The analysis maps payment method segments, industry verticals, transaction size tiers, and billing models, each validated through corporate treasury directors, payment platform product managers, ERP integration specialists, and commercial banking relationship managers. Primary interview insights triangulate against SEC filings of publicly traded payment networks, Federal Reserve payment system statistics, European Banking Authority open banking implementation reports, and SWIFT gpi transaction data. Bottom-up sizing of transaction volumes and top-down validation against central bank clearing statistics ensure consistency across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models payment method adoption curves, industry vertical penetration rates, transaction size distribution shifts, and regional regulatory implementation timelines. CAGRs derive from trend extrapolation of real-time rail deployment schedules and enterprise treasury modernization cycles. Industry-specific inputs include FedNow adoption velocity, PSD2 Strong Customer Authentication compliance rates, and ISO 20022 migration progress by clearing system.
Decision-makers should treat outputs as directional under assumptions of continued regulatory pressure for open banking and real-time settlement; material deviation in central bank digital currency deployment timelines or correspondent banking consolidation patterns would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Payment Gateway Market
Payments
Canada Buy Now Pay Later Market
Payments
India Payments Market
Payments
Indonesia Mobile Payments Market
Payments
GCC Mobile Payment Market
Payments
Germany POS Terminal Market
Payments
Fuel Cards Market
Payments
APAC Mobile Payments Market
Payments
Face-Swiping Payment Market
Payments
India Forex Cards Market
Payments
Sweden Payments Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Remittance Market
Payments
South Korea Digital Payments Market
Payments
Cash Management System Market
Payments
North America Payment Gateway Market