
 Singapore Neobanking Market | 2026-2036
Singapore Neobanking Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Neobanking Market Analytics
Subscription-based cash management is decoupling traditional relationship banking from balance-sheet dependency in Singapore. GXS Bank leverages its ecosystem integration to anchor retail deposit flows. Aspire Financial Technologies Pte. Ltd. specializes in SME credit facilities with automated underwriting. Nium Pte. Ltd. navigates cross-border payment rails to extend its regional footprint beyond Singapore.
A neobank is a digital-native financial institution operating without physical branch infrastructure, delivering account services, lending, and payment solutions through mobile-first interfaces with real-time API connectivity to core banking systems. Its primary commercial purpose is reducing customer acquisition costs and operational overhead while expanding financial access to underserved segments. Account services and payment solutions dominate transaction volume, though lending solutions command the deepest margin pools due to risk-based pricing granularity. Artificial intelligence and mobile apps represent the fastest-expanding technology layer, displacing legacy rule-based underwriting with behavioral scoring models.
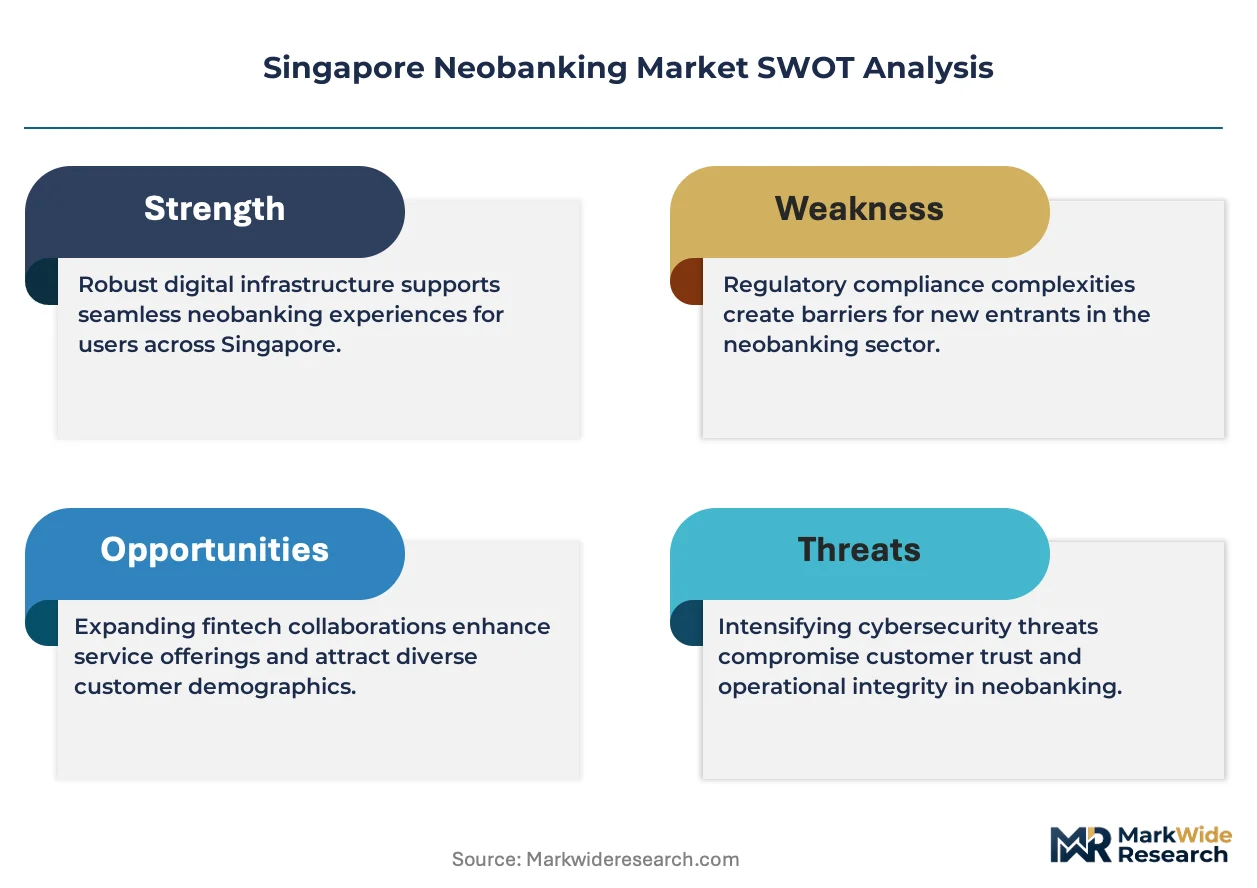
Monetary Authority of Singapore (MAS) digital banking licenses determine market entry standards and capital adequacy thresholds for neobank operators. Association of Banks in Singapore (ABS) guidelines on electronic payments shape interoperability requirements and fraud liability frameworks. Stakeholders must monitor how MAS adjusts liquidity rules for non-bank deposit takers as the neobank ecosystem matures beyond its initial licensing phase.
Market Dynamics
MAS digital banking licenses have restructured competitive entry barriers, forcing deposit-taking neobanks to maintain higher capital buffers than payment-only operators while enabling ecosystem-anchored players to capture customer acquisition economics previously monopolized by incumbent banks.
Growth Catalysts
- Millennial and freelancer payment demand:Mobile-first account services attract digitally native workers seeking real-time cross-border remittance capabilities without branch dependency.
- MAS liquidity framework adjustments:Evolving rules for non-bank deposit takers create regulatory clarity that attracts institutional capital to neobank balance sheets.
- Small business lending automation:API-connected underwriting engines reduce origination costs for SME credit facilities previously underserved by relationship-banking models.
Market Restraints
- Deposit insurance ceiling constraints:MAS-mandated coverage limits cap retail deposit attraction relative to incumbent banks with established trust infrastructure.
- Core banking system vendor concentration:Dependency on a narrow set of cloud-native core providers creates operational resilience risk for licensed operators.
- Cross-border regulatory fragmentation:Divergent licensing requirements across ASEAN markets complicate regional expansion beyond Singapore's jurisdiction.
Strategic Opportunities
- Embedded finance in e-commerce platforms:Neobanks can integrate lending and payment APIs directly into marketplace checkout flows, capturing transaction data for credit scoring.
- Green financing product lines:MAS sustainable finance taxonomy incentives create regulatory tailwind for carbon-linked deposit and lending instruments.
- Wealth-tech convergence:Robo-advisory and fractional investment APIs enable neobanks to expand beyond transactional banking into fee-based asset management.
Industry Challenges
- Behavioral data science talent scarcity:Competitive hiring for machine learning engineers with financial services domain expertise compresses operating margins.
- Legacy bank IT integration complexity:Corporate clients demand seamless connectivity with existing treasury management systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Neobanking Market |
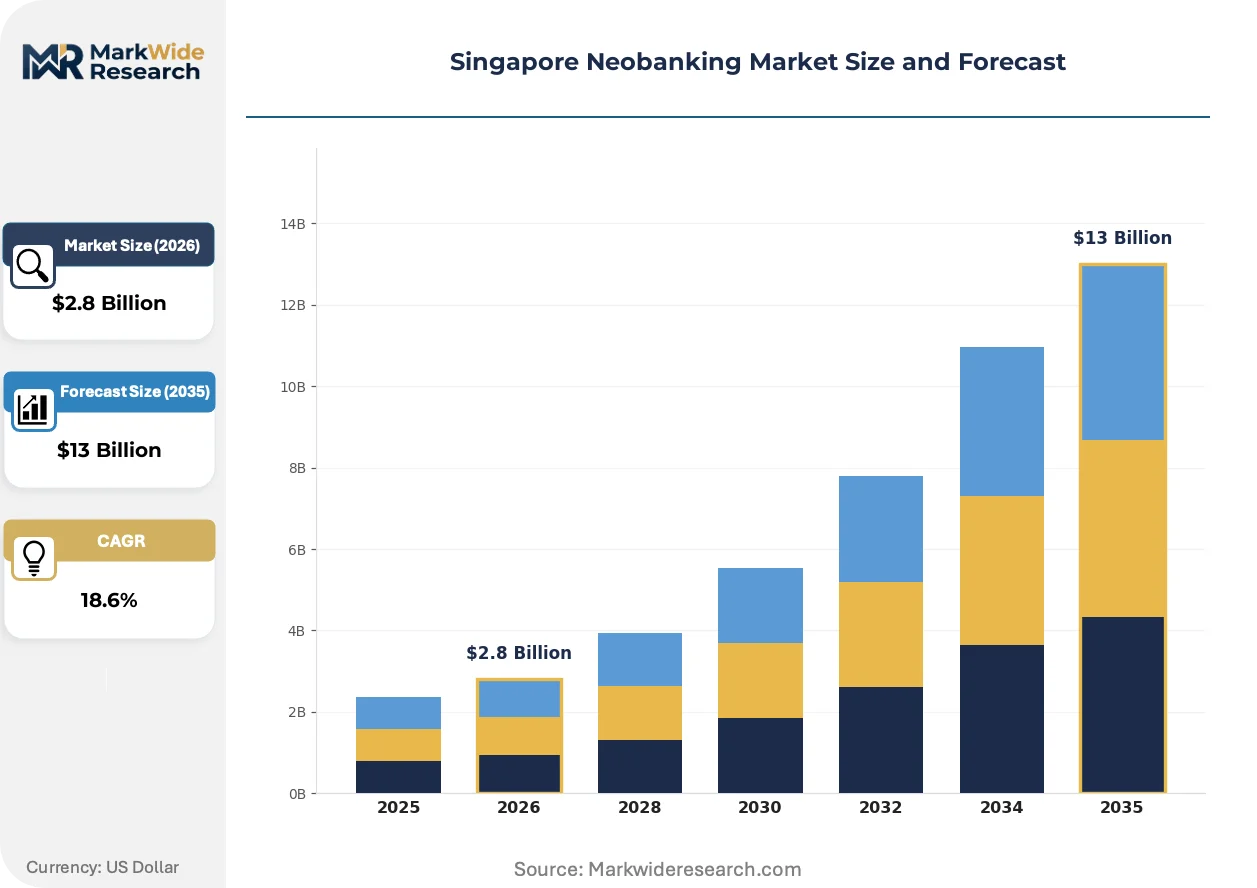
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Services, Payment Solutions, Lending Solutions, Investment Services Target Customer: Millennials, Small Businesses, Freelancers, Students Technology: Blockchain, Artificial Intelligence, Mobile Apps, Cloud Computing Offering: Cash Management, Financial Planning, Digital Wallets, Credit Facilities |
| Companies Covered | GXS Bank, Grab Financial Group, Aspire Financial Technologies Pte. Ltd., MatchMove Pay Pte. Ltd., Nium Pte. Ltd., YouTrip Pte. Ltd., ANEXT Bank, DBS DigiBank, Revolut Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Neobanking Market Evolving Landscape
Artificial intelligence architectures are compressing underwriting timelines from days to minutes, while regulatory sandboxes and open banking mandates restructure how customer data flows between financial institutions and third-party service providers.
Embedded lending APIs are decentralizing credit origination from bank balance sheets to non-financial platforms. E-commerce marketplaces and payroll software providers now embed white-labeled credit facilities directly at the point of transaction. This shift fragments loan distribution across digital touchpoints, compressing traditional branch-based acquisition channels.
MAS sandbox frameworks for digital banks are accelerating controlled experimentation with novel product structures. Licensed neobanks test fractional reserve models and dynamic interest rate instruments under regulatory supervision. SME lending segments respond fastest, leveraging sandbox outcomes to justify full product rollouts ahead of incumbent competitors.
Freelancer banking preferences are unbundling relationship-based service models into modular, pay-per-use components. Gig workers select discrete features—multi-currency wallets, instant invoice financing, tax automation—rather than packaged accounts. This pattern concentrates in creative and technology services verticals where income volatility demands flexible liquidity tools.
Singapore Neobanking Market Segmentation
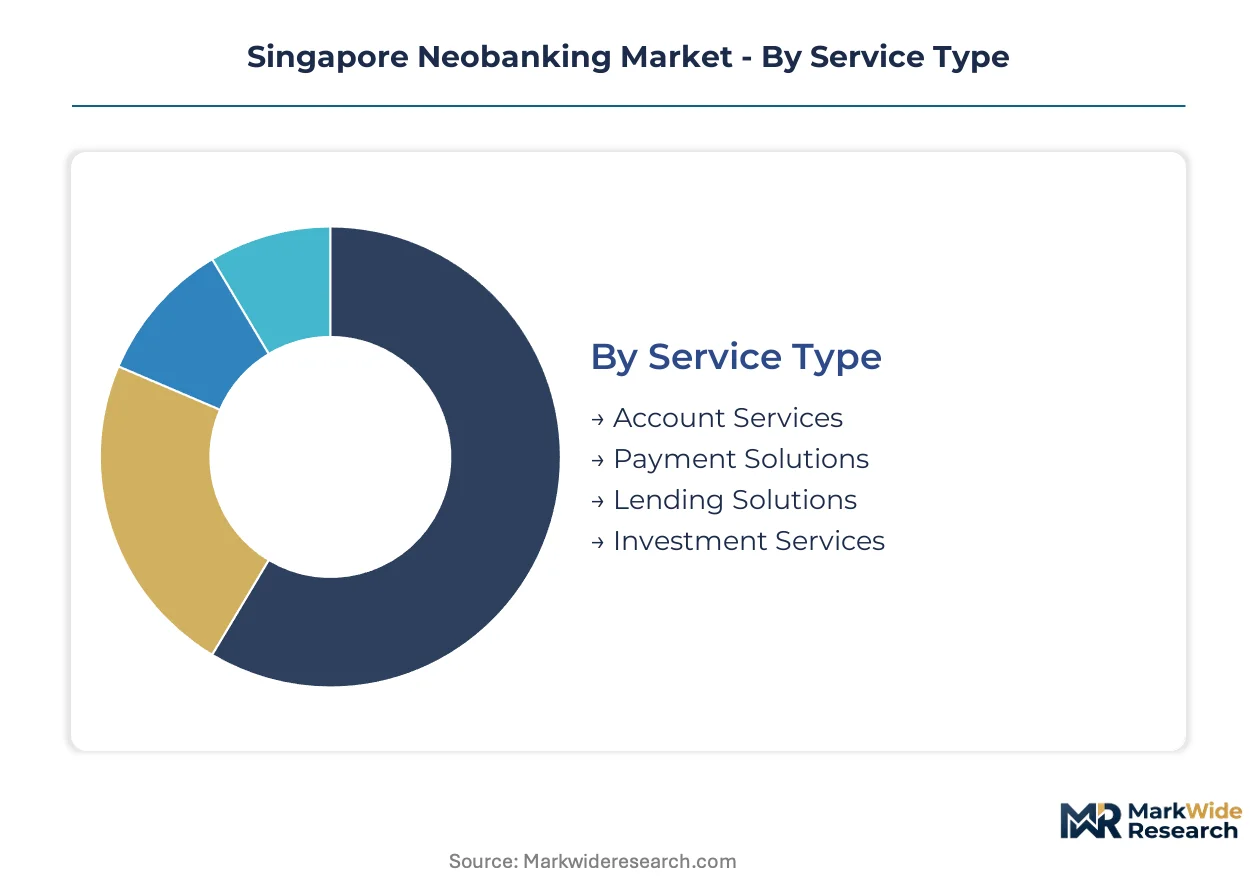
Neobank operators in Singapore deploy distinct service architectures to capture specific customer lifetime value profiles. Segmentation reveals how ecosystem-anchored players prioritize payment velocity over deposit depth, while specialized lenders target risk-adjusted yield pools.
Service Type:
Upgrade cycles in Singapore's neobanking sector accelerate as customers migrate from basic transactional accounts toward integrated financial operating systems.
- Account Services:Digital-native deposit products with real-time balance visibility and automated savings rules anchor customer acquisition funnels. Demand concentrates among millennials establishing primary banking relationships outside incumbent branch networks, driven by MAS digital banking license requirements that mandate robust deposit infrastructure for full-service operators.
- Payment Solutions:Multi-currency transaction rails with instant settlement and cross-border remittance capabilities command the highest engagement frequency. Small businesses and freelancers in Singapore's technology services vertical adopt these tools to bypass correspondent banking delays and FX markup layers.
- Lending Solutions:API-connected credit facilities with alternative data underwriting.
- Investment Services:Fractional securities access and robo-advisory integration.
Volume placements concentrate in Payment Solutions; the faster expansion belongs to Lending Solutions.
Target Customer:
Customer acquisition economics vary sharply across demographic segments, with digitally native cohorts demanding modular product architectures rather than bundled relationship banking.
- Millennials:Mobile-first users seeking seamless multi-currency management and lifestyle-integrated financial tools. This segment drives deposit growth in Singapore's core central business district corridors, constrained by deposit insurance ceiling awareness relative to established bank brands.
- Small Businesses:SME operators requiring automated receivables, payables, and working capital facilities without relationship manager overhead. Demand concentrates in fintech and e-commerce verticals where cash flow volatility demands just-in-time liquidity access.
- Freelancers:Gig economy participants with irregular income patterns.
- Students:Early-stage financial product users building credit histories.
Deposit volume concentrates in Millennial accounts; Small Businesses are climbing the fastest as automated underwriting matures.
Technology:
Technology stack decisions determine operational leverage and regulatory compliance posture for licensed operators competing against incumbent IT budgets.
- Artificial Intelligence:Behavioral scoring engines and natural language processing for customer service automation. Deployment concentrates in lending origination workflows where machine learning compresses decision timelines from days to minutes, though talent scarcity in financial services domain expertise constrains rollout velocity.
- Mobile Apps:Native iOS and Android interfaces with biometric authentication and real-time notification systems. This layer dominates customer touchpoint frequency across all Singapore neobank users, driven by smartphone penetration rates and branch abandonment preferences.
- Blockchain:Distributed ledger infrastructure for settlement and identity verification.
- Cloud Computing:Scalable core banking infrastructure and data storage.
Deployment investment concentrates in Mobile Apps; Artificial Intelligence is gaining share fastest as MAS sandbox frameworks validate novel underwriting models.
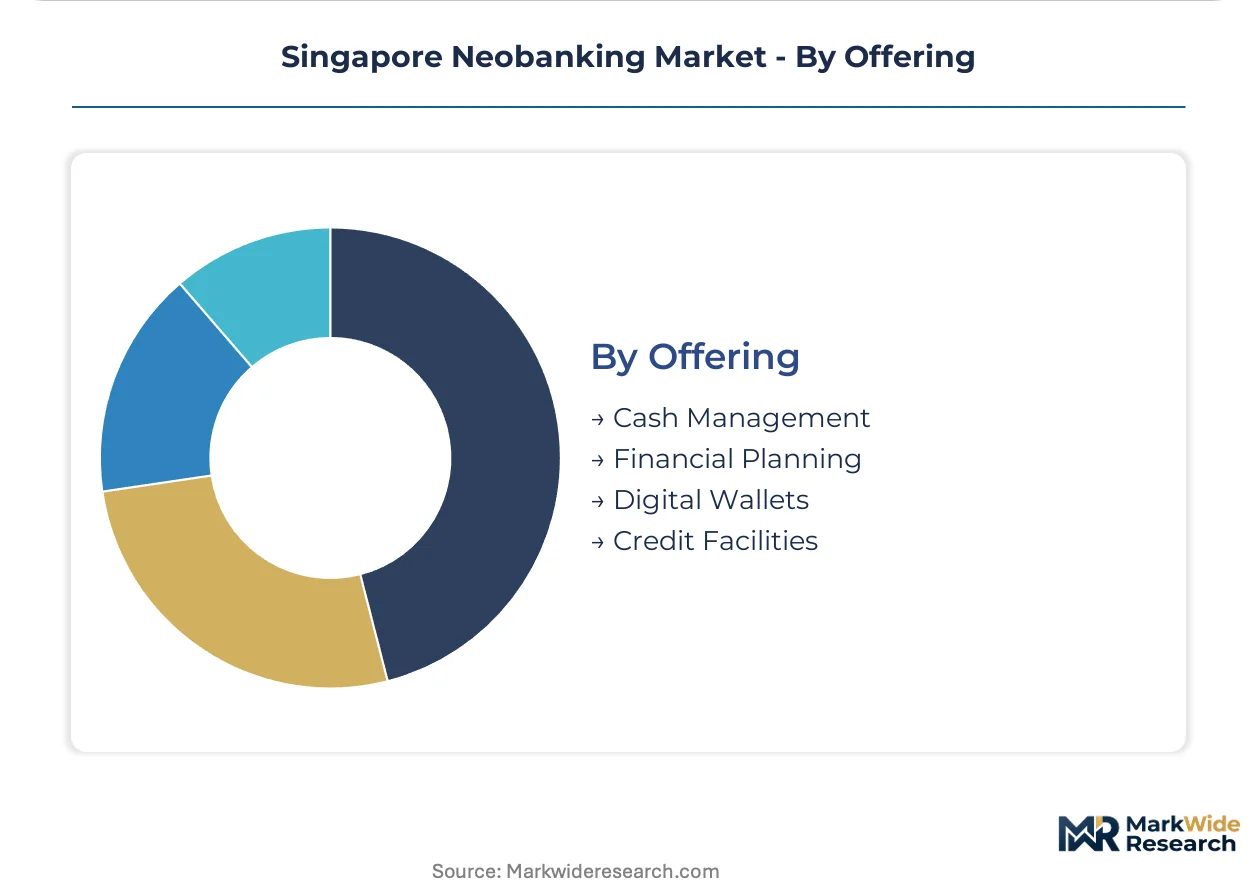
Offering:
Product bundling strategies diverge between ecosystem players leveraging captive distribution and standalone neobanks competing on feature depth.
- Digital Wallets:Stored-value instruments with merchant payment integration and peer-to-peer transfer capabilities. Demand concentrates in retail and food services verticals where contactless transaction velocity rewards real-time balance management tools.
- Credit Facilities:Revolving credit lines and installment products embedded at transaction points. Small business adoption responds to automated eligibility assessment that bypasses traditional collateral requirements, though MAS liquidity framework adjustments for non-bank deposit takers influence pricing flexibility.
- Cash Management:Liquidity optimization tools for business treasury operations.
- Financial Planning:Goal-based savings and automated budgeting features.
Transaction volume concentrates in Digital Wallets; Credit Facilities show the steepest expansion trajectory as embedded lending APIs proliferate across e-commerce platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore generates disproportionate fintech innovation output relative to its domestic consumption base. The city-state functions as a regional production hub for digital banking infrastructure serving Southeast Asian markets.
Central Region
Marina Bay and the Central Business District concentrate neobank headquarters and regulatory engagement. MAS digital banking license applications flow through this corridor. Raffles Place anchors ecosystem-anchored players leveraging captive distribution from ride-hailing and e-commerce platforms.
East Region
Changi Business Park hosts cloud infrastructure nodes supporting real-time payment processing. MAS liquidity framework adjustments for non-bank deposit takers receive implementation testing here. Tampines clusters SME-facing neobanks targeting automated underwriting for regional trade finance.
West Region
Jurong Lake District attracts technology stack vendors serving licensed operators. The country's national technology regulator validates sandbox experiments for fractional reserve models in this zone. One-North startups supply behavioral scoring engines to lending-focused neobanks.
North Region
Yishun and Woodlands corridors concentrate millennial deposit growth outside traditional branch networks. MAS deposit insurance ceiling awareness campaigns target first-time digital bank users here. Seletar aerospace cluster employees drive demand for multi-currency salary crediting tools.
Northeast Region
Punggol Digital District hosts API connectivity providers linking neobanks to corporate treasury systems. The national payment infrastructure operator maintains interoperability testing facilities in this corridor. Sengkang freelancers generate concentrated adoption of instant invoice financing products.
Singapore Neobanking Market Competitive Landscape
Top-tier vendors anchor full-stack digital banking operations, while payment-specialist operators compete on transaction velocity and cross-border rail access. The competitive structure splits between ecosystem-anchored players with captive distribution and standalone neobanks competing on feature depth. Three archetypes dominate: ecosystem-anchored full banks, SME-focused credit specialists, and cross-border payment infrastructure providers. Competitive moves concentrate on strategic partnerships with e-commerce platforms and geographic expansion into ASEAN markets.
Within the ecosystem-anchored tier, GXS Bank and Grab Financial Group occupy positions leveraging super-app distribution to capture deposit flows. Aspire Financial Technologies Pte. Ltd. exemplifies the SME credit specialist archetype, while Nium Pte. Ltd. represents cross-border payment infrastructure providers extending regional footprints beyond Singapore's jurisdiction.
| Leading Market Players |
|---|
| GXS Bank |
| Grab Financial Group |
| Aspire Financial Technologies Pte. Ltd. |
| MatchMove Pay Pte. Ltd. |
| Nium Pte. Ltd. |
| YouTrip Pte. Ltd. |
| ANEXT Bank |
| DBS DigiBank |
| Revolut Ltd. |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure pricing indices from AWS, Azure, and Google Cloud Platform cascade through neobank operating models, compressing margins for standalone operators while ecosystem-anchored players absorb compute costs through captive cloud commitments. This cost structure stratifies pricing tiers between full-stack digital banks and payment-only specialists.
Pricing Analysis
Margin tightening in SME lending reflects automated underwriting commoditization as API-connected credit engines proliferate across Singapore's fintech corridor. Three-tier pricing structure across premium relationship-managed, standard self-service, and economy API-only levels differentiates by human touch density and data integration depth. Cost compression accelerates in payment solutions as real-time rail access fees decline under MAS interoperability mandates. Freelancers exhibit highest price sensitivity, while corporate treasury clients prioritize integration reliability over per-transaction rates.
Supply Chain Analysis
MAS liquidity framework adjustments for non-bank deposit takers are reshaping capital sourcing requirements, pushing licensed operators toward diversified funding structures. Core banking technology concentrates in cloud-native vendors across the United States, United Kingdom, and Singapore itself. Raw material dependencies span API middleware, biometric authentication modules, and regulatory compliance software layers. Single-source vulnerability concentrates in cloud infrastructure providers, where AWS Singapore anchors the majority of licensed neobank workloads. Distribution runs through mobile app stores and embedded finance partnerships with e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's neobanking sector is consolidating around ecosystem-anchored players with captive distribution, as capital adequacy requirements and customer acquisition cost inflation force subscale operators toward acquisition or exit.
For Market Incumbents: Hedge against deposit attrition by deepening API connectivity with corporate treasury management systems, while securing exclusive data-sharing agreements with ride-hailing and e-commerce platforms that feed behavioral scoring engines. MAS liquidity framework evolution presents both threat and opportunity—early compliance investment locks in regulatory goodwill as rules harden for non-bank deposit takers. For New Entrants and Emerging Players: Capture white-space in green financing product lines where MAS sustainable finance taxonomy incentives create first-mover advantages for carbon-linked deposit instruments. SME trade finance in the East Region's Tampines corridor offers the most penetrable entry point, with automated underwriting for regional supply chain participants still underserved by relationship-banking incumbents. Go-to-market through payroll software integration embeds credit facilities at salary crediting touchpoints. For Investors and Strategic Acquirers: Distressed-cycle entries favor SME-focused credit specialists with proven automated underwriting engines in Singapore's Jurong Lake District technology cluster. Long-term viability hinges on regulatory license durability and core banking vendor diversification. Watch MAS adjustments to deposit insurance ceilings as the inflection signal—expanded coverage would accelerate retail deposit migration from incumbents to licensed neobanks, validating balance-sheet-heavy business models.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Positions neobanks to capture transaction data from Shopee and Lazada checkout flows for credit scoring. |
| Green Deposit Product Launch | Aligns with MAS sustainable finance taxonomy incentives while attracting ESG-focused millennial depositors. |
| Cross-Border Payment Rail Expansion | Extends Nium-style regional footprint beyond Singapore into ASEAN markets with divergent licensing requirements. |
| Core Banking Vendor Diversification | Mitigates operational resilience risk from AWS Singapore concentration through multi-cloud deployment. |
| Wealth-Tech Convergence Partnership | Integrates robo-advisory APIs to expand beyond transactional banking into fee-based asset management. |
Research Methodology
Multi-period observation of MAS digital banking license applications, deposit flow patterns, and API transaction volumes anchored the trend analysis, supplemented by interviews with neobank product executives, regulatory compliance officers, SME treasury managers, and cloud infrastructure procurement leads. Secondary validation drew from MAS regulatory circulars, ABS electronic payments guidelines, cloud provider capex disclosures, and fintech funding databases. Bottom-up transaction volume modeling and top-down macroeconomic scenario analysis were triangulated to ensure consistency.
Input-output matrices mapped service type demand against technology deployment costs and regulatory capital requirements across the projection horizon. Segmentation dimensions modeled include service architecture, target customer archetype, technology stack layer, and product bundling strategy. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Forecast inputs incorporated MAS sandbox experiment outcomes and cross-border payment rail expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MAS liquidity rule adjustments and ASEAN regulatory harmonization progress. Forecasts reflect assumptions around license renewal durability, core vendor stability, and deposit insurance framework evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
China Retail Banking System Market
Banking
Smart Machines in Banking Market
Banking
South America Challenger Banks Market
Banking
Video Banking Service Market
Banking
Cloud-Based Core Banking Market
Banking
China Data Analytics in Banking Market
Banking
Corporate Digital Banking Market
Banking
Banking Software Market
Banking
Smart Banking Solutions Market
Banking
Global AI in Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Bank Guarantee Market
Banking
UK Banking as a Service Market
Banking
Cloud Billing in Banking Market
Banking
Banking CRM Software Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market