
 Face-Swiping Payment Market | 2026-2036
Face-Swiping Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Face-Swiping Payment Market Intelligence
Asset-light terminal leasing and pay-per-transaction financing is fragmenting competitive barriers in face-swiping payment infrastructure. Alipay sustains dominance through captive merchant networks across China's urban centers. Mastercard differentiates via tokenization partnerships that secure biometric credentials across issuing banks. Stripe navigates regulatory complexity by embedding identity verification APIs for platform clients entering facial authentication markets.
Face-swiping payment denotes a biometric transaction method where facial geometry captured by infrared or 3D depth cameras authenticates payer identity in under one second, typically leveraging liveness detection algorithms to prevent spoofing. The system replaces card taps or mobile device proximity with direct facial scan-to-debit functionality at point-of-sale terminals. Mobile Wallet deployments currently anchor transaction volume through super-app integration, while Biometric Device installations at transit turnstiles represent the fastest-expanding hardware segment. Cloud-Based deployment models concentrate margin pools among platform operators managing inference workloads and token vaults, whereas On-Premise configurations persist in hospitality settings with strict data residency requirements.
The EU AI Act classifies real-time remote biometric identification as high-risk, mandating conformity assessments before terminal deployment in public spaces. China's SAMR enforces national GB standards for facial information collection, requiring explicit user consent and localized data storage. The US lacks unified federal biometric legislation, leaving NIST frameworks and state-level BIPA statutes to shape compliance costs. Stakeholders must monitor divergent consent architectures across jurisdictions to determine where infrastructure investment yields sustainable merchant adoption.
Market Dynamics
Transit authorities in metropolitan hubs are accelerating adoption of contactless fare systems, compressing deployment timelines from multi-year pilots to 18-month rollouts. This infrastructure push concentrates demand among hardware-software integrated vendors capable of delivering liveness detection and tokenization in unified terminal stacks.
Growth Catalysts
- EU AI Act conformity assessments:Terminal manufacturers completing high-risk biometric system certification gain preferential procurement status in European transit tenders. The mandate creates compliance moats for pre-certified vendors.
- Subway network digitization:Metropolitan rail operators in China, Brazil, and Mexico are replacing magnetic stripe infrastructure with face-swiping turnstiles to reduce fare evasion and processing latency.
- 3D depth sensing modules:Structured light and time-of-flight camera costs have fallen below mass-deployment thresholds, enabling sub-$200 terminal bill-of-materials for convenience retail.
Market Restraints
- GB standards compliance costs:China's SAMR enforcement of localized facial data storage and explicit consent workflows adds 15-20% to terminal software development overhead for foreign entrants.
- Silicon concentration in Taiwan and South Korea:Infrared sensor and edge AI chip supply chains remain vulnerable to foundry allocation constraints and export control friction.
- Biometric spoofing arms race:Presentation attack detection algorithms require continuous retraining against deepfake injection techniques, elevating ongoing R&D burn rates for terminal OEMs.
Strategic Opportunities
- India's UPI-biometric convergence:The National Payments Corporation of India is piloting face authentication linked to Aadhaar for merchant transactions in tier-two and tier-three cities.
- Hospitality data residency carve-outs:Casino and hotel operators in Nevada and Macau require on-premise inference to satisfy gaming commission surveillance mandates, creating premium hardware margins.
- ISO/IEC 30107-3 certification:Liveness detection testing frameworks are becoming de facto procurement filters in European and Middle Eastern transit tenders, favoring certified component suppliers.
Industry Challenges
- Embedded systems firmware talent scarcity:Terminal OEMs compete with automotive and drone sectors for engineers skilled in real-time infrared image processing and edge model optimization.
- Legacy POS integration complexity:Face-swiping terminals must bridge proprietary protocols from incumbent payment acquirers, extending deployment timelines and requiring custom middleware development.
- Cross-border token vault interoperability:Merchant acquirers face technical debt reconciling Alipay, WeChat Pay, and EMVCo token formats in multi-rail acceptance environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face-Swiping Payment Market |
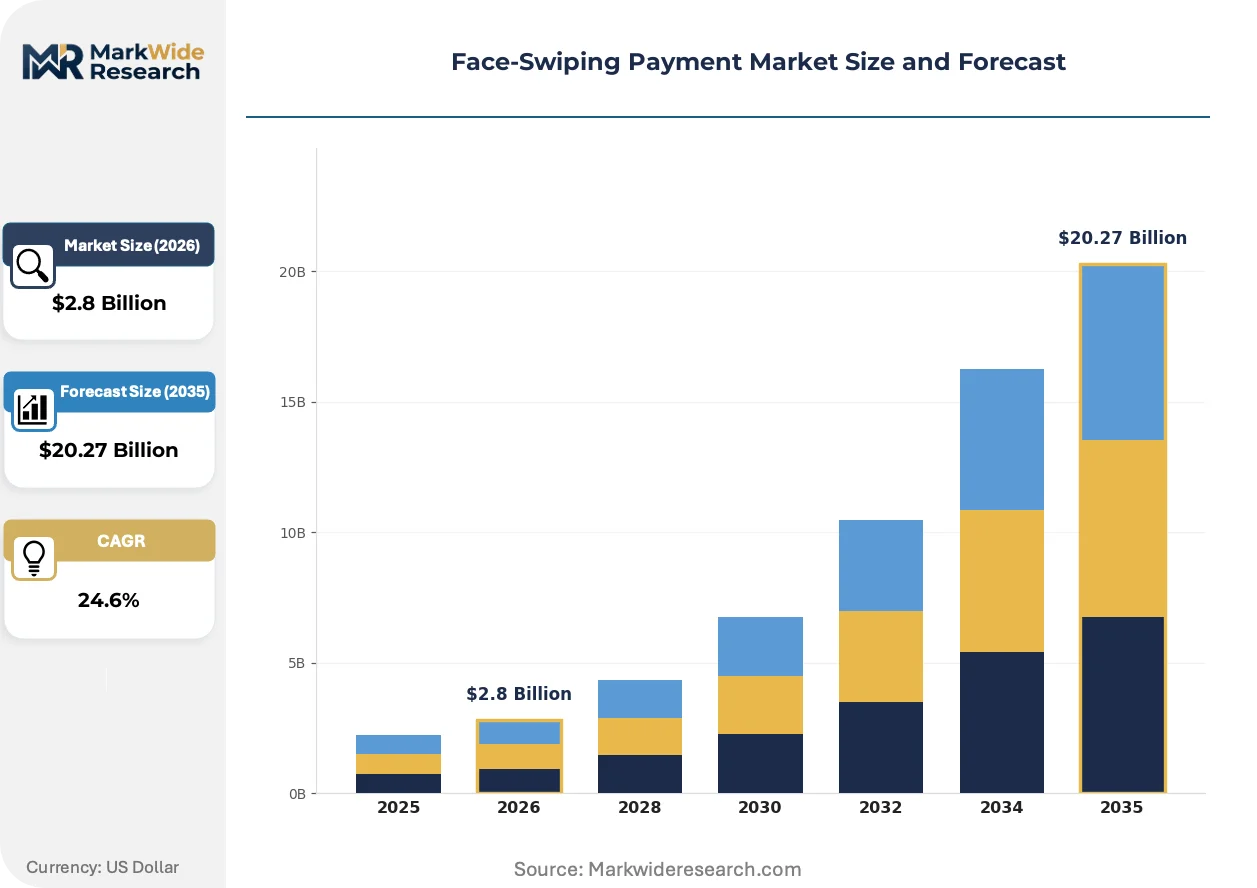
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Wallet, Smart Card, Biometric Device, Wearable Payment Technology: Facial Recognition, NFC, Cloud Computing, Blockchain End User: Retail, E-commerce, Transportation, Hospitality Deployment: On-Premise, Cloud-Based, Hybrid, Managed Service |
| Companies Covered | Adyen, Fiserv, Alipay, Finix, Worldpay, WeChat Pay, Mastercard, Rapyd Financial Network, Stripe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face-Swiping Payment Market Strategic Shifts & Innovations
Hardware-software decoupling is fragmenting vendor control over the payment stack. Terminal OEMs now compete with pure-play algorithm licensors and cloud inference providers for merchant relationships.
Structured light depth sensing is migrating from flagship retail deployments to mass-transit turnstiles. Guangzhou Metro and Mexico City Metrobús have adopted the technology for sub-second authentication in high-throughput environments. The shift is compressing hardware refresh cycles from seven years to four years as transit authorities prioritize spoof-resistance over capital depreciation schedules.
China's SAMR biometric data governance rules are tightening consent frameworks for facial authentication in commercial settings. The regulations mandate granular purpose limitation and localized storage, forcing terminal operators to rearchitect cloud-dependent inference pipelines. Domestic super-apps have responded by deploying hybrid edge-cloud stacks that keep raw biometric data within municipal boundaries.
Merchant procurement of face-swiping infrastructure is consolidating through payment facilitator platforms rather than direct terminal purchases. Small-format retailers in Shenzhen and São Paulo now access hardware via revenue-share arrangements with acquirers. The model shifts capex burden to platform operators while accelerating merchant onboarding velocity in price-sensitive segments.
Face-Swiping Payment Market Segmentation
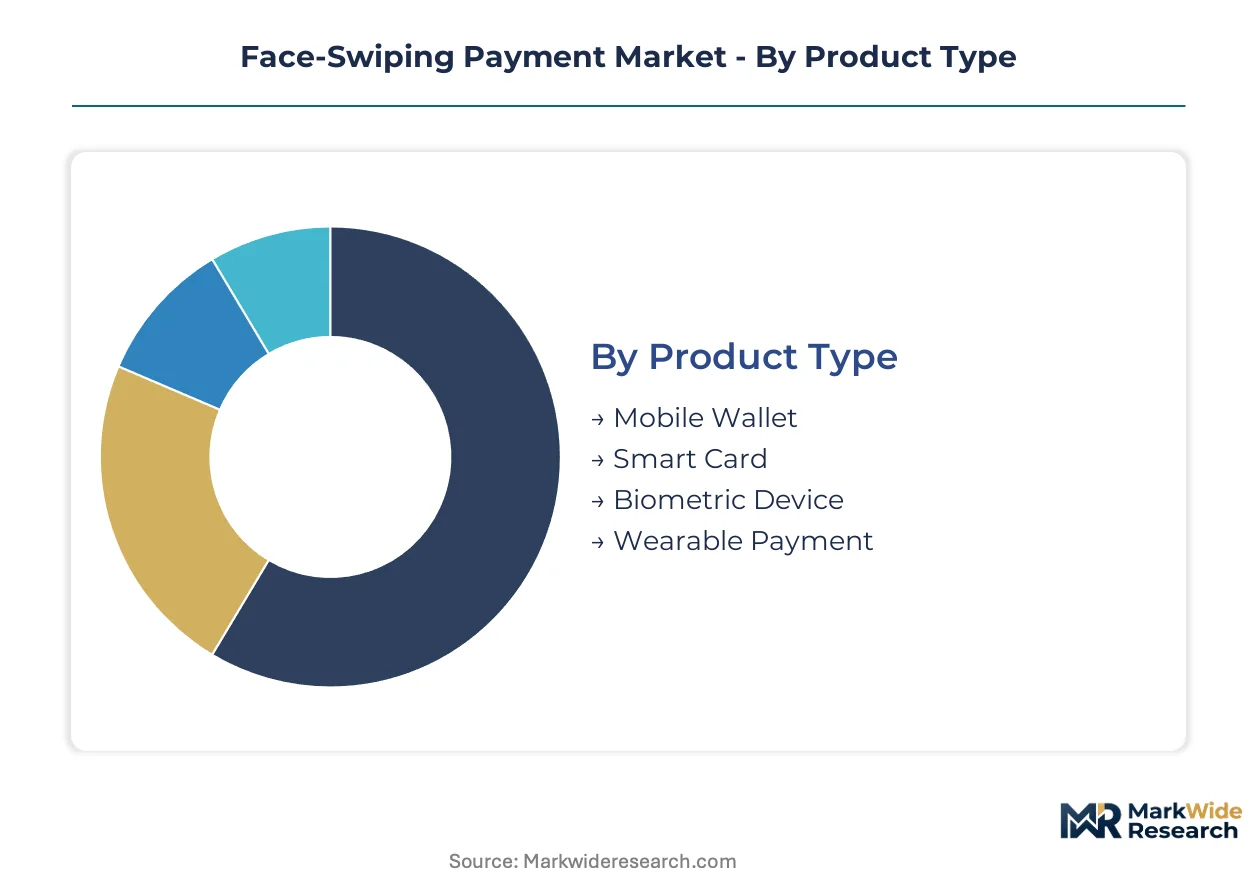
Segmentation in face-swiping payment infrastructure reveals divergent hardware refresh cycles and margin profiles across product architectures. Deployment choices directly determine regulatory exposure and capital intensity for merchant acquirers.
Product Type:
Hardware refresh cycles vary dramatically across this category, with biometric terminals turning over every four years in transit environments versus seven-year depreciation schedules for static retail installations.
- Mobile Wallet:Super-app integrations dominate transaction volume through Alipay and WeChat Pay deployments across Chinese urban centers. Transit authorities in São Paulo and Mexico City are piloting wallet-based face authentication to reduce turnstile hardware capex.
- Biometric Device:Structured light and time-of-flight camera modules enable sub-second authentication at subway turnstiles in Guangzhou and Mexico City Metrobús. These terminals carry the steepest R&D burn rates due to continuous retraining against deepfake injection techniques.
- Smart Card:EMVCo token formats bridge legacy magnetic stripe infrastructure during transition periods. Brazilian transit operators deploy hybrid card-face systems to maintain backward compatibility.
- Wearable Payment:Smartwatch and ring form factors concentrate in hospitality settings requiring discreet authentication. Casino operators in Nevada and Macau pilot wearables to satisfy gaming commission surveillance mandates without visible terminal infrastructure.
Mobile Wallet anchors the volume base while Biometric Device gains share at the steepest rate.
Technology:
Cost tiers separate proprietary algorithm stacks from commodity hardware components, with liveness detection commanding premium licensing fees.
- Facial Recognition:3D depth sensing with liveness detection algorithms prevents spoofing through infrared pattern analysis. ISO/IEC 30107-3 certification has become a de facto procurement filter in European and Middle Eastern transit tenders.
- NFC:Proximity protocols bridge face-swiping terminals to existing payment rails during multi-rail acceptance transitions. Transit operators in Brazil combine NFC fallback with primary biometric authentication to reduce fare evasion.
- Cloud Computing:Inference workloads and token vaults concentrate margin pools among platform operators managing merchant relationships. China's SAMR localized storage mandates have forced rearchitecture of cloud-dependent pipelines.
- Blockchain:Decentralized credential verification remains experimental in cross-border remittance pilots. Technical debt reconciling token formats across Alipay, WeChat Pay, and EMVCo standards limits near-term deployment.
Facial Recognition commands the highest licensing premiums while Cloud Computing expands most quickly among platform operators.
End User:
Application-specific compliance requirements create divergent data residency and consent workflow demands.
- Transportation:Metropolitan rail operators in China, Brazil, and Mexico replace magnetic stripe infrastructure with face-swiping turnstiles. These deployments prioritize throughput velocity over capital depreciation schedules.
- Retail:Convenience stores in Shenzhen and São Paulo access hardware via revenue-share arrangements with payment facilitators. Small-format merchants shift capex burden to platform operators while accelerating onboarding velocity.
- Hospitality:Casinos and hotels in Nevada and Macau require on-premise inference to satisfy gaming commission surveillance mandates. Premium hardware margins persist in these data residency carve-outs.
- E-commerce:Remote biometric authentication faces stricter consent frameworks under EU AI Act high-risk classification. Conformity assessments before deployment in public spaces create compliance moats for pre-certified vendors.
Transportation anchors infrastructure investment while Retail shows the steepest merchant onboarding acceleration.
Deployment:
Customer type separates enterprise merchants with dedicated IT security teams from small-format retailers dependent on platform-managed solutions.
- Cloud-Based:Platform operators manage inference workloads and token vaults, concentrating margin pools among scaled providers. Hybrid edge-cloud stacks keep raw biometric data within municipal boundaries to satisfy China's SAMR localized storage mandates.
- On-Premise:Strict data residency requirements persist in hospitality settings with gaming commission surveillance mandates. These configurations carry higher upfront capital burdens but eliminate recurring cloud service fees.
- Hybrid:Edge inference with cloud tokenization balances latency requirements against regulatory compliance. Transit authorities in Guangzhou deploy hybrid stacks to maintain sub-second authentication while satisfying data localization rules.
- Managed Service:Payment facilitators assume terminal maintenance and software update responsibilities for price-sensitive merchant segments. Revenue-share arrangements dominate procurement in São Paulo and Shenzhen convenience retail.
Cloud-Based deployment commands the largest platform operator margins while Hybrid configurations climb the fastest among transit authorities balancing latency against compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's tier-one cities where Alipay and WeChat Pay have saturated convenience retail with subsidized terminal deployments. European transit authorities extract steeper vendor margins through EU AI Act conformity mandates that filter out uncertified hardware suppliers.
China
Alipay and WeChat Pay have deployed millions of face-scanning terminals across Shenzhen and Shanghai convenience stores. SAMR enforces GB standards requiring localized facial data storage and explicit consent workflows. Guangzhou Metro operates sub-second authentication turnstiles using structured light depth sensing.
United States
Stripe embeds identity verification APIs for platform clients entering facial authentication markets. NIST frameworks and state-level BIPA statutes shape compliance costs without unified federal legislation. Nevada casino operators require on-premise inference to satisfy gaming commission surveillance mandates.
Brazil
São Paulo transit authorities pilot wallet-based face authentication to reduce turnstile hardware capex. ANVISA and central bank guidelines influence biometric payment system approvals. Metropolitan rail operators deploy hybrid card-face systems to maintain backward compatibility during infrastructure transitions.
Germany
Mastercard differentiates via tokenization partnerships securing biometric credentials across issuing banks. EU AI Act high-risk classification mandates conformity assessments before terminal deployment in public transit. Berlin and Munich rail operators prioritize ISO/IEC 30107-3 certified liveness detection components.
India
The National Payments Corporation of India pilots face authentication linked to Aadhaar for merchant transactions in tier-two and tier-three cities. RBI guidelines shape payment system interoperability requirements. Karnataka and Maharashtra urban clusters concentrate early deployment of UPI-biometric convergence infrastructure.
Face-Swiping Payment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying depth-sensing modules and liveness detection algorithms. The vendor base stratifies between captive super-app ecosystems and interoperable payment network providers. Three archetypes dominate: merchant acquirer platforms, hardware-software integrated terminal OEMs, and pure-play biometric algorithm licensors. Competitive moves concentrate on token vault partnerships and edge-cloud stack rearchitecture to satisfy data localization mandates.
Within the platform integrator tier, Alipay and WeChat Pay represent captive ecosystem dominance through merchant network saturation. Mastercard occupies a position bridging tokenization standards across issuing banks in European and North American markets. Stripe exemplifies API-first navigation of regulatory complexity for platform clients entering facial authentication deployments.
| Leading Market Players |
|---|
| Adyen |
| Fiserv |
| Alipay |
| Finix |
| Worldpay |
| WeChat Pay |
| Mastercard |
| Rapyd Financial Network |
| Stripe |
| Others |
Cost & Logistics Intelligence
The Shanghai-Shenzhen freight corridor channels hardware components from Taiwan and South Korea into Guangzhou Metro terminal assembly plants, with logistics cost volatility amplifying margin pressure on sub-$200 retail terminals while premium on-premise hospitality installations maintain pricing power through data residency bundling.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO/IEC 30107-3 liveness detection certification and after-sales firmware update bundling. Cost compression in the standard tier is intensifying because of foundry allocation constraints for infrared sensors. Small-format retailers in São Paulo and Shenzhen exhibit highest price sensitivity, whereas Nevada casino operators accept premium positioning for on-premise inference stacks.
Supply Chain Analysis
Foxconn and Pegatron concentrate contract manufacturing capacity for structured light camera modules, with secondary assembly spread across Mexico and Vietnam facilities. The supply chain draws from Taiwan and South Korea for edge AI chips, from China for infrared sensor housings, and from Japan for precision optics. Single-source vulnerability in Taiwan foundry capacity presents structural risk. Distribution runs through payment facilitator platforms that shift terminal ownership from merchants to acquirer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Face-Swiping Payment Market represents a high-growth disruption where EU AI Act high-risk classification and China's SAMR localization mandates are compressing vendor certification timelines and fragmenting competitive moats.
For Market Incumbents: Entrench merchant relationships through captive token vault partnerships that bridge Alipay, WeChat Pay, and EMVCo formats. Deepen backward integration into edge AI chip sourcing to mitigate Taiwan foundry allocation risk. Prioritize ISO/IEC 30107-3 pre-certification to lock in European transit procurement preference.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two and tier-three UPI-biometric convergence pilots where NPCI infrastructure investment is outpacing incumbent saturation. Target hospitality data residency carve-outs in Nevada and Macau where gaming commission mandates sustain premium hardware margins. Pursue revenue-share terminal leasing to bypass merchant capex barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm licensors with ISO/IEC 30107-3 certification and hybrid edge-cloud deployment capabilities over pure hardware OEMs. Long-term viability rests on regulatory compliance architecture rather than terminal volume scale. Monitor EU AI Act conformity assessment completion rates as the primary inflection indicator for vendor procurement status.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Investment | Pre-certification creates compliance moats for European transit tenders under EU AI Act mandates. |
| Hybrid Edge-Cloud Stack Deployment | Hybrid architectures satisfy China's SAMR localized storage rules while maintaining sub-second authentication latency. |
| Token Vault Partnership Expansion | Multi-rail token interoperability bridges Alipay, WeChat Pay, and EMVCo formats for merchant acquirers. |
| Revenue-Share Terminal Leasing | Asset-light financing accelerates merchant onboarding velocity in São Paulo and Shenzhen convenience retail. |
| Backward Integration into Edge AI Chips | In-house chip sourcing mitigates Taiwan and South Korea foundry allocation vulnerability. |
Research Approach
The analysis maps biometric device hardware, mobile wallet software, and cloud inference services, each validated through terminal OEM procurement directors, payment facilitator platform engineers, transit authority technology officers, and hospitality IT security leads. Primary interview insights triangulate against SAMR regulatory filings, EU AI Act implementation guidance, NPCI pilot announcements, and SEC 10-K hardware segment disclosures. Bottom-up terminal deployment counts reconcile with top-down payment volume estimates across the analysis window.
Assumptions held fixed include EU AI Act high-risk classification enforcement timelines and China's GB standards data localization requirements, while variables included India UPI-biometric pilot expansion velocity and Taiwan foundry capacity allocation. Segmentation dimensions encompass product architecture, deployment model, technology stack, and end-use application. CAGRs derive from hardware refresh cycle compression in transit environments and merchant onboarding acceleration through revenue-share financing. Forecast inputs incorporate liveness detection algorithm licensing fees and edge AI chip bill-of-materials trajectories.
Sensitivities concentrate around EU AI Act conformity assessment bottlenecks, Taiwan semiconductor export control friction, and deepfake spoofing technique evolution. Forecasts reflect documented assumptions on regulatory enforcement consistency and foundry capacity expansion. Quarterly review of ISO/IEC 30107-3 certification completion rates and SAMR enforcement action frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Mobile POS Market
Payments
Indonesia Mobile Payments Market
Payments
Wearable Payments Market
Payments
Asia-Pacific Payments Market
Payments
LAMEA Payment Gateway Market
Payments
3D Secure Payment Authentication Market
Payments
Denmark POS Terminals Market
Payments
Global Gift Card Market
Payments
GCC Mobile Payment Market
Payments
Direct Carrier Billing Market
Payments
Portugal Mobile Payments Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Uganda Mobile Money Market
Payments
New Zealand Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market