
 Germany POS Terminal Market | 2026-2036
Germany POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Germany POS Terminal Market Foresight
Asset-light leasing and terminal-as-a-service models are reshaping competitive entry in the Germany POS Terminal Market, lowering capital barriers for mid-tier hospitality and retail operators. Worldline SA (Ingenico) leverages its embedded finance partnerships to sustain recurring revenue streams across German supermarket chains. Diebold Nixdorf AG anchors its position through in-house manufacturing of cash-handling modules integrated with POS hardware. SumUp Limited competes via mobile-first form factors targeting German specialty stores and pop-up vendors.
Germany POS terminals are electronic payment devices that process card and digital transactions through integrated NFC readers, EMV chip slots, and secure encryption modules, serving as the terminal node between merchant point-of-sale software and banking networks. Fixed terminals dominate German supermarket and big-box deployments due to durability requirements and high transaction volumes. Mobile POS terminals capture the fastest expansion as German quick service restaurants and event venues prioritize tableside and queue-busting checkout flexibility. Self-service kiosks concentrate margin pools in German hospitality and entertainment where labor cost pressures accelerate automation.
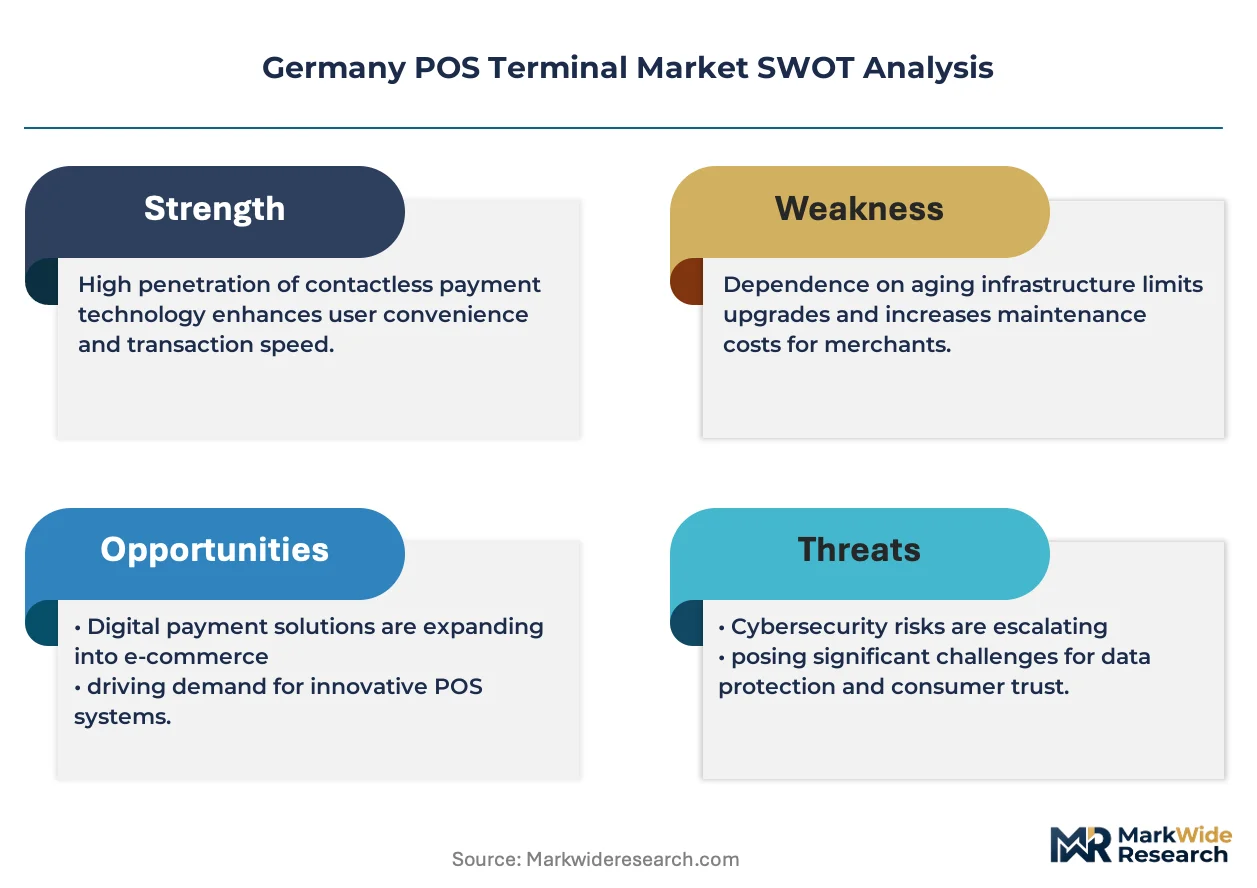
German POS terminal deployment falls under BaFin supervision for payment security, EU PSD2 strong customer authentication mandates, and GDPR data handling requirements, collectively forcing hardware vendors to embed certified encryption and tokenization capabilities. The EU AI Act and incoming product liability directives will extend compliance obligations to software-integrated terminals with biometric or predictive features. Stakeholders must monitor how Berlin and Frankfurt regulatory interpretations diverge on cloud-connected terminal architectures.
Market Dynamics
BaFin's evolving interpretation of PSD2 strong customer authentication is compressing hardware refresh cycles across German merchant networks, forcing terminal vendors to accelerate embedded security module upgrades ahead of planned replacement timelines.
Growth Catalysts
- EU PSD2 mandate:German acquirers must deploy terminals with certified SCA-compliant encryption by 2026 deadlines, creating mandatory replacement demand across retail and hospitality estates.
- Contactless transaction thresholds:Rising tap-to-pay limits across German card schemes are driving NFC reader upgrades in quick service restaurants and convenience stores.
- Bavaria retail density:Concentrated supermarket and specialty store networks in Munich and Nuremberg generate clustered procurement volumes for integrated POS-terminal estates.
Market Restraints
- Semiconductor supply concentration:Dependence on Asian foundries for secure element chips creates lead time volatility for German terminal manufacturers.
- GDPR compliance friction:Transaction data localization requirements limit cloud-connected terminal architectures, constraining software-integrated feature rollouts.
- Smartphone POS substitution:Soft-POS applications on standard Android devices threaten dedicated hardware margins in micro-merchant segments.
Strategic Opportunities
- North Rhine-Westphalia tourism corridors:Cologne and Düsseldorf event venues remain underpenetrated by mobile POS terminals for queue-busting deployments.
- EU AI Act compliance:Biometric authentication modules in self-service kiosks create premium pricing tiers for hospitality automation vendors.
- Terminal-as-a-service channels:Leasing models through German banking cooperatives lower capital barriers for mid-tier restaurant chains seeking integrated payment estates.
Industry Challenges
- EMV certification timelines:German terminal vendors face 6-12 month approval queues from card scheme laboratories, delaying product launches.
- Legacy ERP integration:SAP-dominant retail IT stacks in Germany require custom middleware development for cloud-native POS terminal connectivity.
- Embedded security engineering talent:Shortage of hardware cryptographers in Berlin and Frankfurt constrains R&D velocity for next-generation encryption modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany POS Terminal Market |
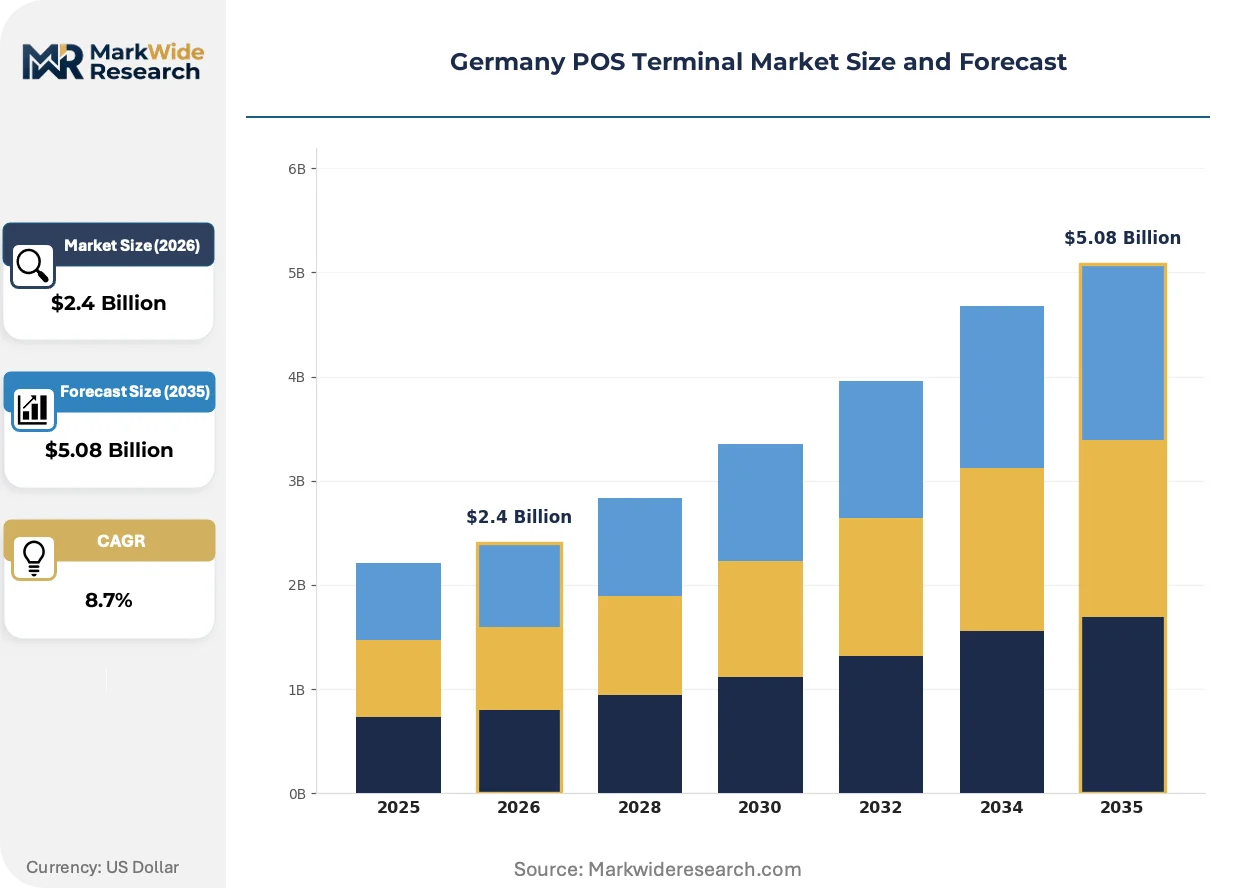
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminals, Mobile POS Terminals, Self-Service Kiosks, PIN Pads Technology: NFC, EMV Chip, Magnetic Stripe, QR Code, Bluetooth, Wi-Fi Application: Retail Stores, Hospitality, BFSI, Transportation, Entertainment, Government End User: Supermarkets, Specialty Stores, Quick Service Restaurants, Hotels, Banks, Event Venues |
| Companies Covered | NCR Voyix Corporation, SumUp Limited, Worldline SA (Ingenico), DATECS Ltd., Zettle (PayPal), Verifone Systems Inc., Diebold Nixdorf AG, Vectron Systems AG, PAX Technology Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany POS Terminal Market Shifts & Advancements
Payment terminal architecture is converging with software-defined platforms, enabling feature updates through remote deployment rather than hardware replacement cycles.
Android-based open payment platforms are collapsing the traditional boundary between proprietary terminal operating systems and merchant application ecosystems. German supermarket chains are adopting these systems to run inventory management and loyalty programs on shared hardware. This convergence is collapsing vendor lock-in advantages that historically protected incumbent terminal manufacturers.
The EU AI Act's risk classification framework is extending compliance obligations to biometric-enabled self-service terminals in German hospitality settings. Vendors must now document algorithmic decision pathways for age-verification and fraud-detection features. Full-service restaurant operators in Hamburg and Frankfurt are delaying kiosk deployments pending regulatory clarity on biometric data handling.
Merchant acquisition patterns are fragmenting as German savings banks and cooperative institutions build direct terminal leasing capabilities. Independent sales organizations that historically controlled distribution are losing volume to in-house procurement teams at retail chains. This disintermediation concentrates most visibly in Bavaria's dense supermarket networks, where centralized IT procurement now dominates terminal selection.
Germany POS Terminal Market Segmentation
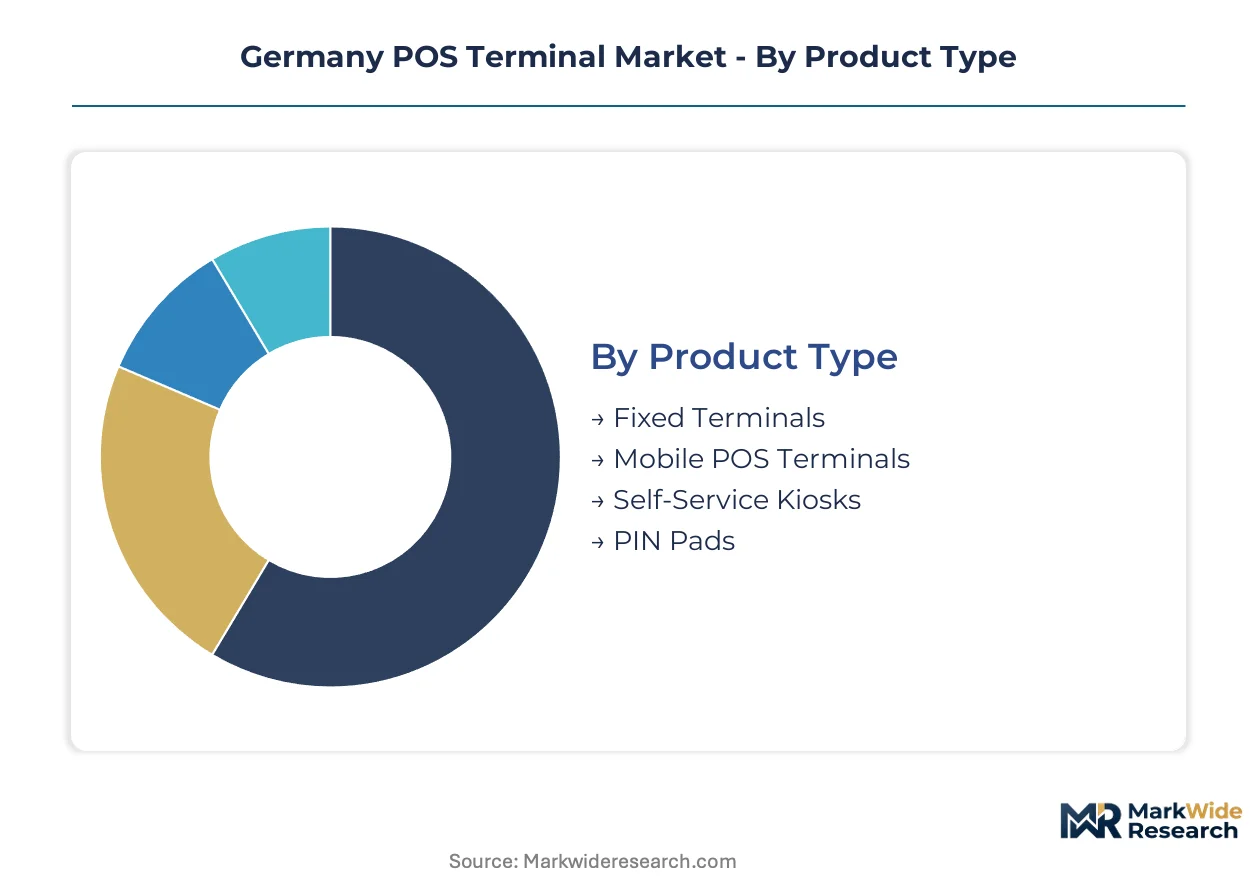
German merchant estates demand heterogeneous terminal configurations reflecting divergent transaction volumes, mobility requirements, and customer interaction models. Segmentation clarity enables hardware vendors to align R&D investment with procurement patterns across Bavaria's supermarket clusters and North Rhine-Westphalia's hospitality corridors.
Product Type:
The use-case spectrum spans high-volume fixed installations through portable queue-busting devices to fully automated self-service interfaces.
- Fixed Terminals:Countertop units with integrated receipt printers, cash drawers, and dual-screen merchant-customer displays anchor German supermarket checkout lanes. REWE and EDEKA central procurement teams specify IP54-rated enclosures for durability across high-frequency transaction environments.
- Mobile POS Terminals:Battery-powered handheld devices with 4G/LTE connectivity and integrated NFC readers enable tableside payment in Munich beer gardens and Cologne event venues. Quick service restaurant chains prioritize these for queue-busting flexibility during peak hours.
- Self-Service Kiosks:Freestanding touchscreen terminals with integrated card readers and receipt printers automate ordering in German fast-casual dining.
- PIN Pads:Compact card-reading peripherals without integrated processing capability supplement existing merchant systems.
Established volume favors Fixed Terminals; emerging adoption favors Mobile POS Terminals.
Technology:
Payment authentication methods stratify by security certification tier and transaction speed requirements.
- NFC:Contactless radio-frequency communication enabling tap-to-pay transactions under raised German card scheme limits. Bavarian convenience stores and Berlin transit operators drive concentrated deployment as contactless thresholds expand.
- EMV Chip:Europay-Mastercard-Visa standard chip-card authentication with dynamic cryptogram generation remains mandatory for German terminal certification. BaFin mandates embedded secure element compliance across all deployed hardware.
- Magnetic Stripe:Legacy card-swiping technology with static data encoding persists for backward compatibility with international cards.
- QR Code:Optical scanning for mobile wallet and loyalty program integration gains traction among German specialty retailers.
- Bluetooth:Short-range wireless pairing for peripheral connectivity in compact merchant setups.
- Wi-Fi:Local network connectivity for cloud-integrated terminal architectures, constrained by GDPR data localization requirements.
Certification mandates cement EMV Chip dominance; consumer preference acceleration elevates NFC expansion.
Application:
Sector-specific compliance obligations and customer throughput patterns shape terminal specification requirements.
- Retail Stores:High-volume checkout environments demanding durable hardware with integrated inventory system connectivity. German supermarket chains specify SAP-compatible middleware for ERP integration.
- Hospitality:Table-service and hotel front-desk deployments prioritize mobile form factors and multi-language interfaces. Frankfurt and Hamburg full-service restaurants drive biometric-enabled kiosk trials pending EU AI Act clarity.
- BFSI:Branch banking and insurance counter applications require enhanced encryption modules for high-value transactions.
- Transportation:Transit ticketing and fleet payment systems demand ruggedized outdoor-rated terminals.
- Entertainment:Stadium, cinema, and event venue deployments favor rapid-queue mobile terminals with offline transaction capability.
- Government:Municipal service payment points require certified accessibility compliance and audit-trail documentation.
Procurement concentration clusters in Retail Stores; Hospitality mobile deployment represents the steepest expansion trajectory.
End User:
Merchant scale and IT sophistication determine terminal-as-a-service versus capital purchase decisions.
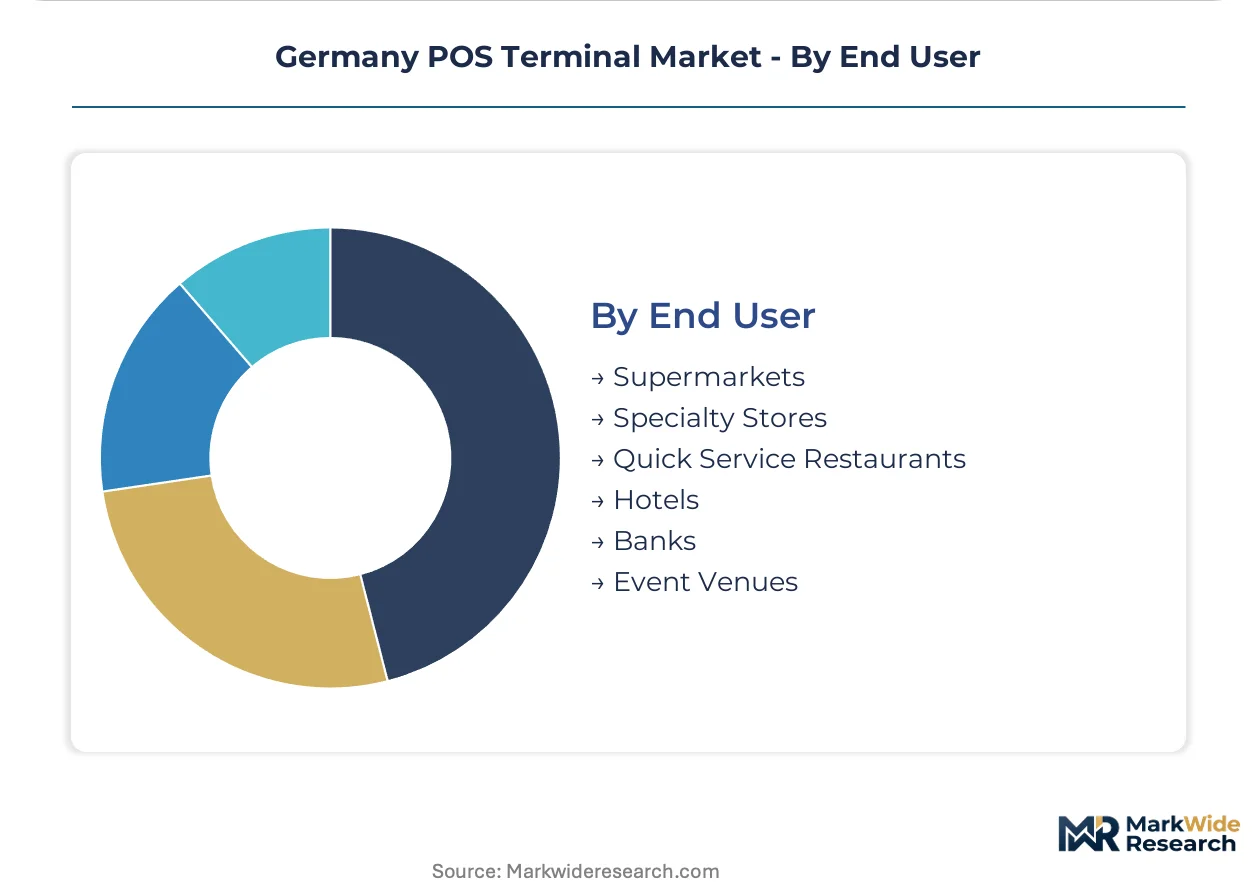
- Supermarkets:Centralized procurement by German retail cooperatives drives volume contracts for integrated fixed-terminal estates with loyalty program integration.
- Specialty Stores:Independent merchants and boutique operators favor leased mobile terminals with minimal technical integration requirements.
- Quick Service Restaurants:Drive-through and counter-service chains prioritize NFC-enabled speed with kitchen display system integration.
- Hotels:Property management system connectivity and multi-currency support differentiate hospitality-specific terminal configurations.
- Banks:Branch transformation projects consolidate counter hardware with video teller and self-service zone deployments.
- Event Venues:Temporary infrastructure demands rental-terminal logistics with rapid deployment and settlement capabilities.
Supermarket centralization sustains volume leadership; Event Venue mobility requirements are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Payment Services Directive and PSD2 strong customer authentication mandates are compressing hardware refresh cycles across German state-level merchant networks, with regulatory deadlines accelerating procurement timelines in high-density retail corridors.
Bavaria
Munich and Nuremberg anchor Germany's densest supermarket and specialty store networks, driving concentrated fixed-terminal procurement volumes. BaFin's evolving PSD2 interpretation forces embedded security module upgrades ahead of planned replacement timelines. The state's retail cooperatives centralize IT procurement for integrated POS-terminal estates with loyalty program connectivity.
North Rhine-Westphalia
Cologne and Düsseldorf event venues remain underpenetrated by mobile POS terminals for queue-busting deployments during peak tourism seasons. GDPR data localization requirements constrain cloud-connected terminal architectures for hospitality operators. The Rhine-Ruhr metropolitan cluster generates clustered demand from quick service restaurant chains prioritizing tableside payment flexibility.
Baden-Württemberg
Stuttgart's automotive-adjacent retail ecosystem demands ruggedized terminals for high-throughput parts and service operations. The state's manufacturing heritage shapes procurement preferences for durable hardware with SAP-compatible middleware integration. Karlsruhe's proximity to French border commerce drives multi-currency terminal specifications for cross-border retail.
Hesse
Frankfurt's financial services concentration sustains branch transformation projects consolidating counter hardware with self-service zone deployments. The city's status as a European banking hub elevates encryption requirements for high-value transaction processing. BaFin's headquarters proximity accelerates regulatory clarity on biometric-enabled terminal features for hospitality automation.
Berlin-Brandenburg
The capital's pop-up vendor density and event economy favor leased mobile terminals with minimal technical integration requirements. Berlin's startup ecosystem accelerates soft-POS application trials threatening dedicated hardware margins in micro-merchant segments. The region's fragmented independent retail base resists centralized procurement patterns visible in southern German states.
Germany POS Terminal Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hardware-software platforms with recurring revenue models displacing traditional capital purchase arrangements. Three strategic archetypes dominate: full-stack platform vendors with embedded finance partnerships, manufacturing-focused specialists with in-house cash-handling capabilities, and mobile-first form factor disruptors targeting micro-merchants. Competitive intensity concentrates on terminal-as-a-service leasing channels and SAP-compatible middleware development for ERP integration.
Among Germany-based fabricators, Diebold Nixdorf AG and Vectron Systems AG exemplify the manufacturing-specialist archetype with captive production of cash-handling modules. Worldline SA (Ingenico) occupies a position representing the full-stack platform model through embedded finance partnerships sustaining recurring revenue streams across supermarket chains. SumUp Limited anchors the mobile-first disruptor tier targeting specialty stores and pop-up vendors with minimal integration requirements.
| Leading Market Players |
|---|
| NCR Voyix Corporation |
| SumUp Limited |
| Worldline SA (Ingenico) |
| DATECS Ltd. |
| Zettle (PayPal) |
| Verifone Systems Inc. |
| Diebold Nixdorf AG |
| Vectron Systems AG |
| PAX Technology Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in secure element chip fabrication across Taiwanese and South Korean foundries is compressing supplier margins and forcing German terminal vendors toward premium pricing tiers for EMV-certified hardware. This utilization squeeze simultaneously accelerates leasing model adoption among mid-tier merchants seeking to bypass capital-intensive procurement cycles.
Pricing Analysis
Certification level (BaFin PSD2 SCA compliance, EMVCo L1/L2 approval) creates the primary spread between economy-grade peripherals and enterprise-integrated terminal estates. Pricing stratifies across premium biometric-enabled kiosks, standard countertop units with SAP middleware, and economy mobile readers for pop-up vendors. Cost compression in the economy tier is intensifying because soft-POS applications on consumer Android devices threaten dedicated hardware margins. Quick service restaurant chains exhibit highest price sensitivity due to thin operating margins, while German supermarket cooperatives prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Upstream feedstock for secure encryption modules draws from specialized semiconductor foundries concentrated in Taiwan, South Korea, and mainland China. German terminal assembly rests on imported secure element chips, NFC antenna substrates, and EMV-certified card reader mechanisms. Single-source vulnerability in advanced cryptography chip supply creates procurement risk exposure for vendors targeting BaFin's accelerated compliance deadlines. Distribution runs through banking cooperative leasing channels and independent sales organization networks serving fragmented specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German POS terminal demand is cycling through a regulatory-mandated replacement wave as PSD2 SCA deadlines compress hardware refresh timelines across merchant estates.
For Market Incumbents: Insulate recurring revenue streams by deepening embedded finance partnerships with German retail cooperatives and accelerating terminal-as-a-service subscription conversions. Prioritize captive secure element sourcing through backward integration into certified semiconductor procurement channels to offset Asian foundry concentration risk. Defend against mobile-first disruptors by bundling SAP-compatible middleware with fixed-terminal deployments in Bavaria's supermarket clusters. For New Entrants and Emerging Players: North Rhine-Westphalia's event venue corridors remain underpenetrated by queue-busting mobile terminals during peak tourism seasons. Target Cologne and Düsseldorf hospitality operators with rapid-deployment rental logistics and offline transaction capability for temporary infrastructure. Enter through German banking cooperative leasing channels rather than competing against established independent sales organization networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance-mandated replacement cycles create predictable demand visibility independent of discretionary merchant IT spending. Target acquisition profiles should emphasize vendors with certified biometric module pipelines and existing BaFin relationship infrastructure. Monitor EU AI Act implementation timelines as the critical inflection signal for hospitality automation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal-as-a-Service Platform Launch | Converts capital expenditure to recurring revenue across German mid-tier restaurant chains. |
| Biometric Authentication Module Certification | Unlocks premium pricing tiers for self-service kiosks pending EU AI Act clarity. |
| SAP-Compatible Middleware Development | Enables ERP integration for supermarket cooperatives dominating Bavaria procurement. |
| Secure Element Supply Agreement | Reduces lead time volatility from Taiwanese and South Korean foundry concentration. |
| Banking Cooperative Distribution Partnership | Disintermediates independent sales organizations controlling legacy merchant acquisition. |
Research Methodology
Cross-validation between executive interviews at German terminal manufacturers and secondary analysis of BaFin regulatory filings anchors the qualitative findings. Primary fieldwork encompassed hardware engineering directors, procurement leads at retail cooperatives, channel managers at banking institutions, and regulatory compliance officers. Secondary sources included EU PSD2 implementation guidance, EMVCo certification databases, German retail association technology surveys, and customs records for secure element chip imports. Bottom-up merchant estate sizing triangulates against top-down payment volume projections.
Calibration against historical replacement cycle data and regulatory deadline impacts shapes the analytical framework across the projection horizon. Segmentation dimensions encompass product type, authentication technology, application sector, and end-user scale. CAGRs derive from installed base evolution modeling and compliance-driven refresh elasticity. Forecast inputs incorporate BaFin supervisory guidance evolution and EU AI Act risk classification timelines for biometric-enabled terminals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by soft-POS platform providers or accelerated EU regulatory shifts would shift outcomes beyond modeled ranges. Cross-checking against German retail technology expenditure surveys and banking cooperative leasing volume disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
China Forex Cards Market
Payments
Mobile Card Reader Market
Payments
Germany Payments Market
Payments
Fuel Cards Market
Payments
Smart Payment Market
Payments
Norway POS Terminals Market
Payments
Latin America Retail Cash Management Market
Payments
B2B Payments Market
Payments
Online Payment Gateway Market
Payments
South Korea Mobile Payment Market
Payments
India POS Terminals Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Canada Real Time Payments Market
Payments
Spain Mobile Payment Market
Payments
Hungary POS Terminal Market