
 Sweden Payments Market | 2026-2036
Sweden Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Payments Market Analytics
Merchant acquiring channels is rewriting competitive dynamics across Swedish retail banking. Adyen N.V. leverages unified commerce technology to anchor premium enterprise relationships. Klarna Bank AB differentiates through buy-now-pay-later integration embedded at checkout. Trustly Group AB specializes in account-to-account transfers, bypassing card networks for direct bank settlement.
Sweden Payments encompasses electronic fund transfer systems, clearing infrastructure, and consumer-facing instruments facilitating commercial exchange, operating through ISO 20022 messaging protocols and real-time gross settlement rails managed by RIX. The primary commercial purpose centers on reducing friction in domestic and cross-border value exchange while minimizing counterparty risk. Mobile payments and digital wallets capture expanding transaction volume as contactless adoption saturates urban centers. Credit card and debit card segments retain substantial merchant service revenue pools despite fintech displacement. Payment processors and fintech service providers compete most intensely for merchant acquisition economics.
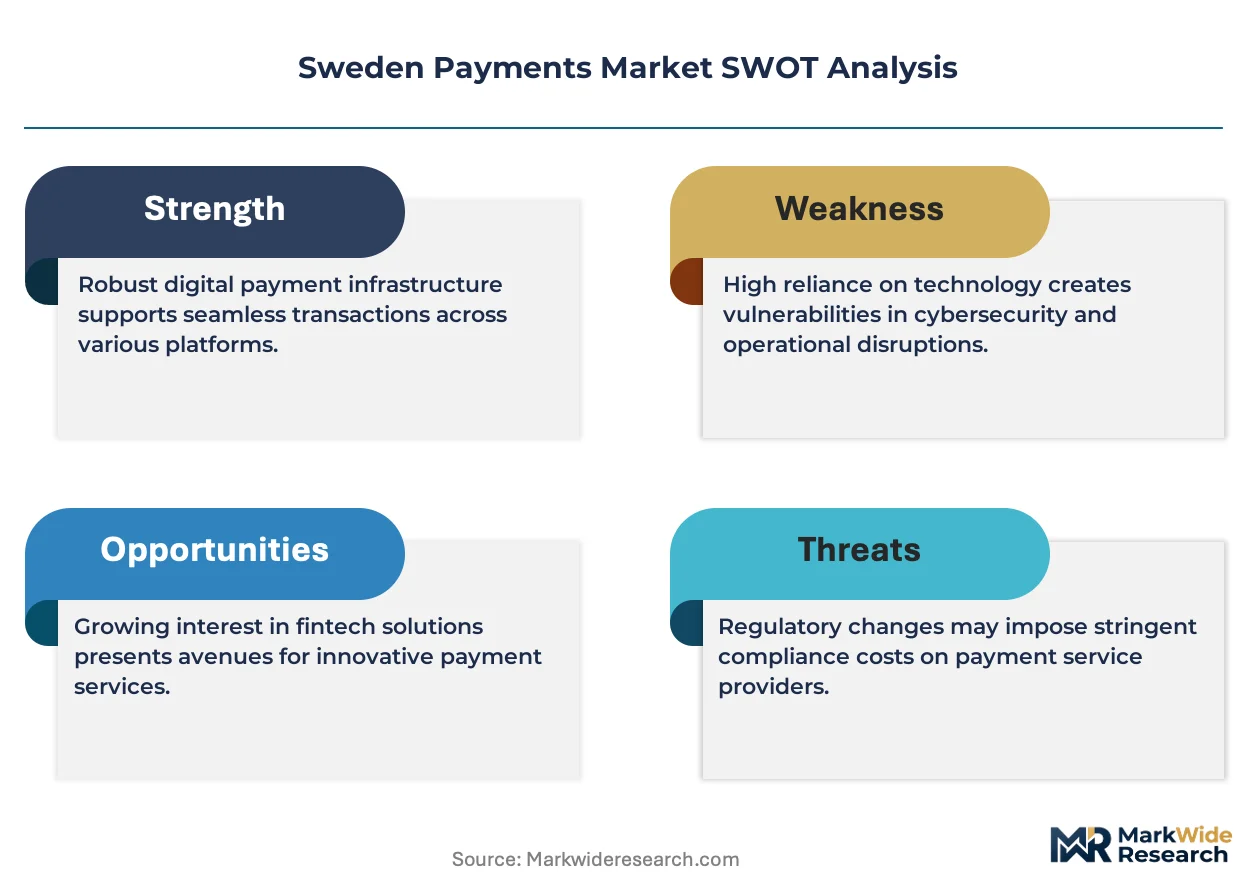
Finansinspektionen supervises payment institution licensing, while the Swedish Payment Services Act transposes PSD2 requirements for open banking access and strong customer authentication. Sveriges Riksbank governs settlement finality and central bank digital currency exploration, shaping infrastructure investment priorities. The European Banking Authority's technical standards on secure communication further constrain product architecture decisions. Stakeholders must monitor regulatory clarity on instant payment pricing caps and CBDC interoperability mandates to align platform roadmaps with evolving compliance obligations.
Market Dynamics
Real-time settlement infrastructure under Sveriges Riksbank oversight is compressing transaction friction and redistributing value capture from traditional card networks to account-to-account rails. This structural shift intensifies competition among payment processors while forcing merchant acquirers to differentiate through embedded finance capabilities.
Growth Catalysts
- PSD2 Strong Customer Authentication:Regulatory mandates for open banking access have accelerated API-based payment initiation across Swedish e-commerce platforms.
- Stockholm Fintech Cluster Density:Geographic concentration of technical talent and venture capital is spawning successive generations of payment infrastructure startups.
- Contactless Terminal Saturation:Urban merchant hardware refresh cycles are completing, enabling tap-to-pay volume expansion across retail and transit use cases.
Market Restraints
- Interchange Fee Compression:EU-wide caps on merchant service charges constrain revenue pools for card-issuing institutions.
- Banking Infrastructure Concentration:Clearing and settlement dependence on RIX creates single-point-of-failure risk for real-time payment availability.
- Consumer Data Localization Requirements:GDPR-derived storage obligations increase operational complexity for cross-border payment service providers.
Strategic Opportunities
- Nordic Cross-Border Corridors:Underpenetrated instant payment linkages between Sweden, Norway, and Denmark offer white space for regional settlement networks.
- Account-to-Account Commerce:Open banking APIs enable direct bank payment integration at checkout, bypassing card network economics entirely.
- Central Bank Digital Currency Pilots:Sveriges Riksbank's e-krona exploration creates early-mover positioning for infrastructure providers.
Industry Challenges
- Legacy Core System Integration:Incumbent banks face technical debt burdens when connecting ISO 20022 messaging to decades-old account platforms.
- Certification Timeline Uncertainty:Finansinspektionen licensing procedures for payment institutions lack standardized duration predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Payments Market |
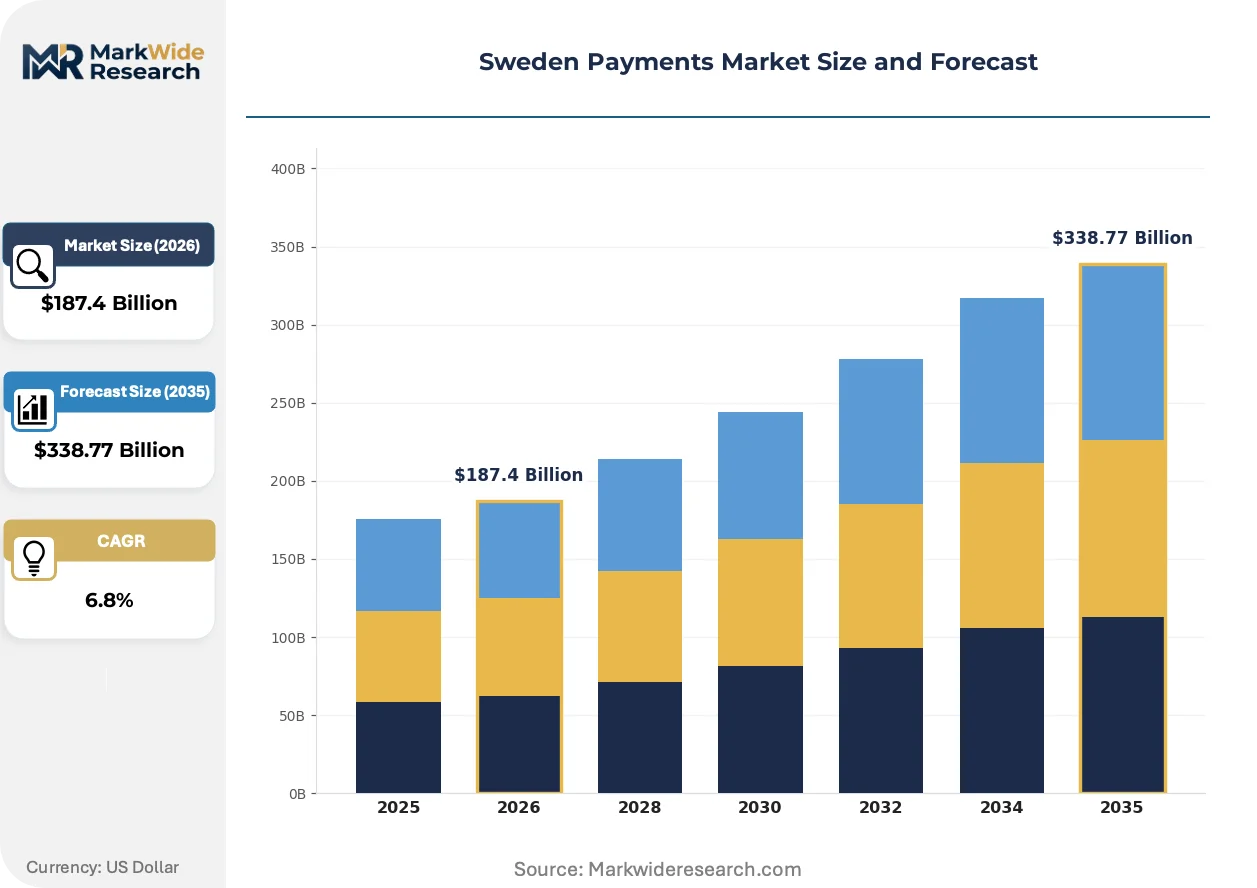
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Payments, Digital Wallets Transaction Method: Online, In-Store, Contactless, Remote End User: Consumers, Merchants, Corporations, Government Service Provider: Payment Processors, Banks, Fintechs, Payment Gateways |
| Companies Covered | Adyen N.V., Nets A/S, Klarna Bank AB, Mastercard Incorporated, Visa Inc., Stripe, Inc., Worldpay, Inc., Trustly Group AB, PayPal Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Payments Market Evolving Landscape
Payment infrastructure is fragmenting across specialized rails as merchants demand settlement speed and cost optimization. Technical architectures are diverging between real-time account-based systems and residual card network dependence.
Request-to-pay messaging protocols are rendering obsolete traditional invoice-based B2B reconciliation workflows. Swedish enterprise treasury departments are adopting these ISO 20022-compliant standards for automated accounts payable matching. The technology is rendering obsolete manual payment reference tracking and multi-day settlement delays in intercompany transfers.
The Swedish Payment Services Act transposes PSD2 technical standards that mandate secure customer authentication for electronic transactions. Finansinspektionen enforcement of these requirements has elevated operational compliance costs for smaller payment institutions. Neobanks and fintech challengers are responding by pooling authentication infrastructure through third-party specialized providers.
Merchant procurement of payment acceptance is consolidating toward unified commerce platforms that collapse online, in-store, and mobile channels into single technical integrations. Traditional point-of-sale hardware vendors are losing standalone contracts to software-embedded payment orchestration layers. This consolidation pattern is most visible among Stockholm-based mid-market retailers replacing fragmented legacy terminal estates.
Sweden Payments Market Segmentation
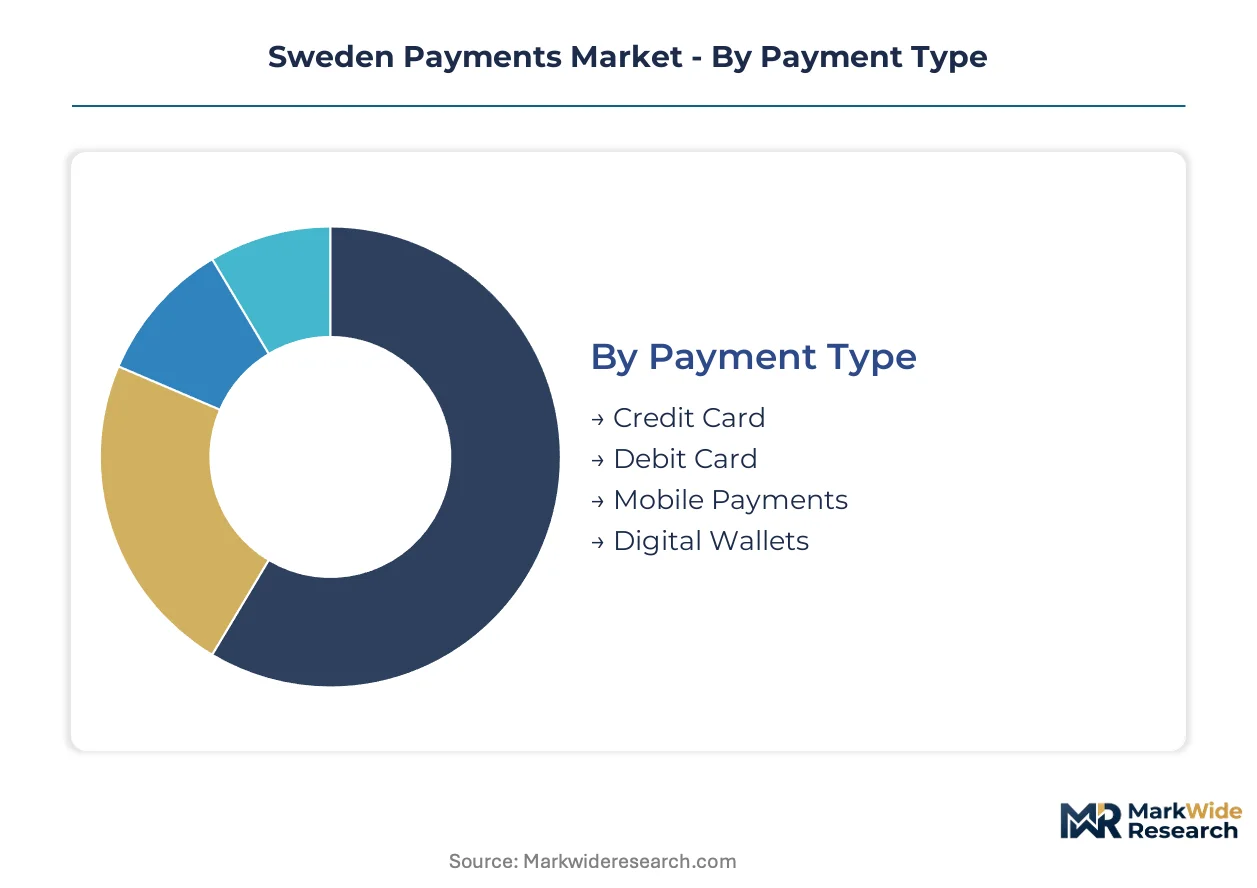
Payment infrastructure in Sweden fragments across multiple technical and commercial dimensions, each with distinct investment cycles and margin profiles. Understanding these divisions reveals where value capture concentrates and which rails are displacing legacy systems.
Payment Type:
Transaction velocity varies dramatically across instruments, with mobile and wallet-based methods turning over fastest while card products retain the deepest merchant integration.
- Credit Card:Revolving credit instruments carrying interchange fees of 0.3-1.4% under EU caps, concentrated in travel, hospitality, and high-ticket retail segments where consumer financing flexibility outweighs cost sensitivity.
- Debit Card:Direct account-linked instruments dominating Stockholm's transit systems and grocery networks, with instant authorization through BankID authentication creating stickiness in everyday purchasing.
- Mobile Payments:Smartphone-native transactions leveraging Swish infrastructure for peer-to-peer and merchant settlement, expanding fastest in urban transit and quick-service restaurant environments where speed trumps loyalty program integration.
- Digital Wallets:Tokenized credential storage enabling one-click checkout across e-commerce platforms, penetrating deepest among Stockholm fintech cluster merchants seeking reduced cart abandonment.
Debit card volumes anchor the transaction base while mobile payments gain share at the steepest rate.
Transaction Method:
Channel economics diverge sharply between physical and digital touchpoints, with infrastructure investment requirements determining competitive entry barriers.
- Online:Browser and app-based checkout flows requiring PCI-DSS compliance and 3D Secure authentication, concentrated in fashion, electronics, and digital services where Swedish e-commerce merchants drive API standardization.
- In-Store:Traditional point-of-sale terminal acceptance with EMV chip and PIN fallback, retaining dominance in pharmacy, automotive, and professional services where invoice integration matters.
- Contactless:Near-field communication tap-to-pay under 400 SEK threshold, saturating Stockholm convenience retail and public transit through SL access card convergence.
- Remote:Card-not-present and account-to-account transactions initiated without physical proximity, expanding in subscription billing and B2B procurement where request-to-pay messaging automates reconciliation.
In-store transactions anchor the volume base while contactless methods gain share at the steepest rate.
End User:
Customer sophistication determines service complexity requirements, with corporate and government segments demanding integration depth that consumer-facing providers rarely match.
- Consumers:Individual purchasers prioritizing convenience and security, driving Swish adoption for splitting restaurant bills and marketplace purchases through mobile number identification.
- Merchants:Retail and service businesses procuring acceptance infrastructure, with Stockholm mid-market retailers consolidating previously fragmented terminal estates toward unified commerce platforms.
- Corporations:Enterprise treasury departments managing cross-border liquidity, adopting ISO 20022 request-to-pay standards for automated accounts payable matching and intercompany settlement.
- Government:Public sector entities disbursing benefits and collecting taxes, with Skatteverket driving real-time settlement requirements for VAT refunds and social insurance payments.
Consumer transactions anchor the volume base while corporate adoption gains share at the steepest rate.
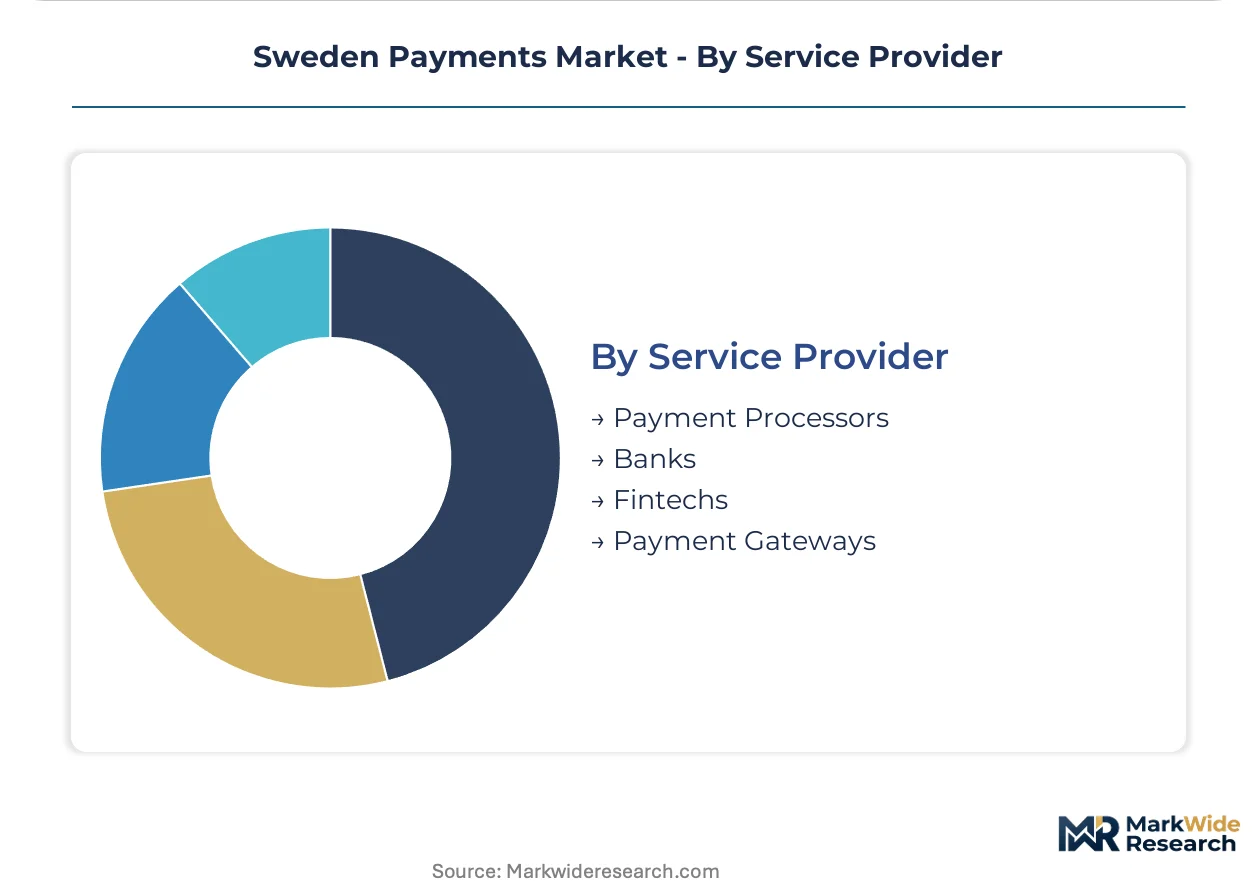
Service Provider:
Provider type determines regulatory burden and capital intensity, with licensed institutions facing Finansinspektionen supervision that fintech challengers navigate through partnership structures.
- Payment Processors:Technical intermediaries managing authorization, clearing, and settlement workflows, competing for merchant acquiring economics through unified commerce platform consolidation.
- Banks:Deposit-taking institutions with direct RIX settlement access, leveraging trust advantages in corporate treasury relationships while facing technical debt from legacy core system integration.
- Fintechs:Technology-native challengers embedding finance into commerce workflows, with buy-now-pay-later and account-to-account specialists bypassing card network economics entirely.
- Payment Gateways:Technical connectors linking merchant systems to acquiring banks, losing standalone contracts to processor-integrated orchestration layers in Stockholm's e-commerce cluster.
Bank-provided services anchor the volume base while fintech alternatives gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's real-time settlement infrastructure under Sveriges Riksbank oversight is attracting cross-border payment service providers seeking Nordic corridor expansion. The country's PSD2 implementation through the Swedish Payment Services Act creates regulatory harmonization pressures across neighboring jurisdictions.
Stockholm
Swish mobile payment adoption concentrates demand in Sweden's capital, where transit integration through SL access cards accelerates contactless volume. Finansinspektionen licensing requirements shape fintech clustering patterns in the urban core. The Stockholm fintech ecosystem anchors merchant acquiring innovation, with mid-market retailers consolidating fragmented terminal estates toward unified commerce platforms.
Gothenburg
Port logistics and manufacturing supply chains drive B2B payment automation demand in Sweden's second-largest metropolitan area. Corporate treasury departments adopt ISO 20022 request-to-pay standards for intercompany settlement. The Gothenburg industrial corridor hosts enterprise payment infrastructure deployments, with automotive and shipping sectors prioritizing real-time reconciliation workflows.
Malmö
Cross-border commerce with Denmark through the Öresund Bridge generates merchant acquiring competition in Sweden's southern gateway. The Swedish Payment Services Act's strong customer authentication mandates elevate operational compliance costs for payment institutions. Malmö's proximity to Copenhagen creates dual-jurisdiction service provider positioning, with fintech challengers leveraging open banking APIs for account-to-account commerce.
Uppsala
University-driven research commercialization spurs early-stage payment technology development in this academic hub. Sveriges Riksbank's e-krona exploration attracts infrastructure pilot programs to the region. Uppsala's proximity to Stockholm enables talent arbitrage, with technical specialists contributing to central bank digital currency architecture design.
Sweden Payments Market Competitive Landscape
On the supply side, the industry is consolidating around unified commerce platforms that collapse online, in-store, and mobile channels into single technical integrations. Payment processors compete for merchant acquiring economics while fintech challengers bypass card network rails entirely. Two strategic archetypes dominate: account-to-account specialists leveraging open banking APIs, and embedded finance providers integrating payment acceptance into commerce workflows. Competitive moves center on strategic partnerships with merchant platforms and technology licensing for real-time settlement infrastructure.
Within the account-to-account tier, Trustly Group AB and Klarna Bank AB exemplify divergent specialization paths. Adyen N.V. anchors the unified commerce platform archetype, serving premium enterprise relationships through technical integration depth. These Amsterdam-based and Swedish-registered entities occupy positions that reflect the market's structural shift from card network dependence to direct bank settlement rails.
| Leading Market Players |
|---|
| Adyen N.V. |
| Nets A/S |
| Klarna Bank AB |
| Mastercard Incorporated |
| Visa Inc. |
| Stripe, Inc. |
| Worldpay, Inc. |
| Trustly Group AB |
| PayPal Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Netherlands-based payment processor concentration upstream anchors margin capture at the unified commerce platform tier, while Swedish merchant acquirers face compression from account-to-account rail displacement. This structural asymmetry concentrates pricing power among technical intermediaries with direct RIX settlement access.
Pricing Analysis
Volume-discount tiering structures dominate merchant acquiring contracts, with enterprise relationships commanding sub-basis-point economics unavailable to mid-market retailers. Price differentiation rests on ISO 20022 messaging certification and real-time settlement guarantees, with Swish infrastructure access creating tier separation. Cost compression in debit card processing is intensifying because Trustly and Klarna bypass interchange entirely. Corporate treasury departments show least price sensitivity due to reconciliation automation value, while Stockholm mid-market retailers exhibit highest sensitivity to per-transaction fees.
Supply Chain Analysis
EU dual-use technology controls on cryptographic authentication modules limit flows from non-EEA jurisdictions into Swedish payment infrastructure. Geographic supply concentration centers on Netherlands, Germany, and Estonia for core processing hardware, with software dependencies drawing from Ireland and UK cloud regions. Raw material dependencies include EMV chip modules, NFC antenna substrates, and PCI-DSS certified server racks. Single-source vulnerability sits with RIX real-time settlement availability. Distribution runs through licensed payment institutions under Finansinspektionen supervision rather than direct merchant relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's payment market represents a platform-economics inflection where open banking API standardization is collapsing traditional merchant acquiring moats. The e-krona exploration by Sveriges Riksbank signals interoperability regime change that will redistribute infrastructure rents.
For Market Incumbents: Build regulatory certification moats through advanced Finansinspektionen licensing for payment institution operations. Incumbent banks must accelerate legacy core system replacement to maintain RIX settlement access against fintech challengers. Defensive consolidation should prioritize ISO 20022 messaging infrastructure investments. Channel control through direct merchant API relationships offers the strongest defensive lever against account-to-account displacement.
For New Entrants and Emerging Players: Establish a beachhead in Nordic cross-border B2B corridors where request-to-pay automation remains underpenetrated. White-space targets include corporate treasury integration for mid-market manufacturers in Gothenburg and intercompany settlement for Öresund Bridge commerce. The most penetrable segment is account-to-account checkout for Stockholm e-commerce merchants seeking reduced cart abandonment. Go-to-market positioning should emphasize direct bank settlement cost advantages over card network economics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across payment gateway infrastructure as software-embedded orchestration displaces standalone hardware. Long-term viability favors fintech challengers with embedded finance capabilities and unified commerce platform architecture. Acquisition targets should display open banking API integration depth and Finansinspektionen licensing completion. The signal to watch as inflection indicator is Sveriges Riksbank e-krona pilot program commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified commerce consolidation collapses fragmented terminal estates for Stockholm retailers. |
| Regulatory Certification Investment | Finansinspektionen licensing completion creates defensible positioning against unlicensed challengers. |
| Strategic Partnership | Swish infrastructure access agreements concentrate mobile payment volume in urban transit corridors. |
| Acquisition of Specialist Firm | Account-to-account technology targets bypass card network economics entirely. |
| Geographic Expansion | Nordic corridor linkages between Sweden, Norway, and Denmark offer white-space settlement networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment institution executives, merchant acquiring specialists, corporate treasury directors, and Finansinspektionen regulatory affairs leads. Secondary validation drew from Sveriges Riksbank payment statistics, EU PSD2 implementation reports, SEC filings of listed payment processors, and Nordic central bank clearing data. Bottom-up transaction volume modeling triangulated against top-down GDP-linked payment flow estimates.
Calibration approaches anchored volume projections to observed Swish adoption curves and contactless terminal saturation patterns across the analysis window. Segmentation dimensions modeled include payment instrument type, transaction channel, end-user category, and service provider regulatory status. CAGRs derived from historical growth rate convergence with infrastructure capacity constraints. Industry-specific inputs incorporated RIX real-time settlement volume trends and open banking API call growth rates.
Macroeconomic conditions sit as an overlay; deviation in Swedish consumer spending velocity or EUR/SEK exchange rate stability would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and infrastructure investment continuity. Material shifts in e-krona pilot program scope or instant payment pricing cap implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Virtual Cards Market
Payments
Latin America Payment Gateway Market
Payments
Credit Card Issuance Services Market
Payments
Canada Payments Market
Payments
North America POS Terminal Market
Payments
Transaction Monitoring Market
Payments
Forex Cards Market
Payments
Asia-Pacific Payments Market
Payments
United States POS Terminals Market
Payments
Convergent Billing Market
Payments
United Kingdom Mobile Payments Market
Payments
Payment Instruments Market
Payments
Greece POS Terminals Market
Payments
Global Gift Card Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Netherlands POS Terminal Market