
 Premium Finance Market | 2026-2036
Premium Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Finance Market Analysis
Asset-light premium financing models are rewriting competitive dynamics in commercial insurance distribution. AFCO Credit Corporation leverages its captive agency relationships to sustain dominant positions in property and casualty premium funding. JPMorgan Chase & Co. anchors institutional-grade credit facilities for high-value life insurance transactions. IPFS Corporation specializes in technology-integrated servicing platforms that reduce operational friction for independent agents.
Premium finance encompasses third-party lending arrangements where borrowers obtain funds specifically to cover insurance premium obligations, typically structured as short-term installment contracts secured by the underlying policy's unearned premium reserves. The mechanism functions as a working capital bridge, converting lump-sum premium payments into manageable periodic outflows while preserving policy coverage continuity. Term financing and premium financing service categories command the largest transaction volumes, though credit facilities for high net worth individuals represent the fastest-expanding margin pool as estate planning complexity intensifies. Life insurance premium types generate the most concentrated demand from institutional funding sources, while property insurance segments attract broader participation from banks and private equity vehicles.
The National Association of Insurance Commissioners model acts shape permissible rate structures and disclosure protocols across US jurisdictions, while state banking regulators supervise non-bank premium finance company licensing and capital requirements. The SEC monitors securitization activities when premium receivables enter structured finance markets, constraining funding source diversification for smaller originators. Stakeholders must track evolving state rate-cap legislation and assess how digital servicing investments alter customer acquisition economics across client type segments.
Market Dynamics
State-level rate-cap legislation across the southeastern United States is compressing origination margins and forcing premium finance companies toward technology-intensive servicing models that reduce operational drag.
Growth Catalysts
- Commercial Property Cost Burdens:Hurricane-exposed commercial property owners in Florida, Louisiana, and Texas face escalating insurance premiums. Installment-based premium structures convert unmanageable lump-sum obligations into working capital bridges.
- NAIC Model Act Harmonization:The National Association of Insurance Commissioners disclosure protocols are standardizing permissible rate structures across multiple US jurisdictions. This reduces compliance fragmentation for multi-state originators.
- Life Insurance Estate Planning Complexity:High net worth individuals deploy premium financing to preserve liquidity for intergenerational wealth transfers. Institutional credit facilities from banking partners concentrate in this margin pool.
Market Restraints
- Funding Source Concentration:Bank-dependent originators face repricing risk when Federal Reserve policy shifts alter wholesale borrowing costs. Smaller premium finance companies lack balance sheet depth to weather rate volatility.
- Securitization Constraints:SEC oversight of premium receivable securitizations limits structured finance access for non-bank originators below institutional scale thresholds.
- Policy Cancellation Risk:Unearned premium reserves serve as primary collateral. Carrier insolvency or mid-term cancellation triggers immediate loan acceleration and recovery uncertainty.
Strategic Opportunities
- Independent Agent Channel Digitization:Technology-integrated servicing platforms reduce friction for independent agents who lack captive finance relationships. API-enabled origination workflows compress decision timelines from days to hours.
- Mid-Market Enterprise Penetration:Commercial policyholders between small business and large corporate tiers remain underserved. Embedded finance partnerships with managing general agents unlock this white space.
- State Banking Charter Optimization:Premium finance companies licensed under state banking frameworks access broader funding diversification than pure insurance-regulated entities.
Industry Challenges
- Legacy System Integration:Established originators operate on decades-old loan servicing infrastructure. API migration requires sustained capital commitment without immediate revenue recognition.
- Compliance Talent Scarcity:Multi-jurisdictional rate-cap monitoring demands specialized legal and regulatory operations functions. Compensation inflation in this skill segment outpaces origination margin compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Finance Market |
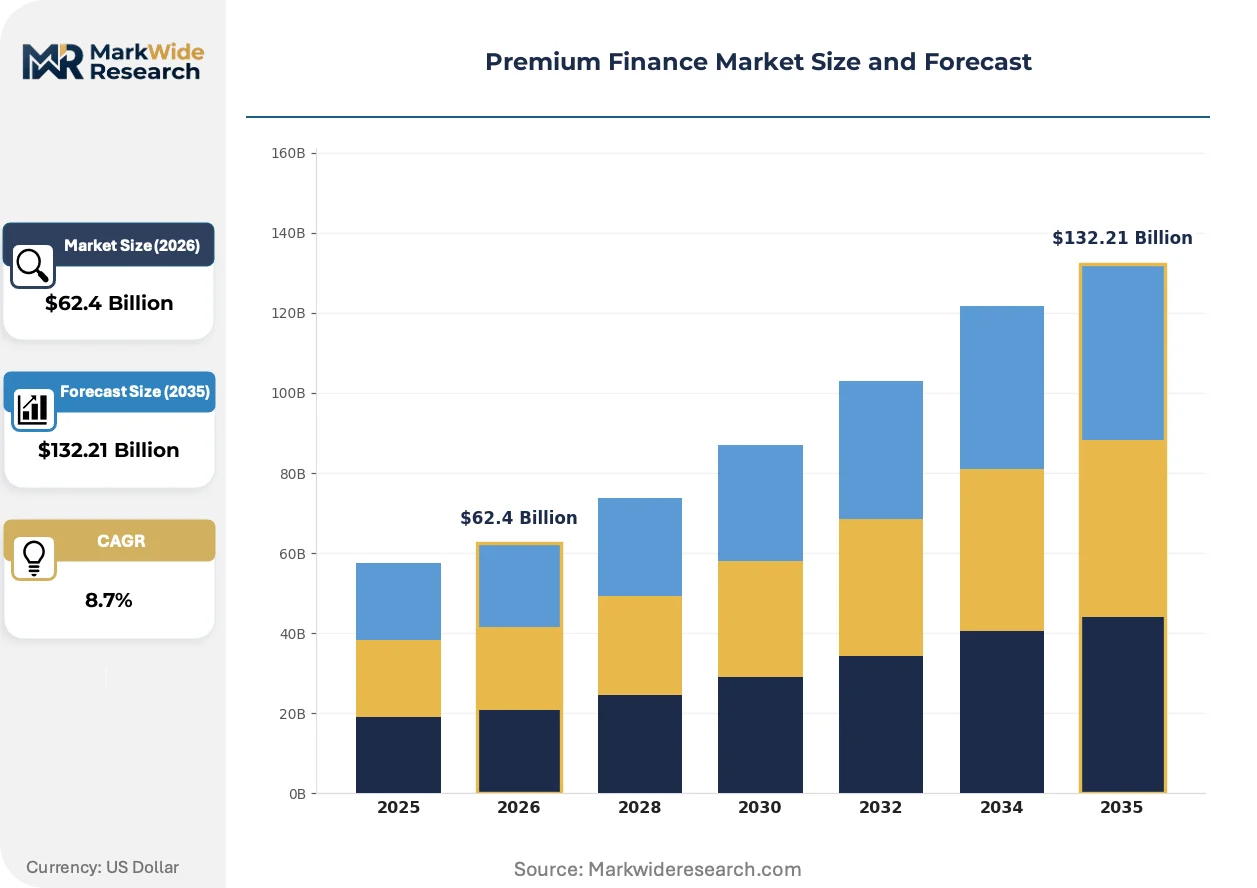
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Term Financing, Premium Financing, Credit Facility, Debt Financing Client Type: High Net Worth Individuals, Corporations, Estates, Trusts Funding Source: Institutional Investors, Private Equity, Family Offices, Banks Premium Type: Life Insurance, Property Insurance, Liability Insurance, Health Insurance |
| Companies Covered | JPMorgan Chase & Co., AFCO Credit Corporation, IPFS Corporation, Valley National Bancorp, ARI Financial Group, US Premium Finance, Lincoln National Corporation, Standard Premium Finance Holdings, Agile Premium Finance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Finance Market Emerging Trajectories
Digital origination infrastructure is displacing paper-based premium finance workflows across independent agency distribution. Automation investments concentrate where disclosure compliance and credit decision velocity intersect.
Real-time premium quote-to-bind APIs are rendering obsolete the traditional 48-to-72-hour credit approval cycle. Independent agents in Florida and Texas adopt these integrations fastest. The compressed timeline is rendering obsolete the competitive advantage of captive finance relationships that historically dominated agency placement decisions.
State-level disclosure requirement tightening under NAIC-influenced legislation mandates itemized APR presentation and cooling-off period standardization. Industrial consequence falls heaviest on non-bank premium finance companies with limited compliance infrastructure. Multi-state originators respond by centralizing regulatory operations in Nashville and Dallas legal hubs.
Mid-market commercial buyers now expect premium financing embedded at point-of-quote rather than broker-referred post-bind. Managing general agents in the southeastern United States displace standalone finance company websites with white-labeled installment options. This behavioral shift is most visible among contractors and property managers facing spring renewal concentration.
Premium Finance Market Segmentation
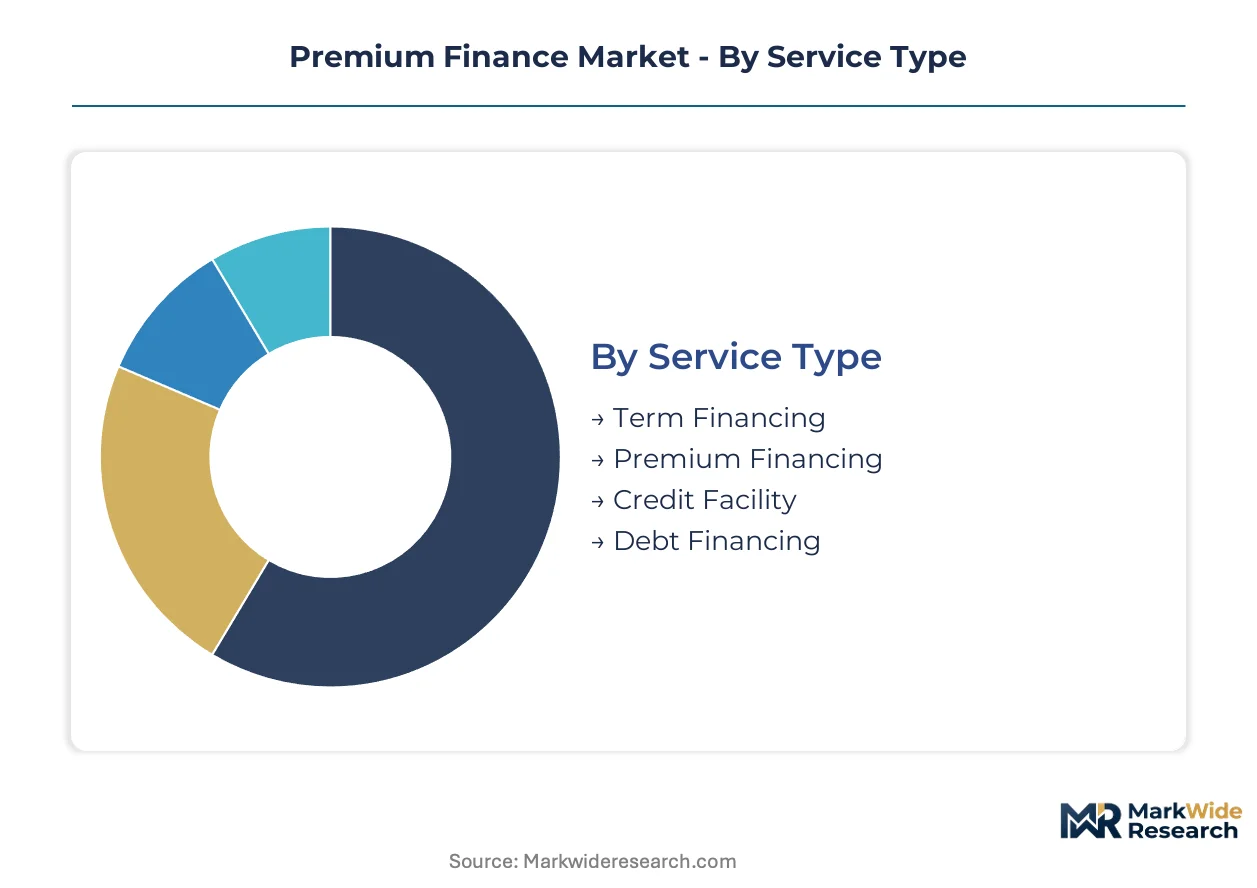
Premium finance market segmentation reveals divergent capital requirements, regulatory exposures, and servicing complexity across client profiles and policy collateral types. Understanding these structural divisions enables originators to align funding sources with risk-return profiles and compliance obligations.
Service Type:
Mature installment structures dominate transaction flow, while emerging digital-native formats reshape origination economics.
- Term Financing:Fixed-duration contracts amortize premium obligations across 3-to-12-month intervals with unearned premium reserves securing principal recovery. Commercial property owners in Florida and Louisiana deploy these structures most intensively as hurricane-exposed premiums escalate beyond working capital thresholds.
- Premium Financing:Short-term revolving facilities match policy renewal cycles with accelerated payoff schedules tied to carrier billing dates. Independent agents in Texas and Georgia adopt API-enabled platforms that compress decision timelines from days to hours, displacing traditional captive finance relationships.
- Credit Facility:Multi-draw arrangements serve high net worth individuals with estate planning liquidity requirements.
- Debt Financing:Securitized premium receivables access institutional capital markets subject to SEC oversight constraints.
Term Financing retains volume leadership; Premium Financing holds the steepest expansion curve.
Client Type:
Cost tier stratification separates mass-market commercial borrowers from capital-intensive private wealth segments with divergent collateral and servicing requirements.
- High Net Worth Individuals:Ultra-liquid borrowers deploy premium financing to preserve intergenerational wealth transfer capacity without policy lapse risk. JPMorgan Chase anchors institutional-grade credit facilities concentrated in this margin pool where estate planning complexity intensifies demand.
- Corporations:Mid-market enterprises between small business and large corporate tiers remain underserved by traditional captive finance relationships. Embedded finance partnerships with managing general agents unlock this white space as contractors and property managers face spring renewal concentration.
- Estates:Post-decedent liquidity vehicles bridge tax obligation timing mismatches.
- Trusts:Fiduciary structures require specialized compliance documentation and extended legal review cycles.
Corporations dominate transaction volume; High Net Worth Individuals generate the highest margin per dollar deployed.
Funding Source:
Supply concentration in banking channels creates repricing vulnerability when Federal Reserve policy shifts alter wholesale borrowing costs.
- Institutional Investors:Pension funds and insurance company general accounts purchase whole loan portfolios or participate in securitization tranches. These participants concentrate in life insurance premium types where collateral stability and predictable duration match liability-driven investment mandates.
- Private Equity:Asset-light premium financing models attract sponsor capital seeking distribution infrastructure roll-ups. IPFS Corporation technology-integrated servicing platforms reduce operational friction for independent agents, creating acquisition targets for operational value creation.
- Family Offices:Direct lending programs seek yield pickup over public fixed income with bespoke collateral structures.
- Banks:Balance sheet-dependent originators face margin compression when rate volatility transmits through wholesale funding markets.
Banks retain structural dominance in deployment capacity; Private Equity is expanding most quickly through platform consolidation.
Premium Type:
Application-driven segmentation separates mortality-based collateral from catastrophe-exposed property risks with divergent regulatory treatment.
- Life Insurance:Level premium obligations and guaranteed cash values create predictable collateral coverage ratios. Institutional funding sources concentrate here as estate planning complexity intensifies demand from high net worth individuals seeking liquidity preservation.
- Property Insurance:Hurricane-exposed commercial risks in the southeastern United States generate accelerating demand for installment structures. AFCO Credit Corporation leverages captive agency relationships to sustain dominant positions in this segment despite rate-cap compression.
- Liability Insurance:Claims-made policy forms introduce mid-term cancellation risk affecting collateral recovery timelines.
- Health Insurance:Shorter policy durations and regulatory scrutiny limit premium finance penetration.
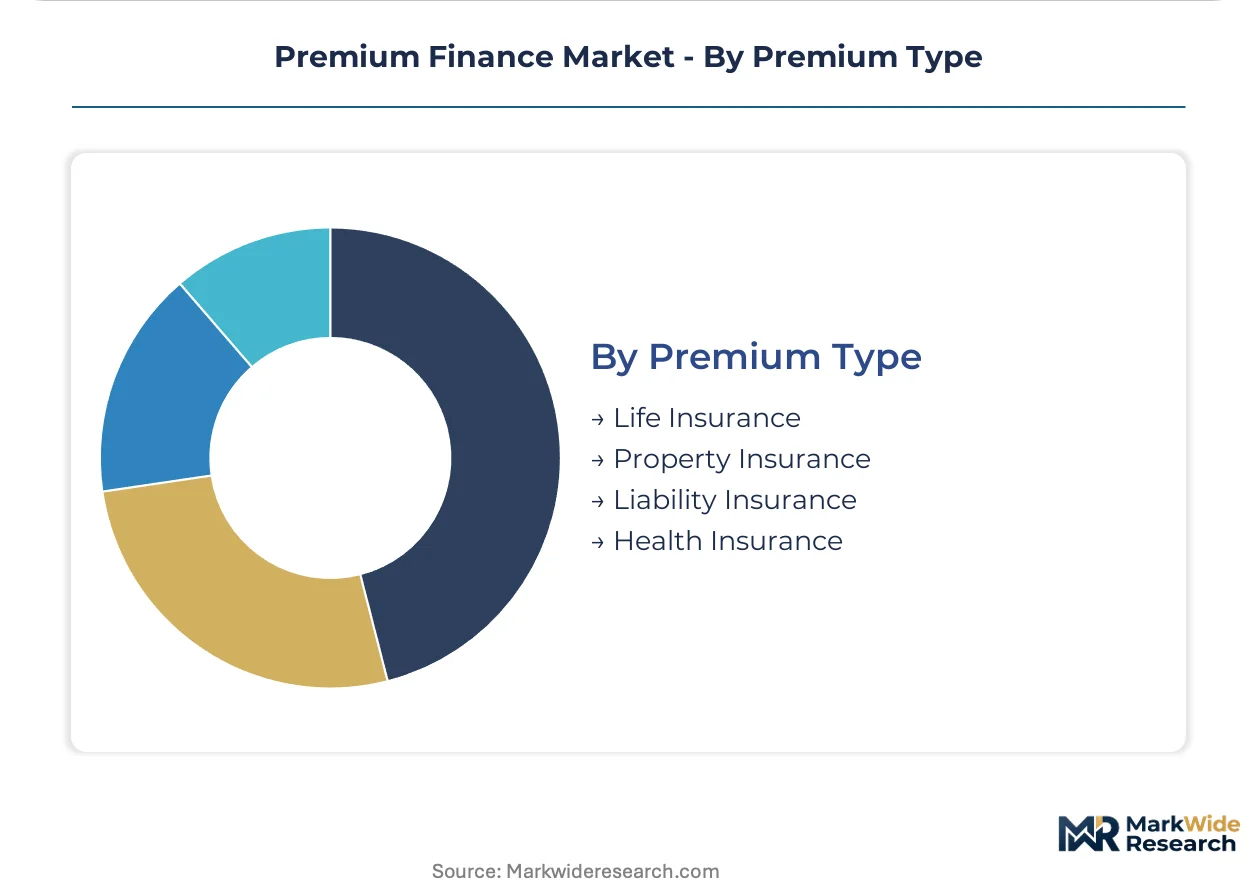
Life Insurance commands institutional capital concentration; Property Insurance is gaining share fastest amid climate-driven premium escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level rate-cap legislation and disclosure harmonization under NAIC model acts are redistributing premium finance activity toward jurisdictions with favorable banking charter frameworks and concentrated commercial property exposure.
United States
Florida, Louisiana, and Texas generate the steepest demand acceleration as hurricane-exposed commercial property premiums escalate beyond working capital thresholds. The National Association of Insurance Commissioners model acts standardize disclosure protocols across multi-state originators, reducing compliance fragmentation. Nashville and Dallas legal hubs concentrate regulatory operations for multi-state premium finance companies responding to state-level rate-cap compression.
Canada
Ontario and Quebec commercial insurance markets exhibit growing installment preference among mid-market enterprises managing cash flow timing. Provincial insurance regulators maintain disclosure requirements below US stringency thresholds, attracting cross-border servicing platform investment. Toronto-based managing general agents embed white-labeled premium finance at point-of-quote for contractor and property manager segments.
United Kingdom
London's specialty insurance market generates concentrated demand for premium financing among international commercial policyholders facing sterling-denominated premium obligations. The Financial Conduct Authority's consumer duty rules extend disclosure standards to premium finance arrangements sold through insurance intermediaries. Lloyd's syndicate distribution channels in the City of London increasingly integrate third-party installment options alongside traditional captive facilities.
Germany
Baden-Württemberg and Bavaria industrial Mittelstand companies deploy premium financing to preserve liquidity for capital equipment cycles while maintaining property and casualty coverage continuity. BaFin supervision of premium finance companies as financial services institutions imposes capital requirements exceeding pure insurance regulation. Munich's insurance cluster hosts technology-integrated servicing platforms targeting cross-border European distribution.
Australia
New South Wales and Victoria commercial property owners facing climate-driven premium escalation adopt installment structures analogous to US southeast patterns. The Australian Securities and Investments Commission's responsible lending obligations extend to premium finance originated through insurance brokers. Sydney-based independent agency networks digitize origination workflows to compress credit decision timelines from days to hours.
Premium Finance Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around banking-regulated entities with balance sheet depth and technology-integrated servicing platforms. Three archetypes dominate: captive finance subsidiaries leveraging agency relationships, institutional-grade credit facility providers, and API-enabled independent agent platforms. Competitive dynamics center on M&A-driven platform consolidation and embedded finance partnerships with managing general agents.
Within the captive-agency tier, AFCO Credit Corporation and Valley National Bancorp occupy positions sustained by exclusive distribution relationships with property and casualty carriers. JPMorgan Chase anchors the institutional-grade segment, exemplifying banking-regulated originators with multi-billion-dollar deployment capacity for high-value life insurance transactions. IPFS Corporation represents the technology-integrated archetype, reducing operational friction for independent agents through API-enabled servicing infrastructure.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| AFCO Credit Corporation |
| IPFS Corporation |
| Valley National Bancorp |
| ARI Financial Group |
| US Premium Finance |
| Lincoln National Corporation |
| Standard Premium Finance Holdings |
| Agile Premium Finance |
| Others |
Supply Flow & Price Mechanics
Undercapacity in state-chartered premium finance licensing across the southeastern United States drives both supplier consolidation and pricing power concentration among banking-regulated originators with balance sheet depth.
Pricing Analysis
Regulatory charter tier creates the primary spread between banking-regulated and pure insurance-regulated premium finance providers. Three-tier pricing structure across institutional-grade, mid-market, and independent-agent segments reflects funding source diversification and compliance infrastructure investment. Cost compression in the mid-market tier is intensifying because state rate-cap legislation compresses origination margins. Independent agents in Florida and Texas exhibit highest price sensitivity due to embedded finance alternatives, while high net worth individuals demonstrate lowest sensitivity given estate planning liquidity preservation priorities.
Supply Chain Analysis
Tariff exposure between commercial property carriers and reinsurance markets dominates collateral risk assessment for hurricane-exposed premium financing. Funding supply concentrates in the United States, the United Kingdom, and Germany, with institutional investors and private equity vehicles providing deployment capacity. The supply chain draws from wholesale bank credit facilities, securitized premium receivables, and direct pension fund participations. Single-source vulnerability in Federal Reserve policy transmission creates repricing risk for non-bank originators. Distribution runs through captive agency relationships, managing general agent partnerships, and API-enabled independent agent platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from embedded finance partnerships that disintermediate standalone premium finance company websites at point-of-quote.
For Market Incumbents: Entrench captive agency relationships through technology-integrated servicing platforms that compress credit decision timelines. Invest in state banking charter optimization to access broader funding diversification than pure insurance-regulated competitors. Rate-cap compression and API-enabled competitor entry threaten legacy margin structures. For New Entrants and Emerging Players: Build out white-label installment solutions for managing general agents serving mid-market commercial contractors and property managers in the southeastern United States. Target Florida, Louisiana, and Texas where hurricane-exposed premium escalation exceeds working capital thresholds. Go-to-market through embedded finance partnerships that displace broker-referred post-bind workflows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology-integrated servicing platforms with API-enabled origination infrastructure. Long-term viability hinges on regulatory operations centralization and multi-state licensing scale. Acquisition target archetype: asset-light platforms with independent agent channel penetration. Monitor state-level rate-cap legislation as inflection indicator for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Origination Platform | Compresses credit decision timelines from days to hours for independent agents in Texas and Florida. |
| State Banking Charter Optimization | Unlocks funding diversification beyond pure insurance-regulated capital constraints under NAIC frameworks. |
| Embedded Finance Partnership | Integrates installment options at point-of-quote through managing general agent white-label arrangements. |
| Regulatory Operations Centralization | Consolidates multi-jurisdictional compliance in Nashville and Dallas legal hubs responding to disclosure tightening. |
| Securitization Market Access | Expands institutional capital participation subject to SEC oversight constraints on premium receivable structures. |
Methodological Framework
A standing panel of premium finance company executives, state banking regulators, independent agency principals, and managing general agent operators provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from NAIC model act documentation, state insurance department filings, SEC securitization disclosures, and Federal Reserve policy transcripts. Bottom-up transaction volume analysis triangulated against top-down funding source deployment estimates.
Scenario-bracketing around Federal Reserve policy trajectories and state rate-cap legislative outcomes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, client profile, funding source tier, and premium collateral category. CAGRs derived from funding source capacity expansion rates and origination volume elasticity to premium escalation patterns. Industry-specific inputs incorporated hurricane exposure premium growth and estate planning complexity indices.
Practitioners should monitor carrier insolvency events and mid-term cancellation frequency for early signals of collateral recovery uncertainty. Forecasts reflect assumptions about NAIC model act harmonization pace and embedded finance adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market