
 Middle East and Africa Payment Gateway Market | 2026-2036
Middle East and Africa Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Payment Gateway Market Insights
API-first architecture is narrowing the gap between enterprise-grade infrastructure and mid-market merchant needs across the Middle East and Africa. Network International leverages its acquiring licenses in the UAE and Jordan to sustain cross-border settlement dominance. Paystack anchors Nigerian e-commerce volume through direct bank integrations. Telr differentiates via multi-currency support tailored to Gulf-based SMEs.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchant platforms and acquiring banks, typically operating through RESTful APIs with TLS 1.3 encryption and tokenized card storage to minimize PCI-DSS scope. Its commercial purpose is to reduce cart abandonment while ensuring settlement finality across heterogeneous banking networks. Digital wallets within the payment method dimension are capturing disproportionate growth as mobile money interoperability expands across East Africa. Hosted payment solutions remain the default entry point for merchants lacking in-house development capacity, though API integration is gaining traction among mid-market retailers seeking checkout customization.
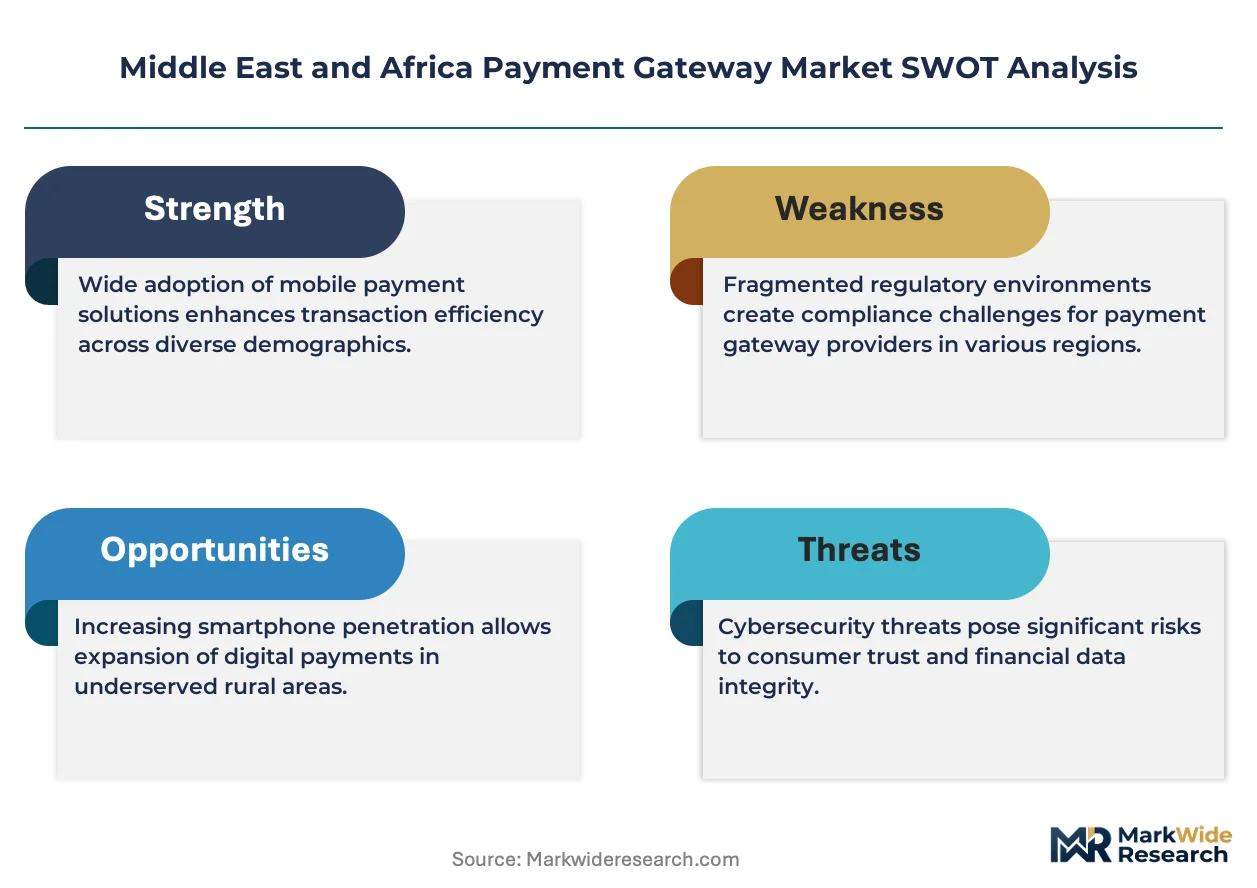
South Africa's Information Regulator enforces POPIA compliance for cross-border data flows, while the UAE Central Bank mandates localization of transaction records for licensed payment service providers. The Saudi Arabian Monetary Authority's open banking framework is reshaping API standards for account-to-account transfers. Stakeholders must weigh the cost of multi-jurisdictional licensing against the revenue potential of unified pan-regional settlement rails.
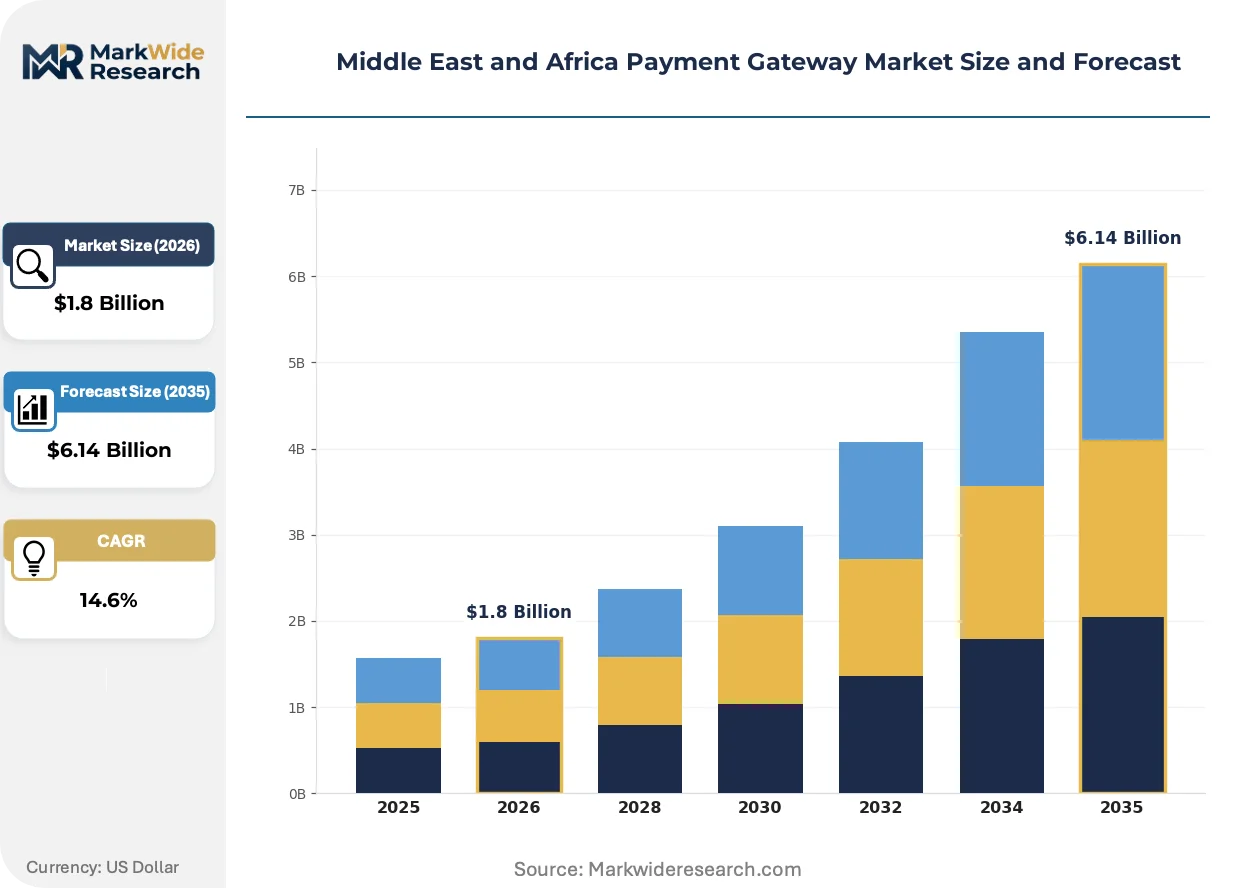
Market Dynamics
Real-time payment infrastructure deployment across the Gulf Cooperation Council corridor is compressing settlement timelines from T+2 to T+0, forcing incumbent gateway providers to re-architect legacy batch-processing systems or cede merchant volume to API-native competitors.
Growth Catalysts
- CBUAE Licensing Mandate:The UAE Central Bank's payment service provider framework requires transaction record localization, creating captive demand for domestically licensed gateway infrastructure among multinational merchants entering the Emirates.
- Mobile Money Interoperability:East African M-Pesa and Airtel Money network convergence is expanding addressable merchant pools beyond card-holding populations into previously cash-dominant consumer segments.
- SAMA Open Banking:Saudi Arabia's account-to-account transfer standards are enabling direct bank integration pathways that reduce interchange dependency for high-volume e-commerce platforms.
Market Restraints
- Multi-Jurisdictional Licensing Costs:Separate regulatory approvals required in the UAE, Saudi Arabia, South Africa, and Nigeria impose cumulative compliance burdens that favor capitalized regional incumbents over specialized entrants.
- Cross-Border Settlement Fragmentation:Absence of unified pan-African clearing rails forces merchants to maintain separate gateway relationships for Maghreb, East African, and Southern African consumer bases.
- Fiat Currency Volatility:Egyptian pound and Nigerian naira exchange rate instability elevates hedging costs for gateways offering multi-currency settlement to international merchants.
Strategic Opportunities
- Underpenetrated Egyptian E-Commerce:Cairo and Alexandria merchant digitization lags Gulf penetration by approximately five years, creating first-mover positioning for localized checkout optimization.
- Embedded Finance Convergence:Integration of payment gateways with inventory management and lending platforms is capturing merchant stickiness beyond transaction processing alone.
- POPIA Compliance Services:South Africa's data protection enforcement creates adjacent revenue streams for gateways offering POPIA-certified hosting and audit documentation to cross-border merchants.
Industry Challenges
- API Talent Scarcity:Shortage of engineers proficient in TLS 1.3 implementation and tokenized vault architecture across Lagos, Dubai, and Johannesburg labor markets delays product roadmap execution.
- Legacy Bank Integration:Direct connections to South African and Nigerian core banking systems require bespoke middleware development, extending merchant onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Payment Gateway Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Digital Wallets, Bank Transfers Service Type: Hosted Payment, API Integration, Payment Page Solutions, Mobile Payment End User: E-commerce, Retail, Travel, Telecommunications Transaction Type: Recurring Payments, One-time Payments, Deferred Payments, Cross-border Transactions |
| Companies Covered | Network International, Payfort, HyperPay, Telr, PayTabs, Checkout.com, Paystack, Flutterwave, Interswitch, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Payment Gateway Market Trends and Innovations
API-first architecture is collapsing the historical capability gap between enterprise-grade infrastructure and mid-market merchant requirements, enabling smaller retailers to deploy customized checkout experiences previously accessible only to scaled platforms.
Tokenized card vault technology with PCI-DSS Level 1 certification is rendering obsolete the practice of merchant-side card data storage that previously required extensive compliance audits and liability exposure. Mid-market e-commerce platforms across Kenya and Nigeria are migrating to hosted vault solutions within eighteen-month replacement cycles. This shift compresses time-to-market for new merchant launches from quarters to weeks.
South Africa's Information Regulator has intensified POPIA enforcement for cross-border data flows, compelling payment gateways to maintain domestic transaction processing nodes rather than routing through European infrastructure. The industrial consequence is elevated capital expenditure for localized data center capacity. Gateways serving South African merchants are responding by establishing Johannesburg-based primary processing with redundant Cape Town failover.
Merchant procurement of payment services is consolidating around bundled offerings that combine gateway, fraud screening, and multi-currency settlement into single-contract relationships. Independent software vendors and systems integrators are displacing direct sales channels as the primary merchant acquisition pathway. This pattern is most visible in the UAE, where Shopify and WooCommerce plugin marketplaces dominate mid-market onboarding.
Middle East and Africa Payment Gateway Market Segmentation
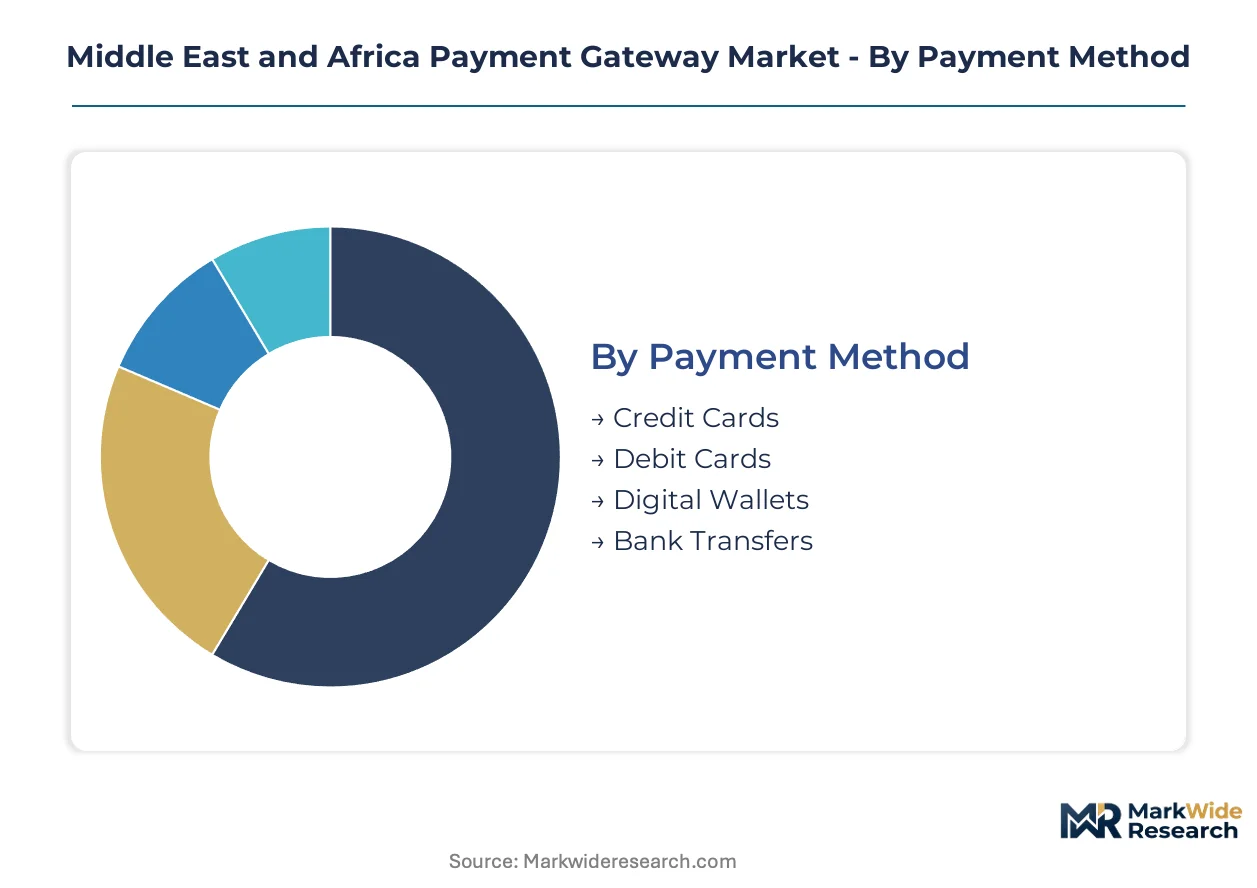
Payment gateway segmentation across the Middle East and Africa reveals distinct technology adoption curves between Gulf Cooperation Council corridors and sub-Saharan markets. Merchant procurement patterns vary sharply by digital maturity, with hosted solutions dominating Egyptian and Nigerian entry-level deployments while API-native architectures capture Saudi and UAE enterprise volume.
Payment Method:
Use-case spectrum spans card-present retail in South African urban centers to mobile money-dominant East African e-commerce, with digital wallets bridging informal economy participation.
- Credit Cards:Visa and Mastercard network dominance persists in UAE and Saudi Arabian luxury retail segments. South African platinum card penetration sustains premium merchant interchange revenue despite gradual wallet displacement.
- Digital Wallets:M-Pesa and Airtel Money interoperability across Kenya, Tanzania, and Uganda is converting previously cash-exclusive merchants. Gulf-based Apple Pay and Samsung Pay adoption accelerates through CBUAE-licensed wallet aggregation.
- Debit Cards:Nigerian bank-issued debit volumes anchor domestic e-commerce checkout flows. Egyptian debit network expansion lags credit infrastructure by approximately three years.
- Bank Transfers:SAMA open banking standards in Saudi Arabia enable direct account-to-account settlement that bypasses traditional card rails. South African EFT integration remains fragmented across legacy core banking systems.
Established volume favors credit cards; emerging adoption favors digital wallets.
Service Type:
Cost tier stratification separates capital-intensive in-house development from subscription-based managed services, with mid-market merchants gravitating toward hybrid deployment models.
- API Integration:RESTful architecture with TLS 1.3 encryption enables customized checkout flows for scaled UAE and Saudi platforms. Nigerian fintechs leverage direct bank API connections to reduce settlement latency from T+2 toward T+0.
- Hosted Payment:PCI-DSS Level 1 certified vault solutions eliminate merchant-side compliance burden. Cairo and Lagos small merchants adopt hosted gateways through Shopify and WooCommerce plugin marketplaces without dedicated engineering resources.
- Payment Page Solutions:Pre-configured checkout templates accelerate time-to-market for Johannesburg mid-market retailers. White-label customization options support brand consistency requirements.
- Mobile Payment:SDK-based integration targets smartphone-first consumer bases across Kenya and Nigeria. USSD fallback protocols maintain transaction completion in low-connectivity environments.
Hosted solutions dominate entry-level merchant acquisition; API integration captures enterprise lifetime value expansion.
End User:
Application concentration varies by geography, with travel and telecommunications verticals driving cross-border transaction complexity in Gulf markets while retail digitization accelerates across North and West Africa.
- E-commerce:Marketplace platforms across Nigeria and Kenya require multi-currency settlement and fraud screening integration. UAE luxury goods merchants prioritize seamless mobile checkout conversion optimization.
- Retail:South African brick-and-mortar POS integration demands EMV certification and real-time inventory synchronization. Egyptian grocery and fashion merchants are transitioning from cash-dominant operations toward hybrid payment acceptance.
- Travel:Saudi Arabian hospitality and airline sectors require multi-acquirer routing for international card acceptance. Cross-border refund handling complexity elevates gateway selection criteria.
- Telecommunications:Airtime purchase and bill payment volumes sustain high-frequency, low-value transaction processing requirements. MNO partnerships enable carrier billing alternatives for unbanked segments.
E-commerce represents the steepest expansion trajectory; retail sustains the largest absolute transaction volume.
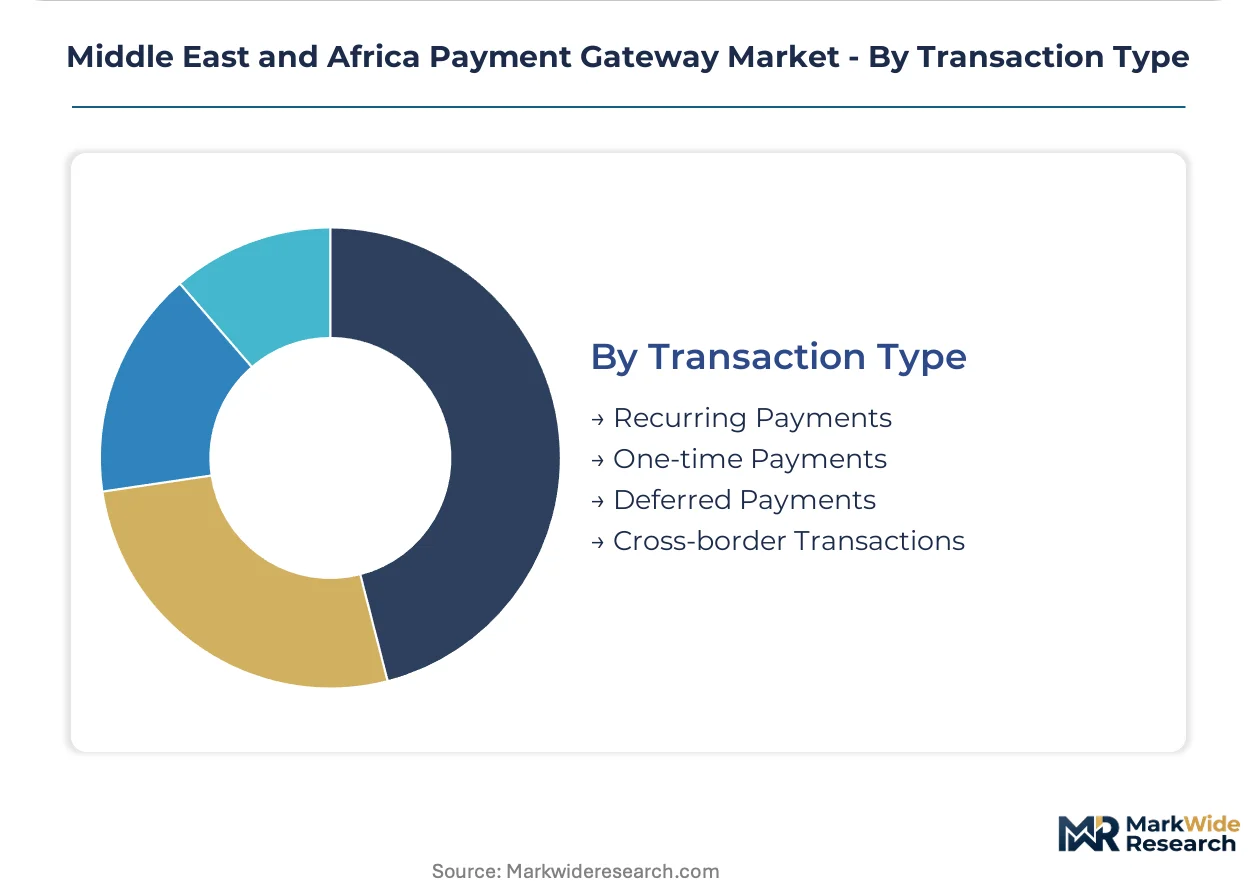
Transaction Type:
Volume concentration in recurring subscription models contrasts with margin concentration in cross-border settlement, where currency hedging capabilities differentiate gateway competitiveness.
- Cross-border Transactions:Multi-currency settlement with Egyptian pound and Nigerian naira hedging attracts international merchants entering North African markets. UAE dirham and Saudi riyal stability supports Gulf corridor volume aggregation.
- Recurring Payments:Tokenized vault storage enables subscription commerce across South African streaming and software-as-a-service platforms. Nigerian utility and insurance billing drives mandate management complexity.
- One-time Payments:Guest checkout optimization targets cart abandonment reduction in high-velocity retail environments. Single-use token generation minimizes PCI scope for occasional purchasers.
- Deferred Payments:Buy-now-pay-later integration through Saudi Tabby and UAE Postpay partnerships captures younger consumer segments. Credit risk assessment APIs extend gateway functionality beyond pure payment processing.
One-time payments anchor current merchant volume; deferred payment integration is gaining share fastest among new gateway deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African gateway providers export fraud-screening and compliance services into Nigerian and Kenyan markets, while UAE-based infrastructure providers supply cross-border settlement rails to Saudi Arabian e-commerce platforms.
United Arab Emirates
Dubai's luxury retail sector and Abu Dhabi's government procurement digitization drive enterprise gateway demand. The Central Bank of the UAE mandates transaction record localization for licensed payment service providers. Dubai Internet City clusters fintech engineering talent developing API-native checkout solutions for Gulf Cooperation Council merchants.
Saudi Arabia
SAMA's open banking framework and NEOM's smart city payment infrastructure anchor domestic gateway expansion. The Saudi Arabian Monetary Authority sets API standards for account-to-account transfers bypassing traditional card rails. Riyadh's financial district concentrates licensed providers serving hospitality and airline verticals with multi-acquirer routing.
Nigeria
Lagos-based e-commerce marketplaces and Port Harcourt petroleum services sustain high-volume transaction processing demand. The Central Bank of Nigeria enforces cashless policy mandates accelerating merchant digitization. Yaba technology cluster hosts direct bank integration specialists reducing settlement latency toward real-time finality.
South Africa
Johannesburg retail POS networks and Cape Town software-as-a-service subscriptions anchor recurring payment volumes. POPIA enforcement by the Information Regulator compels domestic data processing node deployment. Sandton financial hub concentrates PCI-DSS Level 1 certified vault providers serving cross-border merchants.
Kenya
Nairobi's M-Pesa interoperability expansion and Mombasa port logistics digitization convert cash-dominant merchant segments. The Central Bank of Kenya regulates mobile money convergence standards enabling wallet-agnostic checkout acceptance. Konza Technology City development attracts API engineering talent for East African market expansion.
Middle East and Africa Payment Gateway Market Competitive Landscape
On the supply side, the industry is consolidating around regionally licensed infrastructure providers with multi-jurisdictional compliance capabilities. Tiered competitive dynamics separate Gulf-based acquirers with central bank licenses from sub-Saharan API-native specialists. Two strategic archetypes dominate: vertically integrated acquiring-license holders and modular gateway-agnostic platform builders. Competitive moves center on geographic license acquisition and embedded finance partnership expansion.
Among UAE-based licensed acquirers, Network International and Payfort exemplify the integrated-license archetype combining direct settlement authority with merchant-facing gateway services. Telr occupies a position within the mid-market SME-focused tier, differentiating through multi-currency support tailored to Dubai and Abu Dhabi commercial corridors. Paystack anchors the sub-Saharan specialist vector, representing direct bank integration approaches that reduce interchange dependency for Nigerian e-commerce volume.
| Leading Market Players |
|---|
| Network International |
| Payfort |
| HyperPay |
| Telr |
| PayTabs |
| Checkout.com |
| Paystack |
| Flutterwave |
| Interswitch |
| Others |
Pricing and Supply Chain Analysis
UAE-based acquiring license concentration creates margin capture at the settlement layer that API-native competitors cannot replicate without CBUAE authorization. This upstream control forces mid-market gateways into price competition on transaction fees while licensed incumbents extract premium from multi-currency settlement and compliance bundling.
Pricing Analysis
Legacy batch-processing gateways command lower per-transaction rates than API-native alternatives with TLS 1.3 encryption and tokenized vault architecture. Pricing stratifies across enterprise, mid-market, and entry-level tiers based on PCI-DSS certification level and direct bank integration depth. Cost compression in the mid-market tier is intensifying because Nigerian and Kenyan fintechs are undercutting incumbents on settlement speed. Entry-level merchants using hosted solutions through Shopify and WooCommerce marketplaces exhibit highest price sensitivity; UAE luxury retail platforms show lowest sensitivity due to checkout conversion optimization priorities.
Supply Chain Analysis
Export-control restrictions on advanced encryption technologies limit TLS 1.3 implementation hardware flows into the region. Data center capacity concentrates in the UAE, South Africa, and Nigeria, with Johannesburg and Dubai serving as primary processing nodes for POPIA and CBUAE compliance respectively. Raw material dependencies include server-grade semiconductors, fiber-optic cable infrastructure, and redundant power systems. Single-source vulnerability runs through undersea cable chokepoints connecting East African coastal landing stations to global internet backbones. Distribution runs through cloud service provider partnerships and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce platforms in Nigeria and the UAE that demand bundled gateway-fraud-compliance offerings, fragmenting procurement across independent software vendors.
For Market Incumbents: Pre-empt API-native challengers by acquiring direct bank integration specialists in Lagos and Nairobi before settlement latency advantages erode core merchant relationships. Invest in PCI-DSS Level 1 certification upgrades to maintain compliance bundling premium against modular competitors. Vertical integration into hosted vault infrastructure preserves margin pools that pure-transaction processors cannot access. For New Entrants and Emerging Players: Establish a beachhead in Egyptian e-commerce merchant digitization, where Cairo and Alexandria penetration lags Gulf markets by approximately five years and localized checkout optimization remains underserved. Target mid-market retailers seeking API customization without enterprise engineering headcount. Pursue plugin marketplace distribution through WooCommerce and Shopify partner programs to bypass direct sales cost structures. For Investors and Strategic Acquirers: Capital is best deployed toward regionally licensed infrastructure providers with multi-jurisdictional compliance capabilities rather than single-market specialists facing regulatory fragmentation costs. Long-term viability hinges on embedded finance convergence where payment gateways integrate inventory management and lending platforms. Watch SAMA open banking API standard adoption rates as the inflection signal for account-to-account transfer displacement of card rails.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional License Acquisition | CBUAE and SAMA authorization enables captive demand from multinational merchants entering Gulf markets. |
| Embedded Finance Platform Integration | Inventory management and lending partnerships extend merchant stickiness beyond transaction processing. |
| POPIA-Certified Hosting Deployment | Johannesburg-based data nodes satisfy South Africa's Information Regulator enforcement for cross-border flows. |
| Direct Bank API Development | Yaba cluster engineering talent reduces Nigerian settlement latency from T+2 toward T+0 finality. |
| Mobile Money Interoperability Expansion | M-Pesa and Airtel Money convergence captures previously cash-exclusive East African consumer segments. |
Research Methodology
Operator-level perspectives from payment gateway CTOs, CBUAE licensing officers, Nigerian e-commerce platform engineers, and South African compliance consultants anchored the qualitative base. Secondary validation drew from central bank regulatory filings, PCI-DSS certification databases, mobile money interoperability standards, and cloud infrastructure capex disclosures. Bottom-up merchant adoption modeling and top-down regional market sizing were triangulated to constrain variance.
Scenario-bracketing around real-time payment infrastructure deployment timelines and regulatory enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include payment method, service type architecture, end-user vertical, and transaction type. CAGRs were derived from merchant onboarding velocity, transaction volume per active gateway, and average revenue per merchant expansion curves.
Stress conditions across naira and pound exchange rate volatility, POPIA enforcement timing, and Gulf central bank licensing backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about mobile money interoperability expansion and open banking API adoption. Material shifts in SAMA regulatory timelines or CBUAE data localization requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India RTP Market
Payments
Poland Payments Market
Payments
Canada Mobile Payments Market
Payments
Payment Security Software Market
Payments
Poland POS Terminal Market
Payments
Denmark Mobile Payments Market
Payments
North America POS Terminal Market
Payments
Germany POS Terminal Market
Payments
GCC Mobile Payment Market
Payments
UAE POS Terminal Market
Payments
China Virtual Cards Market
Payments
Latin America Subscription and Billing Management Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Cash Management Software Market