
 India Payment Gateway Market | 2026-2036
India Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
India Payment Gateway Market Foresight
India's digital payment infrastructure is tilting toward real-time settlement rails and merchant onboarding automation. Razorpay Payment Gateway Services anchors its position through deep API customization for SaaS and marketplace verticals. PhonePe Payment Gateway Services leverages UPI's network effects to dominate peer-to-merchant transaction flows. Cashfree Payments specializes in subscription billing and payout orchestration, competing aggressively on developer experience.
A payment gateway is a technology layer that encrypts, routes, and authorizes financial transactions between merchants and acquiring banks, typically processing data through PCI-DSS compliant token vaults with sub-second latency thresholds. Its primary commercial purpose is to reduce cart abandonment while ensuring fraud-screened settlement across card, net-banking, and wallet rails. Third-party gateways capture the bulk of merchant sign-ups due to faster onboarding and lower fixed costs versus bank-integrated alternatives. QR code payments and NFC-enabled point-of-sale solutions are expanding fastest among transaction methods, though cross-border transaction infrastructure remains underdeveloped relative to domestic volumes.
The Reserve Bank of India governs capital adequacy, data localization, and tokenization standards through circulars issued under the Payment and Settlement Systems Act. SEBI intersects where gateway providers serve capital-market participants or investment platforms. The PLI scheme for financial technology and BIS certification requirements for hardware POS terminals together shape product roadmaps and market access timelines. Stakeholders must monitor how RBI's proposed credit-on-UPI framework alters merchant acquisition economics and gateway revenue models.
Market Dynamics
UPI infrastructure expansion is compressing settlement timelines and forcing gateway providers to rebuild core routing engines around real-time rails rather than batch-processed card networks.
Growth Catalysts
- RBI Tokenization Mandate:Merchants must replace stored card data with device-specific tokens, creating mandatory upgrade cycles for gateway infrastructure and vault security layers.
- Tier-2 and Tier-3 E-commerce:Digital-native merchants in smaller Indian cities are onboarding payment gateways at accelerating rates as logistics and smartphone penetration catch up.
- PLI Scheme for Financial Technology:Domestic hardware manufacturing incentives are reducing POS terminal costs and expanding merchant addressable market for integrated gateway solutions.
Market Restraints
- Data Localization Compliance:RBI's server location requirements impose capex-heavy infrastructure duplication that foreign-origin providers struggle to justify against domestic unit economics.
- Acquiring Bank Concentration:Four Indian banks control the majority of merchant settlement relationships, limiting gateway pricing power and technical autonomy in routing decisions.
- UPI Network Effect Lock-in:PhonePe's dominance in peer-to-merchant flows creates substitution risk for independent gateways serving identical merchant segments.
Strategic Opportunities
- Credit-on-UPI Framework:RBI's proposed lending layer atop UPI rails would let gateways capture interest-bearing transaction flows previously restricted to card-based EMI products.
- Cross-border Merchant Acquisition:Indian SaaS exporters and marketplace sellers lack purpose-built gateway solutions for multi-currency settlement and foreign tax compliance.
- Voice and Vernacular Interfaces:Converging speech recognition with regional language NLP is opening merchant onboarding for non-English-speaking micro-retailers previously excluded from digital payments.
Industry Challenges
- PCI-DSS Certification Timelines:Annual audit cycles and documentation requirements slow product release schedules for gateway providers updating encryption protocols.
- Legacy Core Banking Integration:Rural cooperative banks and older private sector institutions run on COBOL-based systems that resist API-native gateway connectivity without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Payment Gateway Market |
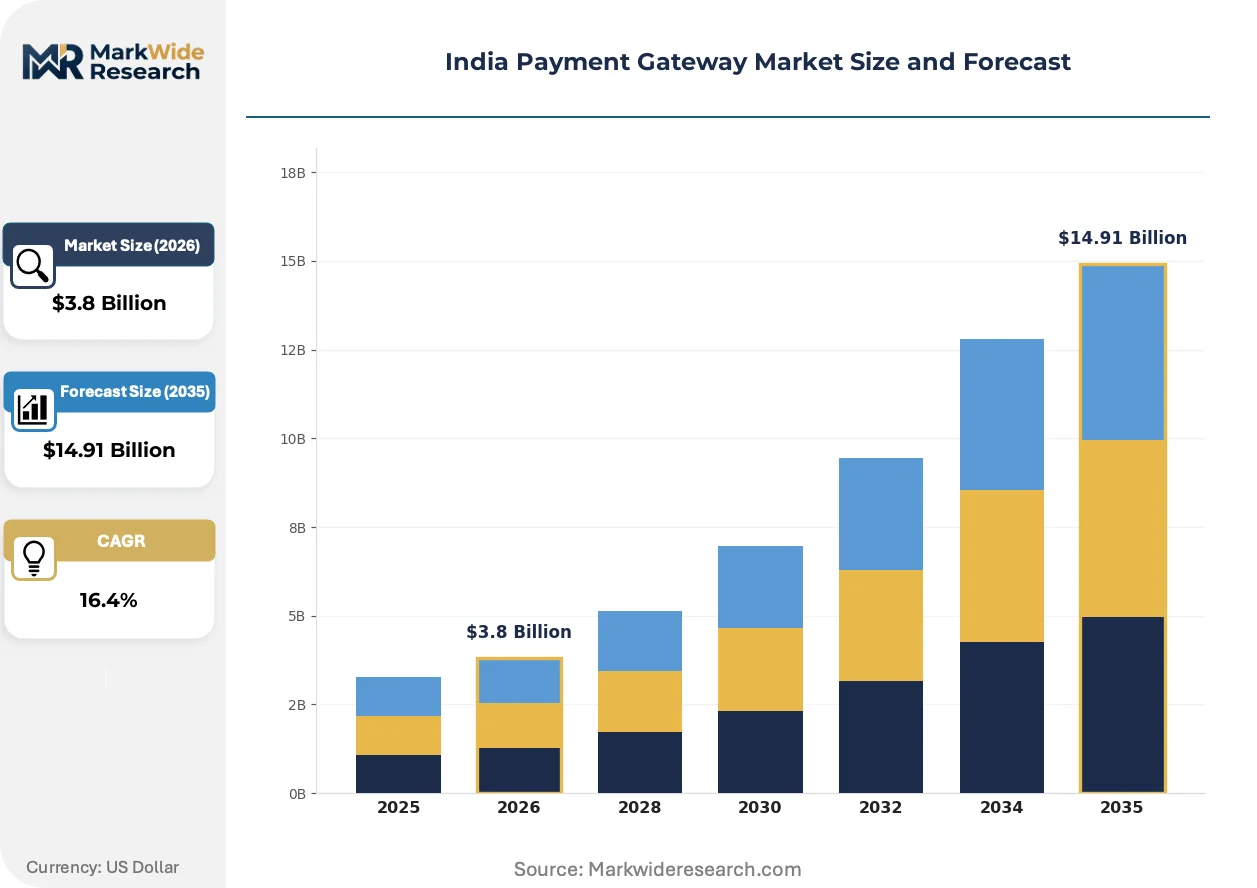
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Third-party Gateways, Bank Integrated Gateways, Cryptocurrency Gateways, Mobile Wallets Customer Type: E-commerce Platforms, Retail Outlets, Service Providers, Subscription Services Transaction Method: Online Transactions, In-store Payments, Recurring Payments, Cross-border Transactions Technology: Mobile Banking, QR Code Payments, NFC, Point of Sale Solutions |
| Companies Covered | PayU Payment Gateway Services, CCAvenue Payment Gateway, PhonePe Payment Gateway Services, MobiKwik Payment Gateway, HDFC Payment Gateway Services, Razorpay Payment Gateway Services, Cashfree Payments, Juspay, Paytm Payment Gateway, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Payment Gateway Market Shifts & Advancements
Payment orchestration is fragmenting merchant tech stacks into modular, multi-provider architectures that treat gateways as interchangeable routing nodes rather than monolithic platforms.
Embedded finance infrastructure is hybridizing checkout experiences across Indian e-commerce marketplaces. Merchant platforms in fashion and grocery verticals are white-labeling gateway APIs to capture payment data ownership. This convergence is compressing standalone gateway margins while expanding total addressable touchpoints.
RBI's recurring payment guidelines under the Payment and Settlement Systems Act are forcing subscription businesses to rebuild billing flows around explicit customer consent mechanisms. SaaS and OTT platforms face higher churn as auto-debit friction increases. Maharashtra-based fintech clusters are responding with pre-debit notification layers that reduce involuntary cancellation rates.
Merchant acquisition through developer communities is displacing traditional direct sales models in Indian payment gateway distribution. API documentation quality and sandbox tooling now determine enterprise selection criteria ahead of pricing. Bangalore and Hyderabad SaaS ecosystems exhibit the strongest concentration of self-serve onboarding patterns.
India Payment Gateway Market Segmentation
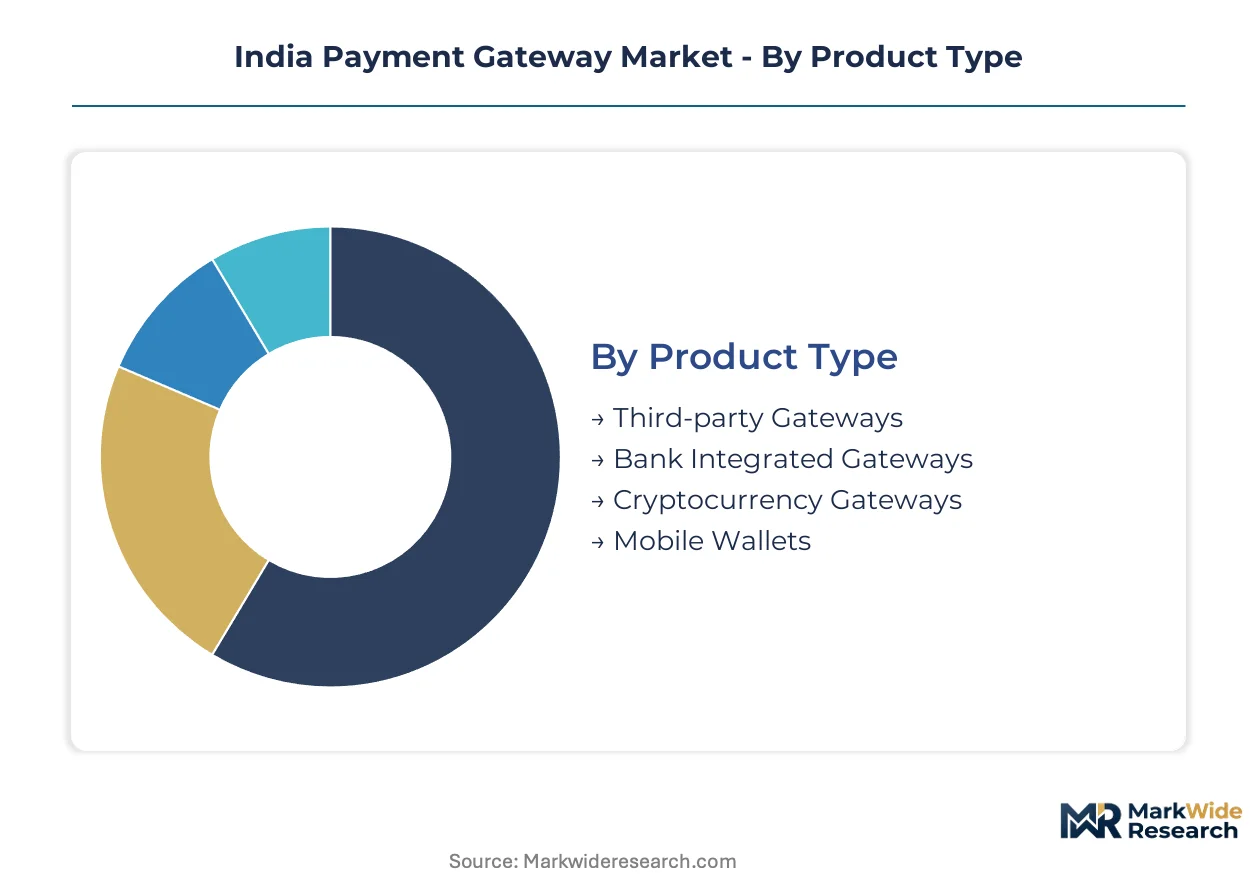
Payment gateway segmentation in India reveals how merchant requirements fragment across settlement speed, integration complexity, and regulatory compliance burdens. Each dimension shapes provider technology roadmaps and pricing architectures differently.
Product Type:
Merchant acquisition economics vary sharply across integration models, with onboarding friction and capital requirements defining competitive boundaries.
- Third-party Gateways:These providers operate as independent technology layers between merchants and acquiring banks, offering API-first integration with sub-24-hour onboarding timelines. Demand concentrates among SaaS startups in Bangalore and Hyderabad where developer self-serve patterns dominate merchant acquisition. The PLI scheme for financial technology is compressing hardware costs for providers bundling POS terminals.
- Bank Integrated Gateways:Institution-owned platforms embed directly into core banking infrastructure, prioritizing settlement reliability over feature velocity. Public sector banks in Maharashtra and Gujarat favor these solutions for regulatory comfort, though API documentation gaps slow enterprise adoption. RBI's tokenization mandate is forcing expensive vault security upgrades across this segment.
- Cryptocurrency Gateways:Blockchain-based settlement rails serving Web3 merchants and cross-border remittance platforms. These providers navigate RBI's restrictive stance on virtual currencies while building offshore hedging infrastructure.
- Mobile Wallets:Closed-loop and semi-closed prepaid instruments with embedded checkout SDKs. Telangana-based fintech clusters drive wallet-to-bank interoperability demands as UPI convergence accelerates.
The dominant share belongs to Third-party Gateways, while Mobile Wallets is closing the gap fastest.
Customer Type:
Vertical-specific transaction patterns determine gateway feature requirements and churn profiles.
- E-commerce Platforms:Marketplace operators and direct-to-consumer brands requiring multi-provider orchestration, split settlements, and real-time reconciliation dashboards. Tier-2 city expansion in Rajasthan and Madhya Pradesh is expanding addressable merchant base for full-stack solutions.
- Retail Outlets:Brick-and-mortar merchants prioritizing QR code acceptance and instant settlement into current accounts. Kirana stores across Karnataka are adopting soundbox-enabled confirmation systems to reduce transaction verification friction.
- Service Providers:Professional services firms and gig economy platforms needing invoice-linked payment links and partial refund capabilities.
- Subscription Services:SaaS and OTT platforms dependent on RBI-compliant recurring payment flows with explicit pre-debit notification layers.
E-commerce Platforms commands the largest merchant volume base, with Subscription Services exhibiting the steepest expansion trajectory as digital services penetrate non-metro markets.
Transaction Method:
Settlement rail selection shapes gateway technical architecture and fraud screening protocols.
- Online Transactions:Card-not-present flows with 3D Secure authentication and device fingerprinting for risk scoring. Maharashtra-based merchant clusters are demanding sub-500 millisecond authorization latency as cart abandonment sensitivity intensifies.
- In-store Payments:Card-present and QR-based face-to-face settlement with PIN-bypass thresholds for low-value purchases.
- Recurring Payments:Standing instruction flows rebuilt around RBI's explicit consent framework, increasing involuntary churn for legacy billing systems.
- Cross-border Transactions:Multi-currency settlement with foreign exchange hedging and tax compliance documentation for Indian SaaS exporters.
Online Transactions retains volume leadership, though Recurring Payments is gaining share fastest as subscription business models proliferate across verticals.
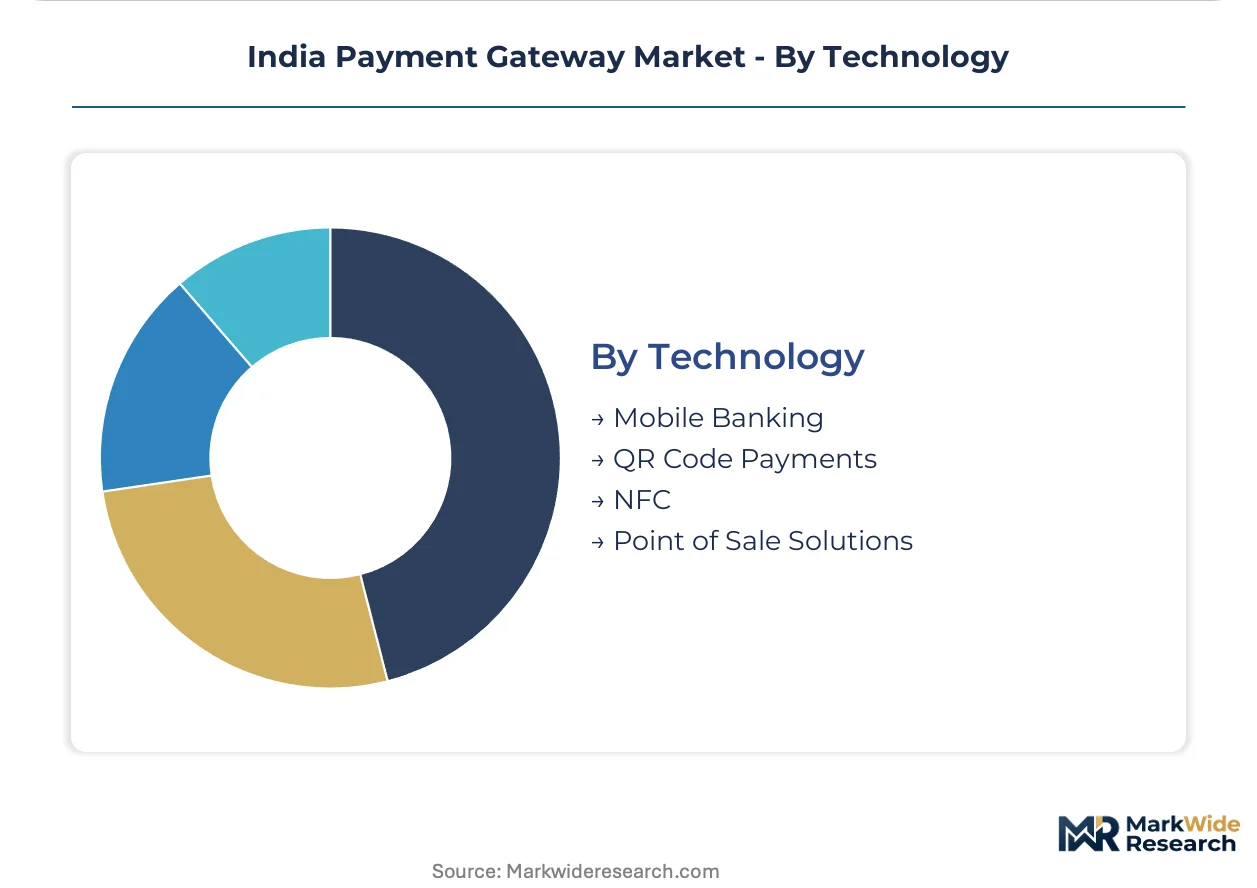
Technology:
Interface modality determines hardware requirements and merchant training burdens.
- Mobile Banking:USSD and app-based flows extending financial inclusion to feature phone users in rural Bihar and Uttar Pradesh.
- QR Code Payments:Static and dynamic code generation with merchant-presented and customer-scanned variants. Interoperable Bharat QR adoption is accelerating across Telangana retail corridors.
- NFC:Contactless card and device tap-to-pay with tokenized credential storage. Metro transit integrations in Delhi and Mumbai are normalizing consumer behavior for low-value contactless.
- Point of Sale Solutions:Android-based terminals with integrated receipt printing, inventory sync, and loyalty program management.
QR Code Payments holds the widest merchant penetration, while NFC is climbing the fastest as contactless limits rise and smartphone ecosystem maturity spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway infrastructure investment concentrates in western and southern Indian states where fintech clusters and digital merchant density overlap. Maharashtra, Karnataka, and Telangana together absorb the majority of new gateway deployments, while tier-2 city expansion across Gujarat and Tamil Nadu is reshaping addressable market geography.
Maharashtra
Mumbai and Pune anchor merchant acquisition volumes for enterprise SaaS and marketplace operators. RBI's tokenization mandate has forced gateway providers to rebuild vault infrastructure for the state's concentrated financial services sector. The Mumbai fintech corridor hosts the densest cluster of API-first gateway providers serving subscription billing verticals.
Karnataka
Bangalore's developer ecosystem drives self-serve onboarding patterns that displace traditional direct sales models. The state's PLI scheme beneficiaries are reducing POS terminal costs for kirana store digitization. Whitefield and Koramangala host the highest concentration of payment orchestration startups building multi-provider routing layers.
Telangana
Hyderabad's retail corridors are accelerating Bharat QR interoperability adoption among merchant-presented payment flows. BIS certification requirements for hardware terminals are shaping product roadmaps for local POS-integrated gateway solutions. The Gachibowli fintech cluster is emerging as a hub for voice-enabled vernacular onboarding tools targeting non-English-speaking micro-retailers.
Gujarat
Surat and Ahmedabad textile exporters are driving demand for cross-border settlement infrastructure with multi-currency hedging capabilities. The state's cooperative banking network presents legacy core integration challenges that middleware providers are targeting. Gandhinagar's startup incubators are cultivating gateway specialists focused on invoice-linked payment links for service provider verticals.
Tamil Nadu
Chennai's manufacturing MSMEs are adopting soundbox-enabled QR confirmation systems to reduce transaction verification friction. The state's tier-2 city logistics expansion is enabling e-commerce platform penetration that feeds gateway onboarding volumes. Coimbatore's industrial clusters are emerging as testbeds for NFC-enabled contactless adoption in B2B procurement payments.
India Payment Gateway Market Competitive Landscape
UPI-native platforms and API-first independents split the market along merchant segment and integration complexity lines. Four acquiring banks control the majority of settlement relationships, compressing pricing autonomy for technology-layer providers. The competitive terrain organizes around developer experience specialization, vertical-specific feature depth, and bank partnership density. Consolidation pressure is mounting through strategic API acquisitions and white-label infrastructure partnerships.
Within the API-first independent tier, Razorpay Payment Gateway Services and Cashfree Payments exemplify developer-centric positioning through deep SaaS and subscription billing specialization. PhonePe Payment Gateway Services occupies a distinct network-effects position leveraging UPI's peer-to-merchant flow dominance. These three providers collectively represent the strategic archetypes reshaping merchant acquisition economics: vertical API customization, payout orchestration automation, and real-time rail native infrastructure.
| Leading Market Players |
|---|
| PayU Payment Gateway Services |
| CCAvenue Payment Gateway |
| PhonePe Payment Gateway Services |
| MobiKwik Payment Gateway |
| HDFC Payment Gateway Services |
| Razorpay Payment Gateway Services |
| Cashfree Payments |
| Juspay |
| Paytm Payment Gateway |
| Others |
Supply & Pricing Matrix
Overcapacity in third-party gateway infrastructure across Bangalore and Hyderabad is compressing per-transaction margins and forcing providers toward volume-based SaaS tiering rather than value-based pricing. This utilization dynamic simultaneously accelerates merchant acquisition automation and erodes pricing power for undifferentiated routing layers.
Pricing Analysis
RBI's tokenization mandate dictates the pricing tier structure across the India payment gateway market. Providers stratify across premium PCI-DSS Level 1 certification tiers, standard mid-market API tiers, and economy self-serve tiers with limited vault customization. Price differentiation hinges on settlement speed guarantees and vertical-specific compliance depth. Cost compression in the economy tier is intensifying because PhonePe's UPI network effects commoditize basic routing functionality. E-commerce platforms in tier-2 cities exhibit highest price sensitivity, while Maharashtra-based financial services merchants prioritize certification grade over cost.
Supply Chain Analysis
Export control regimes on cryptographic hardware and HSM modules limit flows of certified token vault infrastructure into Indian data centers. Hardware security module supply concentrates in Germany, the United States, and Taiwan, with BIS certification requirements adding domestic validation layers. Raw material dependencies span semiconductor chips for POS terminals, encryption processors for vault layers, and specialized firmware for UPI protocol compliance. Single-source vulnerability runs through Taiwan-based HSM foundries serving RBI-mandated localization requirements. Distribution runs through acquiring bank partnerships rather than direct merchant channels, with HDFC, ICICI, Axis, and SBI controlling settlement relationship economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Indian payment infrastructure are tilting toward orchestration-layer intermediation as UPI interoperability dissolves gateway switching costs. Bharat QR standardization and credit-on-UPI framework development are accelerating this ecosystem shift.
For Market Incumbents: Harden vault security differentiation against PhonePe's network-effect lock-in by deepening vertical API customization for subscription billing and marketplace split-settlement workflows. Pursue backward integration into POS hardware manufacturing through PLI scheme incentives to capture terminal economics from kirana store digitization. RBI's proposed credit-on-UPI framework represents the critical regulatory lever for revenue model expansion.
For New Entrants and Emerging Players: Pursue cross-border merchant acquisition for Indian SaaS exporters lacking multi-currency settlement infrastructure with foreign tax compliance automation. Voice-enabled vernacular onboarding tools for non-English-speaking micro-retailers in Gujarat and Tamil Nadu represent the most penetrable whitespace. A developer-community-led go-to-market with superior sandbox tooling can displace legacy direct sales models in tier-2 city expansion.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription billing specialists with RBI-compliant recurring payment infrastructure and pre-debit notification layer patents. Long-term viability over a five-to-ten-year window favors providers with dense acquiring bank partnerships and orchestration-layer API acquisitions. The signal to watch is merchant churn rates following credit-on-UPI framework implementation as interest-bearing transaction flows reshape gateway revenue economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UPI-native routing engines capture real-time settlement flows ahead of batch-processed card networks. |
| Acquisition of Specialist Firm | Voice-enabled vernacular onboarding tools expand merchant addressable market to non-English micro-retailers. |
| Geographic Expansion | Tier-2 city penetration in Rajasthan and Madhya Pradesh feeds e-commerce gateway onboarding volumes. |
| Product Launch | Credit-on-UPI infrastructure captures interest-bearing transaction flows from card-based EMI products. |
| Strategic Partnership | Acquiring bank density agreements with SBI and ICICI secure settlement reliability and pricing autonomy. |
Research Methodology
Initial hypotheses were tested against primary input from payment gateway CTOs, merchant platform engineering leads, acquiring bank digital product officers, and RBI regulatory affairs specialists and refined through secondary validation. Primary fieldwork drew from SEC filings of listed fintech providers, NPCI UPI transaction bulletins, RBI circular archives under the Payment and Settlement Systems Act, and BIS certification registries for hardware terminals. Bottom-up merchant onboarding volume estimates triangulated against top-down addressable market sizing from smartphone penetration and logistics expansion data.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation modeled by integration model, merchant vertical, settlement rail, and interface technology. CAGRs were derived from volume trajectory analysis across tier-2 city expansion corridors and UPI infrastructure deployment timelines. Forecast inputs incorporated PLI scheme incentive disbursement patterns and tokenization mandate compliance upgrade cycles.
Sensitivities concentrate around RBI credit-on-UPI framework implementation timing, merchant acquisition cost inflation in competitive corridors, and hardware terminal supply constraints from BIS certification backlogs. Forecasts reflect documented assumptions on smartphone penetration rates and logistics network expansion. Material shifts in UPI interoperability regulations or acquiring bank consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Prepaid Cards Market
Payments
Global Master Card Market
Payments
Ghana Mobile Money Market
Payments
Online Payment Gateway Market
Payments
Europe Payment Analytics Software Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Norway Mobile Payments Market
Payments
Smart Payment Market
Payments
Europe Mobile Payment Market
Payments
United States Payments Market
Payments
India RTP Market
Payments
Recurring Payments Market
Payments
Malaysia Payments Market
Payments
Thailand Mobile Payments Market
Payments
United Arab Emirates Real Time Payments Market