
 South Korea Digital Payments Market | 2026-2036
South Korea Digital Payments Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Digital Payments Market Insights
MFDS-aligned data governance standards for financial platforms is expanding compliance requirements for domestic payment providers. Viva Republica leverages its super-app architecture to anchor merchant acquisition across verticals from transportation to wealth management. Kakao Corporation sustains dominant consumer mindshare through integrated messaging-to-payment workflows embedded in daily communication habits.
Digital payments encompass electronic fund transfers executed through software-mediated interfaces, typically requiring tokenized credential exchange, PCI-DSS compliant encryption protocols, and real-time settlement rails to replace physical currency or paper instruments in commercial transactions. Mobile wallet penetration among Generation Z users reflects the fastest-expanding demographic cohort, while credit card transaction types retain the largest absolute value pool due to entrenched issuer-bank reward ecosystems. Fintech company service providers capture disproportionate innovation velocity compared to incumbent banking infrastructure.
The Bank of Korea operates the real-time gross settlement backbone that underpins retail payment finality, while the Financial Services Commission enforces e-money licensing and anti-money laundering surveillance that shapes market access thresholds for new entrants. MFDS data handling standards and KISA cybersecurity certification create layered compliance obligations for platform operators. Stakeholders must monitor how open API mandates alter competitive moats between bank-owned and independent payment networks.
Market Dynamics
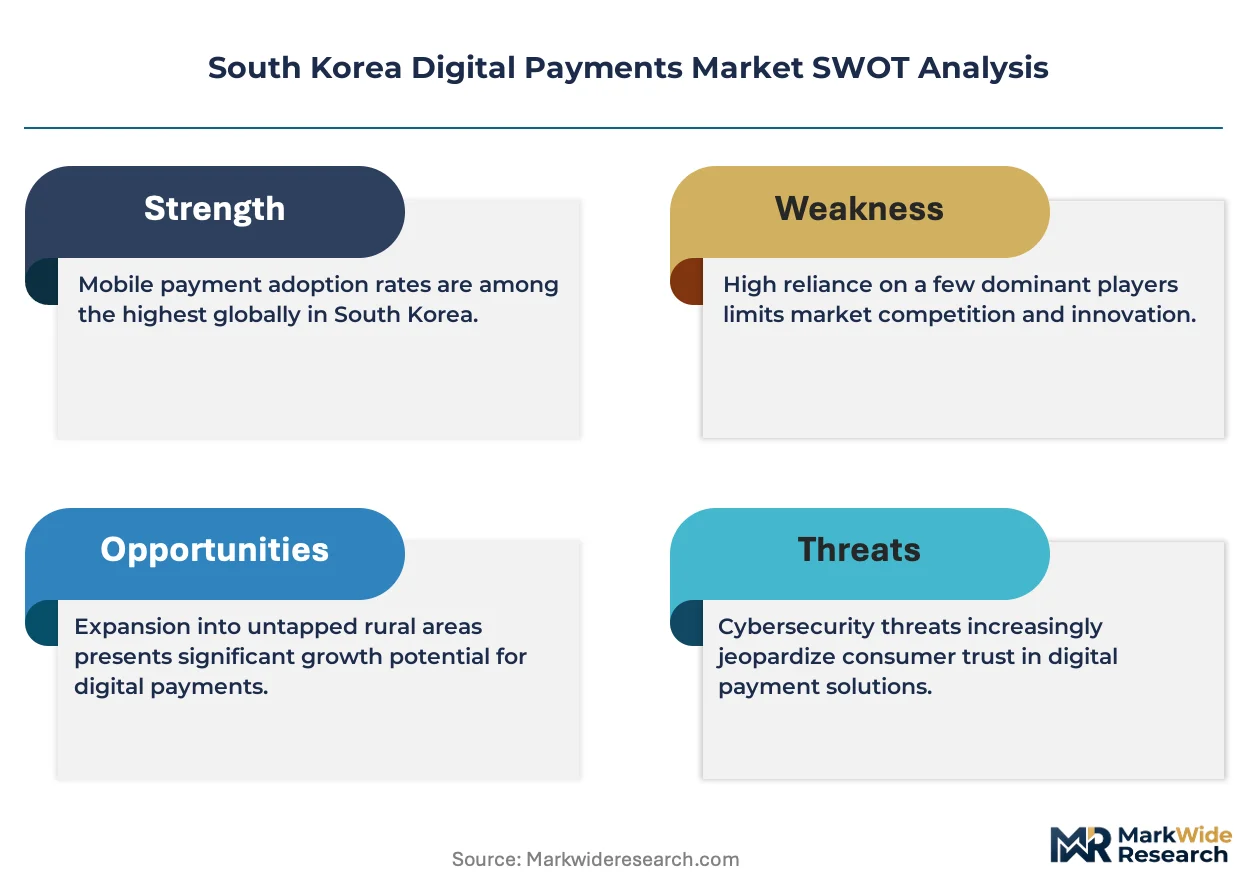
The Financial Services Commission's open banking directives are dismantling closed-loop payment ecosystems and forcing interoperability between bank-owned rails and independent fintech platforms.
Growth Catalysts
- Real-time payment infrastructure:The Bank of Korea's retail payment finality system enables instant settlement without correspondent banking delays. Merchant adoption accelerates in high-frequency transaction environments.
- Generation Z mobile wallet penetration:Younger demographics demonstrate the fastest-expanding cohort for contactless adoption. Daily communication-to-payment workflows embed financial services into habitual platform usage.
- MFDS-aligned data governance:Standardized handling protocols for financial platforms expand compliance requirements that favor scaled operators with dedicated legal infrastructure.
Market Restraints
- Credit card reward ecosystem lock-in:Entrenched issuer-bank loyalty programs create switching costs that slow displacement of traditional transaction types.
- KISA cybersecurity certification burden:Layered technical audits and penetration testing requirements extend time-to-market for new platform entrants.
- Concentrated merchant density:Transaction volumes cluster heavily in Greater Seoul metropolitan area, limiting addressable market expansion into secondary urban centers.
Strategic Opportunities
- Super-app vertical integration:Transportation-to-wealth management bundling creates captive user bases across non-financial daily activities.
- SME contactless settlement gaps:Small and medium enterprises in hospitality and retail outside Seoul present underpenetrated merchant acquisition targets.
- E-money licensing deregulation:Anti-money laundering surveillance thresholds are reshaping market access rules for non-bank payment providers.
Industry Challenges
- PCI-DSS compliant encryption talent scarcity:Tokenized credential exchange expertise concentrates among limited engineering pools in Seoul.
- Legacy core banking integration friction:Incumbent institutions maintain proprietary settlement rails that resist API standardization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Digital Payments Market |
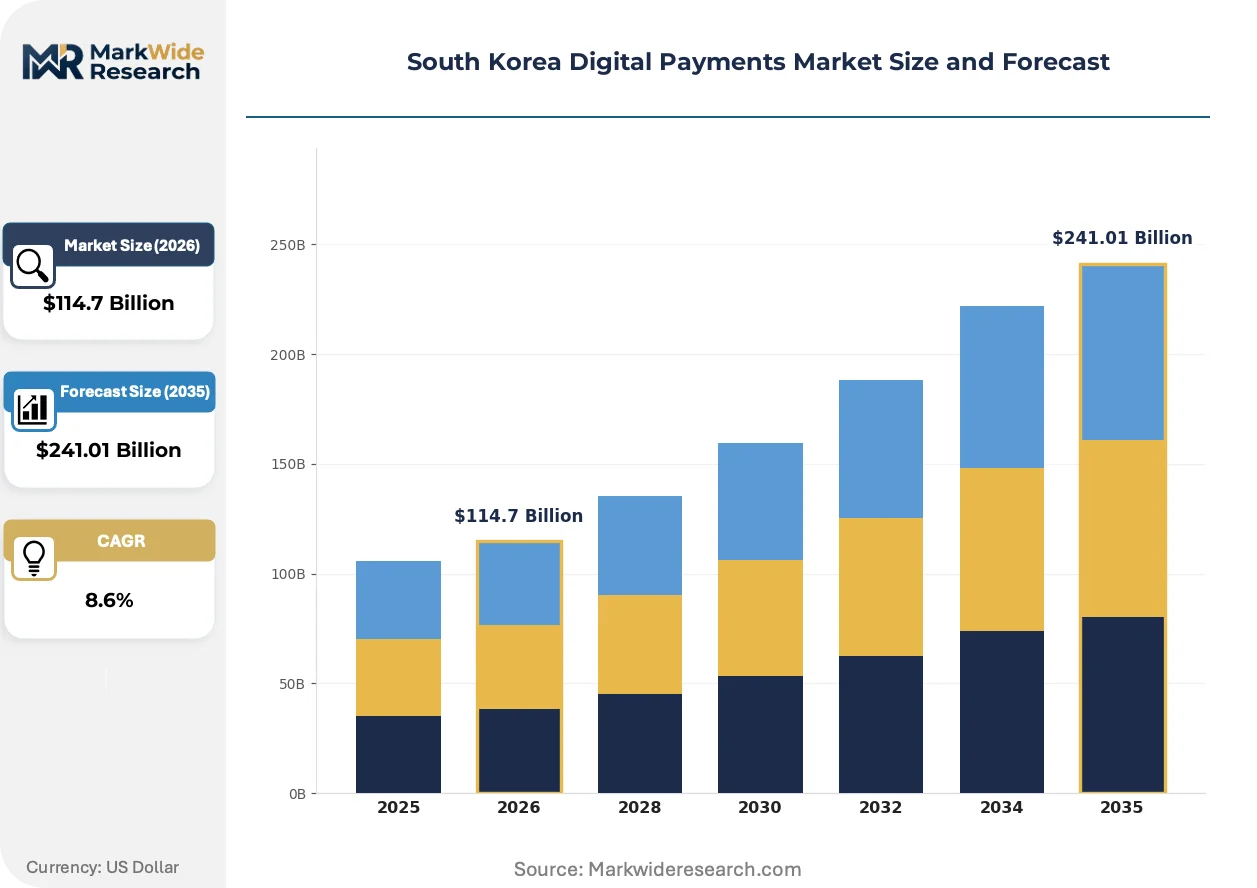
| Market Size in 2026 | $114.7 Billion |
| Market Size in 2035 | $241.01 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Transaction Type: Online Payment, In-Store Payment, Bill Payment, Peer-to-Peer Transfer User Demographic: Millennials, Generation Z, Business Professionals, Retirees Service Provider: Banks, Fintech Companies, Payment Processors, Telecom Operators |
| Companies Covered | Viva Republica, SK Group, Kakao Corporation, SSG com Corp, Coupang, Naver Corporation, PayCo, ZeroPay Pvt Ltd, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Digital Payments Market Trends and Innovations
Software-mediated payment interfaces are displacing physical currency through embedded finance architectures that merge transaction execution with non-financial platform experiences.
Biometric authentication protocols are expanding into retail checkout environments as primary verification methods. Convenience store chains and quick-service restaurants deploy facial recognition and fingerprint scanning at point-of-sale terminals. This convergence of identity verification and payment authorization is compressing transaction time and reducing card-present fraud vectors.
The Financial Services Commission enforces e-money licensing frameworks that tighten capital reserve requirements for platform operators. Fintech providers must maintain segregated customer fund protections and real-time transaction monitoring systems. Independent payment networks respond by building dedicated compliance infrastructure rather than relying on bank partnerships.
Merchant acquisition patterns are rotating toward integrated software vendors that bundle payment acceptance with inventory management and customer relationship tools. Retailers in fashion and specialty goods abandon standalone terminal providers for unified commerce platforms. This consolidation of operational software is most visible in Busan and Daegu metropolitan clusters where mid-sized retail chains dominate commercial districts.
South Korea Digital Payments Market Segmentation
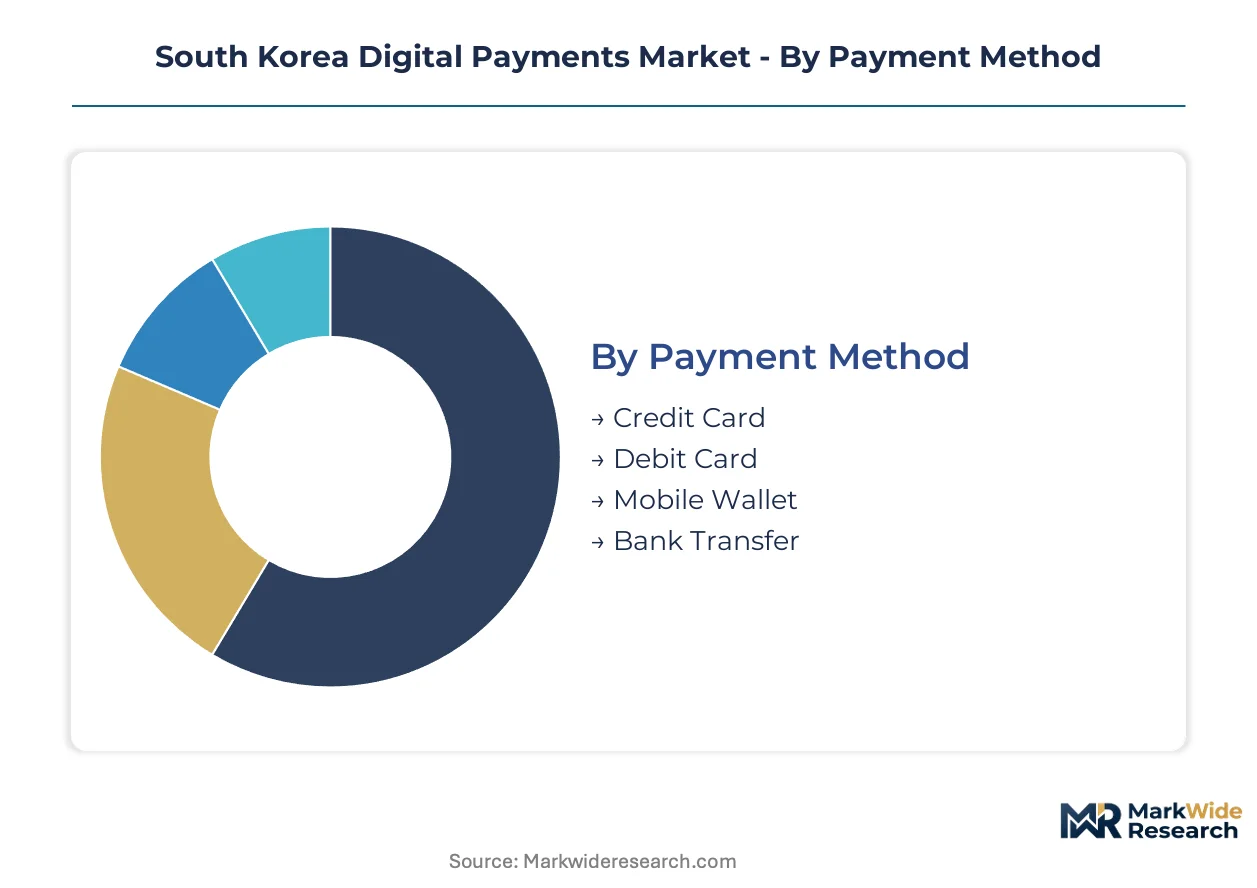
Segmentation reveals how payment infrastructure investments align with distinct user behaviors and settlement requirements across South Korea. The market fragments along four critical dimensions that determine platform architecture, compliance obligations, and merchant acquisition strategies.
Payment Method:
Upgrade cycles in authentication technology and tokenization standards are reshaping how consumers select settlement instruments.
- Credit Card:Magnetic stripe and EMV chip credentials dominate transaction value due to entrenched issuer-bank reward ecosystems in Seoul. Merchant acceptance remains universal across retail and hospitality verticals despite interchange fee pressures from the Financial Services Commission.
- Mobile Wallet:NFC-enabled smartphone applications leverage Bank of Korea real-time settlement rails for instant fund transfers. Generation Z users in the Greater Seoul metropolitan area drive the steepest adoption trajectory as super-app platforms embed payment workflows into daily communication habits.
- Debit Card:Direct linkage to deposit accounts appeals to cost-conscious demographics seeking to avoid revolving credit exposure.
- Bank Transfer:Account-to-account settlement persists in B2B contexts and high-value transactions requiring enhanced audit trails.
Volume placements concentrate in Credit Card; the faster expansion belongs to Mobile Wallet.
Transaction Type:
Cost tier differentiation separates infrastructure-light peer transfers from compliance-heavy commercial settlements requiring PCI-DSS encryption protocols.
- Online Payment:E-commerce checkouts and subscription billing demand tokenized credential exchange with 3D Secure authentication layers. Fashion and specialty goods retailers in Busan metropolitan clusters favor unified commerce platforms that merge payment acceptance with inventory management tools.
- In-Store Payment:Contactless terminal adoption accelerates in convenience store chains and quick-service restaurants deploying biometric verification. Daegu mid-sized retail chains drive merchant acquisition as integrated software vendors displace standalone terminal providers.
- Bill Payment:Recurring utility and telecommunications settlements leverage automatic debit authorization frameworks.
- Peer-to-Peer Transfer:Social payment splitting and informal remittances exploit open banking API interoperability mandated by Financial Services Commission directives.
Merchant density clusters around In-Store Payment; the steepest volume climb occurs in Online Payment.
User Demographic:
Customer type determines platform interface complexity, authentication friction tolerance, and cross-selling potential for wealth management products.
- Generation Z:Digital-native cohorts exhibit highest mobile wallet penetration and lowest loyalty to traditional banking relationships. Daily super-app usage in Seoul creates captive audiences for transportation-to-wealth management vertical bundling.
- Business Professionals:Expense management and corporate card integration requirements prioritize automated receipt capture and accounting software connectivity.
- Millennials:Family formation stage drives demand for mortgage-linked payment automation and insurance premium scheduling.
- Retirees:Biometric authentication protocols reduce password management burden while KISA cybersecurity certification requirements ensure fraud protection standards.
Platform development resources gravitate toward Generation Z; the expanding user base centers on Business Professionals.
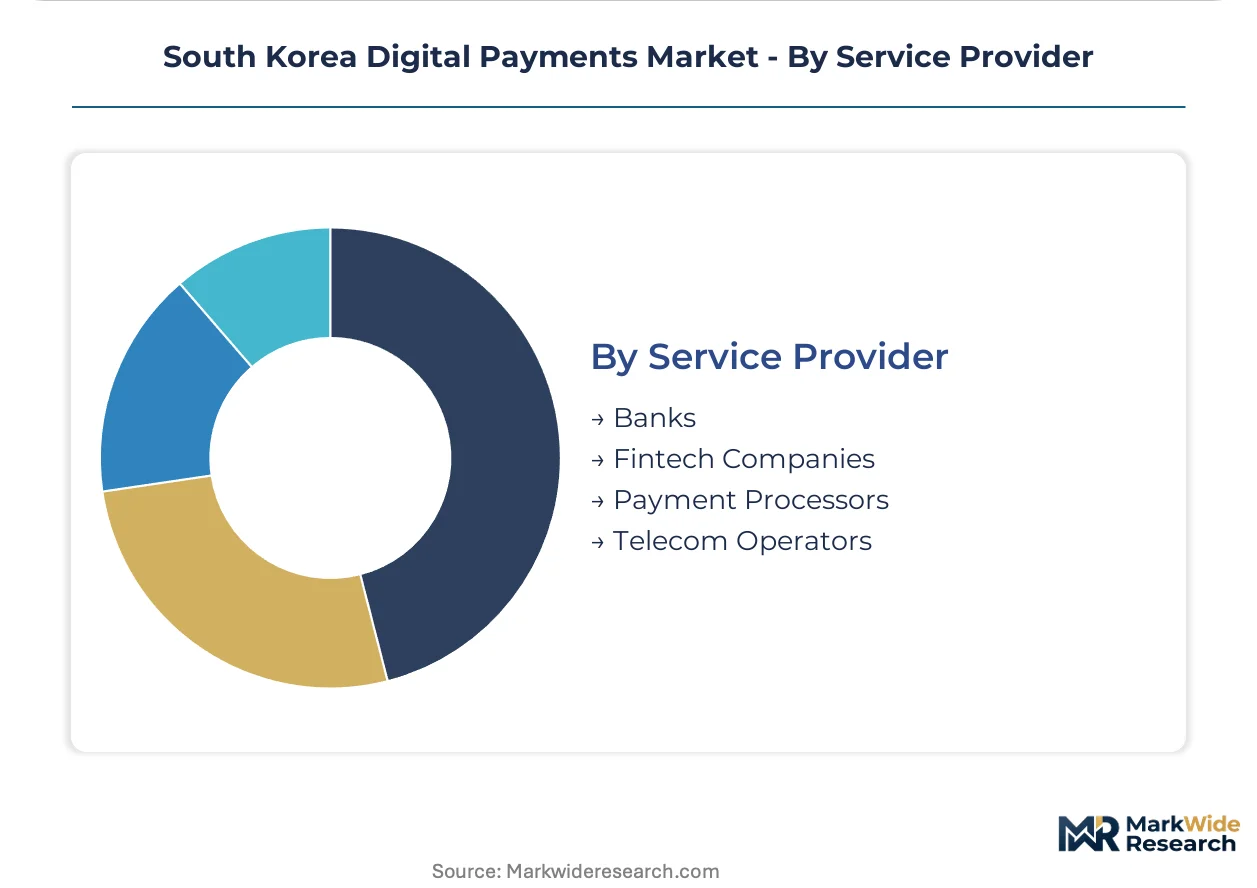
Service Provider:
Supply concentration among licensed operators creates divergent margin structures based on capital reserve requirements and compliance infrastructure scale.
- Fintech Companies:Agile platform architectures enable rapid feature deployment across non-financial daily activities. Viva Republica and comparable independents build dedicated legal infrastructure to satisfy MFDS-aligned data governance standards rather than relying on bank partnerships.
- Banks:Incumbent institutions maintain proprietary settlement rails and core banking integration advantages that resist full API standardization. Credit card reward ecosystems lock in consumer switching costs through loyalty program entrenchment.
- Payment Processors:Merchant acquiring specialization demands PCI-DSS compliant encryption talent concentrated in limited Seoul engineering pools.
- Telecom Operators:Carrier billing integration targets underbanked segments and microtransaction environments.
Regulatory licensing favors Banks; the innovation velocity concentrates with Fintech Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Seoul metropolitan area concentrates transaction volumes through merchant density and consumer digital literacy clusters. The Financial Services Commission's open banking directives reshape interoperability standards across the nation. SME adoption accelerates in secondary urban centers beyond the capital corridor.
Seoul Capital Area
Super-app platforms embed payment workflows into daily communication habits among Generation Z users. The Financial Services Commission enforces e-money licensing frameworks with real-time transaction monitoring requirements. Gangnam and Yeouido financial districts host dense fintech engineering pools for PCI-DSS compliant encryption talent.
Busan-Ulsan
Mid-sized retail chains in fashion and specialty goods drive unified commerce platform adoption. The Bank of Korea's retail payment finality system enables instant settlement for high-frequency hospitality transactions. Haeundae and Seomyeon commercial clusters witness integrated software vendors displacing standalone terminal providers.
Daegu-Gyeongbuk
Convenience store chains and quick-service restaurants deploy biometric authentication at point-of-sale terminals. MFDS-aligned data governance standards expand compliance requirements for regional payment operators. Dongseongno district anchors merchant acquisition as contactless adoption accelerates among local retail networks.
Daejeon-Sejong
Government district proximity creates demand for automated expense management and corporate card integration. KISA cybersecurity certification requirements ensure fraud protection standards for public sector procurement. Sejong administrative city drives B2B account-to-account settlement for high-value transactions requiring enhanced audit trails.
Gwangju-Honam
Underpenetrated SME hospitality and retail segments present merchant acquisition targets outside Seoul gravity. Anti-money laundering surveillance thresholds reshape market access rules for non-bank payment providers. Honam region commercial corridors lag in mobile wallet penetration despite accelerating contactless infrastructure deployment.
South Korea Digital Payments Market Competitive Landscape
The competitive structure tilts toward super-app ecosystems with captive user bases across non-financial daily activities. Fintech independents build dedicated compliance infrastructure rather than relying on bank partnerships. Two strategic archetypes dominate: vertically integrated platform operators bundling transportation-to-wealth management services, and specialized payment processors targeting SME merchant acquisition. M&A activity concentrates on merchant software integration capabilities, while strategic partnerships focus on open API standardization mandates.
Within the super-app archetype, Viva Republica and Kakao Corporation exemplify platform operators embedding financial services into habitual communication workflows. Naver Corporation occupies a position among internet portal-based payment networks leveraging search-to-commerce user journeys. Samsung Electronics represents hardware-anchored wallet providers integrating device-native authentication protocols. These three entities collectively illustrate how consumer mindshare concentration shapes competitive moats between bank-owned and independent settlement rails.
| Leading Market Players |
|---|
| Viva Republica |
| SK Group |
| Kakao Corporation |
| SSG com Corp |
| Coupang |
| Naver Corporation |
| PayCo |
| ZeroPay Pvt Ltd |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fintech specialists anchor supply-side concentration in South Korea's digital payments infrastructure, creating pricing discipline through consolidated merchant acquiring networks and captive settlement rail access. Their ownership structure funnels capital toward compliance infrastructure scale, erecting cost barriers that compress margins for unconsolidated regional operators outside Seoul.
Pricing Analysis
Value-based pricing tied to transaction throughput and merchant settlement velocity anchors the dominant model. Three-tier pricing structure across premium API access, standard gateway services, and economy-tier basic acquiring separates tier-1 fintech platforms from bank-owned rails from independent regional processors. Cost compression in the economy tier is intensifying because KISA cybersecurity certification requirements extend engineering overhead. SME hospitality merchants in secondary cities exhibit highest price sensitivity; enterprise retail chains in Gangnam demonstrate lowest sensitivity due to integrated software bundling.
Supply Chain Analysis
KISA cybersecurity certification and MFDS data governance standards gate upstream access to payment infrastructure components. Hardware manufacturing concentrates in China, Taiwan, and South Korea for NFC terminals and biometric sensors. Software stacks draw from domestic engineering pools in Seoul and open-source cryptographic libraries. Single-source vulnerability runs through the Bank of Korea's real-time gross settlement backbone. Distribution runs through integrated software vendors and direct merchant sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's digital payments sector is consolidating as open banking mandates and compliance cost inflation force weaker regional operators toward exit. The Financial Services Commission's interoperability directives accelerate this pressure by eroding closed-loop ecosystem moats.
For Market Incumbents: Anchor merchant relationships through super-app vertical bundling spanning transportation, wealth management, and daily commerce workflows. Invest in dedicated PCI-DSS compliant encryption talent pools in Yeouido and Gangnam to defend against fintech independents. Build proprietary settlement rail integrations that resist full API standardization mandates from the Financial Services Commission. For New Entrants and Emerging Players: The Financial Services Commission's e-money licensing deregulation in South Korea opens a window for specialized SME acquiring in Busan and Daegu metropolitan clusters. Target mid-sized retail chains in fashion and specialty goods with unified commerce platforms that displace standalone terminal providers. Pursue biometric authentication partnerships with convenience store chains as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional payment processors with KISA certification infrastructure in Gwangju-Honam and Daejeon-Sejong corridors. Long-term viability hinges on captive merchant bases and compliance infrastructure scale rather than transaction volume alone. Watch for inflection when the Financial Services Commission announces revised anti-money laundering surveillance thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Super-App Vertical Integration | Transportation-to-wealth management bundling captures daily user habits across Seoul metropolitan usage patterns. |
| Biometric Authentication Deployment | Facial recognition at convenience store POS terminals compresses transaction time and reduces card-present fraud vectors. |
| SME Merchant Acquisition Expansion | Mid-sized retail chains in Busan and Daegu present underpenetrated targets for unified commerce platforms. |
| Compliance Infrastructure Investment | Dedicated legal and technical teams satisfy MFDS data governance without reliance on bank partnerships. |
| Open API Standardization Partnership | Interoperability mandates from the Financial Services Commission reshape competitive positioning between bank-owned and independent rails. |
Research Methodology
Document review covered Financial Services Commission regulatory filings, Bank of Korea payment system disclosures, and KISA cybersecurity certification records, complemented by interviews with fintech platform executives, merchant acquiring specialists, and compliance officers at domestic payment providers. Secondary validation drew from MFDS data governance guidelines, open banking directive documentation, and Seoul metropolitan area commercial district transaction studies. Bottom-up merchant adoption modeling and top-down regulatory impact assessment were triangulated against real-time settlement volume indicators.
Market sizing outputs reflect segment-level modeling across payment method, transaction type, user demographic, and service provider dimensions, with additional granularity on super-app versus standalone platform architectures. CAGRs were derived from trend extrapolation of Generation Z mobile wallet penetration curves and SME contactless adoption rates. Forecast inputs incorporated Biometric authentication deployment timelines and e-money licensing threshold revisions.
The model assumes a particular technology adoption path; alternative pathways for facial recognition and fingerprint verification at retail POS would alter the outlook. Forecasts reflect assumptions about open banking API interoperability implementation speed and merchant software integration consolidation rates. A model refresh is warranted upon material change in Financial Services Commission e-money licensing or KISA cybersecurity certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Card Reader Market
Payments
Canada Prepaid Cards Market
Payments
Global Mobile Payment Technology Market
Payments
Germany Payments Market
Payments
Argentina Payments Market
Payments
Spain Payments Market
Payments
France Mobile Payment Market
Payments
Japan Mobile Payments Market
Payments
B2B Payments Platform Market
Payments
Cash Management System Market
Payments
Payment Card Market
Payments
Hong Kong Payments Market
Payments
South Korea POS Terminals Market
Payments
Global Prepaid Cards Market
Payments
Saudi Arabia Cash Management Services Market
Payments
US Gift Card and Incentive Card Market