
 Kenya Mobile Money Market | 2026-2036
Kenya Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Mobile Money Market Intelligence
Merchant payment adoption among small enterprises is expanding as Kenya's informal sector digitizes. Safaricom M-Pesa leverages its agent network density to sustain dominance in rural last-mile access. Airtel Money competes on pricing to anchor share among price-sensitive consumer segments. PesaPal specializes in online merchant checkout integration, occupying the e-commerce payment gateway niche.
Mobile money denotes electronic wallet services accessible via basic mobile phones or smartphones, enabling fund storage, transfer, and payment through encrypted SIM toolkit menus, mobile applications, or unstructured supplementary service data sessions. The technology serves as Kenya's dominant retail payment infrastructure, replacing cash in domestic commerce. Peer-to-Peer Transfers retain the largest transaction volume pool, though Merchant Payments generate superior fee-based revenue per transaction. USSD technology leads in rural penetration where smartphone ownership remains limited, while Mobile Apps capture urban consumer preference for feature-rich interfaces.
The Central Bank of Kenya enforces capital adequacy and consumer protection standards through the National Payments System Act, while the Communications Authority of Kenya mandates SIM registration and platform security audits. These frameworks elevate compliance costs for new entrants but reinforce trust in licensed operators. Stakeholders must monitor interoperability mandate enforcement and central bank digital currency pilot outcomes to anticipate platform strategy pivots.
Market Dynamics
The Central Bank of Kenya's interoperability mandates are forcing platform consolidation as agents and merchants demand seamless fund movement across wallets. This regulatory pressure compresses margins while elevating technical requirements for market access.
Growth Catalysts
- Nairobi's Urban Corridor Concentration:Peri-urban counties surrounding the capital generate dense transaction volumes that subsidize rural network expansion through cross-subsidization economics.
- National Payments System Act:The Central Bank of Kenya's licensing framework creates consumer trust barriers that protect incumbent investments in agent infrastructure.
- Informal Sector Digitization:Small enterprises in Kenya's jua kali economy adopt merchant acceptance codes to replace cash handling costs and security risks.
Market Restraints
- Agent Network Concentration:Last-mile cash-in/cash-out liquidity depends on Safaricom's proprietary agent density, creating single-point dependency in rural counties.
- USSD Technical Limitations:Session timeouts and menu navigation friction constrain transaction complexity compared to smartphone applications.
- Smartphone Ownership Gaps:Feature phone dependence in rural Kenya limits advanced service adoption and API integration for merchant ecosystems.
Strategic Opportunities
- Western Kenya Agricultural Corridors:Underpenetrated counties in the Lake Victoria basin present white space for crop payment digitization and input financing.
- API Convergence with Banking:Mobile money platforms integrating with core banking systems enable salary disbursement and loan repayment automation.
- Central Bank Digital Currency Pilots:Regulatory sandbox participation offers first-mover positioning for interoperable settlement infrastructure.
Industry Challenges
- Agent Liquidity Management:Float balancing across thousands of dispersed cash points requires real-time predictive analytics and working capital optimization.
- Interoperability Integration Complexity:Legacy platform architectures demand substantial API redevelopment to meet Central Bank of Kenya switching requirements.
- Fraud Detection Talent Scarcity: Machine learning engineering capabilities for transaction monitoring remain concentrated in Nairobi's technology labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Mobile Money Market |
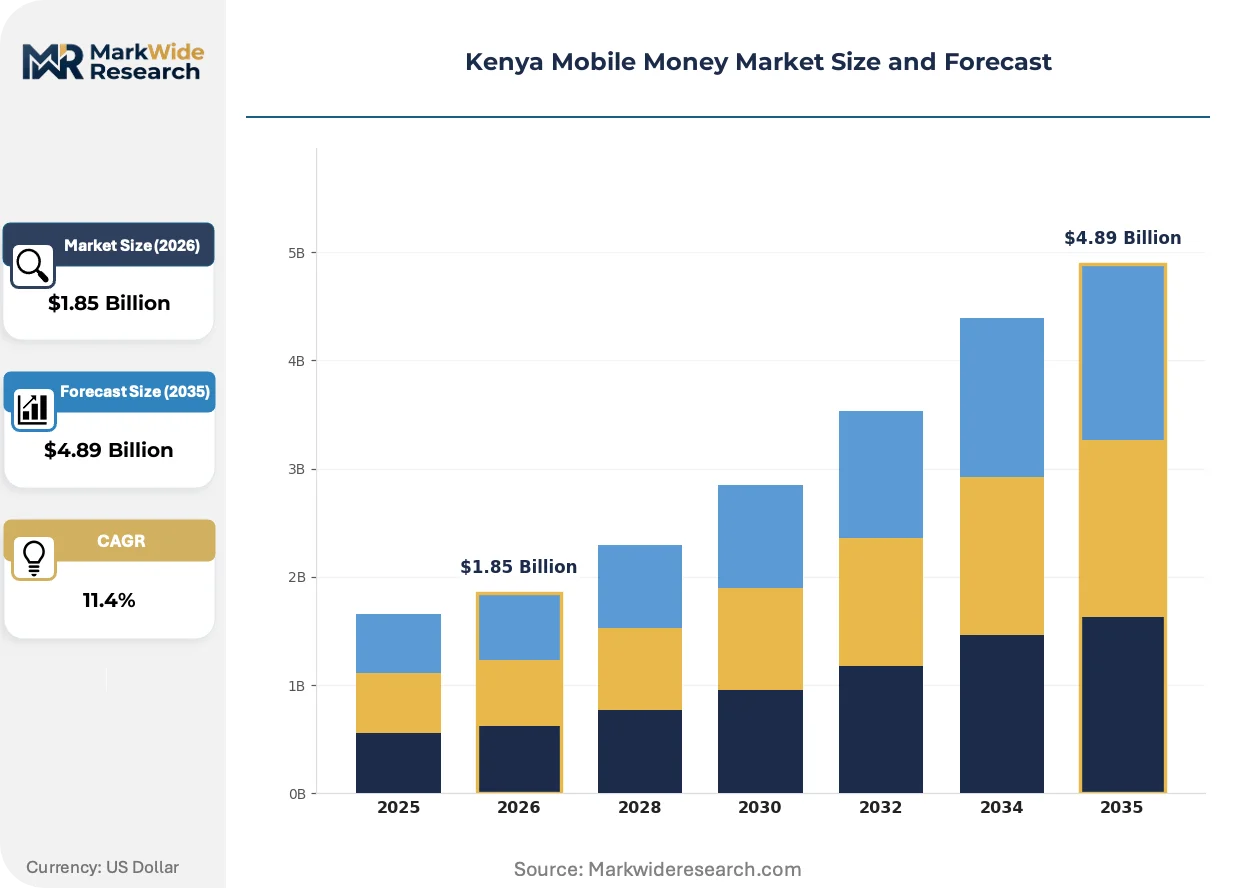
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer Transfers, Bill Payments, Merchant Payments, Savings Technology: USSD, Mobile Apps, Online Portals, NFC User Type: Consumers, Small Enterprises, Corporates, NGOs Transaction Value: Low Value, Medium Value, High Value, Microtransactions |
| Companies Covered | Cellulant, Craft Silicon, Safaricom M-Pesa, Intrepid Data Systems, Africa’s Talking, Airtel Money, PesaPal, Chipper Cash, Telkom T-Kash, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Mobile Money Market Strategic Shifts & Innovations
Platform architecture decisions in Kenya's mobile money sector now pivot on regulatory compliance velocity rather than feature differentiation. Technical investments concentrate on interoperability readiness and merchant ecosystem depth.
Super-app functionality is absorbing standalone payment use cases as platforms bundle savings, credit, and insurance into unified interfaces. Urban smartphone users in Nairobi and Mombasa adopt these consolidated services fastest. This convergence is compressing standalone fintech application viability and forcing niche players toward white-label infrastructure provision.
The Central Bank of Kenya's National Payments System regulations now mandate real-time settlement and capital adequacy disclosures that match commercial banking standards. This elevates compliance costs disproportionately for smaller operators. Tier-2 providers in the Kenyan market are responding through shared infrastructure consortia and API standardization alliances.
Merchant procurement of payment acceptance is fragmenting across multiple wallet providers as interoperability reduces single-platform lock-in. Small enterprises in Kisumu and Nakuru now routinely display three to four acceptance codes. This behavior is most visible in retail and hospitality verticals where consumer wallet diversity is highest.
Kenya Mobile Money Market Segmentation
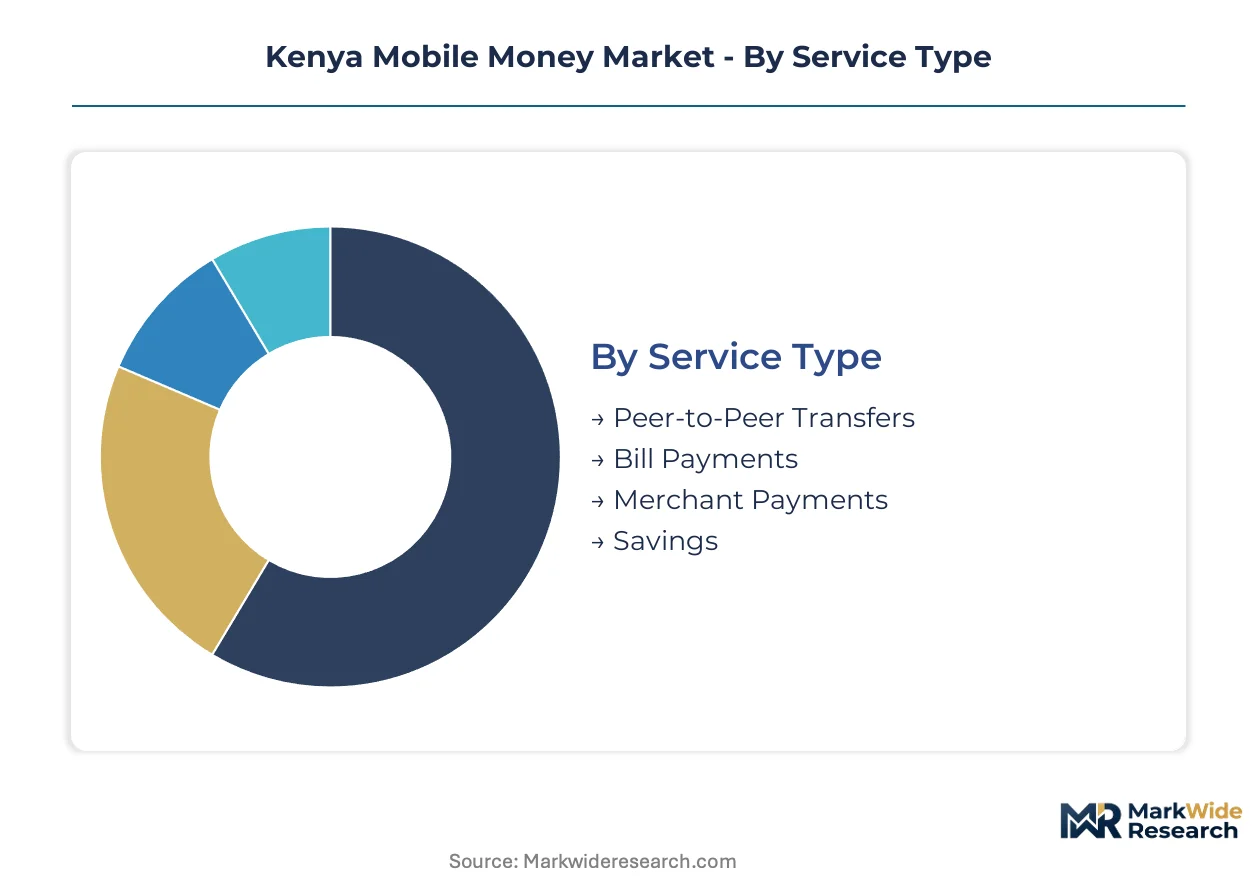
Segmentation in Kenya's mobile money market reveals how transaction economics and infrastructure constraints shape platform architecture. Understanding these divisions clarifies where interoperability investments generate returns and which user categories justify specialized product development.
Service Type:
Transaction purpose determines fee structure, settlement timing, and regulatory treatment across the Kenyan market.
- Peer-to-Peer Transfers:Direct wallet-to-wallet movement between individuals dominates transaction count in Kenya's mobile money infrastructure. Rural corridors rely on this service for remittance flows from Nairobi's urban corridor to family networks in peri-urban counties.
- Merchant Payments:Point-of-sale acceptance codes enable small enterprises to replace cash handling. Kisumu and Nakuru retailers now display multiple wallet acceptance codes as interoperability reduces single-platform lock-in.
- Bill Payments:Recurring utility and subscription settlements through mobile money. Kenya Power and water utilities drive concentrated demand in metropolitan zones.
- Savings:Interest-bearing wallet balances and locked savings products. M-Shwari and competing platforms target consumers lacking formal banking relationships.
Volume sits with Peer-to-Peer Transfers; growth tilts toward Merchant Payments.
Technology:
Device capability and network coverage create distinct technical requirements for platform delivery.
- USSD:Encoded SIM toolkit menus enable transactions on basic feature phones without data connectivity. Rural Kenya depends on this technology where smartphone ownership remains limited and 2G networks persist.
- Mobile Apps:Smartphone applications deliver feature-rich interfaces with biometric authentication and merchant ecosystem integration. Nairobi and Mombasa urban consumers prefer this channel for complex transactions.
- Online Portals:Web-based interfaces for corporate treasuries and bulk disbursement operations. NGOs and salary processors utilize these channels for automated payment runs.
- NFC:Contactless proximity payments at equipped merchant terminals. Deployment concentrates in premium retail locations within the capital's central business district.
USSD carries the transaction load; Mobile Apps capture the steepest expansion trajectory.
User Type:
Organizational scale and financial sophistication dictate service bundling and support requirements.
- Consumers:Individual account holders conducting personal transactions. This segment spans rural subsistence users to urban professionals with divergent feature needs.
- Small Enterprises:Informal sector operators in Kenya's jua kali economy. These merchants adopt acceptance codes to eliminate cash security risks and simplify tax documentation.
- Corporates:Formal businesses with treasury management and payroll integration demands. API connectivity to core banking systems distinguishes service providers competing for this category.
- NGOs:Development organizations requiring transparent fund disbursement and beneficiary tracking. Western Kenya agricultural corridors present white space for crop payment digitization targeting this user type.
Consumers generate the volume base; Small Enterprises are expanding most quickly.
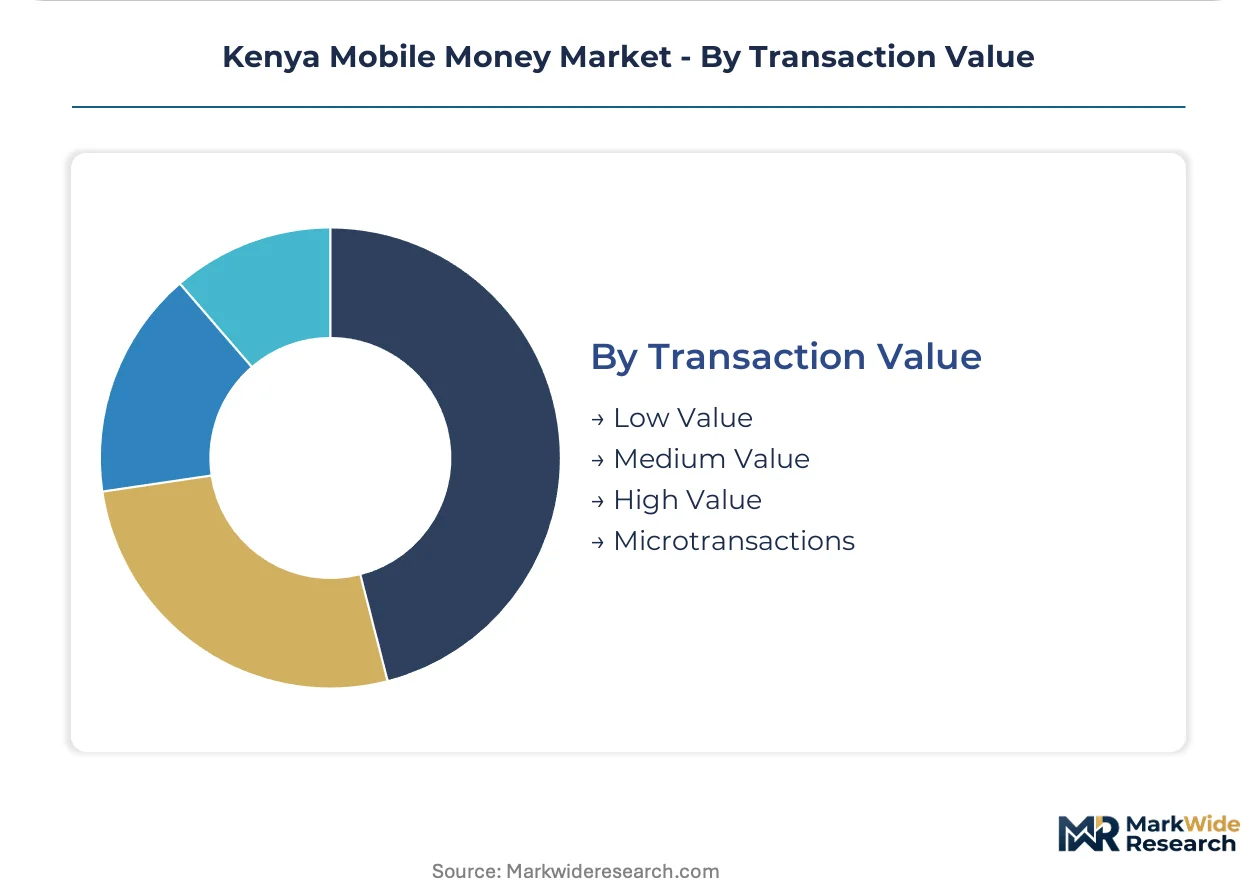
Transaction Value:
Monetary thresholds determine risk scoring, KYC requirements, and fee tiering across platform operations.
- Low Value:Transactions below regulated thresholds with streamlined authentication. Agent cash-in/cash-out operations concentrate in this band across rural counties.
- Medium Value:Mid-range transfers requiring enhanced verification. Salary payments and supplier settlements in peri-urban manufacturing zones populate this category.
- High Value:Large transfers subject to full KYC and real-time monitoring. Corporate procurement and property transactions in Nairobi's commercial districts drive demand.
- Microtransactions:Sub-threshold payments for digital content and transport fares. Matatu operators and kiosk vendors process millions of these daily.
Microtransactions dominate frequency; High Value delivers the strongest fee yield per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Konza Technopolis anchors Kenya's mobile money concentration through its special economic zone status and digital infrastructure incentives. The government's Vision 2030 flagship project attracts fintech operations seeking regulatory sandbox access and fiber connectivity. Tax holidays and streamlined licensing draw payment platform development to this corridor.
Nairobi Metropolitan Area
Nairobi generates the densest transaction volumes through its concentration of corporate headquarters, banking infrastructure, and technology labor pools. The Central Bank of Kenya's headquarters enforces National Payments System Act compliance from this location. Westlands and Upper Hill districts host the majority of mobile money platform operations and API development centers.
Central Kenya Highlands
Tea and coffee cooperative payment digitization drives adoption across Nyeri, Murang'a, and Kiambu counties. The Agriculture Finance Corporation's crop payment programs mandate mobile disbursement channels. Thika's industrial zone factories process salary payments through integrated mobile-banking APIs, creating concentrated B2B transaction flows.
Rift Valley Corridor
Nakuru and Eldoret serve as logistics hubs where transport sector payments and agricultural supply chain settlements concentrate. The Kenya National Highways Authority's toll collection pilots test interoperable wallet acceptance. Mombasa Road freight operators display multiple mobile money acceptance codes at weighbridges and fuel stations.
Western Kenya Lake Basin
Kisumu and surrounding counties present underpenetrated white space for crop input financing and fishing cooperative digitization. The Lake Basin Development Authority promotes mobile payment adoption among smallholder farmers. Busia and Malaba border posts generate cross-border remittance corridors into Uganda.
Coastal Kenya
Mombasa's port economy and tourism sector drive merchant payment adoption in hospitality and logistics verticals. The Kenya Ports Authority's cargo clearance fee digitization mandates mobile payment channels. Diani and Malindi resort corridors display diversified wallet acceptance as visitor payment preferences fragment.
Kenya Mobile Money Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in Kenya's mobile money infrastructure. The market exhibits tiered concentration with one dominant network operator and several specialized challengers. Three archetypes define competitive positioning: agent-network incumbents, API-first fintechs, and bank-integrated platforms. M&A activity concentrates on technology capability acquisition, while partnership strategies dominate expansion into underpenetrated agricultural corridors.
Among Nairobi-headquartered platform operators, Safaricom M-Pesa and Airtel Money exemplify the agent-network incumbent archetype through their telecommunications heritage. PesaPal occupies a position within the API-first specialist tier, anchoring e-commerce payment gateway services. Cellulant represents the bank-integrated platform model with its enterprise-facing infrastructure focus.
| Leading Market Players |
|---|
| Cellulant |
| Craft Silicon |
| Safaricom M-Pesa |
| Intrepid Data Systems |
| Africa's Talking |
| Airtel Money |
| PesaPal |
| Chipper Cash |
| Telkom T-Kash |
| Others |
Cost & Logistics Intelligence
Captive agent network integration anchors Safaricom M-Pesa's supply position and pricing power across Kenya's mobile money infrastructure. This vertical control over last-mile liquidity provisioning locks in merchant acceptance premiums while compressing challenger margins.
Pricing Analysis
Short lead-time liquidity provisioning commands premium pricing in agent cash-in/cash-out operations. Three-tier pricing structure across premium, standard, and economy levels segments by transaction velocity and agent tier certification. Cost compression in rural corridors is intensifying because interoperability mandates force revenue sharing across previously siloed wallets. Small enterprises in Kisumu and Nakuru display the highest price sensitivity, while corporate treasuries in Nairobi's Westlands district prioritize API reliability over fee minimization.
Supply Chain Analysis
Central Bank of Kenya licensing and agent certification gating restricts supply-side participation to capitalized operators. Hardware sourcing concentrates in China, South Korea, and Taiwan for POS terminals and secure element chips. Platform architecture rests on proprietary switching infrastructure, telecom-grade data centers, and agent biometric devices. Single-source vulnerability in Safaricom's proprietary agent management system creates systemic concentration risk. Distribution runs through tiered agent hierarchies: master agents, sub-agents, and merchant aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agent network capacity constraints prop pricing power for licensed operators. Float balancing bottlenecks at rural cash points limit challenger scale-up velocity.
For Market Incumbents: Hedge against interoperability margin compression by deepening API banking convergence and acquiring specialized merchant checkout providers. The Central Bank of Kenya's real-time settlement mandates threaten legacy platform architectures. Priority investment in predictive analytics for agent liquidity optimization defends network effects against Airtel Money's pricing aggression.
For New Entrants and Emerging Players: Agricultural cooperative secretaries in Western Kenya's Lake Victoria basin present underexploited distribution partnerships. Crop input financing and fishing cooperative digitization offer the most penetrable white space. Go-to-market through NGO disbursement contracts builds transaction volume without competing head-on for urban merchant acceptance.
For Investors and Strategic Acquirers: Exit pathways concentrate in API-first infrastructure specialists with enterprise banking integration depth. Long-term viability favors platforms with regulatory sandbox participation and central bank digital currency pilot positioning. Watch interoperability enforcement velocity as the inflection signal for margin structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Agent Network Densification | Expands last-mile liquidity access in underpenetrated Western Kenya agricultural corridors. |
| API Banking Integration | Enables automated salary disbursement and loan repayment for Thika industrial zone factories. |
| Merchant Ecosystem Bundling | Absorbs standalone payment use cases into super-app savings, credit, and insurance interfaces. |
| Interoperability Compliance Investment | Satisfies Central Bank of Kenya switching mandates while elevating technical barriers for challengers. |
| Regulatory Sandbox Participation | Positions platforms for central bank digital currency settlement infrastructure first-mover advantage. |
Research Approach
Document review covered Central Bank of Kenya National Payments System Act filings, Communications Authority of Kenya regulatory circulars, and mobile network operator annual reports, complemented by interviews with platform engineering directors, agent network managers, and agricultural cooperative secretaries. Secondary validation drew from East African banking sector disclosures, fintech investment databases, and customs records for POS terminal imports. Bottom-up transaction volume modeling and top-down GDP-proxy triangulation anchored market sizing.
Cross-referencing historical adoption curves against expert panel inputs shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type, technology channel, user organizational scale, and transaction value tier. CAGRs derived from trend extrapolation adjusted for regulatory intervention timing and smartphone penetration trajectories. Forecast inputs incorporated M-Pesa agent density expansion rates and interoperability mandate enforcement schedules.
Caveats apply where central bank digital currency pilot outcomes or interoperability technical standard revisions could materially shift the outlook. Forecasts reflect assumptions about agent commission structures and rural network coverage economics. A model refresh is warranted upon material change in Central Bank of Kenya switching infrastructure mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Utility Billing Software Market
Payments
United States POS Terminals Market
Payments
North America Accounts Payable Automation Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Japan Real Time Payment Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Croatia POS Terminals Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Spain POS Terminals Market
Payments
Saudi Arabia Mobile Payments Market
Payments
South Korea Payments Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
LAMEA Payment Gateway Market
Payments
Spain Payment Gateway Market
Payments
Canada Gift Card and Incentive Card Market
Payments
E-Commerce Payments Market