
 Fuel Cards Market | 2026-2036
Fuel Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cards Market Intelligence
Fleet payment networks is rewriting how commercial fuel procurement reaches dispersed vehicle pools. FleetCor Technologies leverages its merchant acquiring density across North America to sustain toll and maintenance bundling on fuel card rails. WEX Inc. competes through data analytics platforms that anchor fleet expense visibility for enterprise clients. DKV Mobility dominates European corridor acceptance, controlling overland freight payment infrastructure from the Baltics to Iberia.
Fuel cards are closed-loop or open-loop payment instruments issued to vehicle operators, embedding vehicle identification numbers, driver PINs, and odometer capture fields to authenticate transactions at fueling points. These instruments streamline VAT recovery, prevent fraudulent purchases, and enforce fuel-type restrictions at the point of sale. Fleet cards lead transaction volume among card types due to their embedded spend controls and universal acceptance across branded networks. Prepaid structures attract small fleet operators seeking working capital discipline, while postpaid hybrid arrangements concentrate among national logistics chains optimizing cash conversion cycles.
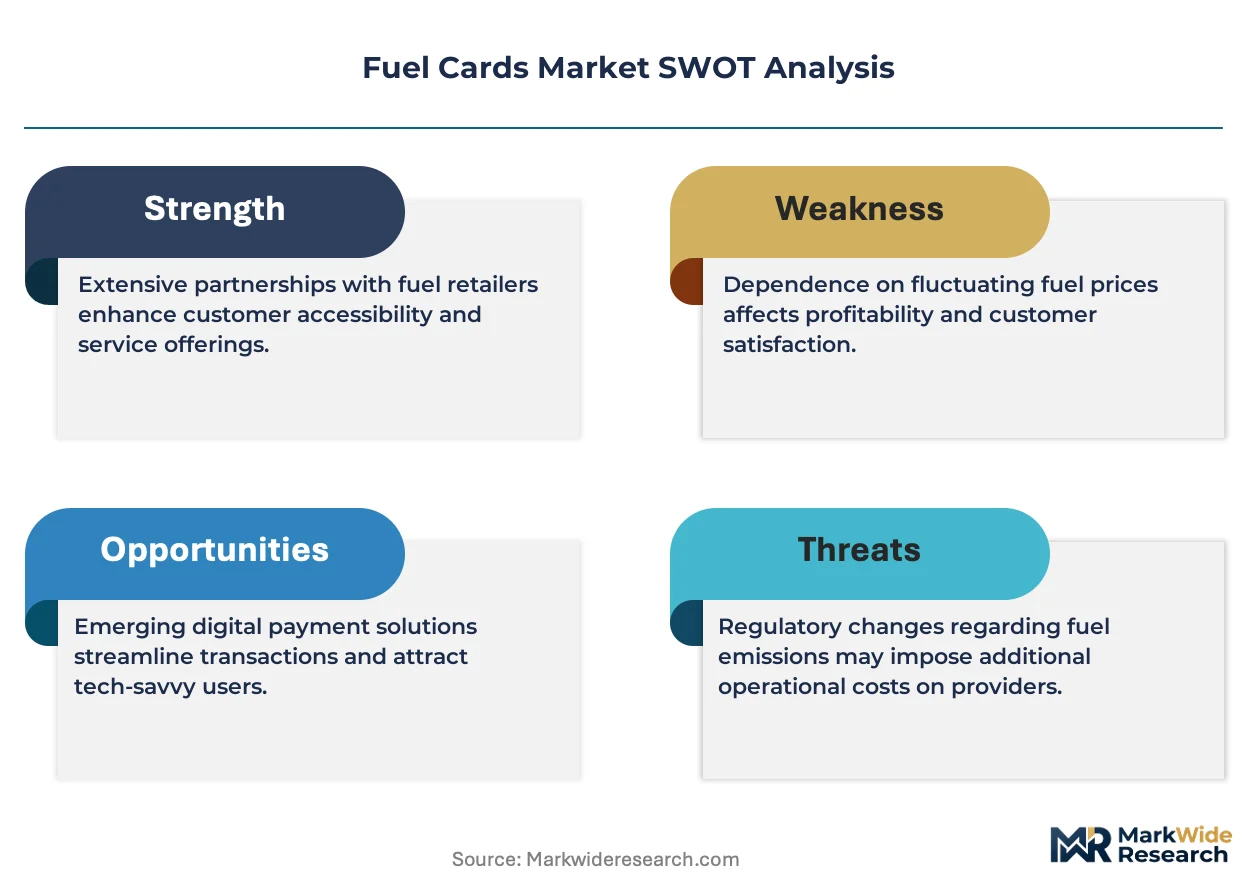
FCC regulations govern telematics data transmission from fuel card terminals, while PCI DSS standards enforce encryption protocols for card-not-present fleet reloads. The EU Green Deal's transport decarbonization targets are redirecting fuel card networks toward alternative fuel acceptance infrastructure. Stakeholders must monitor how open banking APIs and real-time payment rails disintermediate traditional fleet card intermediaries before network effects lock in next-generation platforms.
Market Dynamics
EMV chip mandates from payment networks are forcing fuel card issuers to replace magnetic-stripe infrastructure fleet-wide, compressing upgrade timelines while telematics integration demands simultaneous capital deployment.
Growth Catalysts
- EU Green Deal transport targets:Decarbonization mandates are redirecting fleet card networks toward hydrogen and electric charging acceptance infrastructure across European freight corridors.
- Real-time telematics:FCC-regulated data transmission protocols enable geofenced transaction authorization and automated odometer capture, tightening spend control for logistics operators.
- Long-haul logistics densification:Commercial fleet operators in the United States are consolidating fuel procurement onto card rails to streamline VAT recovery across interstate routes.
Market Restraints
- EMV migration capex burden:Small fleet operators face terminal replacement costs and certification delays that extend payback periods beyond typical working capital cycles.
- Acceptance network fragmentation:Closed-loop fuel cards lock users into branded station networks, creating coverage gaps in rural corridors and cross-border freight lanes.
- PCI DSS compliance complexity:Encryption protocol requirements for card-not-present reloads impose ongoing audit costs and technical staffing demands on regional issuers.
Strategic Opportunities
- German hydrogen corridor buildout:Alternative fuel acceptance infrastructure investments align with federal freight decarbonization subsidies and anchor early-mover network effects.
- Open banking API integration:Real-time payment rails enable direct bank-to-fleet settlement, disintermediating traditional card network interchange structures before platform lock-in.
- Prepaid working capital products:Small fleet segments in China seek disciplined cash conversion tools as alternative to postpaid hybrid arrangements dominating national logistics chains.
Industry Challenges
- Telematics-legacy POS integration:Fueling point terminals require firmware overhauls to capture vehicle identification numbers and driver PINs simultaneously, stretching IT deployment timelines.
- Cross-border VAT reconciliation:Multi-jurisdiction transaction reporting demands specialized accounting functions that mid-size fleet operators struggle to staff internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cards Market |
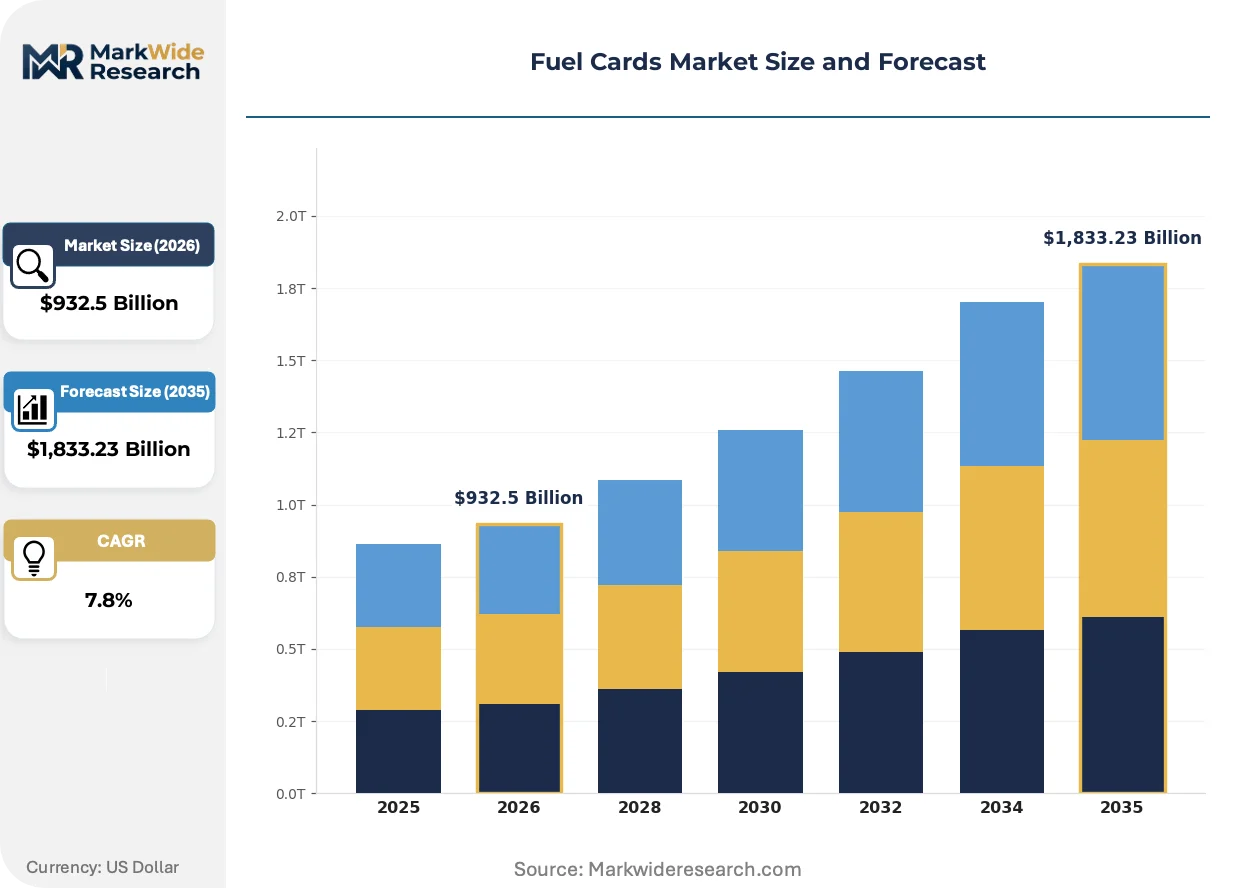
| Market Size in 2026 | $932.5 Billion |
| Market Size in 2035 | $1,833.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Debit Cards, Credit Cards, Fleet Cards, Loyalty Cards Payment Structure: Prepaid, Postpaid, Hybrid, Subscription User Segment: Businesses, Government, Individuals, Fleets Fuel Type: Petrol, Diesel, Alternative Fuels, Others |
| Companies Covered | BP p.l.c., Exxon Mobil Corporation, FleetCor Technologies, Inc., WEX Inc., Shell plc, TotalEnergies SE, Chevron Corporation, DKV Mobility, UTA Edenred, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cards Market Strategic Shifts & Innovations
Payment infrastructure convergence with vehicle telematics is collapsing the distinction between fuel procurement and fleet management platforms, forcing issuers to compete on data analytics depth rather than transaction processing alone.
Contactless EMV fuel card terminals with embedded NFC readers are rendering obsolete magnetic-stripe pumps at high-volume trucking stops. National logistics chains in Germany and the United States are deploying these units at replacement rates exceeding standard equipment refresh cycles. This hardware transition is compressing issuer margins while demanding simultaneous software stack upgrades for real-time authorization.
The EU Green Deal's transport decarbonization framework is redirecting fuel card network investment toward alternative fuel acceptance points. Issuers must retrofit terminals for hydrogen dispensing and electric vehicle charging authentication, diverting capital from conventional petroleum infrastructure. European corridor operators face the steepest compliance curves as member states accelerate freight electrification timelines.
Fleet expense visibility platforms are unbundling traditional card-issuer relationships as enterprise buyers demand standalone analytics tools. Large logistics operators in China and the United States are consolidating procurement decisions around data integration capabilities rather than network coverage breadth. This procurement pattern shift favors technology vendors with API-first architectures over legacy payment processors with closed data ecosystems.
Fuel Cards Market Segmentation
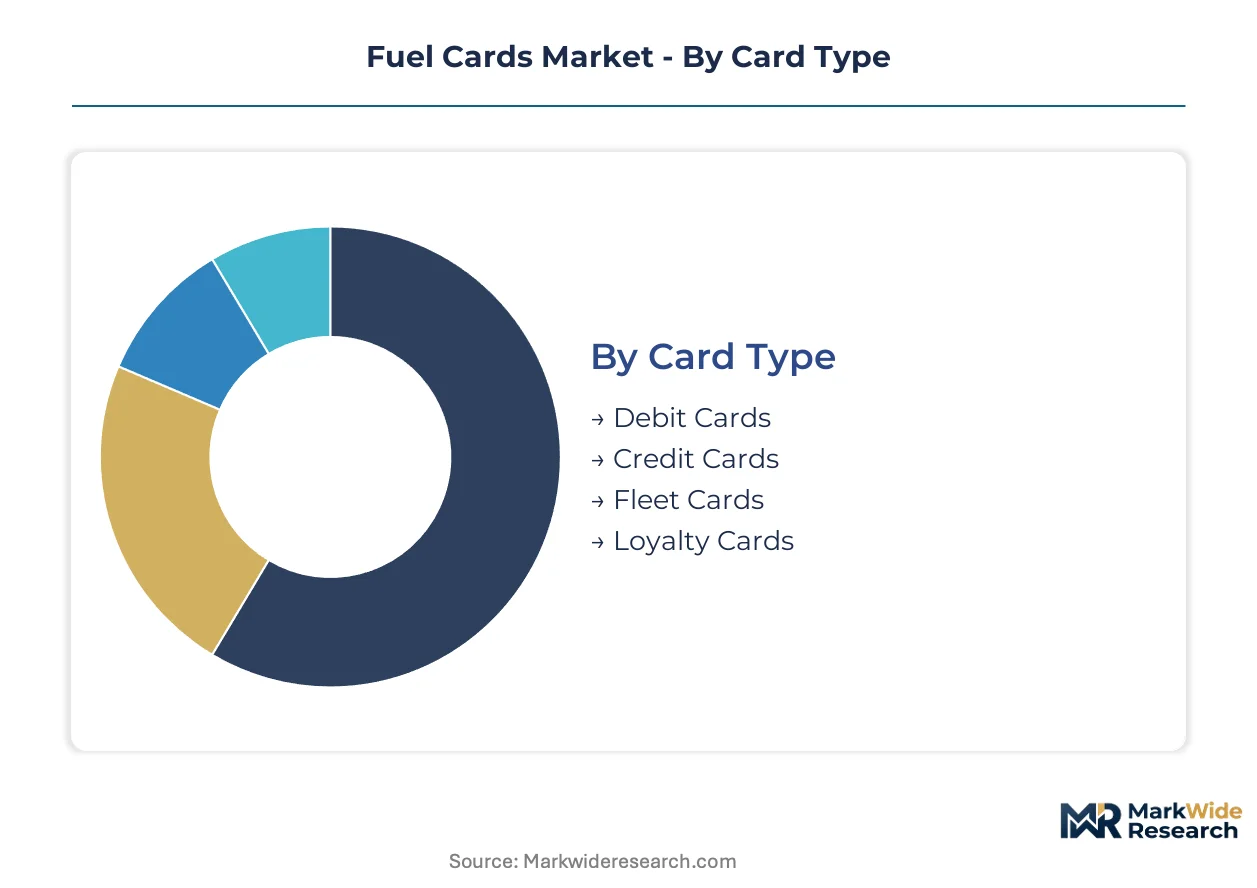
Fuel card segmentation reveals distinct service intensity profiles across card types and user structures. Fleet operators demand embedded telematics support and real-time spend controls that reshape issuer technology roadmaps. Payment structure preferences diver sharply between working-capital-constrained small fleets and enterprise buyers optimizing cash conversion cycles.
Card Type:
After-sales service intensity varies dramatically across card types, with fleet cards requiring continuous telematics integration and loyalty cards demanding ongoing merchant program management.
- Fleet Cards:These instruments embed vehicle identification numbers, driver PINs, and odometer capture fields for authenticated fueling transactions. Long-haul logistics operators in the United States concentrate procurement on fleet cards to enforce fuel-type restrictions and streamline interstate VAT recovery. Real-time geofencing and automated spend controls anchor their commercial appeal.
- Credit Cards:Open-loop payment instruments issued through banking networks, carrying revolving credit facilities and interchange-based economics. National logistics chains in Germany favor credit card rails for their universal acceptance across hydrogen corridor infrastructure. The EU Green Deal's alternative fuel investments are redirecting credit card network priorities toward charging authentication protocols.
- Debit Cards:Direct-account-linked instruments with immediate settlement, appealing to small fleet operators seeking working capital discipline. Immediate fund deduction eliminates post-reconciliation complexity for owner-operators.
- Loyalty Cards:Program-specific instruments tied to branded fuel station networks, offering volume rebates and points accumulation. Merchant acquiring density determines program viability across rural corridors.
By volume, fleet cards lead. By growth pace, credit cards are ahead as open-loop infrastructure expands.
Payment Structure:
Cost tier stratification separates prepaid discipline tools from postpaid working capital optimization platforms.
- Postpaid:Invoice-based settlement with 30-60 day terms, dominating national logistics chains optimizing cash conversion cycles. Enterprise buyers in China consolidate procurement decisions around postpaid hybrid arrangements that embed data analytics platforms.
- Prepaid:Fund-loaded instruments with immediate balance availability, attracting small fleet segments seeking strict expenditure control. Working capital discipline drives adoption among owner-operators across North American freight corridors.
- Hybrid:Combined prepaid-postpaid structures with tiered authorization limits, serving mid-size fleet operators balancing flexibility with oversight. FCC-regulated telematics integration enables automated limit adjustments based on vehicle location.
- Subscription:Fixed-fee unlimited or capped-usage models, emerging in corporate fleet management platforms. Flat-rate predictability appeals to government procurement functions with rigid budget cycles.
Postpaid structures dominate transaction value. Prepaid instruments are expanding most quickly among small fleet entrants.
User Segment:
Application-specific requirements reshape card feature sets, from government audit trails to individual convenience priorities.
- Fleets:Commercial vehicle operators demanding embedded telematics, automated odometer capture, and multi-jurisdiction VAT reporting. Long-haul logistics densification across interstate routes drives procurement consolidation onto card rails.
- Businesses:Corporate entities with decentralized vehicle pools requiring centralized expense visibility and driver-level spend controls. API-first analytics platforms are unbundling traditional issuer relationships.
- Government:Public sector procurement with strict audit compliance and fixed-budget execution requirements. Subscription models align with annual appropriation cycles.
- Individuals:Consumer motorists seeking convenience and loyalty rewards at branded station networks. Limited after-sales service intensity characterizes this segment.
Fleets generate the highest transaction volume. Businesses show the steepest expansion trajectory as enterprise analytics demands intensify.
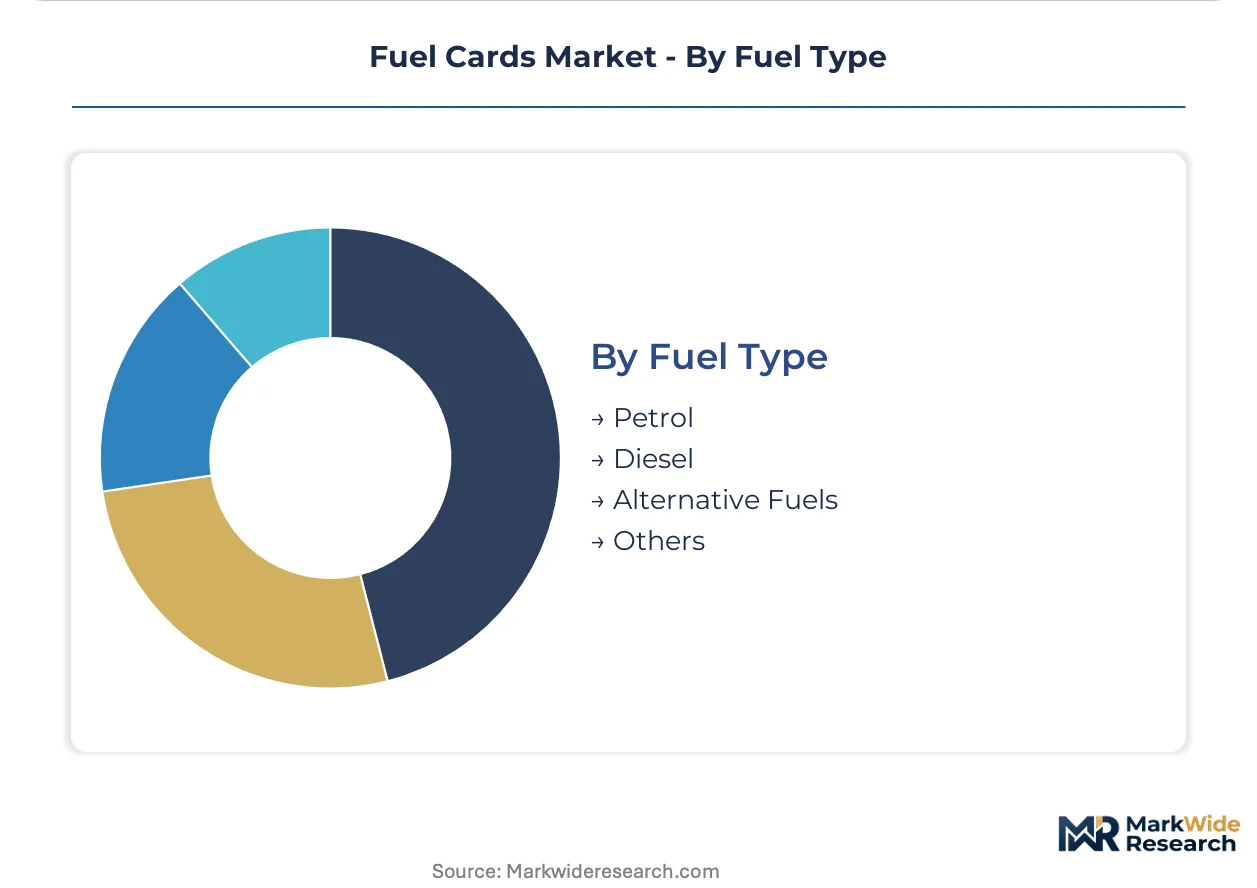
Fuel Type:
Maturity-stage divergence separates established petroleum infrastructure from emerging alternative fuel authentication requirements.
- Diesel:High-energy-density fuel dominating long-haul freight corridors, with card networks optimized for high-volume trucking stops. EMV chip mandates are forcing terminal replacement at diesel pumps ahead of standard refresh cycles.
- Alternative Fuels:Hydrogen and electric charging infrastructure requiring retrofitted terminal authentication and new payment protocols. German federal freight decarbonization subsidies anchor early-mover network effects.
- Petrol:Light-vehicle and short-haul fuel type with mature card acceptance infrastructure. Loyalty program density concentrates competitive positioning.
- Others:Compressed natural gas and biofuel variants with limited but growing corridor acceptance. Niche infrastructure constraints limit card network penetration.
Diesel retains volume leadership. Alternative fuels are gaining share fastest as EU Green Deal timelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with issuers in Germany and the United States, where corridor density and regulatory mandates compress upgrade timelines. Peripheral markets absorb technology spillover at 12-18 month lags. FCC and EU Green Deal frameworks are reshaping capital deployment priorities across issuer networks.
United States
Long-haul logistics operators consolidate procurement onto card rails across interstate corridors. FCC telematics regulations mandate encrypted data transmission from fuel terminals, accelerating EMV terminal replacement cycles. The I-80/I-95 trucking belt drives transaction volume concentration among fleet card issuers.
Germany
Federal freight decarbonization subsidies redirect network investment toward hydrogen corridor infrastructure. EU Green Deal transport targets enforce alternative fuel acceptance mandates by 2030. The Rhine-Alpine freight corridor anchors early-mover terminal retrofit programs for hydrogen dispensing authentication.
China
National logistics chains optimize cash conversion cycles through postpaid hybrid arrangements. SAMR payment infrastructure standards enforce interoperability protocols for fleet card networks. Yangtze River Delta manufacturing clusters generate dense small-fleet demand for prepaid working capital discipline tools.
United Kingdom
Corporate fleet operators demand API-first analytics platforms for decentralized vehicle pool management. FCA consumer duty regulations extend to commercial payment instruments, tightening disclosure requirements. London-Southeast logistics corridors concentrate contactless EMV terminal deployment ahead of national refresh cycles.
India
Owner-operators in long-haul trucking seek VAT recovery automation through card-based procurement. RBI payment system directives encourage prepaid instrument innovation for fleet segments. Maharashtra-Gujarat industrial corridors host pilot programs linking fuel cards to FASTag toll reconciliation systems.
Fuel Cards Market Key Industry Players
Integrated energy majors and specialized fleet payment platforms split the market along infrastructure-versus-software fault lines. Consolidation pressures concentrate among North American and European corridors where merchant acquiring density determines program viability. Three archetypes dominate: oil-company-issued closed-loop networks, independent fleet payment specialists with telematics integration, and banking-network open-loop providers. M&A activity targets telematics capabilities and cross-border VAT reconciliation services.
Among oil-company-issued networks, BP p.l.c., Shell plc, and Exxon Mobil Corporation exemplify the closed-loop archetype with branded station infrastructure. These entities anchor merchant-side acceptance density that constrains competitor network expansion. FleetCor Technologies, Inc. and WEX Inc. occupy positions within the independent specialist tier, representing technology-forward models that unbundle analytics from transaction processing. DKV Mobility exemplifies European corridor specialization with overland freight payment infrastructure spanning multiple jurisdictions.
| Leading Market Players |
|---|
| BP p.l.c. |
| Exxon Mobil Corporation |
| FleetCor Technologies, Inc. |
| WEX Inc. |
| Shell plc |
| TotalEnergies SE |
| Chevron Corporation |
| DKV Mobility |
| UTA Edenred |
| Others |
Cost & Logistics Intelligence
Overcapacity in EMV terminal manufacturing across Southeast Asia compresses hardware margins while accelerating replacement cycles for fuel card issuers. This utilization pressure forces suppliers to absorb certification costs and extend payment terms, reshaping procurement economics for fleet payment networks.
Pricing Analysis
The customization-premium spread between configured-to-order telematics bundles and standard card issuance separates enterprise fleet contracts from small-operator prepaid instruments. Subscription-based SaaS tiers dominate among national logistics chains seeking embedded analytics, while per-transaction interchange economics anchor small fleet pricing. Price differentiation rests on telematics integration depth and PCI DSS certification tier. Cost compression in standard card issuance is intensifying because EMV migration capex demands are squeezing regional issuer margins. Small fleet operators exhibit highest price sensitivity, while enterprise buyers prioritize data integration capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates component sourcing decisions for EMV terminal manufacturers. Hardware assembly concentrates in China, South Korea, and Taiwan, with chip fabrication drawing from Taiwanese and South Korean foundries. Raw material dependencies span semiconductor wafers, NFC antenna substrates, and tamper-resistant card stock. Single-source vulnerability in EMV chip supply creates bottlenecks during network mandate deadlines. Distribution runs through payment network certification labs and regional value-added resellers before reaching fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national logistics chains consolidating procurement decisions around data analytics platforms, fragmenting the traditional issuer-customer relationship. This consolidation shifts negotiating leverage toward enterprise fleet operators demanding API-first architectures.
For Market Incumbents: Pre-empt disintermediation by open banking APIs through captive telematics development and backward integration into vehicle data platforms. FleetCor Technologies and WEX Inc. must accelerate firmware deployment for hydrogen authentication terminals before EU Green Deal mandates lock in competitor networks. Channel control through direct merchant acquiring relationships remains the critical defensive lever against banking-network open-loop expansion.
For New Entrants and Emerging Players: Mid-market hybrid fleet operators in India's Maharashtra-Gujarat corridor represent the most penetrable entry point given VAT recovery automation gaps and limited incumbent telematics penetration. Small fleet segments in China's Yangtze River Delta seeking prepaid working capital discipline offer second-tier expansion potential. A FASTag toll reconciliation bundling strategy provides differentiated go-to-market positioning against established fuel card networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent fleet payment specialists with telematics-integrated platforms. Long-term viability over a five-to-ten-year horizon favors issuers with alternative fuel authentication capabilities aligned with EU Green Deal transport targets. Acquisition targets should demonstrate cross-border VAT reconciliation service depth. The signal to watch as inflection indicator is hydrogen corridor terminal deployment rates across German federal freight subsidies.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded vehicle data capture tightens spend control for FCC-regulated fleet operators. |
| Hydrogen Authentication Infrastructure | EU Green Deal compliance mandates anchor early-mover network effects across Rhine-Alpine corridors. |
| Open Banking API Development | Real-time payment rails disintermediate traditional interchange structures before platform lock-in. |
| Cross-Border VAT Service Acquisition | Multi-jurisdiction reporting capabilities attract mid-size fleet operators lacking internal accounting functions. |
| Prepaid Working Capital Product Launch | Strict expenditure control tools capture small fleet segments in China's manufacturing clusters. |
Research Approach
A spread of perspectives from fleet operations directors, payment network compliance officers, fuel station merchant acquirers, and telematics platform engineers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC filings, FCC equipment authorization databases, EU Green Deal transport policy documents, and customs trade data. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored the analytical framework.
Demand-supply balance dynamics across card type, payment structure, and fuel authentication requirements shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include card type, payment structure, user segment, and fuel type alongside regional regulatory cluster variations. CAGRs were derived through trend extrapolation and adoption curve analysis. Industry-specific forecast inputs encompass EMV terminal replacement cycles and alternative fuel infrastructure deployment timelines.
Practitioners should monitor EMV certification delays, hydrogen corridor subsidy allocation shifts, and open banking regulatory clarifications for early signals. Forecasts reflect assumptions about payment network mandate adherence and freight decarbonization policy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Nigeria Mobile Money Market
Payments
Singapore Payments Market
Payments
Italy POS Terminals Market
Payments
Mobile Payment Security Software Market
Payments
Mpos Terminals Market
Payments
Uganda Mobile Money Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Smart Bands Payments Market
Payments
Global Payments As a Service Market
Payments
Europe Accounts Payable Automation Market
Payments
India Payment Gateway Market
Payments
Poland Payments Market
Payments
EMV Card Market
Payments
India Real Time Payments Market
Payments
Wireless POS Terminals Market
Payments
Europe Mobile Payment Market