
 North America Payment Gateway Market | 2026-2036
North America Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
North America Payment Gateway Market Insights
Market Context
The United States is fragmenting as fintech infrastructure proliferates across state-level banking charters and regional payment networks. Stripe leverages developer-centric API architectures to sustain technology leadership among mid-market software platforms. PayPal anchors consumer trust through its dual-sided wallet and merchant services ecosystem. Square competes by integrating hardware point-of-sale terminals with native gateway software, creating closed-loop commerce flows for small businesses.
Technical Definition and Segment Structure
A payment gateway functions as an encrypted data conduit that authorizes card-not-present transactions between merchant websites and acquiring banks, typically processing through TLS 1.3-secured channels with tokenization protocols that replace sensitive primary account numbers with non-sensitive equivalents. Electronic wallet integrations are capturing disproportionate growth as Apple Pay and Google Pay expand their North American merchant acceptance networks, while API integration dominates enterprise deployments due to customization demands for subscription billing and marketplace split-payment logic. Transaction fee pricing retains the largest revenue pool across pricing models, though subscription-based structures are gaining traction among software-as-a-service platforms seeking predictable cost structures.
Regulatory Environment and Outlook
The Federal Reserve governs systemic payment stability through its FedNow real-time gross settlement service, while state-level money transmitter licenses from entities like the New York Department of Financial Services create compliance complexity for multi-state operators. PCI DSS standards administered by the PCI Security Standards Council mandate annual audits for Level 1 merchants processing over six million card transactions annually. Stakeholders must monitor how state privacy laws in California and emerging federal open banking rules reshape data portability requirements and authentication protocols.
Market Dynamics
FedNow real-time settlement rails are compressing transaction clearing windows from days to seconds, forcing gateway providers to rebuild core infrastructure around instant payment protocols or lose merchant volume to bank-direct alternatives.
Growth Catalysts
- PCI DSS 4.0 mandates:The updated standard requires multi-factor authentication for all administrative access, pushing merchants toward hosted gateway solutions with built-in compliance tooling.
- Subscription economy expansion:SaaS platforms and membership businesses demand automated recurring billing with intelligent retry logic, driving specialized gateway feature development.
- Cross-border e-commerce corridors:Canadian merchants processing US dollar transactions require multi-currency settlement infrastructure, expanding addressable market for gateway providers with dual-currency capabilities.
Market Restraints
- State-level licensing fragmentation:Money transmitter licenses from the New York Department of Financial Services and parallel state regimes create compliance costs exceeding seven figures for multi-state operators.
- Interchange fee compression:Durbin Amendment caps on debit interchange squeeze merchant acquirer margins, pressuring gateway providers to absorb cost reductions or lose distribution partnerships.
- Bank-direct API competition:JPMorgan Chase and Bank of America are virtualizing merchant services through proprietary developer portals, eroding third-party gateway attach rates.
Strategic Opportunities
- Mexico-US remittance corridors:Nearshoring manufacturing growth creates demand for B2B payment rails between Mexican suppliers and US buyers, underserved by incumbent gateway architectures.
- Embedded finance convergence:Vertical SaaS platforms in construction and healthcare are converging payment acceptance with lending and insurance, requiring white-label gateway infrastructure.
- Open banking data portability:Emerging federal rules on consumer financial data access will enable account-to-account payment initiation, creating new authentication and routing service layers.
Industry Challenges
- Token vault migration complexity:Merchants switching gateway providers face multi-month projects to migrate stored payment credentials without disrupting recurring revenue streams.
- Real-time fraud detection talent scarcity:Machine learning engineers with payments-specific risk modeling expertise command compensation premiums exceeding forty percent above general data science roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Payment Gateway Market |
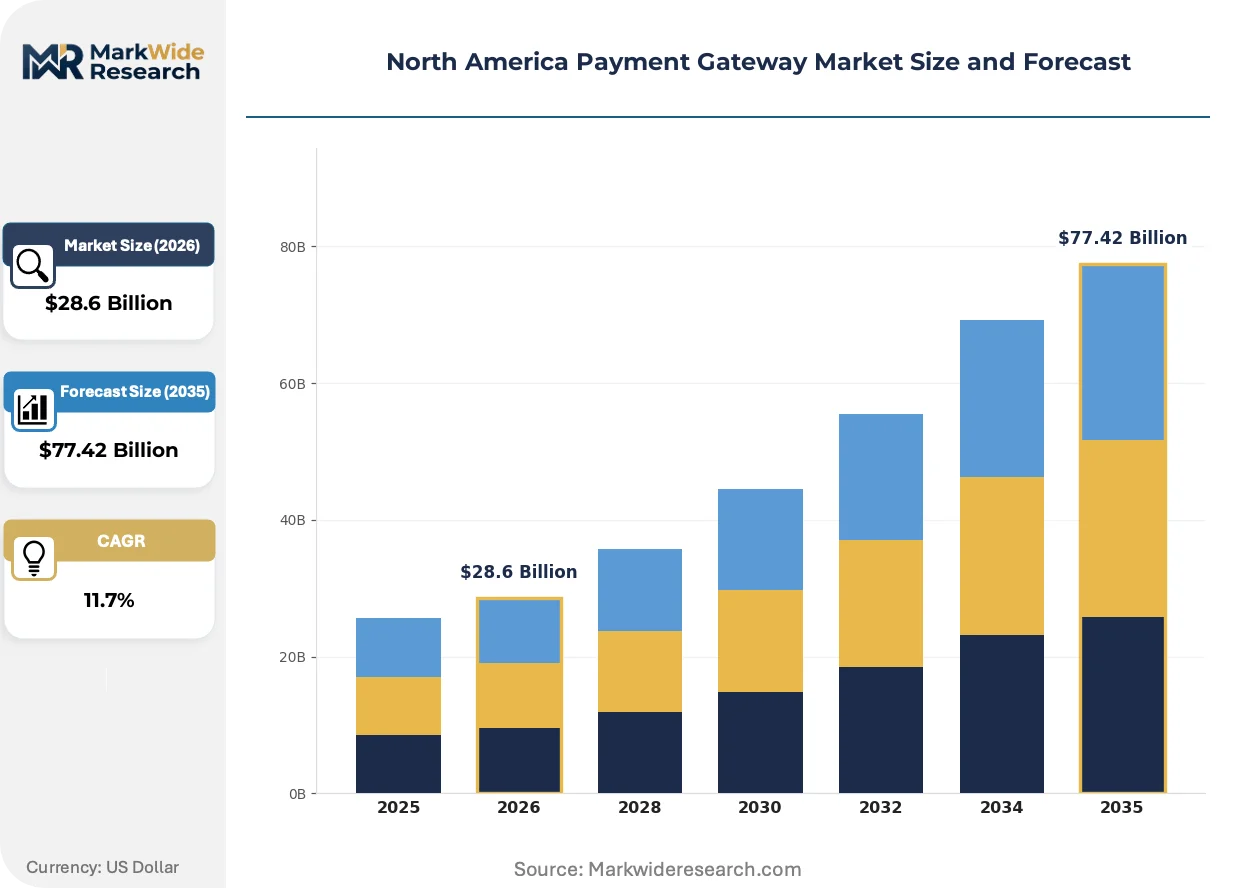
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Electronic Wallet, Bank Transfer End User: Retail, E-commerce, Hospitality, Travel Pricing Model: Transaction Fee, Subscription-Based, Freemium, Tiered Pricing Integration Type: API Integration, Hosted Payment, On-Site Payment, Mobile SDK |
| Companies Covered | PayPal, Stripe, Square, Amazon Pay, Worldpay, Adyen, Fiserv, FIS, Authorize.Net, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Payment Gateway Market Trends and Innovations
Gateway infrastructure is separating into modular components, with merchants unbundling authorization, fraud screening, and settlement into best-of-breed stacks rather than accepting monolithic platforms.
Software-defined tokenization is virtualizing card data storage across distributed cloud environments. Enterprise merchants with complex multi-processor routing requirements are adopting this architecture fastest, with migration timelines compressing from eighteen months to under six. The technology is virtualizing the traditional gateway moat around vault ownership, enabling merchants to switch authorization providers without credential migration friction.
The California Consumer Privacy Act and emerging federal privacy frameworks are mandating granular consent management for transaction data retention. Gateway providers must now embed consent orchestration layers that log opt-in timestamps and purpose limitations alongside payment records. Mid-market e-commerce merchants face the steepest retrofit costs, with many selecting new gateway partners based on native privacy tooling rather than pricing.
Merchant procurement of payment services is fragmenting by transaction type, with large retailers selecting specialized gateways for online, in-app, and marketplace use cases rather than consolidating on single vendors. This pattern is displacing the traditional enterprise sales model of platform-wide exclusivity. The shift is most visible among digitally native retailers in the United States with annual card volumes exceeding fifty million transactions.
North America Payment Gateway Market Segmentation
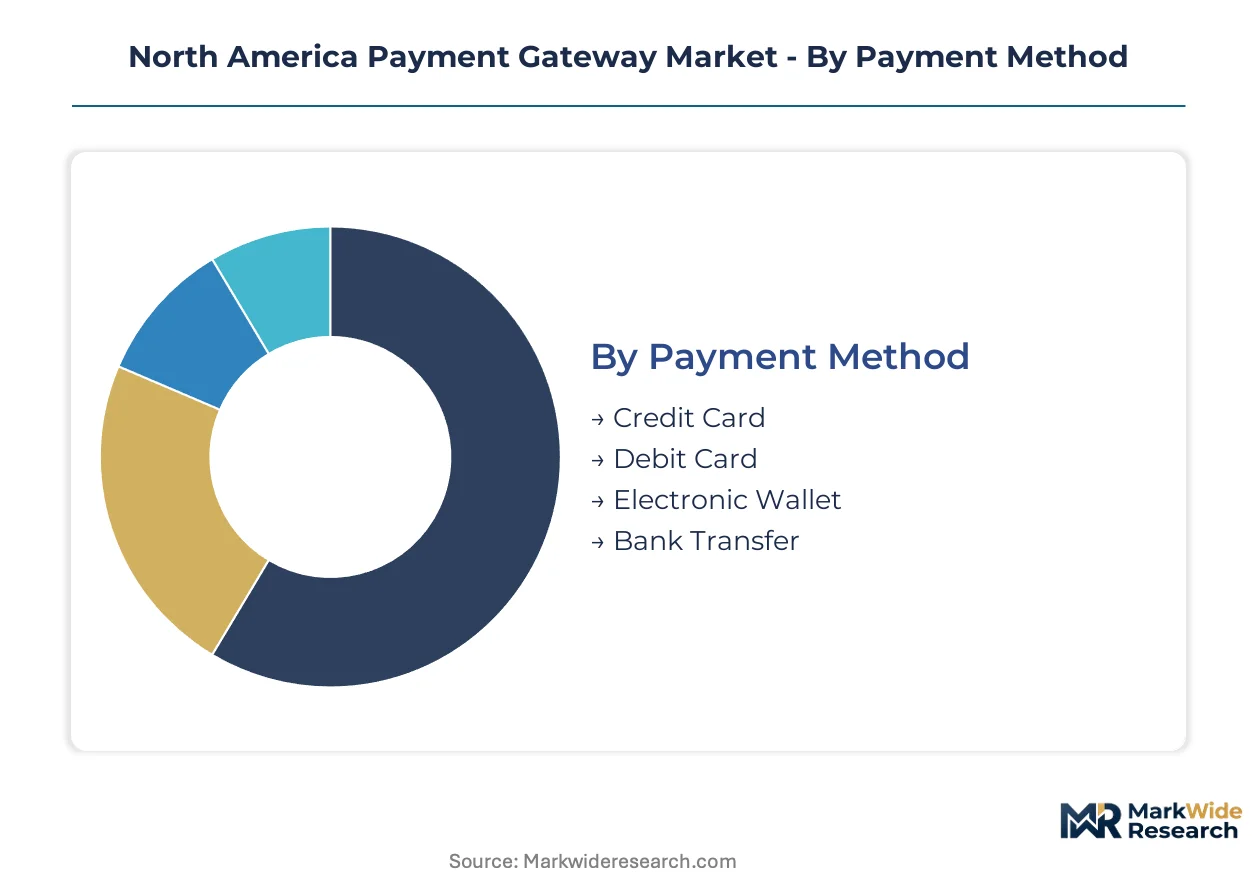
Payment gateway segmentation reveals how infrastructure investments align with merchant scale, transaction velocity, and compliance burden. Each dimension carries distinct service intensity requirements that reshape provider economics and competitive positioning.
Payment Method:
After-sales service intensity peaks with credential storage and token lifecycle management, driving provider differentiation around vault security and PCI DSS audit support.
- Credit Card:Dominates authorization volumes through TLS 1.3-secured channels with dynamic CVV verification. United States e-commerce merchants concentrate demand here, constrained by interchange fee compression from the Durbin Amendment on debit rails.
- Electronic Wallet:Expands through NFC-enabled in-app and browser-based checkout flows. Canadian cross-border merchants processing US dollar settlements represent the fastest-climbing adoption corridor, propelled by Apple Pay and Google Pay network expansion.
- Debit Card:Processes through PIN-less signature debit networks with lower interchange economics.
- Bank Transfer:Leverages FedNow real-time settlement rails for account-to-account payment initiation.
Credit card holds the largest share; momentum sits with electronic wallet.
End User:
Cost tier segmentation separates enterprise-grade compliance tooling from self-serve onboarding paths for smaller merchants.
- E-commerce:Demands API-native architectures with subscription billing logic and intelligent retry mechanisms for recurring revenue protection. California-based digitally native retailers with high transaction volumes drive feature roadmaps, pressured by CCPA consent management mandates.
- Retail:Requires omnichannel reconciliation between online and physical point-of-sale systems. Texas and Florida brick-and-mortar chains with multi-state footprints concentrate procurement, constrained by state-level money transmitter licensing fragmentation.
- Hospitality:Needs pre-authorization holds and incremental settlement for service duration uncertainty.
- Travel:Depends on multi-currency pricing and chargeback protection for high-ticket, high-risk bookings.
E-commerce commands the largest share; retail is expanding most quickly as offline merchants digitize.
Pricing Model:
Volume concentration determines whether merchants absorb per-transaction variability or seek cost predictability through fixed commitments.
- Transaction Fee:Retains the dominant revenue pool through percentage-plus-fixed structures on gross merchandise value. Mid-market software platforms in the United States with fluctuating sales cycles favor this model for alignment with cash flow.
- Subscription-Based:Delivers predictable unit economics for SaaS platforms with steady transaction cadence. Ontario and British Columbia technology vendors are migrating fastest, seeking to cap processing costs against revenue growth.
- Freemium:Captures developer experimentation with volume thresholds triggering paid tiers.
- Tiered Pricing:Segments feature access across basic, professional, and enterprise levels with volume breakpoints.
Transaction fee holds the largest share; subscription-based is climbing the fastest as SaaS platforms scale.
Integration Type:
Customer technical sophistication separates merchants demanding full customization from those prioritizing speed-to-market.
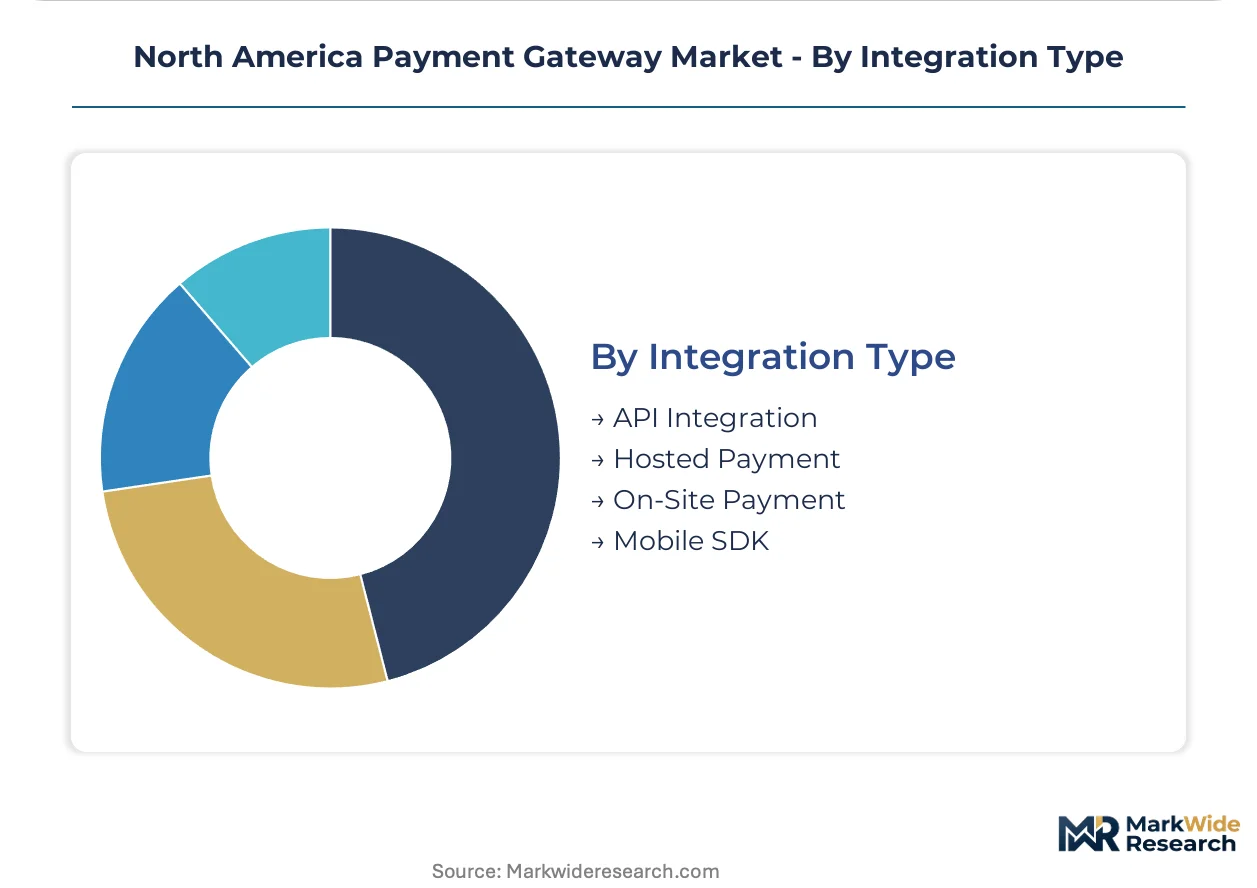
- API Integration:Enables deep customization for marketplace split-payments, subscription logic, and multi-processor routing. Enterprise merchants across Illinois and New York financial services clusters require this flexibility, constrained by token vault migration complexity when switching providers.
- Hosted Payment:Offloads PCI DSS scope through redirect flows to provider-controlled domains. Small and mid-sized California e-commerce merchants with limited engineering resources concentrate here, driven by PCI DSS 4.0 multi-factor authentication mandates.
- On-Site Payment:Maintains full checkout control within merchant infrastructure with highest compliance burden.
- Mobile SDK:Embeds native payment experiences within iOS and Android applications with biometric authentication.
API integration holds the largest share; hosted payment is gaining share fastest among resource-constrained merchants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Reserve anchors payment infrastructure governance across the dominant United States market, while state-level licensing regimes and cross-border corridors reshape competitive positioning throughout North America.
United States
E-commerce merchants and SaaS platforms drive gateway procurement across California and New York technology clusters. The Federal Reserve's FedNow service mandates real-time settlement infrastructure upgrades. Texas and Florida multi-state retail chains concentrate demand, constrained by money transmitter licensing fragmentation across state regimes.
Canada
Cross-border e-commerce merchants processing US dollar settlements fuel electronic wallet adoption through Ontario and British Columbia technology corridors. The Financial Consumer Agency of Canada governs payment service provider registration requirements. Toronto and Vancouver fintech clusters specialize in dual-currency gateway infrastructure for North American trade.
Mexico
Nearshoring manufacturing growth creates B2B payment demand between Mexican suppliers and US buyers across Nuevo León and Jalisco industrial zones. The country's national banking and securities regulator supervises payment system stability. Mexico City metro area hosts emerging gateway providers targeting remittance and trade finance corridors.
North America Payment Gateway Market Competitive Landscape
Developer-centric platforms and dual-sided wallet ecosystems split the market between infrastructure providers and merchant-facing aggregators. The vendor base concentrates around three strategic archetypes: API-native specialists serving mid-market software platforms, integrated hardware-software providers capturing small business volume, and bank-affiliated processors leveraging deposit relationships. Competitive positioning hardens through M&A consolidation of regional payment processors and strategic partnerships embedding gateway services into vertical SaaS workflows.
Among US-based infrastructure providers, Stripe exemplifies the developer-centric archetype through API-first architecture, while PayPal occupies a position anchoring consumer trust through wallet and merchant service convergence. Square represents the integrated hardware-software model, embedding gateway software within point-of-sale terminal ecosystems.
| Leading Market Players |
|---|
| PayPal |
| Stripe |
| Square |
| Amazon Pay |
| Worldpay |
| Adyen |
| Fiserv |
| FIS |
| Authorize.Net |
| Others |
Pricing and Supply Chain Analysis
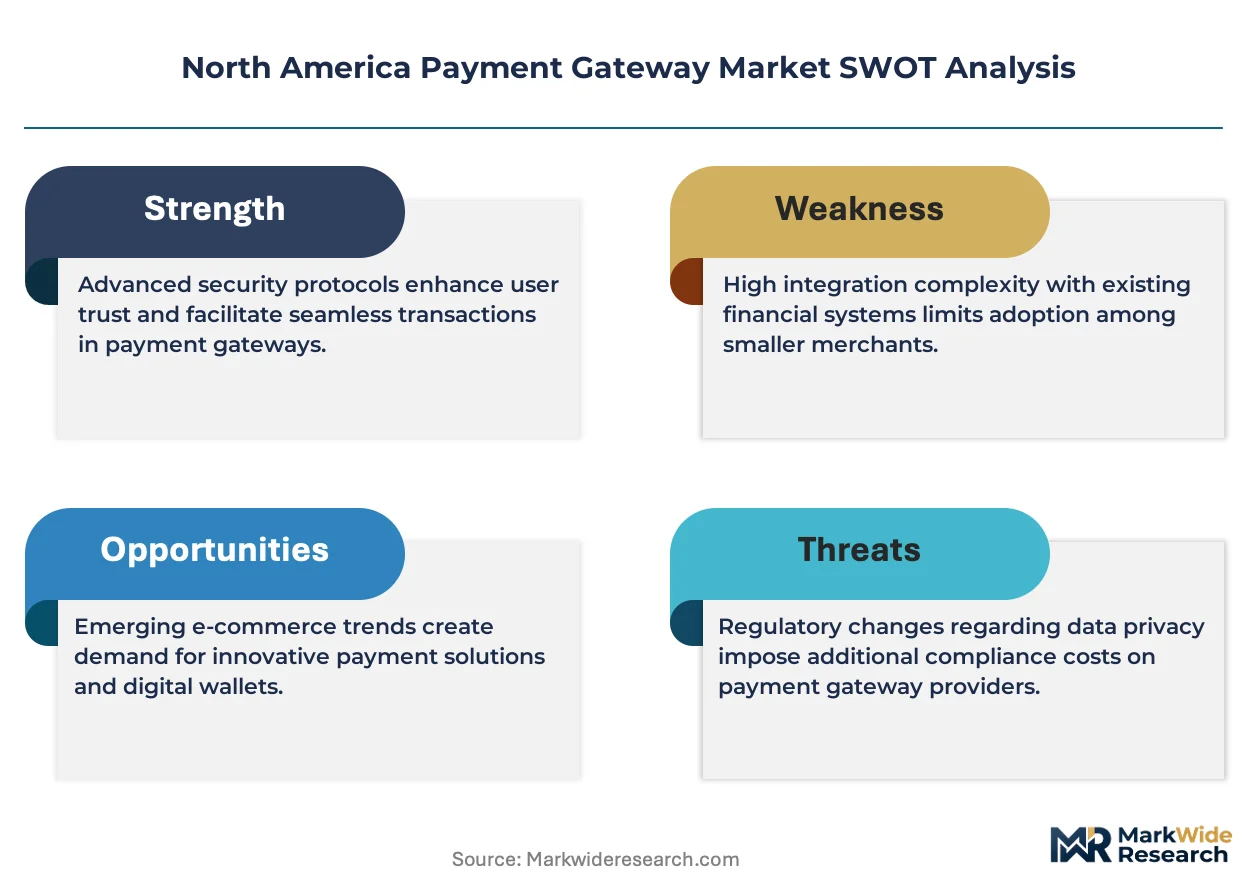
Overcapacity in hosted payment gateway infrastructure across California and New York technology corridors is compressing margins while simultaneously expanding merchant choice, forcing providers to absorb compliance costs or surrender volume to bank-direct alternatives. This utilization dynamic reshapes supplier investment priorities and pricing discipline across the North American market.
Pricing Analysis
Price spreads between API-native and hosted payment solutions widen most dramatically across Texas and Florida multi-state retail chains, where transaction fee structures face downward pressure from Durbin Amendment debit interchange caps. Pricing stratifies across premium API tiers, standard hosted packages, and economy redirect flows, with PCI DSS 4.0 compliance tooling emerging as the primary price differentiation driver alongside token vault security certification. Cost compression in mid-market SaaS subscriptions is intensifying because merchant acquirers are squeezing gateway margins to preserve their own economics. Small and mid-sized e-commerce merchants with limited engineering resources demonstrate highest price sensitivity, while enterprise merchants prioritize customization over cost.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations for gateway providers serving nearshoring manufacturing corridors. Infrastructure development concentrates in the United States, Canada, and Mexico, with core platform engineering anchored in California and New York while customer support and compliance operations draw from Ontario and British Columbia technology clusters. Cloud compute capacity, TLS 1.3 encryption modules, and fraud detection ML pipelines constitute critical input dependencies. Single-source vulnerability in FedNow real-time settlement rail access threatens provider competitiveness. Distribution runs through direct API documentation portals, vertical SaaS partnerships, and merchant acquirer channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedNow real-time settlement infrastructure represents a high-growth disruption forcing gateway providers to rebuild core authorization engines or cede merchant volume to bank-direct alternatives. This technological inflection compresses competitive response windows across the North American market.
For Market Incumbents: Entrench developer ecosystem loyalty through embedded finance partnerships with vertical SaaS platforms in construction and healthcare, while simultaneously hardening token vault architecture to increase switching costs against bank-direct API competition from JPMorgan Chase and Bank of America. Prioritize backward integration into fraud detection ML pipelines to capture talent scarcity premiums.
For New Entrants and Emerging Players: Build out white-label gateway infrastructure targeting Mexico-US B2B remittance corridors where incumbent architectures remain underdeveloped, with specialized authentication layers for account-to-account payment initiation under emerging federal open banking rules. Pursue channel partnerships with Mexican industrial banks as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across real-time fraud detection infrastructure as ML engineering compensation premiums exceed forty percent above general data science roles. Five-to-ten year viability favors acquirers of modular authorization components rather than monolithic platform bets. Monitor FedNow merchant attach rates as the critical inflection signal for third-party gateway displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Infrastructure Integration | Real-time settlement capability separates viable providers from obsolete architectures across the United States. |
| Vertical SaaS Partnership | Embedded finance convergence in construction and healthcare creates captive distribution for white-label gateway services. |
| Token Vault Modularization | Software-defined tokenization reduces merchant switching friction and erodes traditional gateway moats around credential storage. |
| Privacy Tooling Development | Native CCPA consent orchestration layers differentiate gateway selection for California-based digitally native retailers. |
| Dual-Currency Capability Buildout | US dollar settlement infrastructure captures Canadian cross-border e-commerce demand through Toronto and Vancouver corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, FedNow service disclosures, PCI Security Standards Council documentation, and state money transmitter licensing records. Primary interviews engaged payment gateway CTOs, merchant acquirer partnership leads, vertical SaaS platform engineers, and compliance officers at multi-state retail chains. Bottom-up transaction volume modeling triangulates against top-down market sizing from regulatory filings and industry association data.
Forecast inputs include payment method adoption curves, FedNow merchant enrollment trajectories, PCI DSS 4.0 compliance cost burdens, and interchange fee compression effects. Segmentation dimensions span integration type, pricing model, end-user industry, and payment method across the projection horizon. CAGRs derive from regression analysis of historical authorization volume growth against e-commerce penetration and real-time payment rail expansion. Subscription billing logic demand and intelligent retry mechanism adoption serve as industry-specific forecast inputs for SaaS platform segments.
Stress conditions across FedNow adoption velocity, state privacy law fragmentation, and ML engineering talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline stability and merchant acquirer margin preservation behavior. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Prepaid Cards Market
Payments
Credit Card Issuance Services Market
Payments
Global Telecom Billing Market
Payments
China POS Terminals Market
Payments
Portugal POS Terminals Market
Payments
Latin America Subscription and Billing Management Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
North America Real Time Payment Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Southeast Asia POS Terminal Market
Payments
Global Digital Wallets Market
Payments
Master Recharge API Market
Payments
Payment Card Market
Payments
3D Secure Pay Authentication Market
Payments
South Africa Real Time Payments Market
Payments
Payment Security Market