
 Indonesia Mobile Payments Market | 2026-2036
Indonesia Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Mobile Payments Market Outlook
Small merchants is reorganizing demand away from retail consumers as Indonesia's mobile payment ecosystem matures. GoPay leverages its super-app integration with ride-hailing and food delivery to sustain merchant lock-in across tier-2 cities. OVO anchors loyalty-driven spending through its Grab ecosystem partnership, while DANA competes aggressively on user acquisition costs in the digital wallet segment.
Indonesia mobile payments encompass QR code, NFC, SMS-based, and mobile wallet technologies that transmit monetary value through encrypted digital channels without physical card or cash exchange. These systems rely on real-time gross settlement protocols and tokenized credentials to execute peer-to-peer, consumer-to-business, and business-to-business transactions. QR code payments dominate transaction volume due to zero hardware requirements for micro-merchants, though NFC infrastructure is expanding fastest among urban retail chains seeking sub-second checkout speeds. Digital wallet solutions capture the largest margin pool through float income and merchant service fees, while remittance services face regulatory compression on foreign exchange spreads.
Bank Indonesia governs payment system licensing and BI-FAST interoperability mandates, while OJK supervises e-money issuer capital adequacy and consumer protection frameworks. BIS technical standards for QRIS (Quick Response Code Indonesian Standard) unify merchant acceptance across competing wallets, reducing fragmentation costs. Stakeholders must monitor BI-FAST fee structure revisions and OJK data localization requirements as these will determine whether wallet economics shift toward transaction density or value-added financial services.
Market Dynamics
QR code infrastructure is compressing hardware costs for micro-merchants across Java's urban corridor, while BI-FAST interoperability mandates force wallet providers to compete on service layers rather than proprietary lock-in. This dual pressure is restructuring how payment value chains capture margin.
Growth Catalysts
- BI-FAST Interoperability Mandates:Bank Indonesia's real-time settlement protocol eliminates fragmentation costs between competing digital wallets, expanding merchant acceptance networks without duplicate onboarding.
- Java Urban Corridor Density:Smartphone penetration and e-commerce order concentration in Jakarta and Surabaya create natural economies of scale for QR-based transaction infrastructure.
- Super-App Ecosystem Bundling:Ride-hailing and food delivery platforms integrate payment rails, reducing customer acquisition costs through cross-service utility.
Market Restraints
- Float Income Compression:Regulatory caps on e-money issuer investment returns constrain wallet profitability independent of transaction volume growth.
- Remittance Spread Squeeze:Bank Indonesia foreign exchange regulations compress margins on cross-border payment corridors, particularly affecting worker remittance flows.
- NFC Hardware Requirements:Contactless terminal deployment demands capital expenditure that micro-merchants outside tier-1 cities cannot absorb.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi and Papua markets show smartphone adoption gaps closing against underdeveloped banking infrastructure, creating first-mover terrain for mobile wallet expansion.
- BI-FAST Fee Structure Evolution:Anticipated revisions to real-time settlement pricing could shift economics toward high-frequency, low-value transaction density plays.
- Embedded Finance Convergence:Digital wallets integrating lending and insurance products through OJK licensing pathways capture margin pools beyond payment processing.
Industry Challenges
- OJK Data Localization Compliance:E-money issuers face infrastructure reconfiguration costs to meet domestic server requirements for transaction records and customer data.
- QRIS Standardization Complexity:Technical alignment across competing wallet backends demands continuous engineering resources without immediate revenue offset.
- Merchant Onboarding Velocity:Micro-merchant KYC verification at scale requires field agent networks that strain operational cost structures.
Report Scope
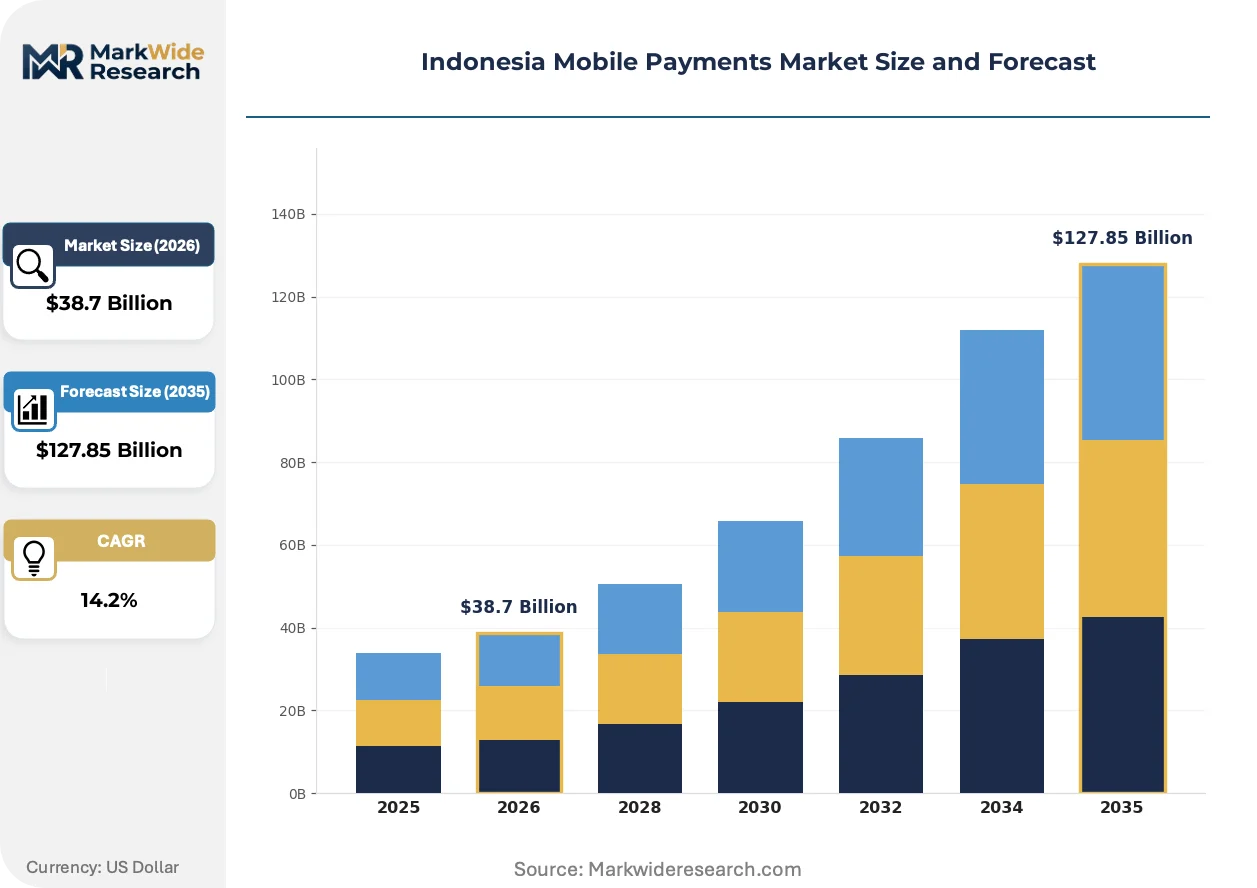
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Mobile Payments Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Field Communication, QR Code, Mobile Wallet, SMS-based Payments End User: Retail Consumers, Small Merchants, Corporates, E-commerce Platforms Service Type: Payment Processing, Digital Wallet Solutions, Remittance Services, Loyalty Programs Distribution Channel: App Store, Website, Direct Sales, Partnerships |
| Companies Covered | SeaMoney Singapore Pte. Ltd. (ShopeePay), PT Artajasa Pembayaran Elektronis, PT Dompet Karya Anak Bangsa (GoPay), GrabPay Holdings Pte. Ltd., PT Nusa Satu Inti Artha (DOKU), PT Espay Debit Indonesia Koe (DANA), PT Fintek Karya Nusantara (LinkAja), Xendit, PT Visionet Internasional (OVO), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Mobile Payments Market Strategic Shifts
Tokenized credential systems are displacing static authentication methods across Indonesia's payment stack. Three forces are compressing development cycles and reshaping competitive positioning.
Biometric authentication is miniaturizing security layers into smartphone-native sensors. Tier-2 city merchants are adopting facial and fingerprint verification at three times the pace of traditional PIN pad deployment. This compression is eliminating dedicated hardware requirements for transaction authorization.
Bank Indonesia's QRIS technical standards unify merchant acceptance codes across all licensed wallets. The regulation forces interoperability at the point of sale, preventing proprietary QR formats from fragmenting merchant experience. Wallet providers are responding by differentiating on loyalty programs and credit extension rather than exclusivity.
Merchant acquisition is rotating from independent sales organizations toward platform-embedded onboarding. Food delivery and ride-hailing apps convert existing driver and restaurant networks into payment acceptance points without standalone sales forces. This channel shift is most visible in Surabaya and Bandung where super-app penetration exceeds traditional bank branch density.
Indonesia Mobile Payments Market Segmentation
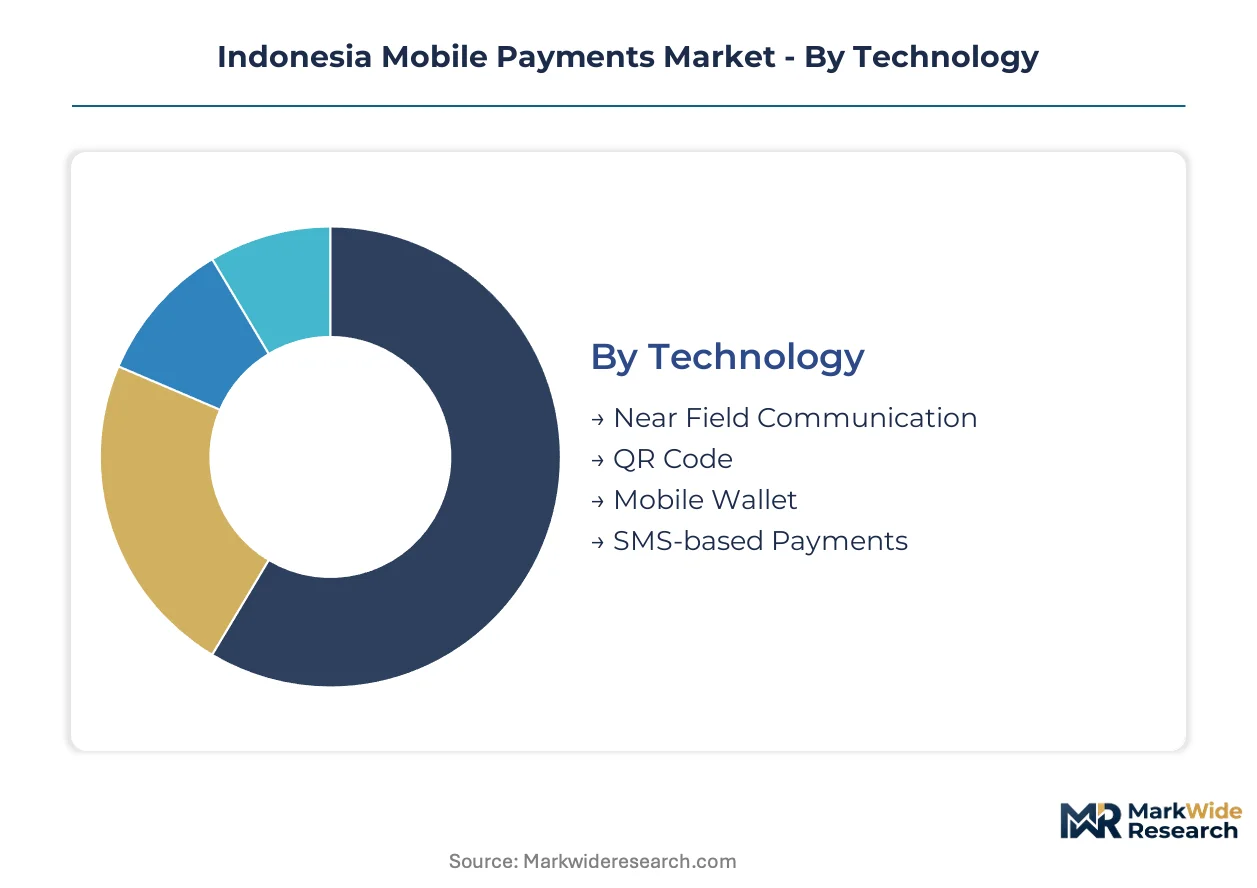
Technology heterogeneity across Indonesia's payment stack creates divergent margin structures and capital requirements. Each segment category carries distinct substitution pressures from adjacent technologies and regulatory treatment.
Technology:
QR Code faces the strongest substitution threat from NFC infrastructure as urban retail chains prioritize sub-second checkout speeds.
- Near Field Communication:Contactless protocols transmit encrypted token data through electromagnetic induction at point-of-sale terminals. Deployment concentrates in Jakarta's retail chains and quick-service restaurants where transaction velocity drives throughput economics. NFC hardware costs limit micro-merchant adoption outside tier-1 cities.
- QR Code:Static or dynamic matrix barcodes encode payment instructions readable by smartphone cameras without dedicated hardware. Demand clusters among Surabaya and Bandung micro-merchants where Bank Indonesia's QRIS standard eliminates proprietary lock-in. Zero terminal cost accelerates penetration across Java's urban corridor.
- Mobile Wallet:Software-based credential storage enables peer-to-peer transfers and merchant payments through tokenized account linking. Float income and service fee revenue streams dominate wallet economics.
- SMS-based Payments:Unstructured Supplementary Service Data protocols execute transactions through cellular signaling channels. Feature phone compatibility sustains relevance in Eastern Indonesia smartphone penetration gaps.
QR Code retains volume leadership; Near Field Communication holds the steepest expansion curve.
End User:
Cost tier stratification separates high-frequency retail consumers from capital-constrained small merchants.
- Retail Consumers:Individual users executing peer-to-peer transfers and merchant purchases through smartphone applications. Super-app bundling reduces acquisition costs in tier-2 cities where ride-hailing and food delivery overlap.
- Small Merchants:Micro-enterprises and informal sector operators accepting digital payments without formal banking relationships. QRIS interoperability eliminates duplicate onboarding across competing wallet networks.
- Corporates:Enterprise treasuries utilizing BI-FAST rails for supplier payments and payroll disbursement. Real-time gross settlement protocols reduce working capital requirements.
- E-commerce Platforms:Marketplace operators integrating escrow and settlement infrastructure for merchant partners. Transaction density in Jakarta and Surabaya creates economies of scale for payment processing.
Small Merchants dominate transaction count expansion; Corporates command the highest average transaction values.
Service Type:
Application maturity varies across payment processing commoditization and embedded finance convergence.
- Payment Processing:Transaction routing and settlement infrastructure executing real-time fund transfers through BI-FAST rails. Regulatory fee structure revisions threaten margin compression independent of volume growth.
- Digital Wallet Solutions:Stored-value accounts enabling closed-loop and open-loop payment execution. OJK capital adequacy requirements constrain issuer profitability through float income caps.
- Remittance Services:Cross-border fund transfers serving worker diaspora corridors. Bank Indonesia foreign exchange regulations compress spreads on outbound flows.
- Loyalty Programs:Points-based reward systems integrated into payment workflows. Grab and Gojek ecosystems anchor program differentiation as QRIS prevents proprietary exclusivity.
Payment Processing captures transaction volume leadership; Digital Wallet Solutions are climbing the fastest toward margin pool dominance.
Distribution Channel:
Geography of customer acquisition determines cost structures and onboarding velocity.
- App Store:Platform-mediated distribution through Google Play and Apple App Store ecosystems. Commission structures and review processes create gatekeeping friction.
- Website:Direct-to-consumer acquisition through mobile web interfaces and progressive web applications. Lower friction alternative for feature phone users.
- Direct Sales:Field agent networks executing merchant onboarding and KYC verification. Operational cost intensity scales with micro-merchant penetration targets.
- Partnerships:Embedded distribution through ride-hailing, food delivery, and e-commerce platforms. Driver and restaurant networks convert to payment acceptance points without standalone sales forces.
Partnerships retain merchant acquisition leadership; Direct Sales maintains the steepest cost curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exports mobile payment infrastructure expertise to Vietnam and the Philippines, where QRIS-standardized technology and super-app deployment models transfer across ASEAN markets. Cross-border transaction corridors between Jakarta, Singapore, and Kuala Lumpur concentrate regional liquidity flows.
Java Urban Corridor
Jakarta and Surabaya smartphone penetration exceeds 85 percent, creating dense QR transaction networks. Bank Indonesia's BI-FAST interoperability mandates force wallet providers to compete on service layers rather than proprietary lock-in. Micro-merchants in Bandung and Yogyakarta adopt QRIS standards at three times the pace of tier-2 cities outside Java.
Sumatra
Medan and Palembang e-commerce order density drives payment infrastructure investment from super-app platforms. The country's central bank mandates QRIS acceptance across provincial retail chains. Merchant acquisition in Riau and Aceh relies on embedded onboarding through ride-hailing driver networks rather than standalone sales forces.
Sulawesi
Makassar and Manado show smartphone adoption gaps closing against underdeveloped banking infrastructure. Regional regulations require e-money issuers to maintain domestic transaction servers. First-mover wallet providers penetrate micro-merchant segments in Southeast Sulawesi where traditional branch banking remains sparse.
Kalimantan
Balikpapan and Samarinda corporates utilize BI-FAST rails for supplier payments in extractive industries. Bank Indonesia foreign exchange regulations compress remittance margins on outbound worker flows. Payment processing infrastructure concentrates in East Kalimantan's industrial zones serving mining and palm oil supply chains.
Papua and Eastern Archipelago
Jayapura and Sorong present frontier terrain where SMS-based protocols sustain relevance amid smartphone penetration gaps. The central bank's financial inclusion directives prioritize mobile wallet expansion in underbanked eastern provinces. Merchant onboarding velocity lags Java by 40 percent due to field agent network cost constraints.
Indonesia Mobile Payments Market Competitive Environment
Listed leaders compete with private specialists across capital access and regulatory compliance dimensions. The vendor base organizes around three strategic tiers: super-app integrated wallets with ride-hailing and e-commerce anchoring, standalone digital wallet specialists competing on user acquisition spend, and payment infrastructure providers enabling merchant acceptance rails. Competitive moves concentrate on embedded finance licensing through OJK pathways and geographic expansion into Eastern Indonesia's underbanked corridors.
Within the super-app integrated tier, PT Dompet Karya Anak Bangsa (GoPay) and PT Visionet Internasional (OVO) exemplify ecosystem-anchored positioning where ride-hailing and food delivery utility sustains merchant lock-in. Standalone specialists PT Espay Debit Indonesia Koe (DANA) and PT Fintek Karya Nusantara (LinkAja) occupy positions competing aggressively on user acquisition costs in the digital wallet segment. SeaMoney Singapore Pte. Ltd. (ShopeePay) represents e-commerce platform-embedded payment rails converting marketplace merchant networks into acceptance points.
| Leading Market Players |
|---|
| SeaMoney Singapore Pte. Ltd. (ShopeePay) |
| PT Artajasa Pembayaran Elektronis |
| PT Dompet Karya Anak Bangsa (GoPay) |
| GrabPay Holdings Pte. Ltd. |
| PT Nusa Satu Inti Artha (DOKU) |
| PT Espay Debit Indonesia Koe (DANA) |
| PT Fintek Karya Nusantara (LinkAja) |
| Xendit |
| PT Visionet Internasional (OVO) |
| Others |
Value Chain & Pricing Dynamics
QR code infrastructure substitution for NFC hardware is redrawing procurement geography across Indonesia's payment stack while compressing merchant acquisition costs in Java's urban corridor. This technology displacement simultaneously expands super-app platform reach and intensifies margin pressure on standalone wallet providers competing for micro-merchant onboarding.
Pricing Analysis
Current-generation QRIS-standardized transactions, prior-generation SMS-based protocols, and next-generation biometric-authentication systems stratify pricing across three distinct service tiers. Three-tier pricing structure across premium, standard, and economy levels reflects settlement speed guarantees, fraud insurance coverage, and loyalty program integration depth. Pricing pressure stems from Bank Indonesia's BI-FAST fee structure revisions and OJK float income caps compressing issuer margins independent of volume expansion. Small merchants in Surabaya and Bandung exhibit highest price sensitivity to merchant discount rates, while corporate treasuries utilizing real-time gross settlement prioritize reliability over transaction cost minimization.
Supply Chain Analysis
Inbound logistics costs through Singapore's transshipment hub and Jakarta's Tanjung Priok port constrain hardware terminal distribution to Eastern Indonesia's archipelago markets. Payment infrastructure draws from China for smartphone manufacturing, South Korea for NFC chip fabrication, and domestic Indonesian software development for wallet application layers. Supply chain risk centers on single-source vulnerability for biometric sensor modules amid export control tightening. Distribution runs through super-app platform partnerships converting existing driver and restaurant networks into payment acceptance points without standalone field agent deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
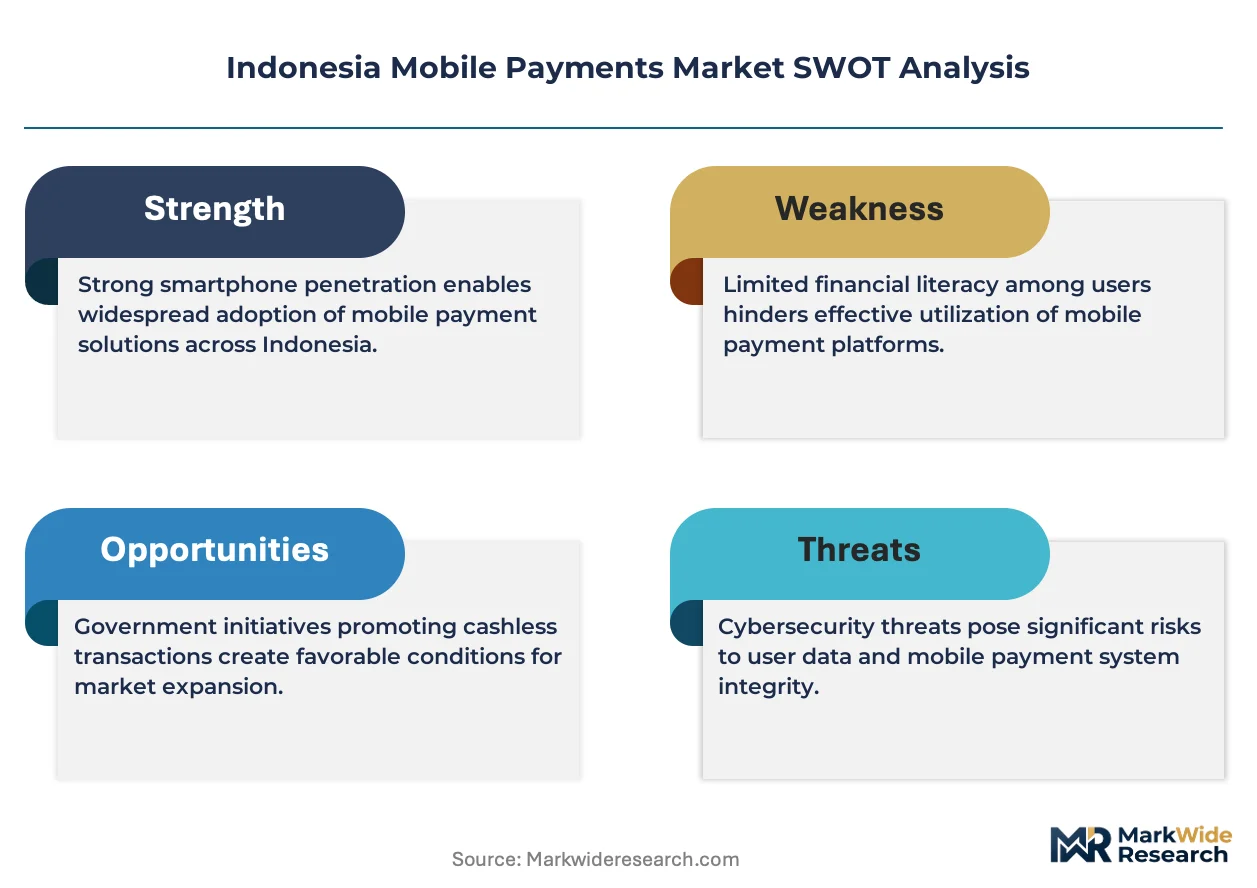
Indonesia's mobile payment market is approaching a platform-economics inflection where BI-FAST interoperability eliminates proprietary lock-in and forces competition toward embedded financial services. The QRIS standardization shift redistributes value capture from merchant exclusivity to data-driven lending and insurance integration.
For Market Incumbents: Fortify merchant lock-in through embedded finance licensing pathways before OJK capital requirements tighten further. Deepen vertical integration into credit underwriting infrastructure to offset float income compression from regulatory caps. Prioritize field agent network density in Sulawesi and Papua corridors where super-app penetration lags Java's urban corridor.
For New Entrants and Emerging Players: Lead with biometric-authentication differentiation targeting tier-2 city micro-merchants where hardware-free onboarding accelerates adoption. Eastern Indonesia's smartphone penetration gaps closing against underdeveloped banking infrastructure represent the most penetrable white-space terrain. Partner with ride-hailing platforms for embedded distribution rather than building standalone merchant acquisition capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward platform-integrated wallet providers with proven super-app ecosystem anchoring rather than standalone specialists facing user acquisition cost spirals. Long-term viability across the projection horizon hinges on OJK embedded finance licensing execution and BI-FAST fee structure evolution. Watch for QRIS standardization completion as the signal indicating margin compression acceleration for non-differentiated payment processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Licensing | OJK approval enables lending and insurance margin pools beyond transaction processing. |
| Biometric Authentication Deployment | Facial and fingerprint verification eliminates dedicated hardware requirements for tier-2 merchants. |
| Eastern Indonesia Geographic Expansion | Sulawesi and Papua corridors offer first-mover terrain with sparse traditional banking infrastructure. |
| Super-App Platform Integration | Ride-hailing and food delivery ecosystems convert existing networks into payment acceptance points. |
| QRIS Technical Standardization | Bank Indonesia mandates force interoperability and prevent proprietary merchant lock-in. |
Study Parameters
Operator-level perspectives from digital wallet product managers, Bank Indonesia payment system supervisors, OJK regulatory compliance officers, and micro-merchant network operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against BI-FAST infrastructure disclosures, OJK e-money issuer capital adequacy filings, QRIS technical specification documents, and super-app platform transaction volume reports. Bottom-up merchant adoption modeling and top-down payment system flow analysis provided triangulation across independent estimation approaches.
Sensitivity analysis tested forecast robustness across BI-FAST fee revision scenarios and OJK float income cap adjustments throughout the projection horizon. The analytical framework modeled technology substitution dynamics, end-user segment penetration curves, service type margin evolution, and distribution channel cost structures. CAGRs derived from segment-level adoption rates, average transaction value trajectories, and merchant density saturation patterns across Java's urban corridor and Eastern Indonesia expansion zones.
Forecasts assume regulatory continuity in Bank Indonesia payment system licensing and OJK e-money issuer frameworks; material policy shifts would require re-modeling. Specific risk factors include QRIS standardization implementation delays, biometric authentication data localization compliance costs, and super-app platform market concentration regulatory intervention. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Smart Bands Payments Market
Payments
Canada Payments Market
Payments
Telecom Cloud Billing Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Denmark Mobile Payments Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Global Payments Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Electronic Payment Processing Software Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Belgium Payments Market
Payments
Global Accounts Payable Automation Market
Payments
Mexico Real Time Payments Market
Payments
MENA Digital Payments Market