
 Hydrotreated Vegetable Oil Market | 2026-2036
Hydrotreated Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrotreated Vegetable Oil Market Foresight
The EU Renewable Energy Directive III is broadening the addressable market for hydrotreated vegetable oil by mandating advanced biofuel quotas in maritime and aviation sectors. Neste leverages its Singapore and Rotterdam refining assets to dominate renewable diesel supply chains. Valero Energy Corporation anchors North American production through its Diamond Green Diesel joint venture. TotalEnergies SE competes by integrating HVO output with its European refining network and downstream fuel retail infrastructure.
Hydrotreated vegetable oil consists of triglyceride feedstocks—rapeseed oil, used cooking oil, or animal fats—processed through catalytic hydrogenation at temperatures exceeding 300 degrees Celsius and pressures above 80 bar to yield paraffinic hydrocarbons with near-zero sulfur and aromatics content. This chemical transformation produces a drop-in diesel substitute compatible with existing compression-ignition engines and distribution infrastructure. Transportation fuels applications occupy the largest value pool within the application dimension, while premium grade quality specifications command superior margins due to stringent cold-flow property requirements in Nordic markets. The aerospace end user segment registers the fastest structural expansion as airlines face mounting pressure to decarbonize scope three emissions through certified sustainable aviation fuel blends.
The European Union's F-Gas Regulation and REACH framework govern feedstock traceability and process emissions disclosure for HVO producers accessing EU markets. EPA's Renewable Fuel Standard and California Air Resources Board's Low Carbon Fuel Standard collectively determine compliance credit values and pathway eligibility for North American suppliers. Stakeholders must monitor feedstock certification schemes and evolving lifecycle assessment methodologies to secure offtake contracts with carbon-intensity-conscious buyers.
Market Dynamics
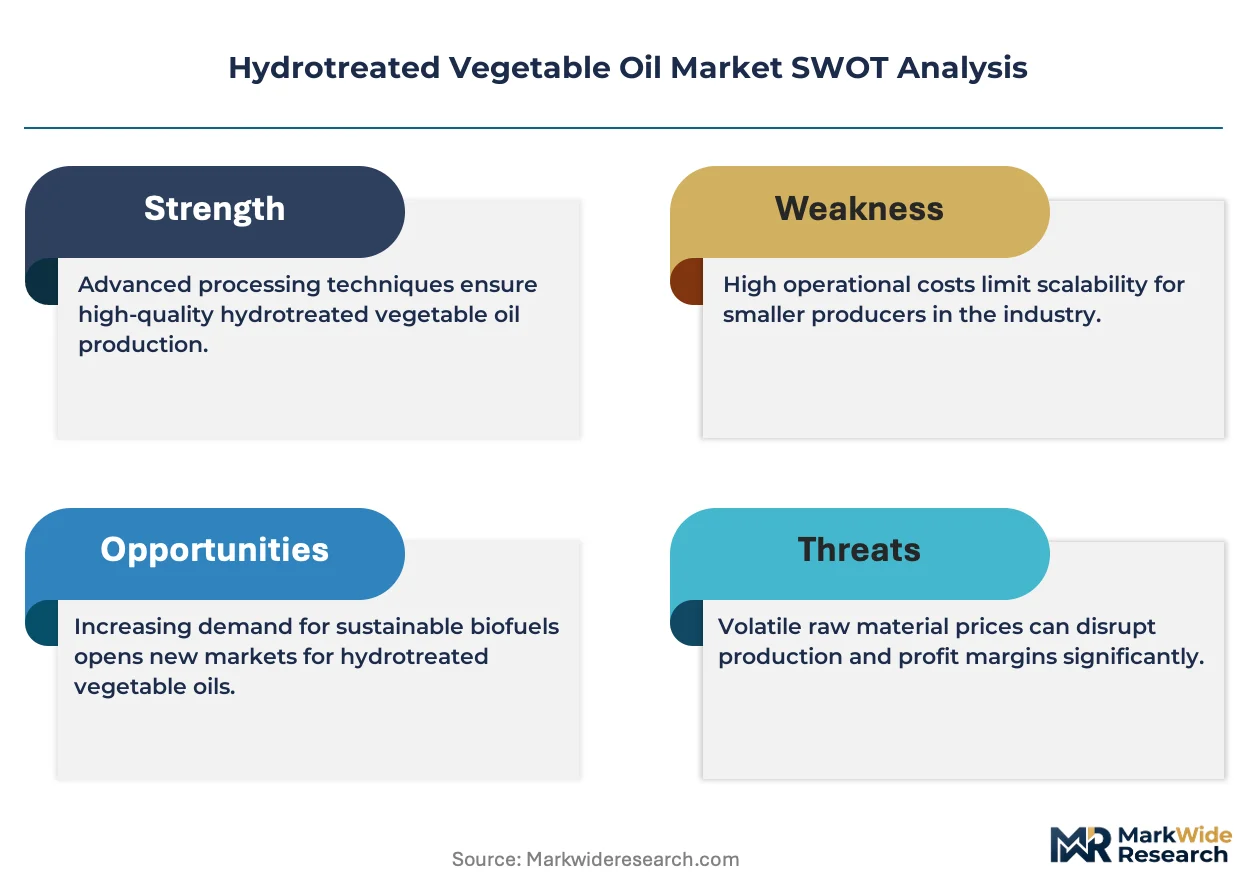
The EU Renewable Energy Directive III is compressing compliance timelines for maritime and aviation fuel suppliers, forcing immediate feedstock requalification and process upgrades across European refining networks.
Growth Catalysts
- California LCFS credit premiums:The state's Low Carbon Fuel Standard generates tradable credits for HVO pathways with sub-30 gCO2e/MJ carbon intensity, attracting refinery investment into used cooking oil processing infrastructure.
- Singapore maritime bunkering:The Port Authority's mandate for B50 biofuel blends in harbor craft by 2026 is creating dedicated HVO demand from Asian shipping lines seeking IMO 2030 compliance.
- Catalytic co-processing:Fluid catalytic cracking unit retrofits at conventional refineries enable HVO output without standalone renewable diesel facilities, lowering capital barriers for mid-scale producers.
Market Restraints
- Feedstock cost volatility:Tallow and used cooking oil prices track vegetable oil futures with 0.7 correlation, exposing margins to palm oil and soybean oil swings at Rotterdam and Singapore trading hubs.
- Rotterdam supply concentration:Europe's HVO output clusters at a single port complex, creating vessel queue bottlenecks and terminal access premiums during quarterly mandate compliance windows.
- FAME cold-flow limitations:Fatty acid methyl ester retains superior pour point performance below minus 20 degrees Celsius, blocking HVO penetration in Nordic winter diesel specifications without costly additives.
Strategic Opportunities
- Brazilian aviation offtake:ANAC's proposed 10% sustainable aviation fuel mandate by 2030 opens demand for HVO-derived synthetic paraffinic kerosene from sugarcane bagasse and soybean oil pathways.
- Power-to-liquid convergence:Fischer-Tropsch synthesis integrated with green hydrogen and captured carbon dioxide enables e-fuel production sharing HVO distribution infrastructure and offtake contracts.
- Industrial heat applications:Marine and stationary engine OEMs are certifying HVO for medium-speed diesel generators, creating non-transport demand pools with lower certification burden than aviation fuel.
Industry Challenges
- ISCC PLUS audit timelines:Feedstock traceability certification requires 14-18 month validation cycles for multi-origin waste oil supply chains, delaying contract execution with European buyers.
- Hydrogen supply security:Renewable diesel hydrotreating consumes 1,200-1,500 cubic meters of hydrogen per ton of output, exposing operations to electrolyzer commissioning delays and natural gas reforming cost spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrotreated Vegetable Oil Market |
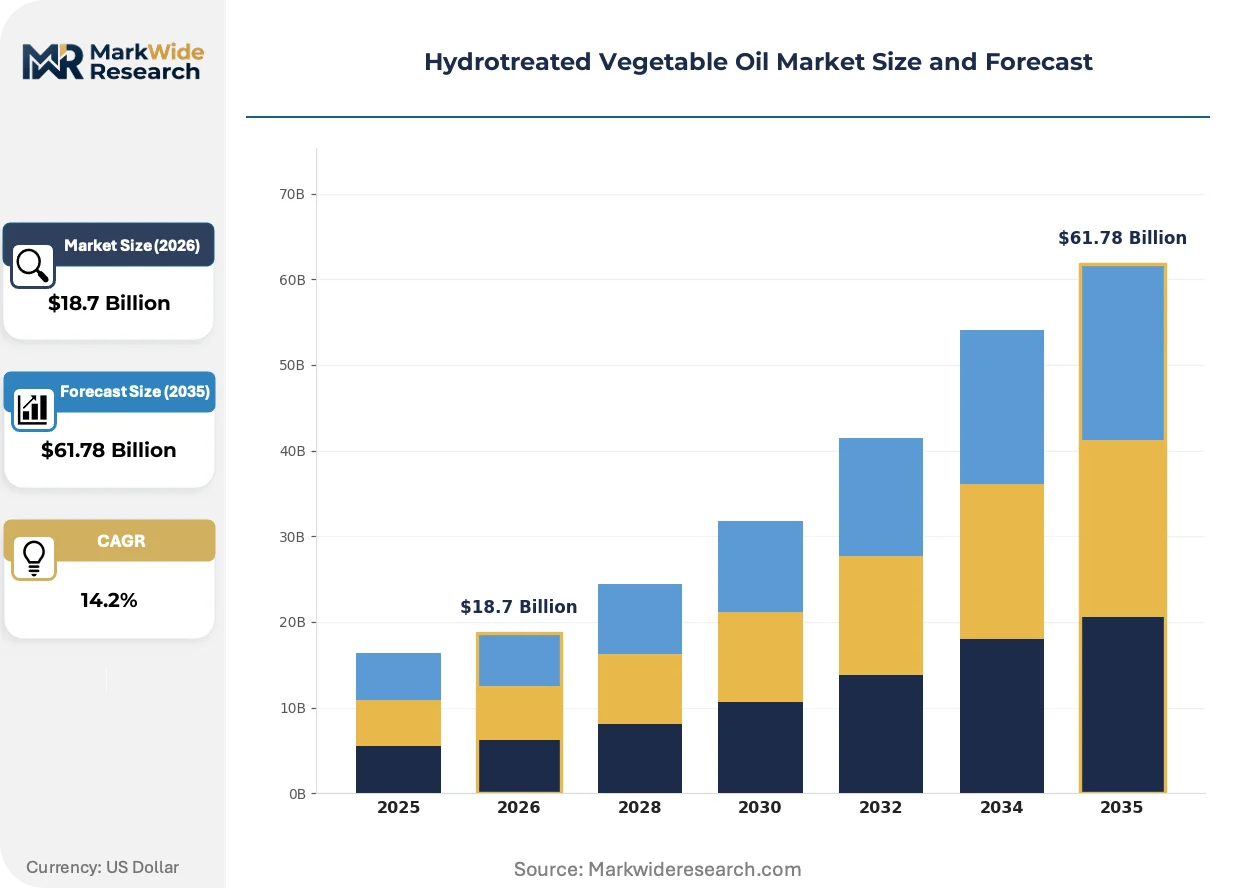
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated Oils, Biofuels, Cooking Oils, Industrial Oils Application: Transportation Fuels, Lubricants, Heating Oils, Food Products End User: Aerospace, Food Service, Automotive, Energy Sector Quality Grade: Premium Grade, Food Grade, Industrial Grade, Others |
| Companies Covered | Neste, Valero Energy Corporation, TotalEnergies SE, Repsol S.A., ENI S.p.A., Preem AB, UPM Biofuels, World Energy LLC, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrotreated Vegetable Oil Market Shifts & Advancements
Refinery technology choices are bifurcating between standalone renewable diesel units and co-processing retrofits, with feedstock flexibility emerging as the decisive competitive variable rather than scale alone.
Co-processing technology is overtaking standalone HVO investments for mid-scale refiners seeking lower capital exposure. This approach injects triglyceride feedstocks directly into existing hydrotreaters at 5-30% co-feed ratios. European refiners in the 50,000-150,000 barrel per day range are adopting this path to avoid stranded asset risk from full renewable diesel conversions. The technology is compressing payback periods from seven years to under four while preserving gasoline and jet fuel output flexibility.
REACH feedstock disclosure requirements are tightening traceability standards for waste-origin HVO entering European markets. ECHA's updated annexes mandate mass-balance documentation from collection point through final hydrotreatment, disqualifying informal used cooking oil aggregators. Maritime fuel suppliers sourcing B30-B100 blends are most affected, with Rotterdam terminal operators investing in blockchain verification systems to maintain berth access.
Airline procurement departments are consolidating sustainable aviation fuel contracts under ten-year offtake structures with fixed-price escalators and carbon intensity guarantees. This replaces the spot-market purchasing dominant through 2022. The shift is most visible among European network carriers facing CORSIA compliance from 2024, with Amsterdam and Frankfurt hub operators locking in HVO-SPK supply from Singapore and Rotterdam producers to secure volume certainty.
Hydrotreated Vegetable Oil Market Segmentation
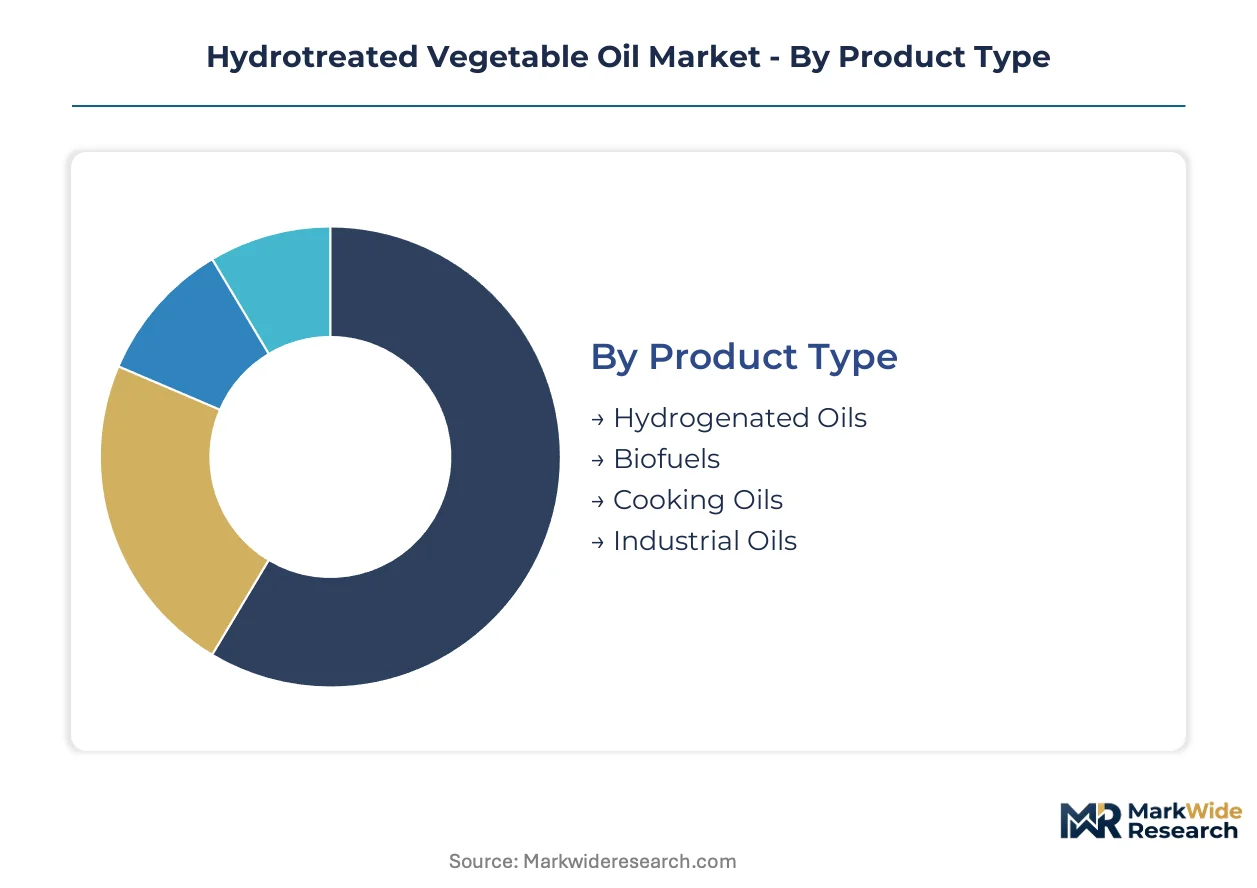
Segmentation in the HVO market reveals how feedstock chemistry, end-use certification requirements, and carbon intensity thresholds create distinct value pools. Buyers select grades based on cold-flow specifications, renewable content mandates, and traceability standards rather than commodity pricing alone.
Product Type:
Hydrotreatment intensity and feedstock origin differentiate product categories along the paraffinic purity spectrum.
- Hydrogenated Oils:Refined from virgin vegetable oils through high-pressure catalytic saturation, delivering C15-C18 paraffinic chains with sub-10 ppm sulfur content. Demand concentrates in German automotive OEM compliance pools where RED III mandates require documented renewable origin.
- Biofuels:Derived from waste feedstocks including tallow and used cooking oil, carrying ISCC PLUS certification for double-counting under EU sustainability criteria. Singapore maritime bunkering terminals are absorbing volumes for B50 blend compliance by the Port Authority's 2026 deadline.
- Cooking Oils:Post-consumer vegetable oil streams requiring extensive pretreatment to remove free fatty acids and moisture before hydrotreatment.
- Industrial Oils:Technical-grade triglycerides from palm fatty acid distillate and tall oil pitch serving non-fuel applications.
Hydrogenated oils lead on scale; biofuels lead on momentum.
Application:
End-use specifications fragment the market across mobility, thermal, and industrial lubrication segments with divergent certification burdens.
- Transportation Fuels:Renewable diesel and sustainable aviation fuel blends dominate volume offtake, with CORSIA-eligible HVO-SPK commanding premium pricing from Amsterdam and Frankfurt hub carriers. California LCFS credit stacking amplifies refinery margins for sub-30 gCO2e/MJ pathways.
- Lubricants:Group III+ base oil substitutes for marine and stationary engines, leveraging HVO's zero-sulfur, zero-aromatic profile to extend drain intervals in medium-speed diesel generators.
- Heating Oils:Residential and commercial boiler fuel requiring no equipment modification, penetrating Nordic markets where FAME cold-flow limitations block biodiesel adoption.
- Food Products:Hydrogenated edible oils for confectionery and baking applications, subject to FDA and EFSA trans-fat labeling thresholds.
Transportation fuels anchor volume concentration; lubricants are climbing the fastest as industrial heat applications expand.
End User:
Customer procurement sophistication varies from ten-year offtake contracting to spot-market purchasing based on emissions disclosure obligations.
- Aerospace:Airlines under CORSIA compliance pressure are locking in HVO-derived synthetic paraffinic kerosene through fixed-price escalator contracts with Rotterdam and Singapore producers. ANAC's proposed Brazilian SAF mandate is opening additional demand corridors.
- Automotive:Fleet operators and OEM compliance pools purchasing renewable diesel for scope three emissions reduction, concentrated in California and Germany where blending mandates are most stringent.
- Food Service:Used cooking oil aggregators supplying feedstock back into HVO supply chains, now requiring blockchain traceability for ECHA REACH compliance.
- Energy Sector:Power generators and marine operators seeking drop-in diesel replacements for medium-speed engines without retrofit requirements.
Automotive leads on installed base scale; aerospace shows the steepest expansion trajectory.
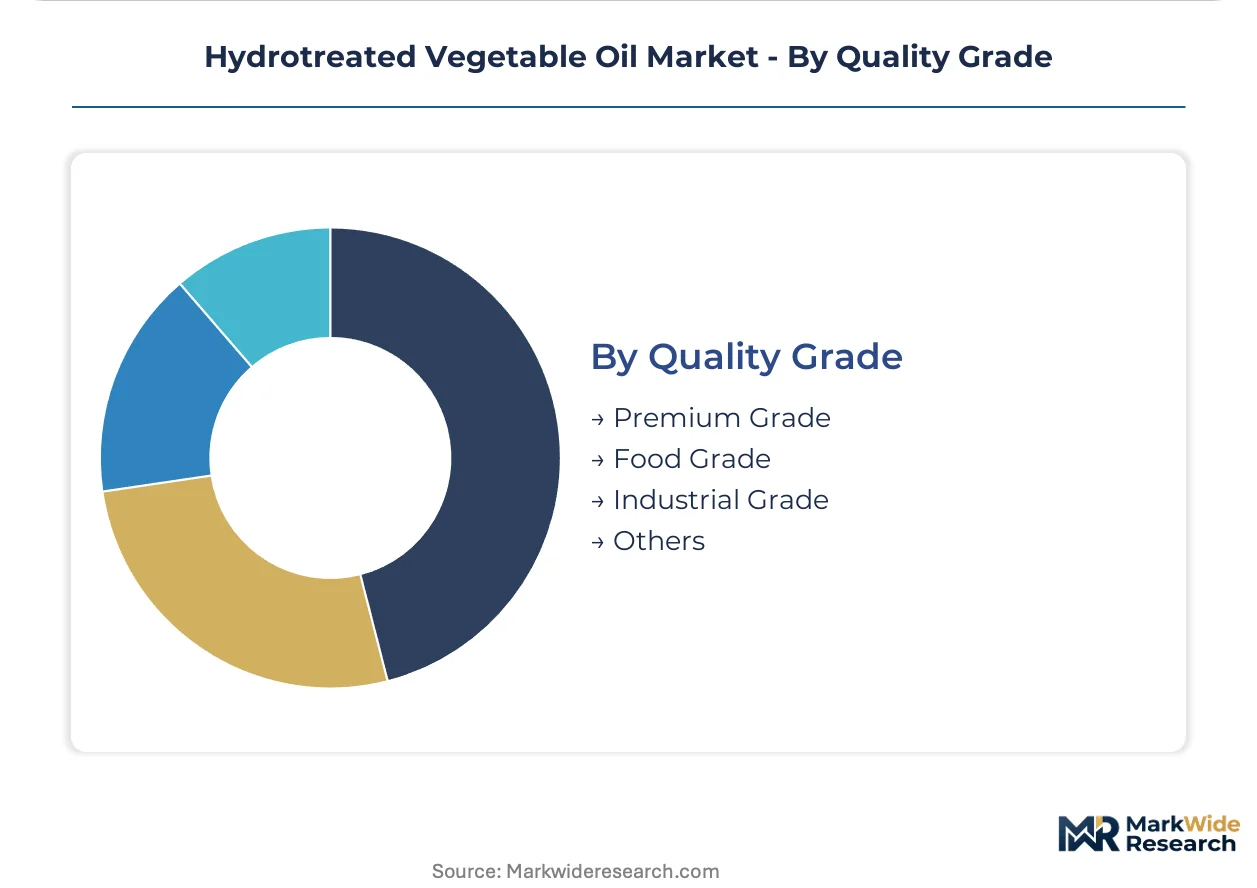
Quality Grade:
Certification tiers separate specification-grade material from commodity product based on traceability documentation and cold-flow performance.
- Premium Grade:Cloud point below minus 20 degrees Celsius enabling Nordic winter diesel specifications without additive blending, commanding Rotterdam terminal premiums during quarterly mandate windows.
- Food Grade:Edible hydrogenated oils meeting FDA 21 CFR and EFSA purity criteria for direct food contact applications.
- Industrial Grade:Technical specifications for marine bunkering and stationary power generation where cold-flow requirements are less stringent.
- Others:Emerging grades including power-to-liquid e-fuels sharing HVO infrastructure and certification frameworks.
Premium grade captures margin concentration; industrial grade handles volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial-scale hydrotreatment of vegetable oils originated in European refining complexes during the early 2000s, with Finland and the Netherlands establishing the first dedicated renewable diesel facilities. This Nordic-Benelux foundation shaped subsequent capacity expansion patterns across multiple continents.
United States
California's LCFS credit market attracts HVO investment into used cooking oil processing infrastructure along the Gulf Coast. EPA's Renewable Fuel Standard determines pathway eligibility for domestic producers. The Diamond Green Diesel joint venture in Louisiana anchors North American output capacity.
Netherlands
Rotterdam's port complex processes the majority of European HVO throughput for maritime bunkering and road fuel blending. The EU Renewable Energy Directive III mandates advanced biofuel quotas tightening each compliance period. Singapore-bound vessels queue at Rotterdam terminals for B30-B100 bunker fuel loading.
Singapore
The Port Authority's B50 biofuel mandate for harbor craft by 2026 concentrates Asian HVO demand at this single bunkering hub. Maritime fuel suppliers invest in blockchain traceability systems to satisfy ECHA REACH documentation requirements. Neste's Singapore refinery exports HVO-SPK to European airline offtakers.
Brazil
ANAC's proposed 10% sustainable aviation fuel mandate by 2030 opens demand for HVO-derived synthetic paraffinic kerosene from sugarcane bagasse pathways. The national petroleum regulator shapes feedstock qualification standards for aviation use. São Paulo-state crushers supply soybean oil to emerging hydrotreatment capacity.
Germany
German automotive OEM compliance pools purchase premium-grade HVO with cloud points below minus 20 degrees Celsius for winter diesel specifications. The country's federal motor transport authority enforces RED III renewable content mandates. Bavarian refiners process rapeseed oil through co-processing retrofits to avoid stranded asset risk.
Hydrotreated Vegetable Oil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across feedstock flexibility and certification tiering. The market structure consolidates around integrated refiners with captive hydrogen supply and long-term offtake contracts, while mid-scale operators compete through co-processing retrofits at conventional facilities. Three archetypes dominate: integrated oil majors leveraging existing refining networks, standalone renewable diesel specialists with dedicated hydrotreatment assets, and regional fuel marketers securing ISCC PLUS certification for waste feedstock sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing hydrogen supply agreements and airline offtake contracts to lock in margin visibility.
Among Nordic-origin renewable fuel specialists, Neste anchors the premium tier through its Singapore and Rotterdam refining footprint. Valero Energy Corporation exemplifies the integrated major archetype via its Diamond Green Diesel joint venture structure. TotalEnergies SE occupies a position bridging European refining integration with downstream fuel retail infrastructure. These three entities represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Neste |
| Valero Energy Corporation |
| TotalEnergies SE |
| Repsol S.A. |
| ENI S.p.A. |
| Preem AB |
| UPM Biofuels |
| World Energy LLC |
| Phillips 66 |
| Others |
Supply & Pricing Matrix
CORSIA compliance eligibility gates both qualified supply access and premium-tier pricing power for hydrotreated vegetable oil producers serving airline offtakers. Rotterdam terminal operators extract berth access premiums during quarterly mandate windows when Singapore-bound vessels queue for B30-B100 bunker fuel loading.
Pricing Analysis
Long-term offtake contracting with fixed-price escalators dominates premium-tier transactions, displacing the spot-market purchasing that prevailed through 2022. Price differentiation separates ISCC PLUS-certified biofuels with double-counting eligibility from uncertified commodity grades, while cloud point specifications below minus 20 degrees Celsius command Nordic winter diesel premiums. Cost compression in standard-grade hydrogenated oils is intensifying because tallow and used cooking oil prices track vegetable oil futures with 0.7 correlation. Fleet operators in California LCFS markets show least price sensitivity due to credit stacking mechanics, whereas industrial heat buyers without mandate exposure drive hardest bargain negotiations.
Supply Chain Analysis
Hydrogen supply security rests on electrolyzer commissioning timelines and natural gas reforming cost exposure at hydrotreatment facilities. Feedstock sourcing draws from the Netherlands, Singapore, and Finland where refining infrastructure concentrates, with tallow, used cooking oil, and rapeseed oil constituting the three primary triglyceride inputs. Single-source vulnerability runs through Rotterdam's port complex where Europe's HVO output clusters, creating vessel queue bottlenecks during compliance windows. Distribution runs through maritime bunkering terminals and road fuel blending facilities with blockchain verification systems for ECHA REACH mass-balance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrotreated vegetable oil arbitrage economics hinge on the carbon intensity differential between California LCFS credit markets and EU Renewable Energy Directive III compliance costs. Producers with feedstock flexibility across both regulatory zones capture structural margin expansion.
For Market Incumbents: Lock in ten-year airline offtake contracts with carbon intensity guarantees before CORSIA compliance windows tighten. Secure captive hydrogen supply agreements to insulate operations from electrolyzer commissioning delays and natural gas reforming cost spikes. Neste's Singapore-Rotterdam refining footprint demonstrates the defensive value of dual-hemisphere production assets against regional mandate volatility. For New Entrants and Emerging Players: Enter via Brazilian aviation offtake corridors where ANAC's proposed sustainable aviation fuel mandate creates first-mover positioning before incumbent capacity allocation hardens. Target sugarcane bagasse and soybean oil feedstock pathways for HVO-derived synthetic paraffinic kerosene production. Pursue co-processing retrofits at existing hydrotreaters rather than greenfield renewable diesel investments to compress capital exposure and preserve fuel output flexibility. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale co-processing operators because stranded asset risk at conventional refineries is forcing distressed asset availability across the 50,000-150,000 barrel per day range. ISCC PLUS certification infrastructure and long-term hydrogen supply contracts constitute the scarce capability bundle that determines acquisition premiums. Watch for electrolyzer commissioning delays at major production hubs as the inflection signal for hydrogen cost volatility and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Processing Retrofit Deployment | Fluid catalytic cracking unit modifications at European refineries compress payback periods below four years. |
| Blockchain Traceability Implementation | Rotterdam terminal operators invest in verification systems to maintain ECHA REACH compliance and berth access. |
| Long-Term Hydrogen Supply Agreement | Captive hydrogen contracts insulate renewable diesel operations from natural gas reforming cost volatility. |
| ISCC PLUS Certification Investment | 14-18 month validation cycles for waste oil supply chains secure double-counting eligibility under EU sustainability criteria. |
| Power-to-Liquid Convergence | Fischer-Tropsch synthesis with green hydrogen enables e-fuel production sharing HVO distribution infrastructure. |
Research Methodology
Direct dialogue with renewable diesel refinery operations managers, airline sustainable aviation fuel procurement directors, maritime bunkering terminal operators, and hydrogen supply specialists grounded the qualitative assessment. Secondary validation drew from EPA Renewable Fuel Standard pathway filings, California Air Resources Board LCFS credit transaction data, ECHA REACH annex updates, and EU Renewable Energy Directive III implementation guidance. Bottom-up capacity and feedstock modeling triangulated against top-down mandate compliance demand projections.
Segment-level volume and value trajectories across the analysis window reflect feedstock chemistry differentiation, end-use certification requirements, and carbon intensity threshold segmentation. The analytical framework modeled product type, application, end user, and quality grade dimensions alongside regional regulatory cluster variations. CAGRs were derived from mandate compliance timeline compression and aviation sector offtake acceleration. Forecast inputs incorporated hydrotreatment capacity expansion announcements and electrolyzer deployment pipelines without project-specific timing assumptions.
Inputs from refinery operations managers and airline procurement directors were available through the study window; gaps in hydrogen supply contract pricing and waste oil aggregator margin structures introduce uncertainty bands around cost curve positioning. Forecasts reflect documented assumptions regarding CORSIA implementation pacing and EU RED III maritime quota enforcement. Feedstock certification timeline delays, hydrogen supply security disruptions, and Nordic winter diesel specification shifts constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Jatropha Biodiesel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market