
 Sustainable Fuel Market | 2026-2036
Sustainable Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Fuel Market Insights
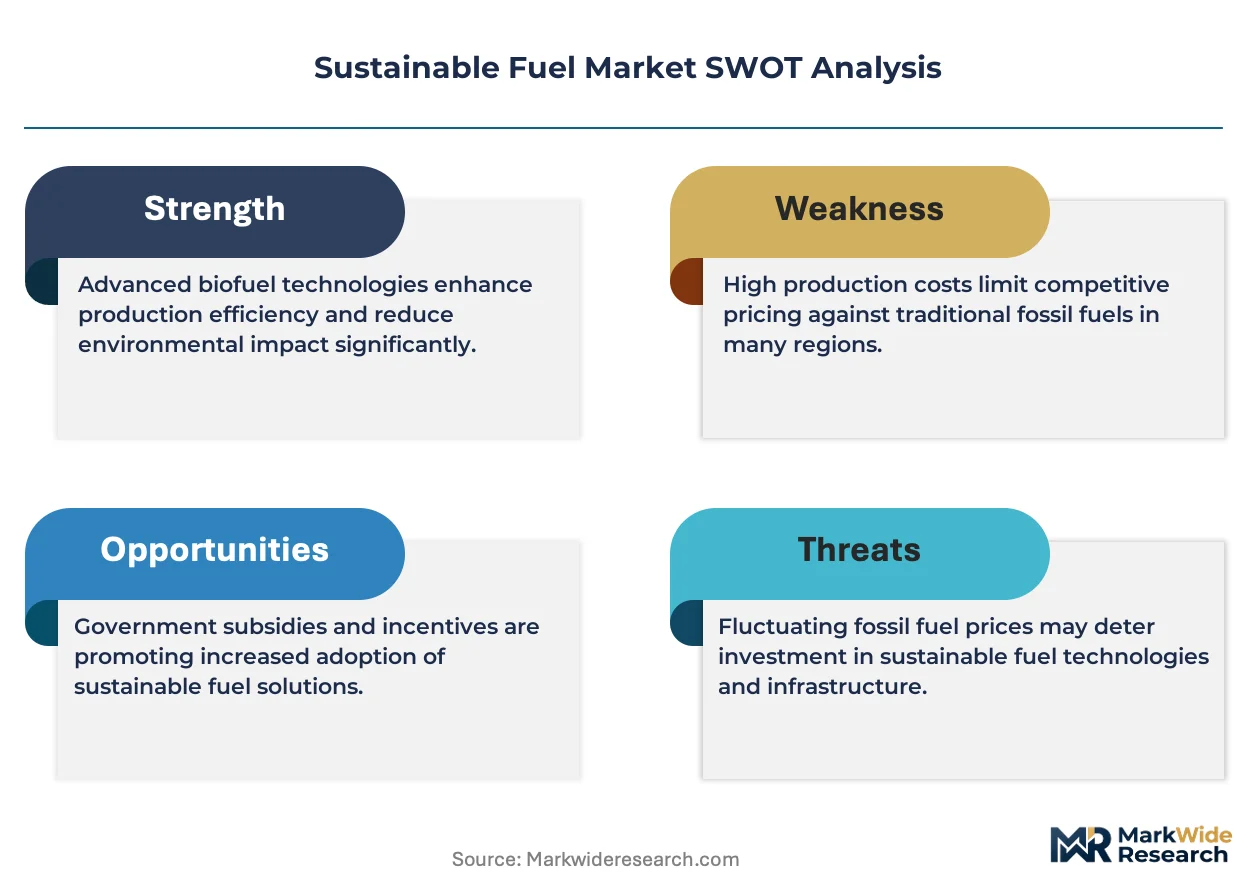
Project finance structures with offtake agreements and green bond issuance is tilting competitive access toward capital-rich incumbents. Neste Corp. anchors its position through backward integration into waste and residue feedstock collection across multiple continents. Shell plc leverages its existing refining infrastructure to co-process sustainable feedstocks at scale. TotalEnergies SE competes by specializing in biogas-to-liquid pathways that differentiate its product slate from conventional hydrotreated esters.
Sustainable fuels encompass liquid, gaseous, or solid energy carriers derived from biomass, waste streams, or renewable hydrogen with lifecycle greenhouse gas reductions typically exceeding 50% relative to fossil counterparts. These fuels function as drop-in replacements in existing internal combustion engines, turbines, and industrial burners without requiring infrastructure overhaul. Bio-jet fuel currently occupies the highest-margin pool as aviation decarbonization timelines tighten, while hydrogen as a fuel type remains capital-intensive but captures growing industrial offtake interest. Biodiesel dominates transportation application volumes, though ethanol faces feedstock competition from food security priorities in key producing regions.
The EU Green Deal's ReFuelEU Aviation mandate and the U.S. Inflation Reduction Act's clean fuel production credits are reshaping demand geography by redirecting investment toward jurisdictions with durable subsidy frameworks. EPA Renewable Fuel Standard obligations and California's Low Carbon Fuel Standard create layered compliance incentives that stack with federal support. Stakeholders must monitor whether feedstock traceability requirements under emerging regulations fragment certification schemes or consolidate market access around vertically integrated suppliers.
Market Dynamics
The EU Green Deal's ReFuelEU Aviation mandate and the U.S. Inflation Reduction Act's clean fuel production credits are concentrating investment flows toward jurisdictions with durable subsidy frameworks. These overlapping compliance obligations are forcing project developers to optimize for stacked incentives rather than standalone economics.
Growth Catalysts
- ReFuelEU Aviation mandate:Airlines face binding blending quotas for sustainable aviation fuel, creating guaranteed offtake demand through 2035.
- Hydrotreated esters and fatty acids (HEFA):Mature refining technology allows rapid capacity deployment without greenfield construction timelines.
- California Low Carbon Fuel Standard:Credit stacking with federal IRA incentives improves project returns for renewable diesel producers.
Market Restraints
- Feedstock competition:Waste oils and animal fats face rival demand from oleochemicals and pet food sectors, tightening input supply.
- Biomass supply concentration:Agricultural residue collection networks remain underdeveloped outside the U.S. Midwest and Brazilian sugarcane belts.
- Power-to-liquid cost structure:Electrolyzer capex and renewable electricity pricing render e-fuels uncompetitive without sustained subsidy support.
Strategic Opportunities
- India ethanol blending:The country's E20 target creates demand for second-generation cellulosic capacity using agricultural residues.
- Biogas-to-liquid pathways:Anaerobic digesters at wastewater treatment plants offer stranded biogas for Fischer-Tropsch conversion.
- Carbon capture integration:Point-source CO2 from ethanol plants and ammonia facilities enables synthetic fuel production with improved lifecycle credentials.
Industry Challenges
- ISCC certification timelines:Third-party verification of feedstock traceability creates bottlenecks for project commissioning.
- Specialized welding and pressure vessel fabrication:Skilled labor shortages delay construction of hydrotreatment units at scale.
- Co-processing compatibility:Existing refinery catalysts require modification to handle elevated oxygen and contaminant levels in bio-feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Fuel Market |
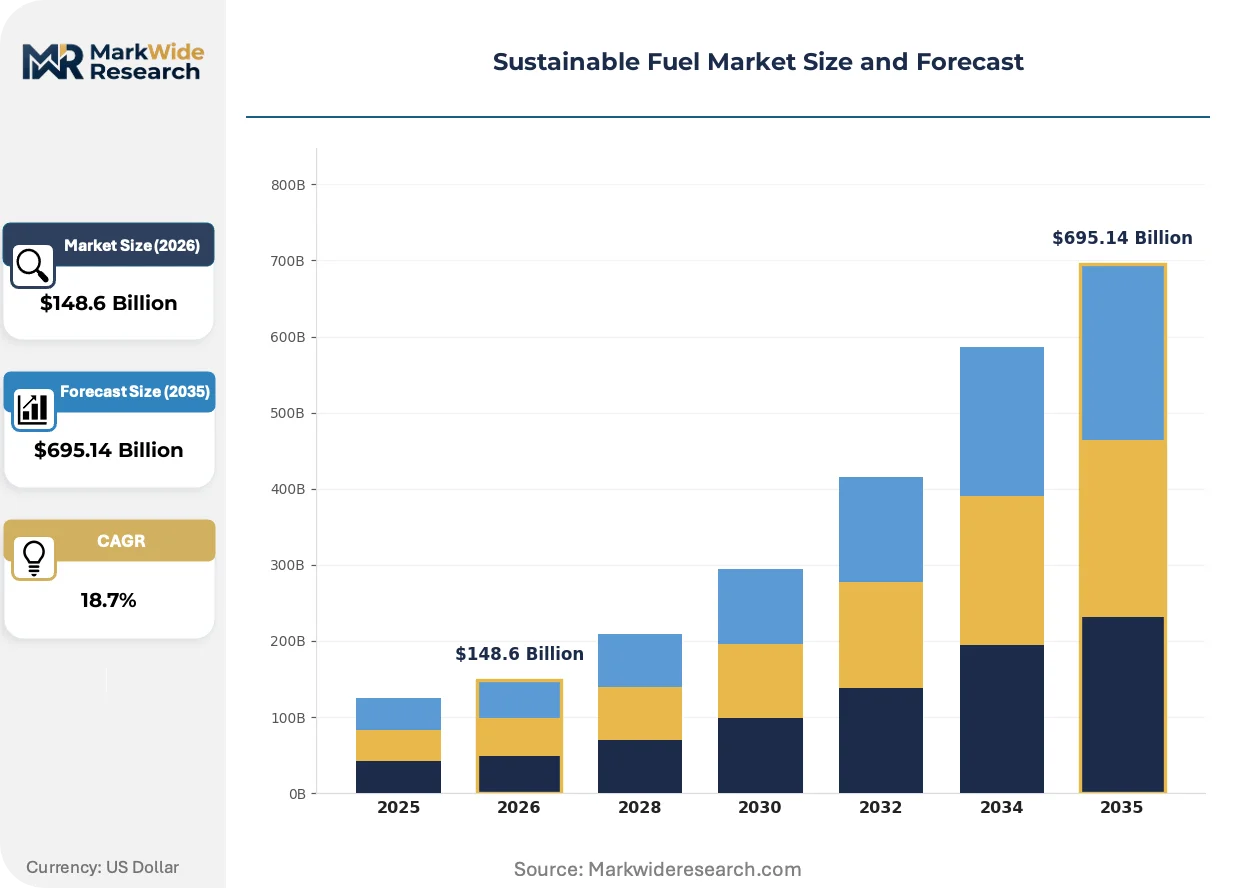
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $695.14 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biodiesel, Ethanol, Hydrogen, Bio-jet Fuel Application: Transportation, Power Generation, Industrial Use, Heating End User: Automotive, Aviation, Marine, Industrial Sector Distribution Channel: Retail, Direct Sales, Online, Wholesale |
| Companies Covered | TotalEnergies SE, Neste Corp., Shell plc, BP plc, Chevron Corporation, Cargill Inc., The Archer-Daniels-Midland Company, Equinor ASA, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Fuel Market Trends and Innovations
Technology developers are pivoting from first-generation lipid pathways toward alcohol-to-jet and gasification routes that expand eligible feedstock pools. This diversification is compressing the cost premium between sustainable and conventional fuels.
Alcohol-to-jet (ATJ) technology is migrating from demonstration scale to commercial deployment. LanzaJet's Freedom Pines facility in Georgia processes ethanol into synthetic paraffinic kerosene for aviation offtakers. The process is enabling corn and cellulosic ethanol producers to access higher-margin jet fuel markets without building dedicated HEFA capacity.
The EU's Renewable Energy Directive III tightens sustainability criteria for biomass feedstocks, excluding crops from high-carbon-stock land. Industrial operators must requalify supply chains under delegated acts from the European Commission. Aviation fuel producers are responding by accelerating waste and residue pathway investments to maintain eligibility for mandate compliance.
Airlines are consolidating procurement through long-term offtake agreements with price escalation clauses tied to carbon credit values. This mechanism transfers volume risk to producers while securing supply for carriers facing ReFuelEU penalties. The model is most visible in European flag carriers, where compliance cost visibility has reached board-level planning cycles.
Sustainable Fuel Market Segmentation
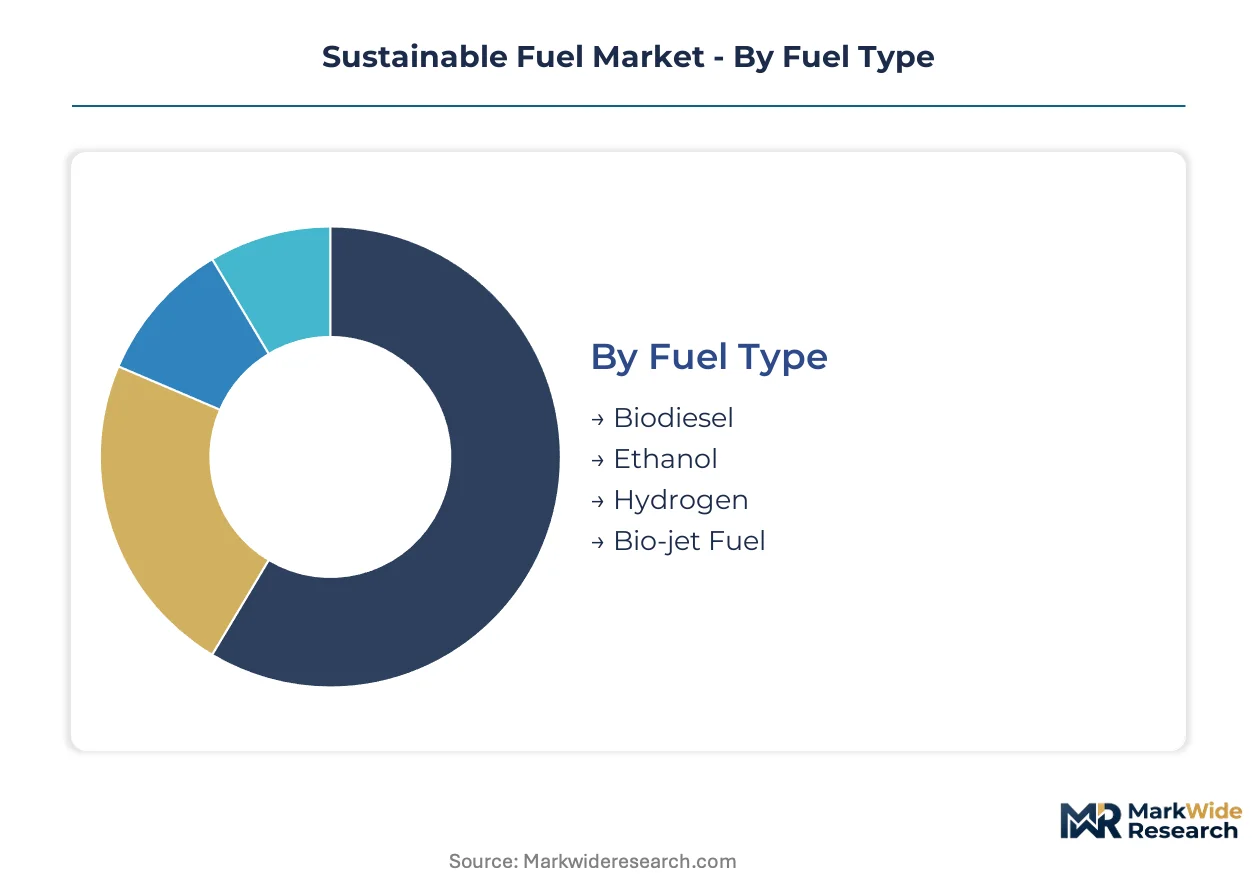
Sustainable fuel procurement patterns diverge sharply across fuel chemistry, end-use application, and customer scale. Understanding these dimensional splits reveals where capital deployment concentrates and which compliance frameworks govern offtake contracting.
Fuel Type:
Cost tier stratification separates mature pathways from emerging technologies still seeking scale economies.
- Biodiesel:Fatty acid methyl ester produced from vegetable oils or animal fats through transesterification. Demand concentrates in California and Germany where Low Carbon Fuel Standard credits stack with national blending mandates, though feedstock competition from oleochemicals tightens input supply.
- Bio-jet Fuel:Hydrotreated esters and fatty acids refined to aviation turbine fuel specifications. Airlines under ReFuelEU Aviation quotas in France and the Netherlands are locking in decade-long offtake agreements, creating guaranteed demand pools that justify greenfield construction.
- Ethanol:Fermentation-derived alcohol blended into gasoline pools. Brazil's sugarcane belt and the U.S. Midwest maintain production gravity, with Indian E20 targets now pulling investment toward cellulosic capacity.
- Hydrogen:Renewable hydrogen produced via electrolysis or biomass gasification. Industrial offtake in the Netherlands and South Korea is climbing fastest as steel and ammonia producers face Scope 3 reduction deadlines.
Biodiesel holds installed capacity. Bio-jet fuel is rotating up the share rankings.
Application:
Volume concentration tracks regulatory obligation intensity across mobility and stationary energy.
- Transportation:Liquid fuels displacing diesel and gasoline in road, rail, and maritime engines. The U.S. renewable diesel boom and EU trucking fleet decarbonization rules are redirecting HEFA capacity toward highway diesel replacement.
- Industrial Use:Process heat and feedstock substitution in cement, steel, and chemicals. German industrial clusters are piloting hydrogen injection into blast furnaces under national hydrogen strategy funding.
- Power Generation:Biogas and liquid biofuels in peaking plants and grid stabilization. Italian and Danish utilities are expanding anaerobic digester networks to capture agricultural methane for electricity production.
- Heating:Residential and commercial building fuel oil substitution. Nordic district heating networks in Sweden and Finland are blending pyrolysis oil into combined heat and power plants.
Transportation dominates current offtake volumes. Industrial use is expanding most quickly as hard-to-abate sectors face carbon border adjustment exposure.
End User:
Customer type determines contract structure, with compliance-driven buyers accepting premium pricing against penalty avoidance.
- Aviation:Airlines purchasing sustainable aviation fuel to meet ReFuelEU blending quotas. European flag carriers are consolidating procurement through airline alliances to secure volume commitments.
- Automotive:Fleet operators and individual consumers via retail fueling infrastructure. California's LCFS credit pass-through mechanisms are narrowing the pump price gap with conventional diesel.
- Marine:Shipping lines responding to International Maritime Organization carbon intensity regulations. Rotterdam and Singapore bunkering hubs are adding biofuel blending capabilities to maintain port competitiveness.
- Industrial Sector:Manufacturing facilities with direct fuel procurement contracts. German chemical parks are negotiating dedicated hydrogen supply agreements with electrolyzer developers.
Aviation commands the steepest price premiums. Automotive is gaining share fastest as renewable diesel scales.
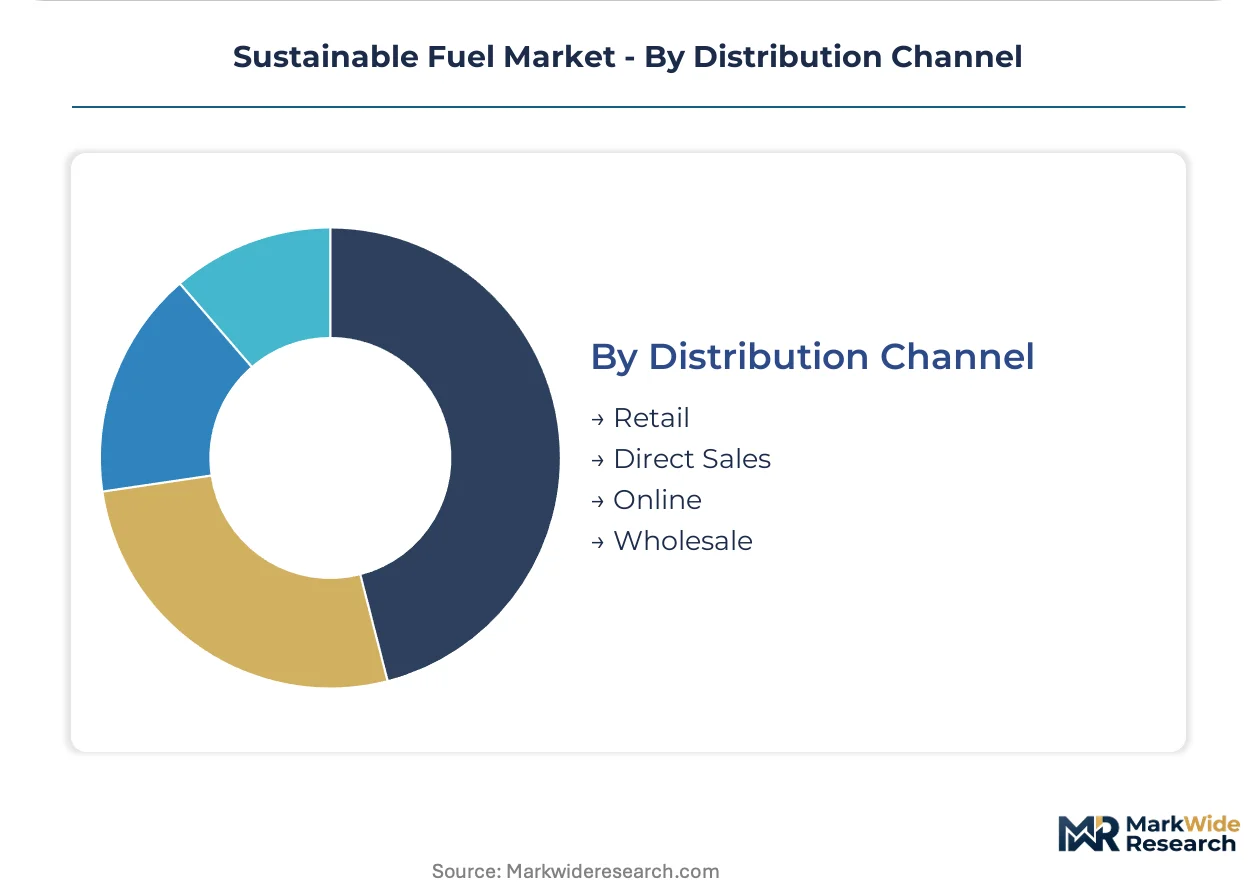
Distribution Channel:
Supply concentration shapes channel economics, with bulk industrial offtake bypassing retail markup structures.
- Direct Sales:Long-term contracts between producers and large industrial or aviation offtakers. Neste's Singapore refinery ships directly to European airline fuel farms under multi-year agreements.
- Wholesale:Intermediate distributors blending sustainable fuels into conventional supply chains. U.S. terminal operators are adding dedicated renewable diesel storage to handle California-bound volumes.
- Retail:Branded fueling stations offering consumer-facing sustainable options. HVO100 pumps in Scandinavian markets serve early-adopter passenger vehicle segments.
- Online:Digital platforms for certificate trading and book-and-claim systems. Emerging markets for SAF certificates allow corporate travel departments to claim emissions reductions without physical fuel offtake.
Direct sales capture margin from large-volume buyers. Wholesale is rotating up the share rankings as infrastructure investment spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA's clean fuel production credits and the EU Green Deal's ReFuelEU Aviation mandate are redirecting capital toward jurisdictions with durable subsidy frameworks. Investment flows concentrate where compliance obligations stack with production incentives.
United States
Renewable diesel capacity expansion along the Gulf Coast and California-bound logistics dominate deployment. The EPA Renewable Fuel Standard obligations layer with California's Low Carbon Fuel Standard credits to improve project economics. Houston-area refineries are retrofitting hydrotreatment units to co-process waste oil feedstocks.
Germany
Industrial hydrogen offtake from steel and chemical producers drives electrolyzer deployment in the Rhineland and Hamburg clusters. The national hydrogen strategy funds blast furnace injection pilots under EU Green Deal alignment. Leuna chemical park operators negotiate dedicated renewable hydrogen supply agreements with infrastructure developers.
Brazil
Sugarcane ethanol producers face feedstock competition from sugar export markets and domestic E20 blending mandates. The RenovaBio program certifies greenhouse gas reductions for export eligibility to California LCFS markets. São Paulo state mills are expanding anhydrous ethanol storage to meet distribution infrastructure gaps.
India
Second-generation cellulosic ethanol investment targets agricultural residue collection networks in Punjab and Haryana. The national biofuel policy's E20 deadline redirects molasses-based capacity toward fuel blending. Indian Oil Corporation's Panipat refinery is commissioning enzymatic hydrolysis units for straw-to-ethanol conversion.
Netherlands
Rotterdam bunkering hub competition for maritime biofuel blending drives storage terminal expansion. The Renewable Energy Directive III tightens biomass sustainability criteria for aviation fuel eligibility. Port authorities are coordinating waste-to-jet supply chain traceability systems with ISCC certification bodies.
Sustainable Fuel Market Competitive Landscape
On the supply side, the industry is consolidating around capital-rich incumbents with backward integration into feedstock collection and existing refining infrastructure. Integrated oil majors leverage co-processing capabilities at scale, while pure-play specialists concentrate on waste and residue pathway differentiation. Dominant competitive moves include long-term offtake contracting with price escalation clauses and geographic expansion into jurisdictions with stacked incentive frameworks.
Among European-integrated energy majors, TotalEnergies SE and Shell plc exemplify the refinery retrofit archetype, while Finland-based Neste Corp. occupies a position within the dedicated renewable products tier. These three companies represent contrasting strategic postures: biogas-to-liquid specialization, existing infrastructure leverage, and waste feedstock supply chain control respectively.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Neste Corp. |
| Shell plc |
| BP plc |
| Chevron Corporation |
| Cargill Inc. |
| The Archer-Daniels-Midland Company |
| Equinor ASA |
| Linde plc |
| Others |
Pricing and Supply Chain Analysis
Feedstock certification chokepoints under ISCC and EU Renewable Energy Directive III determine both the premium spreads between waste-residue and virgin-crop pathways and the geographic clustering of pretreatment capacity around traceable supply origins. Pricing power concentrates with producers who control collection networks in the U.S. Midwest, Brazilian sugarcane belts, and EU waste oil aggregation hubs.
Pricing Analysis
Certification grade creates the primary spread between ISCC-EU compliant waste-residue fuels and conventional HEFA products lacking full traceability. Contract-based long-term offtake dominates, with price differentiation driven by carbon intensity scores under California's LCFS and EU ETS linkage, plus volume scale commitments from airline alliances. Cost compression in cellulosic ethanol is intensifying because enzymatic hydrolysis capex overruns are squeezing project returns. Aviation offtakers under ReFuelEU mandates show least price sensitivity, while road transport blenders facing RIN price volatility exhibit highest elasticity.
Supply Chain Analysis
Waste oil and agricultural residue collection networks anchor upstream supply, drawing from the United States, Brazil, and Indonesia as primary feedstock territories. The chain rests on used cooking oil exports, animal fats from rendering facilities, and corn stover or sugarcane bagasse for cellulosic routes. Single-source vulnerability runs through Malaysian and Indonesian palm oil derivative channels facing EU deforestation regulation exclusion. Distribution runs through Rotterdam, Singapore, and Houston as bunkering and blending hubs serving aviation and maritime offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable fuel market represents a high-growth disruption propelled by the EU Green Deal's binding aviation blending mandates, which guarantee demand visibility through the projection horizon.
For Market Incumbents: Build captive feedstock moats through backward integration into waste oil collection networks across North America and Southeast Asia. Neste's multi-continent aggregation infrastructure demonstrates the defensive value of supply chain control against emerging pure-play competitors. Accelerate co-processing retrofit investments at Gulf Coast refineries to capture IRA credit stacking before qualification windows narrow. For New Entrants and Emerging Players: Build out stranded biogas-to-liquid capacity at municipal wastewater treatment facilities, where anaerobic digester infrastructure already exists and offtake competition remains thin. India's second-generation ethanol gap offers the most penetrable geography, with agricultural residue collection networks underdeveloped in Punjab and Haryana despite E20 policy deadlines. Pursue technology licensing partnerships with LanzaJet or Velocys to bypass greenfield process development timelines. For Investors and Strategic Acquirers: Specialist engineering firms with proprietary gasification or alcohol-to-jet reactor designs represent the highest-conviction acquisition archetype, given catalyst and reactor fabrication bottlenecks delaying project commissioning. Long-term viability hinges on whether power-to-liquid cost curves achieve convergence with HEFA economics before subsidy tapering. Monitor electrolyzer capex trajectories and renewable PPA pricing in Iberia and Australia as the inflection signal for e-fuel competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Secures ISCC-compliant supply chains against oleochemical sector competition for waste oils. |
| Co-Processing Retrofit at Existing Refineries | Shell's leveraging of hydrotreatment units demonstrates capital-efficient capacity expansion without greenfield construction. |
| Long-Term Offtake Agreement with Price Escalation | Air France-KLM and Lufthansa procurement consortia transfer volume risk to producers while ensuring mandate compliance. |
| Biogas-to-Liquid Pathway Development | TotalEnergies' specialization in Fischer-Tropsch conversion differentiates product slate from commodity HEFA supply. |
| Carbon Capture Integration at Ethanol Plants | Point-source CO2 utilization improves lifecycle credentials for synthetic fuel production under EU taxonomy criteria. |
Research Methodology
Cross-validation between executive interviews at renewable fuel producers and secondary analysis of EPA RIN generation data, EIA biofuel production statistics, and EU TARIC customs records anchors the qualitative findings. Primary fieldwork engaged refinery operations directors, airline fuel procurement managers, ISCC certification auditors, and agricultural commodity traders across the value chain. Bottom-up capacity installation tracking and top-down policy incentive modeling were reconciled to triangulate supply-demand balances.
Calibration against historical capacity utilization rates and announced project timelines informed the projection framework across the analysis window. Segmentation dimensions include fuel chemistry pathway, end-use application, customer scale, and regional regulatory cluster. CAGRs were derived from weighted capacity buildout schedules and offtake contract visibility, with electrolyzer cost curves and renewable electricity pricing trajectories serving as key sensitivity inputs for hydrogen and e-fuel segments.
Sensitivities concentrate around feedstock availability constraints, subsidy duration uncertainty, and certification scheme fragmentation. Forecasts reflect assumptions regarding mandate enforcement timelines and credit market liquidity. Cross-checking against IEA biofuel outlook benchmarks and IRENA hydrogen cost roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Sustainable Aviation Fuel Market