
 South Korea Renewable Energy Market | 2026-2036
South Korea Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Renewable Energy Market Analytics
Polysilicon supply from domestic refiners is hardening cost structures for photovoltaic module producers. SK E&S leverages its LNG-to-hydrogen transition infrastructure to anchor early-stage renewable hydrogen integration. Samsung Heavy Industries specializes in floating offshore wind platform fabrication, occupying a narrow but critical manufacturing niche. POSCO E&C extends its steel-intensive construction expertise into wind turbine foundation and substation contracts.
South Korea renewable energy encompasses electricity generation systems—photovoltaic arrays, offshore wind turbines, biomass combustion units, and run-of-river hydro installations—that convert natural flows into grid-synchronous power, typically targeting 60 Hz output at 22.9 kV distribution voltage or 345 kV transmission voltage for utility interconnection. Solar photovoltaic deployment dominates installed capacity, though offshore wind represents the fastest-expanding technology segment as seabed leasing accelerates in the Yellow Sea and South Sea. Utility-scale installations command the largest share of capital deployment, while distributed and microgrid configurations attract industrial end users seeking price hedging against Korea Electric Power Corporation tariff volatility.
MFDS safety standards for energy storage co-location, KOSHA occupational codes for offshore construction, and Ministry of Trade, Industry and Energy renewable portfolio obligations collectively shape project bankability and equipment certification pathways. METI-aligned green hydrogen certification frameworks further condition technology selection for hybrid installations. Stakeholders must weigh turbine supply chain localization requirements against Chinese component cost advantages when structuring procurement for upcoming offshore lease rounds.
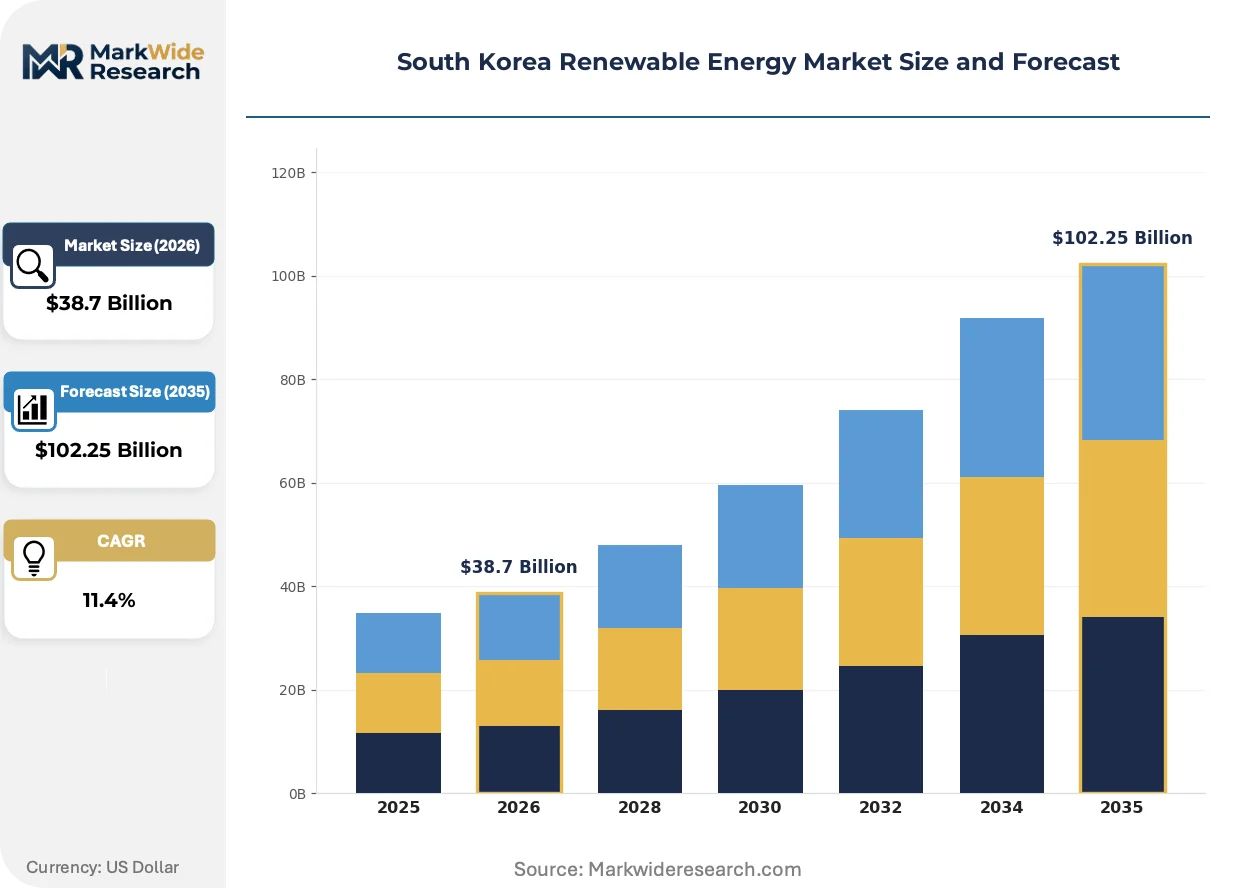
Market Dynamics
Seoul's Green New Deal mandates and floating offshore wind maturation are compressing project timelines while rerouting capital from conventional LNG baseload toward utility-scale photovoltaic and offshore wind complexes along the southern and western coasts.
Growth Catalysts
- Renewable Portfolio Standard:Ministry of Trade, Industry and Energy obligations force utilities to procure specified clean electricity quotas, tightening offtake security for developers.
- Industrial manufacturing clusters:Ulsan and Yeosu anchor accelerating corporate power purchase agreements as petrochemical majors seek tariff hedges against Korea Electric Power Corporation volatility.
- Floating platform fabrication:Specialized shipyard capabilities in Geoje and Mokpo enable deeper-water wind deployment beyond fixed-foundation depth limits.
Market Restraints
- Polysilicon supply concentration:Domestic refiner output constraints harden photovoltaic module cost structures, limiting margin compression for installers.
- Seabed leasing bottlenecks:Korea Hydrographic and Oceanographic Agency permitting timelines extend pre-construction phases for Yellow Sea wind zones.
- Grid interconnection queues:Korea Electric Power Corporation transmission upgrade backlogs delay utility-scale solar and wind synchronization at 345 kV substations.
Strategic Opportunities
- Jeolla-region offshore zones:Untapped South Sea lease blocks offer lower congestion than Gyeonggi coastal areas already saturated with competing maritime claims.
- Renewable hydrogen convergence:SK E&S LNG terminal retrofits enable electrolyzer co-location, linking offshore wind generation to industrial hydrogen offtake.
- Energy storage co-location:MFDS safety standard finalization opens utility-scale battery pairing with photovoltaic arrays for frequency regulation services.
Industry Challenges
- Offshore construction certification:KOSHA occupational codes for jack-up vessel operations create specialist labor bottlenecks, extending crew mobilization timelines.
- Supply chain reconfiguration friction:Turbine localization requirements clash with Chinese component cost advantages, complicating procurement for independent power producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Renewable Energy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Biomass, Hydro End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Offshore Wind, Onshore Wind, Geothermal Installation Type: Utility-Scale, Distributed, Microgrid, Hybrid |
| Companies Covered | SK E&S, Mainstream Renewable Power, Samsung Heavy Industries, Haezoom, Ocean Winds, POSCO E&C, Kumyang Electric Company, SGC Energy, Doosan Enerbility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Renewable Energy Market Evolving Landscape
Technology maturation and procurement model evolution are compressing traditional utility dominance while elevating industrial self-generation and hybrid hydrogen integration as viable alternatives to centralized grid dependence.
Distributed photovoltaic plus storage configurations are decentralizing power architecture across South Korean industrial parks. Mid-sized manufacturers in Gyeonggi and Chungcheong provinces now deploy rooftop arrays with lithium-ion buffering to shave peak demand charges. This shift erodes Korea Electric Power Corporation's historical monopoly over industrial electricity supply.
METI-aligned green hydrogen certification frameworks now condition equipment selection for hybrid installations. Developers must demonstrate renewable origin tracing to qualify for subsidy tiers, forcing electrolyzer vendors to integrate blockchain-verified power purchase agreements. Offshore wind-to-hydrogen projects in South Jeolla Province face the steepest compliance verification burdens.
Corporate buyers now negotiate direct renewable supply contracts outside traditional utility intermediation. Petrochemical complexes in Ulsan and steel producers in Pohang structure long-term fixed-price agreements with independent solar and wind developers. This disintermediation concentrates in manufacturing-heavy provinces where tariff volatility most threatens margin stability.
South Korea Renewable Energy Market Segmentation
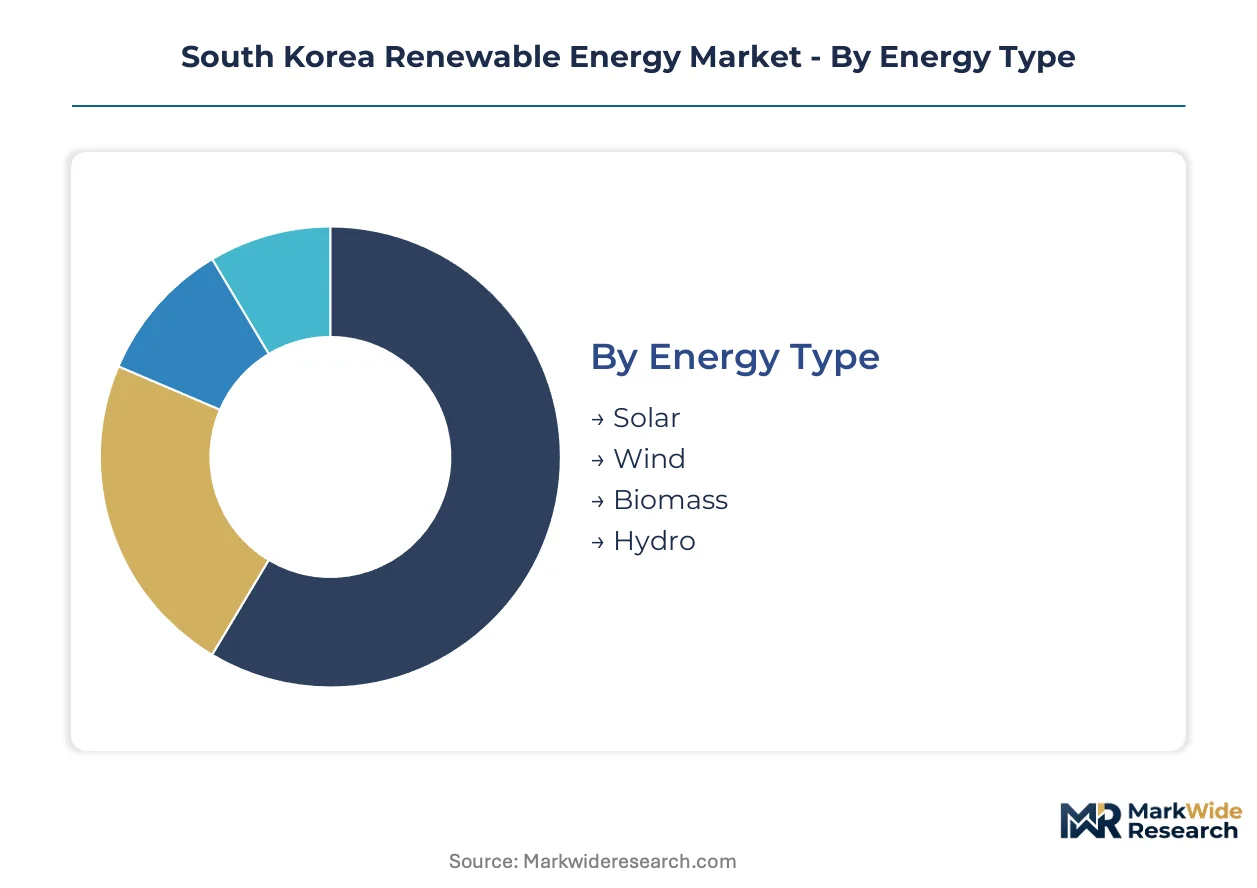
Segmentation reveals how capital allocation diverges across technology maturity curves and customer risk profiles in South Korea's renewable transition. Each dimension exposes distinct procurement patterns, from petrochemical majors hedging tariff volatility to municipal utilities balancing grid stability obligations.
Energy Type:
Standalone generation assets dominate utility procurement, while embedded thermal-coupled systems serve industrial process heat needs.
- Solar:Crystalline silicon photovoltaic arrays convert incident radiation to 60 Hz grid-synchronous power at 22.9 kV distribution voltage. Deployment concentrates in Gyeonggi and Chungcheong provinces where industrial parks seek Korea Electric Power Corporation tariff hedges. Polysilicon supply constraints from domestic refiners harden module cost structures.
- Wind:Horizontal-axis turbines extract kinetic energy from coastal airflows, with fixed-bottom foundations in Yellow Sea shallows and floating platforms for South Sea depths. Ulsan shipyards anchor fabrication demand as seabed leasing accelerates beyond 50-meter depth contours.
- Biomass:Agricultural residue combustion units provide dispatchable baseload for rural municipal utilities.
- Hydro:Run-of-river installations without reservoir impoundment serve mountainous Gangwon Province microgrids.
Volume placements concentrate in Solar; the faster expansion belongs to Wind.
End User:
Cost tier stratification separates price-sensitive residential adopters from industrial buyers prioritizing supply security over unit economics.
- Industrial:Petrochemical complexes and steel producers negotiate long-term fixed-price power purchase agreements independent of utility intermediation. Yeosu and Pohang manufacturing clusters drive corporate procurement volume as margin stability concerns override capital efficiency metrics.
- Commercial:Mid-sized enterprises deploy rooftop photovoltaic with lithium-ion buffering to shave peak demand charges. Gyeonggi Province office buildings and retail complexes lead this segment as electricity tariff volatility threatens operating budgets.
- Residential:Single-family dwellings participate through net-metering arrangements with limited battery penetration.
- Government:Public buildings and military installations anchor procurement through central agency tendering.
Revenue concentration sits with Industrial offtake; Commercial deployments are gaining share fastest.
Technology:
Application context determines technology selection, with grid-scale generation favoring proven platforms and frontier installations accepting performance uncertainty.
- Photovoltaic:Silicon wafer-based panels dominate installed capacity through utility-scale ground-mount and distributed rooftop configurations. MFDS safety standards for energy storage co-location now condition battery pairing approvals.
- Offshore Wind:Floating platform designs enable turbine deployment in South Sea depths exceeding fixed-foundation limits. Samsung Heavy Industries and Geoje shipyards anchor domestic fabrication capability as METI-aligned certification frameworks impose renewable origin tracing requirements.
- Onshore Wind:Land-based turbines face siting constraints in densely populated coastal provinces.
- Geothermal:Binary cycle plants extract low-grade heat for district heating networks in volcanic Jeju Island.
Deployment scale favors Photovoltaic; steepest expansion trajectory belongs to Offshore Wind.
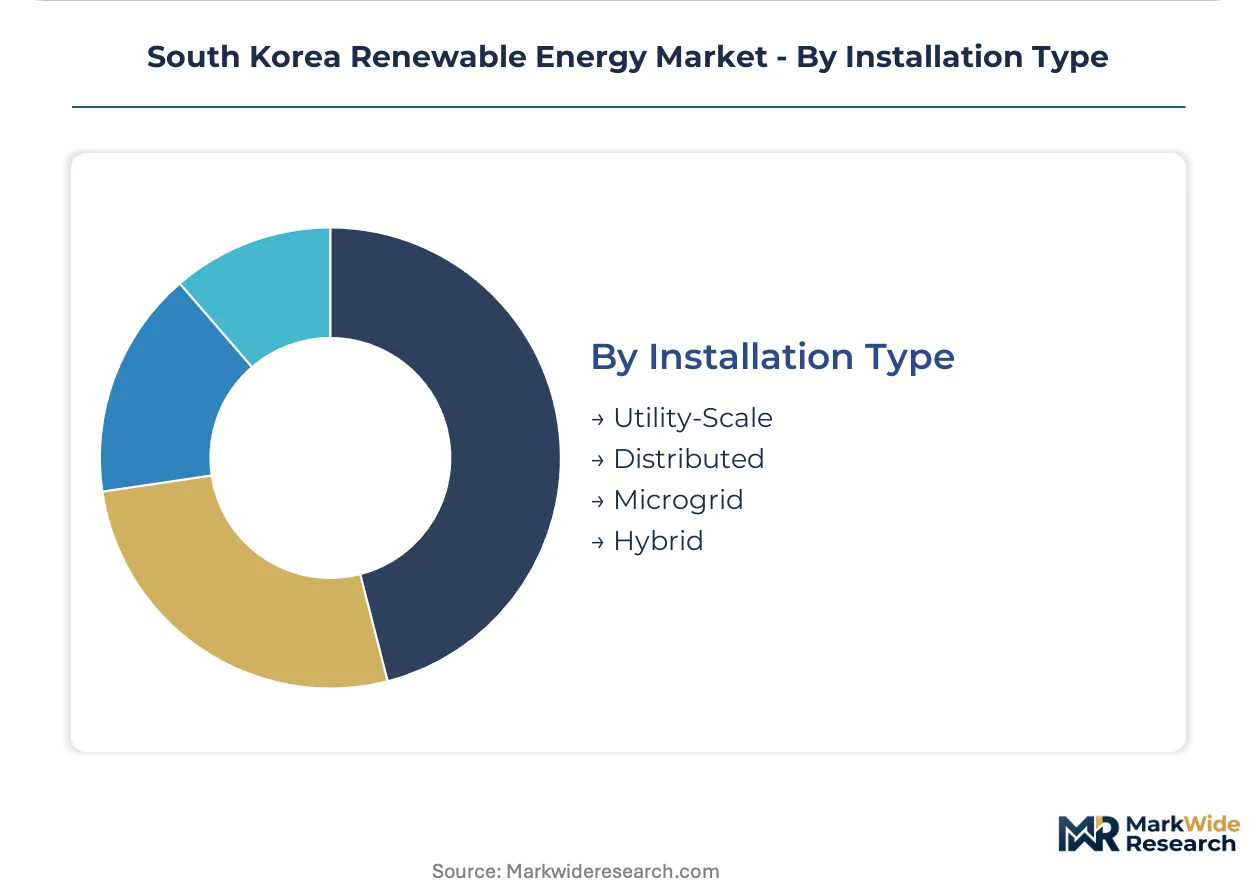
Installation Type:
Customer type and grid access economics drive configuration selection, with centralized assets serving wholesale markets and distributed alternatives targeting behind-the-meter savings.
- Utility-Scale:Centralized photovoltaic and wind complexes interconnect at 345 kV transmission voltage for Korea Electric Power Corporation grid synchronization. Southern and western coastal zones concentrate development as Seoul's Green New Deal redirects capital from LNG baseload.
- Distributed:Decentralized rooftop and small ground-mount systems serve single facilities or campuses without transmission infrastructure dependence. Industrial parks in Gyeonggi and Chungcheong provinces lead adoption as tariff hedging motivation intensifies.
- Microgrid:Islanded configurations with battery storage serve remote coastal communities and military installations.
- Hybrid:Co-located renewable generation with electrolyzer or storage assets enables renewable hydrogen production and frequency regulation services.
Capital deployment concentrates in Utility-Scale; Hybrid configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saemangeum Reclaimed Land Zone anchors concentrated solar and wind development through accelerated permitting and grid infrastructure pre-positioning. This special economic district redirects industrial capital from Seoul toward southwestern coastal provinces.
Seoul Capital Area
Corporate headquarters and financial intermediaries cluster in Gangnam and Yeouido districts, directing power purchase agreement capital toward southern generation assets. Seoul Metropolitan Government enforces building-integrated photovoltaic mandates for structures exceeding defined floor-area thresholds. Data centers in Pangyo Techno Valley drive behind-the-meter solar deployment to hedge Korea Electric Power Corporation commercial tariffs.
Busan-Ulsan
Petrochemical complexes and shipbuilding yards generate concentrated industrial electricity demand exceeding 10 TWh annually. Ulsan Metropolitan City operates renewable portfolio obligations for municipal facilities. Hyundai Heavy Industries and Samsung Heavy Industries anchor floating offshore wind platform fabrication at Geoje shipyards.
Daegu-Gyeongbuk
Textile and electronics manufacturing facilities seek tariff stability through distributed photovoltaic installations. Daegu Metropolitan Government administers feed-in tariff remnants for small-scale solar. Wafer processing plants in Gumi Industrial Complex negotiate direct renewable supply contracts independent of utility intermediation.
Daejeon-Sejong
National research institutes and regulatory agencies concentrate policy formulation and technology certification functions. Korea Institute of Energy Research validates floating wind platform designs for South Sea deployment. Sejong City government buildings anchor procurement for centralized agency tendering.
Gwangju-Honam
Agricultural residue availability and coastal wind resource density converge in South Jeolla Province. Gwangju Metropolitan City targets carbon neutrality through municipal renewable generation. Yeosu National Industrial Complex petrochemical majors structure long-term fixed-price agreements with independent wind developers.
South Korea Renewable Energy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with utility-scale developers commanding procurement decisions while equipment fabricators compete on localization credentials. The vendor base concentrates around three strategic archetypes: integrated energy conglomerates leveraging legacy infrastructure, heavy industrial specialists repurposing shipyard and steel capabilities, and independent power producers securing seabed leases through early-mover positioning. Competitive moves center on turbine supply chain localization commitments and floating platform fabrication capacity expansion.
Among Korea-based integrated players, SK E&S exemplifies the LNG-to-hydrogen transition archetype through terminal retrofit strategies. Samsung Heavy Industries occupies a narrow but critical manufacturing niche in floating offshore wind platform fabrication. POSCO E&C represents steel-intensive construction expertise extension into wind turbine foundation and substation contracting.
| Leading Market Players |
|---|
| SK E&S |
| Mainstream Renewable Power |
| Samsung Heavy Industries |
| Haezoom |
| Ocean Winds |
| POSCO E&C |
| Kumyang Electric Company |
| SGC Energy |
| Doosan Enerbility |
| Others |
Value Network & Pricing Analysis
Industrial power purchasers in Ulsan and Yeosu petrochemical clusters anchor South Korea's renewable energy pricing structure through long-term corporate power purchase agreements that trade Korea Electric Power Corporation tariff volatility for contractually fixed rates over multi-year horizons.
Pricing Analysis
Lead-time premiums dominate equipment procurement as offshore wind developers pay 15-25% markups for turbine components with sub-12-month delivery windows versus standard 18-24 month schedules. Three-tier pricing structure across premium, standard, and economy levels separates certified domestic-content-compliant equipment from imported alternatives and refurbished secondary-market assets. Cost compression in photovoltaic modules is intensifying because polysilicon supply constraints from domestic OCI and Hanwha Solutions refiners limit margin flexibility for installers. Industrial offtakers show lowest price sensitivity, prioritizing supply security and renewable origin certification over unit economics, while distributed commercial adopters in Gyeonggi Province exhibit highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Reverse-logistics flows for end-of-life wind turbine blades and photovoltaic panels remain underdeveloped, with most decommissioned equipment landfilled rather than recycled or remanufactured. Manufacturing concentration centers on South Korea, China, and Vietnam for crystalline silicon wafers, nacelle assembly, and floating platform substructures. Raw material dependencies draw from Australian lithium, Indonesian nickel, and Chinese rare earth processing for battery storage co-location. Single-source vulnerability in polysilicon refining creates supply chain risk as domestic output fails to match module demand growth. Distribution runs through Korea Electric Power Corporation's transmission network for utility-scale projects, while distributed generation bypasses central grid infrastructure entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
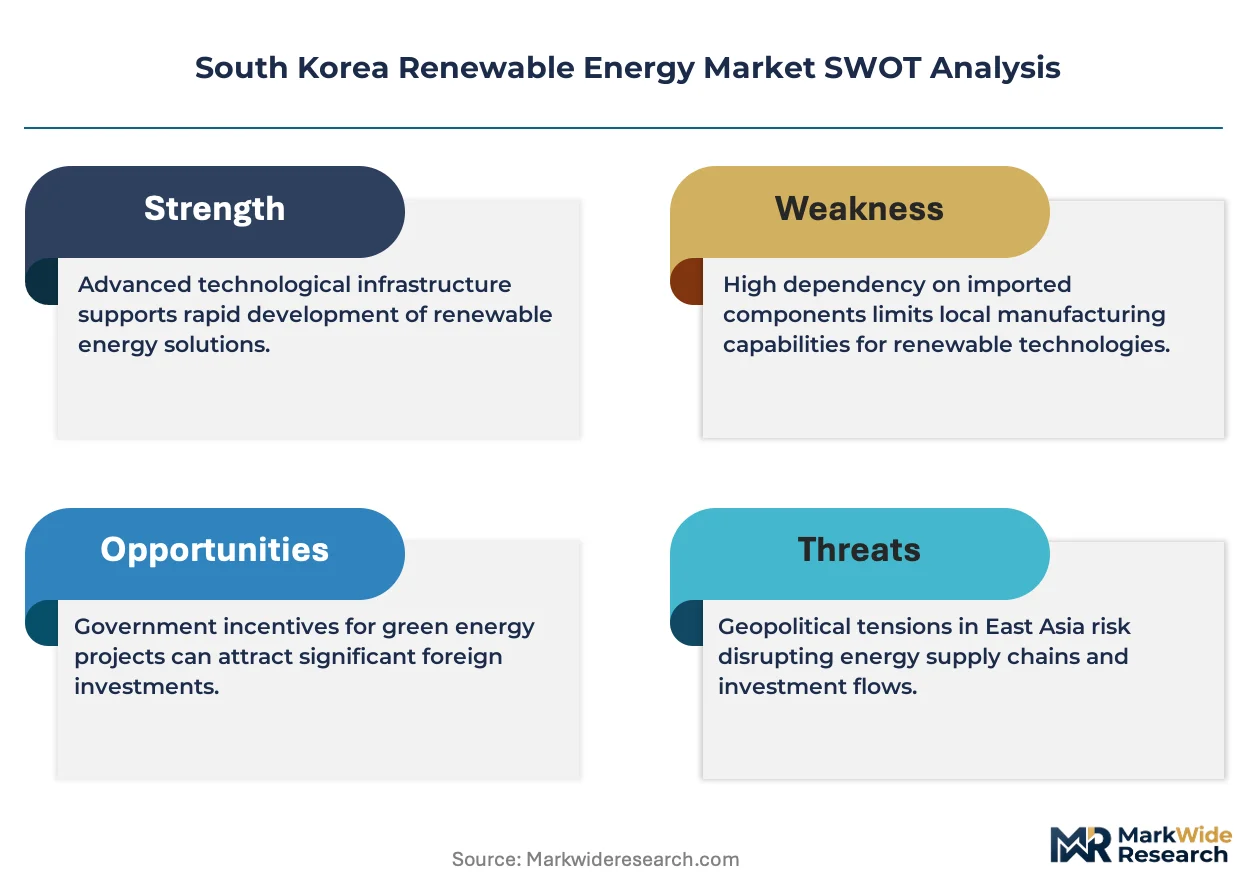
South Korea's renewable energy market represents a consolidation play as seabed leasing bottlenecks and localization requirements force capital-constrained independent power producers toward acquisition or exit.
For Market Incumbents: Deepen backward integration into floating platform fabrication at Geoje and Mokpo shipyards to capture margin pools currently flowing to Samsung Heavy Industries and POSCO E&C. Secure early-mover positioning in Jeolla-region South Sea lease blocks before Korea Hydrographic and Oceanographic Agency permitting timelines compress competitive windows. Defensive moves must address emerging Chinese turbine OEM price competition through domestic-content certification advantages and SK E&S hydrogen convergence partnerships. For New Entrants and Emerging Players: Begin with distributed photovoltaic plus storage configurations in Chungcheong Province industrial parks, where Korea Electric Power Corporation tariff volatility drives immediate payback demand without utility-scale interconnection queue delays. Target mid-sized manufacturers with 500 kW-2 MW rooftop arrays and lithium-ion buffering as the most penetrable segment lacking incumbent saturation. Go-to-market angle should emphasize blockchain-verified renewable origin tracing for METI-aligned green hydrogen certification eligibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent power producers with secured seabed leases but stalled financing in Gwangju-Honam coastal zones, where Korea Hydrographic and Oceanographic Agency permitting delays have frozen project timelines. Long-term viability over the next decade hinges on successful navigation of turbine supply chain localization mandates against Chinese component cost advantages. Monitor Korea Electric Power Corporation transmission upgrade commitment announcements as the critical inflection signal for utility-scale project bankability restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Securement | Early positioning in Jeolla-region blocks avoids Gyeonggi coastal congestion and maritime claim conflicts. |
| Floating Platform Fabrication Capacity | Geoje and Mokpo shipyard expansion captures deeper-water South Sea deployment opportunities beyond 50-meter contours. |
| Domestic Content Certification Investment | MFDS and KOSHA compliance pathways differentiate procurement bids for Korea Hydrographic and Oceanographic Agency lease awards. |
| Renewable Hydrogen Convergence | SK E&S LNG terminal retrofits link offshore wind generation to industrial hydrogen offtake in Yeosu petrochemical complexes. |
| Energy Storage Co-location | Utility-scale battery pairing with photovoltaic arrays opens frequency regulation revenue streams under finalized MFDS safety standards. |
Research Methodology
Multi-period observation of seabed lease issuance rates, Korea Electric Power Corporation interconnection queue depths, and corporate power purchase agreement announcement volumes anchored the trend analysis, supplemented by interviews with utility planning officers at Korea Electric Power Corporation, independent power producer project developers, floating platform EPC contractors, and grid operators at the Korea Power Exchange. Secondary validation drew from Ministry of Trade, Industry and Energy renewable portfolio standard filings, Korea Hydrographic and Oceanographic Agency permitting databases, Korea Institute of Energy Research technology assessments, and customs data on photovoltaic module imports. Bottom-up project pipeline aggregation and top-down policy target reconciliation provided cross-verification.
Input-output matrix framing connected generation capacity additions to equipment procurement flows across the projection horizon, modeling solar, wind, biomass, and hydro segments alongside installation type stratification between utility-scale, distributed, microgrid, and hybrid configurations. CAGRs were derived from segmented capacity buildout trajectories weighted by capital intensity differentials and technology-specific learning curve effects. Forecast inputs incorporated polysilicon supply elasticity assumptions and floating offshore wind platform cost reduction curves.
Regulatory enforcement variance, Korea Hydrographic and Oceanographic Agency permitting timeline slippage, and Korea Electric Power Corporation transmission upgrade commitment delays are the dominant revision risks that could compress or extend the analysis window's growth trajectory. Forecasts reflect documented assumptions about seabed lease round timing and localization requirement phase-in schedules. Practitioners should monitor Korea Electric Power Corporation capital expenditure disclosures and Ministry of Trade, Industry and Energy renewable portfolio standard tightening announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Wave Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Solar Watch Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market