
 South America LNG Bunkering Market | 2026-2036
South America LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
South America LNG Bunkering Market Analytics
Aftermarket service revenue from vessel conversion and maintenance is narrowing as shipowners shift toward newbuild LNG-fuelled fleets. Petrobras leverages its integrated downstream infrastructure to dominate coastal bunkering along Brazil's southeastern corridor. Shell competes through specialized cryogenic logistics and strategic terminal partnerships. Wartsila anchors the technology layer with dual-fuel engine systems that extend manufacturer influence into fuel specification.
South America LNG bunkering denotes the supply of liquefied natural gas as marine fuel to vessels through cryogenic transfer systems operating at approximately minus 162 degrees Celsius, enabling compliance with sulfur oxide emission limits set by the International Maritime Organization. The service type dimension shows ship-to-ship transfer capturing the dominant margin pool due to minimal port congestion and faster turnaround times for deep-sea carriers. Terminal-to-ship installations retain structural importance at hub ports with permanent cryogenic infrastructure, while truck-to-ship delivery occupies a niche role for smaller harbour craft and tugboats lacking alongside berth access.
ANVISA regulates occupational health standards for cryogenic handling personnel in Brazilian port zones, while Brazil's National Petroleum Agency shapes fuel quality specifications and licensing requirements for LNG distribution. The International Maritime Organization's Annex VI framework is forcing fleet operators to evaluate bunkering infrastructure availability before committing to LNG propulsion contracts. Stakeholders must monitor regulatory harmonization between Brazilian federal standards and evolving Chilean maritime environmental codes to anticipate cross-border operational complexity.
Market Dynamics
Ship-to-ship LNG transfer systems are compressing turnaround times at Brazilian deep-water terminals, forcing port authorities to reconfigure alongside berth scheduling and triggering cascading investments in cryogenic barge fleets across the southeastern corridor.
Growth Catalysts
- IMO Annex VI sulfur caps:Fleet operators now face binding emission limits in coastal waters, compelling retrofits and newbuild commitments that anchor LNG bunkering demand at Santos and Rio de Janeiro.
- Brazilian port authority mandates:Terminal operators must meet cleaner marine fuel standards, embedding LNG infrastructure into long-term concession agreements and capital planning cycles.
- Dual-fuel engine penetration:Container lines are specifying LNG-capable propulsion for regional feeder vessels, creating captive demand for cryogenic fueling networks.
Market Restraints
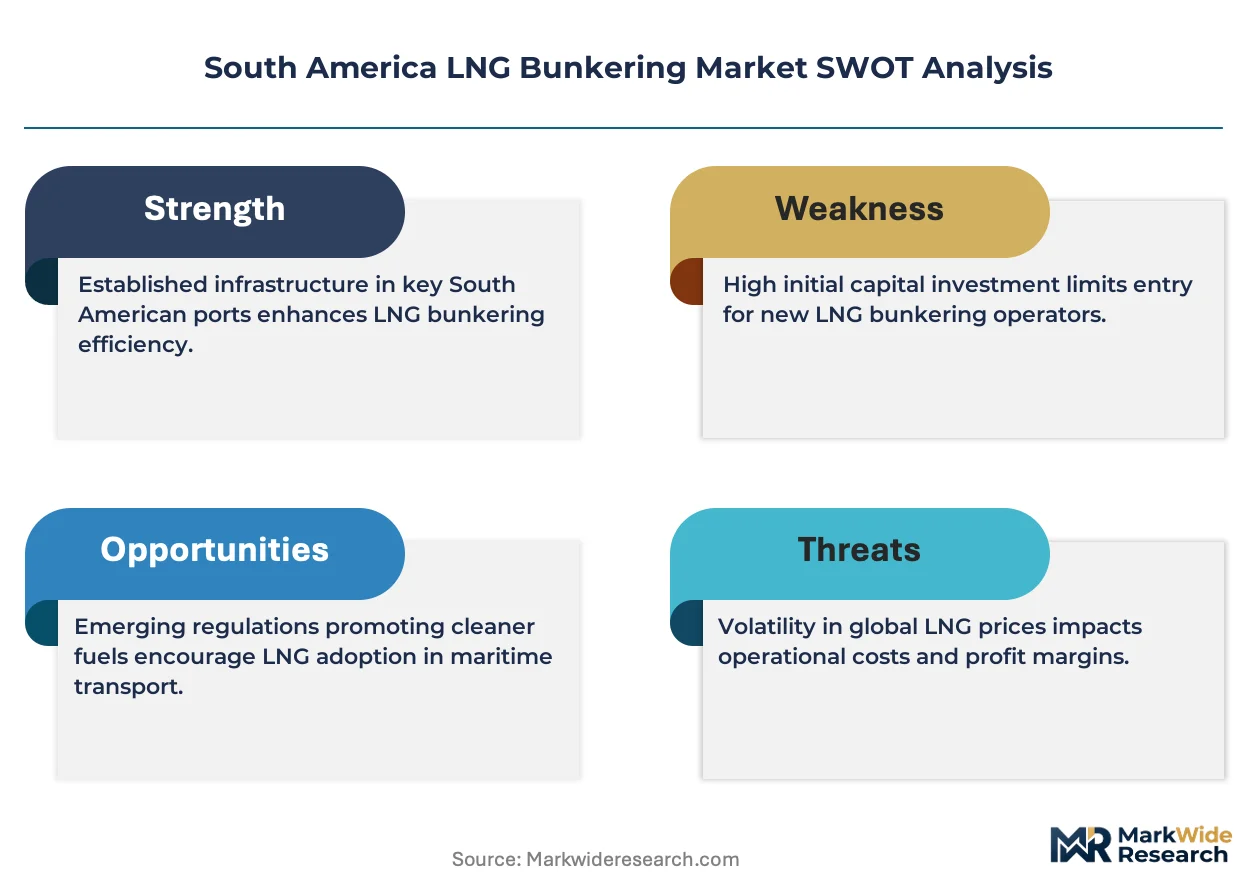
- Cryogenic infrastructure capex concentration:Brazil's National Petroleum Agency licensing requirements impose multi-year approval timelines that deter independent terminal developers from competing with integrated incumbents.
- Liquefaction supply bottlenecks:Domestic LNG production constraints force reliance on imported cargoes, exposing bunkering margins to Atlantic basin price volatility and currency fluctuation.
- Methane slip technical limitations:Current dual-fuel engine designs emit unburned methane during low-load operations, complicating compliance with evolving greenhouse gas accounting frameworks.
Strategic Opportunities
- Chilean maritime environmental code alignment:Regulatory harmonization discussions between Santiago and Brasília could unlock cross-border vessel routing that pools LNG demand across the southern cone.
- Tugboat and harbor craft electrification gaps:Smaller vessels lacking alongside berth access represent underserved demand for truck-to-ship delivery systems at secondary ports.
- Digital bunkering documentation:Blockchain-based fuel provenance tracking is emerging as a procurement differentiator for container lines seeking Scope 3 emissions verification.
Industry Challenges
- Cryogenic handling certification gaps:ANVISA occupational health standards require specialized training pipelines that Brazilian technical institutes have not scaled to match fleet expansion timelines.
- Interoperability between legacy fuel systems:Ports with existing heavy fuel oil infrastructure face complex retrofit sequencing to accommodate cryogenic storage without disrupting conventional bunkering revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America LNG Bunkering Market |
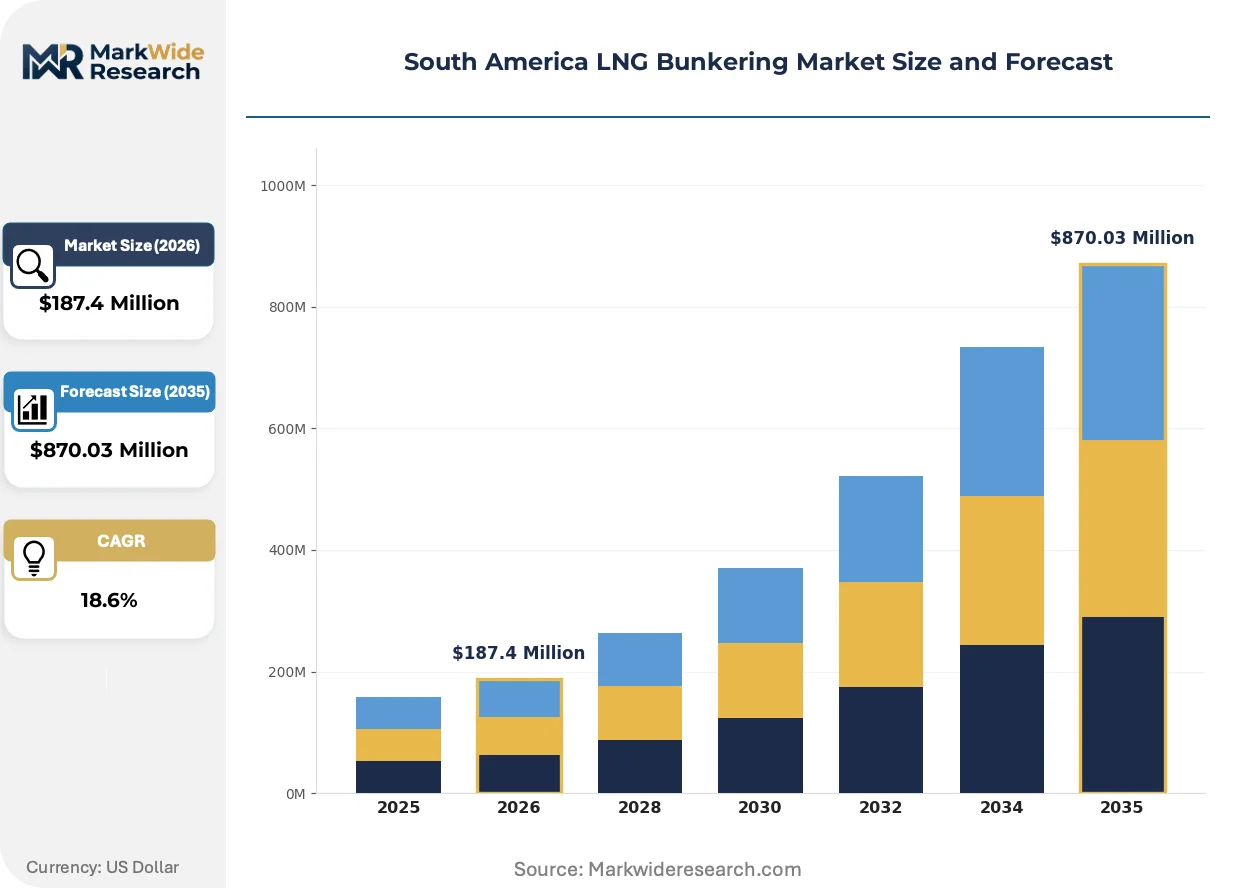
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ship-to-Ship, Terminal-to-Ship, Truck-to-Ship, Barge-to-Ship End User: Shipping Companies, Offshore Vessels, Ferries, Tugboats Installation Type: Permanent, Mobile, Semi-Permanent, Floating Distribution Channel: Direct Sales, Partnerships, Online Platforms, B2B Platforms |
| Companies Covered | Petrobras, Shell, ExxonMobil, Golar LNG, TotalEnergies, Wartsila, AES Corp, Engie SA, Avenir LNG Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America LNG Bunkering Market Evolving Landscape
Automation and digital coordination tools are compressing the operational window for LNG transfers, reducing human exposure to cryogenic hazards while tightening the synchronization between vessel arrival and fuel delivery scheduling.
Modular barge-mounted regasification units are rendering obsolete fixed shoreside infrastructure for mid-size container vessels. Regional carriers operating between Santos and Buenos Aires are adopting these floating systems to avoid permanent terminal commitments. The flexibility is compressing capital recovery periods and enabling port-agnostic fueling strategies that bypass congested hub queues.
Brazil's National Petroleum Agency is tightening fuel quality specifications for marine LNG, mandating stricter methane purity thresholds and traceability documentation. Terminal operators must now install continuous compositional monitoring equipment to maintain distribution licenses. Deep-sea container lines are responding by pre-qualifying suppliers against these specifications before entering long-term charter agreements.
Container shipping procurement departments are unbundling fuel sourcing from vessel charter contracts, creating spot-market liquidity for LNG bunkering that did not exist under traditional bundled arrangements. Third-party fuel traders are capturing margin pools previously retained by integrated carriers. The disintermediation is most visible among Asia-South America route operators repositioning vessels through Brazilian hub ports.
South America LNG Bunkering Market Segmentation
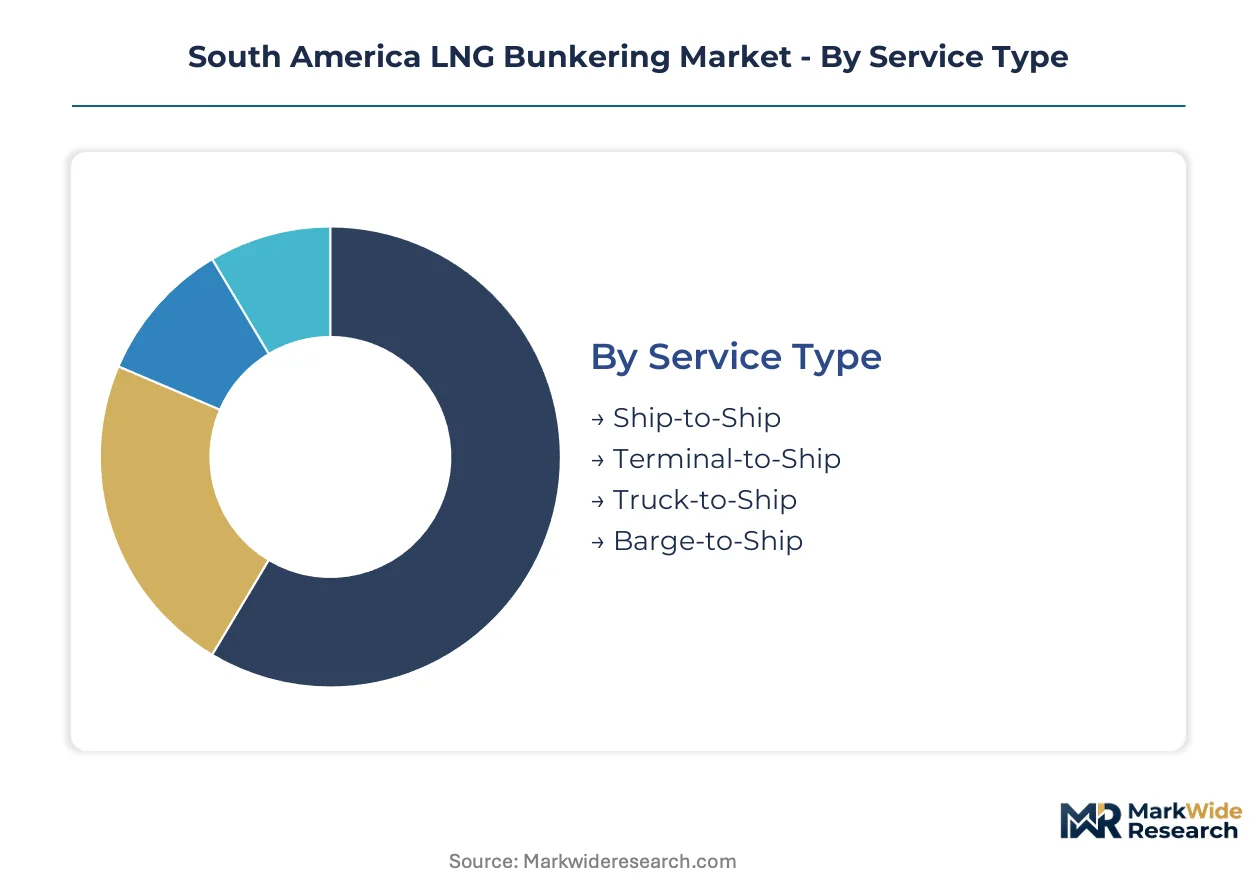
LNG bunkering infrastructure in South America fragments across transfer modalities, vessel classes, and deployment architectures that each impose distinct capital requirements and regulatory burdens. Understanding these segment boundaries clarifies where integrated energy majors can defend margin pools versus where specialized operators gain entry.
Service Type:
The use-case spectrum spans high-volume deep-sea transfers to flexible small-vessel deliveries, with each modality matching specific port infrastructure constraints and turnaround time pressures.
- Ship-to-Ship:Cryogenic transfer between anchored LNG carriers and fueled vessels occurs at minus 162 degrees Celsius through specialized manifold connections. Deep-sea container lines operating Santos-Rio de Janeiro routes specify this method to minimize alongside berth congestion and compress port stays. Brazilian port authority regulations now embed STS capability requirements into long-term terminal concessions.
- Terminal-to-Ship:Fixed shoreside infrastructure delivers LNG through permanent cryogenic loading arms at hub ports with dedicated storage tanks. Petrobras leverages its integrated southeastern corridor terminals to dominate this segment, though ANVISA occupational health standards impose multi-year personnel certification timelines that constrain expansion velocity.
- Truck-to-Ship:Road-mobile cryogenic tankers serve smaller harbor craft lacking alongside berth access at secondary ports. Tugboat operators in Paranaguá and Itajaí represent concentrated demand for this flexible modality.
- Barge-to-Ship:Floating transfer units enable mid-size vessel fueling without permanent terminal commitments. Regional carriers repositioning between Santos and Buenos Aires increasingly specify barge-mounted systems to bypass congested hub queues.
Established volume favors Terminal-to-Ship; emerging adoption favors Barge-to-Ship.
End User:
Customer archetypes diverge sharply in fuel volume profiles, contract structures, and emissions compliance urgency.
- Shipping Companies:Container lines and bulk operators with LNG-dual-fuel newbuilds anchor regional demand. These procurement departments now unbundle fuel sourcing from vessel charters, creating spot-market liquidity previously retained by integrated carriers.
- Offshore Vessels:Platform supply vessels and drilling support craft operating Brazil's pre-salt fields require consistent coastal bunkering access. Petrobras fleet requirements dominate this segment.
- Ferries:Passenger vessel operators face localized emission restrictions at sensitive coastal terminals. Chilean maritime environmental code alignment discussions could expand cross-border ferry route LNG adoption.
- Tugboats:Harbor craft with constrained berth access and modest fuel volumes represent underserved demand for truck-to-ship delivery systems.
Contract concentration clusters with Shipping Companies; regulatory tailwinds strengthen Ferries.
Installation Type:
Capital deployment strategies range from permanent infrastructure commitments to rapidly deployable floating assets.
- Permanent:Fixed cryogenic storage tanks and loading arms at major terminals require decade-plus capital recovery horizons. Brazil's National Petroleum Agency licensing requirements favor integrated incumbents with balance sheet capacity.
- Mobile:Trailer-mounted regasification and transfer equipment enables rapid repositioning across secondary ports. Smaller independent operators exploit this lower-entry structure.
- Semi-Permanent:Modular systems with extended deployment timelines at single locations balance flexibility against operational efficiency.
- Floating:Barge-mounted units render obsolete fixed shoreside infrastructure for mid-size vessels, compressing capital recovery periods and enabling port-agnostic fueling strategies.
Margin durability attaches to Permanent; deployment velocity favors Floating.
Distribution Channel:
Go-to-market architectures determine customer capture economics and working capital intensity.
- Direct Sales:Integrated energy majors negotiate long-term offtake agreements with container lines, capturing volume commitments and specification compliance responsibilities.
- Partnerships:Terminal operators ally with cryogenic logistics specialists to combine infrastructure access with specialized handling expertise.
- Online Platforms:Digital procurement interfaces for spot-market bunkering remain nascent but emerging for third-party fuel traders.
- B2B Platforms:Industry consortium marketplaces pool smaller vessel demand to achieve volume pricing and supplier pre-qualification.
Revenue concentration flows through Direct Sales; liquidity formation favors B2B Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South American bunkering corridors. Brazilian deep-sea container lines absorb premium LNG pricing to secure IMO compliance, while Argentine and Chilean coastal operators remain highly elastic, delaying conversion until cost parity with conventional marine fuels tightens.
Brazil
Container shipping lines operating Santos-Rio de Janeiro routes anchor regional LNG demand with dual-fuel newbuild commitments. ANVISA occupational health standards and National Petroleum Agency licensing requirements embed cryogenic infrastructure into long-term terminal concessions. The southeastern corridor concentrates bunkering activity, with Petrobras leveraging integrated downstream assets to dominate coastal supply.
Chile
Maritime environmental code alignment discussions with Brazil are unlocking cross-border ferry route potential and pooled southern cone demand. The country's national petroleum regulator shapes fuel quality specifications for coastal vessels. Valparaíso and San Antonio port clusters are evaluating truck-to-ship systems for harbor craft lacking alongside berth access.
Argentina
Buenos Aires repositioning traffic from regional carriers is adopting barge-mounted regasification to bypass congested Brazilian hub queues. The national energy secretariat oversees LNG import terminal licensing that constrains bunkering infrastructure deployment. The Río de la Plata waterway is emerging as a secondary demand node for floating transfer systems.
Colombia
Cartagena and Barranquilla port authorities face delayed infrastructure commitments due to capital recovery uncertainty on Atlantic basin LNG price volatility. The national hydrocarbons agency regulates marine fuel quality standards. Caribbean coastal shipping remains tethered to conventional bunkering pending clearer regulatory enforcement timelines.
South America LNG Bunkering Market Competitive Landscape
Integrated energy majors and specialized cryogenic logistics providers split the market along infrastructure control versus operational flexibility lines. Market structure tilts toward consolidated incumbent dominance at fixed terminals, with fragmented entry points emerging in mobile and floating deployment modes. Three archetypes occupy distinct competitive terrain: state-backed integrated suppliers with captive downstream assets, global energy majors with specialized LNG trading desks, and technology-anchored equipment licensors extending into fuel specification. Dominant competitive moves center on strategic terminal partnerships for market access and modular barge fleet expansion to capture port-agnostic demand.
Within the integrated supplier tier, Petrobras anchors Brazilian southeastern corridor dominance through downstream infrastructure control. Shell and TotalEnergies occupy positions among global energy majors competing via cryogenic logistics specialization and strategic terminal alliances. Wartsila sits within the technology-licensor archetype, extending manufacturer influence into fuel specification through dual-fuel engine system deployment.
| Leading Market Players |
|---|
| Petrobras |
| Shell |
| ExxonMobil |
| Golar LNG |
| TotalEnergies |
| Wartsila |
| AES Corp |
| Engie SA |
| Avenir LNG Ltd |
| Others |
Value Network & Pricing Analysis
Santos port cluster capacity expansions concentrate LNG bunkering supply along Brazil's southeastern corridor, granting Petrobras substantial leverage over regional pricing benchmarks and forcing smaller operators to absorb Atlantic basin cargo volatility.
Pricing Analysis
Aftermarket service contracts from vessel conversion and cryogenic maintenance anchor lifetime value capture for integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by methane purity certification and ANVISA handling compliance. Cost compression in standard-tier delivery is intensifying because third-party fuel traders are disintermediating traditional bundled charter arrangements. Container shipping lines demonstrate lowest price sensitivity due to IMO Annex VI compliance mandates, while Argentine coastal operators remain highly elastic pending cost parity with conventional marine fuels.
Supply Chain Analysis
Specialized cryogenic barge fabricators in South Korea, Singapore, and Norway hold concentrated contract-manufacturing capacity for modular regasification units. LNG supply draws from Trinidad and Tobago liquefaction, US Gulf Coast export terminals, and Nigerian Atlantic cargoes. Single-source vulnerability runs through Brazilian import terminal congestion at Santos and Rio de Janeiro. Distribution runs through direct long-term offtake agreements between integrated energy majors and container lines, with spot-market liquidity emerging via third-party fuel traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America LNG bunkering fragments across transfer modalities and deployment architectures, creating niches as procurement departments unbundle fuel sourcing from vessel charter contracts and spot-market liquidity attracts specialized entrants.
For Market Incumbents: Insulate terminal-to-ship dominance at Santos and Rio de Janeiro through accelerated ANVISA certification pipelines and captive cryogenic storage capacity. Backward integration into barge-mounted regasification fleets neutralizes modular competitors bypassing fixed infrastructure. Prioritize blockchain-based fuel provenance systems to defend against third-party fuel traders capturing Scope 3 verification premiums. For New Entrants and Emerging Players: Secondary Brazilian ports including Paranaguá and Itajaí offer underpenetrated demand for truck-to-ship delivery systems serving tugboat operators lacking alongside berth access. Chilean maritime environmental code alignment discussions unlock cross-border ferry route potential with lower competitive density than Brazilian hubs. Pursue B2B platform partnerships to aggregate smaller vessel demand and achieve volume pricing against integrated majors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because IMO Annex VI sulfur caps embed LNG bunkering demand regardless of commodity price cycles. Target acquisition archetypes include specialized cryogenic logistics providers with ANVISA licensing progress and modular barge fleet operators serving port-agnostic repositioning routes. Monitor Chilean-Brazilian regulatory harmonization ratification as the critical inflection signal for southern cone demand pooling.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Barge Fleet Expansion | Modular regasification units bypass fixed terminal congestion and compress capital recovery timelines. |
| ANVISA Certification Pipeline Investment | Occupational health compliance accelerates personnel deployment velocity against constrained technical institute output. |
| Blockchain Fuel Provenance Integration | Digital documentation satisfies container line Scope 3 emissions verification requirements. |
| Cross-Border Regulatory Harmonization | Chilean-Brazilian code alignment pools southern cone demand and enables pooled procurement leverage. |
| Truck-to-Ship Distribution Network | Road-mobile cryogenic tankers capture underserved tugboat demand at secondary ports lacking alongside infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from LNG procurement executives at container shipping lines, terminal operations managers at Santos and Rio de Janeiro, cryogenic logistics specialists, and ANVISA compliance officers, and refined through secondary validation against Brazil National Petroleum Agency licensing records, IMO Annex VI implementation guidelines, SEC filings from listed energy majors, and customs data tracking Atlantic basin LNG cargo flows. Bottom-up volume estimates from individual terminal throughput combined with top-down market sizing from regional fuel consumption patterns.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation by transfer modality, end user archetypes from deep-sea container lines to harbor craft, installation type capital deployment strategies, and distribution channel structures. CAGRs were derived from regression analysis against fleet newbuild order books and regulatory compliance timelines. Forecast inputs included dual-fuel engine penetration rates and methane slip technical limitations affecting greenhouse gas accounting frameworks.
Practitioners should monitor Atlantic basin LNG price volatility, Brazilian real currency fluctuation, and Chilean maritime environmental code ratification progress for early signals requiring forecast revision. Quarterly review of ANVISA certification pipeline throughput and container line unbundled procurement contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Shale Shakers Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Tight Gas Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Vietnam Oil and Gas Midstream Market