
 Water As a Fuel Market | 2026-2036
Water As a Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Water As a Fuel Market Analytics
The EU Green Deal's renewable hydrogen targets is repositioning industrial demand toward water-derived fuel pathways. Plug Power Inc. anchors North American material handling and stationary power deployments through captive hydrogen production. Linde plc leverages its industrial gas infrastructure to control distribution economics across European offtake agreements. FuelCell Energy Inc. specializes in carbonate fuel cell platforms for utility-scale clean power generation.
Water as a fuel denotes hydrogen produced via water splitting—primarily through electrolysis operating at 60-80% system efficiency—then combusted or converted electrochemically to release energy without carbon emissions. Electrolyzers dominate capital deployment as the foundational conversion layer, while fuel cells capture downstream value through electrochemical power generation. Photoelectrochemical pathways remain pre-commercial but attract R&D intensity for their potential to bypass grid electricity inputs entirely.
The EPA regulates hydrogen production emissions thresholds under the Clean Air Act, while the EU AI Act and CE marking frameworks shape equipment certification for automated electrolyzer controls. California's Low Carbon Fuel Standard and Germany's national hydrogen strategy create divergent but complementary demand pull for water-derived fuels. Stakeholders must monitor regulatory parity between production subsidies and end-use carbon accounting methodologies.
Market Dynamics
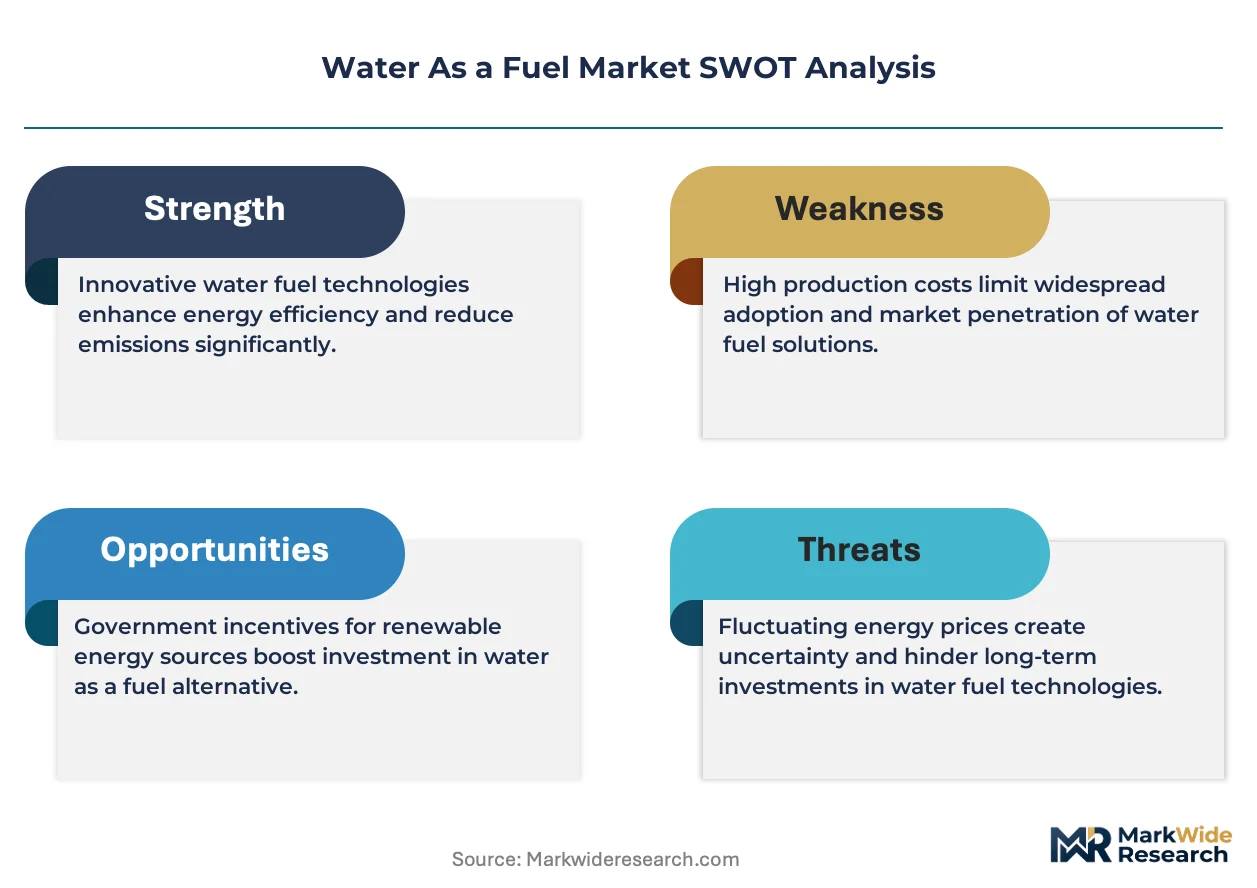
Electrolyzer capital deployment is concentrating around captive industrial hydrogen production, as steelmakers and chemical producers bypass merchant hydrogen markets to secure decarbonization pathways under tightening emissions accounting rules.
Growth Catalysts
- California's Low Carbon Fuel Standard:Fleet operators in the state are procuring hydrogen fuel cell buses at accelerating rates, creating guaranteed offtake for water-derived fuel producers.
- Ruhr industrial cluster concentration:Germany's steel decarbonization trials are aggregating demand for green hydrogen, pulling electrolyzer deployment toward captive production models.
- Photoelectrochemical R&D intensity:Laboratory advances in direct solar-to-hydrogen conversion are attracting venture capital, positioning the technology as a grid-bypass pathway for remote fuel production.
Market Restraints
- Grid electricity cost volatility:Electrolyzer operators face margin compression where renewable power purchase agreements expire into spot market exposure.
- Proton exchange membrane supply concentration:Critical membrane materials for PEM electrolyzers source from a narrow supplier base concentrated in East Asian manufacturing corridors.
- Storage and transport infrastructure gaps:Hydrogen embrittlement in pipeline steel and cryogenic liquefaction energy penalties limit distribution economics outside industrial clusters.
Strategic Opportunities
- EU Green Deal renewable hydrogen mandates:Industrial offtake obligations are repositioning toward water-derived pathways, opening contract structures for electrolyzer operators.
- Maritime fuel cell propulsion:Port authorities in Rotterdam and Hamburg are piloting hydrogen bunkering, creating demand for localized water-splitting production.
- Automated electrolyzer controls:Convergence of industrial IoT and predictive maintenance algorithms is enabling unmanned production facilities, reducing opex in remote deployments.
Industry Challenges
- Electrolyzer stack engineering talent scarcity:Specialized membrane electrode assembly expertise concentrates in a handful of research institutions and incumbent industrial gas firms.
- CE marking timeline compression:Automated control systems for megawatt-scale electrolyzers face extended certification cycles under the EU AI Act and pressure equipment directives.
- Legacy natural gas infrastructure lock-in:Industrial hydrogen consumers face switching costs from reformer-based supply contracts and integrated pipeline networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water As a Fuel Market |
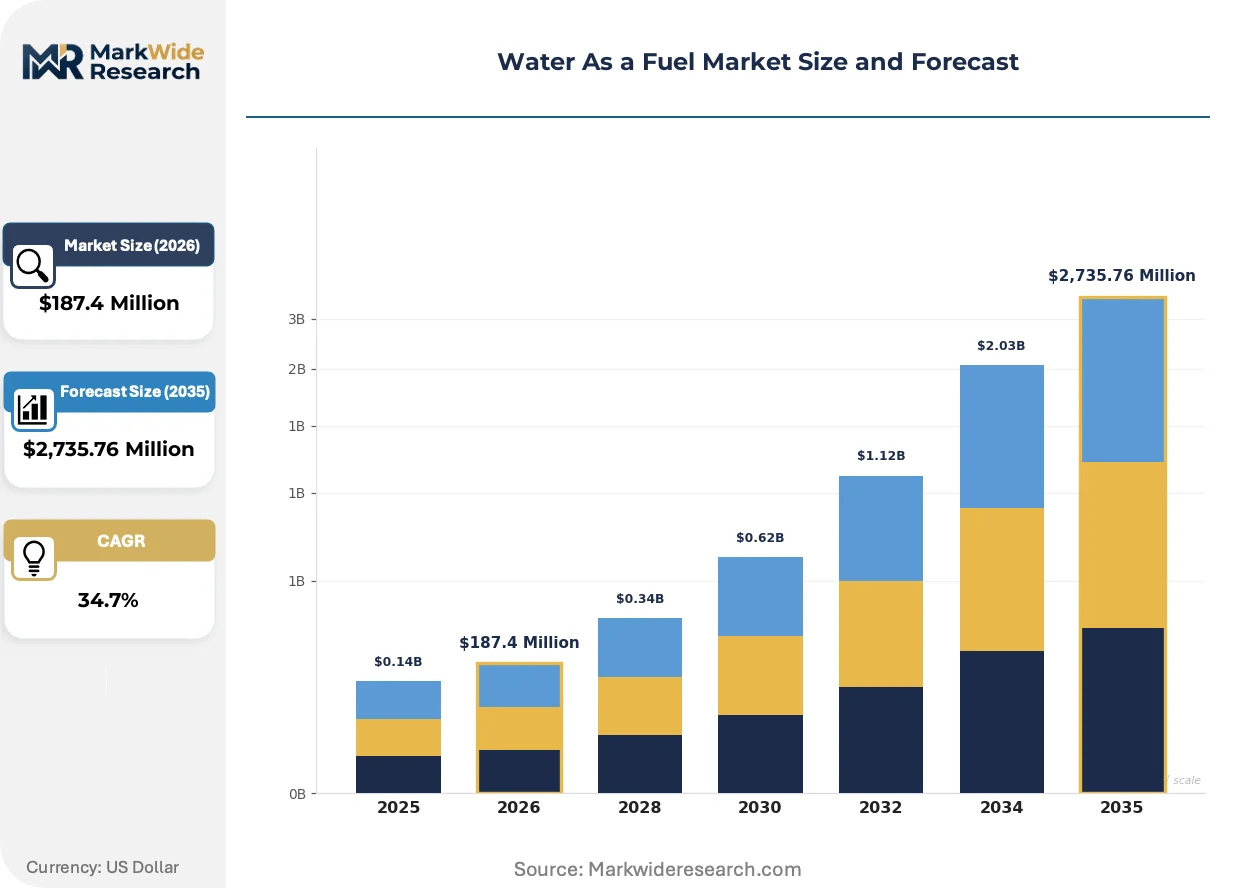
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyzers, Fuel Cells, Hydrogen Generation Units, Storage Systems Technology: Electrolysis, Photoelectrochemical, Thermochemical, Biological Hydrogen Production End User: Transportation, Power Generation, Industrial Applications, Residential Use Applications: Energy Storage, Clean Fuel Production, Cogeneration Systems, Backup Power |
| Companies Covered | ExxonMobil, Air Liquide, Orsted A/S, FuelCell Energy Inc, Plug Power Inc., Linde plc, Iberdrola S.A., China Petroleum & Chemical Corporation, Enel Green Power Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water As a Fuel Market Evolving Landscape
Solid oxide electrolysis is advancing toward commercial scale, rewriting the efficiency frontier for water-derived hydrogen production. This technology shift is compressing the cost gap between gray and green hydrogen, forcing incumbent producers to accelerate capital redeployment.
Solid oxide electrolysis cells operate at elevated temperatures, co-producing hydrogen and usable heat while bypassing the precious metal loadings that constrain PEM economics. Steelmakers in Sweden and the Netherlands are piloting integrated SOE-steel mill configurations, attracted by waste heat recovery and direct reduction compatibility. This architecture is rewriting project finance assumptions, enabling longer debt tenors as efficiency guarantees harden.
The EU AI Act and CE marking frameworks are mandating algorithmic transparency for automated electrolyzer control systems. Equipment manufacturers must now document decision pathways for pressure regulation and membrane protection protocols, extending certification timelines by months. German and Italian engineering firms are responding by segregating safety-critical controls from optimization layers, creating dual-architecture product lines.
Steel and chemical buyers are consolidating procurement around long-term hydrogen purchase agreements with embedded carbon accounting. Merchant hydrogen spot markets are losing liquidity as industrial offtakers demand ten-year contracts with certified renewable electricity linkage. This preference shift is most visible in the Netherlands and Denmark, where port-based electrolyzer projects anchor green hydrogen import-export hubs.
Water As a Fuel Market Segmentation
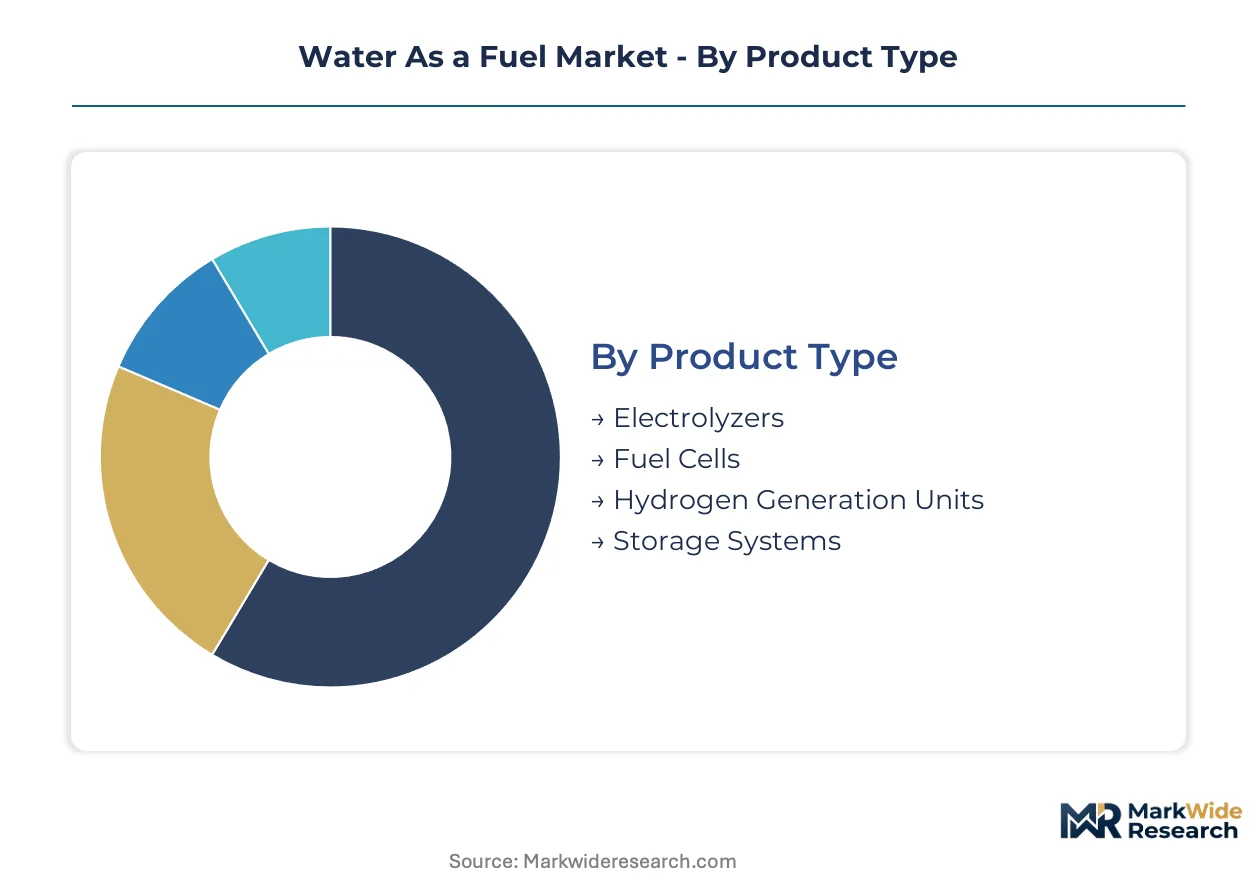
Water-derived hydrogen markets fragment across conversion technology, end-use application, and deployment scale. Procurement patterns diverge sharply between industrial offtakers seeking captive supply and mobility operators demanding distributed fueling infrastructure.
Product Type:
Capital allocation follows the hydrogen value chain from production through end-use conversion.
- Electrolyzers:Alkaline and proton exchange membrane configurations split water using grid or renewable electricity, achieving system efficiencies between 60% and 80%. Germany's Ruhr steel cluster and California transit agencies anchor procurement for industrial and mobility hydrogen supply.
- Fuel Cells:Electrochemical devices convert stored hydrogen into electricity without combustion, with solid oxide and proton exchange membrane variants dominating stationary and mobile applications respectively. Bus fleet operators in California and port authorities in Rotterdam drive demand for heavy-duty propulsion systems.
- Hydrogen Generation Units:Integrated production systems combining electrolysis with compression and purification stages serve remote industrial sites lacking pipeline access.
- Storage Systems:High-pressure gaseous and cryogenic liquid configurations address the density gap between production and consumption timing.
Volume sits with electrolyzers; growth tilts toward fuel cells.
Technology:
Efficiency thresholds and electricity sourcing requirements determine technology selection across production scales.
- Electrolysis:Commercial alkaline systems leverage mature supply chains and lower capital intensity, while proton exchange membrane units offer rapid response to renewable power variability. Solid oxide electrolysis is gaining traction in steel mill integration projects across Sweden and the Netherlands for waste heat recovery.
- Photoelectrochemical:Direct solar-to-hydrogen conversion bypasses grid electricity entirely, attracting venture funding for remote production despite pre-commercial status.
- Thermochemical:High-temperature water splitting using concentrated solar or nuclear heat remains in demonstration phase with limited near-term deployment.
- Biological Hydrogen Production:Algal and bacterial pathways operate at ambient conditions but face productivity constraints that limit industrial relevance.
Deployment concentrates around electrolysis; photoelectrochemical pathways are expanding most quickly in research funding.
End User:
Carbon accounting obligations and fuel cost exposure reshape demand concentration across customer categories.
- Transportation:Heavy-duty trucking, maritime shipping, and rail operators face tightening emissions regulations under California's Low Carbon Fuel Standard and EU maritime fuel mandates. Port authorities in Hamburg and Rotterdam pilot hydrogen bunkering infrastructure.
- Power Generation:Utility-scale fuel cell installations and gas turbine co-firing trials address grid decarbonization in markets with renewable curtailment challenges.
- Industrial Applications:Steelmakers and ammonia producers in Germany, the Netherlands, and Sweden lead offtake as EU emissions trading scheme costs escalate.
- Residential Use:Combined heat and power fuel cell systems penetrate Japanese and South Korean markets with established natural gas distribution networks.
Industrial offtake dominates contract value; transportation applications are climbing the fastest on policy pull.
Applications:
Revenue capture varies between energy arbitrage, fuel substitution, and reliability services.
- Energy Storage:Long-duration hydrogen storage addresses seasonal renewable mismatch, with salt cavern projects advancing in the UK and Germany.
- Clean Fuel Production:Certified renewable hydrogen supply serves industrial processes and mobility under emerging carbon accounting standards.
- Cogeneration Systems:Combined heat and power fuel cells achieve 80% plus system efficiency in district heating and industrial thermal applications.
- Backup Power:Stationary fuel cells replace diesel generators for critical infrastructure resilience in data centers and telecommunications.
Clean fuel production commands margin premiums; energy storage represents the steepest expansion trajectory on grid balancing needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial cluster in Germany anchors electrolyzer deployment for steel decarbonization trials, while California's transit agencies scale hydrogen bus procurement under state-level carbon mandates. Policy divergence between EU emissions trading and US state-level fuel standards is fragmenting investment timelines across production geographies.
Germany
Steelmakers in the Ruhr and chemical producers along the Rhine corridor drive captive hydrogen demand. The EU Green Deal's renewable hydrogen mandates reposition industrial offtake obligations toward electrolysis pathways. ThyssenKrupp's Duisburg site hosts Europe's largest steel decarbonization pilot, aggregating electrolyzer capacity for direct reduction furnaces.
United States
California transit operators and Texas industrial users split demand between mobility and ammonia feedstock applications. The EPA regulates production emissions thresholds under the Clean Air Act, while California's Low Carbon Fuel Standard creates guaranteed offtake for fuel cell bus fleets. The Port of Long Beach pilots hydrogen bunkering infrastructure for maritime decarbonization.
China
State-owned petrochemical groups and provincial energy conglomerates dominate electrolyzer procurement for ammonia and methanol synthesis. MIIT's dual carbon goals pressure heavy industry toward hydrogen substitution in steel and refining. Inner Mongolia and Xinjiang host concentrated renewable hydrogen production zones leveraging curtailed wind and solar capacity.
Netherlands
Port authorities in Rotterdam and industrial users in the Chemelot cluster aggregate demand for import-export hub development. The EU AI Act and CE marking frameworks shape automated electrolyzer certification timelines. Shell's Pernis refinery and Tata Steel's IJmuiden site anchor offtake agreements for gigawatt-scale electrolyzer projects.
Japan
METI's hydrogen roadmap targets ammonia co-firing in power generation and fuel cell deployment in heavy transport. Residential combined heat and power systems penetrate suburban markets around Tokyo and Osaka. The Kobe and Yokohama port authorities trial hydrogen supply chains for maritime and aviation fuel substitution.
Water As a Fuel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrolyzer efficiency guarantees and long-term hydrogen purchase agreement pricing. The vendor base stratifies between industrial gas incumbents with captive distribution infrastructure and pure-play electrolyzer specialists scaling manufacturing capacity. Three archetypes dominate: integrated energy majors leveraging existing fuel supply relationships, industrial gas firms controlling hydrogen logistics economics, and technology-focused specialists advancing solid oxide and PEM stack architectures. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with project developers securing decade-long offtake contracts to underwrite manufacturing scale.
Within the industrial gas tier, Linde plc and Air Liquide occupy positions anchored by pipeline distribution networks and merchant hydrogen customer relationships. Plug Power Inc. exemplifies the captive production specialist archetype, while FuelCell Energy Inc. represents stationary power generation focus. Iberdrola S.A. and Enel Green Power Spa sit within the utility-led developer category, leveraging renewable electricity portfolios to underwrite green hydrogen project economics. Orsted A/S occupies a position bridging offshore wind development with power-to-X integration.
| Leading Market Players |
|---|
| ExxonMobil |
| Air Liquide |
| Orsted A/S |
| FuelCell Energy Inc |
| Plug Power Inc. |
| Linde plc |
| Iberdrola S.A. |
| China Petroleum & Chemical Corporation |
| Enel Green Power Spa |
| Others |
Value Network & Pricing Analysis
California's Low Carbon Fuel Standard gates qualified supply and premium-tier pricing access for electrolyzer operators, reserving contract eligibility for producers with certified renewable electricity linkage and verified emissions accounting. Steelmakers and transit agencies pay margin premiums for hydrogen purchase agreements that satisfy EU Green Deal mandates or state-level carbon intensity thresholds.
Pricing Analysis
Long-term hydrogen purchase agreements with embedded carbon accounting anchor value-based pricing, tying contract rates to verified emissions reductions and renewable energy provenance. Price differentiation rests on certification grade under EU emissions trading scheme alignment and volume scale, with industrial offtakers securing decade-long contracts at fixed escalators. Cost compression in merchant hydrogen spot markets is intensifying because legacy natural gas reformer supply retains short-term cost advantages. Chemical producers and steelmakers exhibit lowest price sensitivity, while distributed mobility operators face acute margin pressure from infrastructure gaps.
Supply Chain Analysis
Specialized membrane electrode assembly expertise concentrates in Germany, Japan, and South Korea, constraining stack manufacturing capacity expansion for proton exchange membrane and solid oxide electrolyzer variants. Critical inputs draw from East Asian manufacturing corridors for proton exchange membranes, Nordic suppliers for advanced ceramics in solid oxide cells, and Australian mining operations for platinum group metal catalysts. Single-source vulnerability in membrane material supply creates exposure to trade restriction and logistics disruption. Distribution runs through industrial gas pipeline networks for captive production sites and cryogenic liquid tanker fleets for remote offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with electrolyzer manufacturers and project developers pursuing upstream control over renewable electricity supply to underwrite green hydrogen cost parity.
For Market Incumbents: Extend efficiency guarantee coverage to capture steelmaker procurement decisions, as ThyssenKrupp and Tata Steel pilot direct reduction compatibility requirements. Deepen backward integration into renewable power development to secure electricity cost predictability against spot market exposure. Solid oxide electrolysis R&D investment defends position against PEM specialists encroaching on industrial heat integration applications.
For New Entrants and Emerging Players: California's Low Carbon Fuel Standard in the United States opens a window for modular electrolyzer deployment at transit agency fueling hubs, where incumbent industrial gas firms lack localized presence. Target maritime bunkering infrastructure at Rotterdam and Hamburg ports, where hydrogen supply contracts remain uncommitted and port authorities seek pilot operators. Pursue automated control system certification as a go-to-market angle, as EU AI Act compliance timelines create bottlenecks for established equipment manufacturers.
For Investors and Strategic Acquirers: ThyssenKrupp's Duisburg steel decarbonization pilot reaching commercial scale is the leading indicator that captive production economics have crossed viability thresholds for project finance. Over a multi-year horizon, vertically integrated developers combining renewable assets with electrolyzer manufacturing and offtake contracting represent the most defensible acquisition profile. Monitor solid oxide electrolysis efficiency guarantees hardening to debt-market standards as the signal for technology substitution risk in incumbent PEM valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Renewable Power Development | Upstream electricity cost control underwrites green hydrogen project economics against merchant power volatility. |
| Long-term Hydrogen Purchase Agreements | Ten-year contracts with certified renewable linkage satisfy EU Green Deal industrial offtake obligations. |
| Solid Oxide Electrolysis Scale-up | Waste heat recovery compatibility attracts steelmaker procurement for direct reduction furnace integration. |
| Automated Control System Certification | EU AI Act compliance enables unmanned production facilities and reduces opex in remote deployments. |
| Port-based Hydrogen Bunkering Infrastructure | Rotterdam and Hamburg pilot projects create localized demand for water-splitting production capacity. |
Research Methodology
Document review covered electrolyzer manufacturer technical specifications, EU emissions trading scheme regulatory filings, and California Air Resources Board Low Carbon Fuel Standard program data, complemented by interviews with electrolyzer engineering directors, renewable hydrogen project developers, steelmaker procurement leads, and industrial gas distribution specialists. Secondary validation drew from International Energy Agency hydrogen technology reports, FERC interconnection queue data, and customs records for electrolyzer stack component trade flows. Bottom-up capacity deployment tracking and top-down policy scenario modeling enabled triangulation across data sources.
Market size outputs reflect segment-level electrolyzer capacity installation, fuel cell deployment, and hydrogen generation unit procurement across the projection horizon, with technology adoption curves modeled for alkaline, proton exchange membrane, and solid oxide electrolysis pathways. End-use segmentation captured industrial applications, transportation, power generation, and residential cogeneration demand patterns. CAGRs were derived from policy-mandated procurement schedules, industrial decarbonization trial timelines, and renewable electricity cost trajectories, with sensitivity analysis applied to grid electricity price volatility and membrane material supply constraints.
The model assumes a particular technology adoption path; alternative pathways for photoelectrochemical direct solar-to-hydrogen conversion would alter the outlook if laboratory advances achieve commercial efficiency thresholds ahead of electrolysis cost decline curves. Forecasts reflect assumptions regarding EU Green Deal implementation pace, California LCFS credit price stability, and steel industry emissions trading scheme cost pass-through. Material deviation in renewable power purchase agreement availability or membrane supply chain concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Green Ammonia Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Renewable Natural Gas Market