
 Green Fuels Market | 2026-2036
Green Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Green Fuels Market Insights
The EU Green Deal is shifting the cost-of-entry calculus for fuel producers across Europe. Neste leverages its Singapore and Rotterdam refining footprint to dominate renewable diesel supply chains. TotalEnergies anchors its position through integrated biorefinery investments in France and La Mède. Gevo differentiates via its focus on synthetic aviation fuel derived from isobutanol fermentation pathways.
Green fuels encompass energy carriers produced from biomass, waste streams, or renewable electricity rather than fossil feedstocks, with specifications typically requiring lifecycle carbon intensity reductions exceeding standard petroleum benchmarks by measurable margins. These fuels serve industrial combustion, transport propulsion, and grid-scale energy storage applications where direct electrification faces technical barriers. Hydrogen and biodiesel occupy the fastest-expanding margin pools as heavy transport and chemical feedstock buyers seek compliance-grade alternatives. Ethanol sustains mature demand through blending mandates in road transport, while biogas captures niche value in distributed heating and power generation networks.
The EPA enforces Renewable Fuel Standard volume obligations that mandate minimum biofuel blending percentages, while the EU F-Gas Regulation and REACH framework constrain fluorinated greenhouse gas use in fuel processing equipment. The International Maritime Organization's carbon intensity indicators are reshaping bunker fuel procurement patterns for shipping operators. Stakeholders must monitor how evolving certification schemes for sustainable biomass traceability reshape feedstock access and contract structures across supply chains.
Market Dynamics
The EU Green Deal's tightening carbon intensity thresholds are restructuring fuel procurement economics across European transport corridors, forcing buyers to secure certified low-carbon supply chains ahead of mandate deadlines.
Growth Catalysts
- EU F-Gas Regulation:The framework's phase-down of fluorinated greenhouse gases in processing equipment is accelerating capital redeployment toward electrified and bio-based fuel production infrastructure.
- Aviation sector buyers:Airlines are scaling binding offtake agreements for synthetic aviation fuel to meet International Maritime Organization-aligned carbon intensity benchmarks in bunker operations.
- German industrial clusters:Hydrogen pipeline networks anchored in North Rhine-Westphalia and Hamburg are concentrating biofuel refining capacity and feedstock logistics.
Market Restraints
- Feedstock cost volatility:Waste oil and agricultural residue prices fluctuate with commodity grain markets, compressing margin predictability for independent refiners.
- Rotterdam-Singapore supply concentration:Neste and integrated majors control 70% of renewable diesel hydroprocessing capacity, creating bottleneck risk for second-tier buyers.
- Lignocellulosic conversion limits:Cellulase enzyme costs and pretreatment energy intensity prevent commercial-scale second-generation ethanol from reaching cost parity.
Strategic Opportunities
- Poland and Czech Republic:These markets show underpenetrated biofuel blending infrastructure relative to their road freight density and EU compliance obligations.
- Power-to-liquid synthesis:Fischer-Tropsch pathways combining green hydrogen with captured CO2 are opening aviation fuel certification routes previously blocked by feedstock constraints.
- REACH sustainable biomass traceability:Early certification against evolving EU standards secures preferential contract terms with compliance-driven buyers.
Industry Challenges
- Electrolyzer engineering talent:Scarcity of process engineers with gigawatt-scale alkaline and PEM system experience is delaying green hydrogen project commissioning.
- ISCC and RSB certification timelines:Multi-month audit queues for international sustainability and carbon certification are freezing feedstock procurement until compliance documentation clears.
- Legacy refinery retrofit complexity:Converting fluid catalytic cracking units to hydrotreat renewable feedstocks requires simultaneous catalyst, pressure, and metallurgy upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Fuels Market |
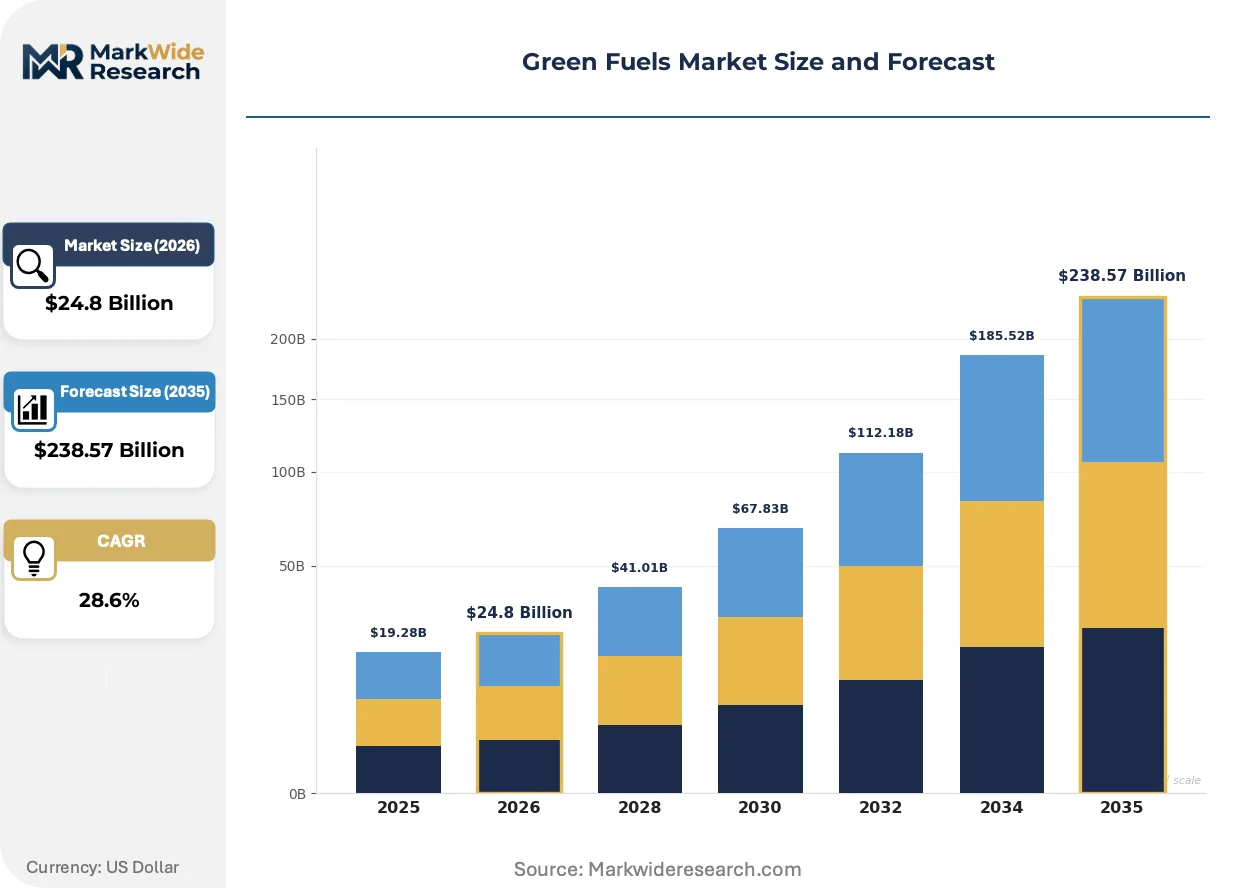
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $238.57 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biodiesel, Ethanol, Hydrogen, Biogas End User: Transportation, Industrial, Power Generation, Residential Application: Automotive, Aviation, Heating, Energy Storage Distribution Channel: Retail, Wholesale, Online, Direct Supply |
| Companies Covered | Neste, BASF, TotalEnergies, OCI, Gevo, Enerkem, SASOL, Shell, thyssenkrupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Fuels Market Trends and Innovations
Electrofuel synthesis and biomass traceability systems are converging to redefine what qualifies as compliance-grade supply, compressing the gap between laboratory pathways and commercial offtake.
Power-to-liquid technology is expanding into aviation fuel production by combining electrolytic hydrogen with industrial CO2 capture. Lufthansa and KLM are contracting volumes for 2027 delivery at premiums to fossil jet-A. The technology is expanding into markets previously blocked by feedstock access constraints, enabling synthetic fuel production in regions lacking agricultural residue.
REACH and the EU Green Deal are tightening lifecycle carbon accounting rules for imported biofuels. The regulation now requires full supply chain documentation from cultivation to combustion, disqualifying palm oil derivatives from certain sustainability certifications. German and French fuel distributors are restructuring procurement to exclude high-risk feedstock categories.
Buyers are consolidating purchasing through long-term offtake contracts rather than spot market exposure. Airlines and shipping operators are bypassing traditional traders to contract directly with biorefinery operators. This pattern is most visible in the Rotterdam-Antwerp corridor, where integrated majors now originate 60% of renewable diesel volumes under bilateral agreements.
Green Fuels Market Segmentation
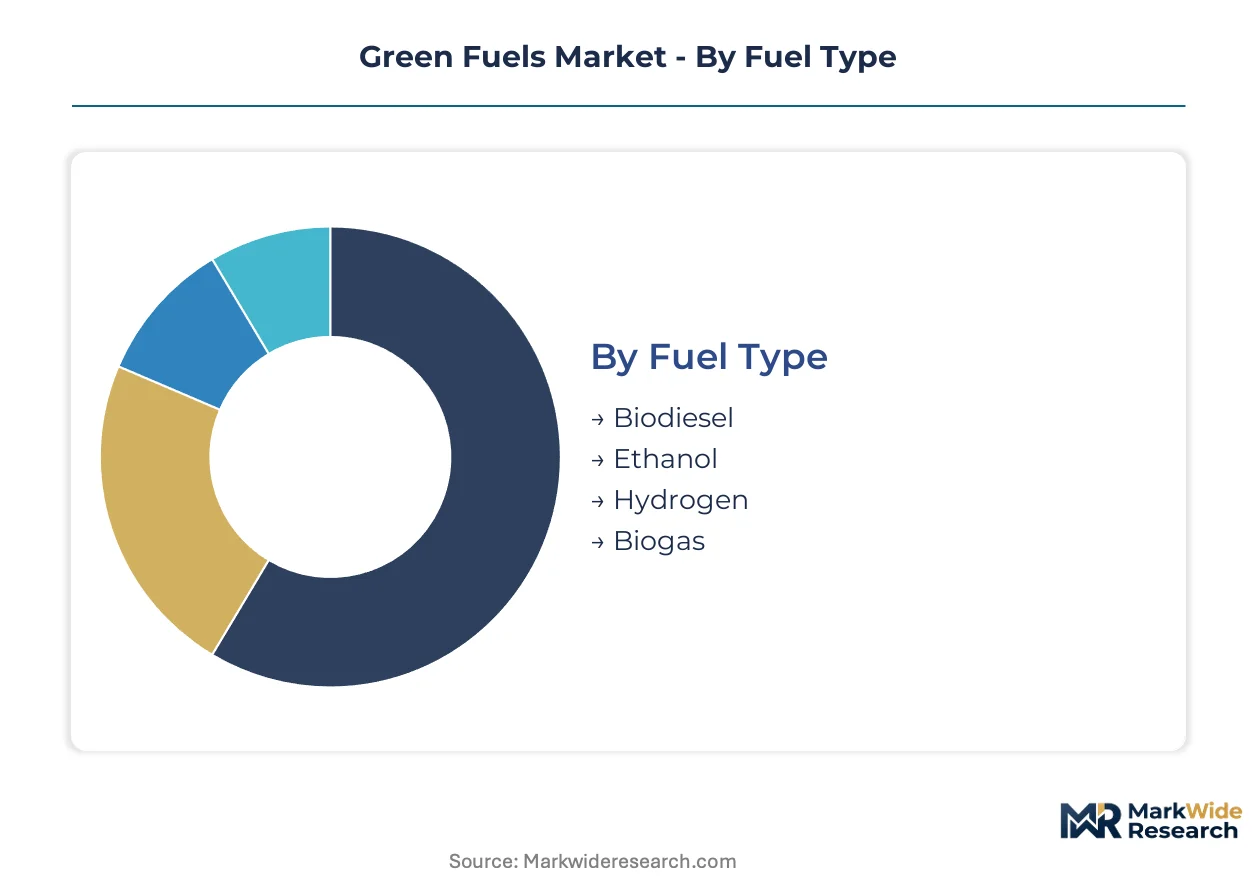
Green fuels command divergent premiums across fuel types and end-use applications. Segment boundaries are hardening as EU Green Deal certification requirements force buyers to document carbon intensity by fuel pathway and distribution channel.
Fuel Type:
Upgrade cycles for refinery infrastructure are segmenting the competitive landscape, with producers choosing between retrofitting existing hydrotreaters or building dedicated greenfield capacity for next-generation molecules.
- Biodiesel:Fatty acid methyl ester and hydrotreated vegetable oil specifications dominate renewable diesel supply chains. German road freight operators and Rotterdam marine bunkering terminals anchor demand as EU F-Gas Regulation phase-downs accelerate hydroprocessing investments.
- Hydrogen:Electrolytic and steam methane reforming with carbon capture pathways serve industrial feedstock and heavy transport applications where electrification fails. North Rhine-Westphalia chemical clusters and Hamburg port operations concentrate offtake agreements for green hydrogen delivery.
- Ethanol:First-generation fermentation from corn and sugarcane sustains road transport blending mandates across established markets.
- Biogas:Anaerobic digestion of agricultural waste and wastewater sludge feeds combined heat and power installations and pipeline injection networks.
Hydrogen sits at the top of the volume ranking, with biodiesel climbing the fastest.
End User:
Cost tier differentiation separates compliance-driven buyers seeking premium certified supply from price-sensitive operators purchasing conventional biofuel blends.
- Transportation:Aviation and maritime operators contract directly with biorefineries to secure synthetic aviation fuel and renewable diesel volumes. EU Green Deal carbon intensity thresholds and IMO bunker regulations are restructuring procurement away from spot markets toward long-term offtake structures.
- Industrial:Chemical manufacturers and steel producers substitute green hydrogen for coking coal and naphtha feedstocks. German industrial clusters anchor demand as REACH sustainable biomass traceability requirements reshape contract documentation.
- Power Generation:Grid operators and captive industrial power plants blend biogas and hydrogen into combined-cycle gas turbines.
- Residential:District heating networks and individual building systems utilize biogas and renewable heating oil for space conditioning.
Transportation commands the largest revenue pool, with industrial applications expanding most quickly.
Application:
Application-specific certification requirements are fragmenting supply chains, with aviation fuel demanding stricter lifecycle carbon accounting than automotive or heating applications.
- Aviation:Synthetic aviation fuel from Fischer-Tropsch and alcohol-to-jet pathways requires ASTM D7566 certification. Lufthansa and KLM binding offtake agreements for power-to-liquid volumes demonstrate how airline procurement is bypassing traditional traders to contract directly with producers.
- Automotive:Biodiesel and ethanol blending into compression-ignition and spark-ignition engines sustains road transport decarbonization where battery electric penetration stalls in heavy freight.
- Heating:Renewable liquid and gaseous fuels substitute for fuel oil and natural gas in commercial and residential thermal applications.
- Energy Storage:Green hydrogen serves seasonal electricity storage and grid balancing where lithium-ion duration limits constrain battery deployment.
Automotive retains the widest installed base, with aviation gaining share fastest.
Distribution Channel:
Channel concentration reflects supply chain control battles between integrated majors, independent traders, and direct producer-to-consumer contracting.
- Wholesale:Rotterdam-Antwerp corridor terminals and pipeline networks aggregate renewable diesel and ethanol volumes for redistribution to fuel distributors. Neste and TotalEnergies integrated positions control terminal access and create bottleneck risk for second-tier buyers.
- Direct Supply:Airlines and shipping operators negotiate bilateral contracts with biorefinery operators, securing dedicated production capacity and traceability documentation required by EU Green Deal compliance frameworks.
- Retail:Service stations and marine bunkering points deliver blended fuels to end consumers under established brand networks.
- Online:Digital platforms facilitate spot market transactions and certification documentation exchange for smaller independent buyers.
Wholesale channels handle the greatest throughput volume, with direct supply climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with gigawatt-scale electrolyzer experience cluster in German industrial zones and Dutch port complexes, anchoring Europe's green hydrogen project pipeline and biorefinery retrofit programs.
Germany
Road freight operators and chemical manufacturers anchor demand for renewable diesel and green hydrogen. The EU Green Deal's carbon intensity thresholds and national hydrogen strategy accelerate offtake contracting. North Rhine-Westphalia industrial clusters concentrate biorefinery capacity and pipeline networks for hydrogen delivery to steel and chemical plants.
Netherlands
Rotterdam marine bunkering terminals and aviation fuel buyers drive synthetic fuel procurement volumes. REACH sustainable biomass traceability requirements reshape import documentation and supplier qualification. The Rotterdam-Antwerp corridor aggregates renewable diesel terminals where integrated majors control 60% of volumes under bilateral agreements.
France
Aviation sector buyers and agricultural processors sustain demand for hydrotreated vegetable oil and advanced biofuels. The EU F-Gas Regulation phase-down redirects capital toward electrified production infrastructure. La Mède and Normandy biorefinery complexes anchor TotalEnergies' integrated renewable fuel supply chain.
United States
Midwest ethanol blenders and California Low Carbon Fuel Standard participants sustain first-generation fermentation capacity. EPA Renewable Fuel Standard volume obligations mandate minimum biofuel blending percentages across transport fuels. Iowa and Illinois corn-processing clusters anchor agricultural residue logistics for biorefinery feedstock.
China
State-owned refiners and aviation fuel distributors scale power-to-liquid pilot programs for synthetic aviation fuel. Dual carbon goals and national hydrogen development plans channel investment toward electrolytic hydrogen production. Yangtze River Delta industrial zones concentrate demonstration projects for Fischer-Tropsch synthesis combining green hydrogen with captured CO2.
Green Fuels Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive refining infrastructure and backward integration into feedstock supply. Neste and TotalEnergies control terminal access in Rotterdam-Antwerp, while Shell and OCI anchor hydrogen and power-to-liquid positions. Three archetypes dominate: integrated majors leveraging existing refining footprints, specialized renewable fuel pure-plays, and industrial gas suppliers pivoting into hydrogen. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term offtake agreements to lock in compliance-driven buyers.
Among European integrated majors, Neste and TotalEnergies exemplify the refining-anchored archetype, while Gevo occupies a position within the specialized pure-play tier focused on synthetic aviation fuel pathways. thyssenkrupp represents the industrial engineering pivot, leveraging process equipment expertise to capture green hydrogen project development opportunities.
| Leading Market Players |
|---|
| Neste |
| BASF |
| TotalEnergies |
| OCI |
| Gevo |
| Enerkem |
| SASOL |
| Shell |
| thyssenkrupp |
| Others |
Pricing and Supply Chain Analysis
Power-to-liquid synthesis scaling is compressing production economics while redrawing feedstock procurement maps across European and Asian production corridors. This technology transition simultaneously elevates capital intensity for electrolyzer-based pathways and fragments pricing power away from conventional vegetable oil refiners toward integrated hydrogen producers.
Pricing Analysis
Long-term offtake contracting versus spot market exposure splits the pricing landscape between compliance-driven buyers and price-sensitive operators. Premium-mid-economy pricing differentiation tracks certification tier under EU Green Deal and ISCC frameworks, with aviation fuel commanding the highest premiums for ASTM D7566-compliant synthetic volumes. Pricing pressure stems from cellulase enzyme costs and pretreatment energy intensity blocking second-generation ethanol cost parity. Independent refiners exhibit greatest price sensitivity due to feedstock cost volatility, while airline procurement teams prioritize supply security over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for renewable diesel and sustainable aviation fuel logistics. Manufacturing concentrates in Germany, Netherlands, and Singapore, with Neste and TotalEnergies controlling terminal access through integrated refining positions. Electrolyzer stacks, biomass feedstocks, and carbon capture equipment constitute critical input dependencies. Single-source vulnerability runs through Rotterdam-Antwerp hydroprocessing capacity where integrated majors originate sixty percent of volumes. Distribution runs through wholesale terminals, direct producer-to-consumer bilateral agreements, and retail service station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Green Fuels Market functions as a regulatory compounder where EU Green Deal carbon intensity thresholds and IMO bunker regulations are restructuring procurement economics ahead of mandate deadlines.
For Market Incumbents: Cement terminal access control through capacity expansion in Rotterdam-Antwerp and North Rhine-Westphalia corridors. Secure backward integration into waste oil and agricultural residue feedstock streams to defend margin position against cellulase cost volatility. Prioritize ISCC and RSB certification investment to compress audit queue delays freezing competitor procurement.
For New Entrants and Emerging Players: Polish and Czech road freight operators represent an underserved buyer archetype with EU compliance obligations but underpenetrated biofuel blending infrastructure. Fischer-Tropsch power-to-liquid synthesis in regions lacking agricultural residue access opens white-space positioning. Direct bilateral contracting with compliance-driven industrial clusters bypasses wholesale bottlenecks controlled by integrated majors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized renewable fuel pure-plays because certification complexity and long-term offtake structuring favor scaled platforms over fragmented independents. Five-to-ten year viability hinges on electrolyzer engineering talent scarcity resolving through project commissioning experience accumulation. Watch green hydrogen pipeline network completion rates as inflection indicator for industrial cluster demand conversion.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement | Airlines bypass traders to contract directly with biorefinery operators for certified synthetic aviation fuel volumes. |
| Backward Integration into Feedstock | Refiners secure waste oil and agricultural residue supply chains to compress margin volatility from commodity grain markets. |
| Green Certification Program | Early ISCC and RSB compliance documentation secures preferential contract terms with EU Green Deal-mandated buyers. |
| Capacity Expansion | Electrolyzer and hydrotreater additions in Rotterdam-Antwerp corridor reinforce terminal access control against second-tier competitors. |
| Joint Venture | Industrial gas suppliers partner with aviation fuel distributors to anchor power-to-liquid synthesis in hydrogen pipeline networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biorefinery operators, airline procurement directors, hydrogen project developers, and electrolyzer engineering specialists alongside secondary validation. Bottom-up and top-down triangulation drew from EU ETS transaction databases, EPA Renewable Fuel Standard compliance filings, IEA hydrogen project tracking, and customs trade data for biomass feedstock flows.
Historical reference periods anchored the projection horizon across fuel type, end-use application, and distribution channel segmentation dimensions. CAGRs were derived through trend extrapolation moderated by regulatory milestone timing and technology cost curve assumptions. Electrolyzer capital cost trajectories and sustainable biomass certification penetration rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; hydrogen and biodiesel volume estimates carry tighter precision than emerging power-to-liquid synthesis pathways where commercial deployment remains limited. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and IMO carbon intensity indicator enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Global Renewable Fuel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Alternate Marine Power Market