
 Jatropha Biodiesel Market | 2026-2036
Jatropha Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
Jatropha Biodiesel Market Insights
Procurement channels for jatropha biodiesel is tilting away from spot-trading terminals toward long-term offtake agreements tied to plantation estates. Renewable Energy Group anchors North American supply through backward integration into feedstock aggregation. Neste Corporation dominates European refining capacity for waste and residue-based pathways including jatropha oil. Cargill extends its origination network across Brazilian and Indian crushing operations, securing volume for export markets.
Jatropha biodiesel denotes fatty acid methyl ester (FAME) produced from the non-edible oilseeds of Jatropha curcas, a drought-resistant shrub yielding 1,500–2,000 liters of oil per hectare under semi-arid cultivation. The fuel serves as a direct substitute or blend component for petroleum diesel in compression-ignition engines, meeting ASTM D6751 or EN 14214 specifications depending on destination market. Blended biodiesel occupies the largest share of product-type revenue as infrastructure compatibility limits near-term pure-fuel penetration. Vehicle fuel leads application demand, though generator fuel for remote industrial sites represents the fastest-growing consumption segment as mining and telecom operators seek liquid-fuel alternatives to diesel imports.
The EPA's Renewable Fuel Standard governs US market access through D-code categorization of biomass-based diesel, while the EU's Renewable Energy Directive imposes sustainability criteria that exclude palm-oil-linked feedstocks and indirectly favor jatropha from certified plantations. India's MNRE blending mandates and state-level biofuel policies create procurement obligations for public sector oil marketing companies. Stakeholders must monitor evolving lifecycle greenhouse gas methodologies, as ILUC (indirect land-use change) calculations will determine which plantation-origin feedstocks qualify for premium credit values in regulated markets.
Market Dynamics
Long-term offtake agreements are displacing spot-market transactions as plantation estates seek revenue certainty and refiners lock in certified feedstock volumes. This structural shift toward contract-based procurement is compressing trading margins while elevating sustainability verification requirements across the value chain.
Growth Catalysts
- EU Renewable Energy Directive:Sustainability criteria excluding palm-oil-linked feedstocks indirectly favor jatropha from certified plantations, redirecting European demand toward non-food crop pathways.
- Remote industrial sites:Mining and telecom operators in Southeast Asia are substituting diesel imports with jatropha-derived generator fuel to reduce supply chain vulnerability and fuel cost volatility.
- India's MNRE blending mandates:State-level biofuel policies create procurement obligations for public sector oil marketing companies, institutionalizing demand for domestic jatropha supply.
Market Restraints
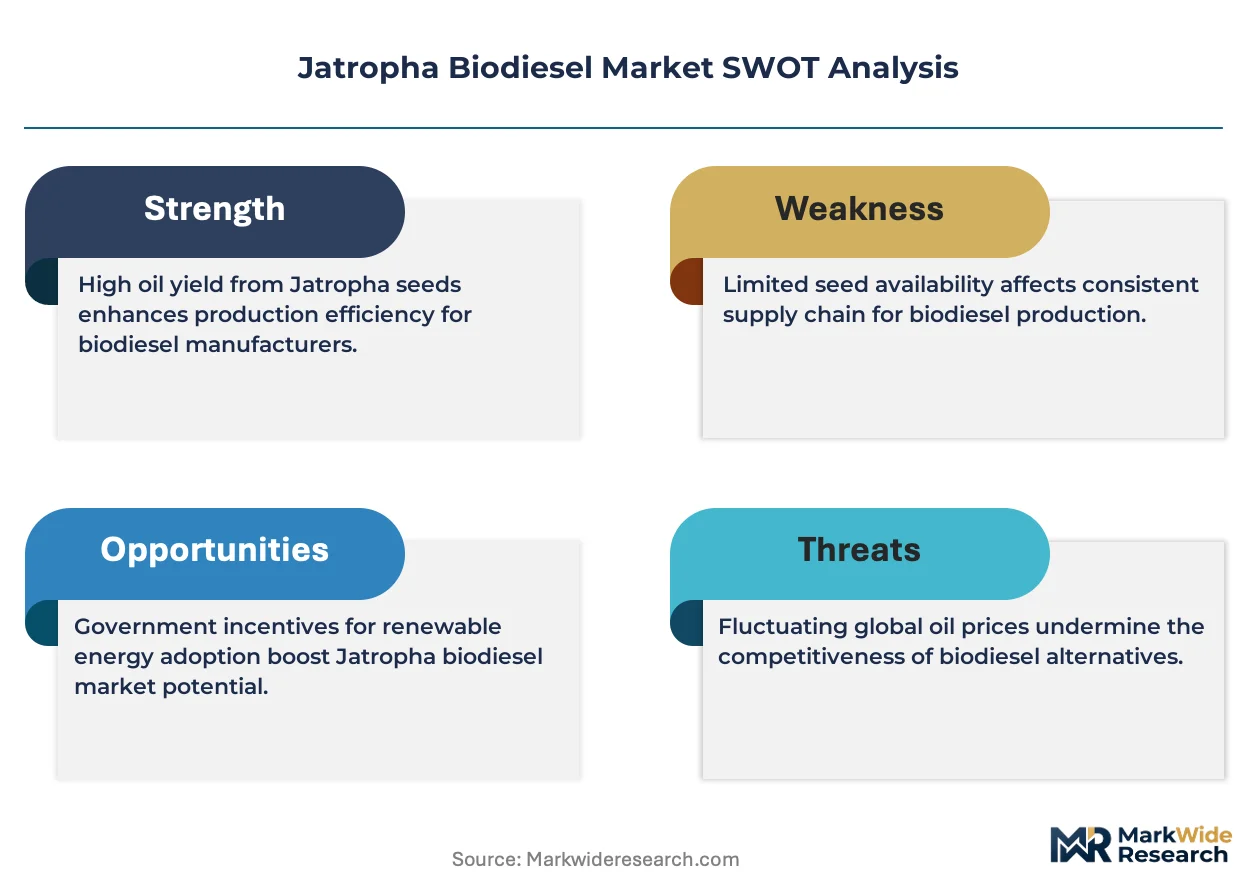
- Input cost volatility:Crude glycerin and methanol prices fluctuate with petrochemical markets, compressing biodiesel production margins during oil price spikes.
- Supply concentration risk:Indonesia's plantation zones dominate upstream feedstock availability, creating geographic vulnerability to El Niño drought cycles and export policy shifts.
- ASTM D6751/EN 14214 cold-flow limitations:Jatropha FAME exhibits poorer low-temperature performance than petroleum diesel, restricting winter deployment in temperate climates without flow-improver additives.
Strategic Opportunities
- Underpenetrated African cultivation:Semi-arid zones in Kenya and Tanzania offer expansion potential where agro-climatic conditions mirror successful Indian and Indonesian estates.
- Aviation biofuel pathways:Hydroprocessed esters and fatty acids (HEFA) certification opens jet fuel applications, commanding premium pricing above road transport markets.
- Blockchain-enabled traceability:Distributed ledger systems for plantation-to-refinery documentation satisfy EU sustainability audit requirements while reducing compliance overhead.
Industry Challenges
- Agronomic expertise scarcity:Skilled plantation managers capable of optimizing jatropha yields in marginal soils remain concentrated in Brazil and India, limiting expansion velocity.
- ISCC/RSB certification timelines:Third-party sustainability audits require 12-18 month implementation cycles, delaying market access for new plantation entrants.
- Legacy diesel infrastructure incompatibility:Existing storage and distribution systems require material upgrades to handle higher FAME blend ratios without seal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jatropha Biodiesel Market |
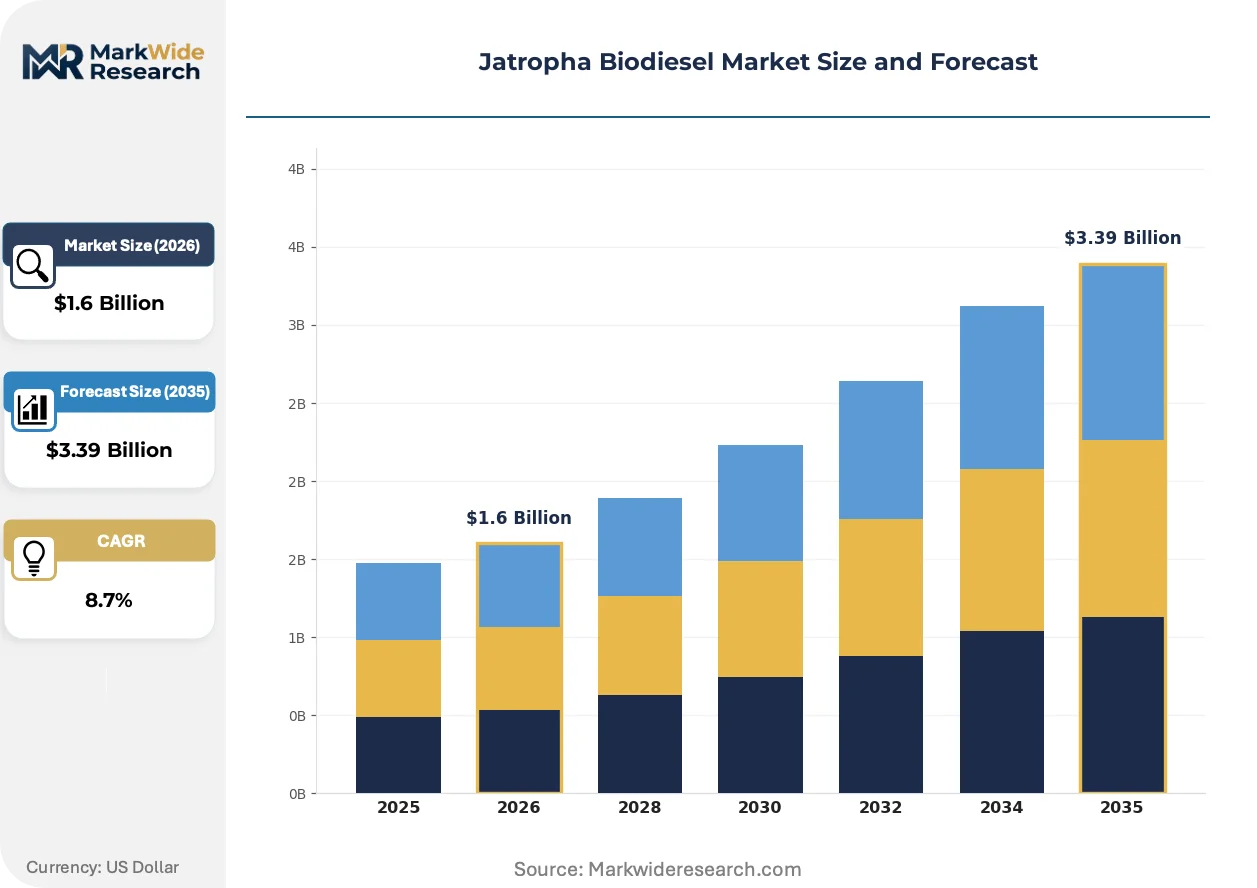
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Biodiesel, Blended Biodiesel, Feedstock, Crude Oil End User: Transportation, Industrial, Power Generation, Agriculture Application: Vehicle Fuel, Generator Fuel, Heating Oil, Lubricants Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Renewable Energy Group, Diester Industries, Neste Corporation, Glencore, Bionor, Cargill, Marathon Petroleum Corporation, Ital Green Oil, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jatropha Biodiesel Market Trends and Innovations
Process intensification and digital traceability systems are restructuring how jatropha biodiesel moves from plantation to combustion. These developments are compressing certification timelines while elevating the technical specifications demanded by regulated end-users.
Supercritical transesterification is migrating from pilot-scale demonstration to commercial deployment in Indian and Indonesian refineries. This non-catalytic process reduces reaction time from hours to minutes while eliminating alkali waste streams. Neste Corporation and domestic processors in Maharashtra are retrofitting continuous-flow reactors to handle variable jatropha oil acidity. The technology is enabling smaller-scale distributed production closer to plantation clusters, reducing feedstock transport costs.
The EU's delegated act on high indirect land-use change (ILUC) risk biofuels entered full enforcement, disqualifying conventional palm oil pathways from counting toward renewable energy targets. This regulatory compression is redirecting European oil major procurement toward jatropha certified under Roundtable on Sustainable Biomaterials (RSB) or International Sustainability and Carbon Certification (ISCC) schemes. German and Dutch fuel distributors are now requiring batch-level sustainability documentation that plantation-origin feedstocks can provide more readily than complex multi-source blends.
Buyer aggregation through fuel-supply consortia is consolidating procurement power among remote industrial operators. Mining companies in Papua New Guinea and telecom tower operators in Myanmar are pooling diesel replacement volumes to negotiate direct offtake contracts with plantation-backed refiners, bypassing traditional petroleum distributors. This channel disintermediation is most visible in archipelago geographies where marine logistics costs previously fragmented demand into uneconomic parcel sizes.
Jatropha Biodiesel Market Segmentation
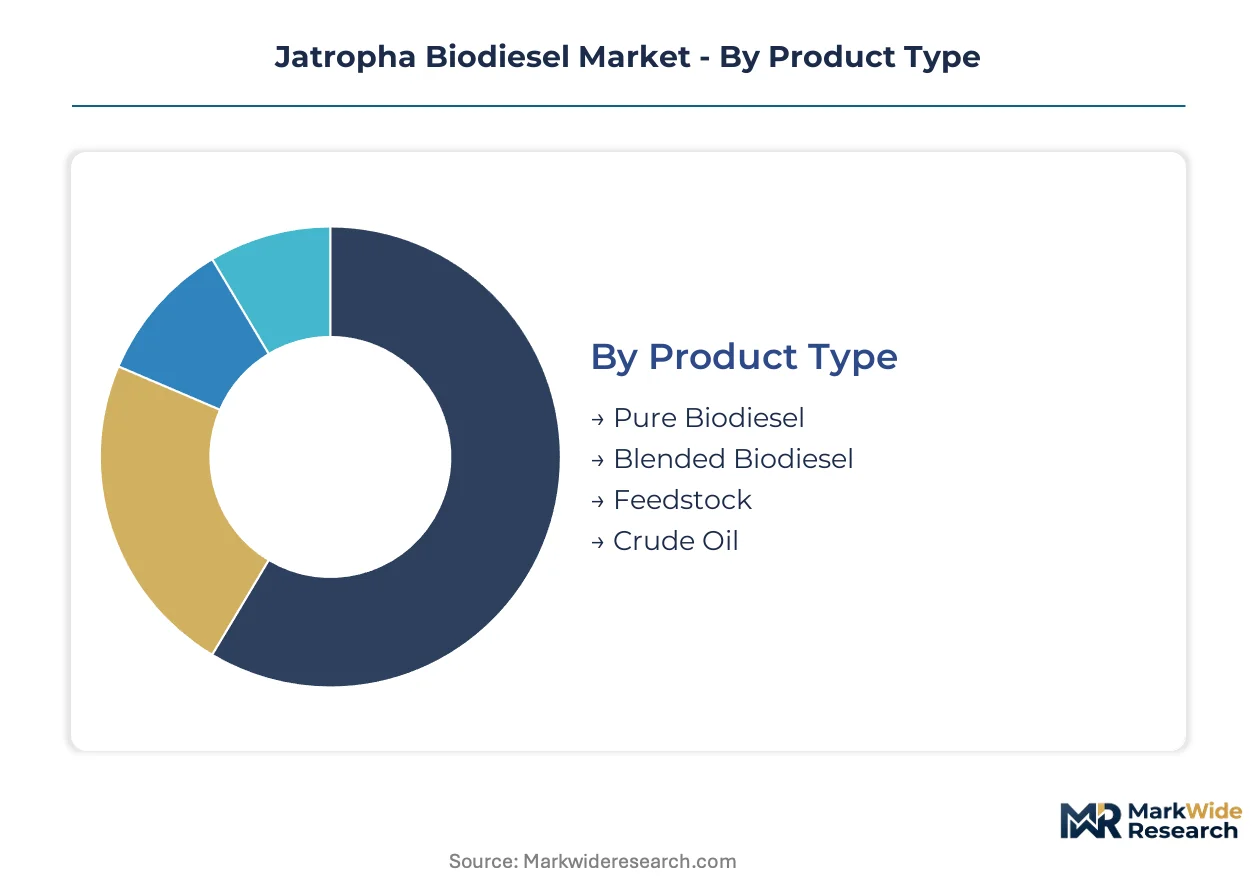
Jatropha biodiesel segments reflect divergent technical specifications and procurement economics across regulated fuel markets. Product form determines blending infrastructure requirements. End-use concentration varies sharply between established transport fleets and emerging remote power applications.
Product Type:
Product form governs margin structure and regulatory compliance burden across refining and distribution stages.
- Blended Biodiesel:Fatty acid methyl ester mixed with petroleum diesel at ratios typically ranging from B5 to B20, compatible with existing compression-ignition engines without modification. Demand concentrates in Indonesia's plantation zones and India's Maharashtra-Gujarat belt where state oil marketing companies fulfill MNRE blending mandates. Cold-flow limitations restrict winter deployment in temperate climates without additive packages.
- Pure Biodiesel:Unblended B100 FAME meeting ASTM D6751 or EN 14214 specifications for specialized fleet applications and export markets. European refiners under the EU Renewable Energy Directive source certified volumes from Indonesian estates with ISCC documentation. Material incompatibility with legacy seals and gaskets limits near-term infrastructure penetration.
- Feedstock:Raw jatropha oilseeds and unprocessed oil delivered to third-party refiners under long-term offtake agreements. Crushing operations in Brazil and India extend origination networks for export markets.
- Crude Oil:Unrefined jatropha oil requiring pretreatment for acidity and moisture content before transesterification. Distributed production clusters in semi-arid cultivation zones reduce transport costs to small-scale refineries.
Blended biodiesel commands the established base. The steepest expansion runs through pure biodiesel for certified sustainable fuel pathways.
End User:
Customer type determines volume scale, contract structure, and sustainability documentation requirements.
- Transportation:Fleet operators and public sector oil marketing companies procuring drop-in diesel replacement for compression-ignition engines. India's state-level biofuel policies create procurement obligations concentrating demand in Maharashtra and Gujarat public transport authorities.
- Power Generation:Mining companies and telecom tower operators in Southeast Asian archipelago geographies substituting diesel imports with jatropha-derived generator fuel. Papua New Guinea mining consortia and Myanmar telecom operators pool volumes to negotiate direct plantation contracts.
- Industrial:Manufacturing facilities and remote processing sites seeking liquid-fuel alternatives to petroleum diesel. Cold-flow performance constraints limit deployment in temperate climate operations without heating infrastructure.
- Agriculture:Farm machinery and irrigation pump sets in water-stressed cultivation regions. Semi-arid zone compatibility with jatropha's drought resistance creates localized demand loops near plantation estates.
Transportation anchors volume commitments. Power generation is gaining share fastest through buyer aggregation consortia.
Application:
Application determines fuel specification tier and pricing premium relative to petroleum diesel benchmarks.
- Vehicle Fuel:Road transport diesel replacement in commercial fleets and passenger vehicles. ASTM D6751 and EN 14214 compliance enables access to regulated blending mandates in the US and Europe.
- Generator Fuel:Stationary power generation for remote industrial sites and off-grid installations. Mining and telecom operators in Indonesia and Myanmar drive demand for supply chain security.
- Heating Oil:Commercial and residential thermal applications requiring sulfur-compliant fuel oils. Cold-flow limitations restrict deployment in northern climate heating seasons.
- Lubricants:Base oil feedstock for biodegradable lubricant formulations. Industrial machinery applications favor jatropha's oxidative stability profile.
Vehicle fuel holds the dominant share. Generator fuel is climbing the fastest as remote operators bypass petroleum distributors.
Distribution Channel:
Channel structure reflects the shift from spot-market terminals toward contract-based procurement with sustainability verification.
- Direct Sales:Long-term offtake agreements between plantation estates and refiners or end-users. German and Dutch fuel distributors now require batch-level sustainability documentation.
- Wholesalers:Aggregators consolidating volumes from multiple plantation sources for regional distribution. ISCC and RSB certification timelines create barriers for new entrants.
- Retail:Branded fuel stations and commercial fuel card networks offering blended biodiesel at point of sale. Infrastructure compatibility limits pure-fuel availability.
- Online:Digital procurement platforms and blockchain-enabled traceability systems for sustainability audit documentation. Distributed ledger systems reduce compliance overhead for EU market access.
Direct sales channels capture the expanding contract base. Online platforms are expanding most quickly for certification documentation efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's MNRE blending mandates anchor the dominant geography for jatropha biodiesel procurement, with Indonesia's plantation zones and European refining demand forming complementary demand poles. Public sector oil marketing companies in Maharashtra and Gujarat create institutional volume commitments. German and Dutch distributors impose batch-level sustainability documentation requirements.
India
State-level biofuel policies in Maharashtra and Gujarat concentrate public transport fleet procurement. The MNRE mandates blending obligations for oil marketing companies, institutionalizing domestic jatropha demand. Crushing operations across the Maharashtra-Gujarat belt secure feedstock for regional refiners.
Indonesia
Plantation estates in Sumatra and Kalimantan supply certified feedstock to European renewable fuel refiners. The country's export-oriented cultivation benefits from EU Renewable Energy Directive criteria excluding palm-oil-linked alternatives. Mining operators in Papua New Guinea source generator fuel through direct offtake agreements with Indonesian plantation-backed suppliers.
Germany
Fuel distributors in Hamburg and Rotterdam require ISCC-certified jatropha volumes for renewable energy target compliance. The EU's delegated act on high ILUC-risk biofuels redirects procurement toward certified non-food crop pathways. German oil majors source batch-documented sustainable feedstock from Indonesian estates.
United States
The EPA's Renewable Fuel Standard governs market access through D-code categorization of biomass-based diesel. Renewable Energy Group anchors North American supply through backward integration into feedstock aggregation. California's Low Carbon Fuel Standard creates premium credit demand for certified sustainable pathways.
Brazil
Semi-arid cultivation zones in Minas Gerais and Bahia offer agro-climatic conditions favorable to jatropha expansion. Cargill extends origination networks across Brazilian crushing operations for export market supply. Agronomic expertise from established soybean biodiesel operations transfers to jatropha yield optimization.
Jatropha Biodiesel Market Competitive Landscape
Vertically integrated plantation-refinery operators and specialized renewable fuel refiners split the market into distinct capability tiers. The structure concentrates around companies commanding certified feedstock access and those with hydroprocessing technology for premium fuel pathways. Three archetypes dominate: plantation-backed integrated producers, technology-licensed independent refiners, and agricultural commodity traders with origination networks. Competitive moves center on long-term offtake contracting and sustainability certification acquisition.
Among plantation-integrated operators, Renewable Energy Group and Neste Corporation exemplify the backward-integration archetype securing captive feedstock supply. Cargill occupies a position within the agricultural trading tier, leveraging origination infrastructure across multiple geographies. These three companies represent the dominant strategic configurations: North American integrated production, European hydroprocessing technology, and global commodity origination.
| Leading Market Players |
|---|
| Renewable Energy Group |
| Diester Industries |
| Neste Corporation |
| Glencore |
| Bionor |
| Cargill |
| Marathon Petroleum Corporation |
| Ital Green Oil |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
Sumatra's plantation estates command downstream pricing power through certified feedstock scarcity, as EU Renewable Energy Directive compliance requirements filter non-ISCC volumes from premium European markets. Contract structures now embed sustainability verification costs, compressing spot-market margins while elevating long-term offtake premiums.
Pricing Analysis
Rotterdam-Hamburg price spreads against Southeast Asian export benchmarks reflect certification tier differentiation. Pricing stratifies across ISCC-certified premium, standard RSB-compliant, and uncertified economy tiers. Cost compression in the economy tier intensifies because crude glycerin and methanol input costs track volatile petrochemical indices. Public sector oil marketing companies in India exhibit highest price sensitivity due to mandate-driven volume procurement, while European renewable fuel refiners show lowest sensitivity given regulatory credit value capture.
Supply Chain Analysis
Raw jatropha oilseeds draw from Indonesian, Indian, and Brazilian crushing operations with agronomic expertise concentrated in Maharashtra-Gujarat and Minas Gerais belts. Methanol, crude glycerin, and alkali catalyst inputs rest on petrochemical supply chains vulnerable to oil price spikes. Single-source vulnerability runs through Indonesia's plantation zones exposed to El Niño drought cycles. Distribution runs through direct sales channels linking estates to refiners, displacing spot-terminal intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are transforming this market's platform economics, as distributed ledger interoperability creates new certification efficiency standards across plantation-to-refinery documentation.
For Market Incumbents: Build certification moats through accelerated ISCC and RSB audit completion, locking in European offtake before new plantation entrants clear 12-18 month implementation cycles. Backward integration into feedstock aggregation secures volume against emerging African cultivation expansion. Neste Corporation and Renewable Energy Group demonstrate this defensive positioning through captive plantation relationships. For New Entrants and Emerging Players: Kenyan and Tanzanian semi-arid cultivation zones offer lowest competitive density with agro-climatic conditions mirroring successful Indian estates. Aviation biofuel HEFA pathways command premium pricing above road transport markets with underpenetrated supplier bases. Direct offtake contracting with mining consortia in Papua New Guinea bypasses petroleum distributor intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated refiners with long-term offtake structures, as spot-exposed traders face margin compression. Long-term viability centers on sustainability certification asset quality and hydroprocessing technology access. Watch for ILUC methodology revisions as the inflection signal determining which feedstock origins qualify for premium credit values.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement | Secures certified feedstock volumes for EU Renewable Energy Directive compliance. |
| ISCC Certification Program | Enables Rotterdam and Hamburg distributor market access with batch-level documentation. |
| Backward Integration into Plantations | Captures upstream margin and controls sustainability verification timelines. |
| HEFA Technology Licensing | Opens aviation biofuel pathways commanding premium above road transport markets. |
| Blockchain Traceability Deployment | Reduces EU sustainability audit compliance overhead through distributed ledger systems. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with plantation operations managers, renewable fuel refinery procurement leads, and EU regulatory compliance officers; and secondary validation through customs trade databases, EPA Renewable Fuel Standard D-code filings, and ISCC certification registries. Bottom-up volume estimates from crushing capacity and plantation yield data triangulated against top-down demand projections from MNRE mandate obligations and EU renewable energy targets.
Forecast inputs span product type segmentation across blended biodiesel, pure biodiesel, and feedstock categories; end-user concentration between transportation fleets and remote power generation; and application tiers from vehicle fuel to aviation HEFA pathways. CAGRs derive from regression analysis against crude oil price elasticity, blending mandate enforcement trajectories, and sustainability premium capture rates across certified versus uncertified supply channels.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by agricultural commodity traders would shift outcomes through feedstock cost structure disruption. Cross-checking against EPA D-code generation statistics and EU TARIC import classification data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Water As a Fuel Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Sustainable Aviation Fuel Market
Alternative Fuels
Biohydrogen Market
Alternative Fuels
Bio-Methane Market
Alternative Fuels
Renewable Natural Gas Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Aviation Alternative Fuel Market