
 Automotive Valve Stem Seal Market | 2026-2036
Automotive Valve Stem Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Valve Stem Seal Market Analysis
China is tilting toward domestic elastomer compounding capacity for high-temperature valve stem seals. SKF leverages its European R&D network to sustain fluoropolymer formulation leadership. Federal-Mogul anchors North American aftermarket distribution through direct service-dealer channels. Qingdao TKS competes on silicone seal cost structures for regional motorcycle OEMs.
An automotive valve stem seal is a precision-molded elastomeric or thermoplastic component installed at the valve guide interface to regulate lubricant flow into combustion chambers while maintaining crankcase pressure integrity; typical specifications include continuous operating temperatures from minus forty degrees Celsius to two hundred thirty degrees Celsius and resistance to aromatic hydrocarbons in modern low-viscosity engine oils. Its primary industrial purpose is to prevent oil consumption and carbon deposit formation that degrade emission control system performance over vehicle life. The rubber product type occupies the dominant volume position across passenger vehicle applications where cost engineering governs mass-market procurement decisions. PTFE formulations represent the fastest-expanding material category in heavy-duty truck installations where extended drain intervals and elevated thermal loads demand superior chemical inertness. The aftermarket provider end-user channel concentrates margin pools in mature vehicle parcs across North America and Western Europe where replacement frequency accelerates with aging engine architectures.
The EPA enforces evaporative emission standards that mandate seal integrity under pressurized crankcase conditions, while the EU Green Deal and REACH framework restrict perfluorinated compound formulations in European-sourced elastomers. China's MIIT implements GB standards for passenger vehicle fuel consumption that indirectly tighten tolerance specifications for valve train sealing systems. Stakeholders must monitor regulatory divergence between fluoropolymer restriction timelines in Europe and continued authorization under US EPA frameworks when allocating compounding capacity across geographies.
Market Dynamics
Downsized turbocharged engines are forcing material upgrades across valve stem seal portfolios as thermal loads exceed traditional elastomer limits. OEM procurement teams now specify fluoropolymer compounds for cylinder heads operating above two hundred degrees Celsius.
Growth Catalysts
- EPA Tier 3 crankcase ventilation mandates:US passenger vehicle fleets require upgraded seal integrity under pressurized conditions. Tier 3 evaporative emission standards tighten tolerance specifications for valve train components.
- Silicone elastomer cost engineering:Motorcycle OEMs in Southeast Asia specify high-volume silicone formulations for regional two-wheeler production. Domestic compounding capacity reduces import dependency for rubber seals.
- Extended drain interval specifications:Heavy-duty truck operators in Germany demand PTFE composite seals for thermal stability under severe duty cycles. Fleet maintenance economics favor longer service intervals.
Market Restraints
- Fluorocarbon raw material concentration:Specialty polymer feedstock production clusters in Japan and Germany create supply vulnerability. Geopolitical friction disrupts just-in-time elastomer deliveries to European compounders.
- REACH perfluorinated compound restrictions:ECHA authorization timelines limit formulation options for European-sourced seals. Alternative chemistries require multi-year validation cycles.
- Technical sealing limits in ultra-low viscosity oils:Zero-twenty and zero-sixteen grade lubricants challenge conventional lip seal designs. Material compatibility testing extends product development timelines.
Strategic Opportunities
- China domestic elastomer compounding expansion:MIIT industrial policy supports captive supply chains for high-temperature seals. Local OEMs reduce reliance on imported fluoropolymer formulations.
- Aftermarket channel digitization:North American service-dealer networks adopt direct-to-installer platforms for replacement seal distribution. Aging vehicle parcs accelerate replacement frequency.
- Thermoplastic hybrid convergence:PTFE-polyimide composite development combines injection molding economics with thermal performance. Material suppliers target crossover applications between passenger and commercial vehicle segments.
Industry Challenges
- Fluoropolymer formulation expertise scarcity:Compound development requires polymer science specialization spanning elastomer physics and tribology. Universities produce fewer graduates with seal-specific material knowledge.
- Dual certification complexity:Suppliers must validate seals against both EPA evaporative standards and EU REACH substance restrictions. Divergent regulatory timelines complicate single-platform product strategies.
Report Scope
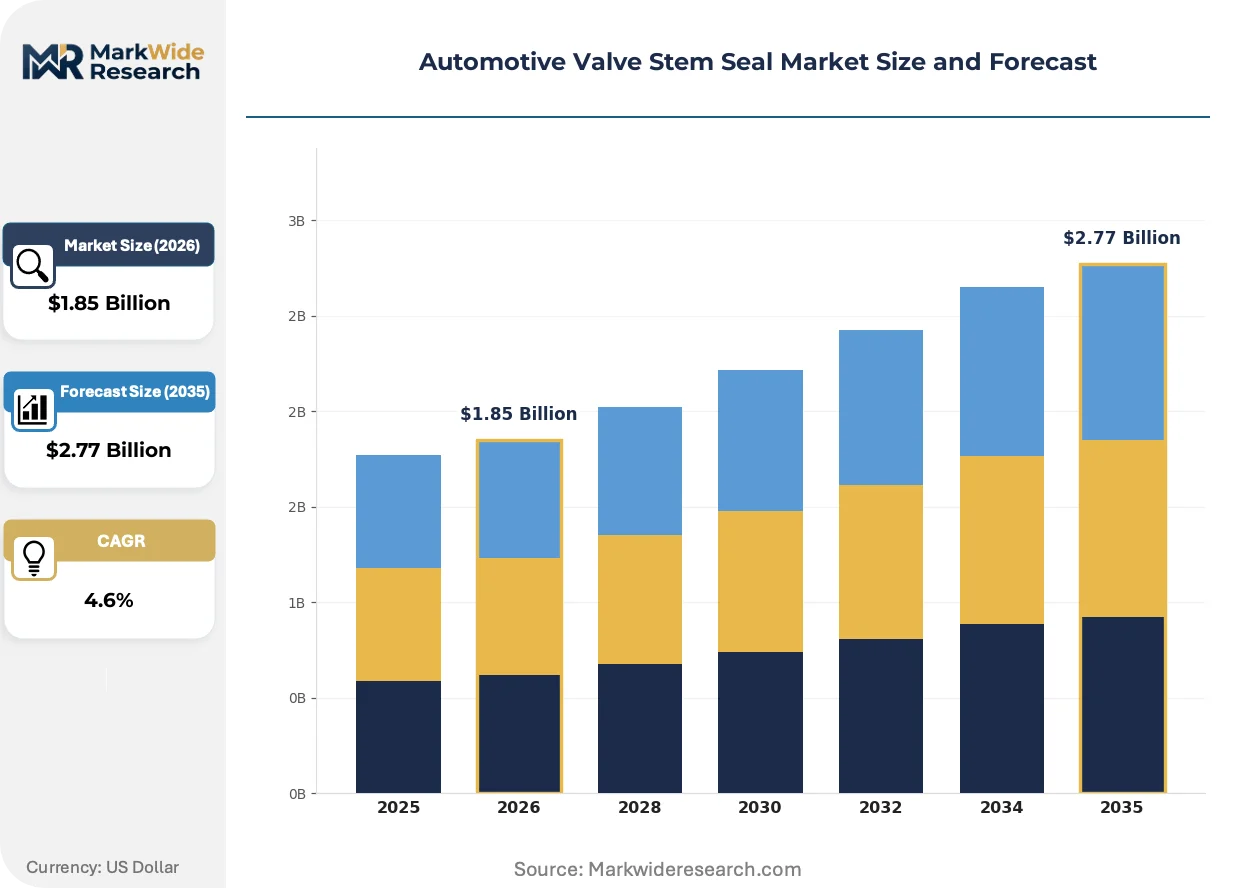
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Valve Stem Seal Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Polyurethane, Silicone, PTFE End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Component Manufacturers Installation Method: Manual, Automated, Hybrid, Remanufacturing Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks |
| Companies Covered | Trelleborg Sealing Solutions, Federal-Mogul, SKF, Freudenberg Group, Dana Incorporated, ElringKlinger, NOK-Freudenberg, Qingdao TKS, Zhong Ding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Valve Stem Seal Market Emerging Trajectories
Material science advances and regulatory divergence are fragmenting competitive positioning across geographic markets. Suppliers must now engineer region-specific formulations rather than global product platforms.
PTFE composite valve stem seals are digitizing quality assurance protocols through in-line vision inspection systems. European tier-one suppliers deploy machine learning defect detection for micron-level dimensional control. This capability compression enables zero-ppm defect rates demanded by premium OEM powertrain contracts.
REACH perfluorinated compound authorization timelines are forcing material substitution roadmaps across European supply chains. ECHA restriction proposals target long-chain fluoropolymers prevalent in high-temperature seal applications. German compounders accelerate bio-based elastomer development to preempt regulatory exclusion.
Fleet procurement teams are consolidating valve stem seal specifications across mixed-vehicle parcs. North American commercial vehicle operators negotiate single-source agreements covering both legacy diesel and emerging natural gas engines. This specification compression rewards suppliers with cross-platform material expertise.
Automotive Valve Stem Seal Market Segmentation
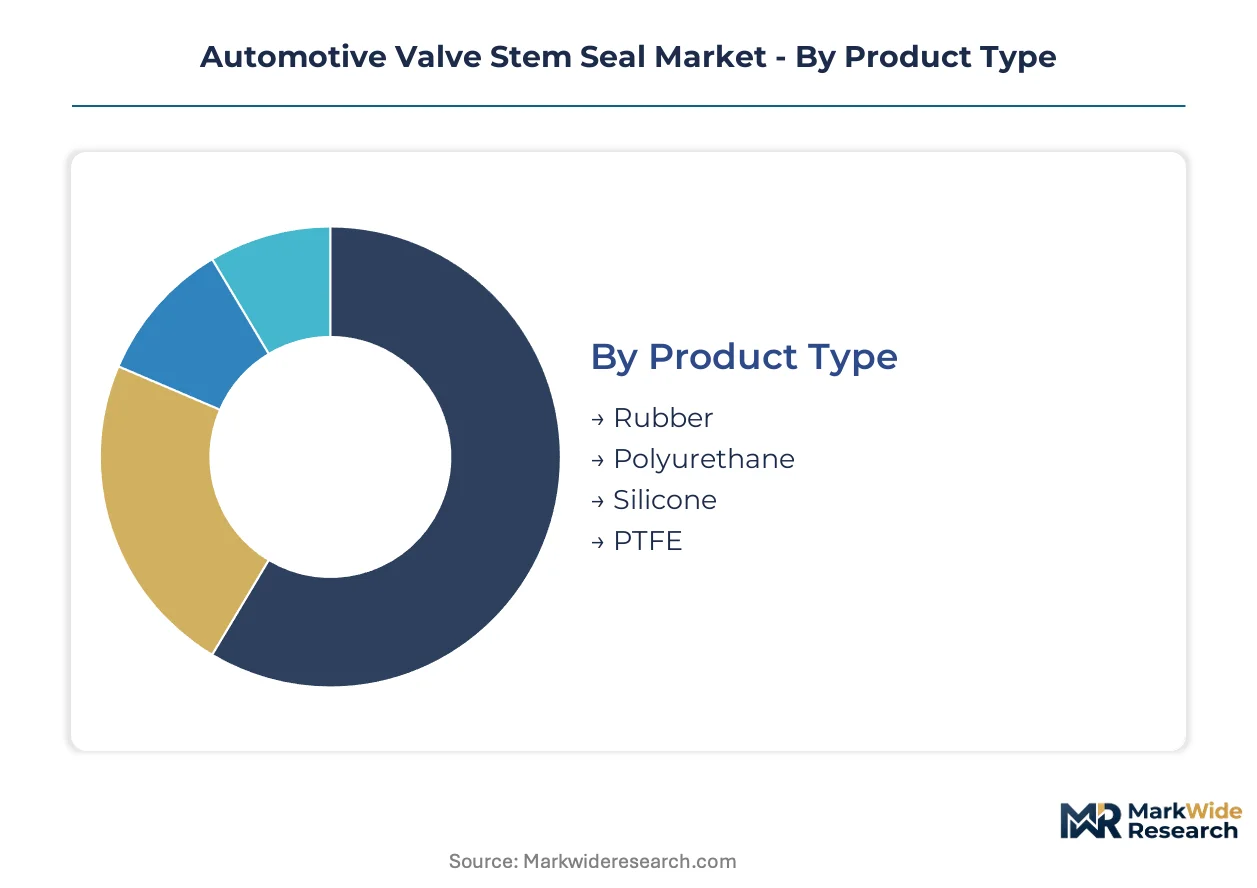
Segmentation in the automotive valve stem seal market reveals how material science, distribution channels, and installation economics fragment procurement patterns. Each dimension carries distinct margin structures and technical validation requirements that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across material formulations, with fluoropolymer-based seals demanding specialized installation tooling and warranty protocols that rubber alternatives rarely require.
- Rubber:Nitrile and hydrogenated nitrile elastomers dominate passenger vehicle platforms where cost engineering governs mass-market procurement. Southeast Asian OEMs concentrate demand here as domestic compounding capacity expands under MIIT industrial policy support.
- PTFE:Polytetrafluoroethylene composites deliver thermal stability above 230°C for downsized turbocharged cylinder heads. German heavy-duty truck fleets specify these formulations for extended drain intervals under severe thermal cycling.
- Silicone:VMQ compounds serve regional motorcycle production with cost-optimized specifications for two-wheeler valve trains.
- Polyurethane:Castable formulations occupy niche aftermarket applications requiring field-installable repair solutions.
Rubber holds the largest share; momentum sits with PTFE as thermal loads escalate across turbocharged engine architectures.
End User:
Cost tier stratification separates specification authority from purchasing execution, with vehicle assemblers wielding design control while aftermarket channels capture replacement economics.
- OEMs:Original equipment manufacturers mandate fluoropolymer validation against EPA Tier 3 crankcase pressure specifications. Powertrain engineering teams at Detroit Three and German premium brands source direct from compounders with polymer physics expertise.
- Aftermarket Providers:North American service-dealer networks concentrate margin pools in aging vehicle parcs where replacement frequency accelerates. Digital distribution platforms are compressing traditional wholesale hierarchies.
- Vehicle Assemblers:Contract manufacturers in Mexico and Thailand procure to OEM-directed specifications without formulation authority.
- Component Manufacturers:Tier-two suppliers integrate seals into camshaft and cylinder head subassemblies for modular powertrain delivery.
OEMs command specification authority; aftermarket providers are climbing the fastest on digitization and parc aging.
Installation Method:
Volume concentration in automated assembly lines creates procurement scale advantages, while remanufacturing channels serve circular economy mandates with distinct quality protocols.
- Automated:Robotic valve train assembly at BMW, Toyota, and Ford plants requires micron-level dimensional consistency. Vision inspection systems validate seal seating force and concentricity at cycle times below eight seconds.
- Manual:Low-volume specialty vehicle production and field service operations rely on technician training and torque-controlled installation fixtures.
- Hybrid:Semi-automated cells balance flexibility and throughput for medium-volume powertrain platforms.
- Remanufacturing:Engine rebuilders in the US Great Lakes region specify reclaimed seal grooves with oversize dimensions for second-life applications.
Automated installation dominates new vehicle output; remanufacturing shows steepest expansion trajectory on circular economy regulation.
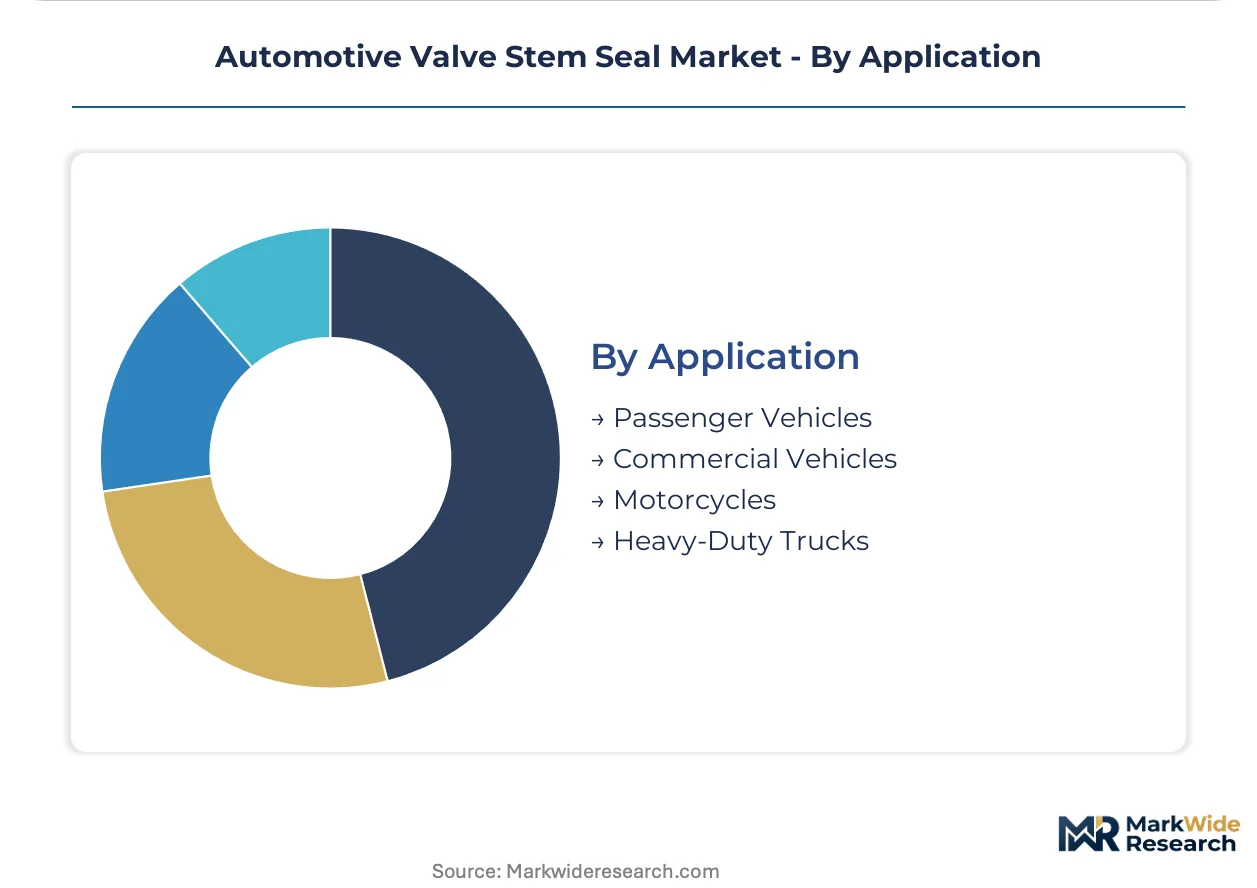
Application:
Customer type fragmentation separates fleet procurement consolidation from individual owner replacement patterns, with commercial vehicle operators negotiating multi-year supply agreements.
- Passenger Vehicles:Mass-market sedans and crossovers specify rubber or silicone formulations where thermal loads remain below 200°C. Chinese domestic brands are accelerating fluoropolymer adoption as GB standards tighten.
- Heavy-Duty Trucks:Long-haul diesel and emerging natural gas platforms demand PTFE-polyimide hybrids for thermal stability across 500,000-mile service lives. Fleet operators in Germany and the US negotiate single-source agreements covering mixed powertrain parcs.
- Commercial Vehicles:Light-duty vans and delivery trucks split procurement between passenger-vehicle derivatives and truck-grade specifications.
- Motorcycles:Southeast Asian two-wheeler production specifies cost-optimized silicone seals with simplified lip geometries for air-cooled engines.
Passenger vehicles generate largest volume; heavy-duty trucks deliver premium pricing power on performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 mandates in the United States are compressing tolerance specifications for crankcase ventilation systems, driving fluoropolymer seal adoption across Detroit Three powertrain platforms. Material suppliers must now validate formulations against both US evaporative standards and divergent European REACH restrictions.
United States
Heavy-duty truck fleets operating across the Great Lakes corridor specify PTFE-polyimide seals for 500,000-mile service intervals under severe thermal cycling. EPA enforcement of pressurized crankcase integrity standards tightens procurement specifications for valve train components. Detroit-based powertrain engineering teams source direct from compounders with polymer physics expertise.
Germany
Extended drain interval specifications from long-haul fleet operators accelerate PTFE composite adoption for downsized turbocharged diesel architectures. ECHA authorization timelines for perfluorinated compounds force German compounders toward bio-based elastomer development. Stuttgart and Munich industrial clusters concentrate formulation R&D for premium OEM powertrain contracts.
China
Domestic OEMs accelerate fluoropolymer adoption as MIIT GB standards tighten passenger vehicle fuel consumption requirements. Industrial policy supports captive elastomer compounding capacity to reduce import dependency. Yangtze River Delta manufacturing bases expand high-temperature seal production for regional motorcycle and light commercial vehicle output.
Japan
Thermal stability demands in downsized turbocharged engines drive material substitution toward PTFE composites among precision powertrain suppliers. METI industrial standards govern seal validation protocols for export-oriented vehicle production. Nagoya and Osaka industrial corridors concentrate fluorocarbon elastomer feedstock production for Asian compounder networks.
Thailand
Light commercial vehicle fleets expand procurement of fluorocarbon elastomer seals as regional emission norms tighten crankcase ventilation requirements. Silicone seal cost engineering dominates two-wheeler production for Southeast Asian export markets. Bangkok and Eastern Seaboard manufacturing zones concentrate regional motorcycle OEM supply relationships.
Automotive Valve Stem Seal Market Vendor Landscape
Capability concentration sits with European compounders possessing polymer physics and tribology expertise; scale advantage sits with Asian fabricators serving high-volume motorcycle and passenger vehicle platforms. The market structures around three tiers: premium fluoropolymer formulators, mid-tier rubber compounders, and cost-optimized silicone specialists. Dominant competitive moves include backward integration into specialty polymer feedstock production and geographic expansion of compounding capacity to serve MIIT-supported domestic supply chains in China.
Within the European formulation tier, SKF and Freudenberg Group exemplify capability-driven positioning anchored by polymer science specialization. Federal-Mogul occupies a position at the aftermarket-distribution vector, leveraging North American service-dealer channel relationships. Qingdao TKS represents the cost-optimized archetype, serving regional two-wheeler production with silicone seal specifications. These three anchors illustrate how competitive positioning fragments across material technology, channel control, and manufacturing economics.
| Leading Market Players |
|---|
| Trelleborg Sealing Solutions |
| Federal-Mogul |
| SKF |
| Freudenberg Group |
| Dana Incorporated |
| ElringKlinger |
| NOK-Freudenberg |
| Qingdao TKS |
| Zhong Ding |
| Others |
Supply Flow & Price Mechanics
The Nagoya-Osaka industrial corridor concentrates fluorocarbon elastomer feedstock production, and this geographic clustering translates into asymmetric pricing power for Japanese compounders serving Asian OEM networks. Downstream buyers in Southeast Asia face cost pass-through volatility when yen-denominated polymer contracts reset against regional currency fluctuations.
Pricing Analysis
Price spreads between German PTFE composite formulations and Chinese silicone alternatives span approximately three certification tiers based on thermal performance validation. Price differentiation rests on EPA Tier 3 compliance grading versus domestic GB standard adherence, with volume scale and after-sales warranty bundling as secondary levers. Pricing pressure stems from REACH authorization uncertainty forcing European compounders toward bio-based elastomer R&D with extended payback periods. Motorcycle OEMs in Thailand exhibit highest price sensitivity; Detroit Three powertrain engineering teams show lowest sensitivity due to performance-specification mandates.
Supply Chain Analysis
Specialty polymer feedstock production clusters in Japan, Germany, and the United States, with downstream compounding capacity expanding in China under MIIT industrial policy support. Raw material inputs draw from fluorocarbon resin synthesis, hydrogenated nitrile rubber stock, and PTFE powder grades. Single-source vulnerability concentrates around long-chain fluoropolymer precursors subject to ECHA restriction timelines. Distribution runs through direct OEM supply agreements for fluoropolymer tiers and wholesale aftermarket channels for rubber replacement seals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive valve stem seal market is entering a cyclical recovery phase as fleet replacement cycles accelerate across aging North American and Western European vehicle parcs. Extended drain interval mandates and emission standard tightening create sustained demand visibility for high-performance seal formulations.
For Market Incumbents: Insulate formulation expertise advantages through captive R&D retention in European polymer science clusters while building regional compounding footprints in China to preempt MIIT-supported domestic supply chain development. Threats from bio-based elastomer substitution and REACH regulatory exclusion require accelerated validation timelines. Backward integration into fluorocarbon feedstock production secures margin control against Japanese supply concentration. For New Entrants and Emerging Players: Mid-tier silicone seal production for Southeast Asian motorcycle OEMs represents the most penetrable entry point given lower certification barriers and expanding domestic compounding capacity. Regional two-wheeler export markets offer volume scale without fluoropolymer formulation complexity. A direct service-dealer digital distribution partnership with Bangkok-based aftermarket networks provides channel access without OEM specification authority requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with polymer physics specialization and established EPA-EU dual certification capabilities. Long-term viability over a five-to-ten year horizon depends on navigating fluoropolymer restriction divergence between regulatory jurisdictions. Acquisition targets should demonstrate cross-platform material expertise spanning passenger vehicle rubber and heavy-duty truck PTFE applications. The signal to watch is ECHA authorization timeline acceleration for long-chain fluoropolymers as an inflection indicator for bio-based substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorocarbon Feedstock | Secures supply continuity for SKF and Freudenberg against Japanese precursor concentration. |
| China Domestic Compounding Capacity Expansion | Aligns Qingdao TKS and Zhong Ding with MIIT policy support for captive regional supply chains. |
| Bio-Based Elastomer R&D Acceleration | Preempts ECHA REACH exclusion risk for German compounders serving Stuttgart OEM powertrain contracts. |
| Aftermarket Channel Digitization | Compresses wholesale hierarchies for Federal-Mogul across North American service-dealer networks. |
| PTFE-Polyimide Composite Platform Development | Targets crossover applications between BMW passenger platforms and German heavy-duty truck fleets. |
Methodological Framework
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on material substitution trends. Primary fieldwork engaged Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributor operations heads, and compounder R&D directors across Germany, China, Japan, and the United States. Secondary sources included EPA enforcement documentation, ECHA authorization timelines, MIIT GB standard publications, and vehicle production databases from IHS Markit. Bottom-up seal demand modeling and top-down elastomer consumption triangulation ensured convergence.
Calibration against historical thermal load specification shifts and regulatory implementation lags structured the projection framework. Segmentation dimensions spanned material formulation, end-user channel, installation method, and vehicle application class across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating downsized turbocharged engine penetration rates and extended drain interval adoption curves. Industry-specific inputs included crankcase pressure specification tightening schedules and fleet replacement cycle timing.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle fleet utilization rates and regional currency volatility would shift the trajectory. Forecasts embed assumptions around REACH authorization timeline adherence and MIIT industrial policy continuity. Cross-checking against IHS Markit vehicle parc aging data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Fluid Couplings Market