
 Automotive Oil and Valve Stem Seals Market | 2026-2036
Automotive Oil and Valve Stem Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil and Valve Stem Seals Market Insights
Aftermarket service revenue is reconfiguring how margin pools migrate from original equipment supply toward replacement and retrofit channels. Freudenberg Sealing Technologies leverages its fluoroelastomer compound expertise to anchor premium aftermarket positions. SKF Group sustains manufacturing scale across multi-material seal platforms for both passenger and commercial vehicle applications. Federal-Mogul LLC competes through geographic dominance in North American heavy-duty engine rebuild networks.
Automotive oil and valve stem seals are precision-molded elastomeric or composite components engineered to prevent lubricant leakage past valve stems while maintaining combustion pressure integrity, typically operating within temperature ranges from minus forty degrees Celsius to over two hundred degrees Celsius depending on material grade. Their primary industrial purpose is to ensure engine emission compliance and oil consumption control across internal combustion and hybrid powertrain architectures. Rubber seals occupy the largest volume share due to cost-efficient nitrile formulations in standard passenger vehicle applications, while fluoroelastomer segments command premium positioning as turbocharged direct-injection engines escalate thermal loads. Aftermarket Providers represent a structurally expanding channel as vehicle aging fleets and extended drain intervals accelerate seal replacement frequency outside warranty periods.
EPA tailpipe emissions frameworks and EU F-Gas Regulation are reshaping material qualification requirements for seal compounds used in engine compartments. NHTSA durability standards and China's GB automotive standards collectively elevate testing protocols for oil seal performance under thermal cycling stress. Stakeholders must monitor how electrification transitions alter seal count per powertrain and whether hybrid architectures sustain demand for high-temperature fluoroelastomer formulations.
Market Dynamics
Electrified powertrain diffusion is fragmenting seal demand as hybrid architectures retain internal combustion thermal loads while battery-electric platforms eliminate valve train assemblies entirely, forcing compound suppliers to recalibrate volume forecasts across divergent propulsion technologies.
Growth Catalysts
- Turbocharger penetration:Downsized direct-injection gasoline engines escalate cylinder head temperatures, expanding fluoroelastomer seal specifications in passenger vehicle powertrains.
- EPA Tier 3 emissions frameworks:Oil consumption limits tighten to 0.5 grams per mile, mandating precision seal tolerances that accelerate premium material adoption across US vehicle fleets.
- China engine localization:Domestic automakers expand proprietary four-cylinder platform volumes, concentrating seal procurement with local tier suppliers in Jiangsu and Zhejiang manufacturing clusters.
Market Restraints
- Fluoropolymer feedstock volatility:Hexafluoropropylene monomer supply concentrates with three chemical conglomerates, exposing compounders to price swings that compress formulation margins.
- Electrification displacement:Battery-electric powertrains eliminate valve stem seals entirely, structurally capping long-term addressable volume in passenger vehicle segments.
- REACH substance restrictions:ECHA candidate list expansions for per- and polyfluoroalkyl substances force reformulation timelines that delay new product qualifications.
Strategic Opportunities
- Commercial vehicle aftermarket:Heavy-duty engine rebuild cycles in North American freight fleets sustain replacement seal demand outside OEM warranty periods.
- India emission escalation:Bharat Stage VI Phase II implementation tightens oil consumption limits, opening specification upgrades for nitrile-to-fluoroelastomer conversions.
- Thermal management convergence:Hybrid powertrain integration of electric motor cooling with combustion thermal circuits creates multi-seal module opportunities.
Industry Challenges
- Compound qualification timelines:OEM validation protocols for new fluoroelastomer grades extend 18-24 months, freezing supplier switching decisions across platform cycles.
- Tooling capex intensity:Precision injection molds for multi-lip seal geometries require six-figure capital commitments per cavity, constraining mid-tier supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil and Valve Stem Seals Market |
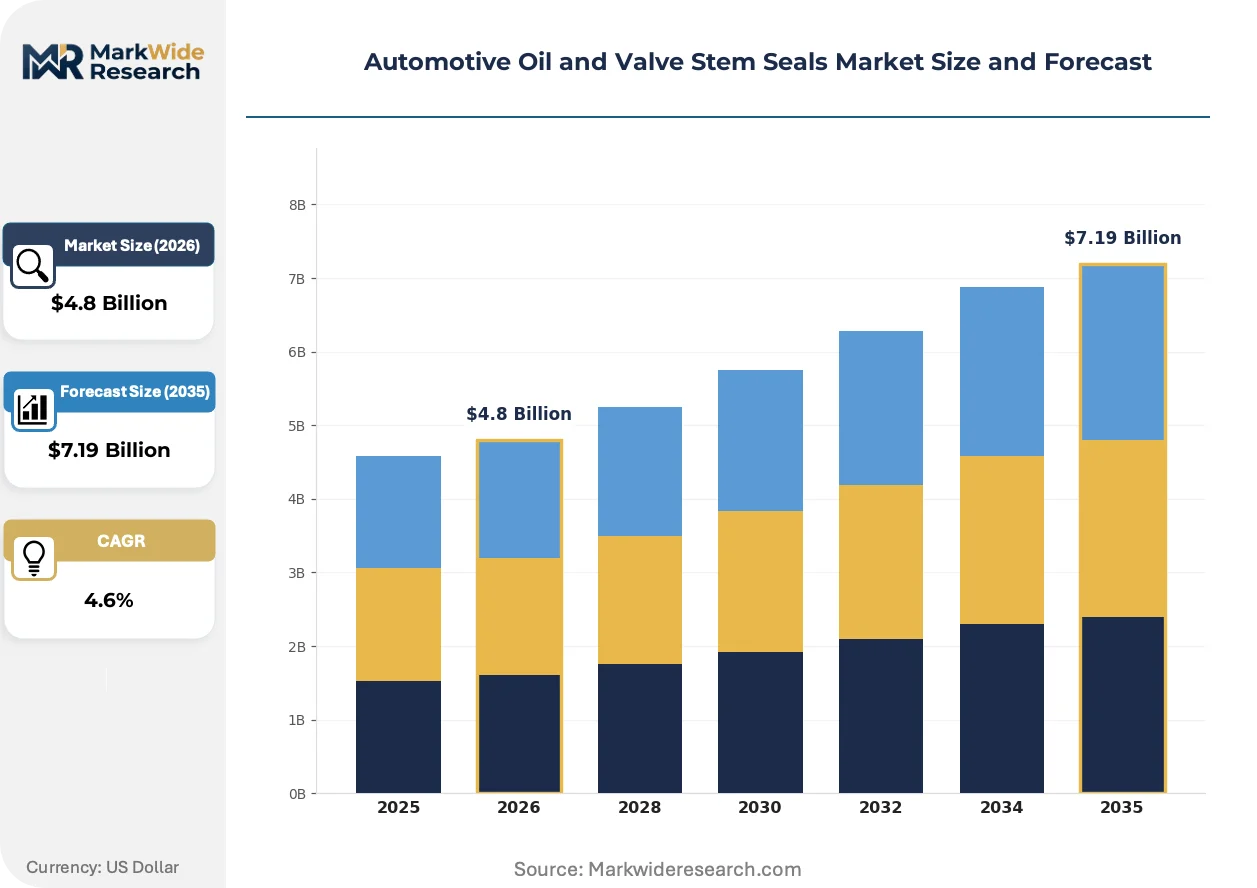
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Seals, Metal Seals, Composite Seals, Silicone Seals End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Installation: Original Equipment, Retrofit, Repair, Custom Material: Nitrile, Fluoroelastomer, Polyurethane, Others |
| Companies Covered | SKF Group, Freudenberg Sealing Technologies, Federal-Mogul LLC, Dana Incorporated, NOK Corporation, ElringKlinger AG, Trelleborg AB, Hutchinson, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil and Valve Stem Seals Market Trends and Innovations
Material science advances and regulatory tightening are compressing traditional seal design cycles while opening specification tiers that reward thermal performance differentiation over commodity cost positioning.
Multi-layer composite seal architectures combining PTFE friction surfaces with fluoroelastomer cores are virtualizing traditional single-material designs in high-temperature turbocharged applications. German powertrain engineers specify these configurations for direct-injection gasoline engines exceeding 220°C valve stem temperatures. The technology is virtualizing established nitrile-dominated supply relationships by enabling compounders to capture value through material integration rather than volume scale.
EU F-Gas Regulation amendments restrict hydrofluorocarbon propellants in seal manufacturing processes, forcing compounders to adopt water-based dispersion systems for fluoroelastomer curing. German and French seal producers face 2027 compliance deadlines that compress process revalidation schedules. Commercial vehicle engine manufacturers in the EU respond by consolidating supplier panels to those with certified low-GWP production lines.
Fleet operators in North American long-haul trucking are unbundling seal replacement from full engine overhaul contracts, creating discrete aftermarket procurement events. Independent repair networks capture this volume through direct distributor relationships that bypass traditional OEM captive parts channels. This pattern concentrates most visibly in Texas and California freight corridors where vehicle utilization rates accelerate wear-cycle frequency.
Automotive Oil and Valve Stem Seals Market Segmentation
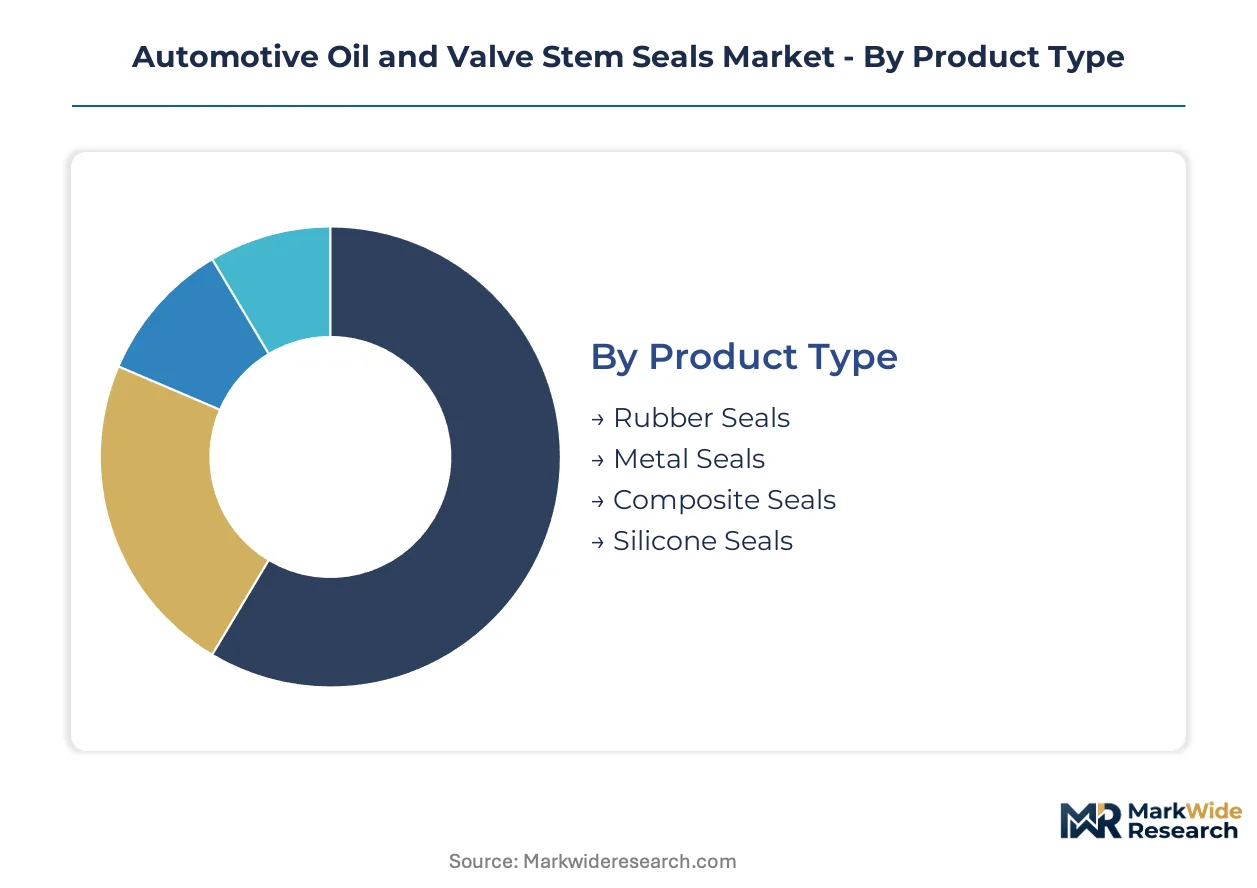
Seal specification tiers diverge sharply across powertrain architectures and service channels. Material selection and installation context determine margin capture, with thermal load requirements fragmenting traditional commodity supply relationships.
Product Type:
Cost tier positioning separates commodity elastomer formulations from engineered multi-material systems designed for extreme thermal cycling.
- Rubber Seals:Nitrile and hydrogenated nitrile formulations dominate standard passenger vehicle applications where cylinder head temperatures remain below 150°C. Demand concentrates in Chinese domestic automaker supply chains as localization policies redirect procurement toward Jiangsu-based molders.
- Composite Seals:PTFE-friction-layer bonded to fluoroelastomer cores withstand valve stem temperatures exceeding 220°C in turbocharged direct-injection engines. German and Japanese powertrain engineers specify these configurations for downsized gasoline architectures where thermal loads exceed conventional rubber limits.
- Metal Seals:Stainless steel or aluminum carriers with elastomeric coatings serve heavy-duty diesel applications requiring mechanical stability under sustained vibration.
- Silicone Seals:VMQ formulations occupy niche cold-climate specifications where flexibility retention at minus forty degrees Celsius outweighs premium material costs.
Rubber Seals commands the established base. The steepest expansion runs through Composite Seals.
End User:
Customer type determines pricing power and qualification timelines, with captive OEM channels diverging from independent aftermarket procurement patterns.
- OEMs:Vehicle manufacturers specify seal compounds during platform development cycles, locking suppliers into 5-7 year production agreements validated through NHTSA durability protocols and EPA emissions testing.
- Aftermarket Providers:Independent distributors and repair networks capture replacement demand outside warranty periods, particularly in North American heavy-duty freight corridors where engine rebuild cycles accelerate seal consumption.
- Tier-1 Suppliers:Modular powertrain integrators consolidate seal procurement within larger thermal management assemblies, reducing discrete component sourcing decisions.
- Dealerships:Authorized service channels retain captive parts revenue for in-warranty repairs, though extended drain intervals compress replacement frequency.
OEMs anchor volume scale. Aftermarket Providers is gaining share fastest as fleet aging extends replacement windows.
Installation:
Application context dictates tooling requirements and technical service intensity, with factory-line specifications diverging from field-installation constraints.
- Original Equipment:High-speed automated assembly lines demand precision-molded seals with dimensional tolerances below 0.05 millimeters, qualified through PPAP protocols.
- Retrofit:Engine upgrade programs for emission compliance or performance enhancement require seal kits compatible with legacy cylinder head geometries.
- Repair:Field replacement of failed seals during engine service drives demand for installation-friendly designs with integrated guide sleeves.
- Custom:Racing and specialty vehicle builders specify bespoke seal dimensions for non-standard valve train configurations.
Original Equipment dominates manufacturing scale. Repair is climbing the fastest as vehicle parc aging accelerates service bay throughput.
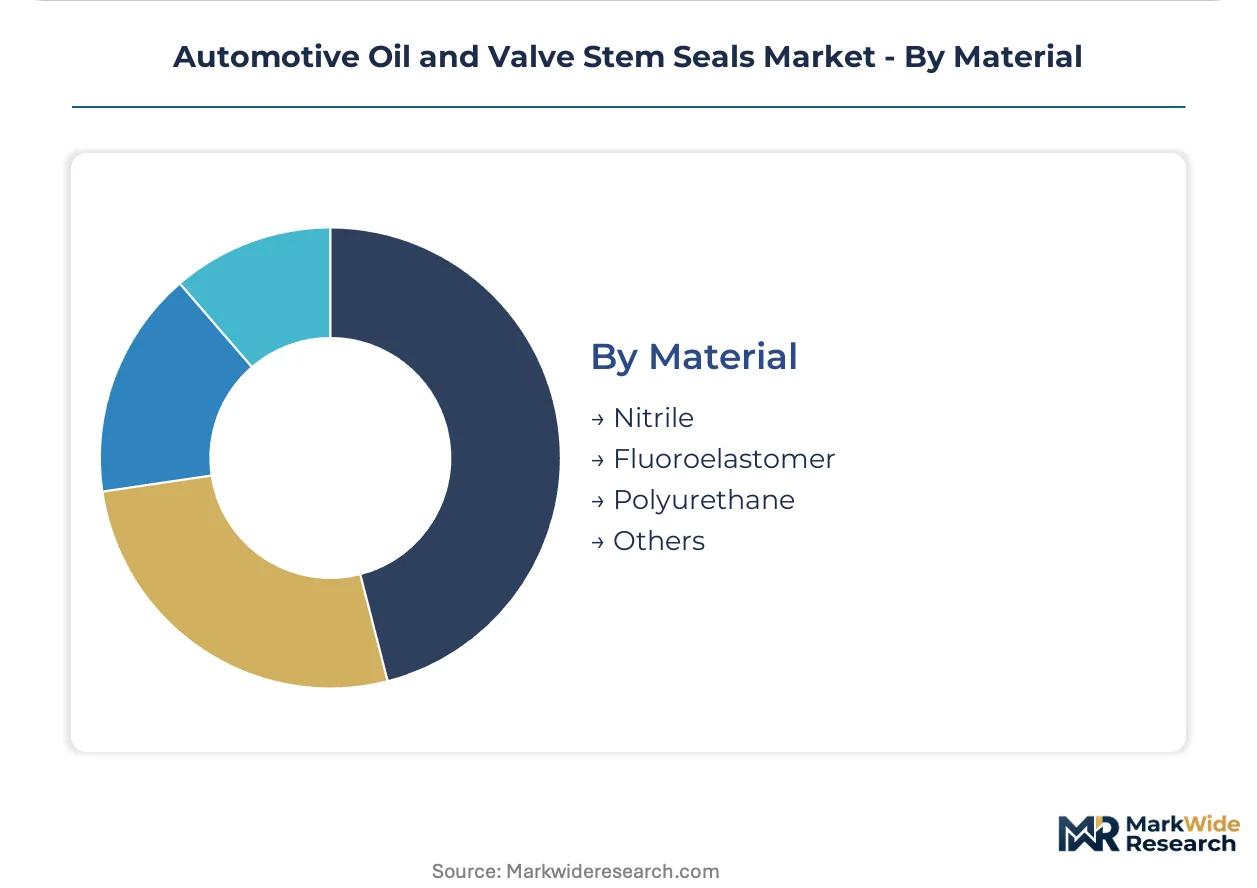
Material:
Performance grade determines thermal ceiling and chemical resistance, with specification upgrades tracking turbocharger penetration and emission tightening.
- Nitrile:NBR and HNBR compounds serve cost-sensitive applications where operating temperatures remain within 120-150°C ranges, retaining dominance in entry-level passenger vehicles.
- Fluoroelastomer:FKM formulations withstand 200°C-plus thermal loads and aggressive lubricant additives, commanding premium positioning in turbocharged gasoline and diesel architectures. EPA Tier 3 oil consumption limits and Bharat Stage VI Phase II standards in India are accelerating specification conversions from nitrile bases.
- Polyurethane:AU and EU grades offer abrasion resistance for high-cycle valve train applications, though thermal limits constrain adoption in modern downsized engines.
- Others:Ethylene acrylic and specialty perfluoroelastomer compounds serve extreme chemical exposure environments in alternative fuel powertrains.
Nitrile retains volume leadership. Fluoroelastomer is expanding most quickly as thermal management requirements escalate across powertrain architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes valve stem seals for high-volume domestic engine platforms while Germany and the United States concentrate demand in premium turbocharged architectures with extended thermal specifications.
China
Domestic automakers expand proprietary four-cylinder engine volumes for mass-market SUVs and sedans. GB automotive standards from SAMR tighten oil consumption testing protocols for locally assembled powertrains. Seal procurement concentrates in Jiangsu and Zhejiang manufacturing clusters where tier suppliers localize fluoroelastomer compounding operations.
Germany
Downsized direct-injection gasoline engines from Stuttgart and Munich engineering centers push valve stem temperatures past 220°C. KBA enforces EU F-Gas Regulation compliance for low-GWP manufacturing processes in seal production. Baden-Württemberg hosts precision molders serving both passenger vehicle OEMs and commercial vehicle retrofit channels.
United States
EPA Tier 3 oil consumption limits of 0.5 grams per mile mandate precision seal tolerances across Detroit Three vehicle fleets. NHTSA durability standards extend validation cycles for thermal cycling performance. Texas and California freight corridors generate concentrated aftermarket demand as long-haul operators unbundle seal replacement from full engine rebuilds.
Japan
Hybrid powertrain architectures sustain demand for high-temperature fluoroelastomer formulations alongside thermal management integration. METI coordinates JIS standard updates for seal performance under electrified powertrain thermal loads. Kanto region molders supply both domestic OEMs and export-oriented tier-one integrators.
India
Bharat Stage VI Phase II implementation tightens oil consumption limits for commercial and passenger vehicle segments. BIS accelerates adoption of nitrile-to-fluoroelastomer specification upgrades. Tamil Nadu and Maharashtra manufacturing hubs attract seal suppliers targeting domestic automaker localization programs.
Automotive Oil and Valve Stem Seals Market Competitive Landscape
Capability concentration sits with compound specialists who command premium fluoroelastomer formulations; scale advantage sits with multi-material platform suppliers serving diversified powertrain portfolios. The vendor base organizes into three tiers: integrated seal-to-system providers, specialized compounders with captive polymer expertise, and regional molders serving cost-sensitive procurement channels. Dominant competitive moves include backward integration into polymer feedstock operations and geographic expansion through distributor network capture in heavy-duty aftermarket corridors.
Within the integrated-system tier, SKF Group and Freudenberg Sealing Technologies occupy positions that span both OEM specification authority and aftermarket channel control. Federal-Mogul LLC anchors the North American heavy-duty rebuild network archetype. These three represent distinct strategic postures: the Swedish-originated multinational with bearing-to-seal platform breadth; the German family-owned compound specialist with century-long fluoroelastomer heritage; and the US-based aftermarket channel consolidator with freight corridor density.
| Leading Market Players |
|---|
| SKF Group |
| Freudenberg Sealing Technologies |
| Federal-Mogul LLC |
| Dana Incorporated |
| NOK Corporation |
| ElringKlinger AG |
| Trelleborg AB |
| Hutchinson |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Hexafluoropropylene monomer supply concentrates with three chemical conglomerates in Germany, Japan, and the United States, anchoring premium fluoroelastomer pricing power with compounders who command specification authority in turbocharged engine programs. This upstream tightness feeds downstream margin capture by seal manufacturers with captive polymer expertise, while nitrile compounders compete on volume scale in cost-sensitive procurement channels.
Pricing Analysis
Long-term offtake agreements dominate OEM supply relationships, locking compounders into five-to-seven-year production contracts validated through NHTSA durability protocols. Price differentiation rests on thermal grade certification and volume scale, with FKM formulations commanding substantial premiums over nitrile bases. Pricing pressure stems from electrification displacement as battery-electric platforms eliminate valve train assemblies entirely, compressing addressable volume in passenger segments. Fleet operators in North American freight corridors exhibit lowest price sensitivity due to unbundled procurement patterns, while Chinese domestic automakers drive hardest negotiation on standard-grade rubber seals.
Supply Chain Analysis
Export-control regimes on fluoropolymer precursor technologies limit technology transfer to emerging compounders in India and Southeast Asia, constraining supply base expansion. Manufacturing concentrates in Germany, China, and Japan, with Jiangsu and Zhejiang clusters serving localized procurement for domestic Chinese automakers. Raw material dependencies center on hexafluoropropylene monomer, fluoroelastomer base polymers, and precision mold tooling. Single-source vulnerability runs through the three-company monomer oligopoly. Distribution runs through tier-one integrators for OEM channels and independent distributor networks for aftermarket rebuild corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated OEM platform engineering teams and unbundled fleet procurement networks, fragmenting traditional supplier pricing leverage across warranty and post-warranty service windows.
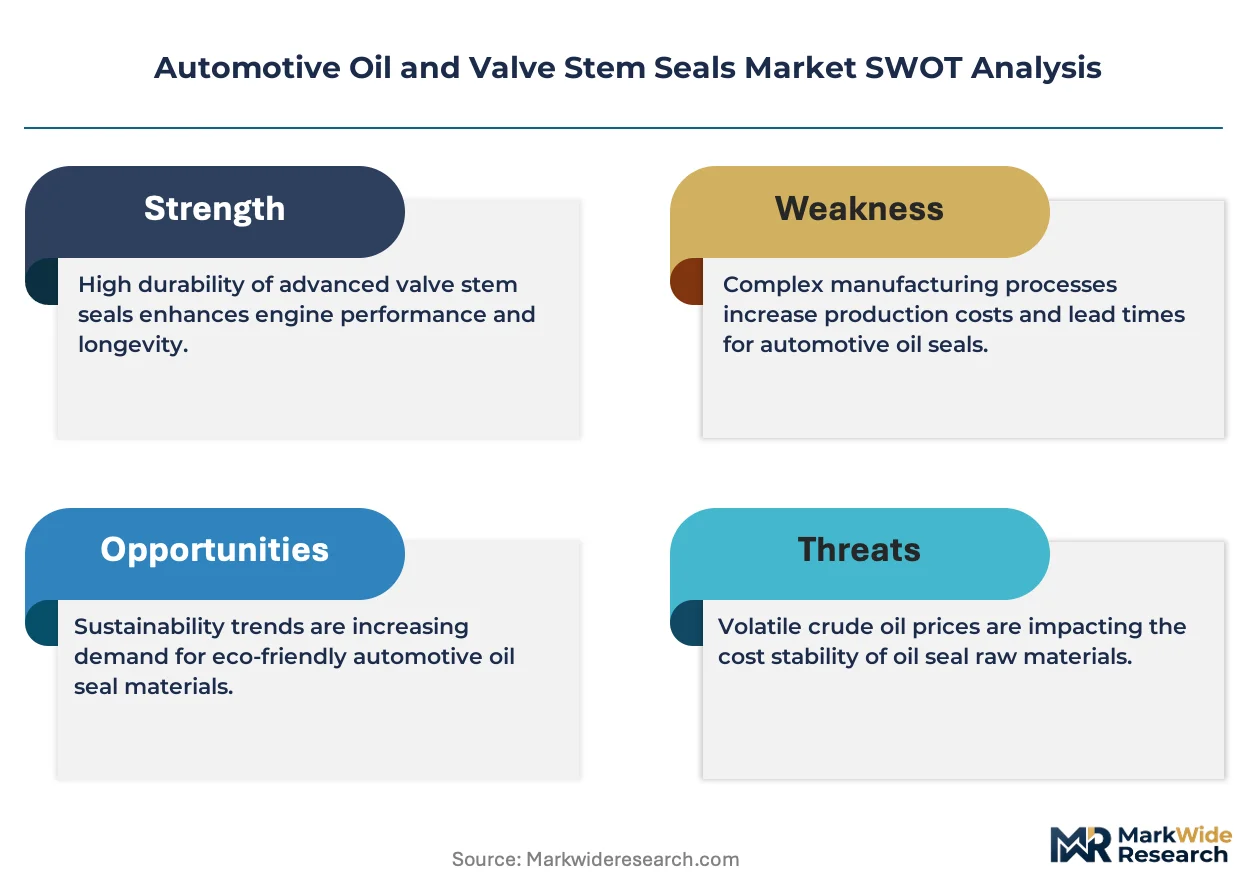
For Market Incumbents: Pre-empt specification displacement by embedding fluoroelastomer expertise into hybrid thermal management modules before electrification eliminates discrete valve train demand. Deepen backward integration into hexafluoropropylene feedstock operations to defend margin position against monomer price volatility. Secure KBA-certified low-GWP production lines ahead of EU F-Gas Regulation deadlines to consolidate supplier panels. For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra manufacturing hubs offer underpenetrated entry points as Bharat Stage VI Phase II implementation forces nitrile-to-FKM specification upgrades. Target commercial vehicle aftermarket distributors in Texas and California freight corridors where engine rebuild cycles sustain replacement demand outside OEM warranty networks. Pursue direct distributor relationships that bypass traditional captive parts channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive seal specialists lacking fluoroelastomer compounding capabilities. Long-term viability hinges on exposure to hybrid powertrain architectures that retain thermal management complexity. Monitor EPA Tier 3 enforcement intensity and China engine localization velocity as inflection indicators for specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstock | Captive hexafluoropropylene supply insulates compounders from monomer oligopoly pricing volatility. |
| Low-GWP Manufacturing Certification | KBA-validated water-based dispersion systems unlock EU commercial vehicle supplier panel consolidation. |
| Hybrid Thermal Management Module Development | Multi-seal integration captures value as electrification fragments traditional valve train demand. |
| Aftermarket Distributor Network Capture | Direct relationships with Texas and California freight operators bypass OEM captive parts channels. |
| India Localization Manufacturing Footprint | Tamil Nadu and Maharashtra hubs position suppliers for Bharat Stage VI Phase II specification upgrades. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fluoroelastomer compound R&D directors; and secondary validation through customs trade data, SEC 10-K filings, vehicle production databases, and EPA emissions compliance records. Bottom-up seal demand modeling triangulated against top-down powertrain production forecasts across the analysis window.
Forecast inputs considered propulsion architecture segmentation, thermal grade specification tiers, regional regulatory compliance clusters, and content-per-vehicle trajectories for hybrid versus battery-electric platforms. CAGRs derived from modeled volume outputs across material grade and installation context dimensions, with specific weighting applied to turbocharger penetration rates and emission standard implementation timelines.
Practitioners should monitor EPA Tier 3 enforcement patterns, EU F-Gas Regulation amendment trajectories, and China domestic engine platform localization velocity for early signals of forecast revision. Material shifts in electrification adoption curves or fluoroelastomer feedstock supply consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Automotive Trailing Arm Market