
 North America Ceramic Ball Bearings Market | 2026-2036
North America Ceramic Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceramic Ball Bearings Market Intelligence
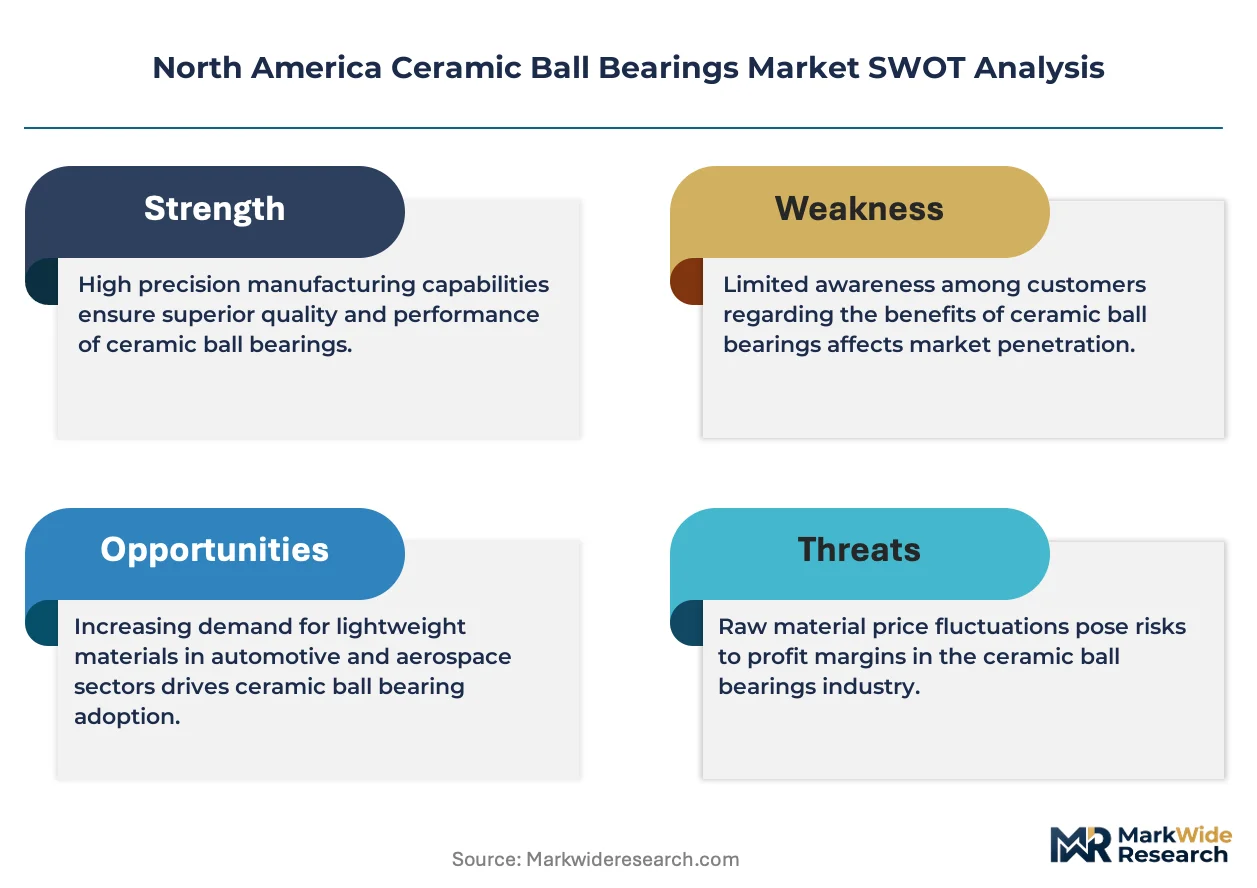
A shortage of precision grinding technicians is rotating factory capacity decisions across the region. AB SKF leverages its captive silicon nitride supply chain to secure raw material continuity. NSK Ltd. anchors its North American position through dedicated ceramic bearing R&D facilities in Indiana. Schaeffler competes by specializing in custom hybrid configurations for medical device OEMs.
North America ceramic ball bearings are rolling-element bearings with balls fabricated from silicon nitride, zirconia, or alumina ceramics, operating at temperatures exceeding 500°C with near-zero thermal expansion and corrosion resistance against aggressive chemical environments. Their primary purpose is to eliminate lubrication failure modes and extend maintenance intervals in extreme-duty rotating machinery. Hybrid bearings dominate current volume shipments due to their cost-performance balance against full ceramic alternatives. Medical device applications represent the fastest-expanding demand pool, driven by MRI-compatible and sterilization-resistant requirements. The miniature size category commands premium positioning in surgical robotics and dental turbine handpiece markets.
The FAA certifies ceramic bearing installations in commercial aviation propulsion systems under rigorous fatigue-life protocols, while FDA 21 CFR Part 820 quality system regulations govern medical-grade bearing traceability and biocompatibility documentation. NHTSA fuel economy mandates indirectly accelerate ceramic bearing adoption in electric vehicle powertrains by rewarding friction reduction technologies. Stakeholders must weigh capital allocation between captive ceramic powder production and strategic sourcing partnerships as supply security becomes the decisive competitive variable.
Market Dynamics
EPA industrial emissions standards are compressing maintenance windows across Great Lakes manufacturing, forcing capital-intensive bearing swaps toward ceramic solutions that eliminate lubrication failure modes entirely.
Growth Catalysts
- FAA Fatigue-Life Certification:Commercial aviation propulsion systems now mandate ceramic bearing installations under rigorous endurance protocols, expanding aerospace OEM procurement.
- Silicon Nitride Material Properties:Near-zero thermal expansion and 500°C+ operating thresholds eliminate thermal seizure risks in extreme-duty rotating machinery.
- Great Lakes Manufacturing Corridor:Concentrated demand from Michigan, Ohio, and Illinois machine tool builders anchors regional volume absorption.
Market Restraints
- Precision Grinding Technician Scarcity:Factory capacity decisions rotate around qualified labor pools, constraining output scaling regardless of capital availability.
- Silicon Nitride Powder Concentration:Captive supply chains dominate raw material continuity, locking out mid-tier competitors from cost-competitive sourcing.
- Full Ceramic Cost Premium:Hybrid configurations retain volume dominance due to prohibitive pricing of all-ceramic alternatives for standard industrial duty cycles.
Strategic Opportunities
- Surgical Robotics Miniaturization:Dental turbine handpiece and robotic surgery platforms demand sub-millimeter ceramic bearings with MRI compatibility.
- NHTSA Fuel Economy Mandates:Electric vehicle powertrain friction reduction technologies receive regulatory credit rewards, accelerating ceramic adoption.
- Hybrid Configuration Customization:Medical device OEMs seek application-specific material pairings between ceramic balls and specialized raceway alloys.
Industry Challenges
- FDA 21 CFR Part 820 Traceability:Medical-grade bearing documentation demands biocompatibility certification timelines that extend product development cycles.
- Legacy Equipment Retrofit Integration:Existing machinery housing geometries constrain ceramic bearing dimensional standardization, forcing custom engineering per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceramic Ball Bearings Market |
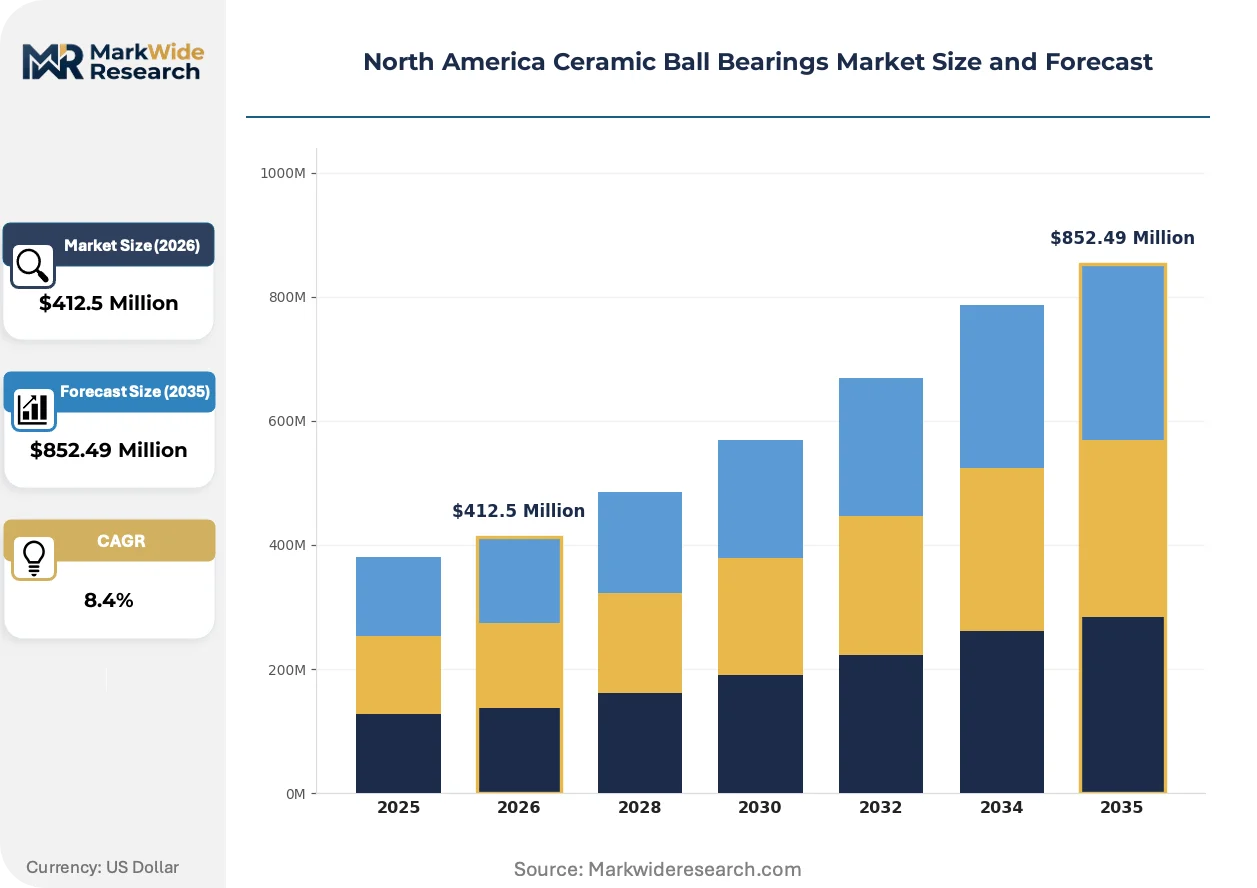
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Ceramic, Hybrid, Stainless Steel, Plastic End User: Aerospace, Automotive, Healthcare, Industrial Application: Robotics, Electric Motors, Pumps, Medical Devices Size: Miniature, Standard, Large, Specialty |
| Companies Covered | AB SKF, NSK Ltd., NTN Corporation, JTEKT Corporation, Schaeffler, CeramicSpeed, Boca Bearings, Inc., GMN Bearing USA Ltd., Ortech Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceramic Ball Bearings Market Strategic Shifts & Innovations
Material science advances and regulatory compression are rewriting bearing specification criteria across North American industrial verticals, with ceramic solutions capturing priority positioning in precision-critical applications.
Silicon nitride ball fabrication is miniaturizing surgical instrument bearings to sub-2mm diameters while maintaining load ratings. Dental turbine manufacturers in Minnesota and California are adopting these micro-scale units for 400,000+ RPM sterilizable handpieces. The dimensional threshold compression is miniaturizing entire instrument categories previously constrained by steel bearing thermal limits.
NHTSA Corporate Average Fuel Economy standards indirectly accelerate ceramic bearing integration into electric vehicle reduction gearboxes. Friction coefficient advantages translate directly into range extension credits under compliance calculations. California and Michigan powertrain engineering centers now specify hybrid ceramic configurations as baseline for new platform development.
After-sales service unbundling is fragmenting traditional distribution relationships across the region. Machine tool operators in Illinois and Ohio now source ceramic bearing replacements directly from specialized distributors rather than OEM captive channels. The disintermediation concentrates in high-frequency maintenance environments where downtime costs exceed premium component pricing.
North America Ceramic Ball Bearings Market Segmentation
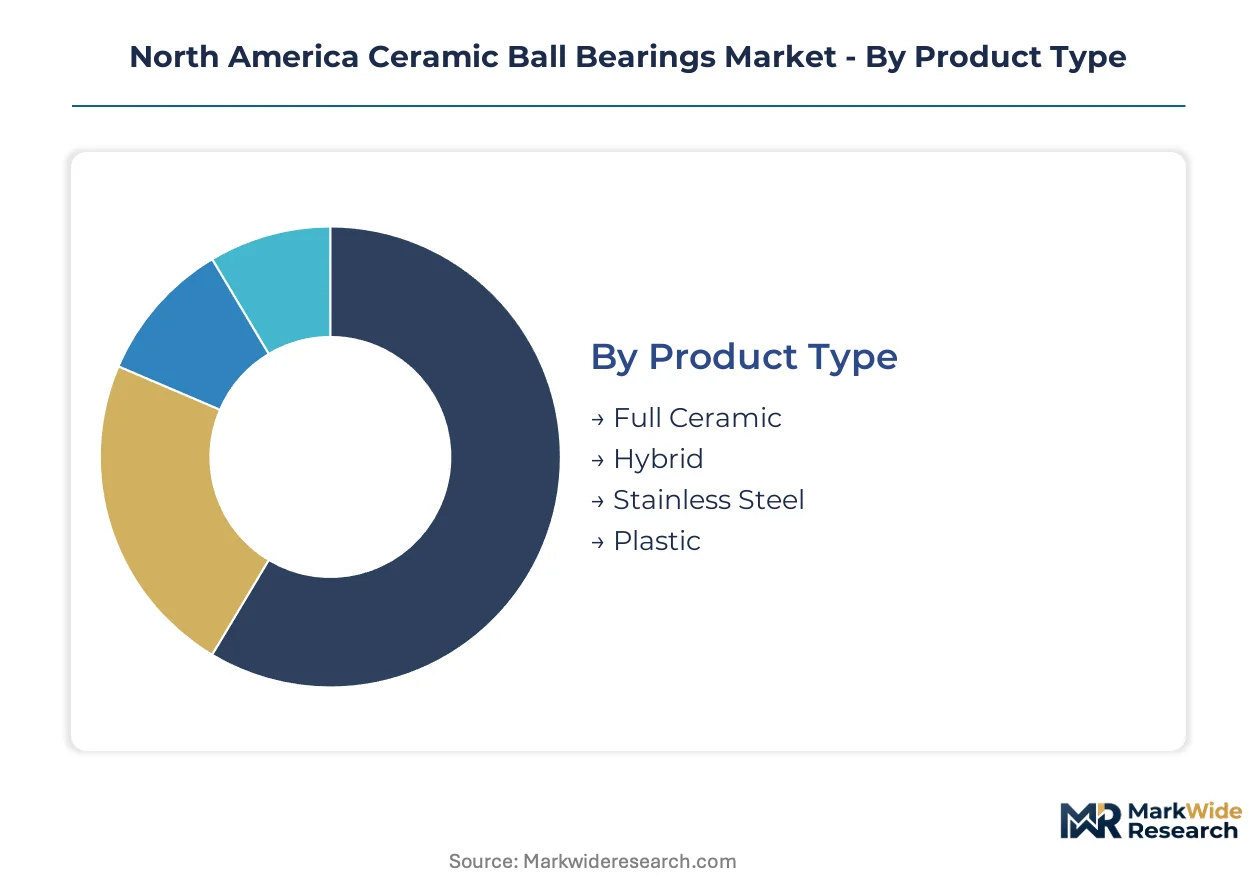
Ceramic ball bearing specifications diverge sharply across North American end-use verticals, with FAA fatigue-life protocols, FDA biocompatibility mandates, and NHTSA fuel economy credits each imposing distinct material and dimensional requirements. Procurement patterns cluster around hybrid configurations for cost-sensitive industrial applications while full ceramic and miniature formats command premium positioning in regulated medical and aerospace environments.
Product Type:
FAA certification requirements for commercial aviation propulsion systems and FDA 21 CFR Part 820 traceability mandates create divergent material qualification pathways across ceramic bearing categories.
- Full Ceramic:Silicon nitride or zirconia construction delivers 500°C+ thermal tolerance and absolute corrosion immunity for chemical processing and semiconductor manufacturing. Demand concentrates in Texas and Arizona wafer fabrication facilities where EPA emissions standards prohibit lubricant contamination risks.
- Hybrid:Ceramic balls paired with steel raceways balance cost-performance for electric vehicle powertrains and machine tool spindles. Michigan and Ohio automotive engineering centers specify these configurations under NHTSA fuel economy compliance frameworks.
- Stainless Steel:Conventional metallurgy retains position in legacy industrial equipment where thermal loads remain moderate and capital replacement cycles extend.
- Plastic:Polymer raceways with ceramic elements serve lightweight, non-magnetic requirements in specialized instrumentation and laboratory automation.
Hybrid configurations handle the majority of throughput; full ceramic is the fastest mover on share.
End User:
Customer procurement scale and technical specification authority vary dramatically across verticals, with OEM captive engineering teams driving aerospace and automotive requirements while healthcare distributors mediate medical device specifications.
- Aerospace:Jet engine OEMs in Connecticut and California mandate FAA-certified ceramic bearings for main shaft and accessory drive applications. Fatigue-life protocols under Part 33 airworthiness standards eliminate steel alternatives for new propulsion platforms.
- Healthcare:MRI compatibility and autoclave sterilization resistance position ceramic bearings in surgical robotics and dental handpieces. Minnesota and Massachusetts device manufacturers source sub-millimeter formats through specialized distributors.
- Automotive:Electric vehicle reduction gearbox specifications in Michigan and California engineering centers prioritize friction reduction for range extension credits.
- Industrial:Machine tool builders across Illinois and Ohio specify hybrid configurations for high-speed spindles where thermal seizure risks compromise steel bearing longevity.
Aerospace commands the highest specification authority; healthcare is expanding most quickly.
Application:
Rotational speed requirements and environmental exposure profiles determine ceramic bearing selection, with miniature formats dominating precision motion systems while larger units serve fluid handling infrastructure.
- Medical Devices:Dental turbine handpieces and surgical robotic joints demand sub-2mm silicon nitride balls rated for 400,000+ RPM and repeated sterilization cycles. California and Minnesota manufacturers qualify suppliers against FDA biocompatibility documentation requirements.
- Electric Motors:Traction motors and high-speed spindle drives in Michigan automotive plants specify hybrid ceramic bearings to eliminate electrical pitting and extend maintenance intervals.
- Robotics:Collaborative and surgical robot joint actuators require precision positioning with zero backlash, favoring ceramic ball configurations for repeatability under cyclic loading.
- Pumps:Chemical and pharmaceutical fluid handling systems in New Jersey and North Carolina specify full ceramic bearings for aggressive media compatibility and zero lubricant contamination.
Medical devices concentrate the highest value per unit; electric motors absorb the greatest absolute volume.
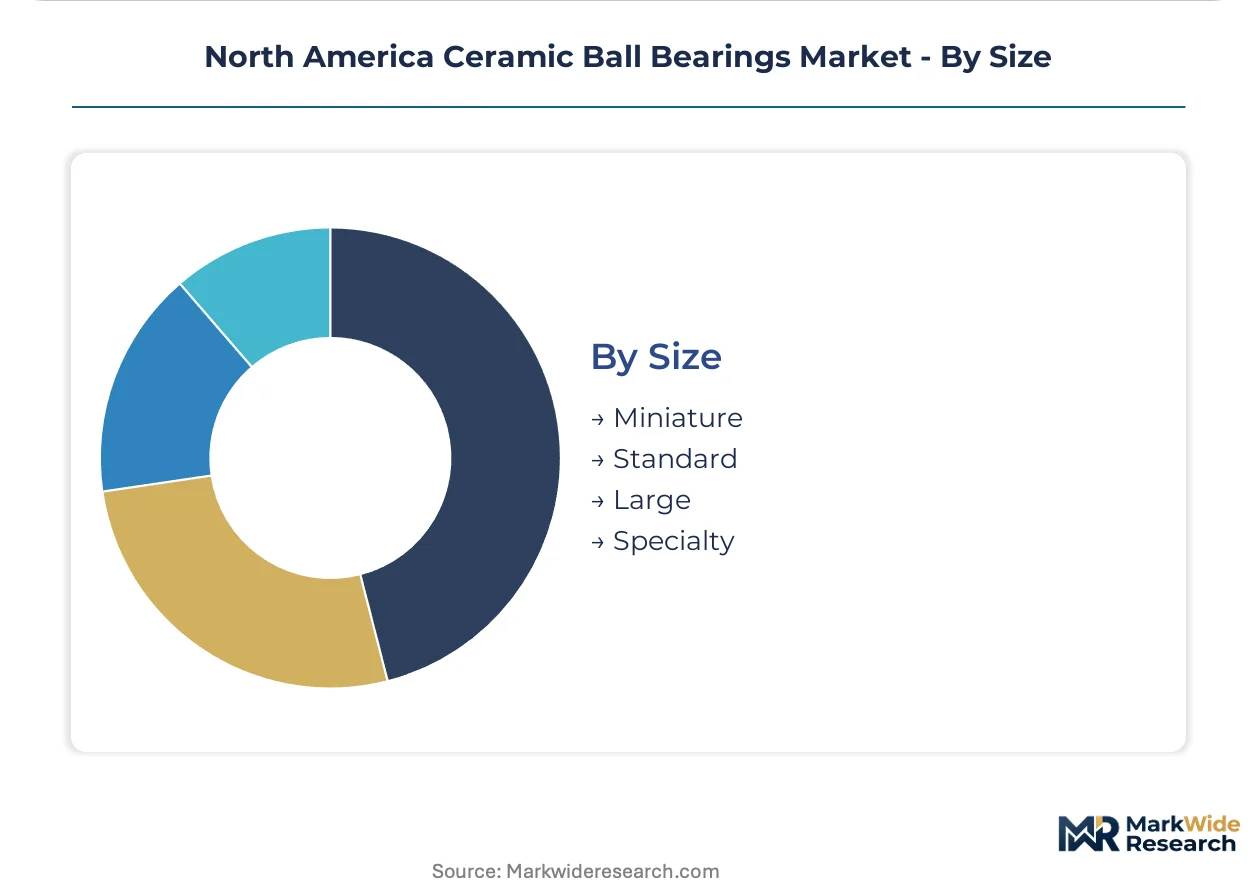
Size:
Dimensional thresholds correlate directly with manufacturing complexity and labor intensity, with miniature formats requiring specialized grinding equipment and technician expertise concentrated in specific regional supplier bases.
- Miniature:Sub-10mm outer diameter bearings serve surgical instruments, dental handpieces, and laboratory automation. Precision grinding technician scarcity in the Great Lakes region constrains output scaling regardless of capital investment.
- Standard:10-50mm formats dominate industrial machinery and automotive auxiliary systems where established supply chains and competitive sourcing maintain cost discipline.
- Large:Wind turbine main bearings and heavy machine tool spindles require custom-engineered ceramic solutions with extended lead times and captive powder supply dependencies.
- Specialty:Non-standard geometries and material pairings address legacy equipment retrofit requirements and application-specific load conditions.
Standard sizes maintain volume dominance; miniature formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification protocols anchor United States demand, while EPA emissions standards compress maintenance windows across Great Lakes manufacturing. Canadian aerospace OEMs expand hybrid ceramic procurement for jet engine applications. Mexican industrial corridors absorb standard-format bearings for automotive auxiliary systems.
United States
Jet engine OEMs in Connecticut and California mandate FAA-certified ceramic bearings under Part 33 airworthiness standards. NHTSA fuel economy credits reward friction reduction in Michigan and California electric vehicle powertrains. The Great Lakes corridor spanning Ohio, Illinois, and Michigan concentrates machine tool builder demand for hybrid configurations.
Canada
Aerospace OEMs in Ontario and Quebec expand procurement of silicon nitride bearings for commercial aviation propulsion systems. Health Canada medical device regulations govern biocompatibility documentation for surgical robotics manufacturers. Toronto and Montreal engineering centers specify miniature ceramic formats for dental turbine handpieces.
Mexico
Automotive tier suppliers in Nuevo León and Baja California specify hybrid ceramic bearings for electric motor auxiliary systems. The country's national environmental regulator enforces industrial emissions standards that favor extended-service-life components. Querétaro and Guanajuato manufacturing clusters integrate standard-format bearings into CNC machine tool spindles.
North America Ceramic Ball Bearings Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North American ceramic ball bearings market. The vendor base organizes into three tiers: multinational bearing conglomerates with captive ceramic powder supply chains, specialized ceramic component fabricators, and regional distributors serving aftermarket replacement demand. Strategic differentiation concentrates on backward integration into silicon nitride production versus strategic sourcing partnerships, alongside customization depth for medical and aerospace qualification pathways.
Among multinational bearing conglomerates, AB SKF and NSK Ltd. occupy positions defined by captive raw material continuity and dedicated R&D infrastructure. Schaeffler exemplifies the specialization archetype through application-specific hybrid configurations. These three entities anchor competitive dynamics around supply security and regulatory certification velocity rather than price-based rivalry.
| Leading Market Players |
|---|
| AB SKF |
| NSK Ltd. |
| NTN Corporation |
| JTEKT Corporation |
| Schaeffler |
| CeramicSpeed |
| Boca Bearings, Inc. |
| GMN Bearing USA Ltd. |
| Ortech Incorporated |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Great Lakes machine tool builders and silicon nitride powder suppliers lock in both raw material continuity and price visibility across multi-year procurement horizons. These arrangements insulate aerospace OEMs from spot-market volatility while compressing margins for mid-tier competitors excluded from captive supply networks.
Pricing Analysis
Michigan and Ohio command 15-20% premiums over Mexican automotive tier pricing for identical hybrid bearing specifications. Three-tier pricing structure across FAA-certified aerospace, FDA-traceable medical, and standard industrial grades anchors differentiation. Cost compression in industrial hybrid configurations is intensifying because Chinese powder entrants are undercutting established suppliers. Machine tool operators exhibit highest price sensitivity; jet engine OEMs prioritize certification velocity over unit economics.
Supply Chain Analysis
Inventory cycles for miniature surgical bearings stretch 16-24 weeks due to precision grinding technician scarcity constraining output scaling. Raw material supply draws from Japan, Germany, and domestic Tennessee powder synthesis facilities. Silicon nitride feedstock dependency creates single-source vulnerability when geopolitical friction disrupts Asian ceramic exports. Distribution runs through specialized industrial distributors in Illinois and Ohio rather than OEM captive channels for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ceramic ball bearings market represents a high-growth disruption as NHTSA fuel economy mandates and FAA fatigue-life certification protocols simultaneously rewire procurement specifications across automotive and aerospace verticals.
For Market Incumbents: Compound captive powder supply advantages by securing long-term offtake agreements with emerging Tennessee synthesis facilities before competitors replicate backward integration. Deepen FDA 21 CFR Part 820 certification infrastructure to accelerate medical-grade bearing velocity against emerging ceramic specialists threatening aerospace margins. For New Entrants and Emerging Players: Lead with miniature format specialization for surgical robotics OEMs in Minnesota and Massachusetts where precision grinding technician scarcity has locked out volume incumbents from rapid scaling. Target dental turbine handpiece manufacturers through direct distributor relationships unbundled from traditional OEM channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid bearing specialists serving electric vehicle powertrain platforms under NHTSA compliance frameworks. Five-to-ten-year viability favors acquisition targets with in-house silicon nitride powder production and existing FAA certification dossiers. Monitor EPA industrial emissions standard tightening velocity as the decisive inflection signal for ceramic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Nitride Synthesis | Secures raw material continuity against Japanese and German supply concentration risks. |
| FAA Certification Velocity Investment | Accelerates airworthiness approval timelines for Connecticut and California jet engine OEMs. |
| Miniature Format Grinding Capacity | Addresses precision technician scarcity constraining surgical robotics bearing output. |
| Hybrid Configuration Customization | Captures NHTSA fuel economy credit rewards in Michigan electric vehicle engineering centers. |
| Aftermarket Channel Disintermediation | Redirects Illinois and Ohio machine tool replacement demand from OEM captive networks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EPA emissions compliance filings, and NHTSA fuel economy credit records. Primary interviews engaged procurement directors at Connecticut aerospace OEMs, biomedical engineers at Minnesota surgical robotics manufacturers, and maintenance directors across Ohio machine tool operations. Secondary validation drew from customs import records, SEC 10-K disclosures of listed bearing manufacturers, and Great Lakes regional economic development databases. Bottom-up unit shipment estimates triangulate against top-down value absorption calculated from disclosed OEM procurement patterns.
Segmentation dimensions modeled include product type hierarchy, end-use vertical authority structures, application speed requirements, and size-category manufacturing complexity across the projection horizon. CAGRs derive from fitted growth curves anchored to disclosed OEM platform rollouts and regulatory compliance deadline clustering. Industry-specific inputs incorporate FAA Part 33 airworthiness protocol revision timelines and EPA industrial emissions standard enforcement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained NHTSA fuel economy mandate continuity or FAA certification protocol stability would require recalibration. Forecasts reflect assumptions regarding silicon nitride powder supply chain integrity and precision grinding technician pipeline development. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Global Automotive Nitrous Oxide System Market