
 India Automotive Parts Aluminum Die Casting Market | 2026-2036
India Automotive Parts Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Parts Aluminum Die Casting Market Outlook
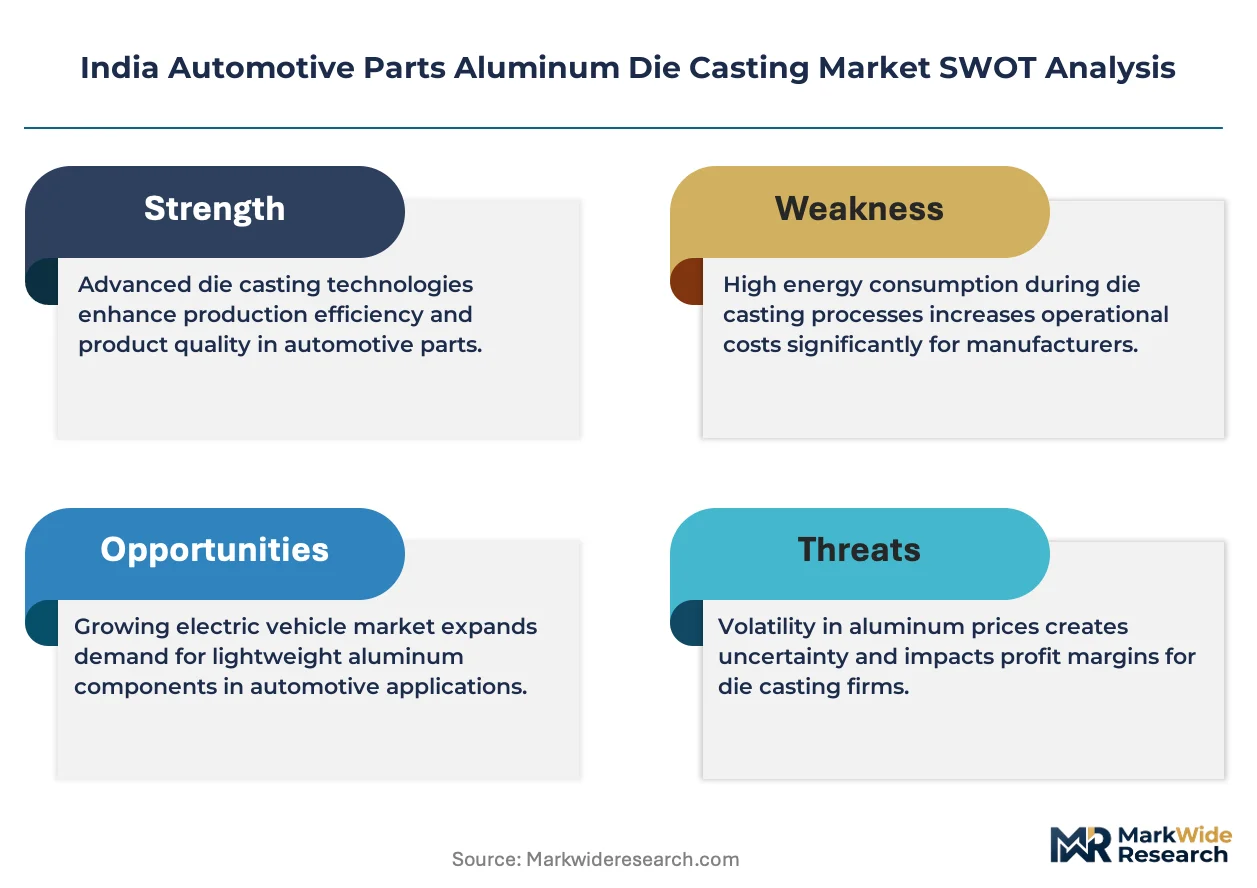
Asset-light leasing models for high-pressure die casting cells are reshaping competitive entry in India's aluminum die casting sector. Endurance Technologies leverages captive machining capabilities to sustain margin control across engine and transmission components. Rockman Industries anchors its position through backward integration into alloy melting, while Sandhar Technologies competes via specialization in chassis and structural castings for passenger vehicles.
Aluminum die casting for automotive parts involves injecting molten aluminum alloys under high pressure into precision steel molds to produce complex, lightweight components with tight dimensional tolerances, primarily serving vehicle weight reduction and structural integrity requirements. Pressure-tight engine components and transmission cases dominate current output volumes, reflecting the segment's maturity in internal combustion applications. Electric vehicle applications represent the fastest-growing category as OEMs demand larger structural castings for battery housings and motor enclosures, while chassis parts concentrate margin pools due to tighter alloy specifications and longer qualification cycles.
BIS certification for aluminum alloy grades and ARAI crashworthiness protocols shape product standards, compelling foundries to upgrade metallurgical testing and traceability systems. The Automotive Mission Plan and PLI scheme for advanced automotive technologies channel capital toward high-tonnage die casting capacity, particularly for EV-destined structural parts. Stakeholders must monitor how upcoming vehicle scrappage regulations and mandatory recycled content thresholds alter alloy sourcing strategies and foundry location decisions across India's automotive manufacturing belts.
Market Dynamics
India's aluminum die casting sector is compressing qualification cycles as BIS and ARAI tighten concurrent standards for crashworthiness, alloy traceability, and recycled content thresholds. Foundries must now synchronize metallurgical upgrades with EV platform timelines or face exclusion from OEM sourcing pools.
Growth Catalysts
- PLI scheme for advanced automotive technologies:The incentive framework channels capital toward high-tonnage die casting capacity, particularly for battery housing and motor enclosure production destined for electric vehicle platforms.
- Tamil Nadu industrial corridor concentration:Chennai-Coimbatore clustering around dedicated aluminum foundry ecosystems generates supplier density effects that compress logistics costs and accelerate prototype-to-production cycles.
- Vehicle scrappage policy pipeline:Mandatory retirement of aging commercial and passenger fleets is stimulating replacement demand for lightweight powertrain and chassis castings across OEM supply chains.
Market Restraints
- Primary aluminum price volatility:Input cost swings tied to LME pricing and import duty structures compress foundry margins and complicate long-term contract negotiations with Tier-1 suppliers.
- Scrap aluminum supply fragmentation:Domestic secondary aluminum sourcing remains geographically dispersed and quality-inconsistent, constraining OEM mandates for certified recycled content integration.
- High-pressure die casting equipment import dependence:Critical machinery sourcing from European and East Asian manufacturers exposes capacity expansion timelines to currency fluctuation and shipping bottlenecks.
Strategic Opportunities
- Gujarat and Maharashtra emerging clusters:Western India automotive manufacturing belts offer underdeveloped foundry infrastructure with proximity to JNPT port logistics and expanding EV OEM assembly operations.
- Structural casting integration with battery pack assembly:Die casters can capture value upstream by supplying crash-optimized battery tray modules that merge thermal management with vehicle chassis load paths.
- BIS alloy grade certification services:Third-party metallurgical testing and traceability system providers face expanding demand as foundries seek accelerated compliance pathways for new EV-destined component qualifications.
Industry Challenges
- Die design and thermal simulation expertise scarcity:Foundries struggle to recruit engineers capable of optimizing mold flow analysis for large structural castings with complex cooling channel geometries.
- Concurrent BIS and ARAI certification timelines:Overlapping alloy grade approval and crashworthiness validation protocols extend product qualification cycles, delaying revenue recognition on new EV platform awards.
- Legacy machining capability integration:Pure-play die casters without captive CNC finishing operations face margin compression when outsourcing precision machining for tight-tolerance transmission and engine components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Parts Aluminum Die Casting Market |
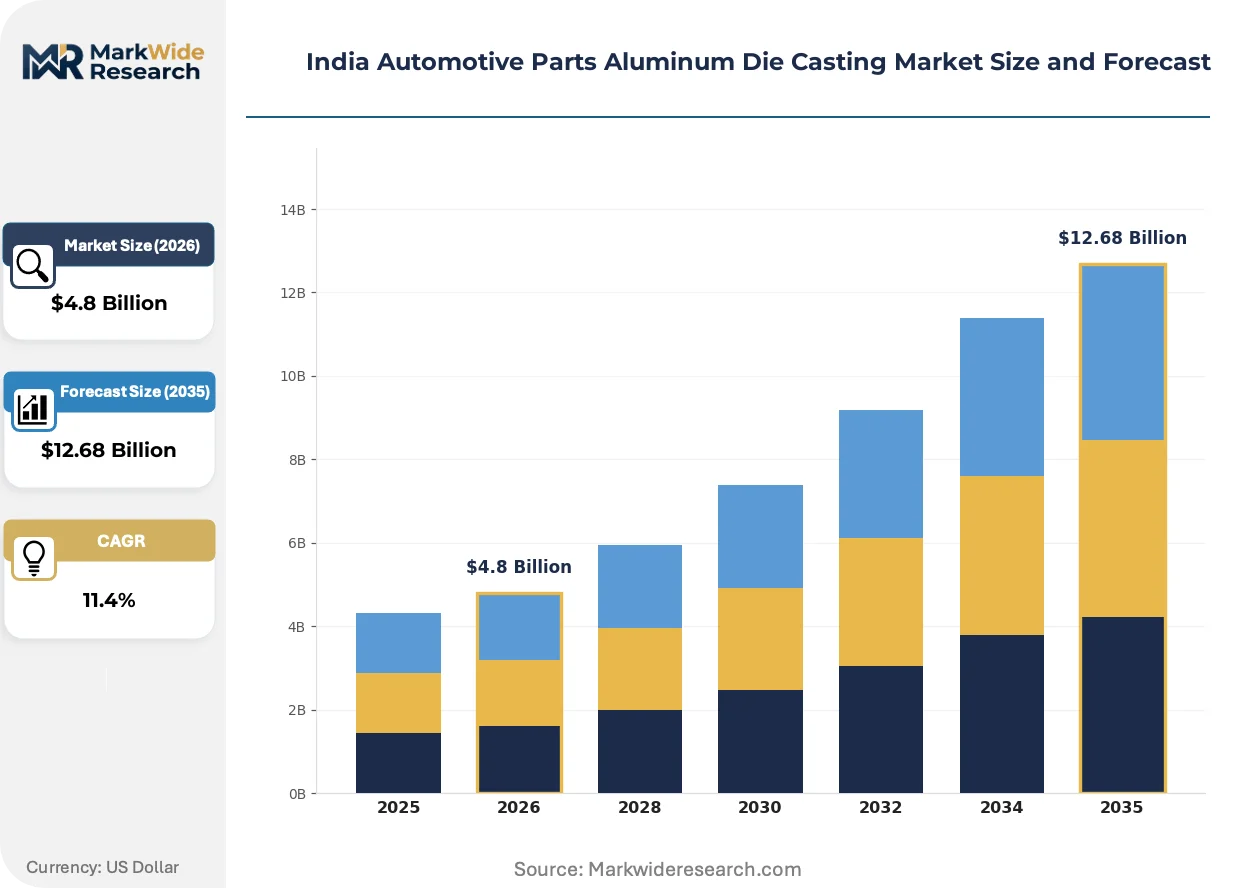
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Chassis Parts, Structural Parts End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Die Casting, Machining, Surface Treatment, Assembly Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | Endurance Technologies, Rockman Industries, Sandhar Technologies, Sundaram-Clayton Limited, Samvardhana Motherson Group, Spark Minda, Indian Diecasting Industries, Rane (Madras) Limited, Jaya Hind Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Parts Aluminum Die Casting Market Strategic Shifts
Large-structural die casting is compressing vehicle assembly architectures by consolidating dozens of stamped and welded components into single aluminum castings. This process convergence is redrawing competitive boundaries between foundries, Tier-1 suppliers, and OEM in-house manufacturing operations.
Multi-directional die casting with real-time thermal monitoring is rendering obsolete traditional single-plane high-pressure systems for battery enclosure production. Mahindra Electric and Tata Motors Passenger Electric Mobility are qualifying 4,000-ton-plus cells for integrated floor pan castings. The technology is compressing part counts from seventy-plus stamped pieces to single castings while tightening dimensional tolerances for battery pack sealing surfaces.
ARAI's updated crashworthiness protocols for electric vehicle structures are mandating alloy-specific energy absorption characteristics that exceed legacy internal combustion chassis standards. Foundries must now submit batch-level tensile and fatigue test data alongside component submissions. Tamil Nadu-based suppliers serving Hyundai Motor India and Kia India are restructuring quality management systems to accommodate this documentation burden.
Leasing arrangements for high-tonnage die casting cells are displacing capital purchase models among mid-tier foundries seeking EV platform entry. Asset-light structures transfer obsolescence risk to machinery financiers while preserving foundry liquidity for alloy and talent investments. Karnataka and Telangana operations are piloting these arrangements most aggressively as they chase qualification for emerging electric two-wheeler and three-wheeler OEM supply chains.
India Automotive Parts Aluminum Die Casting Market Segmentation
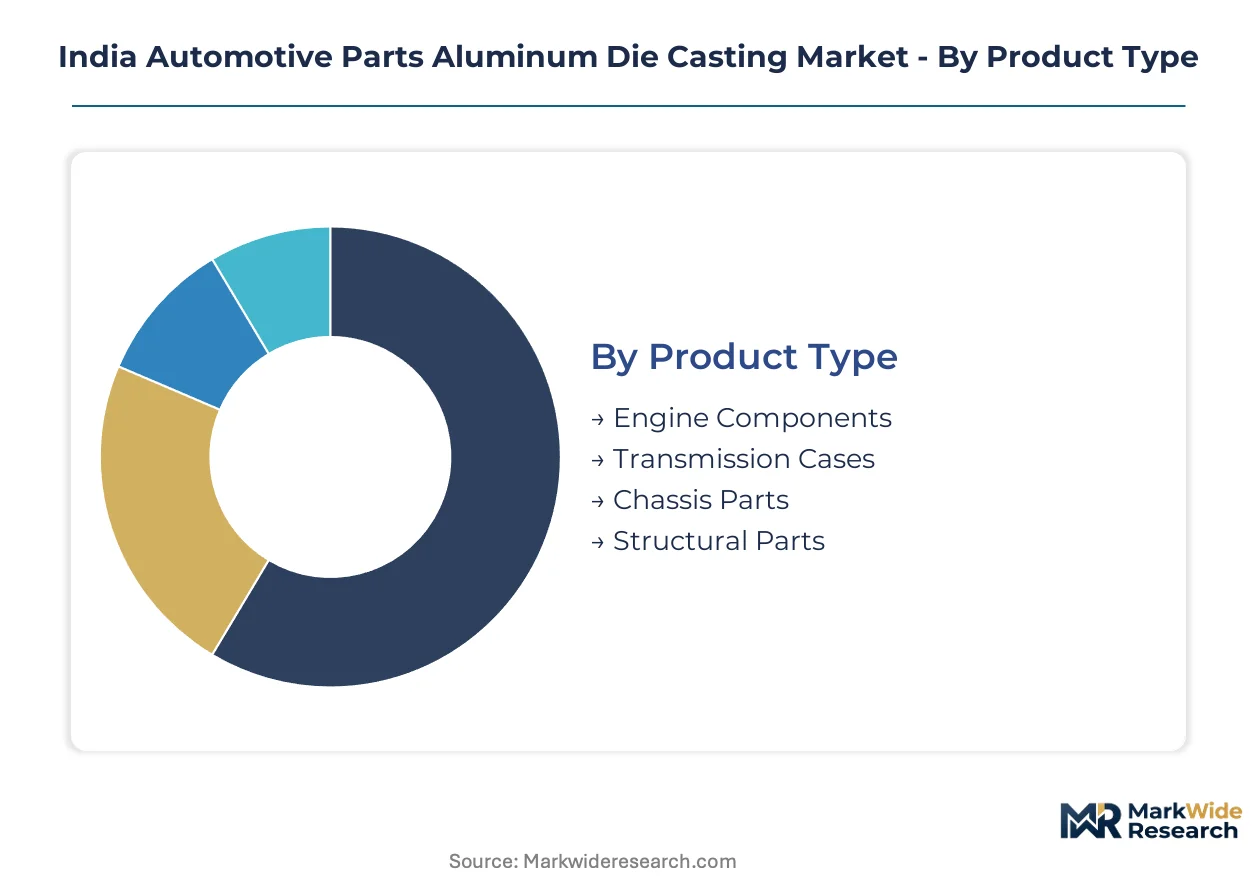
Segmentation in India's aluminum die casting market reveals divergent qualification timelines and margin structures. Product type determines capital intensity and metallurgical complexity. End-user relationships shape contract duration and price negotiation leverage.
Product Type:
Engine components and transmission cases turn inventory fastest due to mature ICE platforms and predictable replacement cycles. Structural parts for EVs carry the longest prototype-to-production timelines as BIS and ARAI standards evolve concurrently.
- Engine Components:Pressure-tight cylinder heads, engine blocks, and intake manifolds demand tight porosity control and thermal fatigue resistance. Tamil Nadu foundries serving Hyundai Motor India and Kia India dominate this segment as OEMs prioritize localized sourcing for ICE powertrains amid export demand.
- Transmission Cases:Complex housing geometries with integrated cooling passages require multi-slide die casting and post-cast machining. Suppliers in the Chennai-Coimbatore corridor capture volume as automated transmission penetration rises in mid-size passenger vehicles.
- Chassis Parts:Control arms, steering knuckles, and subframe nodes concentrate margin pools due to crashworthiness certification requirements.
- Structural Parts:Battery enclosures and motor housings for electric platforms command premium alloy specifications and extended qualification cycles.
Engine components anchor the volume base while structural parts gain share at the steepest rate.
End User:
Cost tier stratification separates captive foundry operations from merchant suppliers. Tier-1 suppliers and OEMs occupy opposite ends of the pricing spectrum based on backward integration depth and volume commitment scale.
- OEMs:Maruti Suzuki India and Tata Motors operate captive die casting for strategic components, insulating supply chains from primary aluminum volatility through long-term alloy contracts.
- Aftermarket Providers:Fragmented distributor networks serving replacement demand for aging commercial fleets concentrate in Maharashtra and Gujarat logistics hubs.
- Tier-1 Suppliers:Endurance Technologies and Rockman Industries leverage captive machining to defend margin position across engine and transmission programs.
- Vehicle Assemblers:Emerging electric two-wheeler OEMs in Karnataka and Telangana source structural castings through short-term contracts with asset-light foundry operators.
Tier-1 suppliers concentrate procurement volume while vehicle assemblers expand their supplier base most aggressively.
Manufacturing Stage:
Geographic concentration follows process complexity. Die casting clusters in Tamil Nadu while machining and surface treatment disperse toward OEM assembly plants in Maharashtra and Gujarat.
- Die Casting:High-pressure cell operations with 2,500-ton-plus clamping force concentrate in the Chennai-Coimbatore corridor where alloy supply and technical talent pools overlap.
- Machining:CNC finishing for tight-tolerance transmission cases and engine blocks locates near Pune and Ahmedabad to minimize logistics costs for just-in-sequence delivery.
- Surface Treatment:Shot blasting, impregnation, and coating operations serve multiple foundries through centralized job shops in industrial zones.
- Assembly:Module integration of cast components with seals, fasteners, and sensors occurs at Tier-1 facilities proximate to OEM assembly lines.
Die casting anchors the volume base while assembly captures value expansion at the steepest rate.
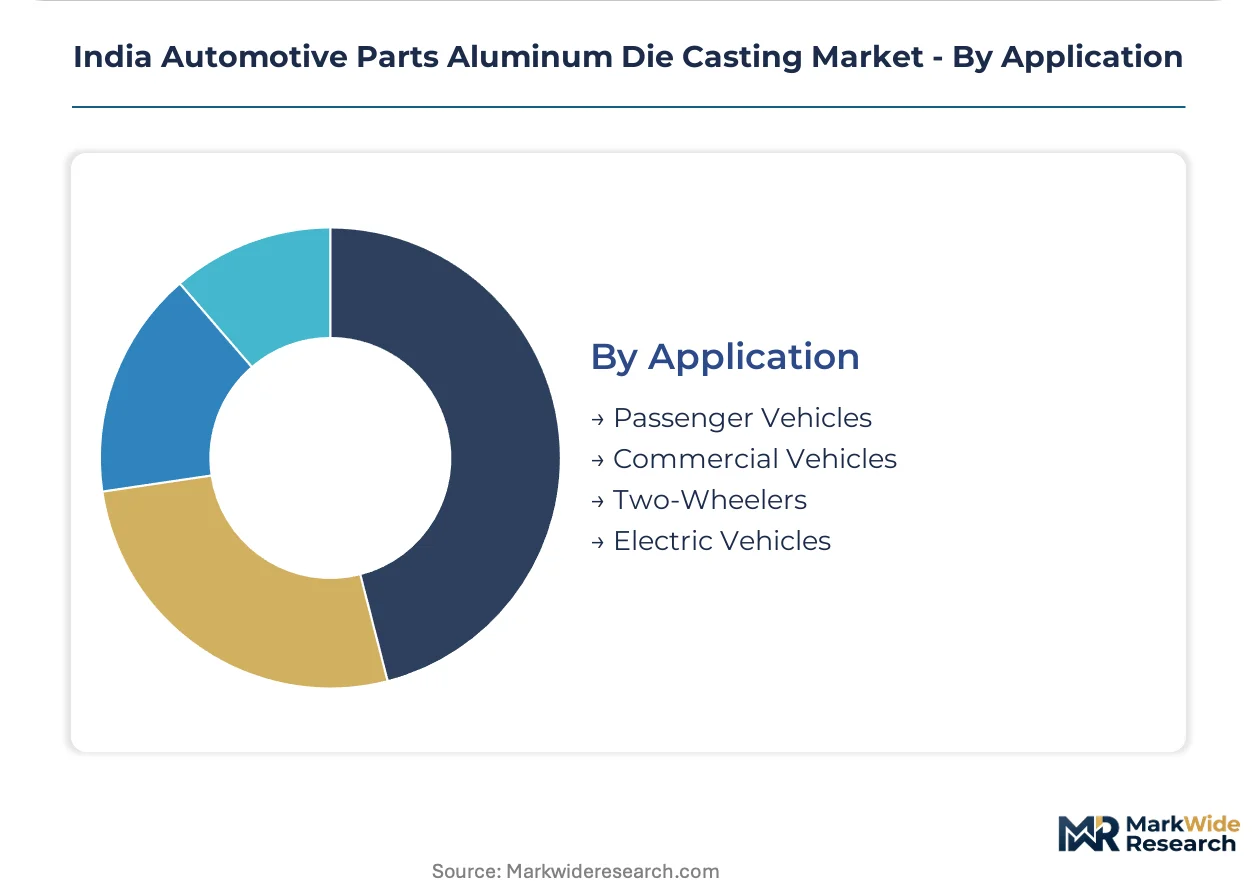
Application:
Customer type segmentation separates high-volume standardized programs from specialized low-volume qualifications. Passenger vehicles and electric vehicles occupy opposite poles of this spectrum.
- Passenger Vehicles:Sedan and SUV programs generate predictable demand for engine, transmission, and chassis castings with established alloy specifications and compressed requalification cycles.
- Commercial Vehicles:Heavy-duty truck and bus applications prioritize durability over weight reduction, sustaining demand for iron-intensive designs that constrain aluminum penetration.
- Two-Wheelers:Scooter and motorcycle engine cases in the 100-150cc segment represent high-volume, low-margin production with minimal alloy differentiation.
- Electric Vehicles:Battery housing and motor enclosure programs for Mahindra Electric and Tata Motors Passenger Electric Mobility drive demand for large-structural die casting cells exceeding 4,000 tons.
Passenger vehicles anchor the volume base while electric vehicles climb the fastest as OEMs consolidate platform architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's aluminum die casting trade flows reflect a structural deficit in high-purity primary aluminum, compelling coastal states to anchor import-dependent foundry ecosystems while inland clusters process secondary alloys for cost-sensitive segments.
Tamil Nadu
Chennai-Coimbatore corridor hosts India's densest concentration of high-pressure die casting cells, serving Hyundai Motor India and Kia India with just-in-sequence delivery schedules. BIS alloy certification requirements and ARAI crashworthiness protocols compress qualification timelines for suppliers in this belt. Sriperumbudur and Oragadam industrial zones concentrate 4,000-ton-plus structural casting capacity for emerging EV programs.
Maharashtra
Pune-Nashik automotive belt generates demand for transmission case machining and engine component finishing, with Tier-1 suppliers locating CNC operations proximate to Tata Motors and Mahindra & Mahindra assembly plants. State industrial policy incentives for electric vehicle component manufacturing redirect some foundry investment toward battery enclosure qualification. Chakan and Talegaon industrial corridors absorb overflow capacity from Tamil Nadu for western OEM supply chains.
Gujarat
Sanand and Halol manufacturing zones offer underdeveloped foundry infrastructure with proximity to JNPT port logistics for primary aluminum import. PLI scheme disbursements for advanced automotive technologies channel capital toward greenfield high-tonnage die casting investments. Emerging EV OEM assembly operations in this belt create first-mover opportunities for structural casting suppliers establishing western India presence.
Karnataka
Bengaluru-Tumkur corridor concentrates electric two-wheeler and three-wheeler OEM operations, driving demand for smaller structural castings with accelerated qualification cycles. Asset-light leasing models for die casting cells proliferate here as foundries chase short-term contract opportunities. State EV policy mandates and BIS certification timelines compress supplier selection windows for battery housing programs.
Haryana
Manesar-Bawal industrial zone anchors Maruti Suzuki India's captive die casting operations and surrounding Tier-1 supplier networks for powertrain components. Proximity to Delhi-NCR logistics hubs supports aftermarket distribution for aging commercial vehicle fleets. Vehicle scrappage policy implementation in this National Capital Region accelerates replacement demand for lightweight chassis castings.
India Automotive Parts Aluminum Die Casting Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying discrete castings for integration into larger modules. Market structure tilts toward consolidation among Tier-1 suppliers with captive machining capabilities, while mid-tier foundries fragment across geography and alloy specialization. Three archetypes dominate: vertically integrated powertrain specialists, asset-light structural casting entrants, and captive OEM operations insulating supply chains. Competitive dynamics center on backward integration into alloy melting and strategic leasing arrangements for high-tonnage equipment.
Among India-based automotive component groups, Endurance Technologies and Rockman Industries occupy positions reflecting distinct integration strategies, while Sandhar Technologies represents specialization in chassis and structural applications. These entities exemplify how captive machining capabilities, backward integration into alloy supply, or focused segment positioning translate into differentiated margin structures across engine, transmission, and emerging EV platform supply chains.
| Leading Market Players |
|---|
| Endurance Technologies |
| Rockman Industries |
| Sandhar Technologies |
| Sundaram-Clayton Limited |
| Samvardhana Motherson Group |
| Spark Minda |
| Indian Diecasting Industries |
| Rane (Madras) Limited |
| Jaya Hind Industries |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gujarat's emerging foundry belt is compressing spot pricing for standard-grade engine components while tightening margins for asset-light operators chasing EV qualification timelines. This utilization imbalance feeds directly into supplier selection behavior, as OEM procurement teams exploit geographic fragmentation to extract volume discounts from mid-tier casters.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term offtake agreements with primary aluminum price pass-through clauses. Pricing stratifies across BIS-certified structural grades, standard engine alloys, and uncertified secondary blends, with certification tier and volume scale as the dominant differentiation drivers. Cost compression in the standard-grade segment is intensifying because Tamil Nadu's dense supplier base enables aggressive competitive bidding. Tier-1 suppliers with captive machining operations exhibit the lowest price sensitivity, while pure-play die casters outsourcing finishing work face acute margin pressure.
Supply Chain Analysis
European and East Asian export controls on high-pressure die casting machinery above 4,000-ton clamping force constrain capacity expansion timelines for Indian foundries seeking EV platform entry. Primary aluminum ingot draws from UAE, Australia, and domestic Hindalco smelters, while secondary alloy scrap feeds from dispersed domestic collection networks. Single-source vulnerability concentrates in German and Japanese equipment suppliers, exposing project schedules to currency fluctuation and shipping bottlenecks. Distribution runs through Tier-1 integrators consolidating castings into powertrain and chassis modules for just-in-sequence delivery to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's aluminum die casting sector sits in early-cycle expansion as electric vehicle platform localization accelerates structural casting demand beyond current qualified capacity. PLI scheme disbursements and BIS certification backlogs are compressing supplier selection windows, favoring prepared participants.
For Market Incumbents: Build metallurgical certification moats by investing in batch-level traceability systems that satisfy ARAI's evolving crashworthiness documentation requirements. Deepen backward integration into alloy melting to insulate margins from primary aluminum volatility, while adding captive machining capacity to defend against margin compression from outsourcing precision finishing work. For New Entrants and Emerging Players: Establish a beachhead in Gujarat's underdeveloped foundry infrastructure, where greenfield high-tonnage capacity can qualify for western OEM supply chains before Tamil Nadu's density effects lock out late movers. Target structural casting programs for emerging electric two-wheeler OEMs in Karnataka, where asset-light leasing models reduce capital barriers and accelerated qualification cycles reward nimble suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers with long-term platform contracts and captive machining capabilities, as these entities capture value across multiple manufacturing stages. Over a multi-year horizon, acquisition candidates should display integrated alloy supply and BIS certification infrastructure. The signal to watch is mandatory recycled content thresholds in forthcoming vehicle scrappage regulations, which would force rapid secondary aluminum supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Melting | Captive supply of certified secondary aluminum insulates margins from LME volatility and scrap fragmentation. |
| High-Tonnage Die Casting Capacity Expansion | 4,000-ton-plus cells qualify suppliers for integrated EV floor pan programs at Mahindra Electric and Tata Motors. |
| BIS Certification Infrastructure Investment | Accelerated alloy grade approval pathways compress prototype-to-production cycles for structural casting qualifications. |
| Captive CNC Machining Capability Addition | In-house finishing operations defend margin pools on tight-tolerance transmission cases and engine components. |
| Asset-Light Equipment Leasing Arrangements | Machinery financiers absorb obsolescence risk while preserving foundry liquidity for talent and alloy investments. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement heads, foundry operations directors, and ARAI certification specialists, then refined through secondary validation against BIS alloy standards documentation, PLI scheme disbursement records, vehicle production databases, and customs trade data for primary aluminum imports. Bottom-up capacity estimates from individual foundry operations were triangulated with top-down demand projections derived from OEM platform announcements.
Demand-supply balance modeling across the analysis window incorporated segmentation by product type, end-user tier, manufacturing stage, and propulsion architecture, with CAGRs derived from regression analysis of historical capacity utilization and forward-looking platform localization timelines. Industry-specific forecast inputs included BIS certification queue lengths, ARAI crashworthiness protocol evolution, and PLI scheme incentive disbursement schedules.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum LME pricing, rupee-dollar exchange rates, or import duty structures would shift the trajectory of foundry investment decisions. Material shifts in BIS alloy grade requirements or ARAI testing protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Canister Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Car Rack Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
EV Reduction Gears Market