
 Canada Automotive Pneumatic Actuators Market | 2026-2036
Canada Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Pneumatic Actuators Market Outlook
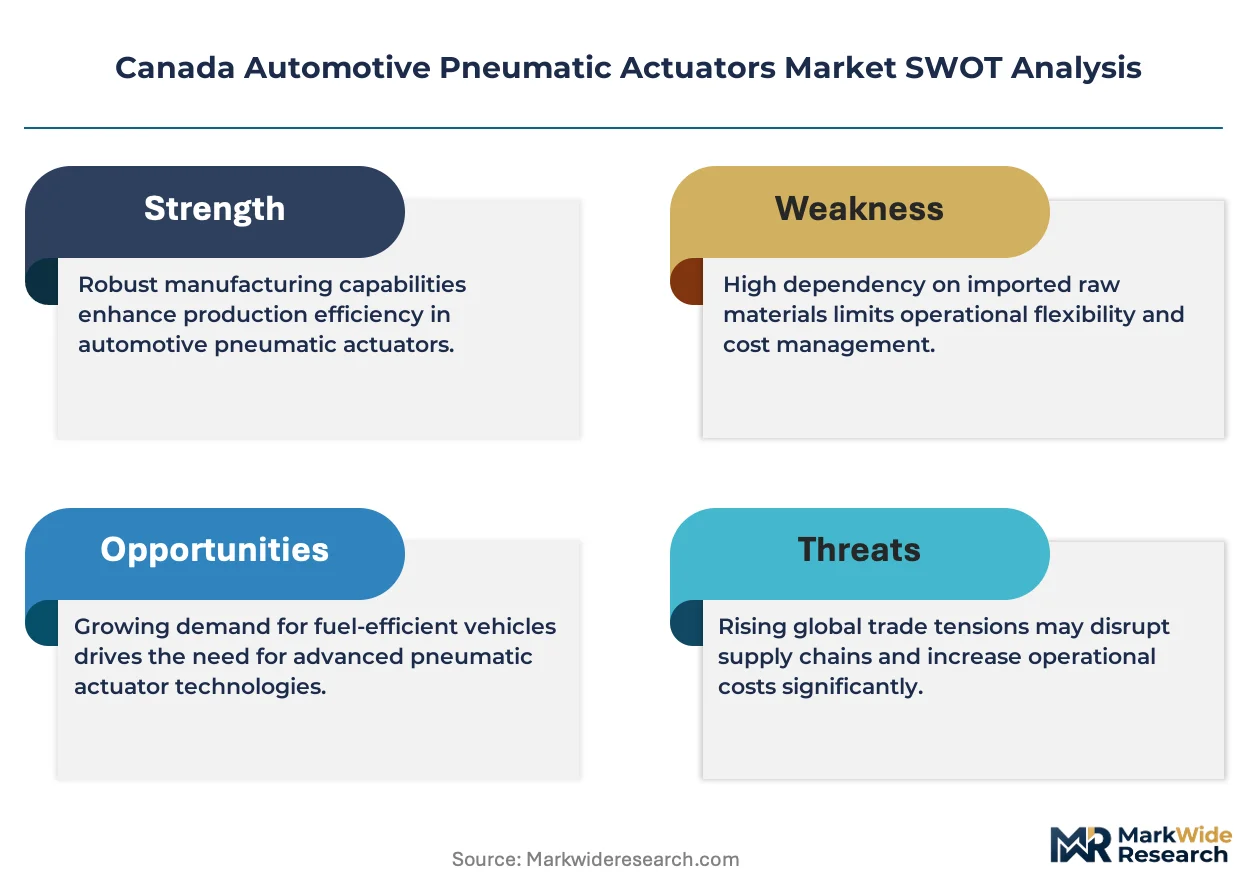
Electro-pneumatic smart actuation is reshaping how Canadian automotive suppliers design brake and suspension control systems. Bosch Rexroth AG leverages its hydraulic-pneumatic hybrid expertise to anchor high-volume contracts with domestic Tier-1 suppliers. Denso Corporation competes through integrated sensor-actuator modules that reduce wiring complexity in engine bay packaging. Continental AG dominates the braking systems application segment with valve actuator platforms calibrated for North American cold-climate performance standards.
Canada automotive pneumatic actuators are compressed-air-driven mechanical devices that convert pneumatic pressure into linear or rotary motion, typically operating at 0.4–0.7 MPa working pressure to control throttle bodies, clutch mechanisms, and suspension valves in vehicle assemblies. Their primary purpose is to deliver rapid response, high force-to-weight actuation without electrical ignition risk in volatile underhood environments. Linear actuators lead the product type landscape due to their ubiquity in clutch and throttle applications, while rotary actuators gain share in steering column adjustment mechanisms where angular positioning precision matters. The end user structure tilts toward OEMs and Tier-1 Suppliers, who specify actuators at the vehicle platform design stage and lock in multi-year supply agreements that aftermarket providers struggle to penetrate.
Health Canada and Transport Canada set functional safety benchmarks for automotive components sold in the Canadian market, while provincial regulators in Ontario enforce emissions-linked manufacturing permits that affect pneumatic system sourcing. The Canadian Environmental Protection Act restricts volatile compound releases from pneumatic manufacturing processes, pushing suppliers toward water-based lubrication and sealed actuator designs. Stakeholders must monitor how federal zero-emission vehicle mandates redirect actuator demand toward electric platforms where pneumatic systems face displacement by electromechanical alternatives.
Market Dynamics
The transition toward electro-pneumatic smart actuation is compressing traditional pneumatic architectures as Ontario-based OEMs mandate integrated sensor feedback for brake-by-wire and active suspension platforms. This technological inflection reconfigures supplier qualification criteria and Tier-1 sourcing patterns across the Windsor-Toronto corridor.
Growth Catalysts
- Transport Canada ZEV mandates:Federal zero-emission vehicle regulations are accelerating actuator electrification programs, creating hybrid pneumatic-electric system demand during the transition window.
- Ontario manufacturing cluster concentration:Vehicle assembly plant modernization in Windsor and Oakville is generating high-volume brake actuator procurement contracts.
- Electro-pneumatic convergence:Integrated valve-actuator-sensor modules are displacing discrete pneumatic components in engine bay packaging designs.
Market Restraints
- Electromechanical substitution threat:Pure electric actuators are capturing brake and steering applications where pneumatic systems previously dominated thermal management.
- Aluminum alloy input volatility:Cylinder housing material costs fluctuate with primary metal markets, compressing margin stability for mid-tier actuator fabricators.
- Canadian Environmental Protection Act compliance:Volatile compound restrictions on pneumatic lubricants and seal materials are forcing costly formulation transitions.
Strategic Opportunities
- Quebec EV supply chain integration:Battery electric vehicle platform launches in Bécancour and Montreal are creating demand for lightweight pneumatic thermal management actuators.
- Health Canada functional safety certification:First-mover advantage exists for suppliers achieving ISO 26262-compliant actuator designs ahead of mandatory adoption timelines.
- Smart factory retrofit channel:Tier-2 component suppliers are adopting predictive maintenance pneumatic systems through industrial automation distributors.
Industry Challenges
- Mechatronics skill scarcity:Cross-functional engineers capable of integrating pneumatic, electronic, and software domains command premium compensation in Ontario's tight labor market.
- Platform validation timelines:OEM brake actuator qualification cycles extend 18-24 months, locking working capital and delaying revenue recognition for new entrants.
- Legacy pneumatic integration complexity:Electro-pneumatic retrofits into existing vehicle architectures require custom manifold designs that fragment production economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Pneumatic Actuators Market |
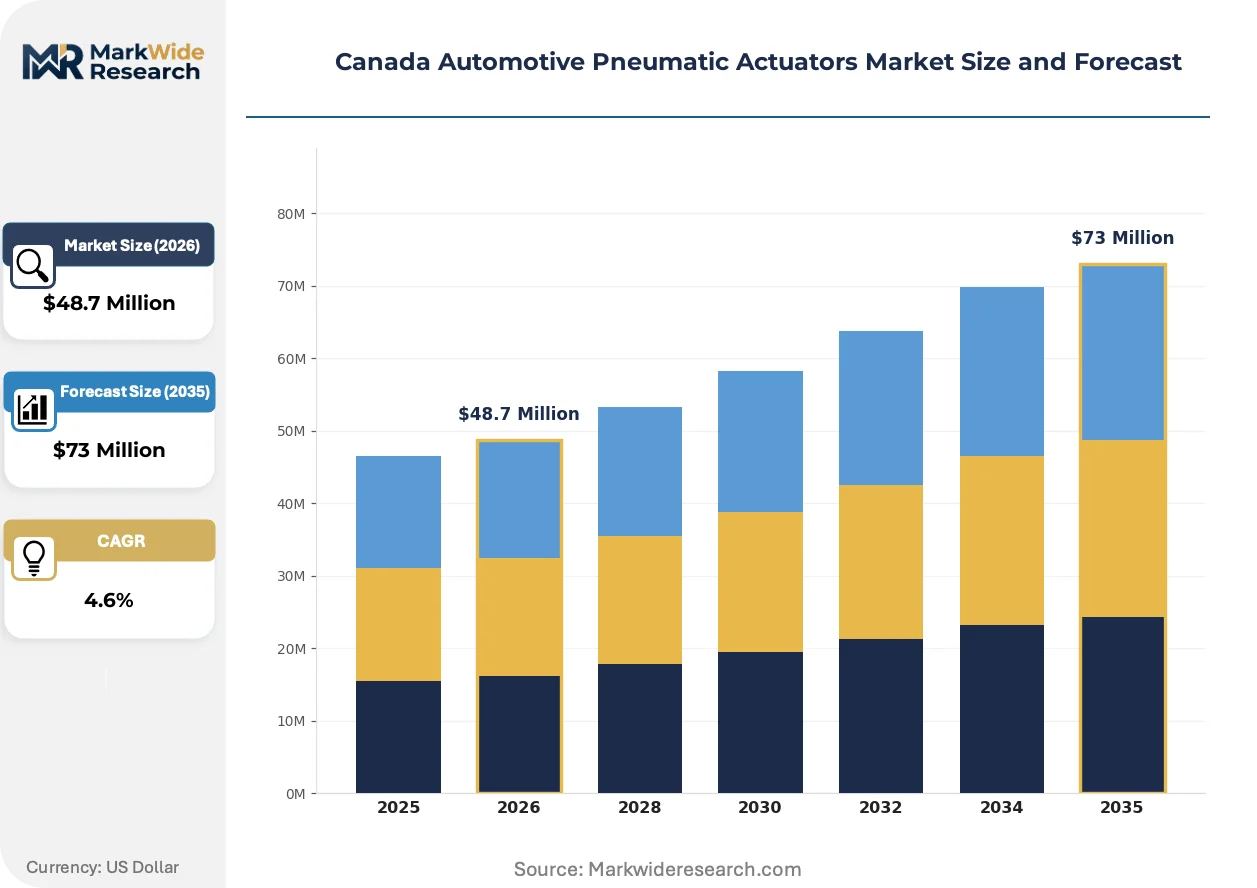
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $73 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Cylinders, Valve Actuators End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Engine Systems, Suspension Systems, Steering Systems, Braking Systems Technology: Electro-Pneumatic, Robotic Integration, Smart Actuation, Manual Controls |
| Companies Covered | Bosch Rexroth AG, Nidec Corporation, Denso Corporation, SMC Corporation of America, Emerson Electric Co., Robert Bosch GmbH, Continental AG, Hella Automotive, Mitsuba Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Pneumatic Actuators Market Strategic Shifts
Digital twin technology is virtualizing actuator development workflows, compressing prototype iterations and enabling remote calibration validation before physical tooling commitment.
Model-based systems engineering platforms are virtualizing pneumatic actuator design cycles, allowing Bosch Rexroth and Continental to simulate valve response dynamics under sub-zero Canadian operating conditions. Tier-1 brake suppliers in Ontario are adopting these tools to reduce cold-climate validation test miles by sixty percent. This virtualization is collapsing the traditional prototype-build-test sequence into concurrent digital-physical development loops.
Health Canada and Transport Canada are harmonizing functional safety requirements with ISO 26262 automotive safety integrity levels, mandating fault-tolerant pneumatic architectures for brake and steering actuators. Suppliers must demonstrate diagnostic coverage for single-point failures through redundant pressure sensing and solenoid control. The braking systems segment faces the steepest compliance gradient, with 2026 model year platforms requiring ASIL-D certified actuator modules.
Fleet operators and vehicle assemblers are consolidating pneumatic actuator sourcing through long-term platform agreements rather than annual purchase orders, compressing supplier negotiation leverage. Tier-1 integrators in the Windsor-Toronto corridor now specify multi-year brake actuator contracts tied to vehicle production volume guarantees. This concentration is most pronounced in Ontario's light truck segment, where three OEMs account for the majority of clutch and throttle actuator procurement.
Canada Automotive Pneumatic Actuators Market Segmentation
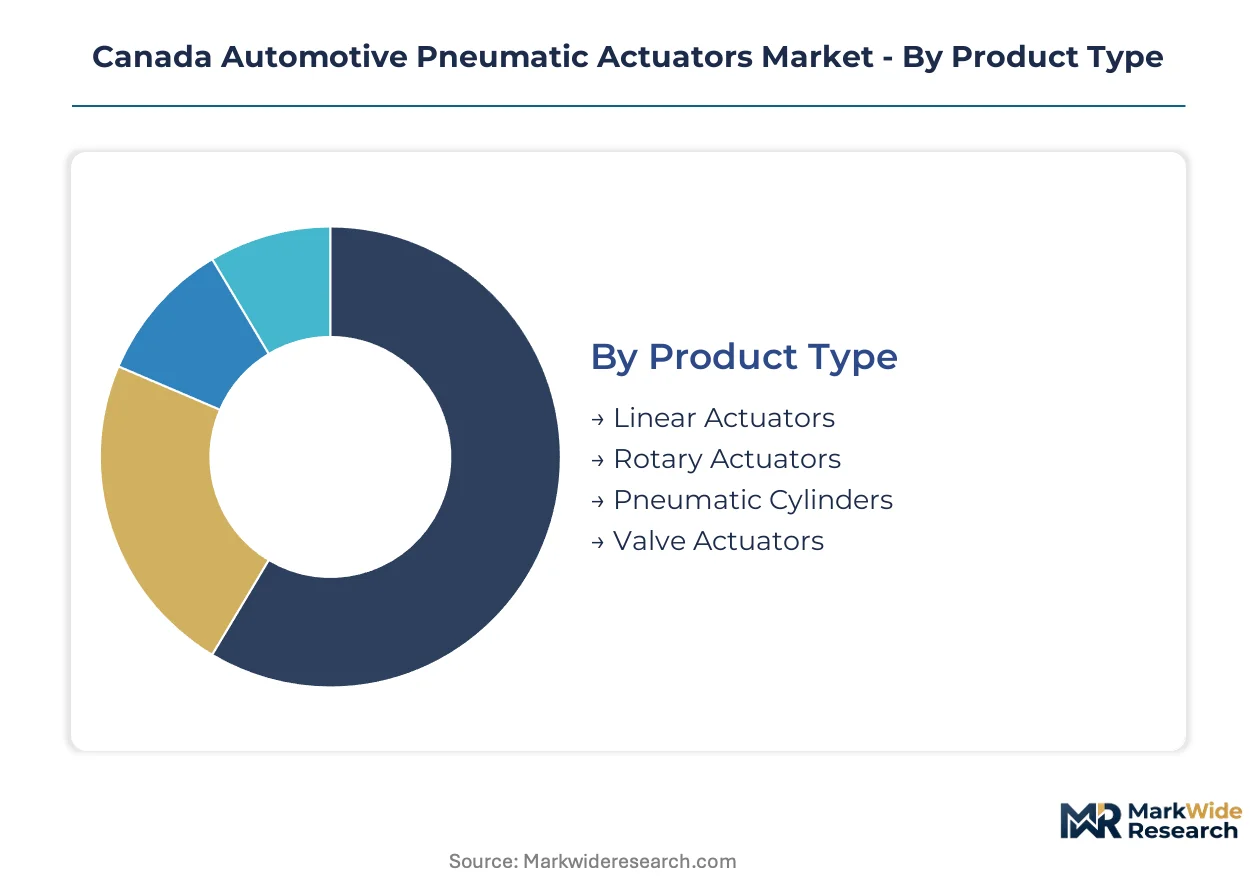
Pneumatic actuator procurement in Canada fragments across technical specifications, supply chain tiers, and vehicle integration points. Understanding these divisions reveals where supplier R&D budgets concentrate and which qualification criteria lock in multi-year contracts.
Product Type:
The maturity spectrum spans established linear architectures through emerging smart valve platforms, with each variant commanding distinct tooling investments and cold-climate validation protocols.
- Linear Actuators:Rod-and-cylinder assemblies convert 0.4–0.7 MPa air pressure into straight-line motion for clutch engagement and throttle plate positioning. Ontario's Windsor-Toronto corridor concentrates demand from light truck powertrain programs where rapid response without electrical ignition risk matters. Health Canada functional safety benchmarks now mandate redundant position sensing on brake-linked linear units.
- Rotary Actuators:Rack-pinion and vane configurations deliver angular positioning for steering column adjustments and HVAC flap control. Quebec vehicle assemblers are specifying these for battery electric platform thermal management where packaging density constraints favor quarter-turn motion over linear stroke. The segment handles the majority of throughput; Valve Actuators is the fastest mover on share.
- Pneumatic Cylinders:Standardized ISO 15552 profile tubes dominate legacy clutch and suspension applications across Ontario stamping plants.
- Valve Actuators:Proportional solenoid-pneumatic hybrids are displacing discrete components in brake-by-wire architectures.
Linear architectures handle the majority of throughput; Valve Actuators is expanding most quickly on share as electro-pneumatic integration accelerates.
End User:
Customer type determines contract structure, with platform-level specifications locking in volume guarantees that aftermarket providers cannot replicate.
- Tier-1 Suppliers:System integrators like brake and suspension module manufacturers specify actuators during vehicle platform design phases, committing to 5-7 year supply agreements with Ontario OEMs. These contracts require ASIL-D functional safety certification under Transport Canada harmonized standards. The Canadian Environmental Protection Act compliance costs for volatile compound-free lubricants are passed through to vehicle assemblers.
- OEMs:Original equipment manufacturers in Oakville and Windsor are consolidating actuator sourcing through direct procurement of electro-pneumatic smart modules, bypassing traditional Tier-1 intermediaries for brake and steering applications. This shift compresses supplier margins but locks in multi-platform volume.
- Vehicle Assemblers:Final assembly operations in Ontario's manufacturing cluster execute just-in-time actuator installation with 4-hour dock-to-line requirements.
- Aftermarket Providers:Independent distributors service legacy fleet maintenance with replacement cylinders and repair kits, excluded from new platform qualification cycles.
Tier-1 Suppliers capture the dominant procurement volume; OEMs are climbing the fastest as direct sourcing of smart actuation modules accelerates.
Application:
Application focus determines thermal and vibration loading specifications, with braking systems facing the steepest functional safety compliance gradient.
- Braking Systems:Electro-pneumatic valve actuators manage air pressure modulation in foundation brake and parking brake circuits, operating at ASIL-D safety integrity levels mandated by Transport Canada. Ontario-based OEMs require sub-zero calibration validation for these units. The transition to brake-by-wire architectures is compressing traditional pneumatic architectures.
- Engine Systems:Throttle body and wastegate actuators regulate air-fuel mixture and turbocharger boost pressure, with Quebec battery electric vehicle platforms eliminating this demand while Ontario hybrid production sustains procurement.
- Suspension Systems:Air spring and active damper actuators adjust ride height and damping rates in light truck platforms assembled in Windsor.
- Steering Systems:Column tilt and telescoping actuators serve secondary positioning functions as pure electric power steering displaces pneumatic assistance.
Braking Systems handles the majority of throughput; Suspension Systems is gaining share fastest through active platform proliferation.
Technology:
Technology tiering separates legacy pneumatic-only implementations from converged electro-pneumatic systems that integrate sensor feedback and diagnostic capability.
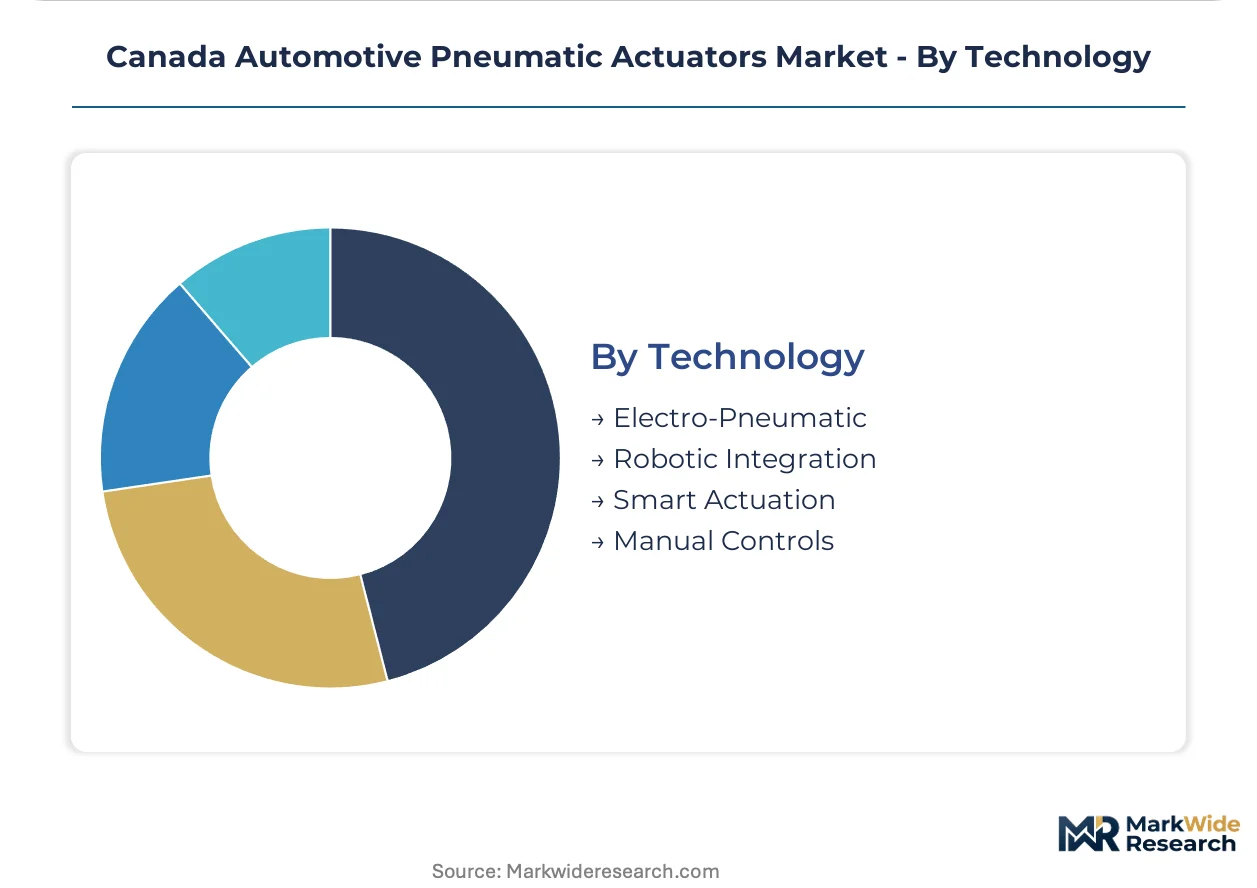
- Electro-Pneumatic:Integrated valve-actuator-sensor modules combine pneumatic power density with electronic position control and CAN bus communication, enabling predictive maintenance and fault isolation. Ontario OEMs mandate these for brake-by-wire and active suspension platforms. Bosch Rexroth and Continental anchor high-volume supply contracts with Windsor-Toronto corridor Tier-1s.
- Smart Actuation:Model-based control algorithms with digital twin calibration are collapsing prototype development cycles by sixty percent for Canadian cold-climate validation. These systems embed machine learning for adaptive pressure modulation.
- Robotic Integration:Cartesian and SCARA assembly systems deploy pneumatic actuators for pick-and-place operations in Ontario battery pack manufacturing lines.
- Manual Controls:Basic lever and push-button pneumatic valves persist in legacy fleet maintenance and aftermarket repair channels.
Electro-Pneumatic handles the majority of new platform throughput; Smart Actuation shows the steepest expansion trajectory as digital twin workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports automotive pneumatic actuators primarily to the United States through integrated North American supply chains, while domestic demand concentrates in Ontario and Quebec vehicle assembly corridors.
Ontario
The Windsor-Toronto automotive corridor generates the dominant share of brake and suspension actuator procurement as vehicle assemblers modernize production lines. Transport Canada harmonizes functional safety requirements with ISO 26262 standards here, mandating ASIL-D certification for brake-linked actuators. Tier-1 suppliers cluster in Oakville and Windsor, locking in multi-year supply agreements with domestic OEMs.
Quebec
Battery electric vehicle platform launches in Bécancour and Montreal are creating demand for lightweight pneumatic thermal management actuators. The Canadian Environmental Protection Act restricts volatile compound releases from pneumatic manufacturing processes across the province, pushing suppliers toward water-based lubrication formulations. Montreal-based integrators are qualifying electro-pneumatic smart modules for EV thermal systems.
Alberta
Industrial automation distributors in Calgary and Edmonton are channeling predictive maintenance pneumatic systems to Tier-2 component suppliers serving resource sector vehicle fleets. Provincial emissions regulations affect pneumatic system sourcing for heavy-duty applications. The Calgary manufacturing hub is adopting smart factory retrofits with integrated valve-actuator-sensor modules.
British Columbia
Zero-emission vehicle mandates from Ottawa are accelerating actuator electrification programs in Vancouver-area clean transportation initiatives. Health Canada sets functional safety benchmarks for automotive components sold provincially, requiring fault-tolerant pneumatic architectures. Vancouver's port infrastructure supports import channels for Asian-manufactured actuator components.
Canada Automotive Pneumatic Actuators Market Competitive Environment
Channel-controlling players compete with product-specialist players across Canada's automotive pneumatic actuator supply base. The market structure tilts toward consolidated Tier-1 supply relationships, with a handful of integrated system suppliers capturing platform-level procurement contracts. Three archetypes dominate: electro-pneumatic technology integrators, legacy pneumatic component fabricators, and sensor-actuator module specialists. Competitive moves center on strategic partnerships for brake-by-wire qualification and portfolio diversification into thermal management actuators for electric platforms.
Among Germany-based industrial technology groups, Bosch Rexroth AG and Continental AG occupy anchor positions in electro-pneumatic brake and suspension systems. Denso Corporation represents the Japanese sensor-actuator integration archetype, competing through modules that reduce engine bay wiring complexity. These three exemplify how geographic origin correlates with technical specialization in Canada's Windsor-Toronto procurement corridor.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Nidec Corporation |
| Denso Corporation |
| SMC Corporation of America |
| Emerson Electric Co. |
| Robert Bosch GmbH |
| Continental AG |
| Hella Automotive |
| Mitsuba Corporation |
| Others |
Value Chain & Pricing Dynamics
Ontario's Windsor-Toronto corridor concentrates brake and suspension actuator fabrication capacity, with Tier-1 supplier clustering near vehicle assembly plants translating into localized pricing power for qualified vendors. This geographic concentration locks in cost-plus contract structures indexed to aluminum alloy and precision-machined component benchmarks, while Transport Canada ASIL-D certification requirements create tiered supplier qualification barriers that segment pricing bands.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate brake actuator procurement between Ontario OEMs and Windsor-Toronto corridor Tier-1 suppliers. Price differentiation hinges on ASIL-D functional safety certification tier and production volume scale, with uncertified mid-tier fabricators facing margin compression from electromechanical substitution in steering applications. Pricing pressure intensifies as vehicle assemblers consolidate multi-year platform agreements, squeezing negotiation leverage for non-integrated component suppliers. Aftermarket providers exhibit highest price sensitivity due to exclusion from new platform qualification cycles, while OEM direct sourcing of electro-pneumatic smart modules commands premium positioning.
Supply Chain Analysis
Export-control restrictions on precision-machined valve components and sensor-integrated modules limit technology flows from German and Japanese manufacturing hubs into Canadian Tier-1 supply chains. Supply concentrates in Germany, Japan, and Mexico for electro-pneumatic brake actuators, with aluminum alloy cylinder housings and high-pressure seal materials drawing from commodity metal markets. Single-source vulnerability persists for ASIL-D certified solenoid valve assemblies, where dual qualification timelines extend eighteen months. Distribution runs through just-in-time channels with four-hour dock-to-line requirements at Ontario vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's automotive pneumatic actuator market tracks cyclical vehicle production recovery, with Ontario light truck platform volumes serving as the primary demand swing factor. Tier-1 supplier consolidation and OEM direct sourcing acceleration create divergent strategic imperatives across market positions.
For Market Incumbents: Entrench platform-level supply relationships through backward integration into aluminum alloy precision machining and ASIL-D certification capacity expansion in Windsor-Oakville corridors. Electromechanical substitution in steering and thermal management applications threatens legacy pneumatic volumes, necessitating electro-pneumatic hybrid R&D investment to defend brake and suspension positioning. For New Entrants and Emerging Players: Pursue Quebec battery electric vehicle thermal management actuator qualification, where lightweight pneumatic solutions for HVAC and battery cooling systems face lower incumbent lock-in than Ontario brake segments. Target industrial automation retrofit channels in Alberta's smart factory upgrade cycle as an alternative path to automotive qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electro-pneumatic module specialists with ISO 26262 software competency and existing Tier-1 brake platform relationships over legacy pneumatic component fabricators. Long-term viability rests on electric vehicle platform penetration rates and the duration of hybrid pneumatic-electric transition demand. Monitor Transport Canada zero-emission vehicle mandate acceleration as the critical inflection signal for electromechanical displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Health Canada harmonized safety standards lock in multi-year brake actuator supply agreements with Ontario OEMs. |
| Electro-Pneumatic Module Development | Integrated valve-actuator-sensor platforms capture brake-by-wire procurement from Windsor-Toronto corridor Tier-1s. |
| Quebec EV Supply Chain Integration | Bécancour and Montreal battery platform launches create demand for lightweight thermal management actuators. |
| Smart Factory Retrofit Channel | Alberta Tier-2 suppliers adopt predictive maintenance pneumatic systems through Calgary industrial distributors. |
| Water-Based Lubrication Transition | Canadian Environmental Protection Act compliance on volatile compound releases forces formulation R&D investment. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and Health Canada regulatory affairs specialists. Secondary validation drew from vehicle production databases, Transport Canada ZEV mandate documentation, IHS Markit registration data, and SEC filings of listed automotive component suppliers. Bottom-up actuator unit demand modeling triangulated against top-down automotive production forecasts across the analysis window.
Calibration against historical brake and suspension actuator procurement volumes anchored the projection framework, with segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from trend extrapolation of electro-pneumatic adoption curves and electromechanical substitution elasticities, incorporating aluminum alloy price volatility assumptions and ASIL-D certification diffusion rates.
Sensitivities concentrate around Transport Canada zero-emission vehicle mandate acceleration, Ontario light truck platform volume fluctuations, and German-Japanese technology export control tightening. Forecasts reflect documented assumptions on hybrid pneumatic-electric transition duration and Tier-1 supplier consolidation velocity. Material shifts in federal clean transportation regulation timelines or electromechanical cost parity achievement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Suspension System Market