
 Rammer Market | 2026-2036
Rammer Market Size, Share, and Industry Trends Forecast 2026-2036
Rammer Market Analysis
EU Green Deal construction equipment emissions targets is consolidating demand toward low-emission compaction equipment across European public works tenders. Wacker Neuson leverages its electric rammer development pipeline to sustain technology leadership in vibratory compaction. Ammann Group anchors German engineering credibility across Middle Eastern infrastructure procurement channels. Chicago Pneumatic competes on pneumatic tool specialization for confined foundation work where hydraulic systems face access constraints.
A rammer is a percussive compaction machine that delivers repeated vertical blows through a spring-actuated or crank-driven foot plate, typically generating impact forces between 10 kN and 40 kN at frequencies of 400 to 700 blows per minute, to densify cohesive soils, granular backfill, or asphalt layers in trenches and foundations. Pneumatic rammers retain dominance in mining and remote construction sites where compressed air infrastructure eliminates electrical hazards, though electric rammers are capturing share in European urban landscaping and indoor foundation work where emissions regulations restrict combustion engines. Trench backfill applications generate the fastest-growing demand pool as utility infrastructure renewal accelerates across aging water and gas networks in North American and European municipalities.
EPA Tier 4 Final nonroad engine standards and EU F-Gas Regulation compliance requirements are reshaping product development roadmaps for engine-powered rammers, while OSHA noise exposure limits in the US and CE machinery directives in Europe mandate operator protection features that add cost but create specification barriers for non-compliant imports. ISO 5349 vibration emission standards further constrain design freedom for handheld and walk-behind units. Stakeholders must monitor battery energy density improvements and fast-charging infrastructure rollout to determine timing for electric product line transitions against residual diesel demand in developing markets.
Market Dynamics
Battery-electric powertrains are compressing the two-stroke engine's dominance in urban compaction equipment as emissions protocols tighten across OECD construction corridors. This electrification wave is restructuring procurement specifications, service revenue models, and manufacturer R&D allocation.
Growth Catalysts
- EU Green Deal equipment mandates:Public works tenders across Germany, France, and the Netherlands now require zero-emission compaction for urban contracts, redirecting municipal procurement toward electric rammers.
- Utility infrastructure renewal:Aging water and gas network rehabilitation in North American municipalities is accelerating trench backfill cycles, expanding rental fleet demand for percussive compaction.
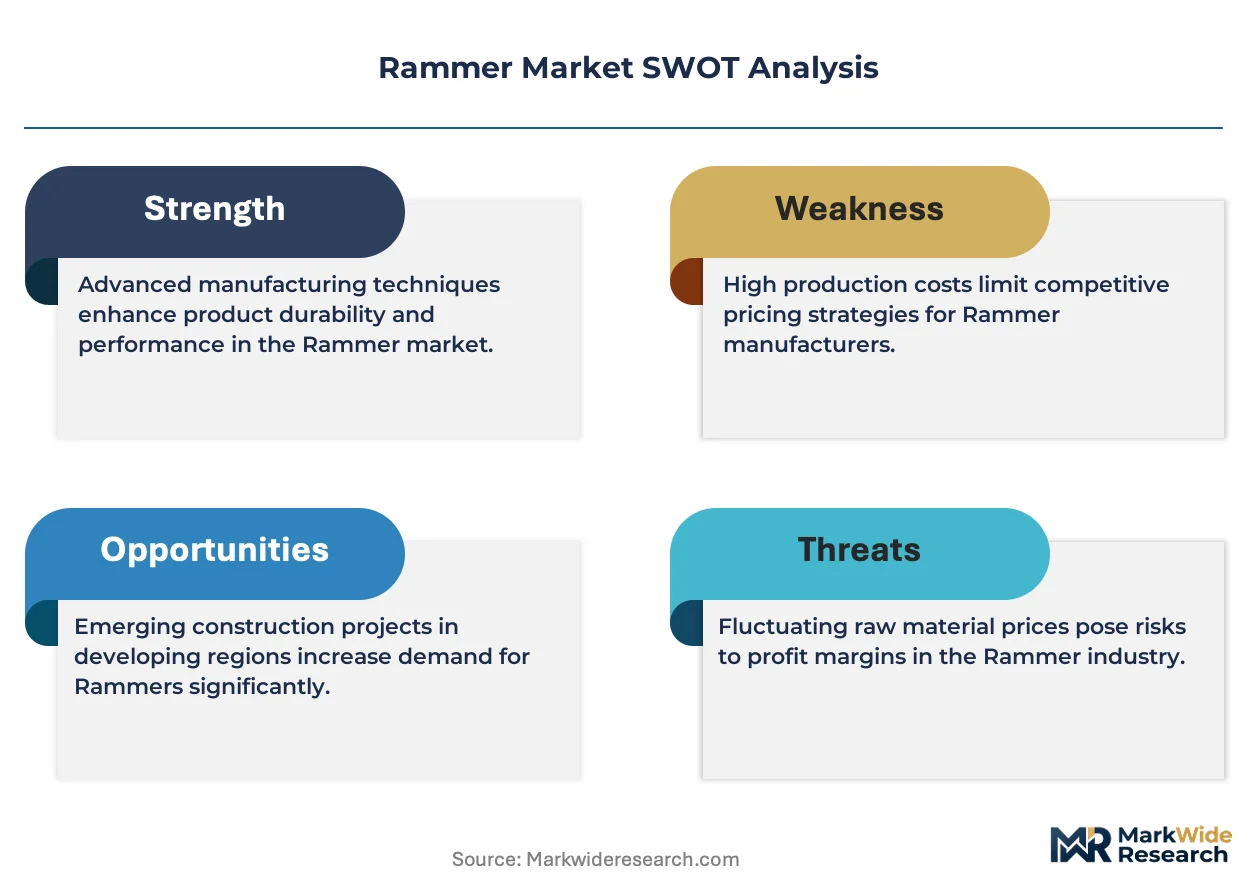
- Lithium-ion energy density gains:Improved battery chemistry is extending runtime per charge for walk-behind electric units, closing the productivity gap with gasoline-powered equivalents on half-day job sites.
Market Restraints
- Steel and aluminum input volatility:Rammer foot plate and housing fabrication faces margin pressure from commodity price swings, compressing OEM profitability on entry-level models.
- Pneumatic infrastructure dependency:Remote mining and tunneling sites remain tethered to compressed air systems, slowing electrification in regions without grid reliability.
- OSHA noise exposure compliance:Operator hearing protection mandates add cost to handheld unit designs, creating specification barriers for import competitors lacking certified attenuation engineering.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea tourism infrastructure are consolidating demand for high-cycle rammers in desert soil conditions, favoring durable pneumatic and hydraulic platforms.
- Fast-charging infrastructure rollout:Construction site electrification partnerships with equipment lessors are enabling battery-swap service models that reduce downtime anxiety for electric adopters.
- CE machinery directive convergence:Harmonized safety certification across EU member states is streamlining cross-border equipment mobility, reducing compliance fragmentation for multi-national contractors.
Industry Challenges
- ISO 5349 vibration certification timelines:Handheld unit manufacturers face extended testing protocols for whole-body vibration emissions, delaying product launches and freezing R&D budgets.
- Legacy fleet retrofit complexity:Rental companies struggle to integrate telematics and battery management systems into existing maintenance workflows without parallel workforce retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rammer Market |
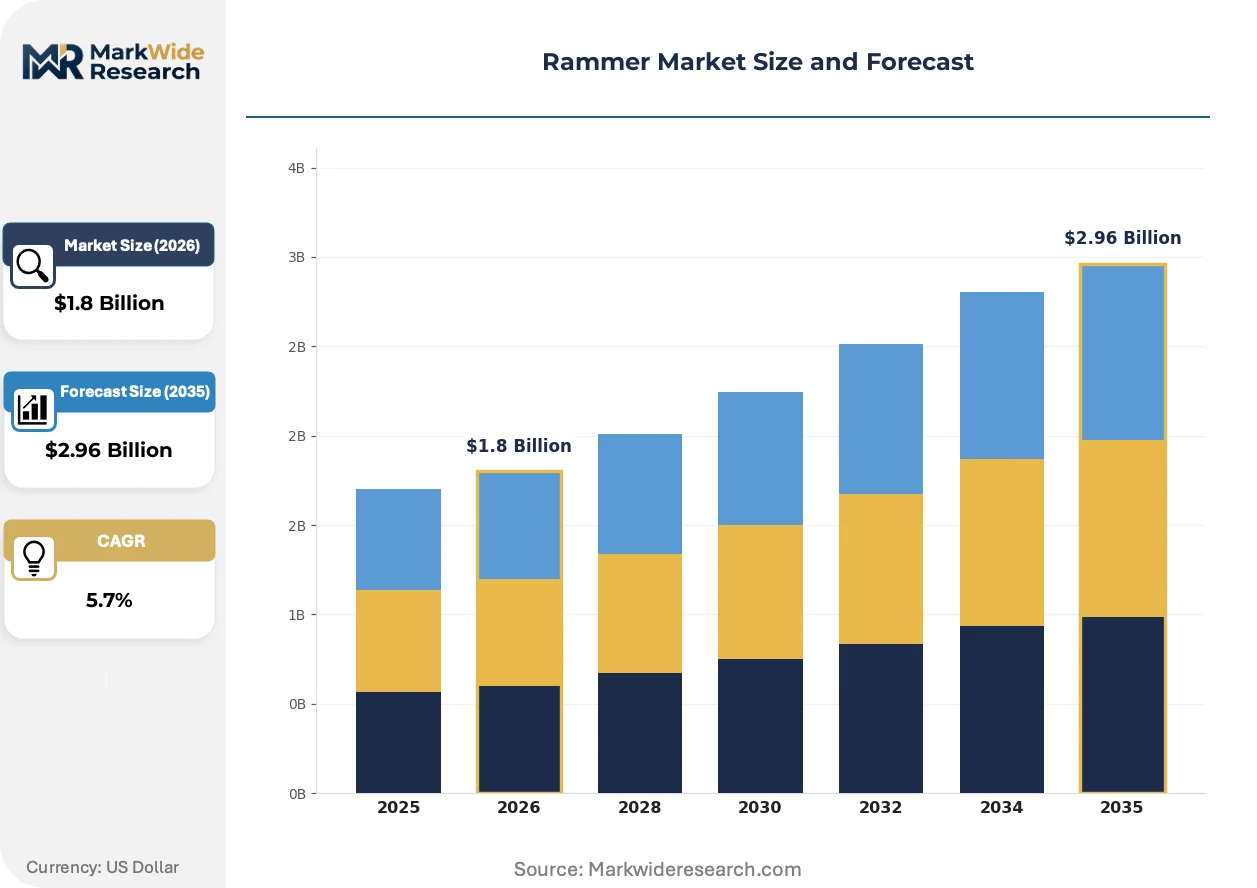
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Rammer, Hydraulic Rammer, Electric Rammer, Manual Rammer End User: Construction, Mining, Road Maintenance, Landscaping Application: Soil Compaction, Asphalt Compaction, Foundation Work, Trench Backfill Technology: Vibratory Rammer, Plate Rammer, Jumping Jack Rammer, Heavy Duty Rammer |
| Companies Covered | Simpson Technologies, Chicago Pneumatic, Ammann Group, JCB, Wacker Neuson, Atlas Copco, Ingersoll Rand, Doosan Corporation, Bomag GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rammer Market Emerging Trajectories
Electrification is rewiring competitive advantage in compaction equipment as battery chemistry and power electronics mature faster than combustion engine efficiency gains. This shift is compressing the traditional technology lifecycle and forcing simultaneous investment in service infrastructure.
Brushless DC motor and silicon carbide inverter technology is integrating into walk-behind electric rammers, delivering impact force parity with 4-stroke engines while eliminating exhaust emissions. Municipal landscaping contractors in German urban zones are adopting these platforms aggressively to secure Green Deal-compliant tender awards. The technology is integrating predictive maintenance capabilities through embedded current sensors that flag bearing wear before catastrophic failure.
EPA Tier 4 Final nonroad engine standards are forcing gasoline-powered rammer redesigns with costly aftertreatment systems that add weight and maintenance burden. Equipment rental chains in the United States are responding by accelerating electric unit procurement to sidestep compliance complexity and parts availability constraints. The regulation is compressing residual value forecasts for combustion fleets, pressuring asset-heavy lessors toward earlier replacement cycles.
Outcome-based equipment access models are displacing traditional ownership in European construction markets, with contractors preferring hourly-rate rental agreements bundled with maintenance and compliance certification. This behavior is concentrating fleet purchasing power with multi-national rental companies that can amortize electrification investments across regional asset pools. Germany and the Netherlands exhibit the fastest adoption curves, where project-based contracting and strict emissions zones amplify total-cost-of-ownership sensitivity.
Rammer Market Segmentation
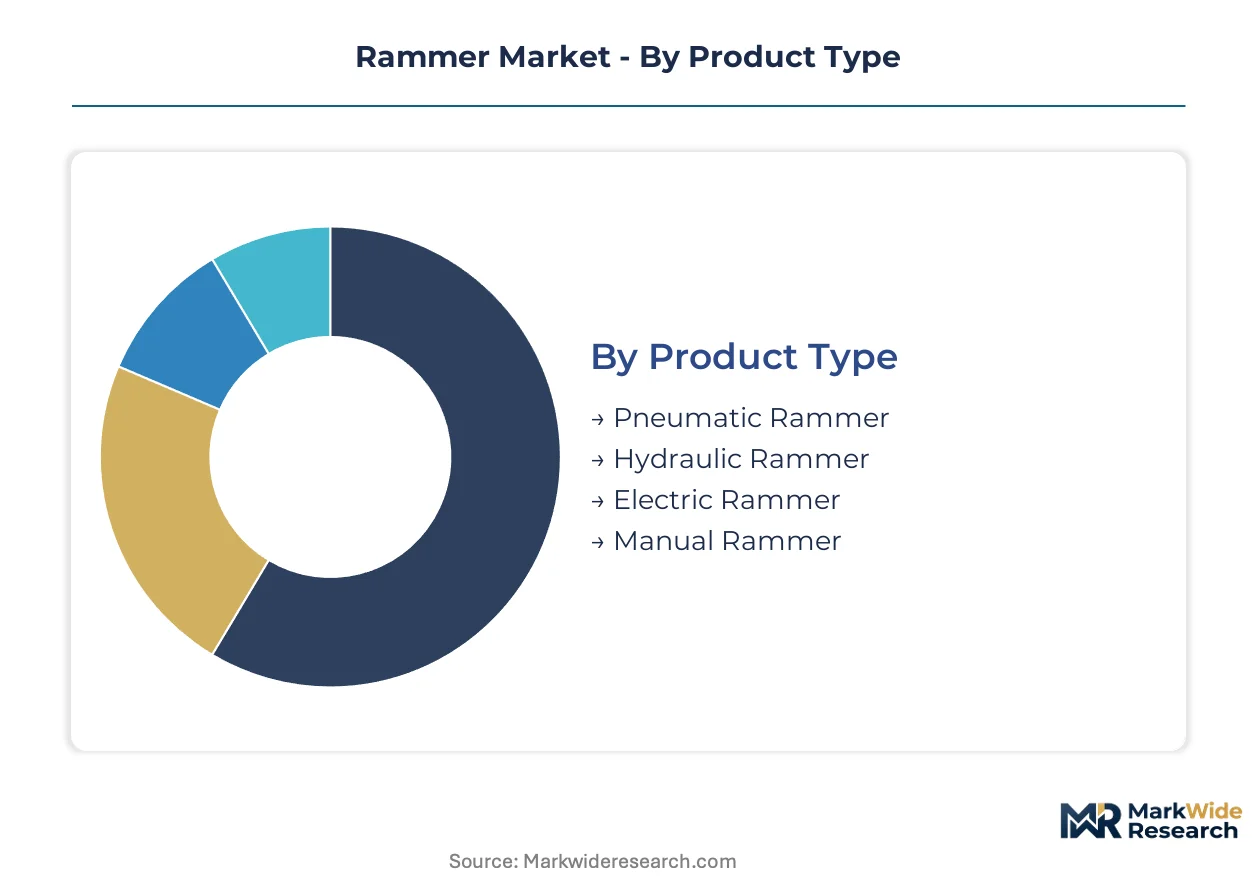
Rammer procurement patterns diverge sharply between standalone equipment purchases and fleet-integrated deployments, with electrification timelines and rental penetration reshaping which segments command premium positioning. Understanding these fault lines reveals where specification power concentrates and how compliance requirements fragment demand.
Product Type:
Pneumatic rammers operate as standalone compressed-air systems in mining and tunneling environments where electrical hazards prohibit alternatives, while electric variants embed into urban construction fleets governed by emissions protocols.
- Pneumatic Rammer:Compressed-air actuation delivers impact forces through spring-loaded foot plates without ignition sources, making these units indispensable in underground mining operations across Chile, Australia, and South Africa where methane accumulation risks mandate intrinsically safe equipment. Demand concentrates in hard-rock extraction sites where pneumatic infrastructure already exists, though electrification pressures are beginning to penetrate surface operations.
- Hydraulic Rammer:Fluid-power systems generate higher impact energies for cohesive soil densification in heavy civil projects, with German and Japanese OEMs dominating specification sheets for Middle Eastern foundation contracts requiring all-day runtime reliability. Municipal utilities in the Netherlands specify hydraulic units for water main trench backfill where productivity metrics outweigh capital cost sensitivity.
- Electric Rammer:Battery-powered units eliminate exhaust emissions for urban landscaping and indoor foundation work, with lithium-ion chemistry advances closing the runtime gap on half-day job sites in German and French metropolitan zones.
- Manual Rammer:Human-powered compaction serves confined access repairs and developing market micro-contractors where capital constraints and intermittent usage patterns preclude engine investments.
Pneumatic rammers lead volumes today; electric rammers are gaining share fastest.
End User:
Construction contractors absorb capital equipment directly into owned fleets, while mining and road maintenance operations increasingly route procurement through rental intermediaries that amortize compliance investments across regional asset pools.
- Construction:General contractors deploy rammers across foundation preparation, utility trenching, and landscaping phases, with German and Dutch firms accelerating electric adoption to secure Green Deal-compliant municipal tenders. Specification power concentrates with tier-one builders capable of absorbing higher upfront capital for total-cost-of-ownership advantages.
- Mining:Underground extraction operations mandate pneumatic rammers for safety compliance in gassy environments, with procurement decisions centralized at headquarters level rather than site level to ensure fleet standardization and parts commonality across remote operations.
- Road Maintenance:Municipal and state transportation departments operate periodic resurfacing cycles that favor rental arrangements over ownership, concentrating demand with national equipment lessors who can guarantee ISO-certified maintenance documentation.
- Landscaping:Smaller contractors in urban European zones prioritize maneuverability and emissions compliance over raw productivity, creating a price-sensitive segment where electric walk-behind units are displacing two-stroke alternatives most aggressively.
Construction absorbs the highest absolute unit volumes; landscaping is expanding most quickly.
Application:
Soil compaction demands span standalone rural deployments and embedded urban infrastructure workflows, with trench backfill applications experiencing the steepest specification tightening as utility network renewal accelerates.
- Soil Compaction:Cohesive and granular soil densification in building pads and embankments requires calibrated impact energy matched to soil classification, with German geotechnical standards influencing specification patterns across Central European public works.
- Asphalt Compaction:Bituminous layer densification for road surfaces and parking areas demands heated foot plate designs that prevent material adhesion, a feature concentration among premium-tier manufacturers serving highway maintenance contractors.
- Foundation Work:Building footprint preparation in residential and commercial construction concentrates demand for mid-weight rammers that balance transportability with sufficient impact force for clay-heavy substrates in northern European markets.
- Trench Backfill:Utility pipeline bedding and cover compaction is experiencing accelerated cycle frequencies as aging water and gas network rehabilitation programs expand across North American and European municipalities, with EPA and EU F-Gas Regulation compliance requirements redirecting rental fleet procurement toward electric alternatives.
Soil compaction maintains the largest installed base; trench backfill is climbing the fastest.
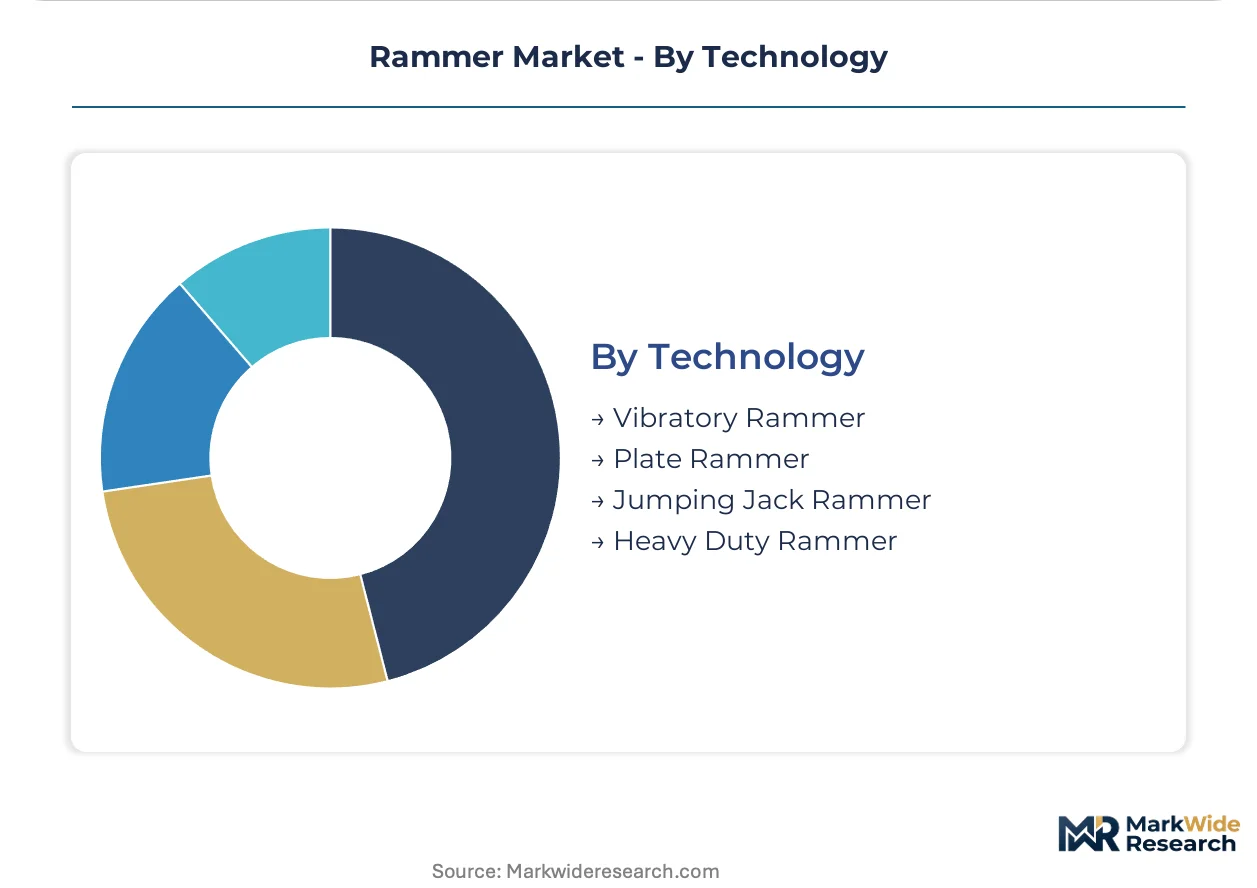
Technology:
Vibratory and plate rammer designs dominate mature replacement demand, while jumping jack configurations capture specification share in confined access applications where dimensional constraints override productivity optimization.
- Vibratory Rammer:Eccentric mass rotation generates high-frequency, low-amplitude compaction waves optimized for granular soils and asphalt layers, with German and Austrian engineering houses holding specification authority in CE-marked European markets.
- Plate Rammer:Large-footprint designs distribute compaction energy over broader surface areas for slab subgrade preparation, favored by commercial concrete contractors in the United States where slab-on-grade construction dominates.
- Jumping Jack Rammer:Vertical reciprocating foot plates deliver concentrated impact forces in narrow trench profiles, with OSHA noise exposure and ISO 5349 vibration standards driving design differentiation between premium-certified and economy-tier imports.
- Heavy Duty Rammer:Reinforced structural components and extended maintenance intervals serve high-utilization rental fleets and mining operations where downtime costs exceed capital premiums, with Saudi giga-project specifications consolidating demand around proven German and Japanese platforms.
Vibratory rammers command the broadest installed base; jumping jack configurations are expanding most rapidly in utility applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses pioneered percussive compaction technology during post-war reconstruction, establishing design standards that still govern European public works specifications. Today, procurement patterns reflect divergent infrastructure investment cycles and emissions enforcement intensity across OECD construction corridors.
United States
Municipal utility rehabilitation programs across rust-belt cities are accelerating trench backfill equipment cycles. EPA Tier 4 Final nonroad engine standards are compressing residual values for gasoline-powered rental fleets. Equipment lessors in Texas and Ohio are consolidating electric unit procurement to sidestep compliance complexity.
Germany
EU Green Deal construction equipment mandates are redirecting municipal tender specifications toward zero-emission compaction platforms. The F-Gas Regulation compliance requirements are reshaping product development roadmaps for engine-powered variants. Bavarian and Baden-Württemberg manufacturing clusters anchor engineering credibility for Middle Eastern infrastructure export contracts.
Saudi Arabia
NEOM and Red Sea tourism giga-projects are consolidating demand for high-cycle pneumatic and hydraulic platforms in desert soil conditions. The central government's infrastructure investment authority is standardizing equipment specifications across megaproject sites. Eastern Province construction corridors are absorbing premium-tier German and Japanese engineered units.
Netherlands
Strict urban emissions zones in Amsterdam and Rotterdam are amplifying total-cost-of-ownership sensitivity for landscaping contractors. CE machinery directive harmonization is streamlining cross-border equipment mobility for multi-national contractors. Randstad metropolitan infrastructure tenders now require battery-electric compaction for canal-side and indoor foundation work.
Australia
Hard-rock mining operations across Western Australia and Queensland remain tethered to pneumatic rammers for intrinsically safe underground compliance. Surface construction sites in New South Wales are beginning to test electric alternatives where grid reliability permits. The country's national work safety regulator is tightening whole-body vibration exposure limits for handheld unit operators.
Rammer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and after-sales service density. The vendor base arranges into three tiers: integrated multi-nationals with rental fleet partnerships, specialized German and Japanese engineering houses with specification authority in public works, and regional fabricators competing on price for developing market volume. Consolidation pressure concentrates among mid-scale European manufacturers facing electrification R&D burdens. Dominant competitive moves include strategic partnerships with construction equipment lessors and geographic expansion into Saudi giga-project corridors.
Within the integrated multi-national tier, Atlas Copco and Ingersoll Rand occupy positions anchored by compressed air system integration capabilities. Among specialized German engineering houses, Ammann Group and Wacker Neuson exemplify specification authority derived from CE-marked safety certification and decades of municipal tender penetration. Chicago Pneumatic represents the pneumatic tool specialization archetype, serving confined foundation access segments where hydraulic systems face dimensional constraints.
| Leading Market Players |
|---|
| Simpson Technologies |
| Chicago Pneumatic |
| Ammann Group |
| JCB |
| Wacker Neuson |
| Atlas Copco |
| Ingersoll Rand |
| Doosan Corporation |
| Bomag GmbH |
| Others |
Supply Flow & Price Mechanics
EU Green Deal construction equipment emissions mandates gate qualified supply and premium-tier pricing access, concentrating certified manufacturing capacity among German and Austrian engineering houses while elevating entry costs for non-compliant competitors. Municipal tender specifications now bundle emissions certification with maintenance documentation, forcing price stratification between CE-marked premium platforms and economy-tier imports lacking ISO 5349 vibration attestation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification depth and after-sales bundling. Premium tiers command spreads through CE-marked safety engineering and predictive maintenance integration, while standard tiers compete on runtime reliability for rental fleet operators. Cost compression in economy segments is intensifying because commodity steel and aluminum volatility squeezes foot plate fabrication margins. Landscaping contractors in Dutch urban emissions zones exhibit highest price sensitivity, whereas Saudi giga-project procurement shows lowest sensitivity due to downtime-cost prioritization.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Baden-Württemberg manufacturing clusters are tightening component lead times for precision-machined crankshaft assemblies. Supply concentrates in Germany, Japan, and China, with German houses anchoring specification authority and Chinese fabricators serving developing market volume tiers. Raw material dependencies rest on high-grade steel forgings, lithium-ion battery cells, and aluminum castings. Single-source vulnerability runs through specialized bearing suppliers serving eccentric mass rotation systems. Distribution runs through multi-national equipment lessors and regional aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU emissions-mandated premium procurement and Middle Eastern volume absorption, with regulatory compliance cost differentials creating margin expansion opportunities for certified exporters.
For Market Incumbents: To counter battery-electric technology disruption from adjacent power tool manufacturers, deepen backward integration into brushless DC motor production and secure captive supply of silicon carbide inverters. Prioritize certification investment for ISO 5349 vibration attestation to maintain specification barriers against Asian import competitors. For New Entrants and Emerging Players: Launch via battery-swap service partnerships with municipal equipment pools in Dutch and German urban zones. Target trench backfill applications for water utility contractors where electrification mandates outpace incumbent electric product availability. Penetrate through outcome-based rental models that bundle compliance documentation with hourly-rate equipment access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European manufacturers facing electrification R&D burdens without rental fleet partnerships. Long-term viability over the next decade hinges on service revenue density and geographic diversification into Saudi giga-project corridors. Watch battery energy density improvement trajectories as the inflection signal for electric product line transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive supply of silicon carbide inverters secures margin control against semiconductor volatility. |
| CE Marking Pathway Acceleration | Expedited EU machinery directive compliance opens municipal tender access across German and Dutch markets. |
| Battery-Swap Service Partnership | Construction site electrification alliances with lessors reduce downtime anxiety for electric adopters. |
| Geographic Expansion into Saudi Giga-Projects | NEOM and Red Sea infrastructure specifications consolidate demand for high-cycle pneumatic platforms. |
| Predictive Maintenance Platform Launch | Embedded current sensors flag bearing wear before failure, shifting revenue toward service contracts. |
Methodological Framework
Coverage spans North America, Europe, Middle East, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged equipment rental fleet managers, municipal procurement officers, OEM engineering directors, aftermarket service heads, and mining operations safety leads. Secondary sources included SEC filings from listed equipment manufacturers, EU tender documentation databases, EPA compliance certification records, and customs trade data for compaction machinery. Bottom-up unit demand modeling and top-down market sizing were cross-validated to establish forecast integrity.
Granularity-level modeling deployed product type, end user, application, and technology dimensions at country-level resolution across the analysis window. CAGRs were derived from regression analysis against infrastructure investment cycles and regulatory phase-in schedules. Forecast inputs incorporated battery chemistry improvement curves, municipal utility rehabilitation program announcements, and Saudi giga-project equipment specification releases.
Several conditions sit outside the modeled scope, including unannounced regulatory phase-in delays, commodity price shocks exceeding historical volatility bands, and breakthrough solid-state battery commercialization timelines. Forecasts reflect documented assumptions about electrification adoption rates and rental fleet replacement cycles. Material deviation in battery energy density trajectories or EU Green Deal enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Universal Joint Shafts Market