
 Japan Commercial Vehicles Lubricants Market | 2026-2036
Japan Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Commercial Vehicles Lubricants Market Foresight
Domestic refinery output in Japan is recalibrating around lower-sulfur base oil production to align with emission norms. ENEOS Corporation leverages its integrated refining network to secure feedstock continuity across the archipelago. Idemitsu Kosan Co Ltd anchors its position through specialized heavy-duty engine oil formulations for commercial fleets. ExxonMobil Corporation competes by extending its synthetic lubricant portfolio through direct technical service agreements with large transport operators.
Japan commercial vehicles lubricants encompass formulated fluids engineered to reduce friction, dissipate heat, and prevent wear in diesel and gasoline engines operating under high load cycles, with viscosity grades typically spanning SAE 15W-40 to 10W-30 for heavy-duty applications. These products serve to extend equipment life and maintain fuel efficiency in trucks and buses covering intensive daily mileage. Engine oil commands the largest volume share given universal application across every commercial vehicle class, while hydraulic fluid generates concentrated margin pools in construction equipment segments where anti-wear additive packages command premium positioning. The logistics end user segment leads absolute consumption as just-in-time delivery networks impose relentless vehicle utilization rates.
METI enforces fuel economy benchmarks that directly influence lubricant viscosity grade approvals, while JIS standards govern minimum performance specifications for commercial vehicle fluids sold in Japan. The country's national petroleum regulator monitors base oil refining emissions, creating compliance costs that favor larger blenders with captive refining assets. Stakeholders must monitor how carbon neutrality commitments reshape base oil sourcing strategies and whether synthetic formulations displace mineral oils in municipal bus fleets.
Market Dynamics
Fleet operators across Japan's logistics corridors are compressing oil drain intervals while METI tightens fuel economy benchmarks, creating simultaneous pressure for lower-viscosity formulations and extended service life.
Growth Catalysts
- Heavy-duty logistics utilization:Just-in-time delivery networks in the Kanto region impose relentless vehicle duty cycles that accelerate lubricant consumption and drive replacement frequency.
- METI fuel economy mandates:Tightening viscosity requirements under Japan's energy efficiency framework force formulation upgrades that expand addressable product value per vehicle.
- Group III base oil expansion:Domestic refinery recalibration toward lower-sulfur hydrocracked stocks improves feedstock quality for premium synthetic blends serving municipal bus fleets.
Market Restraints
- Feedstock cost volatility:Crude-linked Group II and III base oil prices expose blenders to margin compression when refining spreads tighten.
- Refinery asset concentration:Captive base oil production concentrates among integrated refiners, limiting independent blender access to domestic hydrocracked stocks.
- Mineral oil substitution ceiling:Price-sensitive owner-operator segments resist synthetic premiums despite performance advantages, capping category migration speed.
Strategic Opportunities
- Construction equipment hydraulics:Anti-wear additive packages for excavators and cranes command premium positioning in a segment with less price sensitivity than highway trucking.
- Carbon-neutral procurement mandates:Municipal transit authorities are piloting re-refined base oil acceptance, opening circular supply contracts for certified sustainable formulations.
- Direct fleet technical service:Large transport operators are consolidating supplier relationships around embedded fluid analysis and drain interval optimization programs.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for heavy-duty diesel dispersant packages is concentrating among retiring specialists at major blenders.
- JIS certification timelines:New viscosity grade approvals require extended bench and field testing that delays product launches by multiple test cycles.
- Legacy fleet compatibility:Older commercial vehicles with elastomer seal materials face compatibility risks with newer ester-based synthetic chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Commercial Vehicles Lubricants Market |
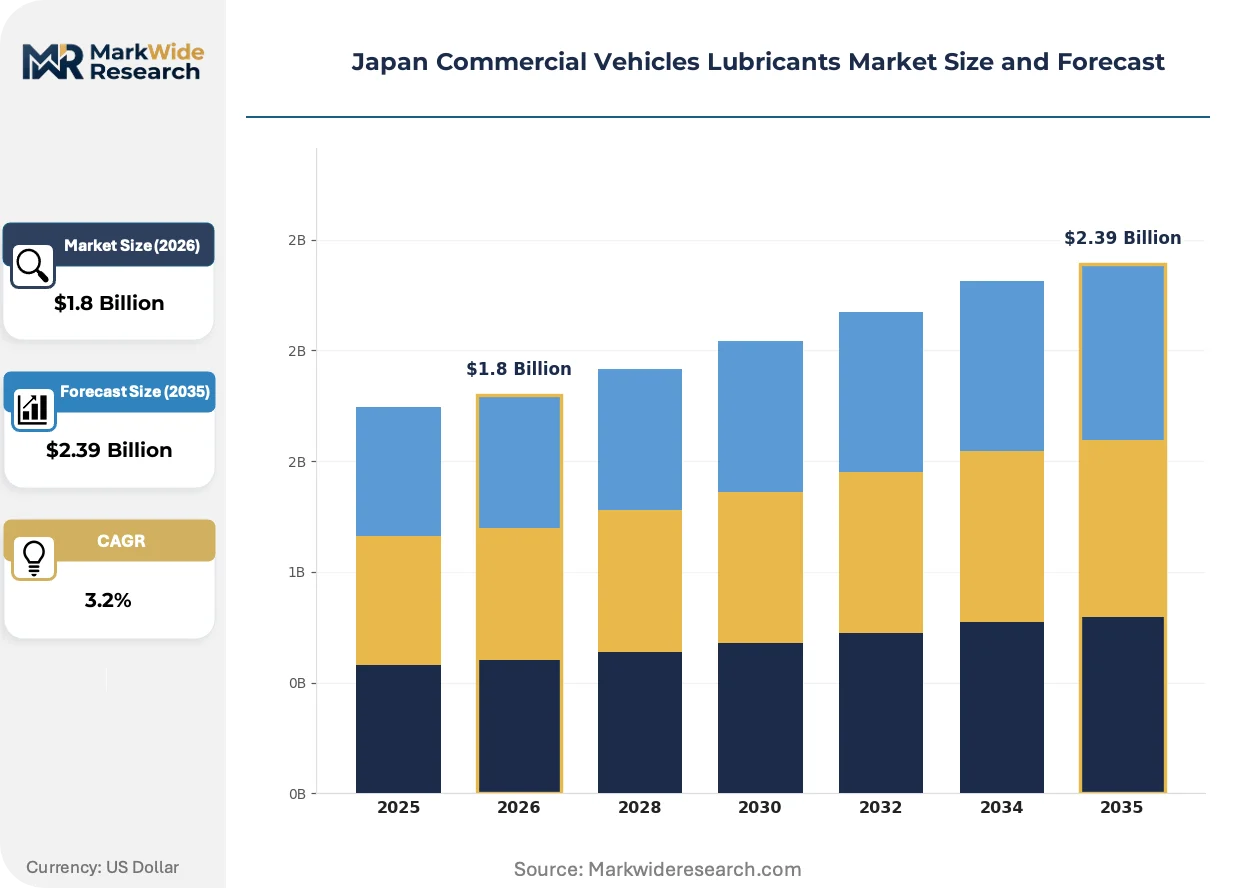
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Grease End User: Logistics, Construction, Agriculture, Transportation Distribution Channel: Online Retail, Direct Sales, Retail Stores, Distributors Application: Heavy Duty Vehicles, Light Duty Vehicles, Commercial Trucks, Buses |
| Companies Covered | Cosmo Energy Holdings Co Ltd, FUCHS, ENEOS Corporation, AKT Japan Co Ltd, Japan Sun Oil Company Ltd, Idemitsu Kosan Co Ltd, Royal Dutch Shell Plc, Chugoku Kogyo Co Ltd, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Commercial Vehicles Lubricants Market Shifts & Advancements
Fluid formulation strategies are fragmenting across end-use specialization, with additive packages diverging sharply between highway diesel, off-highway hydraulic, and natural gas engine applications.
Polyalkylene glycol synthetic base stocks are modularizing lubricant architecture for dual-fuel and natural gas commercial engines. Fleet operators in Tokyo's freight corridors are specifying these formulations for mixed-composition vehicle pools. The technology is modularizing service protocols by enabling unified inventory management across diesel and alternative-fuel assets.
METI's 2030 fuel economy roadmap is mandating SAE 10W-30 and lower viscosity grades for new heavy-duty vehicle registrations. Blenders must reformulate high-temperature high-shear stability into thinner base stocks without sacrificing wear protection. Highway trucking fleets in the Kanto corridor are responding by accelerating drain interval monitoring through onboard oil condition sensors.
Consolidated procurement by mega-fleets is compressing distributor margins and displacing traditional jobber networks. Large logistics operators in Osaka and Nagoya are negotiating direct supply agreements with technical service attachments. The shift is most visible among refrigerated transport specialists where temperature-controlled cargo liability demands documented fluid performance guarantees.
Japan Commercial Vehicles Lubricants Market Segmentation
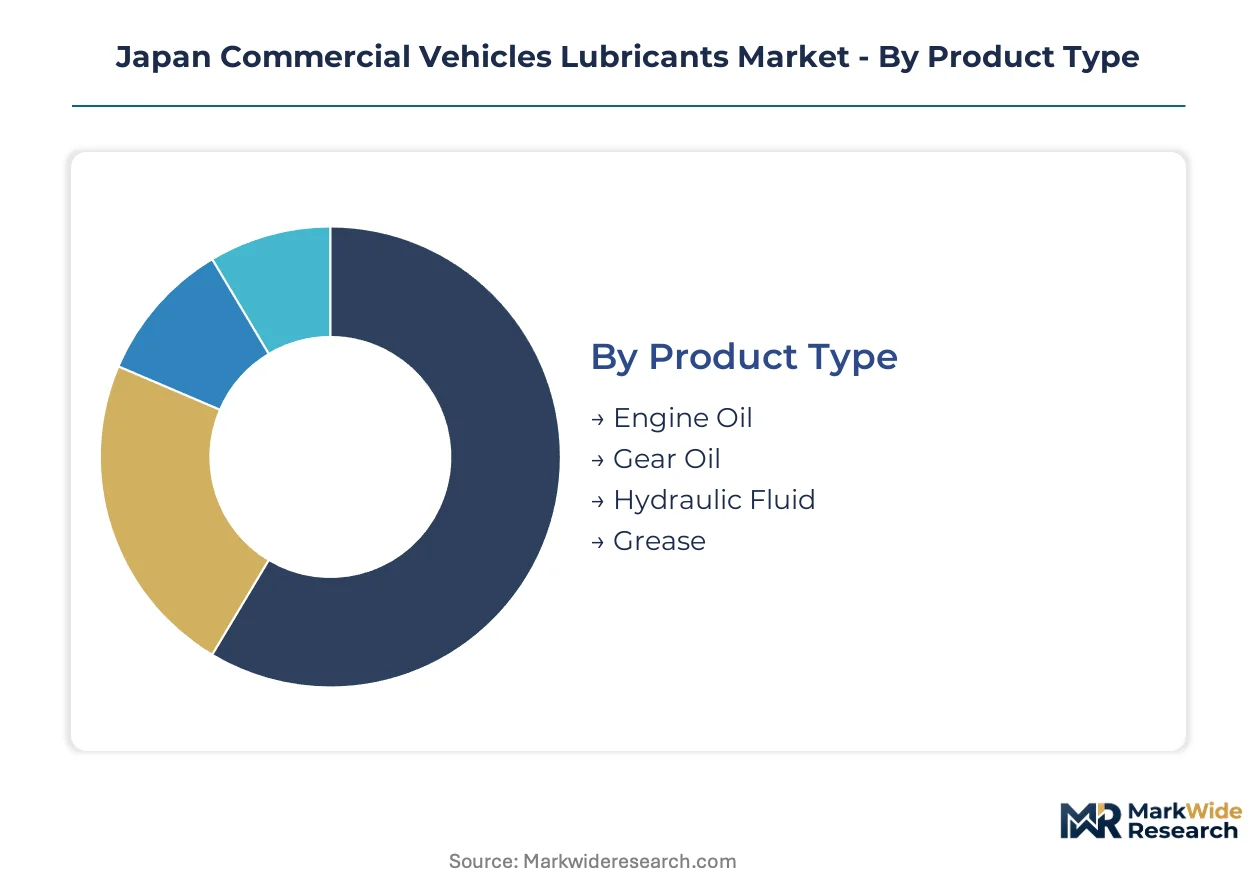
Commercial vehicle lubricant procurement in Japan fragments across four distinct segmentation axes. Each dimension reflects divergent technical requirements, channel economics, and regulatory exposure that shape supplier positioning and margin capture.
Product Type:
Standardization dominates mineral-based formulations while synthetic and semi-synthetic variants command customization premiums tied to fleet-specific drain interval targets.
- Engine Oil:Formulated fluids spanning SAE 15W-40 to 10W-30 viscosity grades serve diesel and gasoline engines under high-load cycles. Kanto region logistics fleets consume the largest volumes as just-in-time delivery networks impose relentless daily mileage requirements.
- Hydraulic Fluid:Anti-wear additive packages for construction equipment command premium positioning. Municipal infrastructure projects in Osaka and Nagoya corridors concentrate demand where equipment downtime costs outweigh fluid price sensitivity.
- Gear Oil:Extreme-pressure formulations protect commercial vehicle transmissions and differentials. Heavy-duty trucking operators specify these for extended drain intervals under METI fuel economy compliance pressures.
- Grease:Lithium-complex and polyurea-thickened lubricants serve chassis, wheel bearing, and fifth-wheel applications. Regional bus fleets in Hokkaido and Kyushu generate seasonal demand spikes tied to winter operating conditions.
Most installed capacity flows through Engine Oil. Expansion is steepest in Hydraulic Fluid.
End User:
Volume concentration versus margin capture splits sharply across customer types, with asset utilization rates determining formulation sophistication and service attachment potential.
- Logistics:Just-in-time delivery networks compress vehicle downtime tolerance. Tokyo-Osaka freight corridor operators specify synthetic blends with onboard oil condition monitoring to extend drain intervals under METI mandates.
- Construction:Excavator and crane fleets demand anti-wear hydraulic packages with premium additive loading. Kansai region infrastructure investment cycles drive irregular but high-margin procurement patterns.
- Agriculture:Seasonal equipment use patterns favor mineral-based economy formulations. Hokkaido grain cooperatives and Kyushu citrus operations represent fragmented, price-sensitive demand.
- Transportation:Municipal and intercity bus fleets face accelerating carbon-neutral procurement mandates. Tokyo Metropolitan Bureau of Transportation pilots re-refined base oil acceptance, opening circular supply contracts.
Logistics channels the greatest absolute volume. Bus fleet decarbonization programs are gaining share fastest.
Distribution Channel:
Channel structure reflects fleet scale concentration, with mega-operators disintermediating traditional networks while smaller buyers remain distributor-dependent.
- Direct Sales:Large transport operators negotiate embedded technical service agreements. Refrigerated logistics specialists in Nagoya and Osaka demand documented fluid performance guarantees with temperature-controlled cargo liability coverage.
- Distributors:Independent blenders and regional jobbers serve mid-sized fleet operators. Chubu and Tohoku regions retain denser distributor networks due to fragmented customer geography.
- Retail Stores:Owner-operators and small construction contractors purchase through automotive parts chains. Price transparency pressures margins on standard mineral formulations.
- Online Retail:E-commerce platforms capture growing share among rural agricultural equipment users. Bulk packaging options and technical documentation availability drive channel migration.
Distributors still handle the majority of volume throughput. Direct Sales is climbing the fastest as mega-fleets consolidate supplier relationships.
Application:
Duty cycle severity and regulatory scrutiny intensity create divergent formulation requirements across vehicle classes.
- Heavy Duty Vehicles:Class 7-8 trucks operating above 26,000 pounds gross vehicle weight require high-temperature high-shear stable formulations. METI's tightening viscosity mandates force continuous reformulation investment.
- Commercial Trucks:Light and medium-duty highway freight vehicles dominate unit volume. Kanto corridor operators balance fuel economy compliance against legacy fleet compatibility concerns with newer ester-based synthetics.
- Buses:Urban transit and intercity coach applications face the most aggressive carbon-neutral procurement timelines. Municipal operators in Tokyo, Yokohama, and Nagoya pilot re-refined and bio-based alternatives.
- Light Duty Vehicles:Commercial vans and small delivery trucks represent the most price-sensitive segment. Independent owner-operators resist synthetic premiums despite performance advantages.
Commercial Trucks absorb the largest share of current formulation output. Bus fleet sustainable procurement mandates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blenders in Japan face compliance cost arbitrage as METI emission standards tighten, while regional production clusters recalibrate around lower-sulfur base oil output. Refinery asset concentration in specific prefectures creates localized supply advantages that shape competitive positioning.
Kanto
Tokyo freight corridors generate the highest lubricant consumption density among Japanese regions. METI fuel economy benchmarks force continuous viscosity grade reformulation for Class 7-8 trucks serving just-in-time logistics networks. Chiba and Kanagawa prefectures host integrated refining complexes that supply hydrocracked base stocks to regional blenders.
Kansai
Osaka-Nagoya industrial belt concentrates construction equipment hydraulic fluid demand. Municipal infrastructure investment cycles in Kyoto and Hyogo prefectures drive irregular but high-margin procurement patterns for anti-wear additive packages. JIS certification requirements extend product launch timelines for local formulators serving this segment.
Chubu
Nagoya automotive manufacturing clusters anchor synthetic lubricant consumption for commercial vehicle production lines. Toyota Motor Corporation's supplier ecosystem in Aichi prefecture specifies premium formulations for fleet validation testing. Regional distributors maintain denser networks here due to fragmented mid-sized fleet geography across Gifu and Shizuoka prefectures.
Kyushu
Agricultural cooperatives in Fukuoka and Kagoshima prefectures generate seasonal mineral oil demand for harvesting equipment. Owner-operator price sensitivity caps synthetic penetration despite performance advantages. Regional bus fleets in Kumamoto pilot re-refined base oil acceptance under municipal carbon-neutral procurement timelines.
Hokkaido
Winter operating conditions in Sapporo and Asahikawa drive seasonal grease demand spikes for chassis and wheel bearing applications. Grain cooperatives in the Tokachi plain represent fragmented, price-sensitive agricultural equipment lubricant consumption. Cold-start viscosity requirements shape formulation specifications distinct from Honshu standards.
Japan Commercial Vehicles Lubricants Market Competitive Landscape
Japanese integrated refiners anchor one tier; international oil majors and specialized domestic blenders occupy differentiated positions. The market structure reflects captive base oil production advantages concentrated among archipelago-based refiners with hydrocracking capacity. Three archetypes dominate: integrated energy conglomerates with full refining-to-blending control, global lubricant specialists leveraging technical service agreements, and regional independents serving price-sensitive owner-operators. Competitive moves center on direct fleet technical service embedding and synthetic formulation portfolio expansion.
Among Japan-based integrated producers, ENEOS Corporation and Idemitsu Kosan Co Ltd exemplify the refiner-blender archetype with captive feedstock access. ExxonMobil Corporation represents the international major tier competing through synthetic portfolio breadth. These three entities occupy positions that reflect the market's split between domestic supply security priorities and global formulation technology access.
| Leading Market Players |
|---|
| Cosmo Energy Holdings Co Ltd |
| FUCHS |
| ENEOS Corporation |
| AKT Japan Co Ltd |
| Japan Sun Oil Company Ltd |
| Idemitsu Kosan Co Ltd |
| Royal Dutch Shell Plc |
| Chugoku Kogyo Co Ltd |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
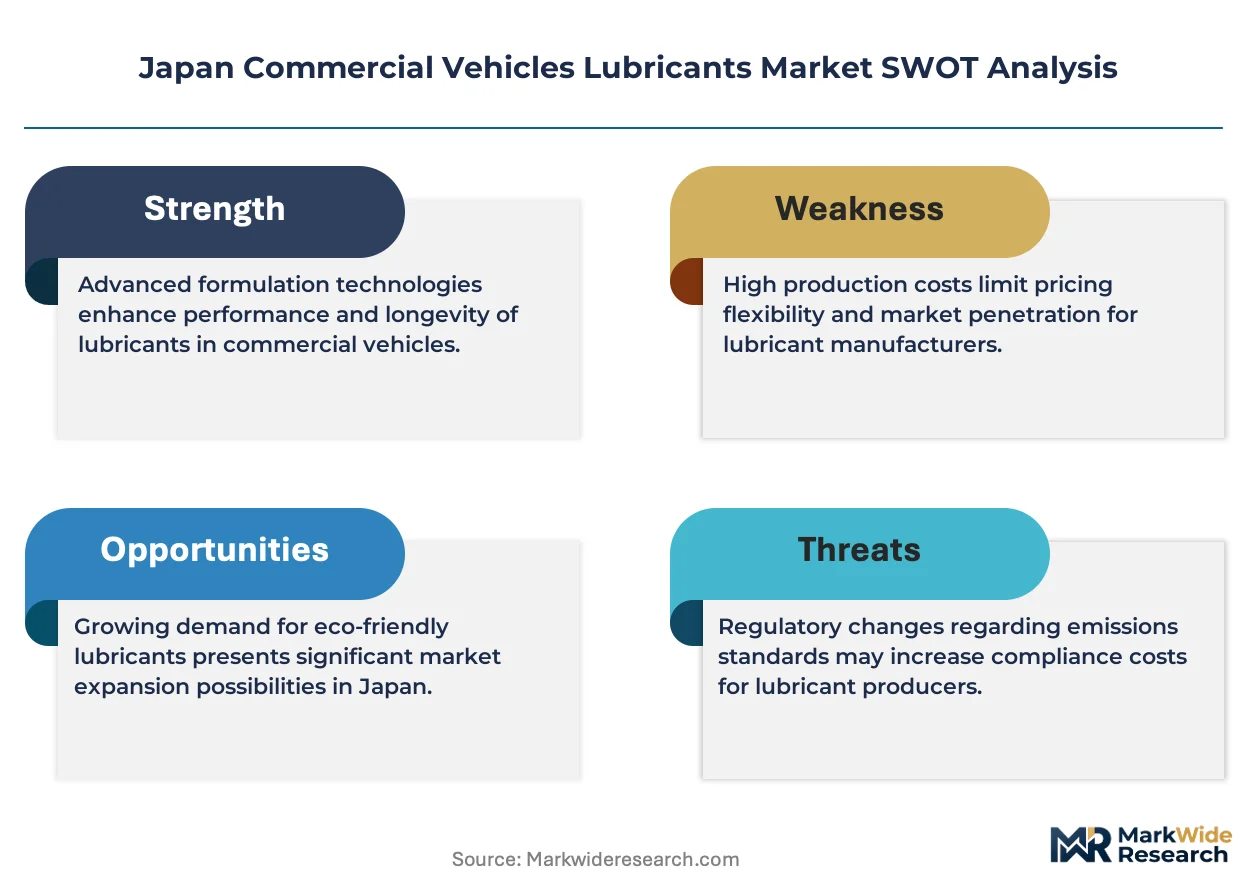
Group III base oil hydrocracking expansion across Chiba and Kanagawa prefectures simultaneously reduces sulfur compliance costs and concentrates feedstock bargaining power among integrated refiners with captive hydrocracking trains. This technological transition tightens price discipline for independent blenders while rewarding archipelago-based producers with backward integration into lower-sulfur stocks.
Pricing Analysis
Distributor margins compress as mega-fleets negotiate direct technical service agreements with embedded fluid analysis programs. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels stratifies by drain interval performance guarantees and METI viscosity grade certification. Pricing pressure stems from consolidated procurement by refrigerated logistics operators demanding documented cargo liability coverage. Owner-operators in Kyushu agricultural cooperatives exhibit highest price sensitivity; municipal bus fleets in Tokyo show least.
Supply Chain Analysis
Specialized additive chemist availability tightens in Osaka-Nagoya industrial corridors where formulation expertise for heavy-duty diesel dispersant packages concentrates among retiring specialists at major blenders. Domestic supply rests on Japan's integrated refining complexes in Chiba, Kanagawa, and Aichi prefectures alongside South Korean Group III base oil imports. Hydrocracked feedstock, anti-wear additive packages, and ester-based synthetic chemistries constitute critical inputs. Single-source vulnerability runs through captive hydrocracking capacity concentration. Distribution runs through direct sales channels for mega-fleets and regional jobber networks for fragmented mid-sized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's commercial vehicles lubricants market offers geographic-arbitrage value through compliance cost differentials between domestic METI-mandated reformulation investments and lower regulatory burden in South Korean export-oriented base oil production.
For Market Incumbents: Extend synthetic formulation portfolios into SAE 10W-30 and lower viscosity grades mandated under METI's fuel economy roadmap. Secure additive chemist talent pipelines through technical apprenticeship programs addressing retiring specialist concentration. Defend against international major technical service embedding by consolidating direct fleet relationships around drain interval optimization programs with onboard oil condition sensor integration. For New Entrants and Emerging Players: Owner-operator segments in Hokkaido grain cooperatives and Kyushu citrus operations represent underserved buyer archetypes with unmet demand for economy mineral formulations with seasonal delivery flexibility. Municipal bus fleet decarbonization programs in secondary cities offer white-space entry through re-refined base oil certification. Construction equipment hydraulic fluid segments in Kansai infrastructure cycles provide premium positioning with less entrenched supplier relationships. Pursue technical partnership routes with regional distributors rather than direct mega-fleet competition. For Investors and Strategic Acquirers: Roll-up economics work for regional independent blenders with established distributor networks in Chubu and Tohoku because fragmented mid-sized fleet geography resists direct sales disintermediation. Long-term viability hinges on synthetic formulation capability acquisition and METI certification asset accumulation. Target acquisition profile centers on independents with JIS-approved viscosity grade portfolios and captive regional distributor relationships. Watch for inflection in municipal re-refined base oil procurement mandates as circular supply contract standardization signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Captive hydrocracked feedstock supply secures margin control against crude-linked price volatility for ENEOS and Idemitsu refining networks. |
| Synthetic Formulation Portfolio Expansion | SAE 10W-30 and lower viscosity grade development aligns with METI fuel economy mandates for Kanto corridor heavy-duty fleets. |
| Direct Fleet Technical Service Embedding | Onboard oil condition sensor programs with drain interval optimization consolidate supplier relationships with Nagoya refrigerated logistics operators. |
| Re-Refined Base Oil Certification Investment | Circular supply contract qualification opens municipal bus fleet procurement in Tokyo, Yokohama, and Nagoya decarbonization timelines. |
| Additive Chemist Talent Pipeline Development | Technical apprenticeship programs address formulation expertise scarcity for heavy-duty diesel dispersant packages at retiring specialist concentrations. |
Research Methodology
Multiple input streams — fleet operator procurement interviews, refinery production data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged lubricant blending plant managers, commercial fleet procurement directors, METI regulatory affairs specialists, construction equipment maintenance heads, and regional distributor network operators. Secondary validation drew from JIS standards documentation, METI fuel economy benchmark disclosures, base oil trade flow customs records, and petroleum refinery SEC filings.
Historical volume trajectories were cross-referenced against panel-derived elasticity assumptions across the projection horizon. Segmentation modeling spanned product type, end user archetype, distribution channel structure, and vehicle application duty cycle. CAGRs were derived from elasticity-adjusted demand curves and feedstock cost pass-through coefficients. Forecast inputs incorporated METI viscosity mandate implementation pacing and municipal carbon-neutral procurement pilot expansion rates.
Underlying measurement precision varies by segment; direct sales channel volume carries tighter precision than fragmented owner-operator retail estimates. Forecasts reflect assumptions around METI regulatory timeline adherence and synthetic formulation substitution elasticity. Material deviation in crude-linked base oil refining spreads or JIS certification timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Air Springs Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Timing Gear Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market