
 Heavy Duty Engines Market | 2026-2036
Heavy Duty Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Engines Market Analysis
Fleet operator consolidation around sustainability targets is repositioning procurement leverage toward buyers who mandate emission-compliant powertrains. Cummins Inc. leverages its vertical integration into fuel systems and aftertreatment to secure long-term supply agreements with consolidated buyers. Volvo Trucks Corporation anchors its position through R&D intensity in hybrid drivetrain architectures. Caterpillar Inc. dominates mining and construction applications where duty cycles demand thermal efficiency above absolute emission minimization.
Heavy duty engines are compression-ignition or spark-ignition power units exceeding 15 liters displacement, producing torque outputs above 2,500 Nm for sustained operation in commercial vehicles and off-highway equipment. Diesel configurations retain structural dominance across construction and mining applications where energy density and refueling infrastructure maturity outweigh first-cost premiums of alternatives. Turbocharged diesel technology leads unit volume while hybrid powertrains represent the fastest-expanding margin pool as fleet operators amortize fuel savings against higher acquisition costs. Natural gas engines occupy a transitional niche in urban transportation corridors with established liquefied or compressed gas infrastructure.
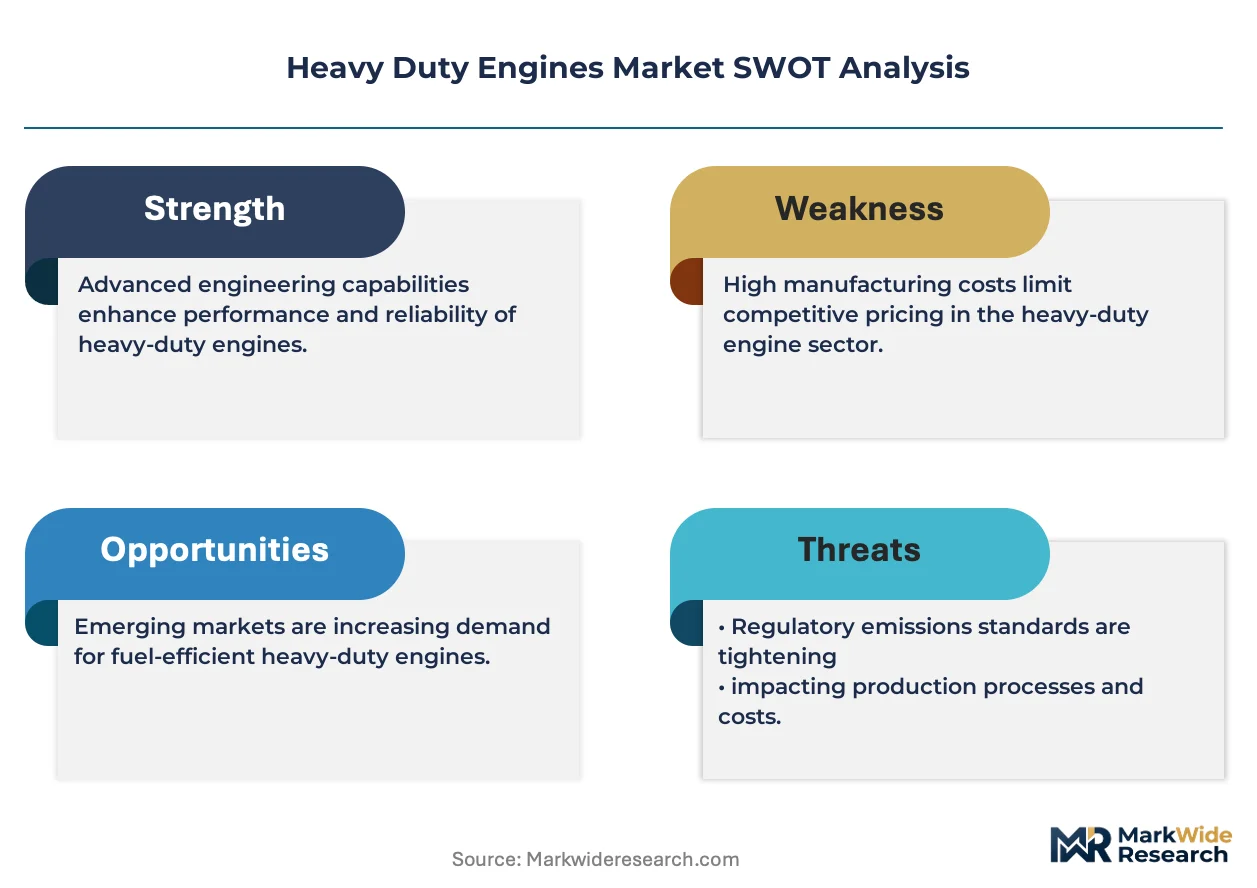
EPA Phase 3 standards, California CARB mandates, and Euro VII proposals from the European Commission are tightening allowable NOx and particulate thresholds, forcing redesign cycles toward integrated aftertreatment and onboard diagnostics. China's MIIT enforces domestic fuel consumption limits that diverge from Western test cycles, creating parallel certification requirements for multinational suppliers. Stakeholders must monitor regulatory divergence between emission jurisdictions to avoid stranded engineering investment in single-market compliance architectures.
Market Dynamics
Fleet procurement consolidation around EPA Phase 3 and CARB mandates is compressing supplier margins while accelerating powertrain redesign cycles toward integrated aftertreatment architectures. Engine manufacturers must absorb compliance costs or risk exclusion from consolidated buyer tenders.
Growth Catalysts
- EPA Phase 3 Standards:The regulation tightens greenhouse gas thresholds for model year 2027 trucks, forcing fleet-wide engine replacements and expanding addressable market for compliant powertrain suppliers.
- China MIIT Fuel Consumption Limits:Domestic certification requirements for heavy trucks create parallel demand for localized engine architectures with divergent test cycles from Western standards.
- Hybrid Drivetrain Maturation:Urban freight operators in German logistics corridors are amortizing acquisition premiums against fuel savings, validating total-cost-of-ownership models for electrified compression-ignition systems.
Market Restraints
- Platinum Group Metal Cost Volatility:Diesel oxidation catalysts and selective catalytic reduction systems depend on palladium and rhodium, exposing aftertreatment suppliers to commodity price swings.
- Refueling Infrastructure Gaps:Liquefied natural gas corridors remain concentrated in California and Sichuan Province, limiting addressable market for spark-ignition alternatives to diesel.
- Thermal Efficiency Trade-offs:Mining duty cycles in Australian iron ore operations prioritize brake-specific fuel consumption over absolute NOx minimization, constraining emission-reduction technology penetration.
Strategic Opportunities
- India BS-VI Transition:The country's leapfrogged emission standards create first-mover advantage for suppliers with proven aftertreatment integration from Euro VI and EPA Tier 4 architectures.
- Onboard Diagnostics Convergence:Euro VII proposals and EPA OBD-III requirements are converging on real-time emission monitoring, opening white space for sensor and telematics integration specialists.
- Remanufactured Powertrain Channels:Independent rebuilders in the US Midwest are capturing warranty-expired fleet demand, creating alternative distribution paths outside OEM captive networks.
Industry Challenges
- Aftertreatment Integration Complexity:Packaging diesel particulate filters, SCR, and oxidation catalysts within chassis envelope constraints demands thermal management expertise scarce in traditional mechanical engineering pools.
- Dual Certification Burden:Suppliers serving both US and Chinese markets must maintain parallel engineering teams for divergent test cycles, compressing R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Engines Market |
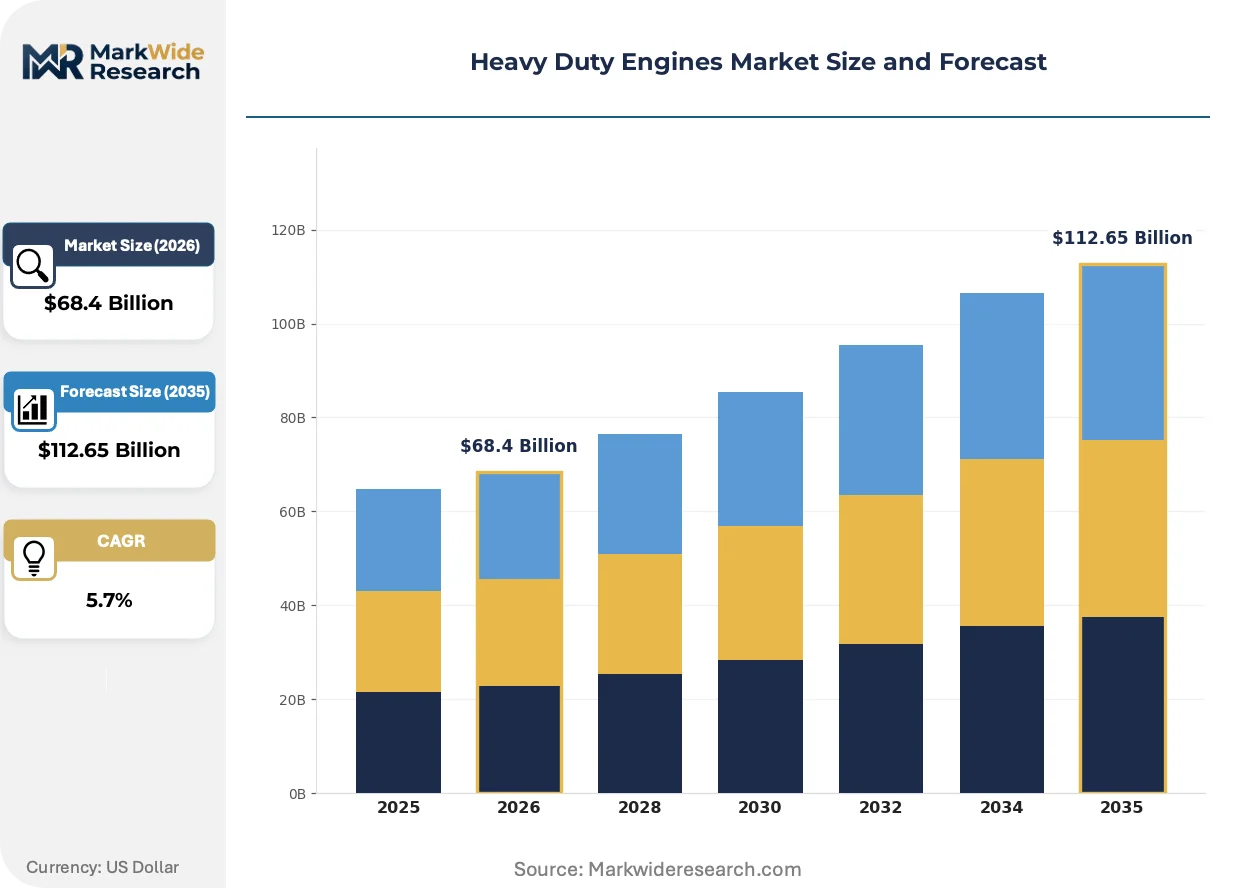
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel, Gasoline, Natural Gas, Biofuel Technology: Turbocharged, Supercharged, Direct Injection, Hybrid Application: Construction, Agriculture, Mining, Transportation End User: OEMs, Aftermarket Providers, Fleet Operators, Rental Services |
| Companies Covered | Volvo Trucks Corporation, PACCAR, Cummins Inc., MAN SE, Komatsu Ltd., Caterpillar Inc., Weichai Power Co. Ltd., Mercedes-Benz, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Engines Market Emerging Trajectories
Powertrain electrification is fragmenting along duty-cycle lines rather than converging on a single architecture, with technology choices diverging between long-haul, urban delivery, and off-highway applications. This specialization is reshaping supplier competitive boundaries.
Integrated turbo-compounding is consolidating thermal energy recovery into mainstream heavy-duty diesel architectures. Long-haul fleet operators in the US Interstate corridor are specifying these systems as standard equipment. The technology is consolidating supplier value capture into turbocharger and waste-heat recovery specialists with in-house casting and aerodynamics capabilities.
California CARB mandates for zero-emission vehicle sales quotas are compressing diesel engine production planning horizons. The regulation forces manufacturers to allocate engineering resources across combustion and battery-electric platforms simultaneously. Engine suppliers with modular architecture strategies are responding faster than those with dedicated legacy product lines.
Asset-light powertrain procurement is displacing traditional equipment financing in European logistics. Fleet operators in Germany and the Netherlands are subscribing to engine-hour contracts rather than purchasing engines outright. This shift concentrates in urban distribution verticals where utilization predictability supports service-based revenue models.
Heavy Duty Engines Market Segmentation
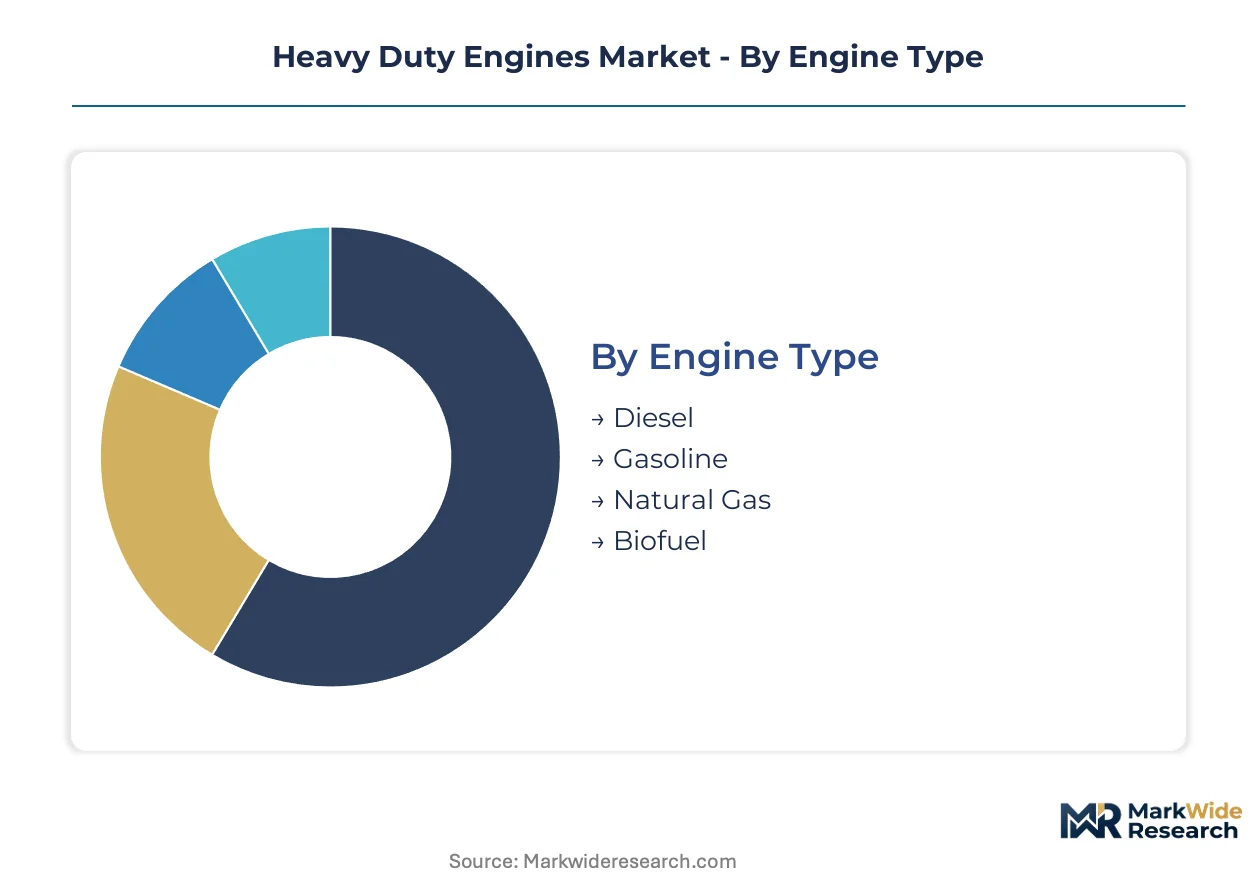
Heavy duty engine procurement decisions pivot on duty-cycle demands, regulatory compliance horizons, and total-cost-of-ownership calculations. Fleet operators and equipment buyers segment their requirements across fuel type, powertrain architecture, and application intensity to optimize asset utilization against emission mandates.
Engine Type:
Upgrade cycles in long-haul trucking and off-highway equipment are compressing around EPA Phase 3 and Euro VII compliance deadlines, forcing premature replacement of pre-certified powertrains.
- Diesel:Compression-ignition architectures exceeding 15 liters displacement dominate construction and mining applications where energy density and refueling infrastructure maturity outweigh first-cost premiums of alternatives. Australian iron ore operations and North American Class 8 trucking fleets specify these powertrains for thermal efficiency under sustained high-load duty cycles.
- Natural Gas:Spark-ignition engines operating on compressed or liquefied natural gas occupy a transitional niche in urban transportation corridors with established fueling infrastructure. California and Sichuan Province concentrate demand where CARB mandates and provincial air quality targets subsidize fleet conversion.
- Biofuel:Biodiesel and renewable diesel-compatible engines leverage existing aftertreatment architectures while meeting lower-carbon fuel mandates.
- Gasoline:Spark-ignition powertrains serve lighter heavy-duty applications where acquisition cost sensitivity outweighs fuel economy optimization.
Diesel sits at the top of the volume ranking, with natural gas climbing the fastest as fleet operators amortize infrastructure investments against carbon reduction targets.
Technology:
Powertrain engineering resources are fragmenting across combustion optimization, electrification, and thermal recovery as regulatory timelines diverge between jurisdictions.
- Turbocharged:Forced induction systems with variable geometry turbine vanes dominate current production volumes, delivering brake-specific fuel consumption improvements required for EPA Phase 3 and China MIIT certification. Long-haul fleet operators in the US Interstate corridor specify these as standard equipment.
- Hybrid:Parallel and series-hybrid architectures combining compression-ignition engines with electric traction motors are expanding most quickly in urban freight applications. German logistics operators in the Rhine-Ruhr corridor validate total-cost-of-ownership models through engine-hour subscription contracts.
- Direct Injection:High-pressure common-rail fuel systems enable precise combustion control for NOx and particulate reduction.
- Supercharged:Mechanically driven forced induction serves niche applications requiring immediate torque response without turbo lag.
Turbocharged technology commands the largest installed base, while hybrid systems are gaining share fastest through fleet electrification mandates.
Application:
Duty-cycle specialization is fragmenting supplier competitive boundaries as thermal efficiency requirements diverge between transient and sustained load profiles.
- Transportation:Long-haul trucking and urban freight applications drive the largest addressable volume, with EPA Phase 3 and CARB zero-emission vehicle quotas compressing diesel engine planning horizons. Fleet procurement consolidation around sustainability targets is repositioning buyer leverage toward emission-compliant powertrain mandates.
- Mining:Australian iron ore and Chilean copper operations prioritize brake-specific fuel consumption over absolute NOx minimization, constraining aftertreatment technology penetration where thermal efficiency determines operating economics.
- Construction:Earthmoving and material handling equipment demand torque density for intermittent high-load cycles.
- Agriculture:Seasonal utilization patterns and rural refueling infrastructure shape powertrain selection for combine harvesters and tractor platforms.
Transportation leads by unit volume, with mining applications showing the steepest margin compression from commodity price volatility in platinum group metals.
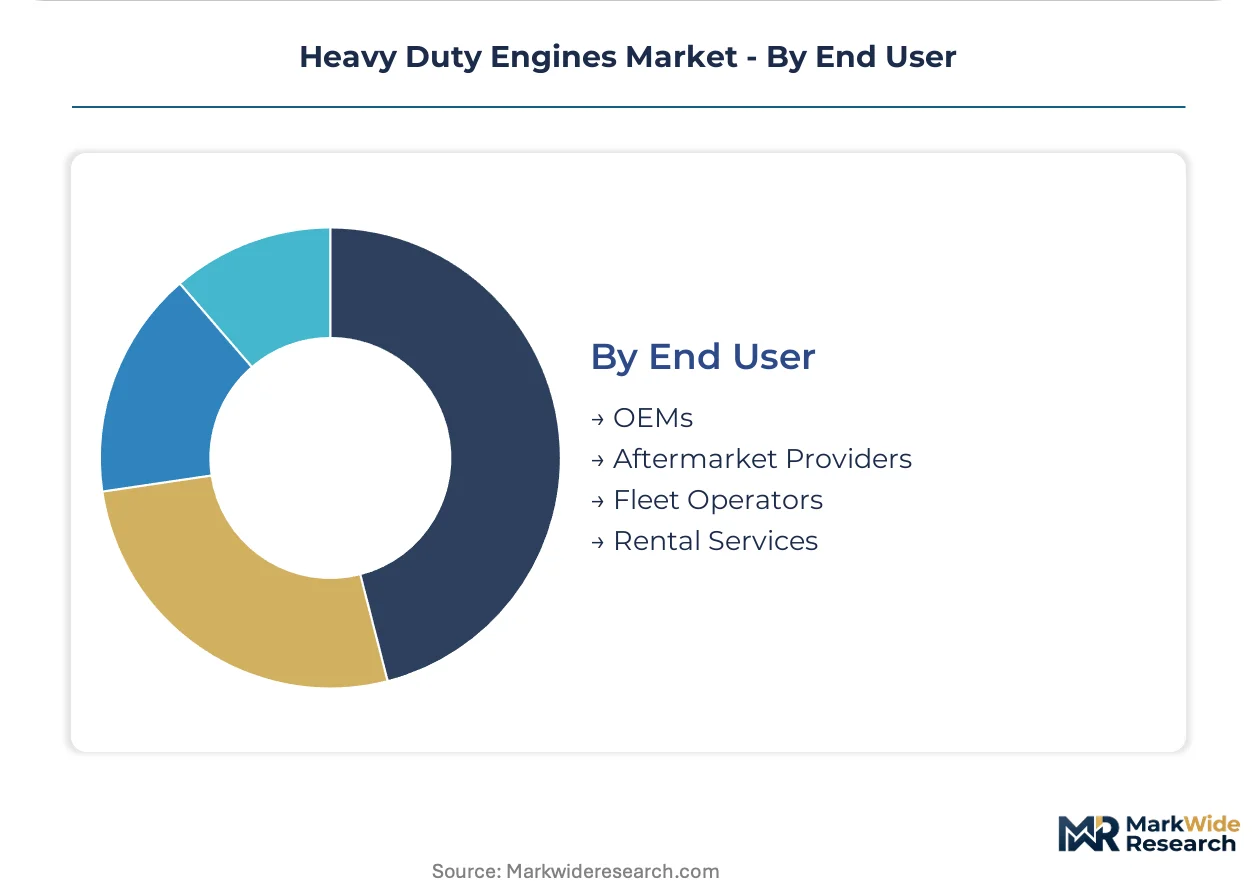
End User:
Procurement channel structure is shifting from equipment financing toward asset-light powertrain access models in European logistics corridors.
- Fleet Operators:Consolidated buyers in long-haul trucking are mandating emission-compliant powertrains through multi-year supply agreements, leveraging sustainability targets to compress supplier margins. These stakeholders amortize acquisition premiums against fuel savings in German and Dutch urban distribution networks.
- OEMs:Original equipment manufacturers integrate engines into complete vehicle platforms, capturing value through vertical control over fuel systems and aftertreatment packaging within chassis envelope constraints.
- Aftermarket Providers:Independent rebuilders in the US Midwest capture warranty-expired demand through remanufactured powertrain channels.
- Rental Services:Equipment leasing companies prioritize utilization predictability and maintenance cost containment in powertrain selection.
Fleet operators dominate procurement volume, with aftermarket providers expanding most quickly through extended asset lifecycles in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification requirements diverge sharply from EPA test cycles, forcing suppliers to maintain parallel engineering teams. Germany's logistics corridors validate hybrid powertrain economics through subscription-based procurement models.
United States
Long-haul fleet operators in the Interstate corridor specify turbo-compounding systems as standard equipment. EPA Phase 3 greenhouse gas standards tighten thresholds for model year 2027 trucks, forcing premature replacement cycles. The Midwest industrial belt hosts independent rebuilders capturing warranty-expired demand through remanufactured powertrain channels.
China
Domestic heavy truck demand concentrates around Sichuan Province's liquefied natural gas corridors and Yangtze River Delta logistics hubs. MIIT enforces fuel consumption limits with test cycles diverging from Western standards, creating parallel certification requirements. Weichai Power anchors localized engine architecture production serving both domestic and export markets.
Germany
Rhine-Ruhr corridor logistics operators amortize hybrid acquisition premiums through engine-hour subscription contracts. Euro VII proposals from the European Commission tighten NOx thresholds, forcing integrated aftertreatment redesigns. MAN SE and Daimler AG anchor R&D intensity in modular drivetrain architectures spanning combustion and electrified platforms.
Australia
Iron ore mining operations in Western Australia prioritize brake-specific fuel consumption over absolute emission minimization. Thermal efficiency under sustained high-load duty cycles constrains aftertreatment technology penetration. Komatsu Ltd. and Caterpillar Inc. dominate equipment procurement where duty cycle economics outweigh compliance premiums.
India
BS-VI emission standards create first-mover advantage for suppliers with proven aftertreatment integration from Euro VI architectures. Fleet operators in Maharashtra and Gujarat consolidate procurement around cleaner-burning powertrains. The leapfrogged regulatory timeline compresses supplier qualification windows for multinational engine manufacturers.
Heavy Duty Engines Market Vendor Landscape
North American producers anchor one tier; European specialists hold differentiated positions in integrated aftertreatment architectures. The supplier base concentrates around vertically integrated engine manufacturers with captive fuel system and turbocharger capabilities. Two strategic archetypes dominate: modular platform strategists responding to regulatory divergence, and duty-cycle specialists optimizing thermal efficiency for mining and construction applications. Competitive moves center on backward integration into aftertreatment components and geographic expansion through localized certification partnerships.
Within the integrated powertrain tier, Cummins Inc. exemplifies the vertically integrated archetype with in-house production of fuel systems and emission control components. Volvo Trucks Corporation occupies a position in hybrid drivetrain development, reflecting European logistics corridor demand patterns. Caterpillar Inc. anchors the heavy-duty application specialist segment where mining duty cycles prioritize thermal efficiency metrics.
| Leading Market Players |
|---|
| Volvo Trucks Corporation |
| PACCAR |
| Cummins Inc. |
| MAN SE |
| Komatsu Ltd. |
| Caterpillar Inc. |
| Weichai Power Co. Ltd. |
| Mercedes-Benz |
| Daimler AG |
| Others |
Supply Flow & Price Mechanics
Backward integration into aftertreatment components anchors supplier pricing power while compressing margins for non-integrated competitors serving EPA Phase 3 and Euro VII compliance markets. Fleet procurement consolidation around emission mandates shifts leverage toward buyers who specify integrated powertrain architectures from vertically integrated manufacturers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for turbocharger and fuel system components. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified engines with full aftertreatment integration from baseline diesel configurations and remanufactured alternatives. Pricing pressure stems from platinum group metal volatility in catalytic converter substrates, squeezing margins on SCR-equipped powertrains. Mining operators in Western Australia exhibit lowest price sensitivity, prioritizing thermal efficiency metrics over acquisition cost.
Supply Chain Analysis
Palladium and rhodium supply rests on South African mining operations and Russian metallurgical exports, creating concentrated dependency for diesel oxidation catalyst producers. Rare earth elements for turbocharger permanent magnets draw from Chinese processing facilities, while precision casting capacity clusters in Germany and Japan. Single-source vulnerability in platinum group metal refining exposes aftertreatment suppliers to supply disruption. Distribution runs through OEM captive networks and independent rebuilders in the US Midwest serving warranty-expired fleet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA Phase 3 and China MIIT certification creates geographic-arbitrage opportunities for suppliers with parallel engineering capabilities, as compliance cost differentials exceed fifteen percent across Atlantic and Pacific markets.
For Market Incumbents: To counter margin compression from fleet procurement consolidation, Cummins-style backward integration into fuel systems and aftertreatment secures long-term supply agreements with consolidated buyers. MAN SE and Daimler AG demonstrate that modular drivetrain architectures spanning combustion and electrified platforms accelerate response to CARB zero-emission vehicle quotas. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian BS-VI transition markets creates entry opportunity for suppliers with proven Euro VI aftertreatment integration. Urban freight electrification in German logistics corridors represents the most penetrable white space, with engine-hour subscription contracts offering recurring revenue models outside traditional equipment financing. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification burdens compress R&D efficiency for mid-tier suppliers serving both US and Chinese markets. Long-term viability favors vertically integrated engine manufacturers with captive turbocharger and emission control capabilities. Watch for EPA OBD-III and Euro VII convergence on real-time emission monitoring as inflection indicator for sensor and telematics integration specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aftertreatment | Cummins and Volvo Trucks secure margin control over SCR and oxidation catalyst supply chains. |
| Modular Platform Standardization | MAN SE and Daimler AG accelerate powertrain redesign cycles across combustion and battery-electric architectures. |
| Localized Certification Partnerships | Weichai Power anchors domestic production serving MIIT fuel consumption limits with divergent test cycles. |
| Remanufactured Powertrain Channel Development | Independent rebuilders in the US Midwest capture warranty-expired fleet demand outside OEM networks. |
| Hybrid Drivetrain R&D Intensity | Volvo Trucks validates total-cost-of-ownership models through German logistics corridor deployment. |
Methodological Framework
Direct dialogue with fleet procurement directors, OEM platform engineers, aftermarket service heads, and regulatory affairs specialists combined with secondary validation from EPA certification databases, MIIT fuel consumption filings, SEC 10-K disclosures, and EU type-approval records. Bottom-up unit volume estimates triangulate against top-down market value assessments across the analysis window.
Bottom-up modeling segments the market by fuel type, powertrain architecture, application intensity, and regional regulatory cluster, with value outputs reflecting installed base turnover rates and compliance-driven replacement cycles. CAGRs derive from segment-specific growth trajectories weighted by EPA Phase 3, CARB mandates, and China MIIT enforcement timelines. Forecast inputs include fleet operator consolidation patterns and platinum group metal price elasticity effects on aftertreatment adoption.
Caveats apply where regulatory delay or acceleration in Euro VII finalization could materially shift the outlook for integrated aftertreatment investment cycles. Forecasts reflect assumptions around platinum group metal supply stability and fleet operator willingness to absorb hybrid acquisition premiums. A small set of named triggers—EPA OBD-III implementation timing, China MIIT test cycle harmonization proposals, and CARB zero-emission vehicle quota stringency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Global Automotive Hydraulic Brake Market