
 UK Automotive Parts Zinc Die Casting Market | 2026-2036
UK Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Parts Zinc Die Casting Market Analytics
Buyer concentration among UK vehicle assemblers and Tier 1 Suppliers is hardening as OEMs reduce supplier bases to secure volume commitments and quality consistency. Dynacast leverages its multi-site European footprint to anchor just-in-time delivery contracts with Midlands-based vehicle manufacturers. Kemlows Diecasting Products Ltd specializes in precision brake and chassis castings, competing on geometric tolerances that meet VCA type-approval requirements.
UK Automotive Parts Zinc Die Casting involves injecting zinc alloys with aluminum, copper, and magnesium additions into steel molds at pressures exceeding 1,000 bar to produce net-shape automotive components with wall thicknesses below one millimeter. The process delivers corrosion-resistant, high-ductility parts for underhood and structural applications where dimensional stability matters. Engine Block and Transmission Housing categories still occupy the largest volume share, though Brake Components and Chassis Parts are gaining share as electric vehicle architectures redistribute weight and thermal loads. High-Pressure Die Casting dominates current output, yet Semi-Solid Die Casting is expanding fastest among EV-focused Tier 1 Suppliers seeking porosity reduction and thinner-wall capability.
The Vehicle Certification Agency enforces type-approval standards that dictate fatigue strength and dimensional precision for safety-critical castings, while HSE regulations govern molten metal handling and fume exposure across foundry floors. The UK's Net Zero Strategy and evolving carbon-border considerations are forcing zinc die casters to document embodied emissions and energy intensity per component. Stakeholders must monitor how BSI standards for recycled content evolve and whether OEMs will mandate secondary zinc minimums in procurement specifications.
Market Dynamics
The UK's Net Zero Strategy and Vehicle Certification Agency emissions standards are compressing foundry energy profiles while Tier 1 Suppliers consolidate procurement around Midlands-based zinc die casters capable of just-in-time brake and chassis component delivery.
Growth Catalysts
- Semi-Solid Die Casting:EV-focused Tier 1 Suppliers are adopting this method to achieve porosity reduction and sub-millimeter wall thickness in chassis components.
- West Midlands Cluster:Concentrated vehicle assembly and foundry infrastructure around Birmingham and Coventry anchors supplier-proximity advantages for brake system manufacturers.
- Net Zero Strategy:The UK's carbon-border documentation requirements are accelerating foundry investment in lower-energy high-pressure die casting equipment.
Market Restraints
- Zinc Alloy Input Volatility:London Metal Exchange pricing fluctuations for zinc-aluminum-copper alloys compress margin predictability for small-batch chassis specialists.
- Single-Region Supply Concentration:Dependence on West Midlands production infrastructure creates geographic vulnerability to localized energy disruptions or logistics constraints.
- Dimensional Precision Limits:Conventional high-pressure die casting struggles to consistently meet VCA type-approval fatigue strength tolerances for safety-critical transmission housings.
Strategic Opportunities
- Secondary Zinc Mandates:Evolving BSI standards for recycled content create procurement specification openings for foundries with documented circular material flows.
- EV Thermal Management:Electric vehicle battery tray and inverter housing applications represent underpenetrated demand for corrosion-resistant zinc die castings.
- Just-in-Time Contracts:OEM supplier-base reduction strategies favor Midlands-based casters capable of same-day brake component delivery to Coventry assembly plants.
Industry Challenges
- Semi-Solid Process Engineering Talent:Foundries face scarcity of technicians trained in thixotropic alloy preparation and controlled-solidification parameter management.
- VCA Certification Timelines:Extended type-approval cycles for novel brake component geometries delay revenue recognition on EV platform contracts.
- Legacy Equipment Retrofit Costs:Converting high-pressure die casting lines for lower-energy operation demands capital deployment that mid-cap foundries struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Parts Zinc Die Casting Market |
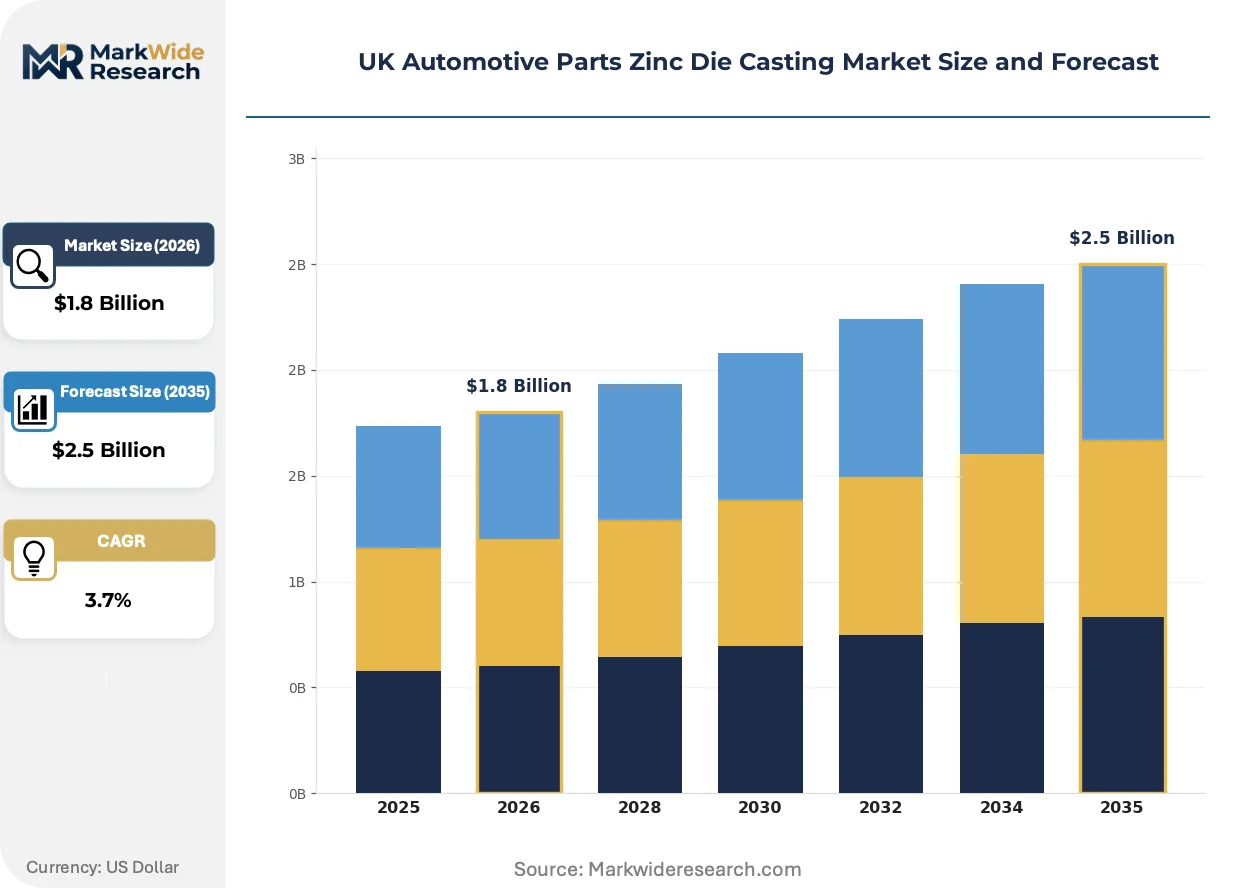
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Block, Transmission Housing, Brake Components, Chassis Parts Application: Passenger Vehicles, Heavy-Duty Trucks, Electric Vehicles, Commercial Vehicles Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Semi-Solid Die Casting End User: OEMs, Tier 1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Brillcast Manufacturing LLC, Empire Casting Co, Sandhar Technologies Ltd, Ashok Minda Group, Cascade Die Casting Group Inc, Dynacast, Kemlows Diecasting Products Ltd, Ningbo Die Casting Company, Pace Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Parts Zinc Die Casting Market Evolving Landscape
Zinc die casting process evolution is fragmenting along thermal management requirements as electric vehicle architectures redistribute component loads and dimensional specifications across UK supply chains.
Semi-solid rheocasting is unifying porosity control and thin-wall capability in a single process platform. Tier 1 brake system manufacturers are adopting this technology at pilot scale for next-generation chassis brackets. The method is unifying previously separate machining and finishing steps into net-shape delivery, compressing supplier tier complexity for West Midlands OEM programs.
The UK's Net Zero Strategy and evolving carbon-border adjustment mechanisms are forcing foundries to document embodied emissions per component. This regulatory pressure is accelerating investment in energy monitoring systems and secondary zinc traceability infrastructure. High-volume engine block casters face the steepest compliance cost escalation as they retrofit legacy high-pressure lines.
Buyer concentration among vehicle assemblers is compressing supplier negotiation leverage and extending payment terms. Tier 1 brake and chassis procurement teams are consolidating award volumes among foundries with proven VCA type-approval track records. This pattern concentrates most acutely around Coventry and Birmingham production hubs where logistics proximity outweighs marginal price differentiation.
UK Automotive Parts Zinc Die Casting Market Segmentation
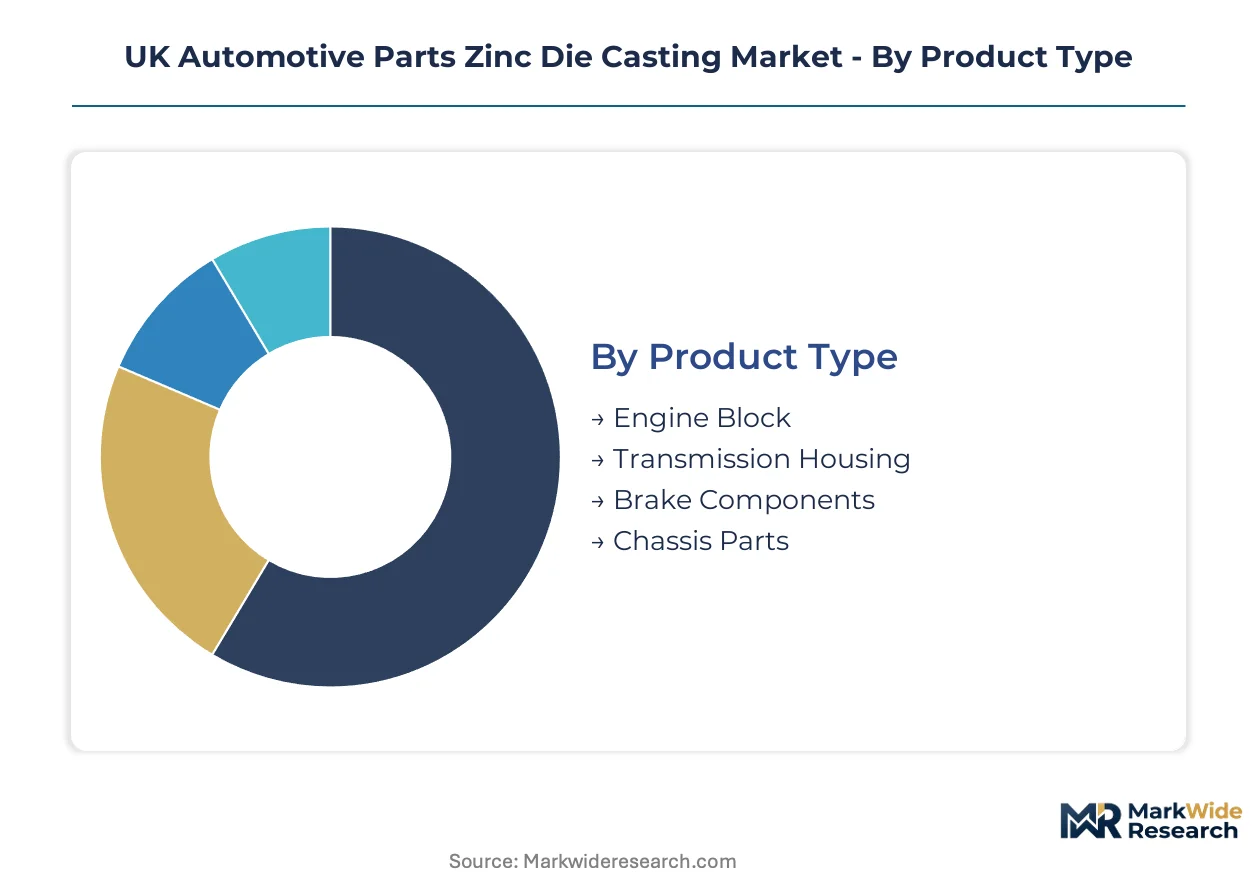
Segmentation in UK automotive zinc die casting reveals how component specifications, thermal requirements, and procurement hierarchies fragment production capabilities across Midlands foundries. Each dimension exposes distinct margin structures and certification burdens that shape supplier positioning.
Product Type:
Standardization dominates high-volume engine categories while brake and chassis components demand geometric customization to meet VCA fatigue tolerances.
- Engine Block:These castings absorb the highest zinc alloy tonnage across UK foundries. Demand concentrates at legacy internal combustion platforms around Birmingham where established high-pressure lines amortize tooling costs across multi-year vehicle programs.
- Transmission Housing:Complex internal geometries and seal-surface precision requirements favor suppliers with CNC finishing integration. West Midlands OEMs source these through Tier 1 transmission specialists who bundle housing supply with gearset procurement.
- Brake Components:Caliper brackets and master cylinder housings require sub-millimeter tolerances for hydraulic sealing.
- Chassis Parts:Suspension brackets and subframe nodes prioritize ductility over hardness for crash energy absorption.
Most installed capacity flows through Engine Block. Expansion is steepest in Brake Components.
Application:
Volume scale separates passenger vehicle programs from commercial duty cycles, while electric vehicle architectures are redistributing thermal load specifications across component categories.
- Passenger Vehicles:High-volume hatchback and sedan programs sustain foundry utilization rates above 80 percent. Coventry-based assemblers specify zinc-aluminum alloys with copper additions for underhood corrosion resistance.
- Electric Vehicles:Battery tray brackets and inverter housings demand thinner walls and superior thermal conductivity than legacy architectures. Tier 1 Suppliers are qualifying semi-solid casters for these programs ahead of volume ramp.
- Heavy-Duty Trucks:Extended service intervals and payload stress prioritize fatigue strength over weight reduction.
- Commercial Vehicles:Delivery van and bus programs favor standardized component families across multiple wheelbase configurations.
Passenger Vehicles anchor current throughput. Electric Vehicles are climbing the fastest as OEMs retool Midlands assembly lines.
Technology:
Energy intensity and capital requirements stratify foundries between legacy high-pressure operators and emerging semi-solid specialists.
- High-Pressure Die Casting:Dominant method for engine and transmission castings with cycle times below 30 seconds. West Midlands infrastructure concentrates here, though Net Zero Strategy pressures are accelerating equipment retrofit costs.
- Semi-Solid Die Casting:Thixotropic processing eliminates porosity for safety-critical brake components. EV-focused Tier 1 Suppliers are piloting this technology for chassis brackets requiring T6 heat treatment compatibility.
- Low-Pressure Die Casting:Slower fill rates suit thicker-walled structural nodes where internal integrity outweighs surface finish.
- Gravity Die Casting:Manual pouring persists for aftermarket batches and heritage vehicle reproduction where tooling amortization is impractical.
High-Pressure Die Casting commands the largest installed base. Semi-Solid Die Casting is gaining share fastest among EV-qualified suppliers.
End User:
Procurement consolidation among vehicle assemblers is compressing negotiation leverage for independent foundries while expanding captive supply roles for Tier 1 integrators.
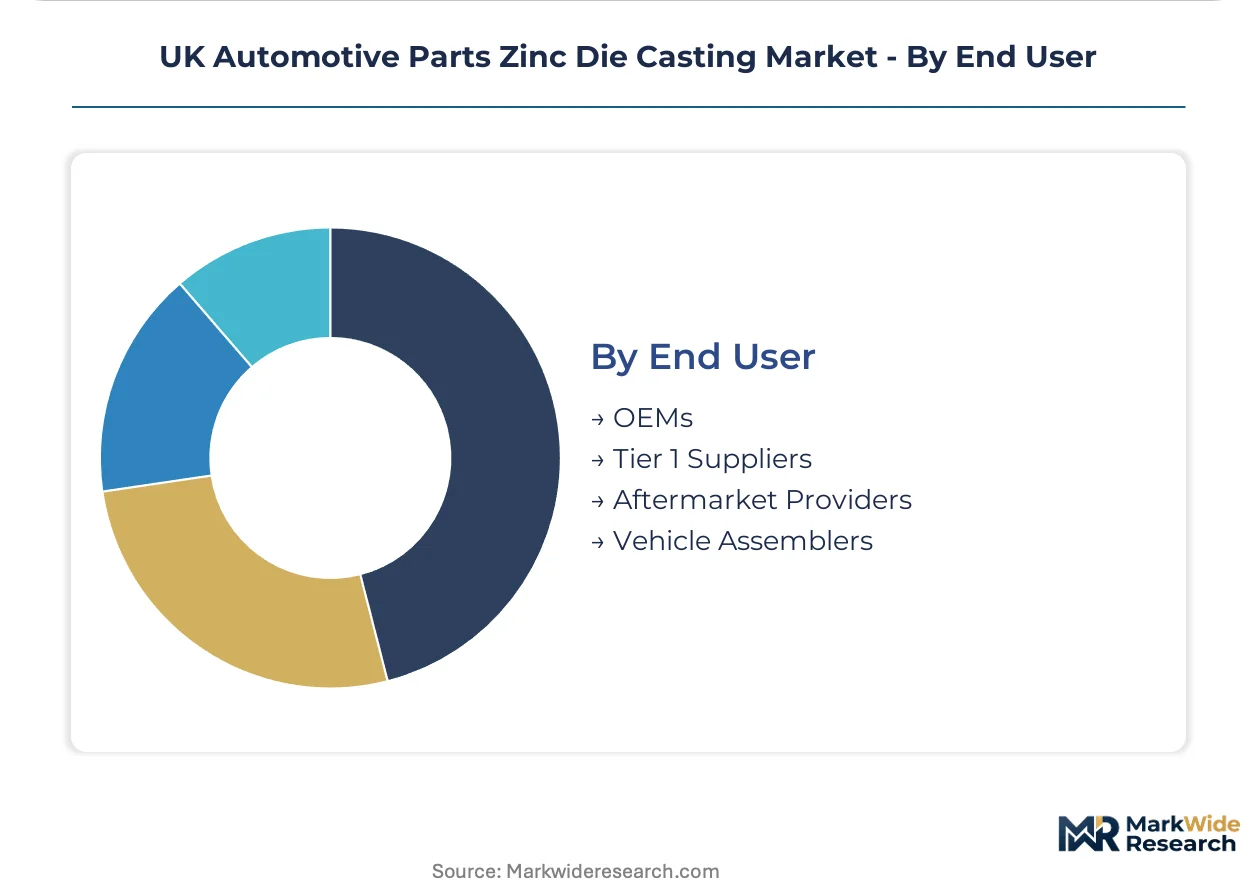
- Tier 1 Suppliers:Brake system and chassis module manufacturers bundle zinc castings with assembly and testing. These stakeholders are consolidating award volumes among foundries with proven VCA type-approval track records.
- OEMs:Direct procurement concentrates at high-volume engine block programs where foundries qualify as single-source suppliers for entire vehicle platforms.
- Vehicle Assemblers:Final assembly plants in Coventry and Birmingham prioritize logistics proximity over marginal price differentiation for just-in-time brake component delivery.
- Aftermarket Providers:Fragmented demand for replacement calipers and transmission cases favors smaller batch gravity casting operations.
Tier 1 Suppliers channel the majority of contract value. Vehicle Assemblers are expanding fastest as OEMs insource chassis procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive die casting sector operates at roughly triple the UK output scale, yet both markets face identical Net Zero Strategy compliance timelines that compress foundry energy profiles before 2035.
West Midlands
Birmingham and Coventry anchor the UK's densest automotive production corridor, with Tier 1 brake system manufacturers clustering within 50 kilometers of final assembly plants. The Vehicle Certification Agency enforces type-approval fatigue standards that disqualify distant suppliers on logistics risk. Foundries here amortize tooling across multi-year OEM platform contracts.
East Midlands
Leicester and Derby host precision casting operations serving transmission housing demand from nearby powertrain specialists. HSE molten metal handling regulations govern fume exposure limits across these older industrial zones. Semi-solid die casting pilot lines are emerging here as EV thermal management requirements displace legacy engine block volumes.
South East England
London periphery operations concentrate on aftermarket brake component distribution rather than OEM supply. The region's elevated energy costs push zinc alloy processing toward smaller batch gravity casting for heritage vehicle reproduction. BSI recycled content documentation requirements are forcing secondary zinc traceability investments here ahead of Midlands adoption.
Northern England
Manchester and Sheffield retain historical foundry infrastructure now repurposed for commercial vehicle chassis brackets. Extended OEM payment terms from Midlands-based assemblers strain working capital at these peripheral suppliers. Net Zero Strategy carbon-border preparation is accelerating slower here due to limited EV platform qualification.
UK Automotive Parts Zinc Die Casting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Large multi-site operators leverage European footprint breadth to anchor just-in-time contracts, while mid-cap Midlands foundries defend position through VCA type-approval track records. Consolidation pressure is intensifying as OEM supplier-base reduction strategies compress viable contract volumes toward fewer award recipients. Strategic moves cluster around semi-solid process licensing partnerships and secondary zinc supply chain integration.
Within the multi-site European operator tier, Dynacast represents scale-driven just-in-time capability across Midlands vehicle programs. Kemlows Diecasting Products Ltd exemplifies the precision-focused specialist archetype, occupying a position defined by geometric tolerance achievement for safety-critical brake applications. Sandhar Technologies Ltd anchors the India-UK cross-border supply vector, sitting within a broader tier of international fabricators qualifying for chassis component procurement.
| Leading Market Players |
|---|
| Brillcast Manufacturing LLC |
| Empire Casting Co |
| Sandhar Technologies Ltd |
| Ashok Minda Group |
| Cascade Die Casting Group Inc |
| Dynacast |
| Kemlows Diecasting Products Ltd |
| Ningbo Die Casting Company |
| Pace Industries |
| Others |
Value Network & Pricing Analysis
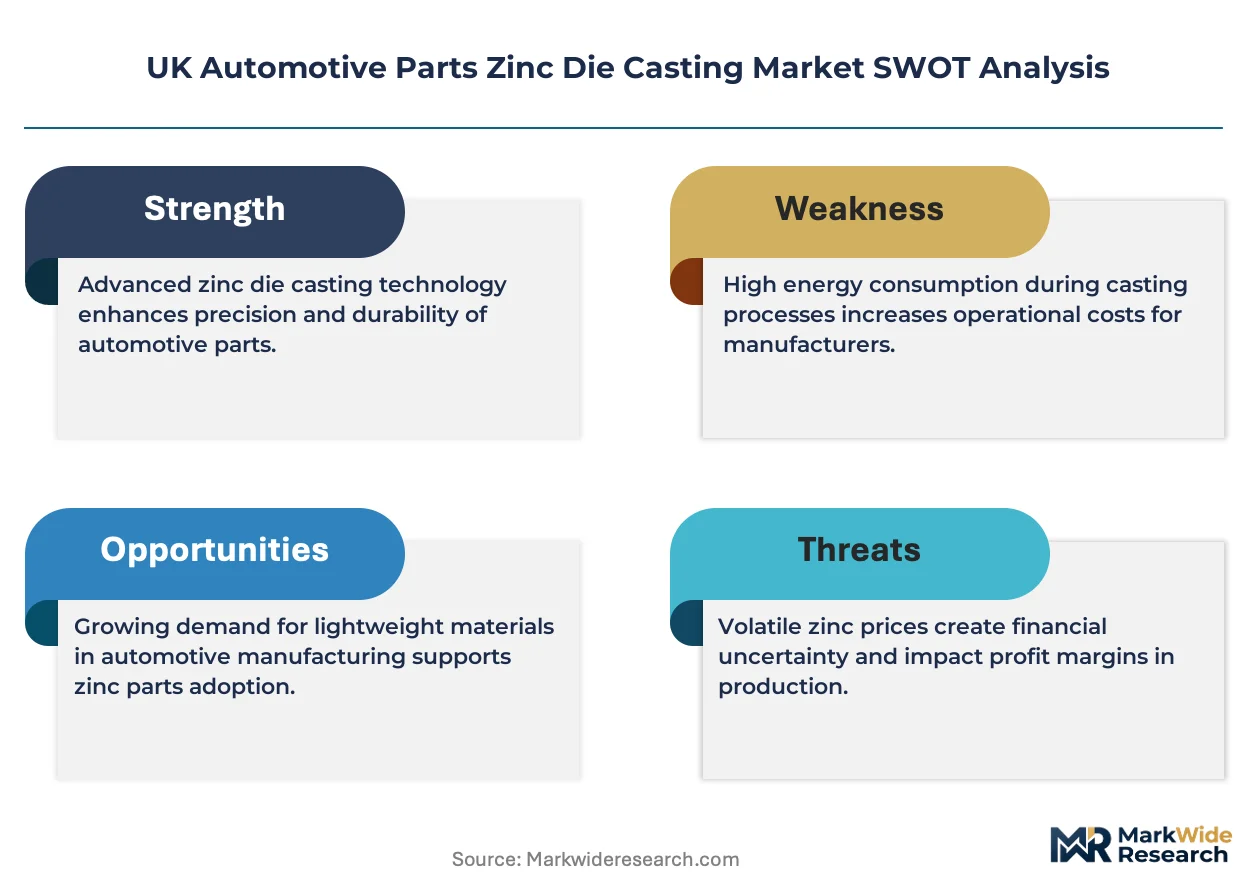
Tier 1 brake system manufacturers concentrate procurement among West Midlands foundries with Vehicle Certification Agency type-approval track records, compressing supplier negotiation leverage and anchoring contract-based long-term offtake pricing with volume-scale discounts.
Pricing Analysis
Capacity additions in semi-solid die casting across the East Midlands are reshaping price floors for safety-critical chassis components. Pricing stratifies across premium, standard, and economy tiers based on VCA certification grade and geometric tolerance achievement. Cost compression in legacy high-pressure engine block casting is intensifying because Net Zero Strategy retrofit requirements escalate energy monitoring investments. Aftermarket distributors exhibit highest price sensitivity, while OEM direct procurement teams prioritize logistics proximity over marginal unit cost.
Supply Chain Analysis
Workforce scarcity for thixotropic alloy technicians across Birmingham and Coventry constrains semi-solid capacity expansion. Raw material flows draw from Belgian zinc smelters, German aluminum suppliers, and domestic copper processors. Single-source vulnerability concentrates at the West Midlands cluster where localized energy disruptions would cascade through just-in-time brake component delivery. Distribution runs through Tier 1 integrators who bundle casting supply with assembly and testing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Automotive Parts Zinc Die Casting Market functions as a geographic-arbitrage play where East Midlands semi-solid pilot lines capture cost advantages against West Midlands legacy infrastructure burdened by steeper Net Zero Strategy compliance timelines.
For Market Incumbents: Hedge against semi-solid process displacement by licensing rheocasting technology from European equipment specialists before VCA certification timelines harden competitive barriers. Secure secondary zinc supply agreements with documented circular material flows ahead of evolving BSI recycled content mandates. Vertically integrate into CNC finishing capabilities to defend margin position as Tier 1 Suppliers consolidate award volumes. For New Entrants and Emerging Players: Begin with EV thermal management applications—battery tray brackets and inverter housings—where qualification pathways remain open and incumbent VCA track records carry less weight. Target Northern England commercial vehicle chassis programs where extended OEM payment terms have strained incumbent working capital. Pursue qualification partnerships with India-UK cross-border fabricators to anchor initial volume commitments. For Investors and Strategic Acquirers: Tier 1 brake system manufacturers are the most active acquirer in this space, seeking captive zinc casting supply to secure just-in-time delivery contracts. The five-to-ten year viability window favors mid-cap foundries with semi-solid process licenses and existing VCA type-approval portfolios over pure-play high-pressure operators facing steep retrofit costs. Monitor BSI secondary zinc minimum specifications as the inflection signal that would accelerate consolidation toward circular-material-capable targets.| Strategic Initiative | Industry Significance |
|---|---|
| Semi-Solid Process Licensing | Tier 1 Suppliers pilot rheocasting technology with East Midlands foundries to achieve sub-millimeter wall thickness for EV chassis brackets. |
| Secondary Zinc Supply Integration | Foundries with documented circular material flows capture procurement specification openings as BSI recycled content standards evolve. |
| VCA Type-Approval Fast-Track | Mid-cap specialists accelerate certification cycles for novel brake geometries to secure revenue recognition ahead of EV platform ramp. |
| Just-in-Time Logistics Proximity | Coventry and Birmingham casters defend contract renewals through same-day brake component delivery that distant competitors cannot match. |
| Legacy Equipment Energy Retrofit | High-volume engine block operators deploy capital to lower-energy high-pressure lines under Net Zero Strategy carbon-border preparation pressure. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, Vehicle Certification Agency type-approval specialists, and aftermarket distribution heads combined with secondary validation from IHS Markit vehicle production databases, UK trade association foundry output records, and HSE regulatory filings. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map zinc alloy consumption to component categories across vehicle propulsion architectures and regional production clusters. Segmentation dimensions span product type, application, technology, and end-user procurement tier. CAGRs derive from production volume trajectories, content-per-vehicle shifts, and pricing dynamics throughout the forecast period. Forecast inputs incorporate EV platform retooling schedules and semi-solid adoption curves among brake system manufacturers.
Several conditions sit outside the modeled scope, including potential Vehicle Certification Agency regulatory acceleration, London Metal Exchange zinc price volatility spikes, and unanticipated OEM insourcing of chassis casting operations. Forecasts reflect assumptions about Net Zero Strategy implementation pacing and Tier 1 supplier consolidation trajectories. Material deviation in BSI secondary zinc mandates or West Midlands energy infrastructure reliability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Automotive Speedometer Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Small Engine Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Valve Stem Seal Market