
 Argentina Automotive Lubricants Market | 2026-2036
Argentina Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Lubricants Market Outlook
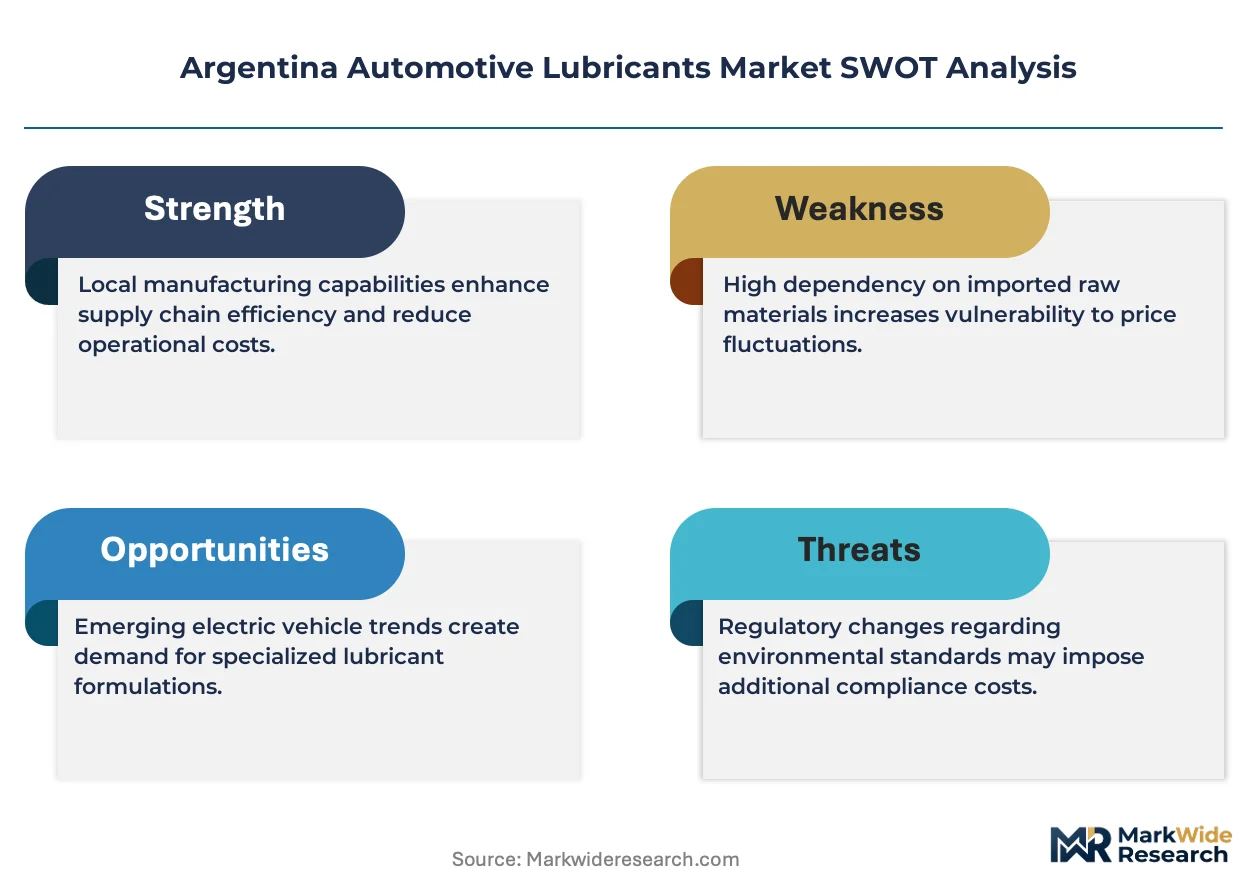
Asset-light leasing models for lubricant blending and packaging capacity are reconfiguring competitive entry barriers across Argentina. YPF leverages its captive crude supply and domestic refinery network to sustain cost advantages in base oil procurement. Shell competes through its controlled retail and service station footprint, while BP (Castrol) differentiates via specialized formulations targeting high-performance passenger vehicle segments.
Automotive lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain and driveline components, with viscosity grades typically ranging from 0W-16 to 20W-50 depending on operating temperature and engine architecture. Engine oil dominates volume consumption given mandatory drain intervals and expanding vehicle parc, while transmission fluid captures expanding margin pools as automatic and dual-clutch penetration deepens in passenger vehicles. Service stations anchor the distribution channel structure for fleet and commercial accounts, though retail outlets lead in passenger vehicle aftermarket sales.
Argentina's Secretariat of Energy and the country's national environmental regulator shape lubricant specifications through fuel economy mandates and waste oil disposal protocols that dictate reformulation cycles and recycling infrastructure investment. The national standards body certifies product compliance, creating non-tariff barriers for imported formulations lacking local homologation. Stakeholders must monitor how evolving emissions alignment with Mercosur trade bloc standards will redefine additive package requirements and sourcing economics.
Market Dynamics
Fleet operators in Argentina's commercial trucking sector are extending vehicle replacement cycles beyond traditional thresholds, forcing lubricant formulators to engineer higher-performance products that withstand elevated thermal loads and extended drain intervals under Mercosur emissions alignment pressures.
Growth Catalysts
- Emissions alignment with Mercosur standards:Argentina's national environmental framework mandates lower-viscosity, fuel-efficient oil formulations, compelling blenders to reformulate additive packages and capture regulatory-compliant market share.
- Greater Buenos Aires corridor concentration:Vehicle density and established service infrastructure in this industrial cluster generate concentrated volume pull for premium lubricant distribution networks.
- Dual-clutch transmission penetration:Passenger vehicle manufacturers are specifying specialized transmission fluids, expanding margin pools beyond conventional engine oil categories.
Market Restraints
- Base oil supply concentration:Domestic refinery capacity constraints and import dependency create input cost volatility for independent blenders lacking captive crude access.
- Homologation barriers:The national standards body's certification requirements impose non-tariff friction on imported formulations without local testing infrastructure.
- Waste oil disposal protocols:Mandatory recycling infrastructure investment increases fixed cost burdens for smaller regional operators.
Strategic Opportunities
- Asset-light leasing models:Third-party blending and packaging capacity rental reduces capital barriers for new entrants targeting niche performance segments.
- Córdoba and Rosario industrial zones:Underpenetrated service infrastructure in these provincial manufacturing hubs offers volume expansion beyond Buenos Aires saturation.
- Automatic transmission fluid specialization:Technical differentiation in dual-clutch and continuously variable transmission formulations commands premium positioning in passenger vehicle aftermarket channels.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages compatible with exhaust after-treatment systems remains concentrated among multinational technical centers.
- Retrofit certification timelines:Existing lubricant portfolios require extended re-homologation cycles to meet evolving fuel economy mandates, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Lubricants Market |
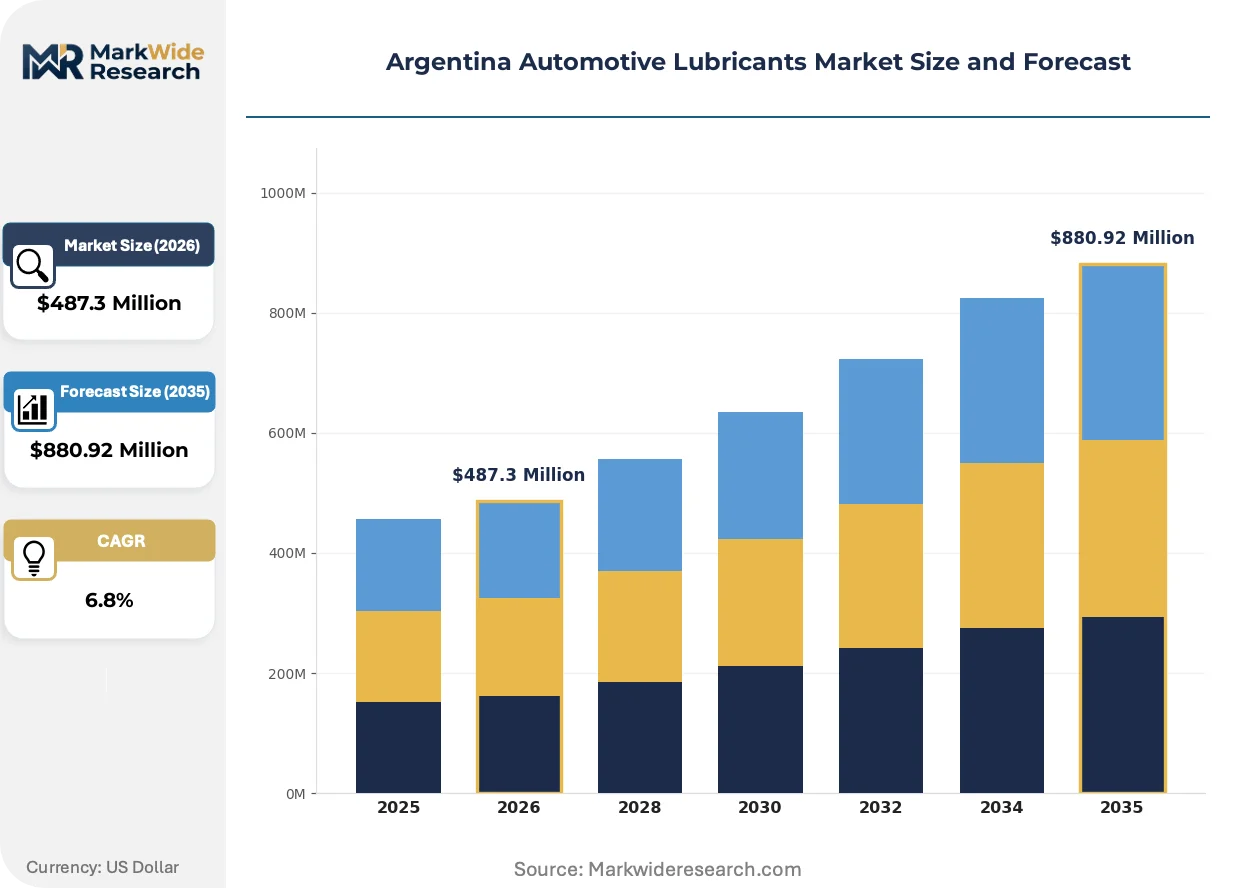
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: Passenger Vehicles, Commercial Trucks, Buses, Two-Wheelers Distribution Channel: Retail Outlets, Online Stores, Wholesalers, Service Stations Packaging Type: Bottles, Drums, Pails, Bulk |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, YPF, Petronas Lubricants International, Puma Energy, TotalEnergies, Shell, Valvoline, BP (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Lubricants Market Strategic Shifts
Reformulation cycles in Argentina are compressing as emissions standards tighten and fleet operators demand predictive maintenance integration. Three intersecting developments are reconfiguring competitive requirements for blenders and distributors.
Synthetic base stock technology is migrating from passenger vehicle premium segments into commercial fleet specifications. Heavy-duty operators in Argentina's long-haul corridors are adopting Group III and Group IV formulations to synchronize drain intervals with telematics-driven maintenance scheduling. This migration from mineral-based heritage formulations is enabling blenders to capture service-contract bundling opportunities and displace commodity competitors on total cost-of-ownership metrics rather than per-liter pricing.
Argentina's Secretariat of Energy fuel economy mandates are forcing additive package redesigns to reduce internal engine friction coefficients. The industrial consequence is accelerated obsolescence of legacy viscosity grades above 10W-40 in OEM first-fill specifications. Passenger vehicle assemblers in the Buenos Aires metropolitan production zone are most affected, responding with backward integration into lubricant technical service agreements that lock in formulation exclusivity.
Service station consolidation is restructuring fleet account access patterns. Independent truck operators and small fleet managers in Argentina's interior provinces are abandoning traditional distributor relationships for direct procurement through integrated fuel-and-lubricant card programs. This channel compression is most visible in Mendoza and Tucumán agricultural corridors, where fuel retailers are capturing lubricant attach rates through bundled pricing and centralized billing infrastructure.
Argentina Automotive Lubricants Market Segmentation
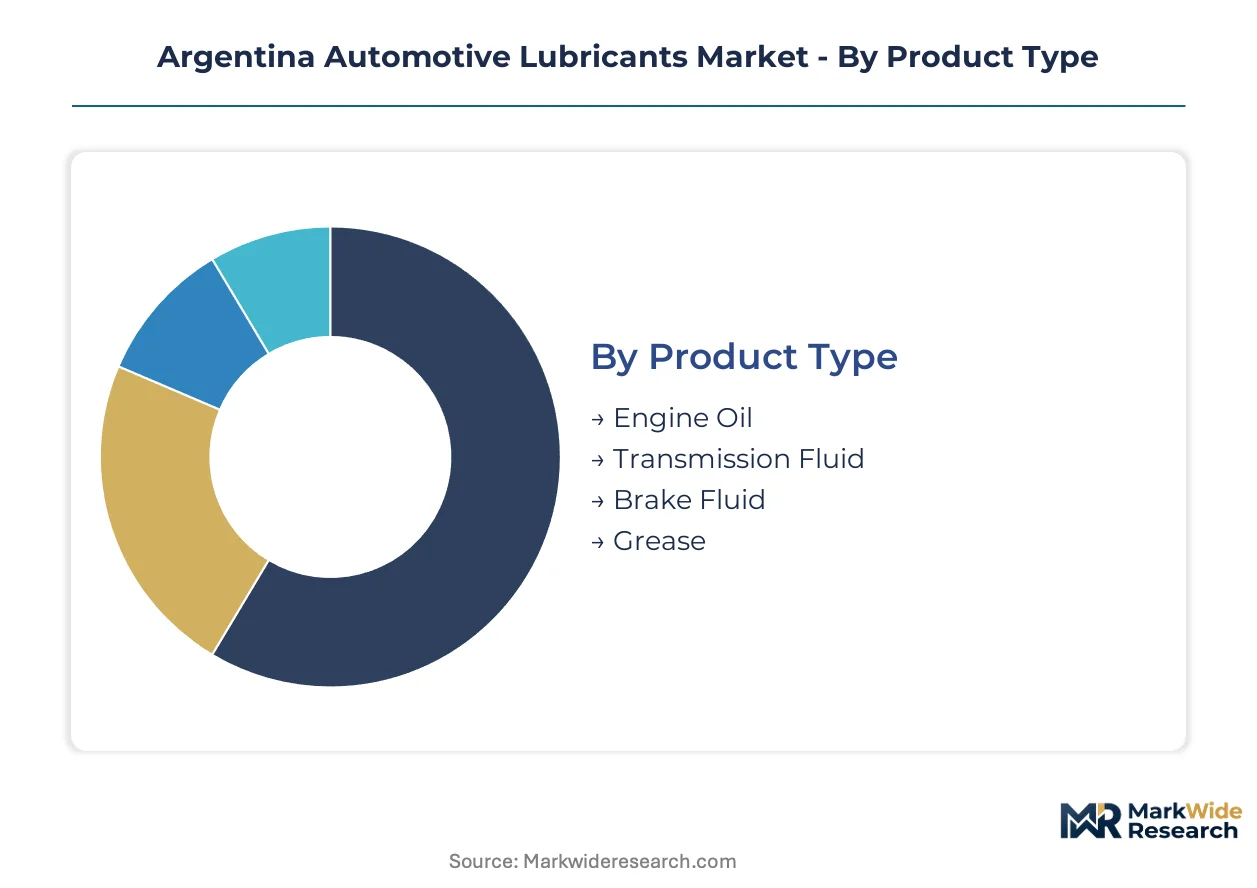
Segmentation in Argentina's automotive lubricants market reveals how formulation requirements diverge across vehicle architectures and procurement channels. Understanding these divides exposes where blenders can capture premium positioning versus commodity volume.
Product Type:
Mature mineral-based formulations coexist with emerging synthetic specifications as fleet operators recalibrate total cost-of-ownership calculations.
- Engine Oil:Formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with viscosity grades typically ranging from 0W-16 to 20W-50. Demand concentrates in the Greater Buenos Aires industrial corridor where concentrated vehicle density and established service infrastructure create volume pull for mandatory drain interval compliance.
- Transmission Fluid:Specialized lubricants for automatic, dual-clutch, and continuously variable transmissions requiring precise friction coefficients and thermal stability. Passenger vehicle assemblers in the Buenos Aires metropolitan production zone are specifying these fluids as automatic and dual-clutch penetration deepens, expanding margin pools beyond conventional engine oil categories.
- Brake Fluid:Hydraulic fluids meeting DOT specifications for moisture resistance and boiling point stability in braking systems.
- Grease:Semi-solid lubricants for chassis, wheel bearings, and industrial applications requiring adhesion under centrifugal load.
Engine Oil retains volume leadership; Transmission Fluid holds the steepest expansion curve.
End User:
Cost tier stratification separates high-frequency drain interval vehicles from extended-cycle commercial operations.
- Passenger Vehicles:Owners of cars and light SUVs demanding lower-viscosity, fuel-efficient formulations under tightening emissions standards. Argentina's Secretariat of Energy mandates are pushing blenders toward reformulated additive packages, with demand concentrating through retail outlets and service stations in urban centers.
- Commercial Trucks:Fleet operators extending vehicle replacement cycles beyond traditional thresholds and demanding higher-performance lubricant formulations that withstand elevated thermal loads. Long-haul corridors through Mendoza and Córdoba are adopting Group III and Group IV synthetic formulations to synchronize drain intervals with telematics-driven maintenance scheduling.
- Buses:Municipal and intercity transport fleets with high-utilization duty cycles and centralized procurement.
- Two-Wheelers:Motorcycle and scooter owners in dense urban environments with frequent stop-start operating conditions.
Commercial Trucks command the highest per-liter margins; Passenger Vehicles deliver the deepest volume base.
Distribution Channel:
Volume concentration versus margin capture splits across procurement infrastructure maturity.
- Retail Outlets:Independent auto parts stores and hypermarkets serving do-it-yourself consumers and independent mechanics. These channels lead in passenger vehicle aftermarket sales across Argentina's interior provinces where small fleet managers are abandoning traditional distributor relationships for direct procurement.
- Service Stations:Integrated fuel-and-lubricant retail points anchoring fleet and commercial account access. Consolidation is restructuring account patterns in agricultural corridors where fuel retailers capture lubricant attach rates through bundled pricing and centralized billing infrastructure.
- Online Stores:E-commerce platforms offering price transparency and bulk purchasing for informed buyers.
- Wholesalers:Regional distributors serving independent workshops and smaller retailers with inventory financing.
Service Stations retain fleet account dominance; Online Stores are climbing the fastest in share gain.
Packaging Type:
Customer scale and application context determine container economics across the procurement spectrum.
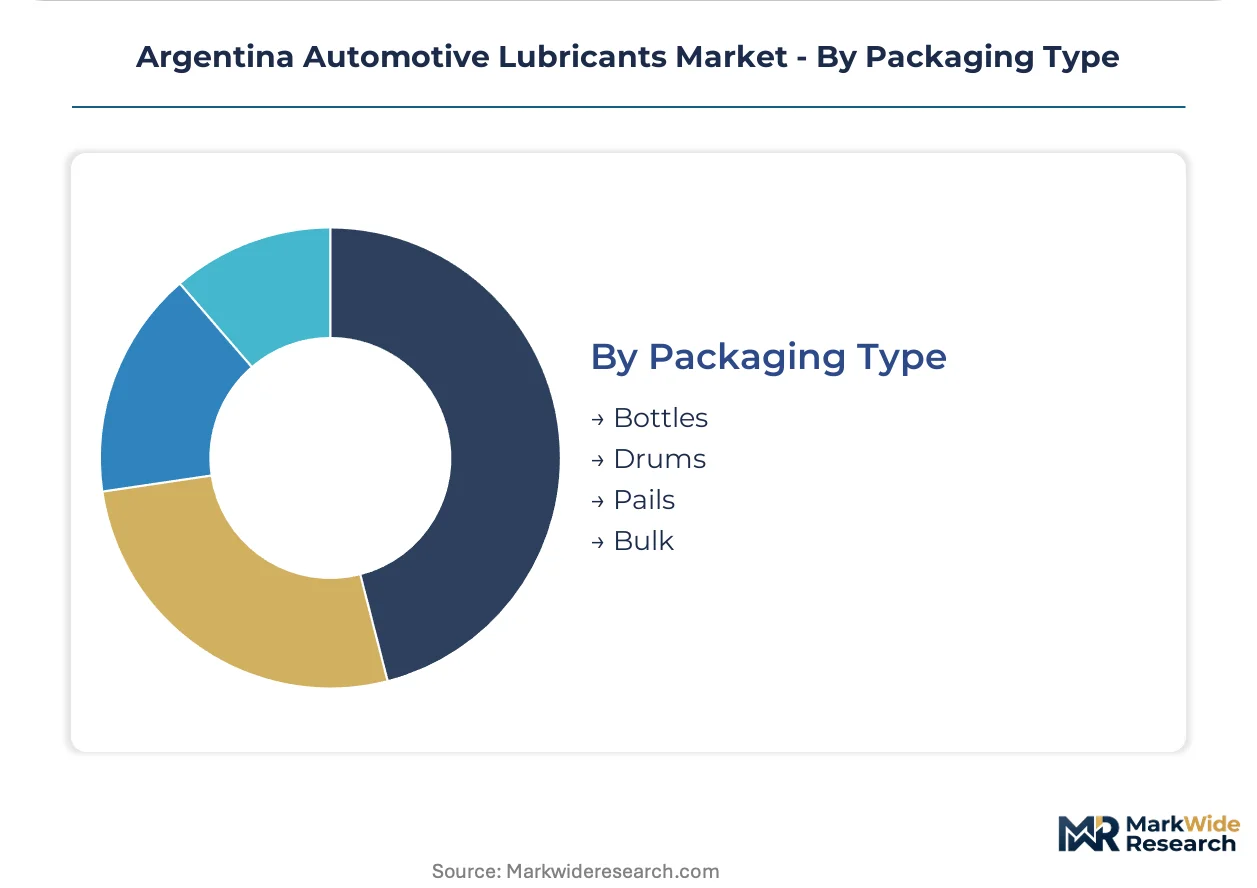
- Bottles:Consumer-format packaging for 1-liter to 5-liter volumes targeting individual vehicle owners and small independent workshops. Retail outlets in Greater Buenos Aires generate concentrated demand for these formats among passenger vehicle do-it-yourself segments.
- Drums:200-liter steel containers for medium-volume commercial operators and fleet maintenance bays. Córdoba and Rosario industrial zones present underpenetrated expansion opportunities for drum-format distribution beyond Buenos Aires saturation.
- Pails:20-liter to 50-liter plastic containers bridging retail and bulk procurement for small commercial accounts.
- Bulk:Tanker and tote deliveries for large fleet operators with on-site storage and dispensing infrastructure.
Bottles retain the broadest customer reach; Bulk deliveries are expanding most quickly among telematics-integrated fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Greater Buenos Aires while interior provinces absorb higher logistics premiums. The national market fragments across five distinct economic corridors with divergent fleet compositions and service infrastructure maturity.
Greater Buenos Aires
Passenger vehicle density and consolidated service infrastructure generate volume concentration unmatched elsewhere. Argentina's Secretariat of Energy fuel economy mandates enforce reformulation cycles fastest here. The metropolitan production zone anchors OEM first-fill specifications and backward integration into lubricant technical service agreements.
Córdoba Industrial Zone
Automotive parts manufacturing and agricultural machinery fleets create blended demand for commercial and passenger formulations. Provincial environmental regulators enforce waste oil disposal protocols with tighter inspection regimes than national baselines. Underpenetrated service infrastructure relative to vehicle stock offers expansion headroom for drum-format distribution.
Rosario Port Corridor
Grain export logistics and long-haul trucking to Atlantic terminals sustain heavy-duty lubricant consumption. Fleet operators here pioneered telematics-driven maintenance scheduling and Group III synthetic adoption. The Paraná River industrial belt lacks the blending capacity density of Buenos Aires, creating procurement cost disadvantages.
Mendoza Agricultural Belt
Wine industry transport fleets and mining equipment service generate seasonal demand spikes. Fuel retailers have captured lubricant attach rates through integrated card programs. Provincial regulators lag Buenos Aires in emissions enforcement timelines, extending heritage formulation viability.
Patagonian Extraction Zones
Oilfield service vehicles and remote mining operations demand extreme-temperature formulations with extended drain intervals. Logistics costs inflate delivered prices versus coastal benchmarks. YPF's captive crude access provides supply security unavailable to independent blenders in this corridor.
Argentina Automotive Lubricants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in base oil and additive supply. Argentina's market structures around three tiers: national oil companies with captive refinery networks, multinational lubricant marketers with controlled retail footprints, and independent blenders leasing third-party capacity. Strategic archetypes include vertically integrated supply chain controllers, formulation technology licensors, and asset-light niche specialists. Competitive moves concentrate on backward integration into additive package design and service station network consolidation.
Among multinational marketers, Shell, BP (Castrol), and TotalEnergies occupy positions defined by retail infrastructure control and specialized formulation portfolios. Shell exemplifies the integrated fuel-and-lubricant platform model through its service station dominance. BP (Castrol) anchors the premium passenger vehicle segment via technical differentiation in high-performance specifications. TotalEnergies represents European-based formulation expertise applied to Mercosur regulatory alignment. National champion YPF sits apart with captive crude supply and domestic refinery network advantages that independent blenders cannot replicate.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| YPF |
| Petronas Lubricants International |
| Puma Energy |
| TotalEnergies |
| Shell |
| Valvoline |
| BP (Castrol) |
| Others |
Value Chain & Pricing Dynamics
Domestic refinery concentration around Buenos Aires anchors input cost structures for independent blenders lacking YPF's captive crude access. Margin pools concentrate downstream with formulators who control additive package design and service station network consolidation, while base oil procurement economics remain tethered to national refining capacity utilization.
Pricing Analysis
The customization-premium spread between fleet-configured synthetic formulations and standard mineral grades widens as telematics integration demands tailored drain interval programming. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because import-dependent blenders face exchange rate volatility on additive packages. Fleet operators with centralized procurement show lowest price sensitivity; independent retail buyers in interior provinces exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock flows draw from domestic Argentine refinery output, imported Group II/III base stocks from the United States, and additive packages sourced from European and Asian chemical majors. The supply chain rests on Group III synthetic base oils, friction modifier additives, and viscosity index improvers as critical inputs. Single-source vulnerability concentrates in exhaust after-treatment compatible low-SAPS additive chemistries controlled by multinational technical centers. Distribution runs through YPF's captive retail network, Shell's integrated fuel-and-lubricant platforms, and independent wholesalers serving provincial workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive lubricants market operates as a substitution defense against electrification-driven fluid demand erosion and synthetic base stock technology migration that displaces mineral heritage formulations.
For Market Incumbents: Build formulation exclusivity moats through backward integration into additive package design and OEM technical service agreements. Lock in fleet accounts with telematics-integrated maintenance contracts that synchronize drain intervals with lubricant specification. Defend against synthetic technology migration by accelerating Group III/IV portfolio conversion before independent blenders capture service-contract bundling opportunities.
For New Entrants and Emerging Players: Córdoba and Rosario industrial zones present underpenetrated drum-format distribution infrastructure relative to vehicle density. Target commercial trucking fleets in Mendoza agricultural corridors where fuel retailers have captured lubricant attach rates but formulation expertise remains thin. Enter through asset-light leasing of third-party blending capacity to bypass capital barriers while specializing in dual-clutch transmission fluid technical differentiation.
For Investors and Strategic Acquirers: Capital is best deployed toward independent blenders with established homologation infrastructure and provincial distribution networks that larger platforms can consolidate. Long-term viability hinges on Mercosur emissions alignment execution and the pace of automatic transmission penetration in passenger vehicles. Monitor Secretariat of Energy fuel economy mandate enforcement timelines as the inflection signal for reformulation cycle acceleration and legacy grade obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Package Design | Captures margin pools from multinational chemical suppliers while locking OEM exclusivity through formulation control. |
| Telematics-Integrated Service Contracts | Bundles lubricant supply with predictive maintenance scheduling, displacing commodity competitors on total cost-of-ownership metrics. |
| Provincial Distribution Network Expansion | Captures volume in Córdoba and Rosario corridors where service infrastructure lags vehicle density concentration. |
| Synthetic Base Stock Portfolio Conversion | Aligns product mix with fleet operator extended drain interval demands under Mercosur emissions pressures. |
| Homologation Infrastructure Investment | Reduces non-tariff friction on imported formulations and accelerates product refresh cycles against regulatory deadlines. |
Study Parameters
A spread of perspectives from lubricant formulators, fleet procurement managers, service station operators, and additive chemists converged on the working assumptions driving demand modeling. Primary interviews with YPF technical directors, Shell retail network managers, and independent blender operations heads combined with secondary validation from Secretariat of Energy regulatory filings, national standards body certification databases, and Mercosur emissions alignment protocols. Bottom-up segmentation analysis triangulated against top-down macroeconomic indicators to establish volume and value baselines.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, end user category, distribution channel, and regional production cluster dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporated vehicle parc expansion rates, automatic transmission penetration assumptions, and synthetic base stock adoption elasticities specific to commercial fleet operating profiles.
Practitioners should monitor Secretariat of Energy mandate enforcement intensity and Mercosur emissions protocol adoption timelines for early signals of reformulation cycle compression. Forecasts reflect assumptions about base oil import dependency stability and additive chemist talent availability that material regulatory or macroeconomic shifts could revise. Cross-checking against vehicle production and registration data from Buenos Aires metropolitan manufacturing associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Europe Industrial Roller Chain Drive Market