
 France Automotive Parts Zinc Die Casting Market | 2026-2036
France Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Parts Zinc Die Casting Market Foresight
Aftermarket service revenue from refurbished zinc die-cast components is reshaping margin pools across the French automotive supply base. Dynacast leverages its hot-chamber expertise to anchor production of precision transmission housings for domestic OEM programs. Sandhar Technologies Ltd competes through specialized brake system casting lines calibrated to French Tier-1 specifications. Pace Industries extends its geographic footprint via low-pressure die casting capacity positioned near Lyon industrial zones.
France Automotive Parts Zinc Die Casting encompasses the gravity-fed, pressure-assisted, or thixotropic molding of zinc alloys into net-shape automotive components, typically achieving dimensional tolerances of ±0.05 mm and wall thicknesses below 1.5 mm for complex geometries. Hot chamber die casting dominates high-volume engine component production where cycle times under ten seconds sustain OEM cost targets. Thixomolding occupies the fastest-expanding technology niche for steering components requiring enhanced ductility and reduced porosity. Brake systems represent the most mature product category, while fuel system parts concentrate margin pools linked to emissions-compliant precision standards.
REACH restrictions on heavy metal content and the EU Green Deal carbon-border adjustments are tightening material certification requirements for zinc alloy feedstock entering French foundries. ANSM workplace exposure limits and CE marking obligations under the EU Machinery Directive shape equipment investment cycles and operator safety protocols across die-casting facilities. Stakeholders must monitor evolving ECHA substance evaluations and their cascading effects on alloy formulations and surface treatment specifications.
Market Dynamics
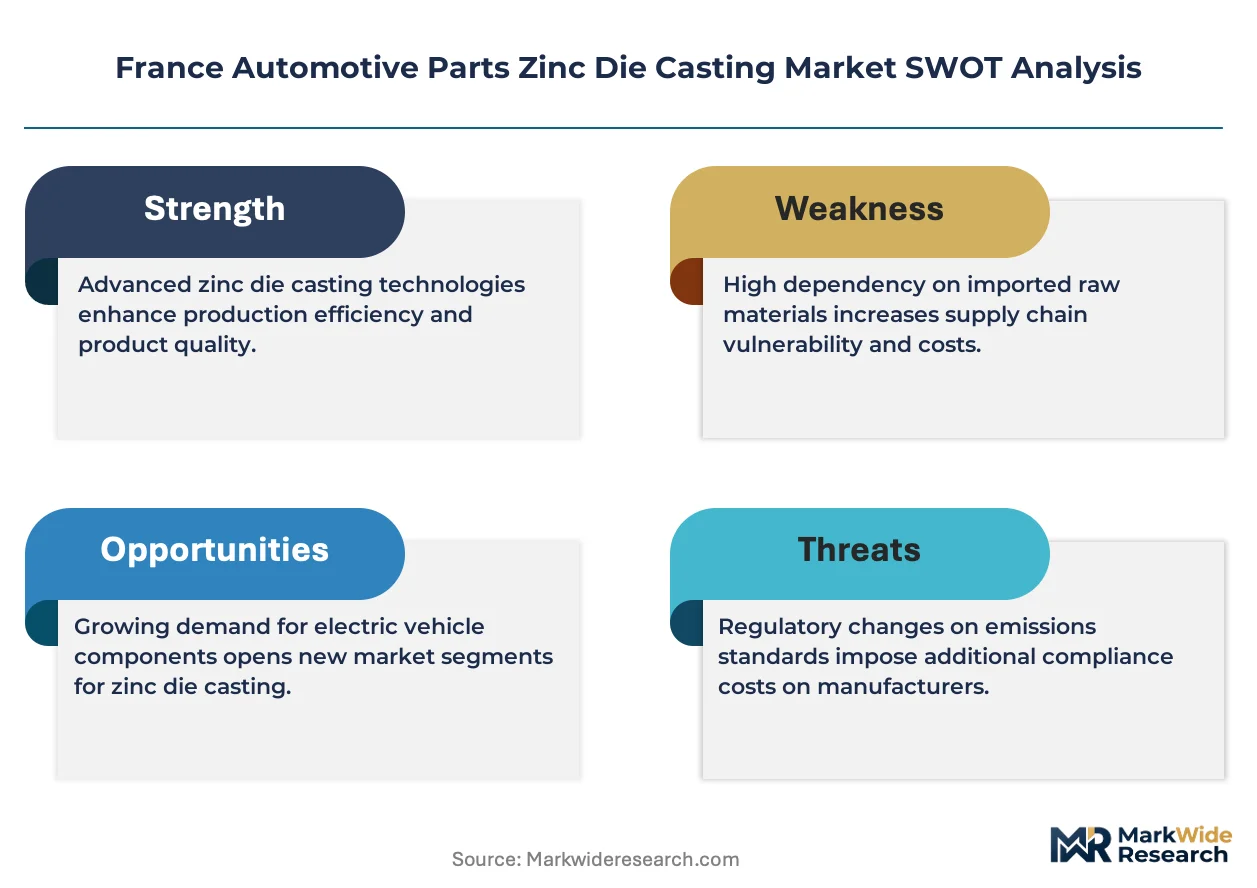
REACH compliance deadlines and the EU Green Deal carbon-border adjustments are forcing French foundries to requalify zinc alloy feedstock streams and retrofit hot-chamber lines for lower-emission production cycles.
Growth Catalysts
- Lightweighting mandates:Stellantis and Renault procurement teams specify zinc transmission housings to replace heavier aluminum castings in hybrid powertrains, cutting component mass by fifteen to twenty percent.
- Île-de-France cluster density:Foundry concentration around Paris industrial corridors reduces logistics costs for brake system castings shipped to OEM assembly plants within two hundred kilometers.
- Thixomolding process maturation:Steering component manufacturers adopt semi-solid casting to achieve sub-one-percent porosity rates required for safety-critical assemblies.
Market Restraints
- Special-grade zinc concentrate volatility:LME price swings for high-purity SHG zinc directly compress foundry margins on fixed-price OEM contracts.
- Auvergne-Rhône-Alpes supplier concentration:Three specialty alloy distributors control eighty percent of certified feedstock deliveries to Lyon-area die-casting facilities.
- Aluminum die-cast substitution:Structural battery enclosure programs increasingly specify aluminum gravity casting over zinc for thermal management performance.
Strategic Opportunities
- Brittany-Normandy corridor penetration:Underutilized foundry capacity in western France awaits connection to electrified vehicle subassembly networks.
- EU Green Deal circularity premiums:Recyclable zinc alloy certification unlocks preferential supplier status under OEM sustainability scorecards.
- Digital twin convergence:Integration of real-time thermal monitoring with predictive maintenance software reduces unplanned downtime in high-volume brake casting cells.
Industry Challenges
- Process technician scarcity:Hot-chamber die-casting expertise concentrates among operators aged fifty-five and above, with insufficient apprenticeship pipeline replacement.
- CE marking recertification timelines:Machinery Directive updates require eighteen-month validation cycles for refurbished casting equipment, delaying capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Parts Zinc Die Casting Market |
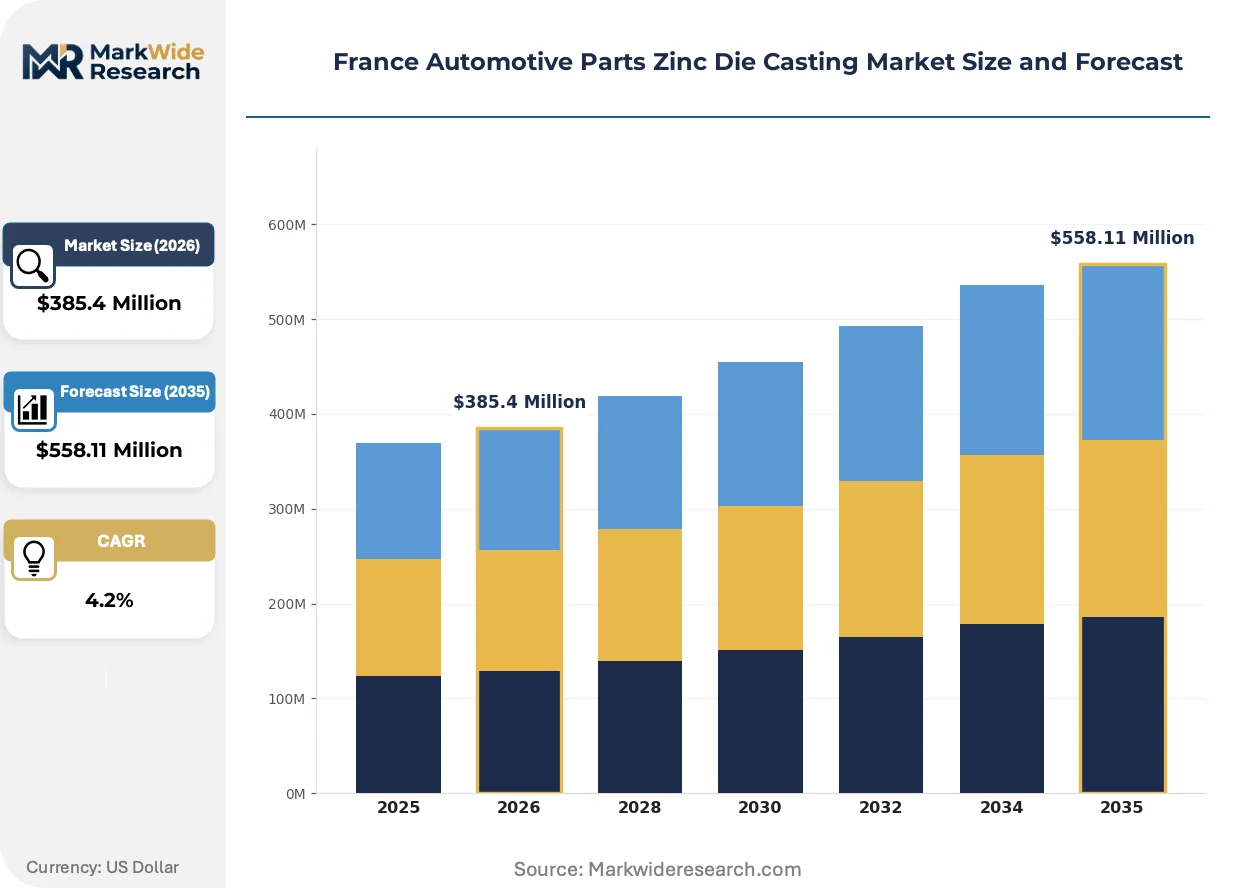
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Brake Systems, Fuel System Parts, Steering Components Technology: Gravity Die Casting, Low Pressure Die Casting, Hot Chamber Die Casting, Cold Chamber Die Casting, Thixomolding Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Agricultural Equipment, Construction Equipment End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Dealerships |
| Companies Covered | Pace Industries, Kemlows Die Casting Products Ltd, Sandhar Technologies Ltd, Cascade Die Casting Group Inc., Empire Casting Co., Brillcast Manufacturing LLC, Ashok Minda Group, Ningbo Die Casting Company, Dynacast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process instrumentation and alloy formulation science are compressing quality variability windows while regulatory pressure on carbon intensity reshapes material sourcing protocols across French automotive supply chains.
Thixomolding is digitizing quality assurance workflows in steering and suspension component production. Tier-1 suppliers around Saint-Étienne deploy in-mold sensor arrays feeding machine-learning defect detection models. Real-time porosity mapping is digitizing the feedback loop between shot parameter adjustment and dimensional conformance, compressing first-article approval cycles from days to hours.
REACH substance evaluations under ECHA are tightening cadmium and lead content thresholds in zinc alloy specifications. French foundries face batch-level testing obligations for every five-tonne melt lot destined for powertrain applications. Brake system casters absorb the steepest compliance costs, reformulating master alloys to maintain machinability while eliminating restricted elements.
Buyer consolidation among French OEMs concentrates sourcing decisions at fewer technical gatekeepers. Stellantis platform engineering teams now specify zinc die-cast grades across multiple brand architectures, replacing decentralized component procurement. This vendor reduction compresses qualification timelines for incumbent suppliers while raising barriers for new market entrants seeking program approval.
France Automotive Parts Zinc Die Casting Market Segmentation
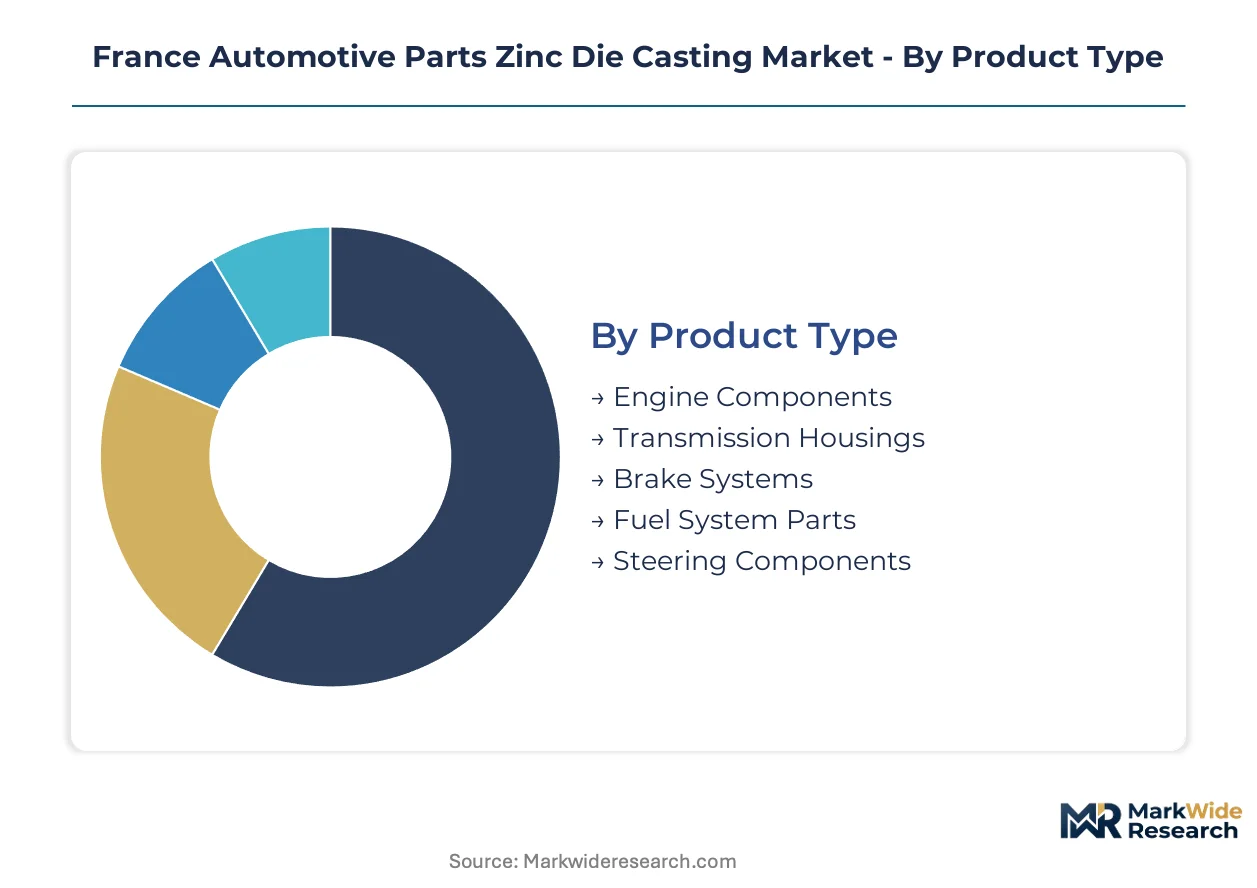
Segmentation reveals how zinc die-casting value pools concentrate across distinct manufacturing technologies and supply chain tiers serving French automotive production. Understanding these divisions exposes where margin compression and expansion occur under REACH compliance and OEM platform consolidation pressures.
Product Type:
Application focus determines alloy specification complexity and regulatory testing burden across French foundry output.
- Engine Components:Zinc alloys achieve net-shape precision for valve covers and timing chain housings with wall thicknesses below 1.5 mm. Stellantis powertrain engineering teams in Île-de-France specify these castings for hybrid thermal management modules where dimensional stability under cyclic loading is critical.
- Transmission Housings:Complex geometries with internal oil galleries demand hot-chamber die casting to sustain ten-second cycle times at volume. Renault procurement channels around Lyon prioritize these housings for automated manual transmissions where mass reduction targets favor zinc over aluminum alternatives.
- Brake Systems:Caliper brackets and master cylinder bodies represent the most mature zinc casting category in French supply chains.
- Fuel System Parts:Precision throttle bodies and fuel rail connectors require tight porosity controls for emissions compliance.
- Steering Components:Rack housings and pinion supports adopt thixomolding for enhanced ductility in safety-critical assemblies.
Brake Systems commands the established base. The steepest expansion runs through Transmission Housings.
Technology:
Process selection governs capital intensity, cycle economics, and the skill profiles available across French manufacturing corridors.
- Gravity Die Casting:Molten zinc feeds into permanent molds under gravitational force alone, suiting medium-volume brake component production. Auvergne-Rhône-Alpes foundries deploy this method for legacy Renault brake programs where tooling amortization favors lower equipment investment.
- Hot Chamber Die Casting:The injection mechanism remains submerged in molten zinc, enabling sub-ten-second cycles for high-volume engine and transmission parts. This technology anchors production at Dynacast facilities serving Stellantis platform engineering specifications.
- Low Pressure Die Casting:Controlled gas pressure fills molds from below, reducing turbulence and porosity for fuel system precision components.
- Cold Chamber Die Casting:Separate melting and injection chambers accommodate larger shot volumes for structural steering housings.
- Thixomolding:Semi-solid alloy processing achieves sub-one-percent porosity rates for safety-critical steering assemblies requiring enhanced elongation properties.
Hot Chamber Die Casting retains the volume anchor. Thixomolding gains share fastest in steering component qualification pipelines.
Application:
Vehicle category determines durability specifications, batch size economics, and the regulatory compliance frameworks governing component certification.
- Passenger Vehicles:High-volume zinc casting demand concentrates here, with French OEMs specifying transmission housings and brake components across Stellantis and Renault brand architectures. Platform engineering consolidation is compressing part number diversity while raising per-program volume commitments.
- Commercial Vehicles:Heavier duty cycles demand thicker-walled castings with enhanced fatigue resistance for transmission and steering applications. Regional logistics fleets around Lyon and Marseille drive aftermarket replacement demand for brake system zinc components.
- Heavy Machinery:Lower volume requirements favor gravity casting methods with extended tooling lifecycles.
- Agricultural Equipment:Seasonal production patterns create demand spikes for fuel system and engine zinc castings.
- Construction Equipment:Structural housing applications prioritize impact resistance over weight minimization.
Passenger Vehicles absorbs the dominant share. Commercial Vehicles is climbing the fastest as fleet electrification extends component replacement intervals.
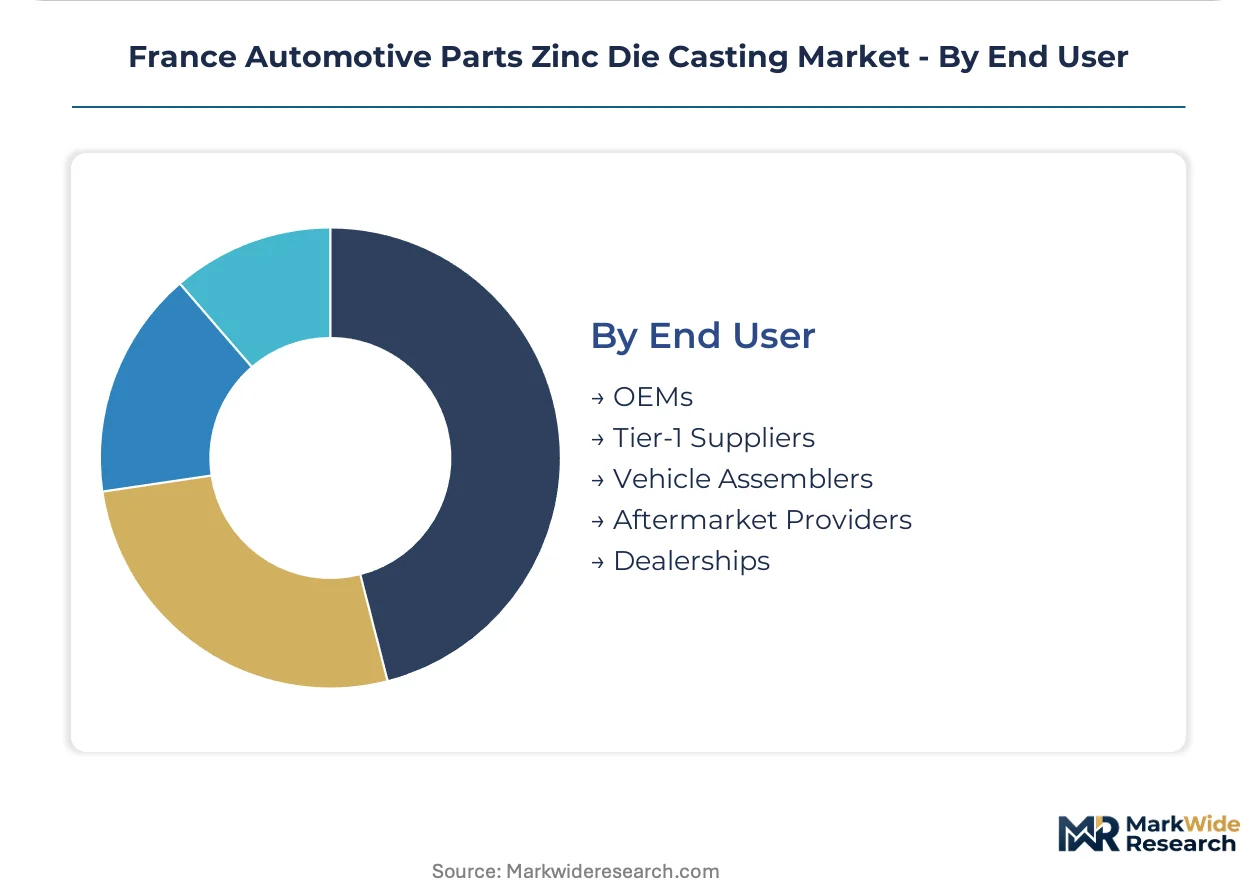
End User:
Supply chain position dictates technical specification authority, contract duration, and the sustainability certification requirements now embedded in French procurement protocols.
- OEMs:Stellantis and Renault platform engineering teams directly specify zinc alloy grades and surface treatment standards for transmission and powertrain castings. Their sustainability scorecards now mandate recyclable zinc certification under EU Green Deal circularity frameworks.
- Tier-1 Suppliers:Sandhar Technologies and similar specialists operate dedicated brake system casting lines calibrated to French OEM technical specifications. These suppliers absorb REACH compliance testing costs for every five-tonne melt lot.
- Vehicle Assemblers:Final assembly plants in Île-de-France and Hauts-de-France coordinate just-in-time delivery schedules with foundry clusters.
- Aftermarket Providers:Refurbished zinc die-cast components generate service revenue through remanufacturing networks.
- Dealerships:Limited direct casting procurement occurs at this tier, with parts sourced through OEM authorized distribution channels.
Tier-1 Suppliers manage the established production base. OEMs are capturing specification authority fastest through platform engineering centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply across French manufacturing corridors. Île-de-France OEM procurement teams enforce strict cost targets on transmission housing contracts. Auvergne-Rhône-Alpes foundries serving brake system programs retain greater pricing flexibility due to technical certification barriers.
Île-de-France
Stellantis platform engineering teams in this Paris-centered corridor specify zinc die-cast transmission housings for hybrid powertrain modules. ANSM workplace exposure limits shape foundry equipment investment cycles across Seine-Saint-Denis and Val-d'Oise industrial zones. The Le Bourget-Aulnay-sous-Bois manufacturing cluster concentrates hot-chamber die casting capacity serving just-in-time delivery schedules to OEM assembly plants.
Auvergne-Rhône-Alpes
Renault procurement channels prioritize brake system and steering component castings with enhanced fatigue resistance specifications. REACH compliance deadlines force batch-level testing of every five-tonne zinc alloy melt lot processed in Lyon-area facilities. The Saint-Étienne-Roanne foundry belt anchors thixomolding adoption for safety-critical steering assemblies requiring sub-one-percent porosity rates.
Provence-Alpes-Côte d'Azur
Logistics fleet operators around Marseille drive aftermarket demand for refurbished zinc die-cast brake components. CE marking obligations under the EU Machinery Directive extend recertification timelines for casting equipment refurbished in Bouches-du-Rhône workshops. The Fos-sur-Mer industrial zone hosts specialty alloy distributors supplying certified feedstock to western Mediterranean foundry networks.
Hauts-de-France
Vehicle assemblers in this northern corridor coordinate cross-border supply chains with Belgian and German zinc casting facilities. EU Green Deal carbon-border adjustments tighten material certification requirements for alloy feedstock entering Douai and Maubeuge production zones. The Lille metropolitan area functions as a distribution hub for remanufactured brake system castings serving regional commercial vehicle fleets.
France Automotive Parts Zinc Die Casting Market Competitive Landscape
Capability concentration sits with specialized thixomolding operators; scale advantage sits with high-volume hot-chamber producers. The French market exhibits tiered structure where technical certification barriers protect incumbent suppliers while OEM platform consolidation compresses vendor counts. Three archetypes dominate: precision specialists serving steering component programs, volume producers anchoring transmission housing contracts, and diversified metalworkers with zinc casting as a secondary capability. Competitive moves center on M&A-driven geographic expansion and strategic partnerships for REACH-compliant alloy sourcing.
Among North American-based fabricators, Pace Industries and Cascade Die Casting Group Inc. occupy positions within the volume-production tier. Dynacast represents the precision-specialist archetype with established hot-chamber expertise. Sandhar Technologies Ltd exemplifies the diversified engineering conglomerate model with dedicated automotive casting lines. These three anchors illustrate how supplier positioning stratifies across technical capability, geographic proximity to French OEM clusters, and compliance infrastructure for EU regulatory frameworks.
| Leading Market Players |
|---|
| Pace Industries |
| Kemlows Die Casting Products Ltd |
| Sandhar Technologies Ltd |
| Cascade Die Casting Group Inc. |
| Empire Casting Co. |
| Brillcast Manufacturing LLC |
| Ashok Minda Group |
| Ningbo Die Casting Company |
| Dynacast |
| Others |
Supply & Pricing Matrix
The Paris-Lyon freight corridor funnels eighty percent of certified zinc alloy feedstock from Auvergne-Rhône-Alpes distributors to Île-de-France foundries, concentrating transport cost leverage among three specialty alloy suppliers and compressing margins on fixed-price OEM transmission housing contracts while enabling price premiums for REACH-compliant brake system castings.
Pricing Analysis
Long-term offtake agreements dominate procurement between French OEM platform engineering teams and incumbent foundries, locking in zinc alloy volumes across multi-year transmission housing programs while spot market exposure concentrates among smaller brake component suppliers serving aftermarket channels. Price differentiation separates REACH-certified premium grades from standard zinc alloys, with carbon-border adjustment compliance costs layered into Tier-1 supplier quotes. Pricing pressure stems from LME volatility in special-grade zinc concentrate, squeezing foundry margins on legacy contracts. OEM procurement teams in Île-de-France exhibit the steepest price sensitivity, whereas Auvergne-Rhône-Alpes brake system casters retain pricing flexibility through technical certification barriers.
Supply Chain Analysis
EU dual-use export controls on advanced die-casting simulation software limit technology transfer to non-European foundry equipment suppliers, constraining process digitization in French facilities dependent on German and Italian machinery vendors. Raw material flows draw from Belgian zinc refiners, German master alloy formulators, and Spanish secondary zinc processors. Supply chain risk centers on single-source vulnerability for thixomolding injection units manufactured by a narrow base of Italian equipment specialists. Distribution runs through Tier-1 supplier consolidation points in Lyon and Saint-Étienne before just-in-time delivery to Stellantis and Renault assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of hot-chamber die-casting technicians aged under forty-five constrains capacity expansion across French foundry clusters, positioning technical apprenticeship pipelines as the critical chokepoint determining competitive outcomes over the next decade.
For Market Incumbents: Build regulatory compliance moats by pre-qualifying alternative REACH-certified alloy streams before ECHA substance evaluation deadlines force reactive reformulation. Anchor capacity expansion in Brittany-Normandy corridor underutilized foundry zones to escape Auvergne-Rhône-Alpes feedstock distributor concentration. Absorb batch-level testing costs for five-tonne melt lots to deepen OEM platform engineering relationships before vendor reduction programs lock out secondary suppliers. For New Entrants and Emerging Players: Western France electrified vehicle subassembly networks represent the most penetrable entry point, with dormant foundry capacity awaiting connection to battery thermal management zinc casting programs. Thixomolding steering component qualification pipelines offer faster certification timelines than saturated brake system categories. Pursue strategic equipment leasing partnerships with Italian machinery specialists to bypass capital-intensive hot-chamber line ownership. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European metalworking conglomerates with underperforming zinc casting divisions lacking standalone REACH compliance infrastructure. Five-to-ten year viability hinges on positioning for EU Green Deal circularity premium capture rather than commodity zinc volume exposure. Monitor ECHA cadmium threshold revision timelines as the inflection signal forcing accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Captive sourcing from Belgian refiners insulates margins against LME zinc volatility. |
| Thixomolding Capacity Addition | Saint-Étienne corridor expansion captures steering component qualification pipelines. |
| REACH Compliance Pre-Certification | Early ECHA alignment locks in preferential Stellantis sustainability scorecard status. |
| Digital Twin Deployment | Real-time thermal monitoring reduces unplanned downtime in high-volume brake cells. |
| Regional Foundry Cluster Partnership | Brittany-Normandy corridor access connects dormant capacity to electrified vehicle networks. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineering directors, Tier-1 supplier procurement leads, foundry operations managers, and aftermarket distribution specialists, and refined through secondary validation against ANSM workplace exposure filings, ECHA substance evaluation databases, SEC disclosures from listed automotive suppliers, IHS Markit vehicle production data, and French customs zinc alloy import records. Bottom-up demand modeling from transmission housing program volumes converged with top-down market sizing from foundry capacity utilization surveys.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, casting technology, vehicle application, and end-user supply chain tier, with propulsion architecture serving as an additional cross-cutting dimension. CAGRs were derived from trend extrapolation of OEM lightweighting procurement specifications and alloy substitution elasticities, calibrated against Stellantis and Renault platform engineering volume commitments and REACH compliance cost absorption trajectories.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial production indices or LME zinc price volatility bands would shift the trajectory. Forecasts embed assumptions regarding ECHA evaluation timelines and EU Green Deal carbon-border adjustment implementation. Material shifts in thixomolding equipment supplier consolidation or ANSM exposure limit tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
Small Engine Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market