
 Automotive Viscosity Index Improvers Market | 2026-2036
Automotive Viscosity Index Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Viscosity Index Improvers Market Outlook
API SP-Resource Conserving qualification is unwinding the competitive field for additive suppliers seeking OEM approvals. Evonik Industries AG leverages its methacrylate chemistry platform to sustain formulation leadership across European and Asian markets. Chevron Oronite Company LLC anchors its position through integrated base oil and additive manufacturing in the Americas. The Lubrizol Corporation dominates dispersant-VII hybrid technologies that reduce treat rates in next-generation engine oils.
Automotive viscosity index improvers are polymeric additives—typically polymethacrylates, olefin copolymers, or hydrogenated styrene-diene polymers—that expand across temperature ranges to stabilize lubricant viscosity between cold starts and high-temperature operation. These polymers function by coiling at low temperatures to minimize thickening and uncoiling at elevated temperatures to resist thinning, enabling SAE 0W-16 and 0W-8 grades demanded by modern engine architectures. Hydrocarbon-based improvers lead volume shipments due to cost efficiency in mass-market engine oils, while ester chemistry captures premium positioning in transmission fluids where oxidative stability requirements intensify. Polyalkylene glycol formulations represent the fastest-expanding category as electric vehicle thermal management fluids create adjacent demand beyond traditional drivetrain applications.
EPA fuel economy regulations and Euro 6 emission standards collectively mandate lower high-temperature high-shear viscosity grades that reshape additive specification requirements. REACH registration obligations in Europe and evolving GB standards in China create divergent compliance pathways that fragment formulation strategies across regions. Stakeholders must monitor OEM factory-fill approval timelines and regional lubricant specification divergence to align R&D portfolios with the next certification cycle.
Market Dynamics
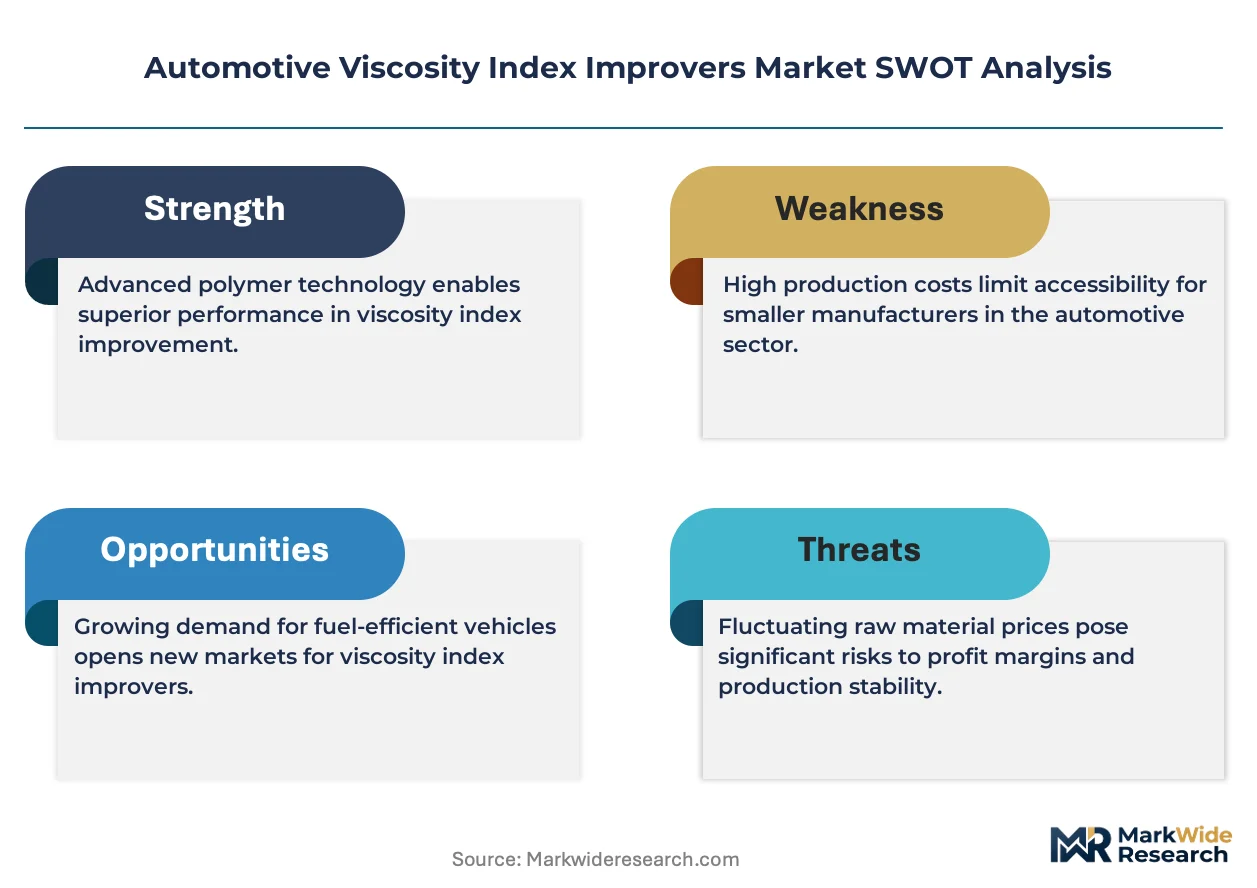
EPA fuel economy mandates and Euro 6 emission limits are compressing lubricant viscosity grades, forcing polymer suppliers to reformulate for SAE 0W-16 and 0W-8 engine oils that maintain film strength under thinner operating conditions.
Growth Catalysts
- EPA CAFE Standards:Corporate Average Fuel Economy targets in the United States mandate lower-viscosity lubricants that reduce engine friction losses, expanding specification demand for high-performance viscosity modifiers.
- Synthetic Oil Conversion:Passenger vehicle OEMs in China are accelerating factory-fill synthetic adoption, creating formulation pull for polymethacrylate and olefin copolymer improvers compatible with Group III and PAO base stocks.
- Electric Vehicle Thermal Fluids:Battery electric vehicle powertrain architectures require dedicated thermal management fluids with stable viscosity across wider temperature ranges, opening adjacent polymer demand beyond traditional engine oils.
Market Restraints
- Alpha-Olefin Feedstock Volatility:Hydrocarbon-based viscosity improvers depend on ethylene-propylene copolymer supply chains concentrated in Gulf Coast petrochemical corridors, exposing margins to olefin price swings.
- REACH Registration Burden:ECHA compliance obligations for polymer imports into Europe impose documentation costs and timeline risks that disadvantage smaller additive blenders against integrated majors.
- Base Oil-Additive Integration:Captive supply relationships between major lubricant marketers and in-house additive divisions restrict third-party VII supplier access to factory-fill specifications at leading OEMs.
Strategic Opportunities
- India Two-Wheeler Synthetic Transition:BIS lubricant specification upgrades and OEM push for longer drain intervals create first-mover positioning for improver suppliers targeting Hero MotoCorp and TVS Motor formulations.
- Polyalkylene Glycol Convergence:PAG chemistry compatibility with both electric vehicle coolants and high-performance transmission fluids enables cross-application polymer platforms that reduce R&D duplication.
- China GB Standard Harmonization:Evolving national lubricant classifications toward international viscosity grades reduces regional formulation fragmentation, streamlining approval investments for multinational additive suppliers.
Industry Challenges
- OEM Approval Timeline Compression:API SP-Resource Conserving and ILSAC GF-6A certification cycles demand 24-36 month field test commitments that strain R&D resource allocation across simultaneous qualification programs.
- Dispersant-VII Hybrid Integration:Converging soot-handling and viscosity-stabilization functions into single-polymer architectures requires polymer chemistry expertise scarce among mid-scale additive houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Viscosity Index Improvers Market |
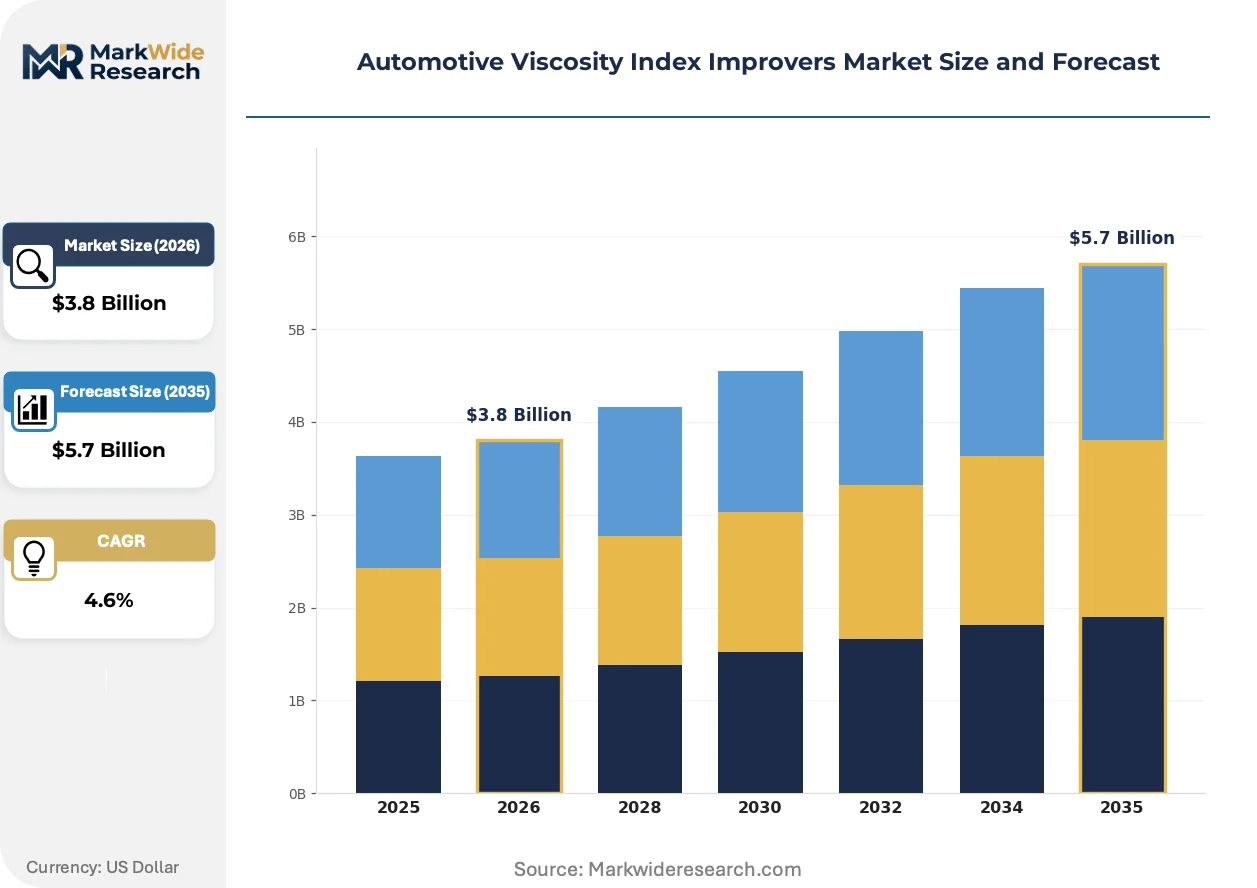
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyalkylene Glycol, Hydrocarbon, Ester, Others Application: Engine Oils, Transmission Fluids, Hydraulic Fluids, Greases End User: OEMs, Aftermarket Providers, Lubricant Manufacturers, Distributors Service Type: Custom Formulation, Technical Support, Regulatory Assistance, Quality Control |
| Companies Covered | Evonik Industries AG, Chevron Oronite Company LLC, The Lubrizol Corporation, Akzo Nobel N.V., Sanyo Chemical Industries, Ltd., Infineum International Limited, Afton Chemical Corporation, Mitsui Chemicals, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Viscosity Index Improvers Market Strategic Shifts
Formulation chemistry is pivoting toward multifunctional polymer architectures that combine viscosity modification with dispersancy or antioxidant properties, reducing total additive treat rates while meeting tighter performance specifications.
Star-branched polymethacrylate architectures are miniaturizing molecular coil dimensions while maintaining thickening efficiency, enabling SAE 0W-8 and 0W-12 grades that European OEMs specify for downsized turbocharged gasoline direct injection engines. Mercedes-Benz and Volkswagen Group powertrain divisions are validating these polymers for 2027 model year factory fills. The technology is miniaturizing the boundary between achievable viscosity grade and mechanical durability, compressing the performance gap that once separated synthetic from mineral formulations.
REACH Annex XVII restrictions on microplastic release are compelling ECHA-registered suppliers to demonstrate biodegradation pathways for polymer fragments in used lubricants, reshaping R&D priorities toward ester-functionalized and hydrocarbon structures with documented environmental fate profiles. Blenders serving the European aftermarket face reformulation deadlines that Asian-export-focused competitors do not. Passenger car motor oil categories with extended drain claims are absorbing disproportionate compliance attention as OEMs preempt regulatory scrutiny.
Long-term service contracts linking additive treat rates to measured engine wear outcomes are displacing traditional volume-based procurement at North American heavy-duty fleet operators. Shell Lubricant Solutions and Chevron have piloted performance-guarantee structures with Schneider National and J.B. Hunt that shift technical risk to suppliers. This model is most visible in Class 8 trucking corridors between Dallas-Fort Worth and Southern California, where fuel economy verification drives contract renewal decisions.
Automotive Viscosity Index Improvers Market Segmentation
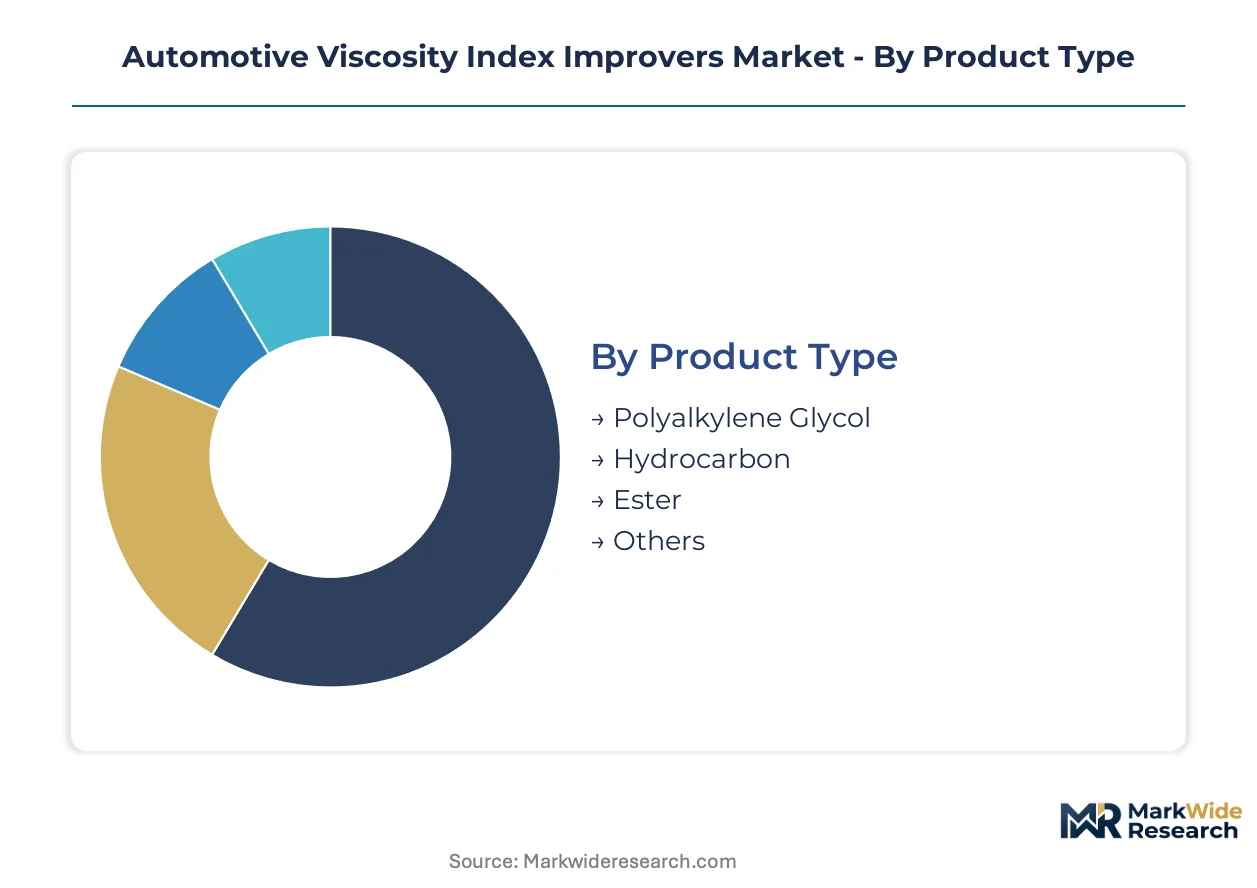
Viscosity index improver segmentation reveals how polymer chemistry, application requirements, and service intensity partition margin pools across the value chain. Formulators target divergent performance specifications while navigating OEM approval timelines and regional regulatory divergence.
Product Type:
Hydrocarbon formulations command the widest manufacturing scale, while ester and PAG chemistries capture premium positioning through performance differentiation.
- Hydrocarbon:Ethylene-propylene copolymer and hydrogenated styrene-diene polymers dominate volume shipments through cost efficiency in mass-market engine oils. Demand concentrates in China where domestic automakers expand Group III synthetic adoption for passenger vehicle factory fills. Olefin feedstock volatility along Gulf Coast petrochemical corridors compresses margins during ethylene price spikes.
- Ester:Synthetic ester-functionalized polymers deliver superior oxidative stability for transmission fluids operating under severe thermal stress. European OEMs specify these chemistries for extended drain intervals under REACH-compliant formulations. Mercedes-Benz and Volkswagen Group powertrain divisions validate ester-based improvers for 2027 model year factory fill approvals.
- Polyalkylene Glycol:PAG chemistry enables electric vehicle thermal management fluids with stable viscosity across wider temperature ranges than hydrocarbon alternatives.
- Others:Specialty polymer architectures including star-branched polymethacrylates target SAE 0W-8 and 0W-12 grades for downsized turbocharged gasoline direct injection engines.
Hydrocarbon holds installed capacity. Polyalkylene Glycol is rotating up the share rankings.
Application:
Engine oil specifications drive formulation complexity, while transmission and hydraulic applications reward oxidative stability and shear resistance.
- Engine Oils:SAE 0W-16 and 0W-8 grades demanded by EPA CAFE standards and Euro 6 emission limits require polymers that maintain film strength under thinner operating conditions. China GB standard harmonization toward international viscosity grades reduces regional formulation fragmentation for multinational additive suppliers.
- Transmission Fluids:Dual-clutch and continuously variable transmissions impose severe shear stability requirements that favor ester and PAG chemistries over hydrocarbon alternatives. OEM factory-fill approvals from Mercedes-Benz and Volkswagen Group concentrate demand in European and Asian passenger vehicle segments.
- Hydraulic Fluids:Construction and agricultural equipment manufacturers specify viscosity-stable formulations for extreme ambient temperature operation.
- Greases:Thickener compatibility and mechanical stability requirements drive specialized polymer selection for rolling element bearing applications.
Engine Oils anchors volume demand. Transmission Fluids is climbing the fastest on specification premiumization.
End User:
OEM factory-fill approvals concentrate technical validation resources, while aftermarket and distributor channels reward formulation flexibility and regional regulatory compliance.
- OEMs:Passenger vehicle manufacturers specify SAE 0W-16 and 0W-8 grades through 24-36 month field test commitments for API SP-Resource Conserving and ILSAC GF-6A certification cycles. Captive supply relationships between major lubricant marketers and in-house additive divisions restrict third-party VII supplier access to leading OEM factory-fill specifications.
- Aftermarket Providers:Independent service channels in North America and Europe demand formulation compatibility across multiple OEM specifications with shorter approval timelines than factory-fill programs.
- Lubricant Manufacturers:Blenderies serving regional markets navigate divergent REACH, GB standards, and BIS compliance pathways that fragment formulation strategies.
- Distributors:Bulk fluid suppliers to fleet operators and industrial accounts prioritize inventory consolidation across viscosity grades and application categories.
OEMs holds approval authority. Aftermarket Providers is gaining share fastest on service flexibility.
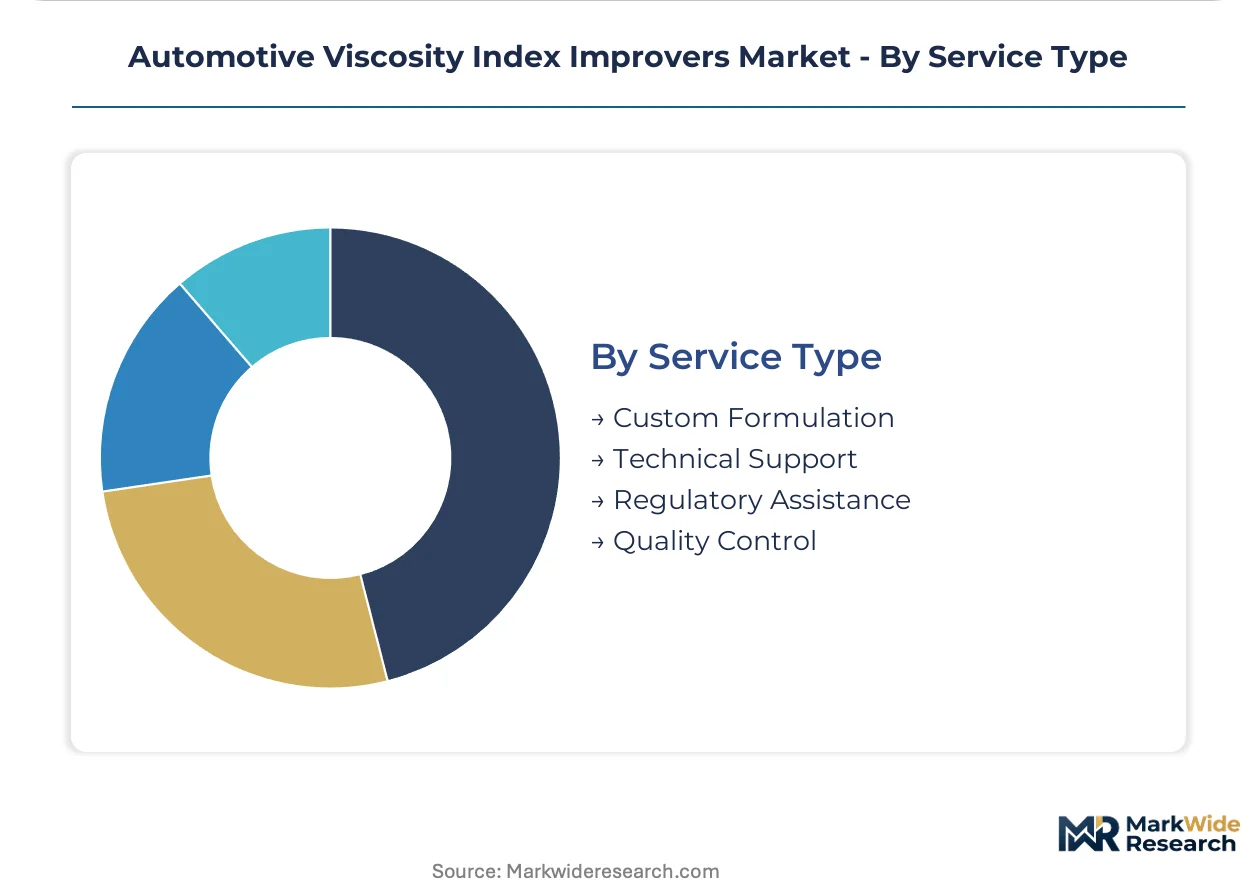
Service Type:
Custom formulation and regulatory assistance concentrate value-added margins, while technical support and quality control anchor ongoing customer relationships.
- Custom Formulation:Polymer architecture design for specific base oil compatibility and performance targets requires deep methacrylate or olefin copolymer chemistry expertise scarce among mid-scale additive houses. Evonik Industries AG leverages its methacrylate platform to sustain formulation leadership across European and Asian markets.
- Regulatory Assistance:REACH registration obligations for polymer imports into Europe impose documentation costs and timeline risks that disadvantage smaller additive blenders against integrated majors. ECHA Annex XVII restrictions on microplastic release compel biodegradation pathway demonstrations for polymer fragments in used lubricants.
- Technical Support:Field engineering resources guide OEM customers through 24-36 month certification test programs for API SP-Resource Conserving qualification.
- Quality Control:Batch consistency verification and shear stability testing protocols ensure specification compliance across manufacturing campaigns.
Custom Formulation holds technical differentiation. Regulatory Assistance is rotating up the share rankings on compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA CAFE standards and Euro 6 emission limits are compressing lubricant viscosity grades across major automotive manufacturing economies. Factory-fill synthetic adoption accelerates formulation demand for high-performance viscosity modifiers in passenger vehicle powertrains.
United States
Corporate Average Fuel Economy targets mandate SAE 0W-16 and 0W-8 engine oils that reduce friction losses in light-duty trucks and passenger cars. EPA enforcement of fuel economy regulations intensifies additive specification requirements for domestic OEM factory-fill programs. Houston-Gulf Coast petrochemical corridors concentrate ethylene-propylene copolymer supply chains for hydrocarbon-based improver manufacturing.
Germany
Mercedes-Benz and Volkswagen Group powertrain divisions validate star-branched polymethacrylate architectures for 2027 model year factory fills. ECHA Annex XVII restrictions on microplastic release compel biodegradation pathway demonstrations for polymer fragments in used lubricants. Stuttgart and Wolfsburg engineering centers drive qualification timelines for next-generation SAE 0W-8 and 0W-12 grades.
China
Domestic automakers expand Group III synthetic oil adoption for passenger vehicle factory fills under evolving GB standards. MIIT fuel economy mandates and dual carbon goals accelerate lower-viscosity lubricant designs across state-owned and independent OEM portfolios. Shanghai and Guangzhou formulation laboratories concentrate multinational additive supplier technical resources for regional approval programs.
Japan
METI energy efficiency guidelines push OEMs toward thinner engine oil specifications for hybrid and downsized turbocharged gasoline direct injection powertrains. JIS lubricant classifications harmonize toward international viscosity grades, streamlining multinational supplier investments. Nagoya and Osaka industrial corridors host precision polymer research for transmission fluid applications in dual-clutch and continuously variable architectures.
India
BIS lubricant specification upgrades and OEM push for longer drain intervals create formulation opportunities in two-wheeler and passenger vehicle segments. Hero MotoCorp and TVS Motor factory-fill programs demand viscosity modifiers compatible with tropical ambient temperature operation. Pune and Chennai manufacturing clusters concentrate domestic lubricant blending capacity for regional aftermarket distribution.
Automotive Viscosity Index Improvers Market Competitive Environment
Listed leaders compete with private specialists across integrated formulation capabilities and regional approval access. The vendor base concentrates around integrated majors with captive base oil supply and independent additive houses with polymer chemistry expertise. Three archetypes dominate: integrated energy majors with backward control into olefin feedstocks, diversified chemical conglomerates with methacrylate platforms, and specialized lubricant additive pure-plays. Competitive moves center on OEM factory-fill approval timelines and capacity expansion in Asia-Pacific formulation corridors.
Within the integrated major tier, Evonik Industries AG and Chevron Oronite Company LLC exemplify divergent geographic anchoring strategies. Evonik occupies a position representing European methacrylate chemistry leadership, while Chevron Oronite sits within the Americas-integrated supply archetype. The Lubrizol Corporation anchors the specialized additive pure-play category. These three entities collectively illustrate how polymer chemistry expertise and regional manufacturing presence partition competitive access to OEM qualification programs.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Chevron Oronite Company LLC |
| The Lubrizol Corporation |
| Akzo Nobel N.V. |
| Sanyo Chemical Industries, Ltd. |
| Infineum International Limited |
| Afton Chemical Corporation |
| Mitsui Chemicals, Inc. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
API SP-Resource Conserving and ILSAC GF-6A certification cycles gate both supply qualification and price differentiation simultaneously, as 24-36 month field test commitments concentrate purchasing power among OEMs with approved factory-fill positions while fragmenting aftermarket access.
Pricing Analysis
Certification level creates the primary spread between premium polymethacrylate formulations and commodity hydrocarbon alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects treat rate efficiency, base oil compatibility, and OEM approval status. Cost compression in mass-market engine oils intensifies as Chinese domestic automakers expand Group III synthetic adoption. Aftermarket blenders exhibit highest price sensitivity due to fragmented volume procurement, while Mercedes-Benz and Volkswagen Group powertrain divisions command formulation premiums through captive supply relationships.
Supply Chain Analysis
China and the United States anchor viscosity improver manufacturing through concentrated base oil refining and additive blending infrastructure. Ethylene-propylene copolymer feedstocks draw from Gulf Coast petrochemical corridors, while methacrylate monomer supply rests on German and Japanese chemical production networks. Single-source vulnerability concentrates in alpha-olefin feedstock channels exposed to ethylene price volatility. Distribution runs through lubricant manufacturer direct procurement for OEM factory fills, with aftermarket channels served by regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM consolidation around factory-fill synthetic specifications shifts buyer power toward passenger vehicle manufacturers with 24-36 month certification timelines, fragmenting aftermarket pricing leverage.
For Market Incumbents: Secure API SP-Resource Conserving and ILSAC GF-6A approvals through accelerated field test commitments to defend against integrated lubricant marketers with captive additive divisions. Deepen backward integration into methacrylate monomer supply to offset alpha-olefin feedstock volatility compressing hydrocarbon improver margins. For New Entrants and Emerging Players: Anchor in India's two-wheeler synthetic transition where BIS specification upgrades and Hero MotoCorp factory-fill demand outpace established supplier coverage. Target polyalkylene glycol formulations for electric vehicle thermal fluids as adjacent demand beyond traditional drivetrain applications, leveraging PAG chemistry cross-compatibility to reduce R&D duplication against entrenched hydrocarbon specialists. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dispersant-VII hybrid technologies requiring scarce polymer chemistry expertise. Five-to-ten year viability favors acquisition targets with demonstrated REACH registration capabilities and established ECHA compliance pathways. Monitor OEM factory-fill approval timeline compression as inflection signal for technical validation resource strain among mid-scale additive houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Monomer Supply | Evonik Industries AG sustains formulation leadership through captive methacrylate chemistry platforms across European and Asian markets. |
| Polyalkylene Glycol Capacity Expansion | PAG chemistry captures electric vehicle thermal fluid demand beyond traditional engine oil applications with wider temperature stability. |
| REACH Registration Compliance Investment | ECHA Annex XVII biodegradation pathway documentation reshapes R&D priorities toward ester-functionalized polymer architectures. |
| India Two-Wheeler Factory-Fill Partnership | Hero MotoCorp and TVS Motor synthetic adoption creates first-mover positioning in tropical ambient temperature formulations. |
| Dispersant-VII Hybrid Technology Development | The Lubrizol Corporation dominates converged soot-handling and viscosity-stabilization functions reducing total additive treat rates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineers, lubricant manufacturer procurement leads, additive blender technical directors, and aftermarket distributor channel heads. Primary interview insights triangulated against customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from integrated energy majors, and vehicle production databases. Bottom-up volume modeling across polymer chemistry grades converged with top-down market sizing through regional lubricant consumption patterns.
Across the analysis window, forecasts segment by product chemistry, application specification, end-user channel, and service intensity to capture margin pool distribution. CAGRs derive from elasticity modeling against EPA CAFE standard stringency, MIIT fuel economy mandate trajectories, and synthetic oil conversion rates in Chinese passenger vehicle production. Industry-specific inputs include OEM factory-fill approval timelines, REACH registration obligation schedules, and alpha-olefin feedstock price correlation coefficients.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory compression toward SAE 0W-16 and 0W-8 grades; material deviation in OEM synthetic adoption timelines or ECHA microplastic restriction enforcement would warrant model refresh. Recalibration cycles align with material shifts in API certification cycles, GB standard harmonization milestones, and electric vehicle thermal fluid specification crystallization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
South America Gear Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Brake Shoe Market