
 Fluid Couplings Market | 2026-2036
Fluid Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Couplings Market Intelligence
The EU F-Gas Regulation is hardening efficiency mandates for industrial power transmission equipment, compelling OEMs to redesign fluid coupling architectures for lower thermal losses. Voith GmbH leverages its hydrodynamic engineering heritage to dominate high-torque mining applications across Central Europe. Siemens AG sustains competitive positioning through integrated drive-train solutions that bundle couplings with variable-frequency systems. Altra Industrial Motion anchors its presence in North American material handling through specialized distribution partnerships with conveyor OEMs.
Fluid couplings are torque-transmitting devices that use a hydraulic fluid medium to transfer rotational power between driving and driven shafts, typically operating with fill volumes of 80-95% mineral oil or synthetic fluid to achieve controlled slip and overload protection. Their primary industrial purpose is to enable smooth start-up of heavy inertial loads while isolating vibration and protecting motors from shock loading. Hydrodynamic couplings capture the dominant share of mining equipment applications where stall torque management remains critical. Variable capacity designs represent the fastest-expanding category as cement and steel producers retrofit fixed installations for energy recovery. Electronic control integration across hybrid technology couplings is concentrating margin pools in systems that combine mechanical reliability with sensor-based condition monitoring.
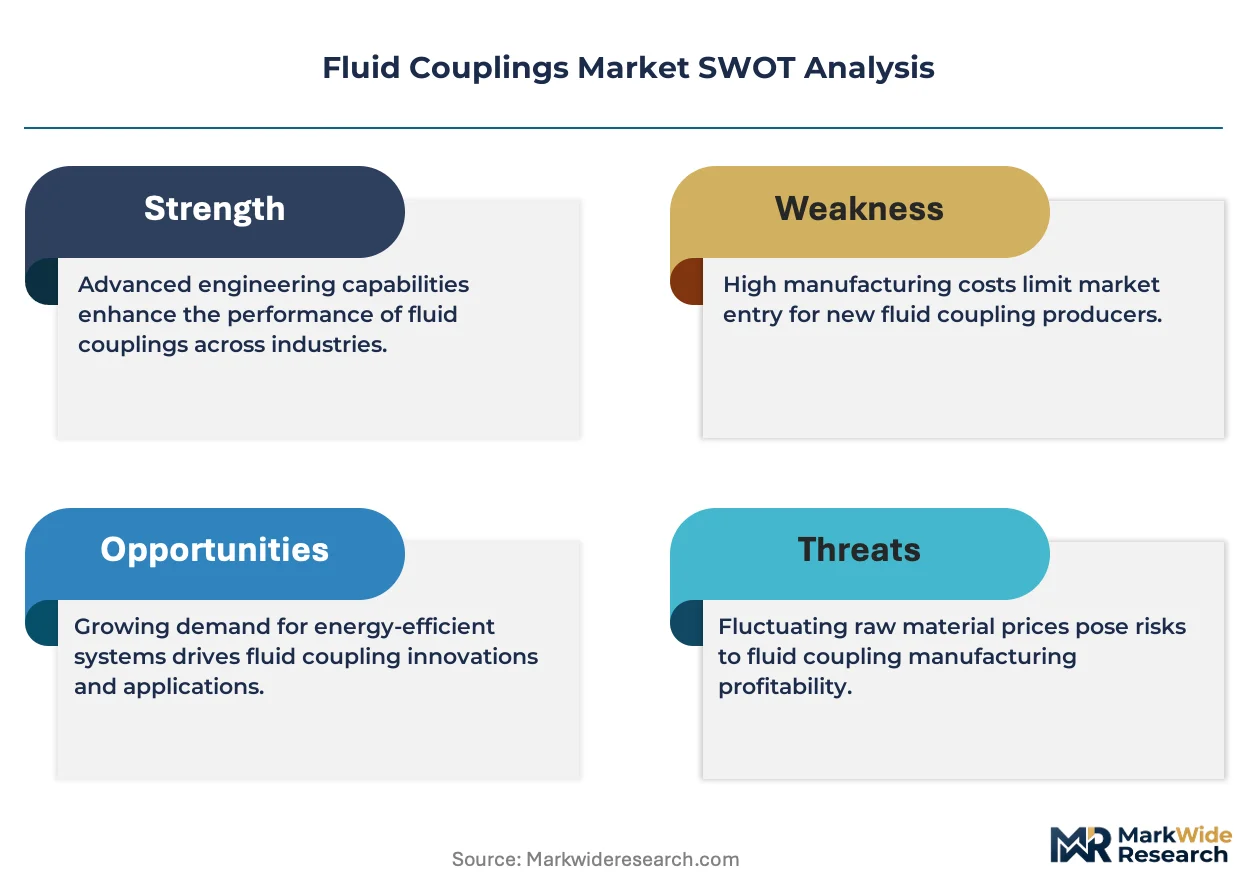
EPA industrial efficiency guidelines and China's GB standards for motor-driven systems are converging to mandate minimum performance thresholds for fluid coupling slip losses and standby energy consumption. EMA machinery directives in Europe further require CE-marked couplings to demonstrate compliance with vibration emission limits and material safety documentation for oil-filled units. Stakeholders must monitor how regional carbon border adjustments reshape sourcing economics for cast steel housings and precision-machined impeller components.
Market Dynamics
EU F-Gas Regulation and China's dual carbon goals are compressing thermal loss tolerances for industrial power transmission, forcing OEMs to redesign hydrodynamic architectures for measurable efficiency gains.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates reduced thermal losses in industrial power transmission equipment, compelling manufacturers to redesign fluid coupling architectures with optimized impeller geometries and synthetic fluid formulations.
- Mining equipment operators:Heavy inertial load management requirements in Australian and Brazilian open-pit operations sustain demand for hydrodynamic couplings with stall torque protection and controlled slip characteristics.
- Variable capacity designs:Energy recovery retrofits in cement and steel installations accelerate adoption of adjustable-fill couplings that modulate power transmission based on real-time load conditions.
Market Restraints
- Cast steel housing supply:Regional carbon border adjustments reshape sourcing economics for precision-machined impeller components and cast steel housings, concentrating supplier leverage in German and Chinese foundry clusters.
- Fixed-fill coupling obsolescence:Regulatory efficiency thresholds strand installed bases of constant-fill units, creating replacement cost burdens for operators with multi-decade capital cycles.
- Electronic variable-speed drives:Integrated motor-drive systems displace mechanical soft-start functions in light-to-medium torque applications below 500 kW rated power.
Strategic Opportunities
- Sensor-integrated hybrid couplings:Convergence of hydrodynamic reliability with IoT condition monitoring creates margin pools in predictive maintenance service contracts for critical conveyor systems.
- China's GB standards for motor-driven systems:National efficiency mandates for fluid coupling slip losses open retrofit markets for compliant variable-capacity units in provincial steel and cement plants.
- Aftermarket service unbundling:Independent service providers capture value from oil analysis, seal replacement, and impeller refurbishment programs outside OEM captive networks.
Industry Challenges
- Hydrodynamic engineering specialization:Scarcity of technicians trained in computational fluid dynamics for torque converter design limits OEM capacity to accelerate product development cycles.
- CE marking documentation:EMA machinery directives require extensive vibration emission testing and material safety documentation for oil-filled units, extending certification timelines by 8-14 months.
- Legacy system integration:Retrofit installations face mechanical interface mismatches with existing shaft alignments and foundation constraints in brownfield mining and materials processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Couplings Market |
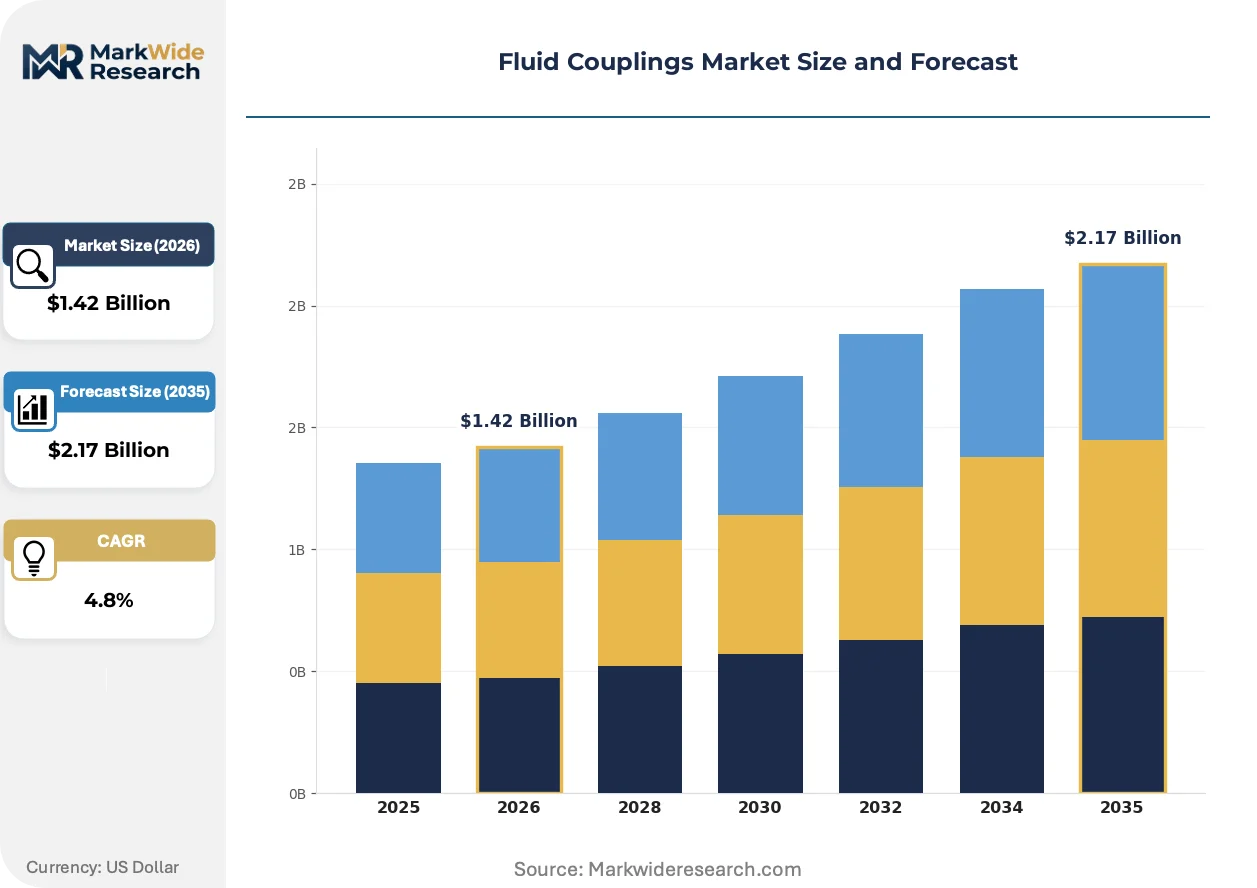
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydrodynamic, Fluid Drive, Variable Capacity, Rigid Couplings Application: Mining Equipment, Material Handling, Marine Propulsion, Industrial Machinery End User: Manufacturing, Construction, Oil & Gas, Renewable Energy Technology: Mechanical, Electronic, Hybrid, Pneumatic |
| Companies Covered | Voith GmbH, Siemens AG, ABB Ltd, Altra Industrial Motion, Rexnord Corporation, Transfluid S.p.A., Fluidomat Limited, Elecon Engineering Company Limited, KTR Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Couplings Market Strategic Shifts & Innovations
Active integration of electronic control systems with mechanical torque transmission is redefining value capture in fluid coupling markets, shifting margin pools from hardware sales to data-enabled service architectures.
Hybrid technology couplings are unifying mechanical overload protection with real-time sensor telemetry for vibration, temperature, and fill-level monitoring. Mining operators in Australia's Pilbara region deploy these units for predictive maintenance scheduling on critical conveyor lines. The technology is unifying hardware reliability with software-defined service models, compressing traditional aftermarket parts revenue into subscription-based performance contracts.
China's dual carbon goals and GB standards for motor-driven systems are mandating measurable reductions in fluid coupling slip losses across industrial installations. Provincial environmental regulators enforce compliance through energy audit requirements for designated high-consumption enterprises. Steel producers in Hebei and Shandong provinces respond by retrofitting fixed-fill installations with variable-capacity designs capable of 15-20% efficiency gains under partial load conditions.
Procurement patterns among European heavy manufacturing clusters are consolidating supplier relationships around integrated drive-train solutions rather than standalone coupling purchases. German automotive press lines and Bavarian cement plants now specify bundled contracts covering couplings, variable-frequency drives, and commissioning services. This consolidation concentrates purchasing leverage with system integrators and compresses margins for component-only manufacturers.
Fluid Couplings Market Segmentation
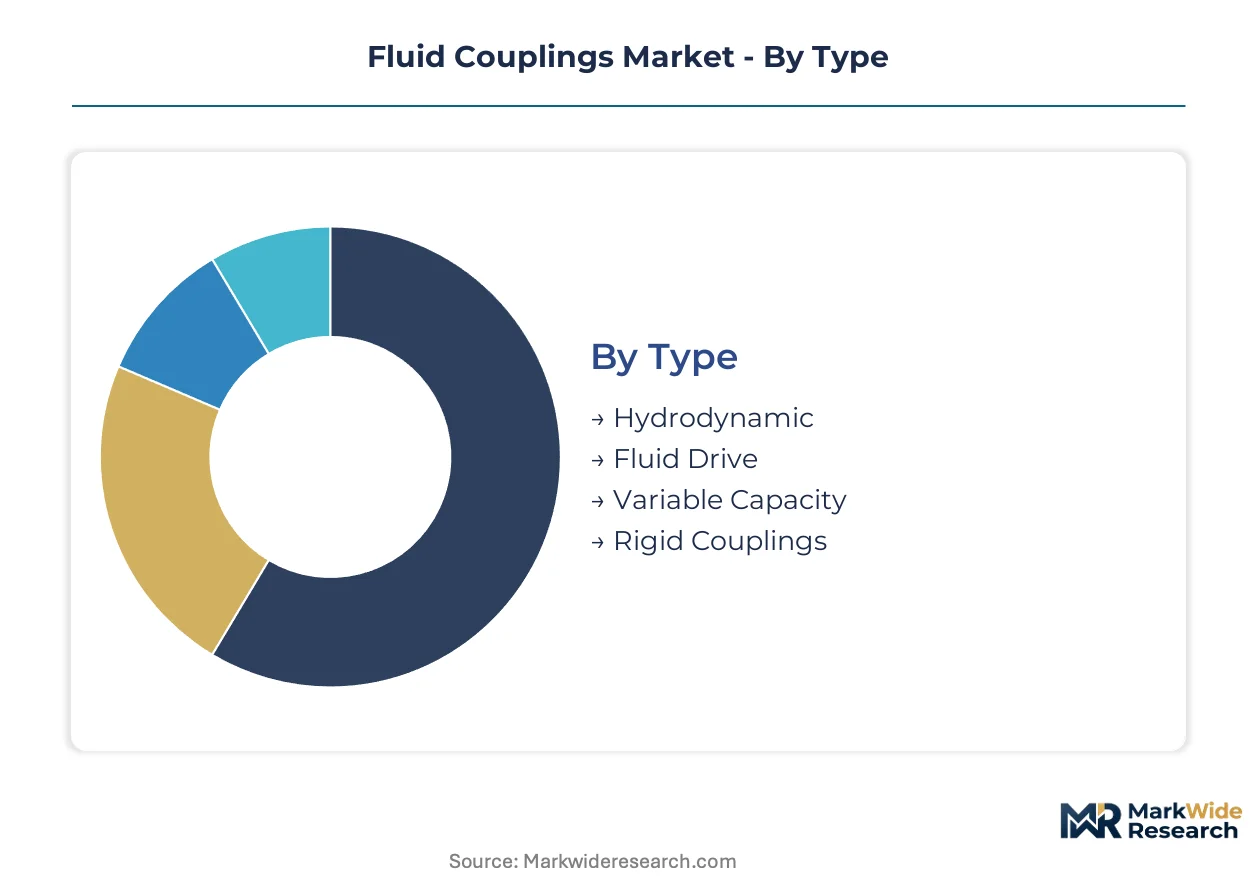
Segmentation in fluid couplings reflects divergent engineering requirements across torque ranges, start-up dynamics, and integration complexity. Equipment buyers select architectures based on load inertia profiles, regulatory efficiency mandates, and retrofit feasibility against existing mechanical infrastructure.
Type:
Standardization dominates high-volume mining applications while custom-engineered units serve specialized marine and process industry installations with unique shaft configurations.
- Hydrodynamic:These units transmit torque through kinetic energy transfer between pump and turbine wheels enclosed in oil-filled housings, achieving controlled slip of 2-4% at rated load. Australian iron ore operators in the Pilbara region specify these for conveyor systems exceeding 1000 kW, driven by stall torque protection requirements in abrasive dust environments.
- Variable Capacity:Adjustable-fill designs modulate working fluid volume through external scoop tubes or valve systems, enabling real-time torque matching to fluctuating loads. Cement producers in Germany's North Rhine-Westphalia retrofit these for 15-20% efficiency recovery under partial-load kiln operations, responding to EU F-Gas Regulation thermal loss thresholds.
- Fluid Drive:Compact integrated packages combine pump, turbine, and cooling circuits for space-constrained industrial settings.
- Rigid Couplings:Zero-slip mechanical connections serve precision alignment applications where vibration isolation is secondary to positional accuracy.
Most installed capacity flows through hydrodynamic units. Expansion is steepest in variable capacity designs.
Application:
Volume concentrates in bulk material movement where start-up shock protection preserves motor winding integrity across multi-decade operational horizons.
- Mining Equipment:Open-pit operations in Brazil's Carajás basin deploy high-torque couplings on dragline and shovel drives, managing inertial loads exceeding 50,000 Nm. Controlled acceleration prevents mechanical damage to gearboxes during frequent stop-start cycles in 24-hour extraction schedules.
- Material Handling:Port terminal operators in Rotterdam and Hamburg specify hybrid-coupled conveyor systems with integrated condition monitoring, shifting maintenance from calendar-based to predictive models. GB standards compliance for motor-driven systems in Chinese steel ports accelerates comparable retrofits in Tianjin and Qingdao.
- Marine Propulsion:Naval and commercial vessel builders prioritize torsional vibration damping in diesel-mechanical drivelines.
- Industrial Machinery:General manufacturing applications span presses, crushers, and pumps with moderate torque variability.
Mining equipment absorbs the largest share of high-torque unit shipments. Material handling demonstrates the sharpest technology upgrade trajectory.
End User:
Capital intensity and duty cycle severity determine specification tiers, with continuous-process industries commanding premium engineered solutions over intermittent-use sectors.
- Manufacturing:Automotive press lines and metal forming operations require rapid cycling couplings with thermal management for sustained high-frequency engagement. Bavarian automotive suppliers bundle these with variable-frequency drive packages under consolidated procurement contracts.
- Oil & Gas:Upstream pumpjack and compressor installations in West Texas and Alberta specify explosion-proof fluid couplings with sealed housings for hazardous area classification. API compliance documentation extends procurement cycles but locks in long-term aftermarket service relationships.
- Construction:Mobile crushing and screening equipment favors compact, maintenance-light designs for field deployment.
- Renewable Energy:Wind turbine gearbox manufacturers evaluate fluid couplings for drivetrain damping in multi-megawatt offshore platforms.
Manufacturing channels the highest unit volume through standardized configurations. Oil and gas commands the longest specification lead times and steepest engineering margins.
Technology:
Mechanical reliability competes with electronic precision across the power transmission architecture, with hybrid approaches capturing value in data-intensive operating environments.
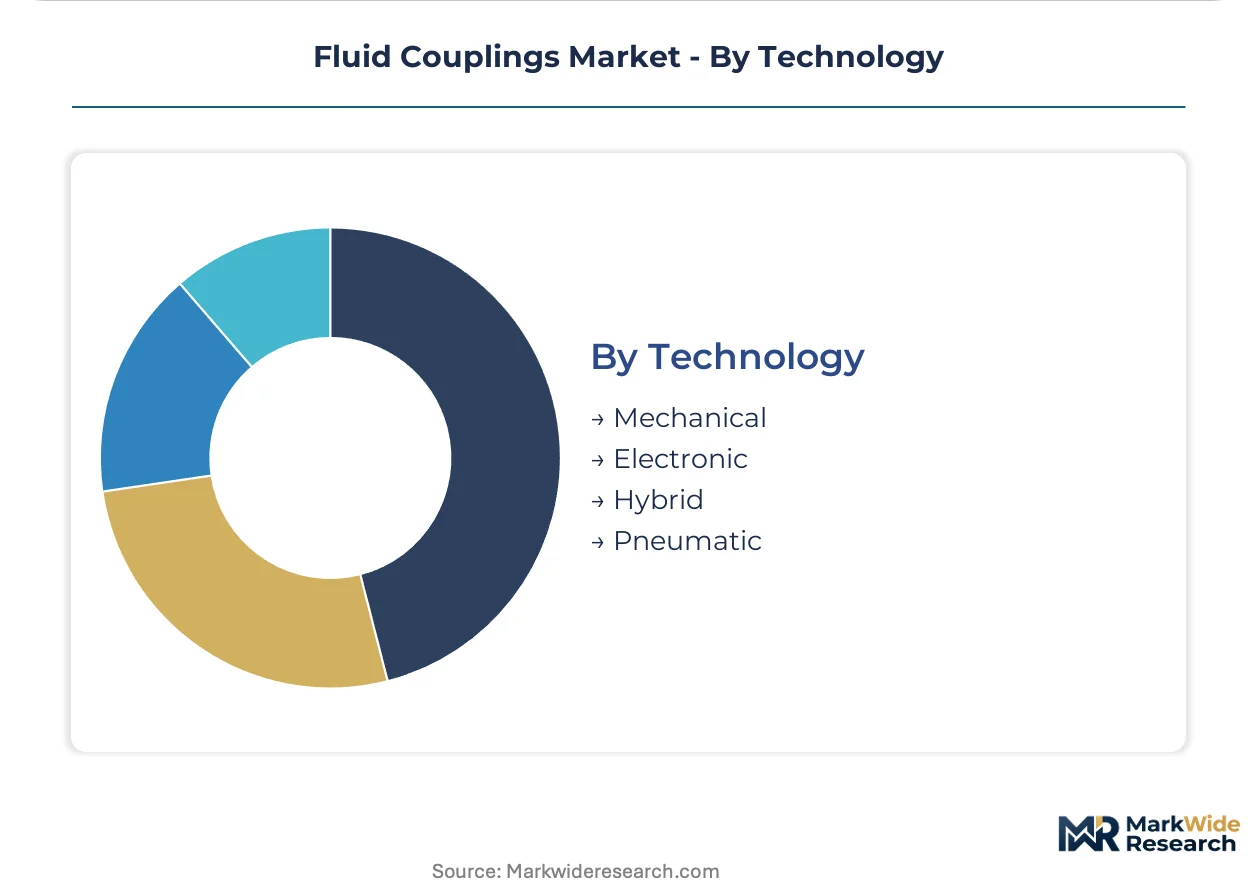
- Mechanical:Proven hydrodynamic architectures with no electronic dependencies serve remote mining and marine installations where technician availability is constrained. These units prioritize seal longevity and bearing service intervals measured in years rather than months.
- Hybrid:Sensor-integrated mechanical systems combine torque transmission with real-time telemetry for vibration, temperature, and fill-level monitoring. Australia's BHP and Rio Tino deploy these on critical conveyor lines, compressing parts revenue into subscription-based performance contracts with predictive maintenance guarantees.
- Electronic:Fully variable-speed motor-drive systems displace mechanical soft-start functions below 500 kW.
- Pneumatic:Compressed-air actuation serves specialized clutch applications in explosive atmospheres.
Mechanical technology retains dominance in heavy-torque segments. Hybrid architectures are gaining share fastest in integrated drive-train procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered hydrodynamic coupling engineering in the early twentieth century, establishing the technical foundations that now govern global efficiency standards for industrial power transmission equipment.
Germany
Heavy manufacturing clusters in Bavaria and North Rhine-Westphalia sustain demand for integrated drive-train solutions bundling couplings with variable-frequency systems. The EU F-Gas Regulation mandates reduced thermal losses, compelling Voith GmbH and Siemens AG to redesign impeller geometries at their Heidenheim and Erlangen facilities. Precision-machined component production concentrates in the Stuttgart industrial corridor.
China
Provincial steel and cement plants in Hebei and Shandong provinces drive retrofit demand for variable-capacity couplings achieving partial-load efficiency gains. GB standards for motor-driven systems enforce compliance through energy audit requirements for designated high-consumption enterprises. Foundry clusters in Jiangsu and Shandong supply cast steel housings for domestic OEMs and export markets.
Australia
Open-pit iron ore operators in Western Australia's Pilbara region specify high-torque hydrodynamic units for conveyor systems exceeding 1000 kW. The country's national mining safety regulator mandates stall torque protection in abrasive dust environments. BHP and Rio Tinto deploy sensor-integrated hybrid couplings on critical lines, shifting maintenance to predictive models.
Brazil
Carajás basin extraction schedules require controlled acceleration for dragline and shovel drives managing inertial loads exceeding 50,000 Nm. ANVISA and environmental agencies enforce equipment certification for hazardous mining operations. Heavy machinery procurement concentrates in São Paulo state's industrial distribution networks serving southeastern mining corridors.
United States
West Texas pumpjack installations and Alberta-bound compressor systems specify explosion-proof fluid couplings with sealed housings for hazardous area classification. EPA industrial efficiency guidelines converge with API compliance documentation to extend procurement cycles. Altra Industrial Motion anchors North American material handling through specialized distribution partnerships with conveyor OEMs.
Fluid Couplings Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the fluid couplings market, with integrated foundry operations holding cost advantages in cast steel housing production while specialized engineering houses capture premium margins in custom torque converter design. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates bundling couplings within drive-train systems, standalone hydrodynamic specialists with century-old engineering legacies, and component suppliers focused on specific torque ranges or regional aftermarket service. Dominant competitive moves include backward integration into precision-machined impeller manufacturing and geographic expansion through distribution partnerships with mining and materials handling OEMs.
Within the diversified industrial tier, Voith GmbH and Siemens AG exemplify integrated engineering conglomerates leveraging hydrodynamic heritage to anchor high-torque mining applications across Central Europe. Altra Industrial Motion represents the specialized component archetype, occupying a position in North American material handling through captive distribution networks. KTR Systems GmbH sits within the mid-market precision coupling segment, serving standardized industrial applications with shorter specification lead times than custom-engineered alternatives.
| Leading Market Players |
|---|
| Voith GmbH |
| Siemens AG |
| ABB Ltd |
| Altra Industrial Motion |
| Rexnord Corporation |
| Transfluid S.p.A. |
| Fluidomat Limited |
| Elecon Engineering Company Limited |
| KTR Systems GmbH |
| Others |
Cost & Logistics Intelligence
Family-owned German mid-caps with century-long hydrodynamic engineering legacies anchor pricing discipline through captive foundry operations and long-term service contracts, while private-equity-rolled-up component specialists compress margins in standardized industrial segments through volume aggregation and distributor consolidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. CE-marked units with EMA machinery directive compliance and integrated condition monitoring command substantial premiums over unmonitored mechanical alternatives. Cost compression in economy tiers intensifies because Chinese foundry exports and Indian precision-machining houses compete on cast steel housing production. Mining equipment operators in Australia's Pilbara region demonstrate lowest price sensitivity due to 24-hour extraction schedules where downtime costs dwarf hardware procurement, while construction equipment rental fleets in Southeast Asia exhibit acute price sensitivity favoring lowest-first-cost procurement.
Supply Chain Analysis
Scarcity of technicians trained in computational fluid dynamics for impeller design constrains production scaling in Germany's Stuttgart industrial corridor and China's Jiangsu foundry clusters. Precision-machined impeller components draw from German and Chinese manufacturing bases, with synthetic fluid formulations sourcing from specialty chemical producers in the United States and Belgium. Single-source vulnerability concentrates in precision-cast turbine wheel production where only three European and two Asian suppliers maintain API-compliant quality systems. Distribution runs through OEM captive networks for mining and oil and gas applications, while independent distributors serve standardized industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fluid couplings hinges on sensor-integrated hybrid architectures capturing predictive maintenance revenue streams, with efficiency-mandate compliance costs in Europe and China accelerating premium-tier substitution away from fixed-fill legacy units.
For Market Incumbents: Lock in aftermarket service relationships through oil analysis and impeller refurbishment programs that extend beyond OEM captive networks, while deepening backward integration into precision-machined component production to defend against Chinese foundry cost pressure. Electronic variable-speed drives below 500 kW represent the most acute substitution threat requiring bundled drive-train solutions that couple mechanical reliability with variable-frequency integration. For New Entrants and Emerging Players: Independent service providers in North American material handling represent the most penetrable buyer archetype for aftermarket unbundling strategies, with predictive maintenance contracts for critical conveyor systems offering recurring revenue without capital-intensive manufacturing scale. China's provincial steel and cement retrofit markets under GB standards compliance mandates provide white-space entry through variable-capacity coupling specialization, with local foundry partnerships enabling cost-competitive positioning against European imports. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market precision coupling specialists with standardized industrial exposure and limited aftermarket service penetration, where sensor integration investments could re-rate revenue quality toward subscription-based models. Hydrodynamic engineering talent scarcity in computational fluid dynamics disciplines constrains competitive entry and protects incumbent margin structures over the medium term. The signal to watch is carbon border adjustment implementation timelines reshaping sourcing economics for cast steel housings and precision-machined impeller components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision-Machined Components | Captive production of impeller assemblies reduces dependency on German and Chinese foundry clusters. |
| Sensor-Integrated Hybrid Coupling Development | Real-time telemetry for BHP and Rio Tino conveyor lines compresses hardware sales into predictive maintenance contracts. |
| GB Standards Compliance Certification | Energy audit alignment opens retrofit markets in Hebei and Shandong provincial steel plants. |
| Aftermarket Service Network Expansion | Oil analysis and seal replacement programs outside OEM captive networks capture recurring revenue from Altra Industrial Motion's distribution base. |
| Variable-Capacity Design Portfolio Buildout | Adjustable-fill architectures address EU F-Gas Regulation thermal loss thresholds in German cement and automotive press applications. |
Research Approach
Bottom-up mining equipment and material handling modeling reconciled against top-down foundry output and hydrodynamic component trade tracking forms the analytical core of this study. Primary interviews with maintenance directors at Australian iron ore operators, plant engineers in Germany's North Rhine-Westphalia manufacturing belt, OEM procurement teams at conveyor system builders, and aftermarket service heads at North American distribution networks combined with secondary validation from customs trade data, SEC filings of listed industrial conglomerates, EMA machinery directive certification databases, and GB standards compliance audit records. Triangulation between demand-side equipment installation tracking and supply-side precision-machining capacity utilization ensures cross-verified volume estimates.
Input-output matrices mapping torque range specifications against end-use application intensity, regulatory compliance tier, and technology architecture generated segment-level projections across the analysis window. Segmentation dimensions modeled include coupling type, application sector, end-user industry, and technology integration level, with CAGRs derived from regression analysis of historical equipment procurement patterns against industrial capital expenditure cycles and energy efficiency mandate implementation schedules. Forecast inputs incorporated foundry capacity expansion announcements in Jiangsu and Shandong provinces, EU F-Gas Regulation enforcement timelines, and mining safety regulator mandates in Western Australia.
Inputs from EMA certification databases and Australian mining safety regulator filings were available through the study window; gaps in provincial-level Chinese energy audit compliance rates introduce uncertainty bands around retrofit demand quantification. Forecasts reflect assumptions regarding carbon border adjustment implementation scope and hydrodynamic engineering graduate pipeline capacity in German technical universities. Material deviation in EU F-Gas Regulation enforcement stringency or Chinese dual carbon goal provincial allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Stampings Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Seat Track Market